
 Electric Kebab Machine Market | 2026-2036
Electric Kebab Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Kebab Machine Market Foresight
Foodservice distribution through specialty kitchen equipment dealers is narrowing as direct-to-operator digital procurement gains share. Günther Dönertechnik GmbH leverages its German engineering reputation to command premium positioning in European markets. Hatco Corporation anchors North American supply through broadline foodservice relationships and extensive distributor networks. Guangzhou Itop Kitchen Equipment Co., Ltd. competes on manufacturing scale, exporting standardized units across Southeast Asia and the Middle East.
An electric kebab machine is a motorized, thermostatically controlled vertical or horizontal rotisserie appliance designed to cook stacked, marinated meat—typically lamb, chicken, or beef—using infrared quartz or ceramic heating elements rated between 500W and 2000W, with stainless steel construction dominating commercial specifications for durability and food safety compliance. Countertop machines lead unit volume in compact urban kitchens where floor space commands premium pricing, while vertical grills capture the fastest growth trajectory as Middle Eastern and Mediterranean restaurant formats expand internationally. Stainless steel material grades anchor margin pools due to regulatory mandates for commercial food-contact surfaces, whereas aluminum variants occupy value-tier positioning in emerging markets with less stringent inspection regimes.
FDA food-contact surface regulations in the United States and EU Ecodesign requirements under the EU Green Deal shape material selection and energy efficiency benchmarks, compelling manufacturers to redesign heating element architectures. BIS electrical safety certifications in India and CE marking obligations across Europe create divergent compliance pathways that fragment product platform standardization. Buyers must monitor how dual carbon goals in China and evolving commercial kitchen energy codes in Germany redirect capital toward regenerative heating technologies.
Market Dynamics
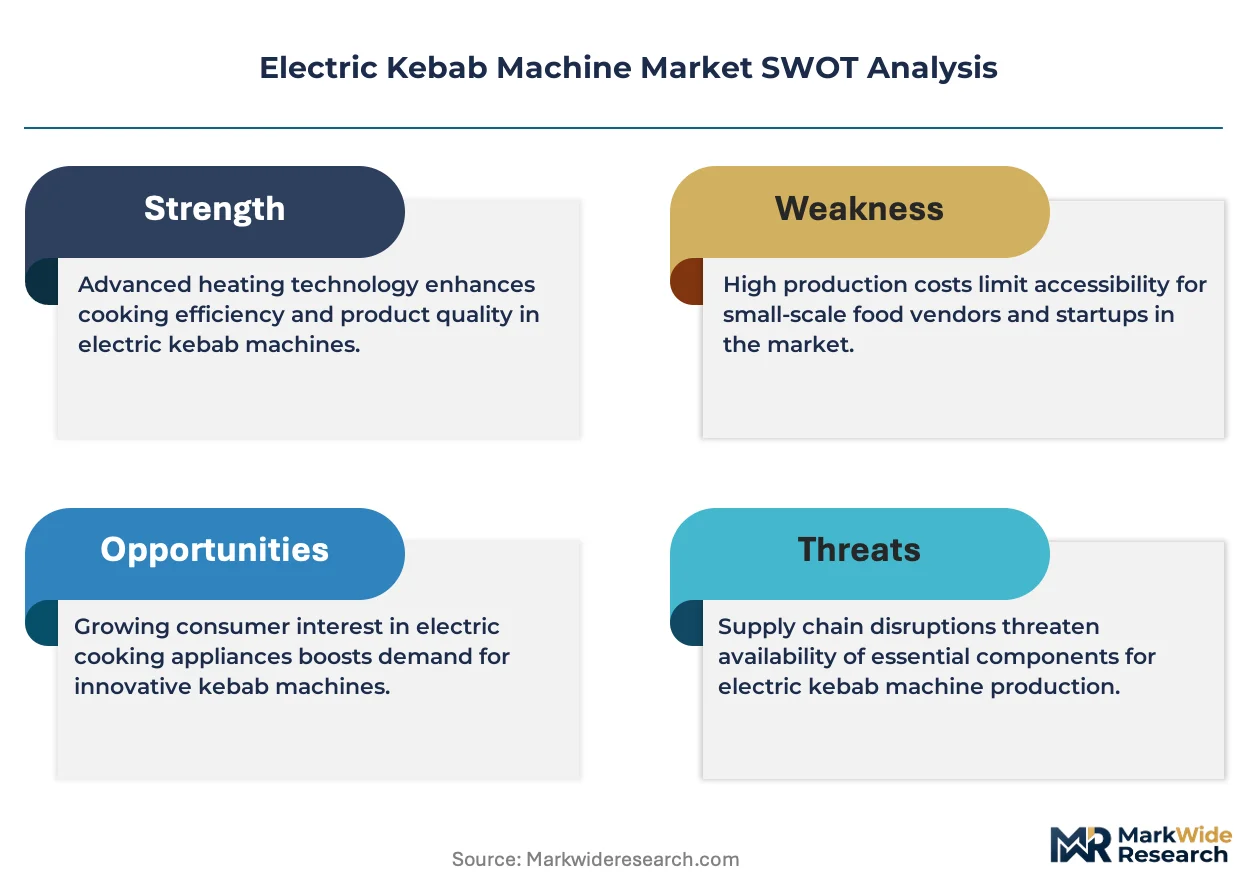
Energy efficiency mandates under the EU Ecodesign Directive are forcing heating element redesigns across the electric kebab machine supply base, compressing margins for manufacturers reliant on legacy quartz architectures while rewarding ceramic infrared adopters with compliance headroom.
Growth Catalysts
- EU Ecodesign Directive:Mandatory energy efficiency benchmarks for commercial cooking equipment are pulling replacement demand toward regenerative heating technologies in Germany, France, and Italy.
- Quick-service restaurant automation:Labor cost pressures in Saudi Arabia and UAE foodservice operations are accelerating vertical rotisserie deployments to reduce manual slicing dependency.
- Gaziantep fabrication cluster:Turkey's concentrated stainless steel machining capacity anchors regional supply chains, lowering procurement lead times for Middle Eastern buyers.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress margin predictability for commercial-grade fabricators dependent on food-contact surface compliance.
- CE marking fragmentation:Divergent electrical safety testing protocols across EU member states extend certification timelines and raise compliance costs for standardized product platforms.
- Gas rotisserie substitution:Propane and natural gas vertical broilers retain cost advantages in energy markets with subsidized fossil fuel pricing, limiting electric penetration in price-sensitive segments.
Strategic Opportunities
- India BIS certification gap:Underpenetrated commercial kitchen equipment certification infrastructure creates first-mover advantage for compliant electric kebab machine suppliers targeting Mumbai and Delhi foodservice hubs.
- Direct-to-operator digital procurement:Bypassing specialty kitchen equipment dealers through B2B platforms is compressing distribution margins and enabling manufacturer pricing control.
- Smart thermostat convergence:Integration of IoT temperature monitoring with HACCP logging systems opens premium positioning for connected rotisserie units in chain restaurant deployments.
Industry Challenges
- Skilled welder scarcity:Food-grade stainless steel fabrication requires certified TIG welding expertise that concentrates in aging workforce pools across European manufacturing bases.
- Dual certification burden:Simultaneous FDA food-contact surface validation and EU Ecodesign efficiency testing extends product launch timelines by eight to fourteen months for transatlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Kebab Machine Market |
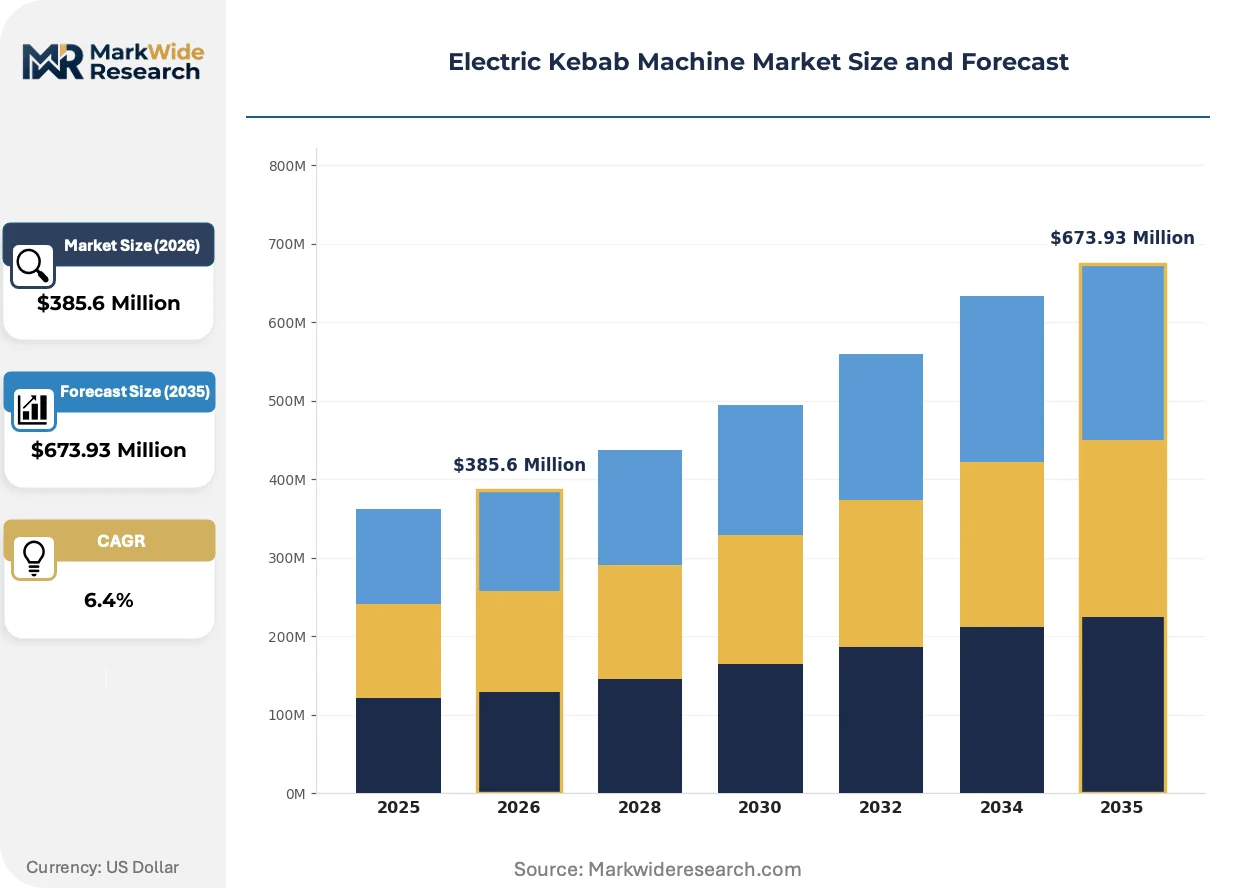
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Machines, Vertical Grills, Rotisserie Units, Commercial Equipment End User: Restaurants, Food Trucks, Caterers, Home Users Power Rating: 500W, 1000W, 1500W, 2000W Material: Stainless Steel, Aluminum, Plastic, Composite |
| Companies Covered | Hatco Corporation, Günther Dönertechnik GmbH, ELANGRILL, Guangzhou Itop Kitchen Equipment Co., Ltd., ANKO Food Machine Co., Ltd., Bartscher GmbH, Friulinox S.r.l., SKS Maschinenbau GmbH, Lincat Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Kebab Machine Market Shifts & Advancements
Active redesign of heating architectures and procurement channel structures is compressing traditional supply relationships while elevating energy performance as a primary purchase criterion.
Infrared ceramic heating elements with embedded thermocouple feedback loops are digitizing temperature control precision in commercial rotisserie operations. High-volume kebab chains in Germany and the Netherlands are adopting these systems to satisfy HACCP documentation requirements with automated logging. This digitizing capability is compressing demand for manual probe thermometers and paper-based compliance workflows.
REACH chemical safety restrictions on hexavalent chromium surface treatments are redirecting stainless steel finishing toward electropolishing and passivation alternatives across EU manufacturing. Fabricators in Italy and Spain are retooling anodizing lines to eliminate prohibited conversion coatings from food-contact components. Vertical grill product lines targeting European export markets bear the highest compliance burden, with redesign cycles accelerating to meet phased substance restrictions.
Foodservice buyers are consolidating vendor relationships through integrated equipment procurement platforms that bundle kebab machines with slicers and holding cabinets. Specialty kitchen equipment dealers in France and Belgium are losing share to these consolidated purchasing systems operated by broadline distributors. This consolidation is most visible in institutional catering contracts across Benelux education and healthcare sectors, where single-source accountability reduces vendor management overhead.
Electric Kebab Machine Market Segmentation
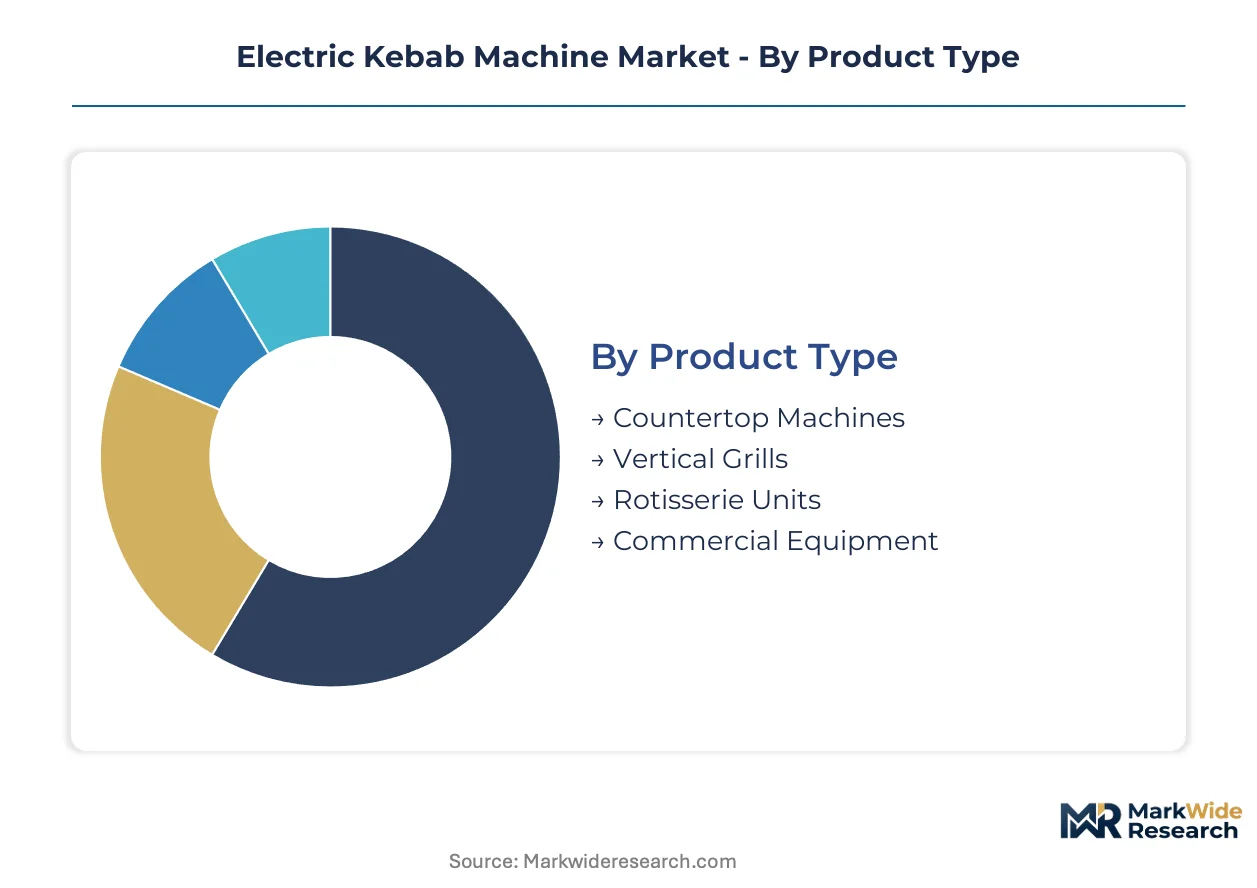
Equipment specification tiers in the electric kebab machine market align directly with operational intensity and regulatory exposure. Segmentation reveals how procurement patterns diverge between high-volume commercial operators and constrained-space installations.
Product Type:
Replacement cycles stretch from eighteen months for entry-level countertop units to seven years for heavy-duty vertical installations. Countertop machines turn over fastest due to thermal degradation of compact heating elements.
- Countertop Machines:Compact motorized rotisseries with 500W-1000W infrared quartz elements dominate urban kitchens where floor space commands premium lease rates. Demand concentrates in Istanbul's dense restaurant districts and Parisian bistro clusters where kitchen footprints average under fifteen square meters.
- Vertical Grills:Floor-standing units with 1500W-2000W ceramic infrared architectures accommodate stacked meat columns exceeding sixty centimeters. Saudi quick-service chains and UAE food courts are expanding these deployments to automate slicing operations and reduce labor dependency.
- Rotisserie Units:Horizontal-spit configurations serve Mediterranean and Latin American cooking formats with continuous rotation mechanisms.
- Commercial Equipment:Heavy-gauge stainless steel platforms rated for sixteen-hour daily operation anchor institutional catering contracts.
Countertop machines dominate installed base. Vertical grills are where expansion concentrates.
End User:
Procurement sophistication varies sharply across operator categories, with enterprise buyers demanding IoT-enabled temperature logging while independent operators prioritize capital efficiency.
- Restaurants:Full-service and quick-service establishments specify Grade 304 stainless steel construction to satisfy FDA food-contact surface mandates and simplify HACCP documentation. Germany's Döner kebab chains and Turkey's traditional ocakbaşı venues drive specification intensity.
- Food Trucks:Mobile operators favor 1000W-1500W units with reinforced suspension mounts and compact footprints. California's permitted food truck zones and London's street food markets are standardizing around dual-voltage compatibility for generator flexibility.
- Caterers:Event-service operators prioritize rapid heat-up ceramic elements for intermittent duty cycles.
- Home Users:Enthusiast segments in Australia and South Korea import compact vertical units through cross-border e-commerce channels.
Restaurants dominate installed base. Food trucks are where expansion concentrates.
Power Rating:
Energy efficiency regulations under the EU Ecodesign Directive are compressing demand toward higher-efficiency architectures at each wattage tier.
- 500W:Entry-tier infrared quartz elements serve countertop installations with thermal output sufficient for chicken and turkey preparations. India's emerging foodservice hubs in Mumbai and Delhi favor these units for voltage stability in grid-constrained districts.
- 1000W:Mid-range ceramic and quartz hybrid configurations balance recovery speed with energy consumption.
- 1500W:High-output ceramic infrared systems with embedded thermocouple feedback dominate German chain restaurant deployments.
- 2000W:Maximum-density heating arrays support continuous commercial operation with sub-three-minute recovery intervals.
1000W and 1500W ratings dominate installed base. 2000W configurations are where expansion concentrates.
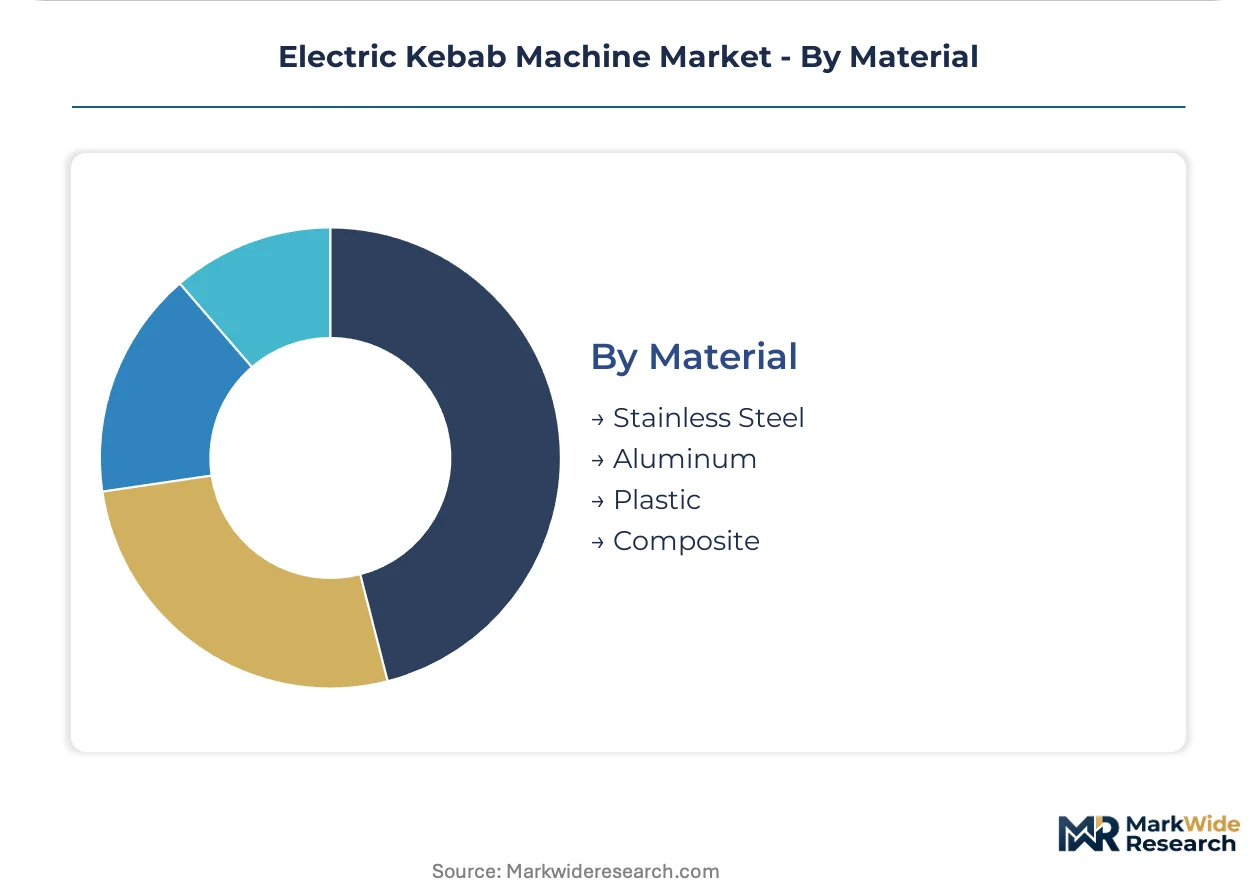
Material:
Surface treatment regulations under REACH are eliminating hexavalent chromium conversion coatings from EU-bound supply chains.
- Stainless Steel:Grade 304 and 316 austenitic alloys with electropolished or passivated finishes satisfy FDA and EU food-contact mandates. Gaziantep's fabrication cluster anchors regional supply for Middle Eastern buyers seeking Grade 316 corrosion resistance for high-humidity coastal installations.
- Aluminum:Anodized variants occupy value-tier positioning in Southeast Asian markets with less stringent inspection regimes.
- Plastic:High-temperature polymer housings and control interfaces reduce conductive heat transfer to operator contact surfaces.
- Composite:Ceramic-metal hybrid heating element substrates optimize thermal mass and response speed.
Stainless steel dominates installed base. Aluminum variants are where expansion concentrates in price-sensitive emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors German distribution for commercial kitchen equipment moving into Central European foodservice networks. This maritime gateway channels stainless steel fabrication inputs from Turkish suppliers toward industrial catering hubs in the Netherlands and Belgium.
Germany
Quick-service Döner chains in Berlin and Hamburg drive specification intensity for ceramic infrared heating systems. The EU Ecodesign Directive mandates efficiency benchmarks that favor regenerative heating architectures in Baden-Württemberg manufacturing zones. Stuttgart-area fabricators retool production lines to eliminate legacy quartz element platforms.
Turkey
Gaziantep's concentrated stainless steel machining capacity supplies Grade 316 corrosion-resistant platforms for high-humidity coastal installations across the Middle East. The country's national standards body aligns commercial food-contact regulations with EU REACH substance restrictions. Istanbul's dense restaurant districts favor compact countertop units averaging under fifteen square meters per kitchen.
United States
California's permitted food truck zones standardize dual-voltage compatibility requirements for generator-flexible mobile operations. FDA food-contact surface regulations mandate Grade 304 stainless steel construction across commercial specifications. Chicago's institutional catering contracts consolidate vendor relationships through integrated procurement platforms.
United Arab Emirates
Dubai food courts and Abu Dhabi quick-service chains deploy vertical rotisserie units to automate slicing operations and reduce labor dependency. The national health regulator enforces HACCP documentation standards that pull demand toward IoT-enabled temperature logging systems. Sharjah's logistics corridors channel equipment toward Saudi Arabian expansion markets.
India
Mumbai and Delhi foodservice hubs favor 500W entry-tier units for voltage stability in grid-constrained districts. BIS electrical safety certifications create compliance pathways that fragment product standardization for transnational suppliers. Tamil Nadu's emerging commercial kitchen clusters attract first-mover investment from certified equipment suppliers.
Electric Kebab Machine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying heating elements and control modules. The vendor base organizes around three strategic archetypes: German engineering-centric premium fabricators, Chinese scale-driven exporters, and regional specialists serving Middle Eastern kebab formats. Competitive dynamics center on certification acceleration and direct-to-operator digital channel capture rather than price-based displacement.
Among German-based fabricators, Günther Dönertechnik GmbH and SKS Maschinenbau GmbH exemplify the engineering-premium archetype, occupying positions where regulatory compliance headroom commands pricing control. Guangzhou Itop Kitchen Equipment Co., Ltd. represents the scale-export model, anchoring supply relationships across Southeast Asian and Middle Eastern markets through manufacturing volume rather than specification intensity. These three players illustrate how geographic origin and corporate structure map to divergent competitive vectors in a market where energy efficiency mandates and food-contact regulations increasingly determine procurement outcomes.
| Leading Market Players |
|---|
| Hatco Corporation |
| Günther Dönertechnik GmbH |
| ELANGRILL |
| Guangzhou Itop Kitchen Equipment Co., Ltd. |
| ANKO Food Machine Co., Ltd. |
| Bartscher GmbH |
| Friulinox S.r.l. |
| SKS Maschinenbau GmbH |
| Lincat Group plc |
| Others |
Supply & Pricing Matrix
Gaziantep's concentrated stainless steel machining cluster anchors input cost structures for Middle Eastern fabricators, concentrating margin pools with Grade 316 suppliers serving high-humidity coastal installations while compressing value-tier positioning for aluminum variants in Southeast Asian markets.
Pricing Analysis
Volume-discount tiering structures separate premium ceramic infrared systems from standard quartz architectures and economy-grade aluminum variants. Price differentiation hinges on EU Ecodesign compliance headroom and Grade 304 versus 316 stainless steel certification tiers. Pricing pressure stems from gas rotisserie substitution in subsidized fossil fuel markets, squeezing electric penetration in price-sensitive segments. Quick-service chains in Saudi Arabia and UAE show least price sensitivity due to labor automation priorities, while independent Istanbul bistro operators maximize capital efficiency.
Supply Chain Analysis
Contract-manufacturing concentration sits with Turkish stainless steel fabricators, Chinese scale exporters, and German engineering-centric specialists. Geographic supply concentration centers on Turkey, China, and Germany for finished equipment, with ceramic heating element sourcing anchored in Japan and Germany. Raw material dependencies include Grade 304 and 316 stainless steel, infrared quartz and ceramic substrates, and high-temperature polymer housings. Single-source vulnerability concentrates in certified TIG welding expertise pools across European manufacturing bases. Distribution runs through broadline foodservice networks and direct-to-operator digital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment—specifically dual FDA and EU Ecodesign certification requirements—creates eight-to-fourteen-month launch barriers that protect incumbent positioning.
For Market Incumbents: Pre-empt gas rotisserie substitution threats by accelerating ceramic infrared R&D investments and securing backward integration into heating element production. Expand capacity in Gaziantep to exploit regional stainless steel machining advantages and compress procurement lead times for Middle Eastern buyers. Prioritize channel control through direct-to-operator digital platforms to bypass eroding specialty dealer margins. For New Entrants and Emerging Players: Build out white-space presence in India's BIS certification gap, where underpenetrated commercial kitchen infrastructure creates first-mover advantage in Mumbai and Delhi foodservice hubs. Target food truck mobility segments in California and London with dual-voltage compatible designs. Pursue go-to-market partnerships with integrated equipment procurement platforms bundling kebab machines with slicers and holding cabinets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German engineering specialists possessing dormant EU Ecodesign compliance headroom. Long-term viability favors platforms with regulatory acceleration capabilities and IoT-enabled temperature logging integration. Watch for inflection signals in India BIS certification completion rates and Middle Eastern quick-service automation deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Infrared Heating Migration | EU Ecodesign compliance rewards adopters with margin headroom against legacy quartz architectures. |
| Direct-to-Operator Digital Channel | Bypassing specialty dealers compresses distribution margins and restores manufacturer pricing control. |
| India BIS Certification Investment | First-mover compliance creates protected positioning in underpenetrated Mumbai and Delhi hubs. |
| IoT Temperature Logging Integration | HACCP automation opens premium positioning for connected units in German chain restaurant deployments. |
| Gaziantep Capacity Expansion | Regional stainless steel machining concentration lowers procurement lead times for Middle Eastern buyers. |
Research Methodology
Cross-validation between primary interviews with commercial kitchen equipment procurement managers, restaurant chain operations directors, and stainless steel fabricators anchors the qualitative findings against secondary validation from EU Ecodesign regulatory filings, BIS certification databases, FDA food-contact surface guidance documents, and customs trade flow records. Bottom-up demand modeling triangulates with top-down market sizing across equipment specification tiers.
Calibration approaches stress-test volume and value outputs against historical replacement cycle data and regulatory phase-in schedules across the projection horizon. Segmentation dimensions modeled include product type, end-user category, power rating tier, material grade, and regional regulatory cluster. CAGRs derive from equipment shipment trajectories and energy efficiency mandate adoption curves, with ceramic versus quartz heating element mix shifts serving as primary forecast sensitivity inputs.
Stress conditions across stainless steel price volatility, CE marking timeline extensions, and gas-electric substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and quick-service automation adoption rates. Quarterly review of India BIS certification issuance velocity and Gaziantep fabrication capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Dispensing Systems and Equipment Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
USA Commercial Walk-In Refrigeration Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Food Processing Machinery Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
North America Beverage Filling and Capping Machine Market
Food Processing Equipment
Industrial Fryers Market
Food Processing Equipment
Mooncake Production Line Market