
 Food Irradiation Equipment Market | 2026-2036
Food Irradiation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Irradiation Equipment Market Foresight
REACH is expanding compliance burdens for cobalt-60 sourcing across European supply chains. STERIS Isomedix Services leverages vertical integration across contract sterilization networks to sustain service reliability. Sterigenics International anchors its position through multi-site electron beam and gamma capacity. Nordion Inc. dominates isotope supply logistics for gamma irradiator operators.
Food irradiation equipment encompasses systems that expose food products to ionizing radiation at controlled doses, typically 1–10 kGy for microbial decontamination, using gamma rays, accelerated electrons, or X-rays to disrupt pathogen DNA without significantly raising product temperature. The primary purpose is to eliminate foodborne pathogens, extend shelf life, and satisfy phytosanitary trade requirements without chemical residues. Gamma irradiators retain the largest installed base due to proven reliability for high-density products, while electron beam systems capture fastest growth owing to faster dose rates and elimination of radioactive source management. Conveyor-based continuous processing technology leads operational throughput in high-volume meat and spice applications.
FDA clearance under 21 CFR 179.26 shapes permissible applications and labeling requirements for irradiated foods in the United States. USDA-FSIS enforcement of HACCP plans for meat and poultry processors mandates pathogen controls that irradiation satisfies. The EFSA scientific panel on food contact materials evaluates migration risks from irradiated packaging under EU framework conditions. Stakeholders must monitor cobalt-60 source availability and electron beam energy efficiency benchmarks as technology substitution accelerates.
Market Dynamics
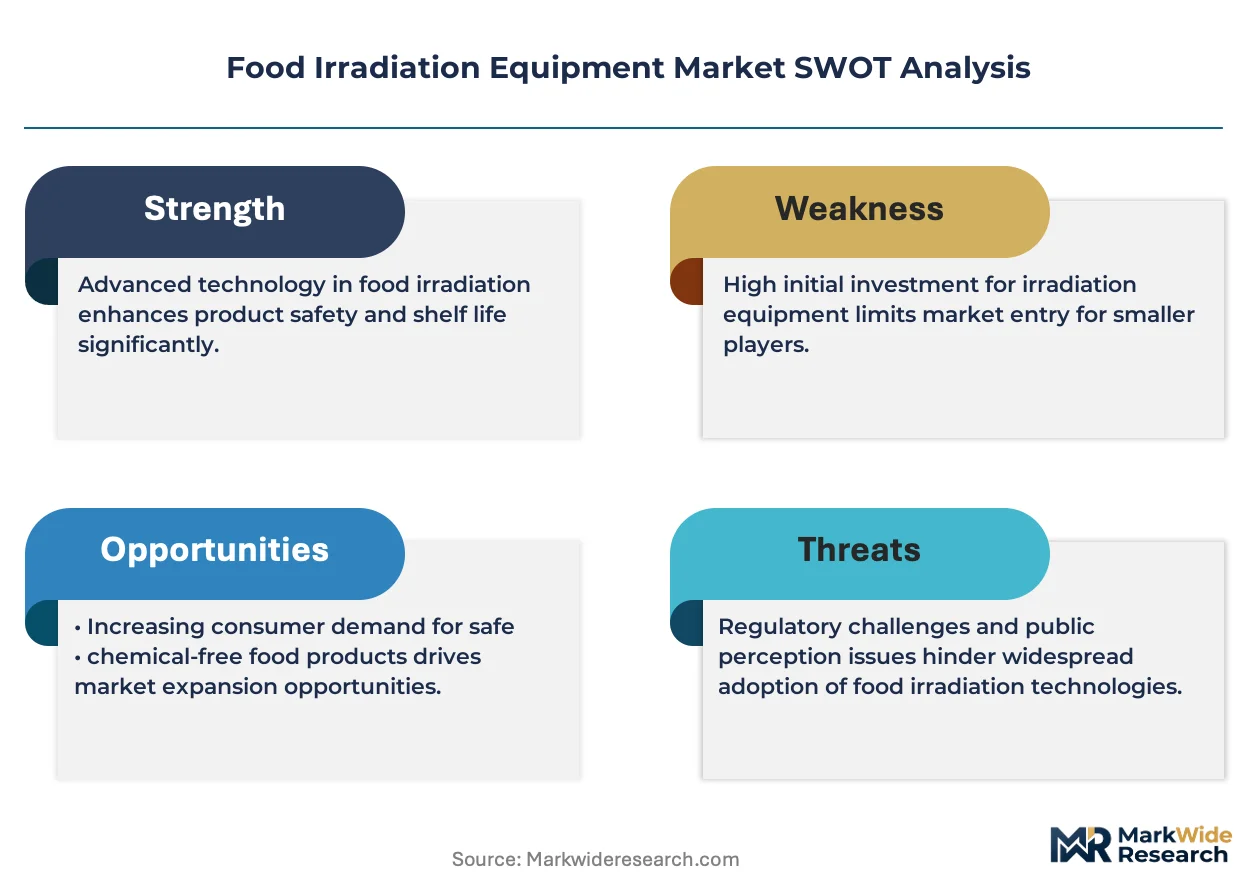
Electron beam systems are displacing cobalt-60 gamma irradiators as supply chain constraints for radioactive isotopes intensify and energy efficiency benchmarks tighten across food processing operations.
Growth Catalysts
- USDA HACCP mandates:Meat and poultry processors face mandatory pathogen controls that irradiation satisfies under USDA-FSIS enforcement, driving equipment procurement at inspected facilities.
- Phytosanitary trade requirements:Cross-border agricultural exporters deploy irradiation to meet quarantine standards without chemical residues, expanding system installations at port-adjacent processing hubs.
- Electron beam throughput advantages:Dose rate acceleration enables continuous conveyor processing that gamma systems cannot match, shortening treatment cycles for high-volume spice and poultry applications.
Market Restraints
- Cobalt-60 supply concentration:Isotope production clusters in aging nuclear reactors create sourcing vulnerability for gamma irradiator operators dependent on scheduled refueling cycles.
- Capital intensity of beam systems:Electron accelerator installations require shielding infrastructure and power conditioning that gamma facilities avoid, compressing returns for mid-scale processors.
- REACH compliance burdens:European supply chains face expanded documentation and handling protocols for radioactive source transport under ECHA frameworks.
Strategic Opportunities
- Indian food safety modernization:FSSAI implementation of Codex-aligned irradiation standards creates first-mover positioning for equipment suppliers as domestic cold chain infrastructure expands.
- X-ray hybrid configurations:Convergence of electron beam and X-ray generation technologies enables single-source flexibility for processors handling variable product densities.
- Spice export corridors:Phytosanitary treatment requirements for cardamom, pepper, and turmeric shipments to EU and US markets drive dedicated irradiation facility construction near cultivation clusters.
Industry Challenges
- Accelerator technician scarcity:Electron beam maintenance requires specialized high-voltage engineering expertise that food processing regions lack, extending downtime windows.
- Validation protocol complexity:FDA 21 CFR 179.26 compliance demands dose mapping studies that delay facility commissioning by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Irradiation Equipment Market |
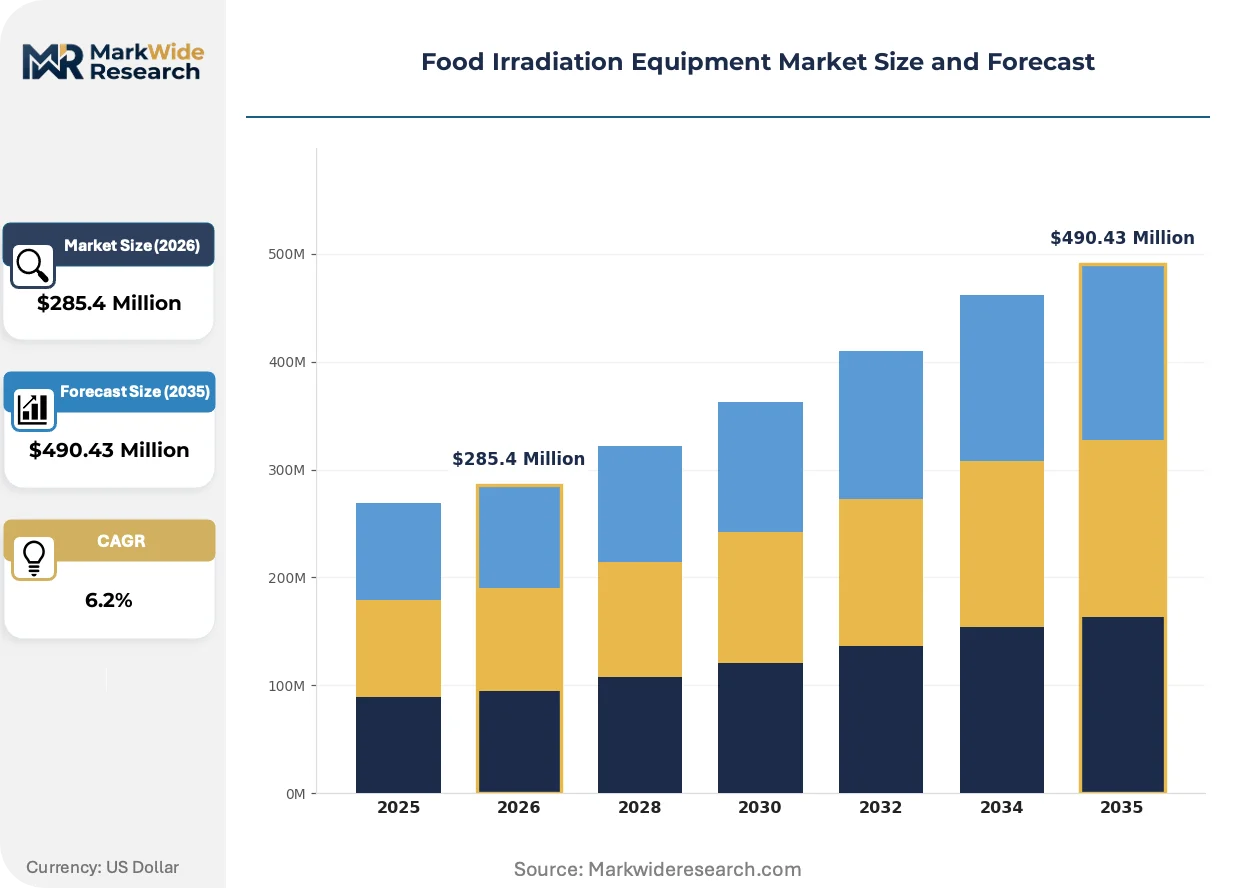
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Gamma Irradiators, Electron Beam Irradiators, X-ray Irradiators, Co-60 Irradiators Technology: Batch Processing, Continuous Processing, Dry Source Storage, Wet Source Storage, Conveyor Systems Application: Microbial Decontamination, Pest Control, Shelf-Life Extension, Sprout Inhibition, Pathogen Reduction End User: Food Processing Plants, Packaging Companies, Agricultural Cooperatives, Food Retailers |
| Companies Covered | STERIS Isomedix Services, Sterigenics International, Nordion Inc., Sadex Corporation, Food Technology Service Inc., Gray Star Inc., Ionisos SA, Scantech Sciences Inc., Mevex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Irradiation Equipment Market Shifts & Advancements
Technology substitution is compressing equipment lifecycles as processors weigh radioactive source management against electrical infrastructure investments. Three developments are reshaping competitive positioning.
High-voltage electron accelerator design is modularizing into containerized units that processors deploy without purpose-built concrete bunkers. Mid-scale spice and dried fruit operations in India and Vietnam are adopting these skid-mounted systems to bypass civil construction timelines. This architecture is modularizing entry barriers that previously confined electron beam adoption to multinational processors with captive engineering teams.
EFSA scientific panel evaluations of food contact material migration under EU framework conditions are tightening packaging specifications for irradiated products. Industrial consequence includes accelerated testing protocols for polymer films and modified atmosphere structures. Spice exporters to European markets are most affected, responding with pre-qualified packaging supplier relationships and dedicated irradiation lines.
Processor procurement of irradiation capacity is fragmenting between captive installations and contract sterilization networks. Large meat packers favor in-house electron beam systems for HACCP control, while mid-tier operators access Nordion-sourced gamma capacity through Sterigenics and STERIS Isomedix service agreements. This bifurcation is most visible in the United States, where USDA-inspected facility scale determines ownership versus outsourcing economics.
Food Irradiation Equipment Market Segmentation
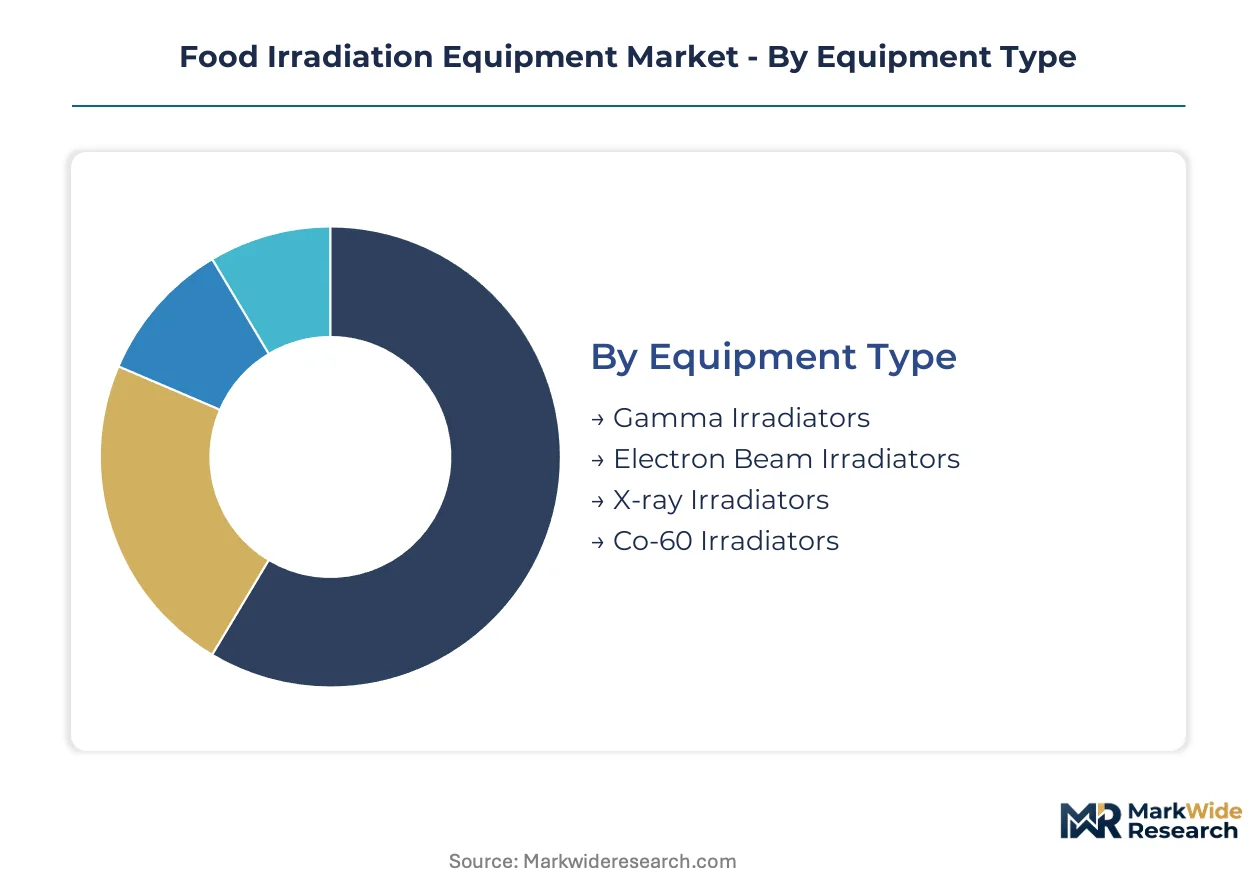
Equipment procurement patterns diverge sharply based on scale, regulatory exposure, and source material availability. Segment boundaries are blurring as electron beam modularization and contract sterilization networks reshape ownership economics across processor tiers.
Equipment Type:
Supply concentration in cobalt-60 isotope production clusters procurement decisions around source security and dose rate requirements.
- Gamma Irradiators:These systems deploy cobalt-60 isotopes housed in wet or dry storage pools to deliver deep penetration for high-density meat and spice loads. Demand concentrates in the United States at USDA-inspected facilities where proven pathogen reduction protocols satisfy HACCP mandates, though reactor refueling cycles create sourcing vulnerability.
- Electron Beam Irradiators:High-voltage accelerators generate directed electron streams that achieve surface-to-mid-depth treatment without radioactive materials. Adoption is climbing fastest among poultry processors in the United States seeking continuous conveyor throughput and elimination of source transport compliance under DOT and NRC frameworks.
- X-ray Irradiators:Bremsstrahlung conversion of electron energy enables penetration depths approaching gamma performance with electrical infrastructure alone. Mid-scale spice exporters in India are piloting hybrid configurations for variable-density cardamom and turmeric shipments.
- Co-60 Irradiators:Dedicated cobalt-60 systems with optimized source geometry serve high-volume contract sterilization facilities. Nordion's isotope logistics network sustains operator reliance despite aging reactor supply bases.
Today's leader: Gamma Irradiators. Tomorrow's challenger: Electron Beam Irradiators.
Technology:
Cost tier separation between civil infrastructure requirements and skid-mounted deployment options is fragmenting processor adoption paths.
- Batch Processing:Chamber-based systems treat discrete product loads with precise dose mapping for low-volume, high-value applications. Artisanal spice processors in Vietnam favor these units for phytosanitary certification of small-lot pepper exports to EU markets.
- Continuous Processing:Conveyor-integrated accelerators enable uninterrupted throughput that gamma systems cannot match. Large meat packers in the United States deploy these configurations to satisfy USDA-FSIS enforcement timelines without batch handling delays.
- Dry Source Storage:Sealed cobalt-60 rods in concrete-shielded vaults reduce water management overhead. Aging installations in Canada rely on this architecture where Health Canada regulations govern source security protocols.
- Wet Source Storage:Submerged isotope pools provide thermal management and radiation shielding for high-capacity gamma facilities. Sterigenics operates wet-storage networks across the United States Midwest to service regional meat processors.
- Conveyor Systems:Automated material handling integrates with electron beam accelerators for spice and dried fruit treatment. Indian food safety modernization under FSSAI is accelerating conveyor adoption at port-adjacent processing hubs.
Continuous Processing commands premium investment. Batch Processing retains viability at the artisanal tier.
Application:
Customer type stratification separates commodity volume processors from specialty exporters facing distinct phytosanitary gatekeeping regimes.
- Microbial Decontamination:Targeted reduction of Salmonella, E. coli, and Listeria in raw poultry and ground beef dominates United States equipment utilization. FDA 21 CFR 179.26 compliance frameworks mandate validated dose protocols that shape system specification.
- Pest Control:Quarantine treatment of fresh produce and grains eliminates insect infestation without chemical residues. Australian mango exporters to Japan deploy irradiation to satisfy METI phytosanitary import requirements.
- Shelf-Life Extension:Delayed spoilage organisms in refrigerated meats and seafood expand distribution reach. Cold chain infrastructure expansion in India is creating first-mover positioning for shelf-life-focused equipment deployments.
- Sprout Inhibition:Potato and onion storage applications suppress budding to extend marketable windows. Limited adoption outside bulk commodity handlers with captive storage infrastructure.
- Pathogen Reduction:Regulatory-mandated treatment of ready-to-eat meats and pet food ingredients. USDA-FSIS enforcement of HACCP-linked controls drives captive installation at inspected United States facilities.
Microbial Decontamination anchors current procurement. Pest Control is expanding most quickly with agricultural trade liberalization.
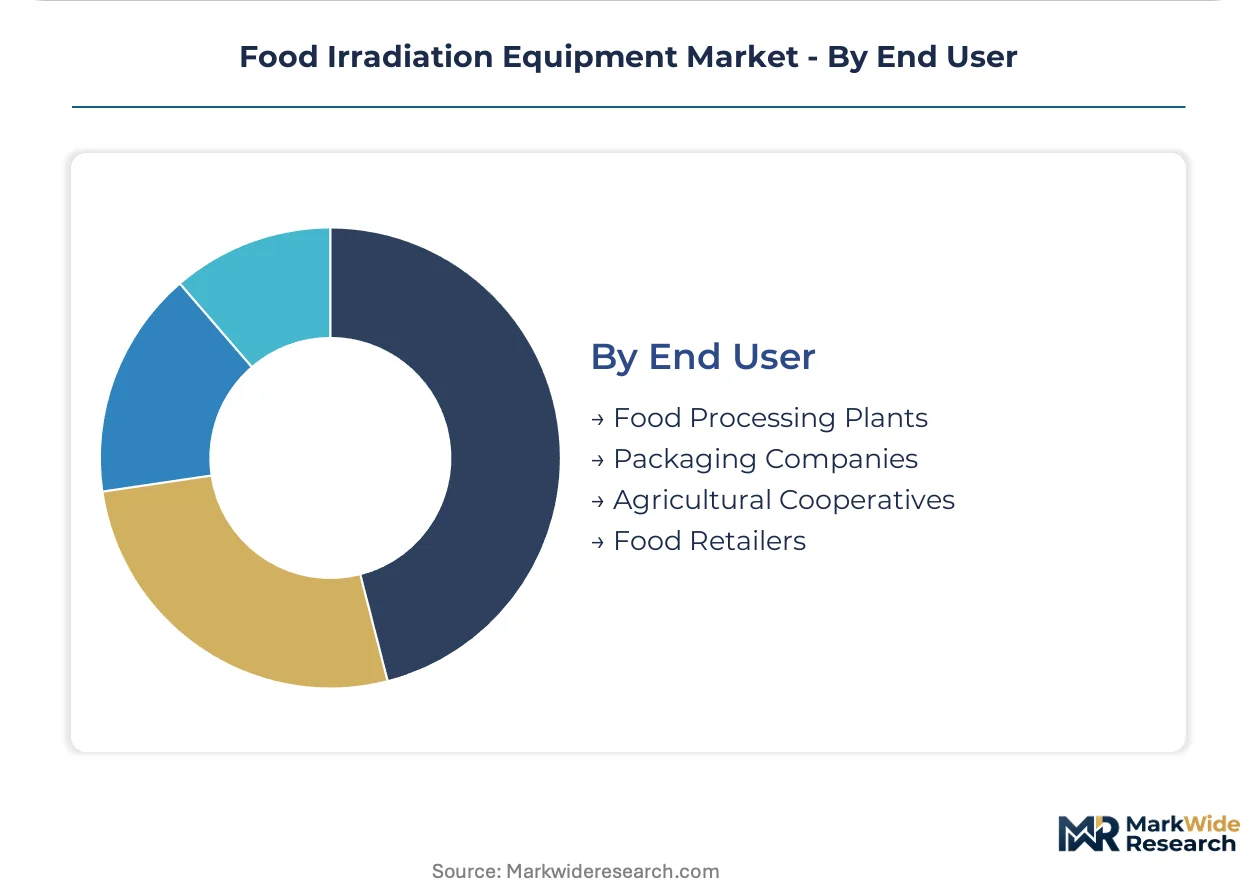
End User:
Margin structure and capital access determine whether processors own capacity or access contract sterilization networks.
- Food Processing Plants:Large meat packers and spice grinders favor in-house electron beam systems for HACCP control and throughput certainty. Tyson Foods and Cargill-scale operators in the United States justify shielding infrastructure investments through volume economics.
- Packaging Companies:Pre-treatment of modified atmosphere films and polymer structures addresses EFSA migration concerns. European spice exporters are integrating packaging qualification with dedicated irradiation lines.
- Agricultural Cooperatives:Pooled procurement of batch gamma capacity serves smallholder mango and papaya exporters. Mexican cooperative networks access Sterigenics contract services for US-bound shipments.
- Food Retailers:Private-label processors and ready-to-eat meal suppliers deploy irradiation for brand protection. Limited direct equipment ownership; predominant reliance on toll processing arrangements.
Food Processing Plants dominate capital deployment. Agricultural Cooperatives represent the underserved expansion frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized accelerator technicians and cobalt-60 logistics specialists concentrate in regions with mature nuclear infrastructure and established food processing corridors. Their expertise anchors equipment deployment decisions and maintenance reliability.
United States
USDA-FSIS enforcement of HACCP-linked pathogen controls drives electron beam procurement at inspected meat and poultry facilities. FDA 21 CFR 179.26 governs permissible irradiation doses and labeling requirements for commercial food products. Chicago-area contract sterilization hubs service regional meat processors through Sterigenics-operated gamma and electron beam networks.
Germany
REACH documentation burdens for radioactive source transport compress gamma irradiator economics across European supply chains. ECHA frameworks mandate expanded handling protocols for cobalt-60 logistics that operators must integrate. Bavarian spice processing clusters near Nuremberg are piloting X-ray hybrid configurations to satisfy EFSA migration standards for polymer packaging.
India
FSSAI implementation of Codex-aligned irradiation standards creates equipment demand as domestic cold chain infrastructure expands. The national food regulator validates dose protocols for microbial decontamination of spices and agricultural exports. Mumbai-port adjacent processing hubs in Maharashtra are installing conveyor-integrated electron beam systems for cardamom and turmeric shipments to EU markets.
Australia
Phytosanitary treatment requirements for mango and stone fruit exports to Japan and Korea drive gamma facility construction near Queensland growing regions. METI import standards mandate quarantine verification without chemical residues. Brisbane-area irradiation capacity anchors Pacific trade corridors for horticultural exporters seeking Asian market access.
Canada
Health Canada regulations govern source security protocols for aging cobalt-60 installations with dry-storage architecture. The national health regulator oversees refueling cycle coordination with reactor operators. Ontario-based food processors rely on Nordion-sourced isotope logistics for pathogen reduction in ready-to-eat meat products.
Food Irradiation Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment manufacturing and contract sterilization services. Market structure tilts toward consolidation at the isotope supply tier while fragmenting across regional service networks. Three archetypes dominate: reactor-linked isotope suppliers, accelerator manufacturers with electrical engineering heritage, and multi-site contract sterilization operators. Capacity expansion and strategic partnerships constitute the primary competitive moves as technology substitution accelerates.
Among North American service providers, STERIS Isomedix Services and Sterigenics International occupy positions spanning multi-site electron beam and gamma capacity. Nordion Inc. anchors the isotope logistics tier that sustains gamma irradiator operator networks. These three entities exemplify the bifurcation between captive processing infrastructure and outsourced contract sterilization arrangements that processors navigate based on scale and capital access.
| Leading Market Players |
|---|
| STERIS Isomedix Services |
| Sterigenics International |
| Nordion Inc. |
| Sadex Corporation |
| Food Technology Service Inc. |
| Gray Star Inc. |
| Ionisos SA |
| Scantech Sciences Inc. |
| Mevex Corporation |
| Others |
Supply & Pricing Matrix
REACH compliance documentation for cobalt-60 transport gates qualified supplier status and premium-tier service pricing across European food irradiation networks. Processors lacking certified logistics partners face exclusion from gamma-based contract sterilization arrangements, compressing their sourcing options to higher-cost electron beam alternatives.
Pricing Analysis
The bundled-versus-unbundled service split separates turnkey electron beam installations from cobalt-60 source leasing arrangements with separate handling fees. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in mid-scale gamma capacity is intensifying because reactor refueling delays extend source availability premiums. Smallholder agricultural cooperatives exhibit highest price sensitivity, while USDA-inspected meat packers prioritize throughput certainty over unit economics.
Supply Chain Analysis
Accelerator technician scarcity in United States and German manufacturing geographies constrains production ramp rates for high-voltage electron beam systems. Supply concentrates in Canada for cobalt-60 isotope processing, Belgium for sealed source fabrication, and the United States for accelerator assembly. Raw material dependencies span high-purity cobalt, specialized high-voltage ceramics, and radiation-hardened conveyor components. Single-source vulnerability in aging nuclear reactor networks creates sourcing risk for gamma irradiator operators. Distribution runs through Nordion-coordinated isotope logistics and Sterigenics-operated regional service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in electron beam system manufacturing as modularization reduces civil infrastructure costs and opens mid-tier processor segments. The shift from radioactive source management to electrical infrastructure investment favors suppliers with captive high-voltage engineering capabilities.
For Market Incumbents: Deploy backward integration into high-voltage accelerator component manufacturing to secure margin control against specialist electrical engineering suppliers. Incumbents should consolidate regional service networks before modular electron beam adoption fragments contract sterilization markets. Electron beam throughput advantages threaten gamma-dominant positioning; STERIS Isomedix and Sterigenics must anchor multi-technology capacity to retain processor relationships. For New Entrants and Emerging Players: Containerized electron accelerator design offers entry into Indian and Vietnamese spice processing markets previously closed by civil construction barriers. New entrants should target port-adjacent processing hubs in Maharashtra and Ho Chi Minh City corridors where FSSAI and Codex-aligned standards are accelerating equipment procurement. A technology-first wedge emerges through skid-mounted deployment partnerships with regional engineering firms lacking accelerator expertise. For Investors and Strategic Acquirers: Roll-up economics work for regional contract sterilization operators because USDA-inspected facility scale determines captive-versus-outsourced procurement decisions that fragment ownership patterns. The acquisition target archetype is mid-scale gamma-dependent service providers with established processor relationships and convertible electron beam upgrade paths. Watch cobalt-60 reactor decommissioning announcements as inflection indicators for accelerated technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Accelerator Deployment | Containerized electron beam units bypass concrete bunker construction timelines for Indian spice exporters. |
| Multi-Technology Capacity Expansion | Sterigenics and STERIS Isomedix anchor positioning through combined gamma and electron beam networks. |
| Isotope Logistics Integration | Nordion's cobalt-60 supply chain control sustains gamma operator reliability despite reactor aging. |
| Packaging Qualification Partnerships | EFSA-aligned migration testing secures European market access for irradiated spice shipments. |
| Technician Training Program Development | Specialized high-voltage engineering pipelines address accelerator maintenance scarcity in food processing regions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate equipment procurement patterns across food processing segments. Primary engagement captured plant engineering directors at USDA-inspected meat facilities, procurement leads at spice export cooperatives, and regulatory affairs specialists navigating FDA 21 CFR 179.26 compliance. Secondary validation drew from FDA docket records, USDA-FSIS inspection databases, EFSA scientific panel opinions, and FSSAI notification filings. Bottom-up facility-level capacity estimates and top-down market sizing reconstructions were cross-checked for convergence.
Historical reference periods anchored volume and value trajectories across the projection horizon, with CAGR derivation reflecting technology substitution rates and regulatory enforcement intensity. Segmentation modeling captured equipment type, processing technology, application purpose, and end-user scale dimensions. Industry-specific forecast inputs incorporated cobalt-60 reactor refueling schedules and electron beam energy efficiency benchmarks from accelerator manufacturer disclosures.
The model holds under steady regulatory enforcement and isotope supply continuity; deviation in reactor decommissioning timelines or REACH documentation expansion would shift technology adoption curves. Forecasts reflect documented assumptions regarding FSSAI implementation pace and USDA HACCP inspection density. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Ice Maker Machines Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Food-Grade Mixing Tank Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market