
 Europe Safety Switches Market | 2026-2036
Europe Safety Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Safety Switches Market Foresight
The EU Green Deal is decoupling safety switch procurement from pure cost metrics toward lifecycle carbon accountability. Rockwell Automation leverages its integrated safety platform to anchor premium positioning across German automotive OEM accounts. ABB Ltd. competes through IEC 62061-certified architectures that dominate retrofit installations in Nordic paper mills. Schneider Electric extends its channel control via embedded installation partnerships with French system integrators.
Safety switches are electromechanical or electronic control devices designed to interrupt power circuits when protective guards open, pull cords activate, or emergency stops engage, typically rated for IP65-IP69K ingress protection and SIL 3/PLe functional safety integrity. Their primary purpose is preventing operator injury by ensuring machinery cannot operate while access points are compromised. Emergency stop switches capture the deepest margin pools due to mandatory redundancy requirements in high-risk environments, while interlock switches sustain volume leadership across automated manufacturing lines. Fixed installation configurations lead the installation type dimension, though modular formats are gaining specification in flexible production cells serving batch-oriented Food & Beverage operations.
CE marking under the EU Machinery Directive shapes baseline product standards, while ECHA REACH compliance restricts hazardous substances in contact materials, and the EU AI Act introduces emerging conformity obligations for smart safety systems with diagnostic connectivity. National regulators including Germany's KBA and France's ANSM enforce sector-specific adaptations of these frameworks. Stakeholders must monitor whether the EU's forthcoming machinery regulation revision will mandate built-in safety communication protocols, reshaping R&D allocation across the supplier base.
Market Dynamics
The EU Machinery Directive revision is forcing safety switch architectures toward built-in communication protocols, compelling manufacturers to redesign electromechanical platforms for diagnostic connectivity before the regulatory deadline crystallizes.
Growth Catalysts
- Food & Beverage automation:Processing lines across Germany and France are expanding gate switch installations to meet hygienic design requirements under EC 1935/2004 food contact material rules.
- CE marking enforcement:Member state market surveillance authorities are tightening conformity assessment penalties, driving replacement demand for non-compliant legacy interlock systems.
- SIL 3/PLe certification:Functional safety integrity ratings are becoming mandatory specification criteria in Nordic paper mill retrofits, accelerating certified product adoption.
Market Restraints
- Stainless steel input costs:IP69K-rated housing materials face price volatility from nickel supply concentration in Indonesian processing facilities.
- Semiconductor dependency:Smart safety switches with diagnostic electronics remain exposed to foundry capacity constraints concentrated in East Asian manufacturing hubs.
- REACH substance restrictions:ECHA authorization lists are eliminating certain contact material chemistries, forcing reformulation cycles that extend product development timelines.
Strategic Opportunities
- Eastern European manufacturing expansion:Polish and Czech automotive component suppliers are undersupplied with IEC 62061-certified emergency stop devices relative to Western European penetration rates.
- EU AI Act compliance services:Smart safety systems with predictive maintenance algorithms create adjacent revenue streams through conformity documentation for machine learning-enabled diagnostics.
- Wireless safety communication:Integration of IO-Link Wireless with traditional interlock hardware opens specification opportunities in flexible production cells serving batch-oriented pharmaceutical packaging.
Industry Challenges
- Functional safety engineering scarcity:TÜV-certified SIL assessor availability constrains manufacturer R&D throughput across German industrial automation corridors.
- Legacy system integration:Hardwired safety relay architectures in decades-old French metalworking equipment resist seamless migration to networked safety switch topologies.
- Multi-standard certification complexity:Simultaneous compliance with EN ISO 13849, IEC 62061, and emerging EU machinery regulation drafts fragments testing resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Safety Switches Market |
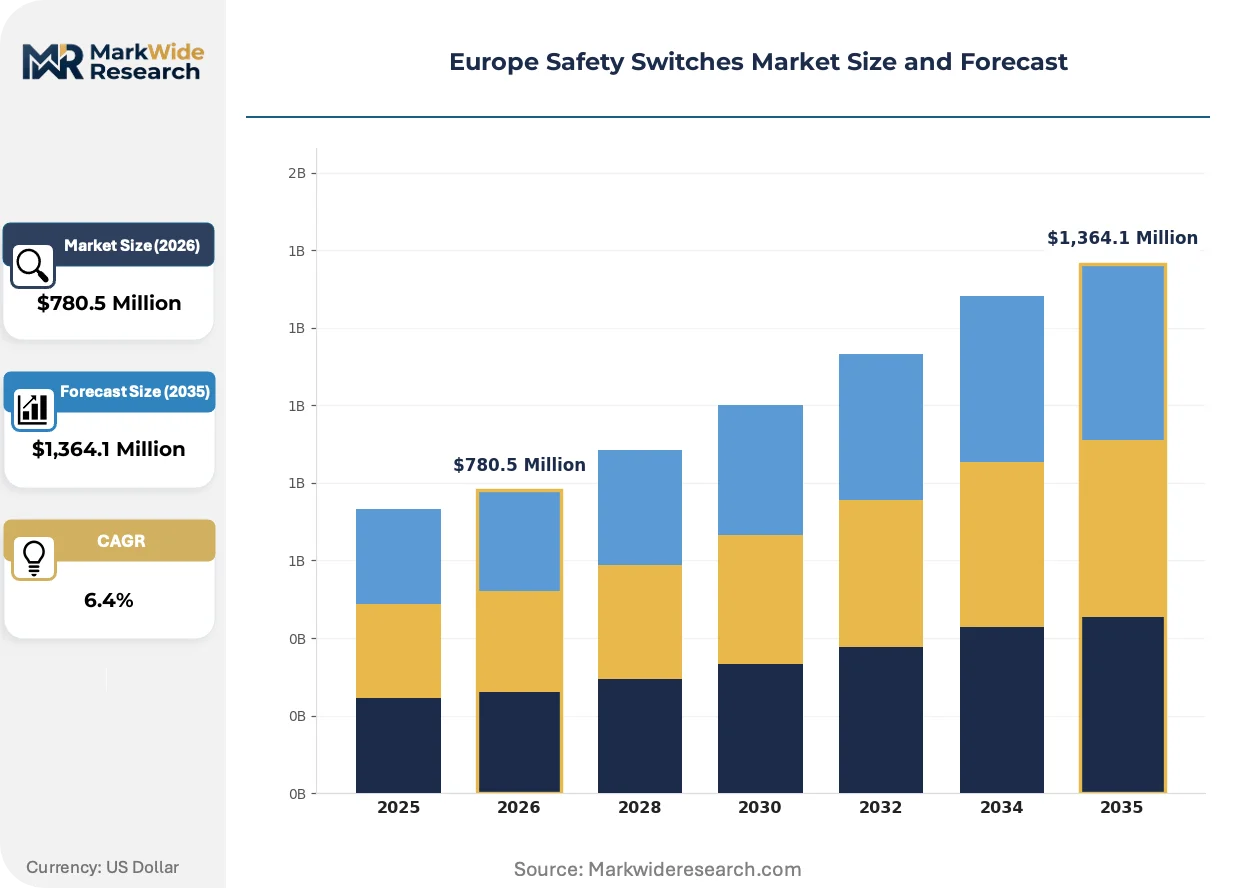
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,364.1 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interlock Switches, Gate Switches, Pull Switches, Emergency Stop Switches Industry Vertical: Automation, Manufacturing, Oil & Gas, Food & Beverage Installation Type: Fixed Installation, Portable Installation, Embedded Installation, Modular Installation End User: OEMs, Tier-1 Suppliers, System Integrators, Maintenance Providers |
| Companies Covered | Rockwell Automation, Idem Safety Switches, ABB Ltd., EUCHNER GmbH, Eaton, Schmersal GmbH & Co. KG, Schneider Electric, Pilz GmbH & Co. KG, SICK AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Safety Switches Market Shifts & Advancements
Safety switch hardware is converging with industrial communication protocols, compressing the boundary between electromechanical reliability and data-driven diagnostics. This convergence is restructuring supplier capabilities and buyer evaluation criteria across European manufacturing.
Modular interlock platforms with standardized mounting interfaces and field-replaceable contact blocks are modularizing safety switch deployment in automotive body shops. BMW and Volkswagen tier-one suppliers are specifying these configurations to reduce changeover downtime between vehicle model generations. The approach is compressing lifecycle costs while enabling rapid reconfiguration of robotic cell perimeters without complete system replacement.
REACH substance restrictions under ECHA authorization procedures are eliminating cadmium-based contact plating from safety switch manufacturing. The regulation is forcing migration to silver-nickel or gold-flash alternatives that alter electrical endurance ratings. German component suppliers are responding with accelerated wear-testing protocols to validate alternative metallurgies under high-cycle Food & Beverage applications.
Specification authority is migrating from maintenance departments to corporate EHS functions with centralized procurement mandates. This consolidation is displacing distributor-led technical selling in favor of direct OEM engagement and framework agreements with integrated automation vendors. The shift is most pronounced in Benelux chemical processing, where multinational operators standardize safety architectures across plant networks.
Europe Safety Switches Market Segmentation
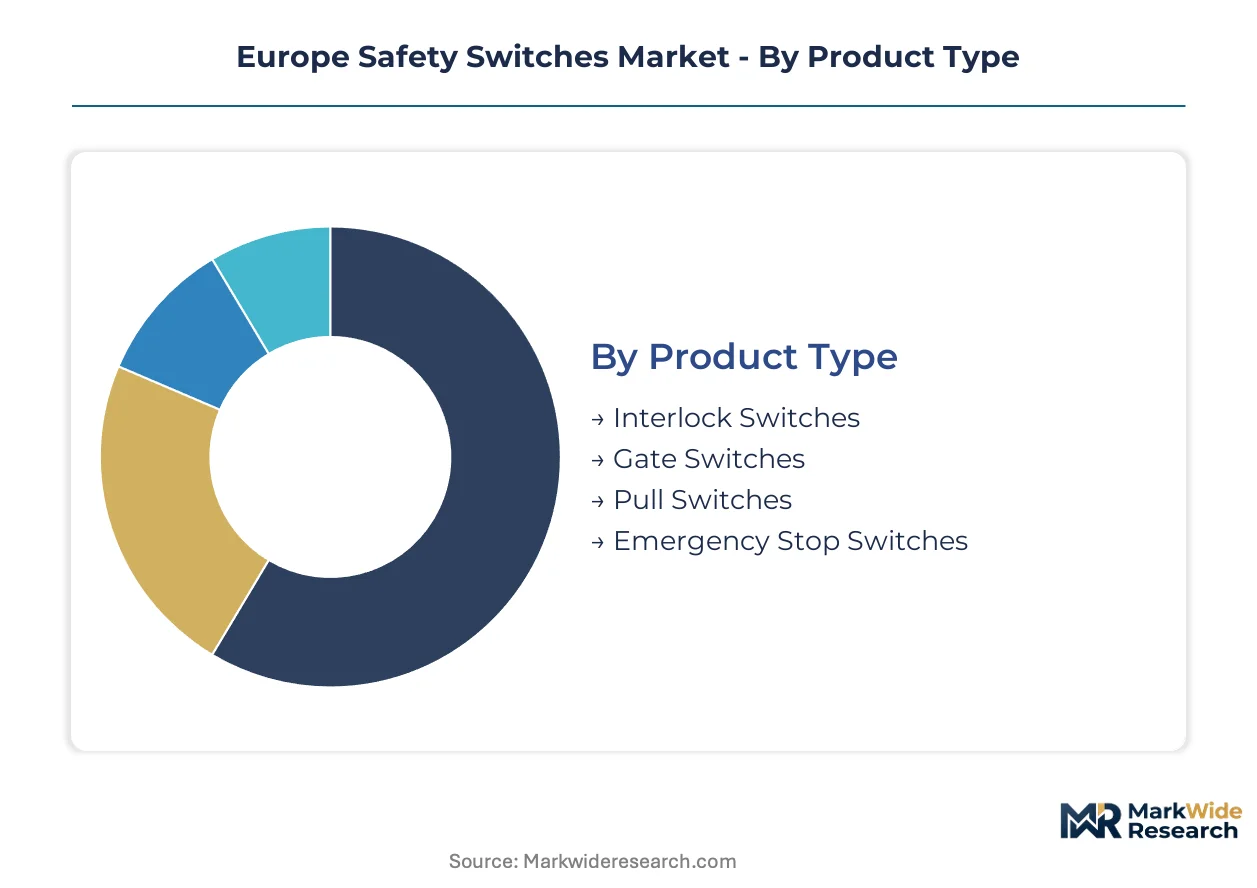
Safety switch procurement in Europe fragments across four distinct dimensions, each reflecting different technical requirements and buyer authority structures. Understanding these segment boundaries clarifies where specification power resides and which integration architectures command premium positioning.
Product Type:
Standalone interlock devices dominate legacy machinery retrofits, while embedded emergency stop modules anchor new machine designs with built-in diagnostic connectivity.
- Interlock Switches:Electromechanical devices with positive-opening contacts that force circuit interruption when guards separate from machinery frames. German automotive body shops specify these for robotic cell perimeters where frequent access cycles demand mechanical reliability over electronic complexity.
- Emergency Stop Switches:Redundant-contact mushroom-head devices with mandatory latching mechanisms and high-visibility coloring under EN ISO 13850. French chemical processors prioritize these for SIL 3-rated zones where operator panic response must override all automated sequences.
- Gate Switches:Hinged-guard monitoring devices with adjustable actuators for misalignment tolerance.
- Pull Switches:Cable-actuated devices spanning conveyor lengths for distributed emergency access.
Volume placements concentrate in Interlock Switches; the faster expansion belongs to Emergency Stop Switches.
Industry Vertical:
Cost tiers separate process industries with extended replacement cycles from discrete manufacturing with higher switch turnover rates.
- Automation:Integrated safety platforms combining switches with programmable controllers and networked diagnostics. German OEMs drive specification here, embedding switches directly into robotic end-effector guarding systems.
- Food & Beverage:Hygienic-design switches with IP69K ratings and smooth surfaces preventing bacterial accumulation under EC 1935/2004. Danish dairy processors and Dutch meatpacking operations lead adoption of stainless steel housings with crevice-free construction.
- Manufacturing:General-purpose interlock applications across metalworking and assembly operations.
- Oil & Gas:Explosion-proof variants for hazardous atmosphere zones under ATEX Directive requirements.
Automation captures the deepest margin pools; Food & Beverage climbs the fastest on regulatory hygiene mandates.
Installation Type:
Customer type differentiation separates permanent infrastructure investments from reconfigurable production setups.
- Fixed Installation:Hardwired switches mounted directly to machinery frames with dedicated cable runs. Italian packaging machinery builders favor these for high-volume standardized equipment with minimal reconfiguration needs.
- Modular Installation:Standardized mounting interfaces with field-replaceable contact blocks enabling rapid cell reconfiguration. Polish automotive component suppliers adopt these to accommodate model-year changeovers without complete safety system replacement.
- Portable Installation:Mobile switches for temporary guarding during maintenance or construction.
- Embedded Installation:Switches integrated directly into machine control enclosures at manufacturing stage.
Fixed Installation retains volume leadership; Modular Installation gains share fastest on flexible manufacturing demand.
End User:
Supply concentration varies sharply between specification authorities with design influence versus procurement executors with limited technical discretion.
- OEMs:Original equipment manufacturers with platform-level safety architecture decisions affecting thousands of installed units. Siemens and Bosch Rexroth affiliates in Germany specify safety switches at machine design phase, locking in component relationships for entire product lifecycles.
- System Integrators:Engineering firms assembling complete production lines from multiple vendor equipment. French integrators serving Benelux chemical processors increasingly demand switches with standardized communication protocols to reduce commissioning complexity.
- Tier-1 Suppliers:Component manufacturers integrating switches into subsystems for OEM delivery.
- Maintenance Providers:Service contractors replacing failed units with limited redesign authority.
System Integrators dominate new project placements; OEMs anchor the steepest expansion trajectory through design-in capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors Europe's safety switch specification activity, with OEM engineering centers in Essen and Dortmund driving design-in decisions for machinery exported across the continent.
Germany
Automotive OEMs in Stuttgart and Munich specify integrated safety platforms for robotic assembly cells. KBA enforces type approval standards for machinery safety components. Bavarian automation clusters concentrate emergency stop device procurement for electric vehicle battery line expansions.
France
Chemical processors in Lyon and pharmaceutical packagers in Paris prioritize SIL 3-certified gate switches for high-risk zones. ANSM adapts EU Machinery Directive requirements for sector-specific safety implementations. The Île-de-France region concentrates system integrator activity serving Benelux multinational operators.
Italy
Packaging machinery builders in Bologna and Modena favor fixed-installation interlock switches for standardized equipment runs. CE marking surveillance intensified under national market authority enforcement since 2023. Emilia-Romagna's automotive component suppliers accelerate modular safety switch adoption for model-year flexibility.
Poland
Automotive component manufacturing in Silesia and Greater Poland generates undersupplied demand for IEC 62061-certified emergency stop devices. EU cohesion fund investments in industrial modernization tighten machinery safety compliance timelines. Wrocław's emerging automation sector attracts Western European safety switch distributors seeking Eastern European expansion.
Netherlands
Food processing operations in North Brabant specify IP69K-rated hygienic switches under EC 1935/2004 food contact mandates. Dutch dairy cooperatives drive stainless steel housing procurement for washdown environments. The Eindhoven-Tilburg corridor concentrates embedded safety switch integration into OEM equipment for export markets.
Europe Safety Switches Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and diagnostic capability dimensions. The vendor base stratifies between integrated automation platforms and specialized electromechanical component suppliers. Three archetypes dominate: diversified industrial conglomerates with safety divisions, dedicated functional safety specialists, and regional electromechanical fabricators. Competitive moves concentrate on embedded installation partnerships and SIL assessor certification capacity expansion.
Among diversified industrial conglomerates, Rockwell Automation and ABB Ltd. exemplify platform-level positioning through integrated safety architectures. Schneider Electric occupies a comparable tier with channel control strategies. Dedicated specialists including Pilz GmbH & Co. KG and SICK AG represent the functional safety purist archetype. Schmersal GmbH & Co. KG anchors German mid-cap fabrication capabilities. EUCHNER GmbH and Idem Safety Switches sit within specialized interlock and emergency stop device segments.
| Leading Market Players |
|---|
| Rockwell Automation |
| Idem Safety Switches |
| ABB Ltd. |
| EUCHNER GmbH |
| Eaton |
| Schmersal GmbH & Co. KG |
| Schneider Electric |
| Pilz GmbH & Co. KG |
| SICK AG |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between SIL 3/PLe-rated platforms and unverified commodity interlocks manifests in both pricing premiums and supply chain tiering across European manufacturing corridors. German automotive OEMs anchor value-based procurement for certified architectures, while price-sensitive maintenance providers in Southern Europe source through distributor channels with minimal technical validation.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for integrated safety platforms serving continuous-process industries. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels reflects SIL rating stratification and diagnostic capability bundling. Cost compression in economy tiers intensifies as Asian imports penetrate replacement markets through online industrial distributors. System integrators demonstrate lowest price sensitivity due to total-project margin absorption, while independent maintenance contractors face acute pressure from procurement centralization mandates.
Supply Chain Analysis
Stainless steel feedstock rests on Indonesian nickel processing concentration and German specialty alloy fabrication. Electromechanical contact materials draw from Chinese rare earth processing and Swedish precision metallurgy. Semiconductor components for diagnostic-enabled switches hinge on Taiwanese foundry capacity. Single-source vulnerability concentrates in SIL assessor certification capacity at German TÜV laboratories. Distribution runs through authorized distributor networks with technical pre-sales support, though direct OEM engagement is displacing channel intermediaries in high-volume automotive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European safety switch competition is becoming a vertical-integration race, with control over SIL certification capacity and embedded installation partnerships serving as the decisive upstream and downstream levers. Players capturing assessor relationships and OEM design-phase influence will consolidate specification authority.
For Market Incumbents: Anticipate margin compression from modular platform competitors by locking in multi-year embedded installation partnerships with German automotive OEMs. Prioritize TÜV-certified assessor capacity expansion to constrain competitor R&D throughput. Defensive patent positioning around IO-Link Wireless integration protocols will delay follower entry into flexible manufacturing segments. For New Entrants and Emerging Players: Capture specification authority in Polish and Czech automotive component manufacturing, where IEC 62061-certified emergency stop penetration lags Western European saturation. Target system integrator channel partnerships in France's chemical processing corridor, where standardized communication protocol demand outpaces incumbent response capacity. Lead with EU AI Act compliance documentation services as a differentiated entry wedge. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking functional safety capability fill-ins. Five-to-ten year viability favors specialists with captive SIL assessor relationships and embedded OEM design wins over pure component fabricators. Monitor EU machinery regulation revision timing as the critical inflection signal for communication-protocol mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Metallurgy | Captive silver-nickel alloy supply secures REACH-compliant formulations against ECHA authorization volatility. |
| SIL Assessor Certification Expansion | TÜV-certified engineering capacity constrains competitor product development timelines across German automation corridors. |
| Embedded Installation Partnership | OEM design-phase capture at Siemens and Bosch Rexroth affiliates locks in lifecycle component relationships. |
| IO-Link Wireless Platform Launch | Diagnostic connectivity integration opens specification in batch-oriented pharmaceutical packaging cells. |
| Eastern European Distribution Expansion | Wrocław hub establishment addresses undersupplied Polish automotive component demand for certified emergency stop devices. |
Research Methodology
Document review covered EU Machinery Directive implementation guidance, ECHA REACH authorization lists, and TÜV functional safety certification databases, complemented by interviews with plant engineers at German automotive OEMs, maintenance directors at French chemical processors, procurement leads at Danish dairy cooperatives, and channel managers at industrial distributors. Secondary validation drew from CE marking surveillance reports, IEC standards documentation, and customs trade flow data. Bottom-up demand modeling and top-down supply capacity estimates underwent cross-triangulation.
Market size and growth trajectories across the projection horizon reflect segmented modeling by product type, installation configuration, industry vertical, and end-user authority structure. CAGRs derive from regression analysis against machinery capital expenditure cycles and regulatory compliance deadline clustering. Forecast inputs incorporate EU cohesion fund industrial modernization disbursement patterns and automotive platform electrification timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU machinery regulation revision scope, nickel price volatility from Indonesian export policy shifts, and foundry capacity allocation at Taiwanese semiconductor manufacturers. A small set of triggers warrants ongoing watch: ECHA substance restriction list expansion, KBA type approval standard updates, and Tier 1 supplier consolidation in German automotive supply chains.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market
Safety Equipment and Personal Protective Equipment (PPE)
Wearable Airbag Belt Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Explosion-Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market