
 Process Safety System Market | 2026-2036
Process Safety System Market Size, Share, and Industry Trends Forecast 2026-2036
Process Safety System Market Outlook
Advanced fiber-optic sensing is recalibrating flame and gas detection economics by displacing conventional electrochemical sensors in high-noise process environments. Honeywell International leverages its distributed control system installed base to bundle safety instrumented system upgrades across downstream refineries. ABB anchors European project engineering capabilities for offshore platform safety packages. Emerson Electric differentiates through embedded analytics in its emergency shutdown system portfolio.
A process safety system comprises engineered hardware and software layers designed to detect abnormal operating conditions, execute automatic shutdown sequences, and mitigate hazardous energy release, typically achieving safety integrity levels from SIL 1 through SIL 4 per IEC 61508 certification protocols. Safety instrumented systems occupy the largest product category due to mandatory retrofit cycles in legacy chemical manufacturing plants, while fire and gas detection segments are expanding fastest in floating production storage and offloading vessel deployments. Oil and gas end users command the deepest margin pools because project specifications demand vendor certification to IEC 61511 and API RP 754 standards.
The EPA Risk Management Program and OSHA Process Safety Management standard shape United States demand by mandating hazard analysis refresh cycles and mechanical integrity programs for covered processes. IEC 61508 and IEC 61511 standards govern European and Asia-Pacific market access by defining safety lifecycle requirements from conceptual design through decommissioning. Functional safety technology segments face escalating third-party certification burdens as notified bodies tighten interpretation of systematic capability requirements. Stakeholders must monitor evolving cybersecurity annexes to IEC 62443 as digital integration exposes safety networks to remote attack vectors.
Market Dynamics
Refinery operators face mounting pressure to retrofit legacy safety instrumented systems as IEC 61511 certification deadlines compress project timelines and force capital reallocation toward compliance-heavy automation infrastructure.
Growth Catalysts
- OSHA Process Safety Management:United States refineries must complete hazard analysis refresh cycles every five years, forcing continuous investment in automated shutdown systems and mechanical integrity monitoring hardware.
- Floating production storage and offloading vessels:Deepwater oil field development off Brazil and West Africa is expanding fire and gas detection deployments in marine environments where conventional sensor arrays fail.
- Embedded analytics integration:Safety instrumented systems now incorporate predictive diagnostics that reduce spurious trip rates and extend proof test intervals for high-availability process units.
Market Restraints
- Specialized engineering labor scarcity:Functional safety certification programs produce fewer qualified TÜV Rheinland or exida-certified engineers than project pipelines demand, extending commissioning timelines.
- Semiconductor supply concentration:Safety system logic solvers depend on industrial-grade microcontrollers sourced disproportionately from Taiwanese foundries, exposing delivery schedules to geopolitical friction.
- IEC 62443 cybersecurity annexes:Emerging requirements for safety network security certification add engineering hours and third-party validation costs without direct productivity returns.
Strategic Opportunities
- India's petroleum refining expansion:Reliance Industries and Indian Oil Corporation are building mega-refineries with integrated safety systems that bypass legacy retrofit constraints entirely.
- Hydrogen economy infrastructure:Electrolyzer and ammonia synthesis facilities require flame detection adapted for invisible hydrogen flames, opening specialized sensor development pathways.
- Carbon capture and storage:CO2 compression and pipeline safety systems represent greenfield application territory with distinct pressure-boundary and leak-detection specifications.
Industry Challenges
- SIL verification calculation complexity:Quantitative reliability analysis for safety instrumented functions demands specialized software tools and statistical competency that many EPC contractors lack in-house.
- Legacy DCS integration friction:Brownfield sites running proprietary communication protocols face protocol gateway engineering and real-time performance validation that extend project risk windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Safety System Market |
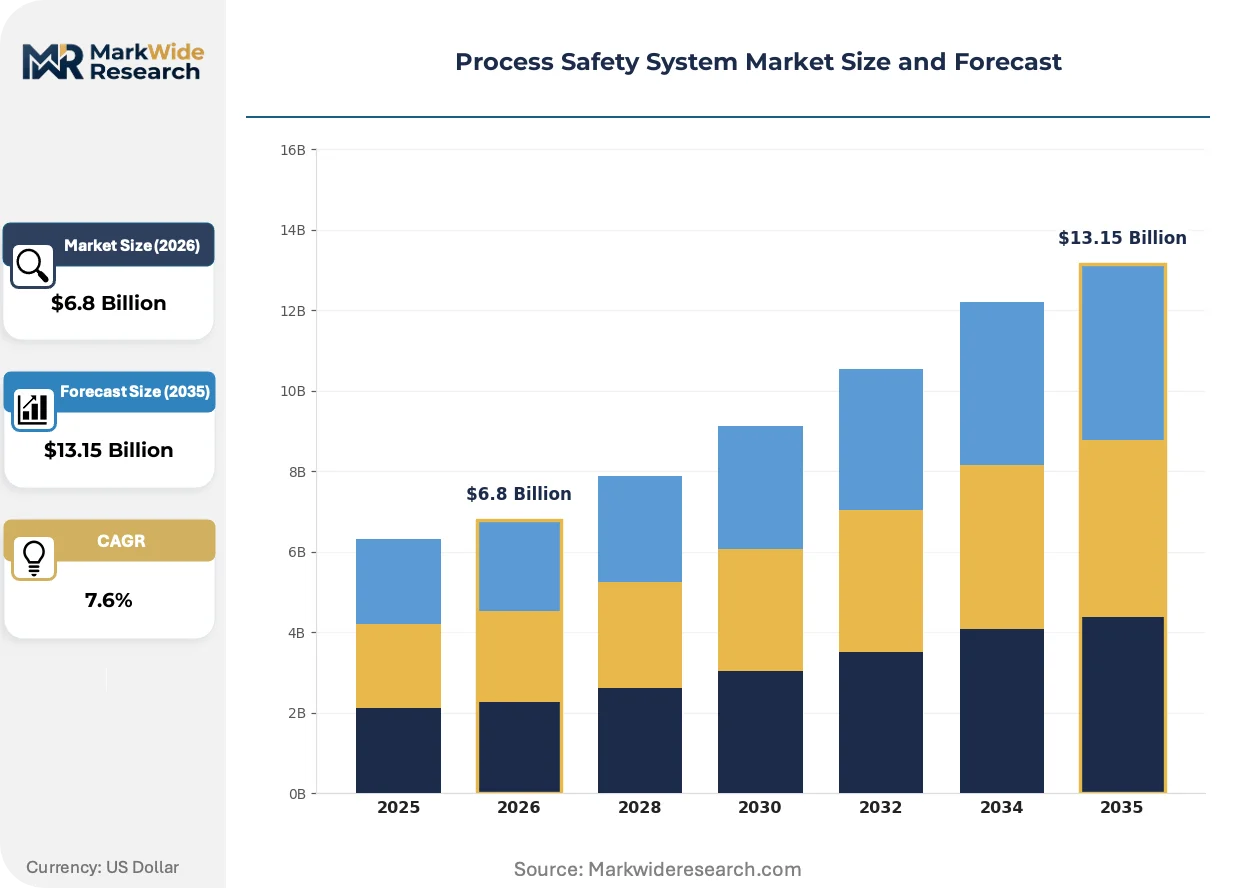
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Instrumented Systems, Emergency Shutdown Systems, Fire & Gas Systems, Process Control Systems End User: Oil & Gas, Chemical Manufacturing, Power Generation, Pharmaceuticals Technology: Functional Safety, Real-Time Monitoring, Risk Assessment, Compliance Management Application: Hazardous Area Safety, Process Automation, Risk Management, Operational Safety |
| Companies Covered | Honeywell International, ABB, Rockwell Automation, Emerson Electric, Schneider Electric, Yokogawa Electric, HIMA Paul Hildebrandt, Siemens, Bureau Veritas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Safety System Market Strategic Shifts
Fiber-optic sensing architectures are rewriting detection economics while regulatory bodies accelerate certification burdens. Buyers now demand predictive capabilities that compress maintenance windows and reduce unplanned outages.
Multispectral infrared flame detection is converging with machine vision algorithms to discriminate between actual process fires and welding arcs or solar glint in high-UV refinery environments. Offshore platform operators in the North Sea and Gulf of Mexico are deploying these fused systems to cut false alarm rates below 0.1 per detector per year. The convergence is compressing insurance premium negotiations and enabling manned platform staffing reductions during hot work campaigns.
EPA Risk Management Program amendments are mandating third-party compliance audits and root cause investigation protocols for catastrophic release scenarios. Chemical manufacturers must now document safety system independence from basic process control systems in greater technical detail. Large integrated refineries in Texas and Louisiana are responding by segregating safety network architectures and hiring dedicated functional safety managers.
Refinery procurement departments are unbundling safety system hardware from long-term service contracts and competing maintenance agreements separately. Integrated automation vendors face margin pressure as buyers source logic solvers from one supplier and engineering services from specialty system integrators. This pattern is most pronounced in the United States, where independent EPC firms have built IEC 61511 competency centers that challenge OEM service organizations.
Process Safety System Market Segmentation
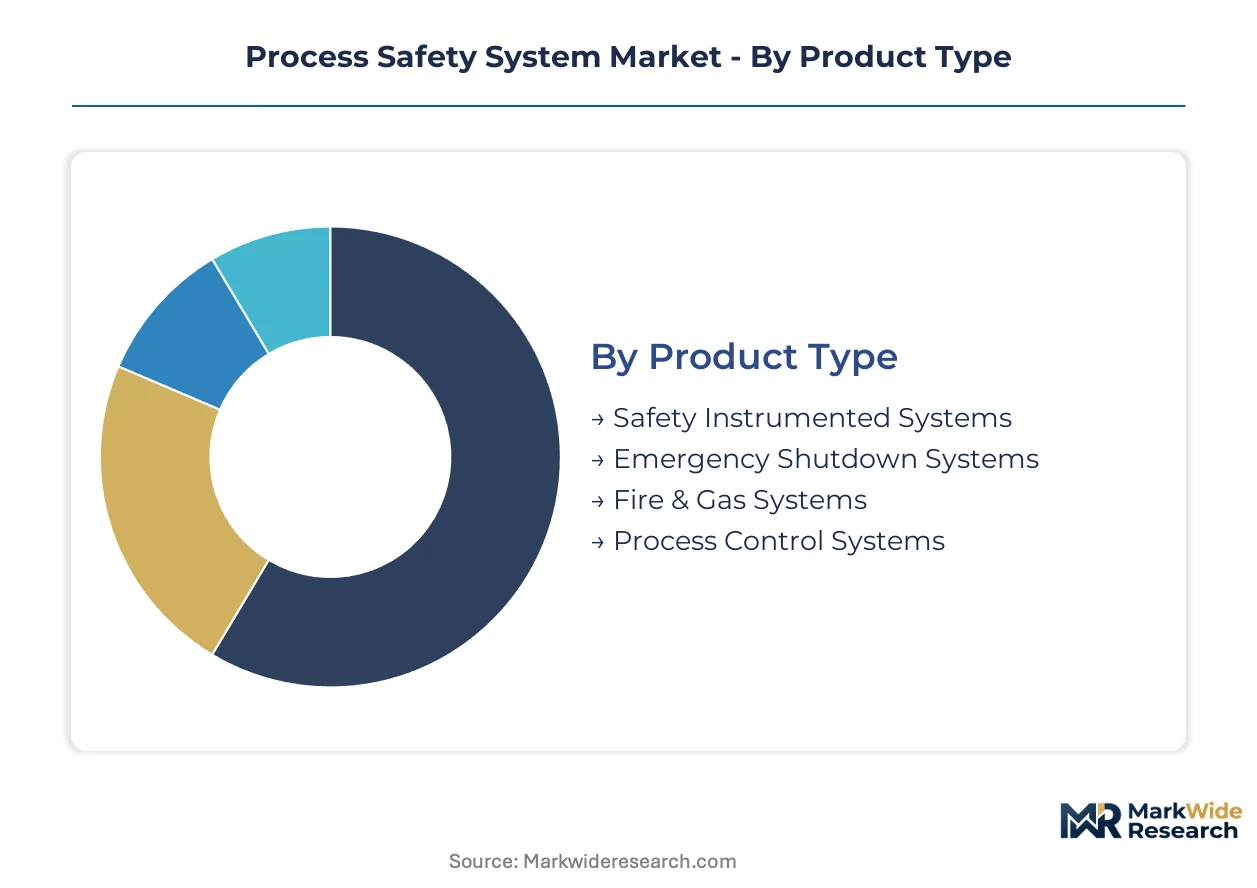
Process safety system procurement decisions hinge on matching SIL certification levels to specific hazard scenarios, with buyers weighing retrofit compatibility against greenfield integration economics. Segmentation reveals how technology maturity and regulatory exposure drive divergent investment patterns across industrial verticals.
Product Type:
Standardization dominates high-volume categories while engineered-to-order configurations persist in specialty safety functions requiring SIL 3 or SIL 4 certification.
- Safety Instrumented Systems:Logic solvers, sensors, and final elements configured as safety instrumented functions achieve defined safety integrity levels through redundant architectures. Chemical manufacturers in the United States and Germany dominate demand as IEC 61511 retrofit deadlines force replacement of pneumatic relay-based systems installed before functional safety standards took effect.
- Fire & Gas Systems:Detection arrays combining point and open-path sensors with voting logic to initiate suppression or isolation sequences. Floating production storage and offloading vessel deployments off Brazil and West Africa are expanding fastest as marine environments degrade conventional electrochemical sensors.
- Emergency Shutdown Systems:Dedicated final control elements and isolation valves engineered for fail-safe positioning within specified safety time requirements.
- Process Control Systems:Basic process control layers segregated from safety functions per IEC 61511 independence requirements.
Most installed capacity flows through Safety Instrumented Systems. Expansion is steepest in Fire & Gas Systems.
End User:
Margin structures vary sharply by sector, with oil and gas commanding premium pricing for offshore certification while pharmaceutical buyers prioritize documentation intensity over hardware performance.
- Oil & Gas:Upstream, midstream, and downstream operations subject to OSHA Process Safety Management and EPA Risk Management Program mandates. Refinery operators in Texas and Louisiana represent the deepest investment pools as catastrophic release prevention regulations enforce continuous safety system refresh cycles.
- Chemical Manufacturing:Batch and continuous processes handling flammable, toxic, or reactive materials requiring layer of protection analysis documentation. German chemical clusters along the Rhine and specialty chemical producers in India are expanding fastest as regulatory harmonization accelerates functional safety adoption.
- Power Generation:Boiler protection, turbine overspeed prevention, and combustion safety applications in thermal and nuclear facilities.
- Pharmaceuticals:Containment integrity and sterile process isolation with emphasis on batch record integration and audit trail documentation.
Revenue concentrates in Oil & Gas. Chemical Manufacturing is gaining share fastest.
Technology:
Technology selection tracks the progression from prescriptive compliance toward predictive risk management, with software-enabled capabilities commanding expanding budget share.
- Functional Safety:Hardware and software engineered to IEC 61508 and IEC 61511 lifecycle requirements, spanning hazard analysis through decommissioning verification. European process industries and Japanese automotive chemical suppliers anchor demand as notified bodies tighten systematic capability interpretations.
- Real-Time Monitoring:Continuous sensor data acquisition with edge computing for anomaly detection before safety limits are breached. United States shale operators and Middle Eastern gas processing facilities are deploying fastest to compress proof test intervals and reduce spurious trips.
- Risk Assessment:Quantitative and semi-quantitative methods including HAZOP, LOPA, and QRA for safety requirement specification.
- Compliance Management:Documentation workflows, audit trail maintenance, and regulatory reporting automation.
Functional Safety captures the largest technology spend. Real-Time Monitoring is expanding most quickly.
Application:
Application scope determines whether safety systems operate as permanent engineered safeguards or as procedural controls activated during abnormal operations.
- Hazardous Area Safety:Explosion protection and ignition source management in classified zones per IEC 60079 and NFPA 70 standards. Offshore platform operators in the North Sea and Gulf of Mexico dominate procurement as zone classification complexity drives specialized engineering requirements.
- Process Automation:Integration of safety functions with distributed control architectures while maintaining independence per safety lifecycle standards. Indian mega-refinery greenfield projects and Chinese petrochemical complexes are expanding fastest by embedding safety instrumented systems in integrated automation platforms.
- Risk Management:Enterprise-level hazard identification and mitigation prioritization frameworks.
- Operational Safety:Permit-to-work systems, lockout-tagout verification, and personnel location tracking.
Hazardous Area Safety commands the largest installed base. Process Automation is climbing the fastest.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors process safety system procurement intensity, with OSHA Process Safety Management enforcement driving continuous retrofit cycles across aging refinery infrastructure.
United States
Texas and Louisiana refinery operators face compressed IEC 61511 certification deadlines that force capital reallocation toward automated shutdown systems. EPA Risk Management Program amendments mandate third-party compliance audits for catastrophic release scenarios. Houston's petrochemical corridor concentrates the deepest investment pools as integrated refineries segregate safety network architectures from basic process control layers.
Germany
Rhine River chemical clusters demand functional safety hardware engineered to IEC 61508 lifecycle requirements from conceptual design through decommissioning. ECHA chemical safety regulations harmonize with EU machinery directives to tighten systematic capability interpretations for notified body certification. BASF's Ludwigshafen complex and Bayer's Leverkusen operations anchor European demand for SIL 3 and SIL 4 safety instrumented systems.
China
Zhejiang and Jiangsu province petrochemical complexes are embedding safety instrumented systems in integrated automation platforms for greenfield refinery construction. GB standards and MIIT industrial safety mandates accelerate functional safety adoption across state-owned enterprise facilities. Ningbo-Zhoushan port's crude oil processing capacity expansion drives fire and gas detection deployments in marine loading environments.
Brazil
Pre-salt deepwater oil field development off the Santos Basin expands flame and gas detection deployments in floating production storage and offloading vessels. ANP petroleum regulator safety requirements enforce vendor certification to IEC 61511 for offshore platform packages. Rio de Janeiro's naval engineering cluster specializes in marine-rated sensor arrays that withstand high-humidity process environments.
India
Reliance Industries and Indian Oil Corporation mega-refinery construction in Gujarat bypasses legacy retrofit constraints through integrated safety system design. CEA electrical safety regulations and Petroleum Ministry hazardous facility mandates compress project timelines for domestic engineering procurement. Jamnagar's refining complex represents the largest greenfield safety instrumented system deployment in Asia-Pacific.
Process Safety System Market Competitive Environment
Strategic partnerships dominate the current landscape as specialized engineering firms build IEC 61511 competency centers that challenge original equipment manufacturer service organizations. The vendor base stratifies across three tiers: integrated automation conglomerates with distributed control system installed bases, functional safety specialists certified to TÜV Rheinland or exida standards, and independent system integrators unbundling hardware procurement from long-term maintenance agreements. Portfolio diversification and geographic expansion constitute the primary competitive vectors as buyers demand predictive diagnostics capabilities and cybersecurity-hardened safety networks.
Within the integrated automation tier, Honeywell International, ABB, and Emerson Electric exemplify archetypes that leverage legacy control system footprints to bundle safety instrumented system upgrades. These conglomerates occupy positions where embedded analytics and proof test interval compression capabilities differentiate emergency shutdown portfolios. Honeywell's North American refinery relationships anchor its downstream positioning, while ABB's European project engineering capabilities concentrate on offshore platform safety packages. Emerson's specialization in real-time monitoring architectures represents the predictive maintenance vector that reduces spurious trip rates for high-availability process units.
| Leading Market Players |
|---|
| Honeywell International |
| ABB |
| Rockwell Automation |
| Emerson Electric |
| Schneider Electric |
| Yokogawa Electric |
| HIMA Paul Hildebrandt |
| Siemens |
| Bureau Veritas |
| Others |
Value Chain & Pricing Dynamics
Refinery procurement departments unbundling safety system hardware from long-term service contracts force supply chains to fragment engineering capabilities from manufacturing scale, compressing margins on bundled offerings while elevating specialist integrator premiums.
Pricing Analysis
Industrial-grade microcontroller costs from Taiwanese foundries pass through to safety logic solver pricing, with project-based contracting dominating as buyers segregate hardware procurement from engineering services. Price differentiation hinges on SIL certification tier and after-sales bundling intensity, with IEC 61511-certified systems commanding substantial premiums over uncertified alternatives. Pricing pressure stems from independent EPC firms building functional safety competency centers that challenge OEM service organizations. Chemical manufacturers in Germany exhibit lowest price sensitivity due to regulatory compliance mandates, while Indian mega-refinery projects drive hardest bargaining through volume concentration.
Supply Chain Analysis
Functional safety engineering labor scarcity in Germany and the United States constrains final assembly capacity for SIL 3 and SIL 4 systems, forcing project timeline extensions. Supply draws from Taiwan for industrial microcontrollers, Germany for precision sensors, and the United States for embedded analytics software. Single-source vulnerability concentrates in Taiwanese foundry capacity for safety-grade logic solvers. Distribution runs through certified system integrators and EPC contractors rather than direct OEM channels, with marine-rated sensor arrays for floating production vessels requiring specialized Rio de Janeiro engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The process safety system market compounds steadily as IEC 61511 retrofit deadlines across legacy chemical and refinery infrastructure create recurring replacement cycles that outpace discretionary capital expenditure volatility.
For Market Incumbents: Lock in refinery relationships through proof test interval compression capabilities that reduce unplanned outages, while embedding cybersecurity-hardened architectures ahead of IEC 62443 annex enforcement. Defend against independent EPC functional safety centers by captive supply of TÜV Rheinland-certified engineering talent through acquisition or exclusive contracting arrangements. For New Entrants and Emerging Players: Begin with hydrogen economy flame detection for invisible hydrogen flames, where established sensor architectures fail and certification requirements remain unsettled. Target carbon capture and storage greenfield projects in the United States Gulf Coast, where CO2 compression safety specifications diverge from legacy hydrocarbon experience. Pursue direct contracting with electrolyzer developers before incumbent automation vendors bundle safety systems with process control platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with functional safety specialists holding exida or TÜV Rheinland certification credentials that outpace engineering graduate pipeline output. Five-to-ten year viability rests on regulatory enforcement durability rather than technology disruption risk. Monitor EPA Risk Management Program amendment implementation timelines as inflection indicators for third-party compliance audit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | IEC 62443 compliance hardens safety networks against remote attack vectors in integrated refinery architectures. |
| Specialist Engineering Acquisition | Captive TÜV Rheinland-certified talent pools compress commissioning timelines for SIL 3 and SIL 4 projects. |
| Hydrogen-Adapted Sensor Development | Invisible hydrogen flame detection opens greenfield electrolyzer and ammonia synthesis facility deployments. |
| Predictive Diagnostics Integration | Embedded analytics reduce spurious trip rates and extend proof test intervals for high-availability process units. |
| Marine-Rated Packaging Expansion | Floating production storage and offloading vessel demand off Brazil requires humidity-resistant sensor architectures. |
Study Parameters
Direct dialogue with functional safety managers at Texas and Louisiana refineries, TÜV Rheinland certification auditors, EPC project engineers, and Honeywell and ABB account executives grounded demand-side validation. Secondary sources included OSHA enforcement databases, EPA Risk Management Program compliance filings, IEC 61511 interpretation guidance from notified bodies, and SEC 10-K automation segment disclosures. Bottom-up installation base analysis and top-down capital expenditure tracking triangulated market sizing across safety instrumented system, fire and gas detection, and emergency shutdown system categories.
Bottom-up modeling aggregated safety integrity level-specific unit economics by end-use vertical, while top-down approaches tracked OSHA Process Safety Management mandate enforcement intensity across the analysis window. Segmentation dimensions spanned product type, end-use industry, technology maturity, and regional regulatory framework clustering. CAGRs derived from hazard analysis refresh cycle frequencies, SIL verification calculation complexity trends, and floating production vessel deployment pipelines. Forecast inputs incorporated semiconductor supply concentration risk and functional safety engineering graduate pipeline constraints.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwanese foundry operations, accelerated IEC 62443 cybersecurity annex enforcement timelines, and hydrogen economy infrastructure buildout pace. Forecasts reflect assumptions about regulatory enforcement continuity and certification body interpretation stability. Practitioners should monitor EPA compliance audit mandate implementation, notified body systematic capability guidance revisions, and deepwater oil field development licensing activity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Shock Trouser Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market