
 Global Hazmat Suits Market | 2026-2036
Global Hazmat Suits Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hazmat Suits Market Foresight
The hazmat suits market is repositioning around a widening gap between mission-critical encapsulated systems and commoditized disposable coveralls. DuPont de Nemours, Inc. leverages its Tyvek and Tychem material science heritage to dominate premium chemical barrier applications. Lakeland Industries, Inc. competes aggressively on manufacturing scale in the industrial disposable segment. Kimberly-Clark Corporation anchors its position through channel control in healthcare-adjacent contamination cleanup.
Hazmat suits are impermeable or selectively permeable garments engineered to protect wearers from chemical, biological, radiological, and nuclear agents, typically constructed from multi-layer barrier fabrics with sealed seams and integrated respiratory interfaces. Encapsulated suits command the highest performance tier due to gas-tight construction and positive-pressure SCBA compatibility, while disposable polyethylene variants serve high-turnover decontamination protocols. Non-encapsulated suits lead volume in industrial chemical handling where mobility requirements outweigh absolute containment. Fire-resistant Nomex-based suits concentrate margin pools in nuclear facility operations where thermal and radiological threats co-occur.
OSHA's Hazardous Waste Operations and Emergency Response standard shapes US product certification requirements, while the EU's REACH regulation and PPE Regulation 2016/425 govern material composition and conformity assessment across European markets. China's GB 24539 standard for chemical protective clothing, administered by SAMR, creates a parallel compliance track for domestic manufacturers and importers. Stakeholders must monitor diverging national test protocols for permeation resistance as these frameworks evolve independently.
Market Dynamics
The hazmat suits market is bifurcating around OSHA's 29 CFR 1910.120 enforcement surge, which is compressing demand toward certified encapsulated systems while squeezing uncertified disposable alternatives out of hazardous waste remediation contracts.
Growth Catalysts
- Gulf Coast chemical expansion:Petrochemical capacity additions across Texas and Louisiana are generating procurement pipelines for Level A suits under stricter EPA RCRA oversight of hazardous waste operations.
- EU Green Deal material mandates:REACH-driven phaseouts of chlorinated barrier polymers are pulling bio-based alternatives into commercial validation for chemical processing applications.
- Sealed seam automation:Ultrasonic welding systems are reducing production defect rates in encapsulated suit manufacturing, expanding addressable supply for mission-critical deployments.
Market Restraints
- Butyl rubber supply concentration:Gas-tight glove and boot component sourcing clusters in Southeast Asian specialty chemical zones create single-point vulnerability for encapsulated suit assemblers.
- SCBA integration complexity:Positive-pressure respiratory interface certification timelines stretch 18-24 months, throttling speed-to-market for next-generation encapsulated designs.
- Polyethylene price volatility:Feedstock fluctuations in ethylene derivatives compress margins on high-volume disposable coverall production.
Strategic Opportunities
- India's industrial safety upgrade cycle:Factory Act enforcement expansion in Gujarat and Maharashtra chemical corridors is opening certified protective equipment penetration ahead of BIS standard harmonization.
- Wearable sensor convergence:Biometric monitoring integration with respiratory interfaces is creating premium positioning for connected hazmat systems in nuclear facility maintenance.
- Direct-to-utility procurement platforms:Municipal fire department consortium purchasing is disintermediating traditional safety distribution channels for emergency response suit procurement.
Industry Challenges
- Permeation testing technician scarcity:ASTM F739 certified laboratory capacity constraints are extending product validation queues for new barrier fabric introductions.
- Multi-standard compliance overhead:Simultaneous OSHA, REACH, and GB 24539 certification requirements are fragmenting R&D resource allocation across regional product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hazmat Suits Market |
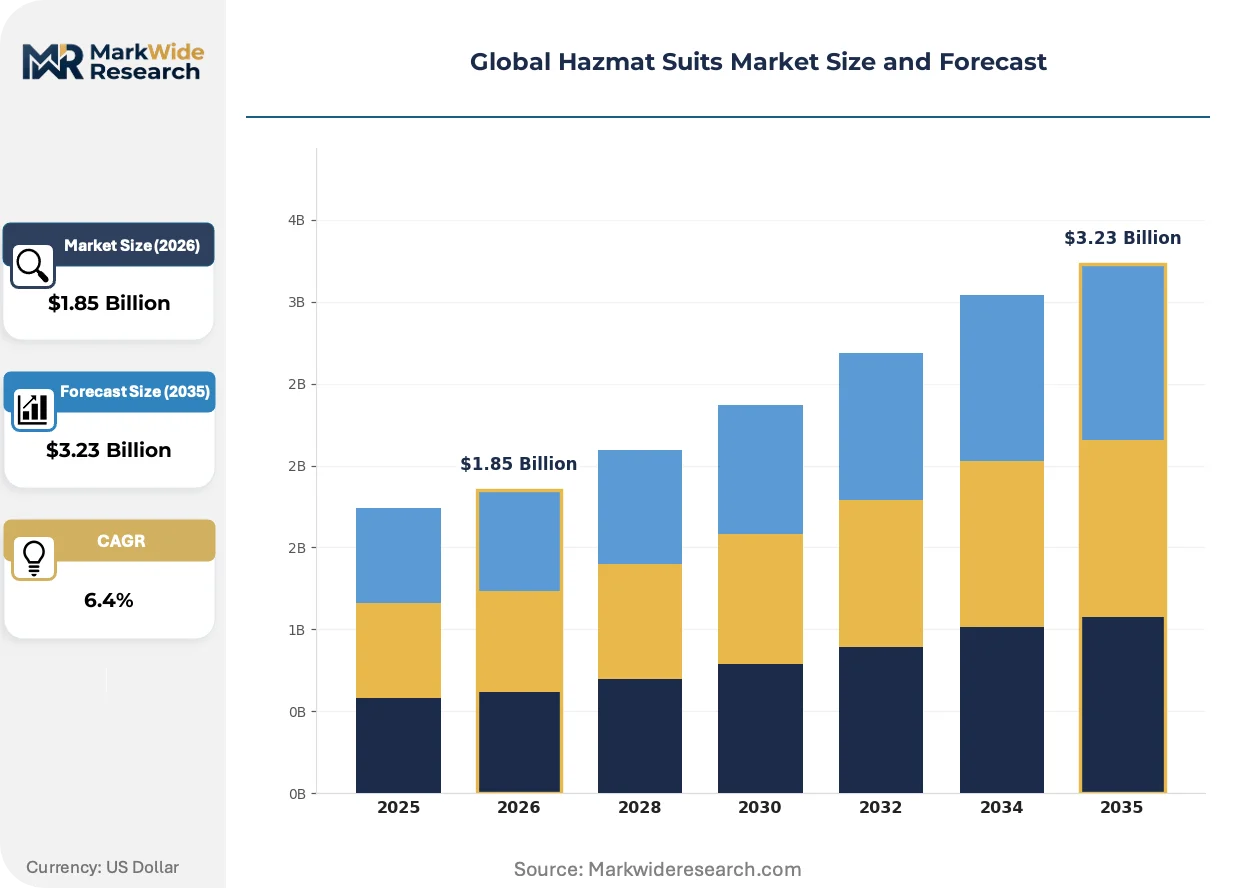
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Encapsulated Suits, Non-Encapsulated Suits, Gas-Tight Suits, Fire-Resistant Suits, Disposable Suits Material: Polyethylene, Tyvek, PVC, Neoprene, Butyl Rubber, Nomex End User: Emergency Responders, Industrial Operators, Scientific Researchers, Cleanroom Personnel, Environmental Contractors Application: Chemical Handling, Biological Hazard Response, Nuclear Facility Operations, Firefighting, Contamination Cleanup |
| Companies Covered | DuPont de Nemours, Inc., 3M Company, Kimberly-Clark Corporation, Drägerwerk AG & Co. KGaA, Ansell Limited, Lakeland Industries, Inc., Honeywell International Inc., Kappler, Alpha Pro Tech Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hazmat Suits Market Shifts & Advancements
Barrier fabric engineering is pivoting from passive chemical resistance toward active environmental sensing, while regulatory fragmentation is forcing modular certification architectures that can adapt to diverging national test protocols.
Selectively permeable membrane technology is decentralizing the traditional encapsulated suit hierarchy by enabling breathable protection against specific chemical classes without full gas-tight enclosure. Pharmaceutical manufacturing cleanrooms in Ireland and Singapore are adopting these systems for solvent handling operations where mobility requirements previously forced compromise on protection levels. The technology is decentralizing procurement decisions from centralized safety departments to individual facility managers who can match protection tiers to specific exposure profiles.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of oil-repellent barrier treatments that have dominated chemical protective fabrics for three decades. German and French textile finishers are accelerating plasma-based surface modification research to replicate legacy performance without fluorinated chemistry. Encapsulated suit manufacturers serving EU petrochemical markets are absorbing 12-18 month requalification timelines as they validate replacement treatments against EN 943 test protocols.
Consolidated procurement through integrated safety service contracts is compressing vendor counts among multinational chemical operators. Dow and BASF facility networks are centralizing hazmat suit specification authority at regional hub levels, displacing plant-level purchasing autonomy that previously sustained fragmented supplier relationships. This concentration is most visible in the Antwerp-Rotterdam chemical cluster where integrated service providers are capturing multi-year protective equipment contracts with embedded training and decontamination service bundles.
Global Hazmat Suits Market Segmentation
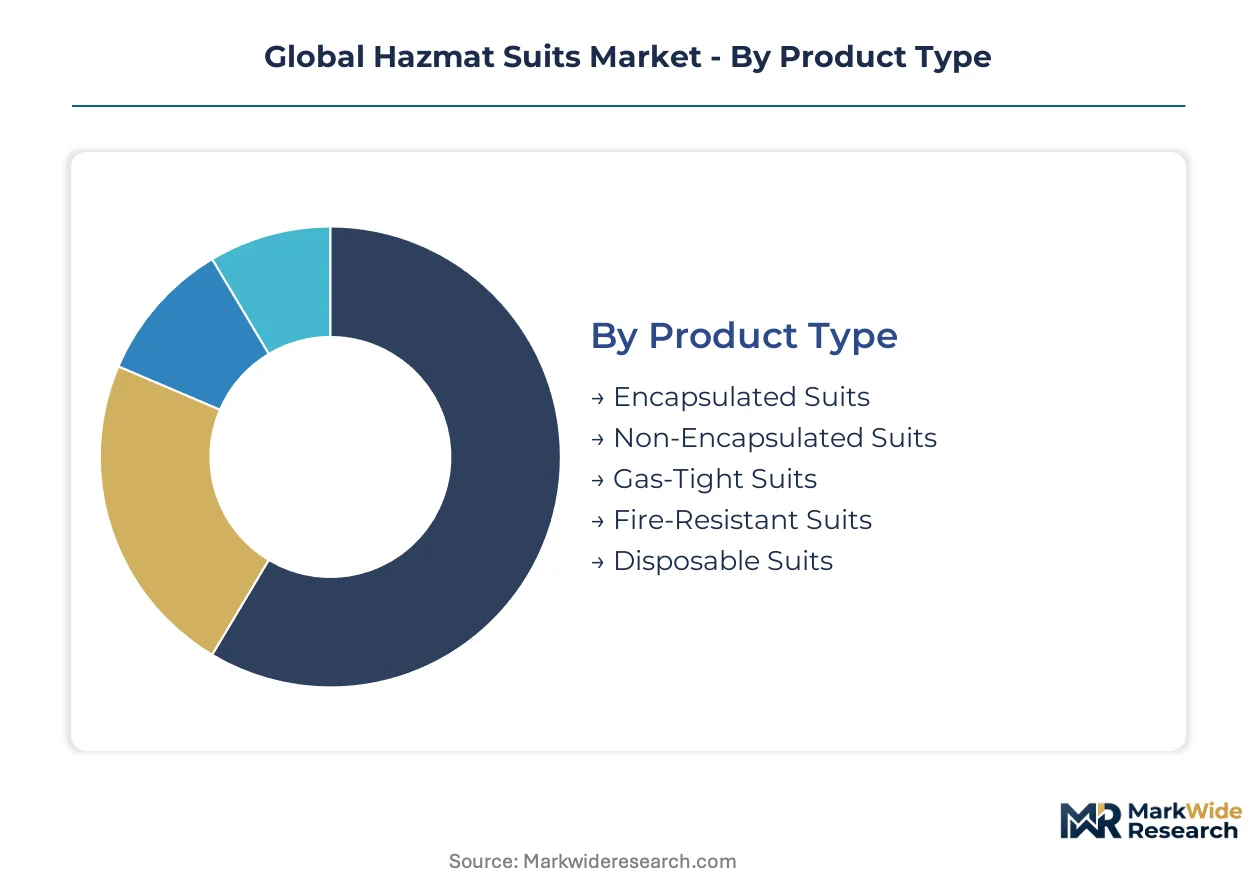
Hazmat suit procurement decisions pivot on protection level specifications, material compatibility matrices, and operational mobility requirements. Each segmentation axis reveals distinct margin structures and certification barriers that shape vendor positioning across mission-critical and high-turnover applications.
Product Type:
Technical specifications around permeation resistance and respiratory interface integration define the product hierarchy and pricing architecture.
- Encapsulated Suits:Gas-tight construction with positive-pressure SCBA compatibility delivers absolute containment for unknown chemical atmospheres. Demand concentrates in US Gulf Coast petrochemical facilities where OSHA 29 CFR 1910.120 enforcement mandates certified systems for hazardous waste entry operations.
- Non-Encapsulated Suits:Selectively permeable designs balance chemical protection against mobility requirements through multi-layer barrier fabrics with sealed seams. Industrial chemical handling in Germany's Rhine-Ruhr manufacturing belt drives volume, with REACH-compliant material transitions absorbing R&D resources.
- Gas-Tight Suits:Fully sealed systems with integrated breathing apparatus connections for maximum isolation scenarios. Nuclear decommissioning contracts across France and the UK sustain specialized procurement pipelines.
- Fire-Resistant Suits:Nomex-based thermal protection combined with radiological shielding for concurrent threat environments. Nuclear facility maintenance programs in Japan and South Korea anchor demand.
- Disposable Suits:Single-use polyethylene or Tyvek garments for high-frequency decontamination protocols. Pandemic preparedness stockpiling and pharmaceutical manufacturing in Ireland and Singapore sustain volume procurement.
Mature deployment sits with Non-Encapsulated Suits across established industrial chemical corridors. Newer deployment is concentrated in connected Encapsulated Suits with biometric monitoring integration.
Material:
Barrier chemistry and seam integrity specifications determine permeation resistance ratings and regional regulatory acceptance.
- Polyethylene:Cost-effective moisture barrier for short-duration splash protection in standardized decontamination workflows. Environmental remediation contractors across China's Yangtze River Delta favor disposability over reusability for cost control.
- Tyvek:High-density polyethylene flash-spun nonwoven delivering particulate and light liquid splash resistance. Cleanroom operations in pharmaceutical manufacturing clusters sustain premium positioning.
- PVC:Legacy chlorinated polymer facing REACH-driven phaseout pressures across EU chemical processing markets. Replacement validation timelines extend procurement cycles.
- Neoprene:Synthetic rubber offering broad chemical resistance with moderate flexibility. Industrial maintenance applications in Brazil's petrochemical sector sustain regional demand.
- Butyl Rubber:Gas-tight elastomer for glove and boot components in encapsulated suit assemblies. Southeast Asian specialty chemical concentration creates supply vulnerability.
- Nomex:Aramid fiber providing thermal protection alongside chemical barrier properties. Nuclear facility operations requiring concurrent fire and radiological defense anchor premium pricing.
Established volume sits with Polyethylene and Tyvek in high-turnover applications. Material transition investment is concentrating in bio-based barrier alternatives replacing PVC under EU Green Deal mandates.
End User:
Operational protocols and certification requirements fragment demand across institutional buyer types with diverging procurement authority structures.
- Emergency Responders:Municipal fire departments and hazardous materials teams requiring rapid donning capabilities under incident command protocols. Consortium purchasing platforms across US metropolitan areas are disintermediating traditional distribution channels.
- Industrial Operators:Petrochemical and pharmaceutical facility safety departments with integrated protective equipment contracts. Dow and BASF regional hub centralization compresses vendor counts in the Antwerp-Rotterdam chemical cluster.
- Scientific Researchers:Laboratory and field investigation personnel handling engineered biological agents or novel chemical compounds. BSL-3 and BSL-4 facility networks sustain specialized specification requirements.
- Cleanroom Personnel:Semiconductor and pharmaceutical manufacturing operators requiring particulate control alongside chemical protection. Singapore and Ireland fabrication facilities drive precision garment demand.
- Environmental Contractors:Remediation specialists performing soil and groundwater decontamination under EPA RCRA or equivalent national oversight. China's provincial environmental bureau mandates are accelerating equipment upgrades.
Procurement standardization is most advanced among Industrial Operators with integrated service contracts. Procurement fragmentation persists among Emergency Responders with municipal budget autonomy.
Application:
Exposure profile specificity determines protection tier selection and drives divergence between reusable encapsulated systems and disposable alternatives.
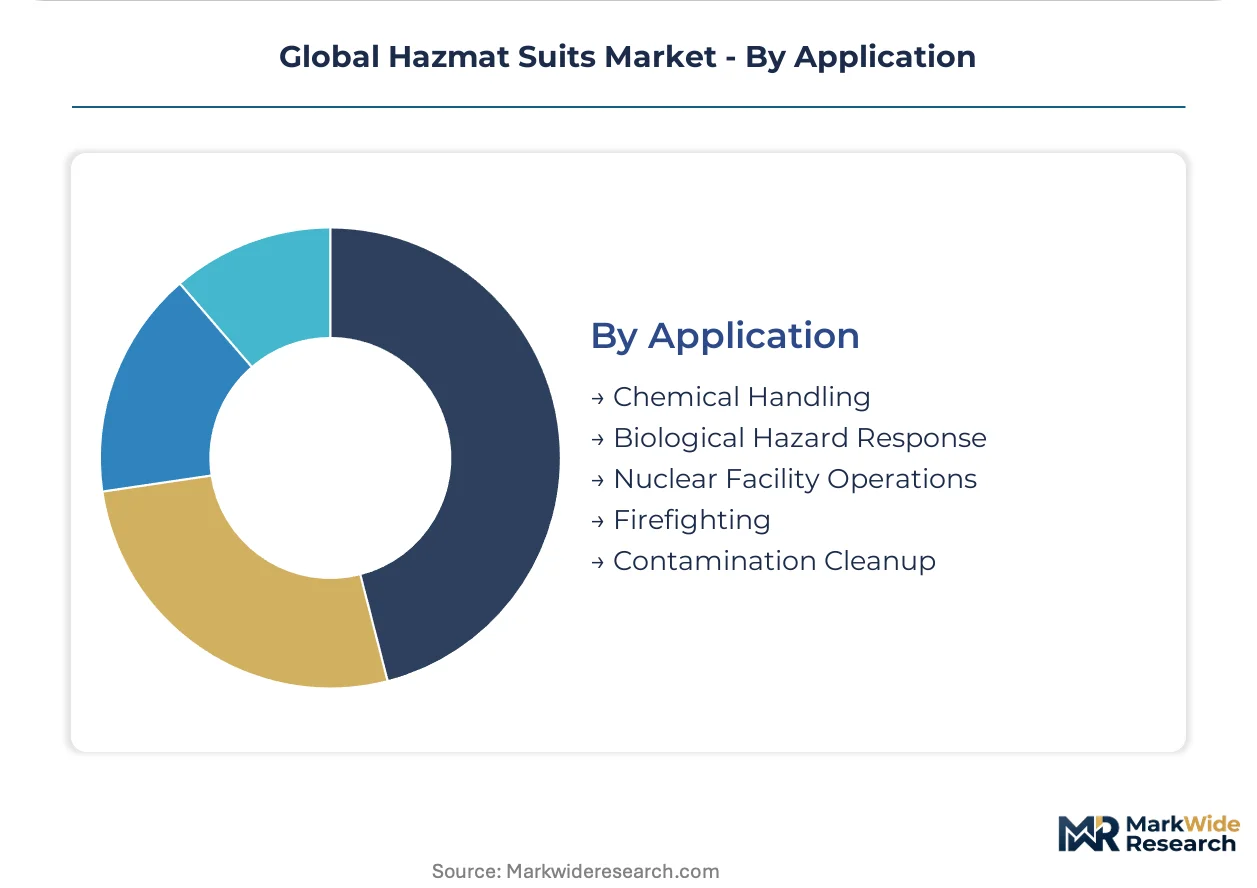
- Chemical Handling:Routine industrial operations with characterized substance exposure enabling selectively permeable protection. India's Gujarat and Maharashtra chemical corridors are opening certified equipment penetration ahead of BIS harmonization.
- Biological Hazard Response:Pathogen containment protocols requiring particulate filtration and liquid-tight integrity. Pandemic preparedness stockpiling cycles sustain strategic reserve procurement.
- Nuclear Facility Operations:Concurrent radiological, thermal, and chemical threat environments demanding multi-hazard protection. Decommissioning programs across France, the UK, and Japan sustain specialized garment development.
- Firefighting:Structural fire entry combined with hazardous materials response requiring thermal protection with chemical resistance. Urban search and rescue integration is expanding capability requirements.
- Contamination Cleanup:Post-incident decontamination with high garment turnover and disposal cost sensitivity. Disaster response frameworks standardize disposable coverall specifications.
Application maturity sits with Chemical Handling across established industrial safety protocols. Capability expansion is concentrated in Biological Hazard Response with engineered pathogen research facility construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta petrochemical corridor drives Asia-Pacific procurement intensity. China's provincial environmental bureaus mandate upgraded personal protective equipment for hazardous waste remediation. This concentration shapes regional demand patterns across three continents.
United States
Gulf Coast chemical processing plants expand Level A encapsulated suit procurement under stricter OSHA enforcement of 29 CFR 1910.120. EPA RCRA oversight of hazardous waste operations tightens compliance thresholds. Texas and Louisiana capacity additions generate sustained procurement pipelines for certified systems.
Germany
Rhine-Ruhr manufacturing belt industrial chemical handling sustains non-encapsulated suit volume. REACH-driven phaseouts of chlorinated barrier polymers pull bio-based alternatives into commercial validation. Plasma-based surface modification research accelerates at textile finishers in Baden-Württemberg.
China
Yangtze River Delta petrochemical corridor concentrates provincial environmental bureau mandates for equipment upgrades. SAMR-administered GB 24539 standard creates parallel compliance tracks for domestic manufacturers. Shanghai and Ningbo remediation contractors favor disposability for cost control.
France
Nuclear decommissioning programs sustain specialized gas-tight suit procurement pipelines. ECHA restrictions on per- and polyfluoroalkyl substances force 12-18 month requalification timelines for barrier treatments. Lyon and Marseille facility networks absorb embedded training and decontamination service bundles.
India
Gujarat and Maharashtra chemical corridors open certified protective equipment penetration ahead of BIS standard harmonization. Factory Act enforcement expansion accelerates industrial safety upgrade cycles. Mumbai and Ahmedabad procurement decisions decentralize to facility managers matching protection tiers to exposure profiles.
Global Hazmat Suits Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material science heritage and manufacturing scale. DuPont de Nemours, Inc. leverages Tyvek and Tychem heritage to dominate premium chemical barrier applications. Lakeland Industries, Inc. competes aggressively on manufacturing scale in the industrial disposable segment. Three archetypes emerge: integrated material science conglomerates, specialized protective equipment fabricators, and diversified safety technology multinationals. Dominant competitive moves include sealed seam automation investments and direct-to-utility procurement platform development.
Within the material science heritage tier, DuPont de Nemours, Inc. anchors premium positioning through barrier fabric innovation. Lakeland Industries, Inc. exemplifies scale-driven manufacturing concentration in high-turnover disposables. Kimberly-Clark Corporation occupies a position anchored through channel control in healthcare-adjacent contamination cleanup. These three represent the structural divergence between mission-critical encapsulated systems and commoditized disposable coveralls.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| 3M Company |
| Kimberly-Clark Corporation |
| Drägerwerk AG & Co. KGaA |
| Ansell Limited |
| Lakeland Industries, Inc. |
| Honeywell International Inc. |
| Kappler |
| Alpha Pro Tech Ltd. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators in Germany's Baden-Württemberg region anchor premium encapsulated suit production, translating generational technical debt into pricing discipline that resists commoditization pressure from Asian disposable manufacturers. Their captive control over plasma-based surface modification R&D insulates margin pools from REACH-driven reformulation costs that fracture pricing coherence among competitors dependent on outsourced finishing.
Pricing Analysis
Value-based pricing anchored to worker safety outcomes and facility uptime protection stratifies across premium, standard, and economy tiers. Certification grade under OSHA 29 CFR 1910.120 and EN 943 protocols creates the primary price differentiation driver, with gas-tight encapsulated systems commanding substantial premiums over selectively permeable alternatives. Cost compression in disposable polyethylene coveralls intensifies as Chinese Yangtze River Delta contractors prioritize disposability over reusability for environmental remediation budgets. Emergency responders exhibit highest price sensitivity due to municipal procurement constraints, while nuclear facility operators demonstrate lowest sensitivity given concurrent threat protection requirements.
Supply Chain Analysis
Domestic-content mandates in India's Factory Act enforcement zones are reshaping sourcing patterns for Gujarat and Maharashtra chemical corridor deployments. Butyl rubber for gas-tight glove and boot components concentrates in Southeast Asian specialty chemical zones, while high-density polyethylene feedstock clusters in US Gulf Coast petrochemical complexes and Chinese state-owned refinery networks. Single-source vulnerability in butyl elastomer supply creates structural risk for encapsulated suit assemblers. Distribution runs through integrated safety service contracts that disintermediate traditional channel partners in the Antwerp-Rotterdam chemical cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hazmat suits market is executing a technology-transition phase as bio-based barrier fabrics displace PVC and perfluorinated treatments under EU Green Deal mandates. Selectively permeable membrane systems are decentralizing procurement authority from centralized safety departments to facility-level managers.
For Market Incumbents: Extend material science heritage into connected hazmat systems by integrating biometric monitoring with respiratory interfaces for nuclear facility maintenance contracts. Sealed seam automation investments defend margin position against ultrasonic welding technology diffusion to mid-tier competitors. Backward integration into butyl rubber compounding mitigates Southeast Asian supply concentration risk.
For New Entrants and Emerging Players: Begin with India's industrial safety upgrade cycle ahead of BIS standard harmonization, where Factory Act enforcement expansion outpaces certified supplier capacity. Target environmental remediation contractors in China's Yangtze River Delta favoring disposability for cost control. Direct-to-utility procurement platforms for municipal fire department consortium purchasing disintermediate entrenched distribution relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized protective equipment fabricators with GB 24539 certification traction and SAMR regulatory relationships in China. Long-term viability rests on bio-based barrier validation timelines and plasma surface modification IP positions. Watch sealed seam automation adoption rates as inflection indicator for manufacturing cost structure divergence between premium and commodity tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Sealed Seam Automation Investment | Ultrasonic welding systems reduce defect rates in encapsulated suit manufacturing for OSHA 29 CFR 1910.120 compliance. |
| Bio-Based Barrier Fabric Validation | REACH-driven PVC phaseouts accelerate commercial qualification of sustainable alternatives across EU petrochemical markets. |
| Biometric Monitoring Integration | Wearable sensor convergence creates premium positioning for connected hazmat systems in French nuclear decommissioning programs. |
| Direct-to-Utility Procurement Platforms | Municipal fire department consortium purchasing disintermediates traditional safety distribution channels across US metropolitan areas. |
| Butyl Rubber Supply Security | Upstream control over gas-tight elastomer sourcing mitigates single-point vulnerability for encapsulated suit assemblers. |
Research Methodology
Trade data from customs authorities, SEC 10-K filings of protective equipment manufacturers, and EU REACH registration databases formed the secondary backbone. Primary interviews with plant safety managers at Dow and BASF facility networks, procurement leads at municipal fire departments, technical R&D directors at German textile finishers, and distribution channel partners in the Antwerp-Rotterdam cluster combined with secondary validation. Bottom-up and top-down triangulation reconciled unit shipment estimates with value aggregation across protection level tiers.
Bottom-up modeling segmented demand by product type, material chemistry, end-user institutional category, and application exposure profile across the projection horizon. Top-down validation cross-referenced petrochemical capacity expansion announcements with OSHA enforcement intensity and provincial environmental bureau mandate trajectories. CAGRs derived from regression analysis of historical procurement patterns against regulatory compliance timelines. Forecast inputs included ultrasonic welding adoption curves and bio-based barrier fabric commercialization schedules.
Underlying measurement precision varies by segment; encapsulated suits with certified SCBA integration carry tighter precision than commoditized disposable coveralls. Forecasts reflect assumptions around REACH Annex XVII enforcement consistency and SAMR GB 24539 harmonization timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Explosion Proof Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Protection Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market