
 Small Satellite Launch Market | 2026-2036
Small Satellite Launch Market Size, Share, and Industry Trends Forecast 2026-2036
Small Satellite Launch Market Analysis
China's Hainan Wenchang spaceport expansion is tilting Asia-Pacific launch capacity toward higher-throughput small satellite missions. SpaceX leverages reusable Falcon 9 architectures to sustain cost leadership on dedicated and ride-share missions. Rocket Lab anchors the small-lift segment with Electron production scale and vertical integration into satellite systems. Arianespace competes through Vega C reliability and European institutional backlog security.
Small satellite launch services encompass orbital insertion of spacecraft under 500 kilograms using dedicated small-lift vehicles, ride-share arrangements on medium-lift rockets, or emerging air-launched platforms; propulsion spans liquid bi-propellant, solid-fuel, and hybrid motor systems optimized for rapid turnaround and payload flexibility. The primary purpose is enabling commercial constellations, government reconnaissance, and scientific payloads to reach targeted orbits at lower cost and schedule risk than traditional heavy-lift alternatives. Dedicated launch services command premium pricing for orbital specificity and schedule certainty, while ride-share options capture volume from standardized CubeSat and microsatellite operators seeking cost minimization. Low Earth Orbit deployment dominates current activity, though polar and sun-synchronous trajectories for Earth observation are expanding fastest as remote sensing constellations proliferate.
FAA launch licensing governs US commercial operations, mandating flight safety analyses and environmental review that shape vehicle design and site selection timelines. ESA member-state frameworks plus EU Space Programme funding direct European procurement toward indigenous launch capability development. China's SAMR and CNSA coordination governs commercial launch firm licensing under state supervision. Stakeholders must monitor how ITAR and export control evolution affects cross-border component flows and overseas launch site access arrangements.
Market Dynamics
Reusability engineering in liquid propulsion systems is compressing per-launch economics and redrawing competitive moats between dedicated small-lift providers and ride-share aggregators.
Growth Catalysts
- US FAA streamlined licensing:Accelerated flight safety review timelines reduce vehicle development cycles for commercial launch operators. Reduced regulatory friction attracts venture capital into new vehicle programs.
- Earth observation constellations:Agriculture and logistics operators are procuring dedicated launch slots to maintain orbital phasing for synthetic aperture radar coverage. Precision agriculture demand in Brazil and Australia drives polar orbit insertion contracts.
- India's IN-SPACe framework:Public-private launch partnerships now permit private firms access to ISRO facilities and technical heritage. Domestic launch capacity expands through technology transfer agreements.
Market Restraints
- Solid propellant supply concentration:Ammonium perchlorate production clusters in the United States and China, creating single-source vulnerability for hybrid motor manufacturers. Price volatility in specialty chemicals constrains margin predictability.
- ITAR component restrictions:US export controls limit avionics and guidance system transfers to overseas launch sites. Non-US vehicle developers face procurement delays for flight-critical subsystems.
- Range capacity bottlenecks:Eastern and western US launch ranges operate at saturation during peak windows. Schedule certainty premiums escalate for customers requiring specific orbital planes.
Strategic Opportunities
- Mobile sea-launch platforms:Equatorial launch from international waters enables optimal inclination access without range congestion. Marine-based operations circumvent fixed-site infrastructure limitations.
- European institutional backlog:ESA member-state frameworks mandate indigenous launch capability procurement. Vega C and future microlauncher programs secure multi-year government anchor contracts.
- Air-launch system maturation:Carrier aircraft deployment from regional airports reduces weather scrub rates and expands launch site flexibility. Horizontal takeoff integration suits rapid-response defense and responsive space architectures.
Industry Challenges
- Turbopump manufacturing expertise:Liquid oxygen-kerosene engine production requires specialized welding and cryogenic handling skills. Talent scarcity in aerospace propulsion engineering extends vehicle development timelines.
- Flight termination system certification:Range safety approval processes demand extensive fault-tree analysis and hardware-in-the-loop validation. Each new vehicle configuration triggers redundant qualification cycles.
- Supply chain reconfiguration:Western launch providers are qualifying alternative suppliers for radiation-hardened electronics and specialty alloys. Component substitution introduces qualification risk into flight-proven architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Satellite Launch Market |
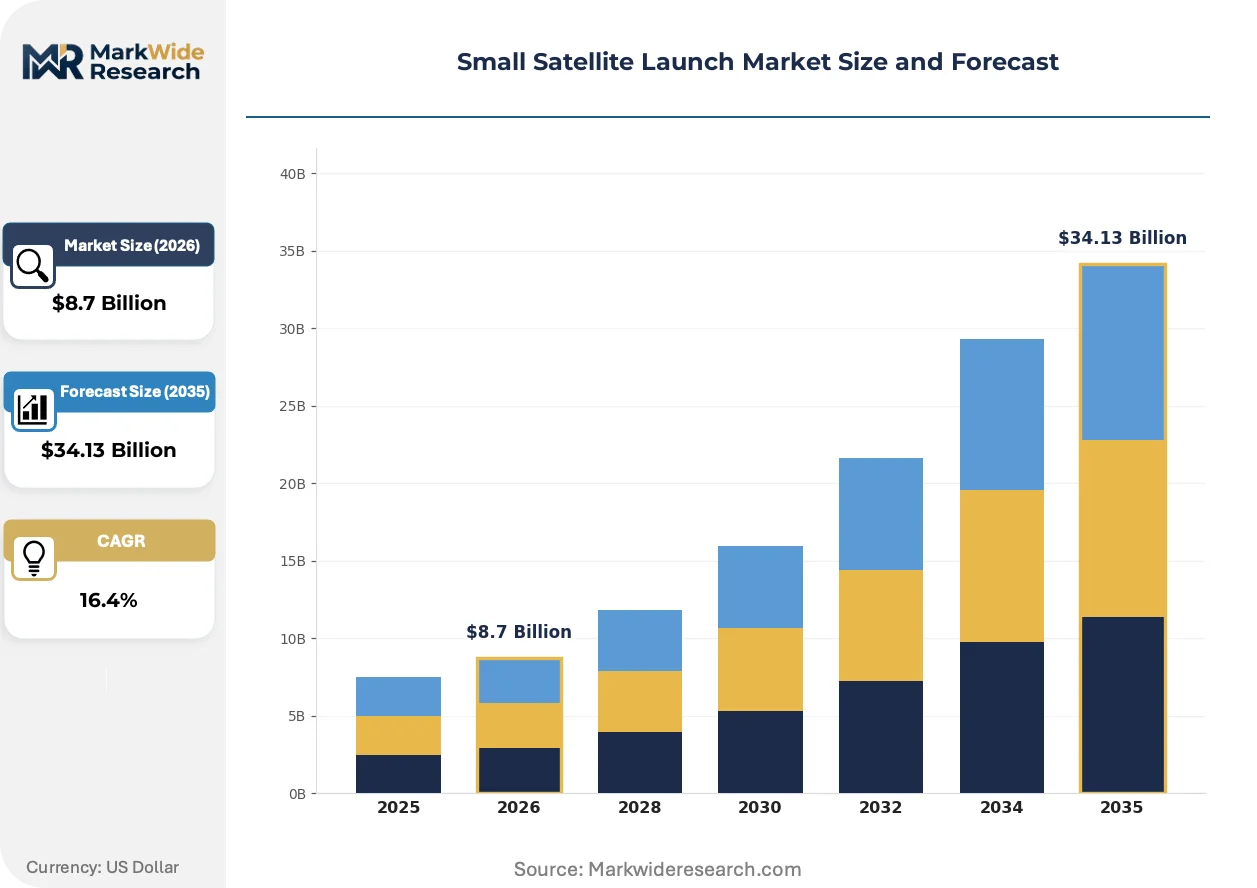
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Launch, Ride-Share, Mobile Launch, Mass Production Payload Type: Communication Satellites, Earth Observation, Scientific Research, Technology Demonstration Launch Platform: Ground-Based, Airborne, Sea-Based, Hybrid Launchers Orbit Type: Low Earth Orbit, Medium Earth Orbit, Geostationary Orbit, Polar Orbit |
| Companies Covered | SpaceX, Rocket Lab, Arianespace, Northrop Grumman, Lockheed Martin, Sierra Nevada Corporation, Blue Origin, United Launch Alliance, Orbital ATK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Satellite Launch Market Emerging Trajectories
Additive manufacturing of combustion chambers and regenerative-cooled nozzles is collapsing lead times for engine development while enabling geometry-optimized designs previously unmachinable through conventional subtractive methods.
Reusability engineering is collapsing the cost structure of orbital insertion services. Propulsive landing of first-stage boosters enables rapid turnaround with minimal refurbishment. Commercial constellation operators now demand flight-proven hardware for dedicated missions, compressing the price premium for new vehicles.
FAA launch licensing reforms are compressing approval timelines for experimental permits and operator licenses. Streamlined environmental review under the National Environmental Policy Act reduces site selection uncertainty. Small-lift developers in California and Florida are expanding test flight cadence in response to regulatory acceleration.
Constellation operators are consolidating procurement around multi-launch service agreements rather than transactional single-manifest contracts. Anchor tenancy arrangements provide cash flow visibility for vehicle developers while locking in schedule priority for satellite deployers. This pattern concentrates most visibly in US and Chinese commercial remote sensing ventures seeking orbital plane population on accelerated timelines.
Small Satellite Launch Market Segmentation
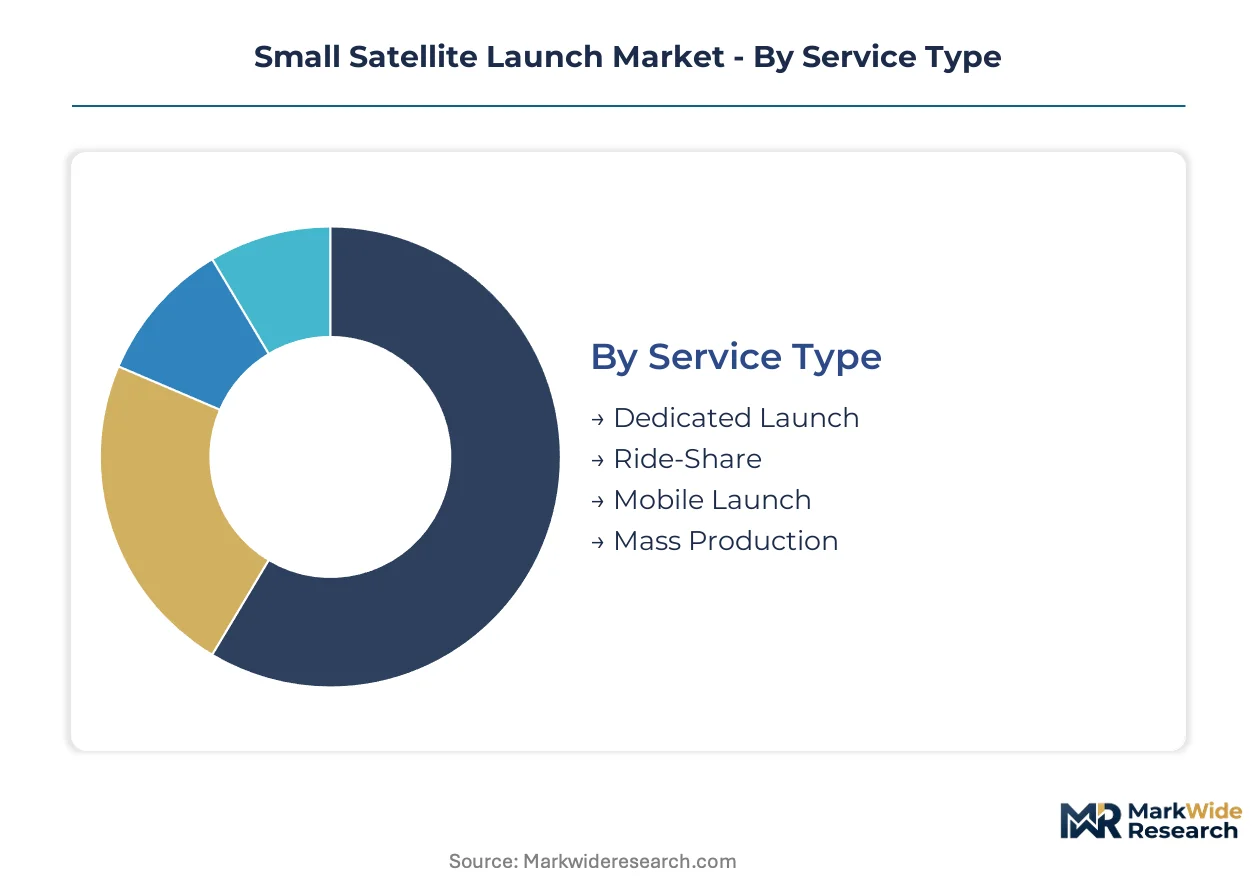
Launch service segmentation reveals divergent operational economics across mission architectures. Dedicated providers require intensive post-flight refurbishment programs, while ride-share aggregators amortize fixed costs across multi-manifest manifests. Understanding these structural differences guides procurement strategy for constellation operators.
Service Type:
After-sales service intensity varies dramatically by mission architecture, with dedicated launch providers carrying full vehicle recovery obligations while ride-share operators distribute liability across multiple payload customers.
- Dedicated Launch:Single-manifest missions using small-lift vehicles under 500 kg capacity. ISRO's commercial arm and US private operators dominate procurement from Earth observation constellations requiring precise orbital phasing for synthetic aperture radar coverage.
- Ride-Share:Aggregated payloads on medium-lift rockets or dedicated small-lift missions with multiple customers. SpaceX Transporter missions and ISRO's PSLV commercial rides compress per-kg economics for standardized CubeSat operators in university and startup segments.
- Mobile Launch:Sea-based or air-launched platforms enabling equatorial access without fixed-range congestion. Marine operations from international waters and carrier aircraft deployments reduce weather scrub rates for responsive defense architectures.
- Mass Production:Standardized launch services for constellation deployment at high cadence. Vertical integration of vehicle manufacturing with satellite production lines supports rapid replenishment of commercial remote sensing networks.
By volume, ride-share leads. By growth pace, dedicated launch is ahead.
Payload Type:
Customer procurement patterns split between commercial operators seeking schedule certainty and government agencies prioritizing orbital specificity over cost minimization.
- Communication Satellites:Broadband constellation deployments driving demand for high-cadence launch services. Low Earth Orbit megaconstellations from US and Chinese operators require sustained injection rates that favor mass production service models over transactional procurement.
- Earth Observation:Synthetic aperture radar and multispectral imaging payloads demanding precise sun-synchronous insertion. Agriculture and logistics operators in Brazil and Australia procure dedicated polar orbit slots to maintain revisit timing for crop monitoring and supply chain tracking.
- Scientific Research:University and institutional payloads with flexible schedule tolerance. NASA and ESA small satellite programs leverage ride-share economics for technology validation missions with extended development timelines.
- Technology Demonstration:Experimental payloads proving novel propulsion, communication, or sensing architectures. Defense agencies in the United States and India fund rapid-response launch contracts for responsive space capability validation.
Earth observation commands the largest contract value. Technology demonstration is climbing the fastest.
Launch Platform:
Platform selection determines range access constraints, weather vulnerability, and regulatory jurisdiction for flight operations.
- Ground-Based:Fixed-site launch complexes with established range safety infrastructure. Cape Canaveral, Vandenberg, Satish Dhawan, and Jiuquan anchor global capacity with FAA and CNSA licensing governing commercial access.
- Airborne:Carrier aircraft releasing rockets at altitude from regional airports. Virgin Orbit's former operations and emerging Chinese programs reduce infrastructure dependency for small payload missions.
- Sea-Based:Floating platforms enabling equatorial launches without territorial restrictions. China's Long March maritime deployments and prospective international ventures target optimal inclination access for communications constellations.
- Hybrid Launchers:Systems combining horizontal takeoff with rocket-powered orbital insertion. Emerging concepts aim to collapse turnaround times through aircraft-like operational cadence.
Ground-based platforms dominate current manifest volume. Sea-based operations are gaining share fastest.
Orbit Type:
Orbital destination dictates propulsion requirements, launch azimuth constraints, and competitive positioning between dedicated small-lift and ride-share alternatives.
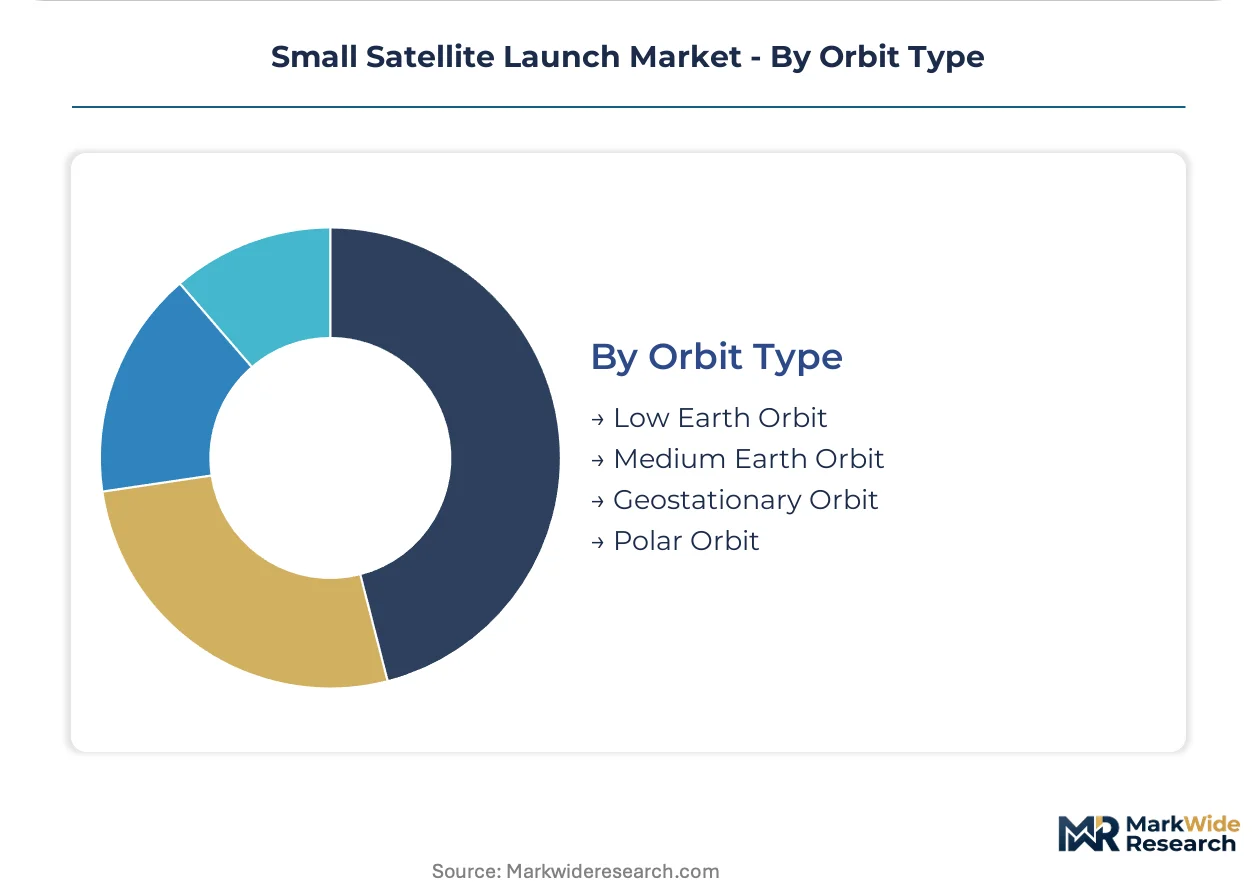
- Low Earth Orbit:Altitudes under 2,000 km hosting the majority of commercial constellations. Starlink and comparable networks drive demand for high-frequency injection at inclinations accessible from mid-latitude launch sites.
- Medium Earth Orbit:Intermediate altitudes for navigation augmentation and specialized communications. GPS backup constellations and regional positioning systems require precise deployment windows that favor dedicated launch scheduling.
- Geostationary Orbit:Equatorial plane at 35,786 km for persistent coverage applications. Small satellites in this regime typically serve as technology demonstrators or gap-fillers rather than primary mission architectures.
- Polar Orbit:High-inclination trajectories for global Earth observation coverage. Sun-synchronous orbits for agriculture and climate monitoring drive dedicated launch premiums from Vandenberg and Satish Dhawan.
Low Earth Orbit handles the greatest launch volume. Polar orbit services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA launch licensing reforms in the United States are compressing approval timelines and attracting venture capital into new vehicle programs. National space agencies across multiple geographies are expanding public-private launch partnerships to accelerate domestic capacity.
United States
Commercial Earth observation operators in agriculture and logistics are expanding procurement of dedicated launch services. FAA streamlined licensing accelerates flight safety review timelines and reduces vehicle development cycles. Cape Canaveral and Vandenberg anchor capacity, though range saturation during peak windows escalates schedule certainty premiums.
China
State-backed commercial launch firms are scaling under CNSA and SAMR coordination. Hainan Wenchang spaceport expansion tilts Asia-Pacific capacity toward higher-throughput small satellite missions. Jiuquan and Taiyuan launch complexes support polar and sun-synchronous trajectories for remote sensing constellations.
India
Precision agriculture demand in domestic and Australian markets drives polar orbit insertion contracts. IN-SPACe framework permits private firms access to ISRO facilities and technical heritage. Satish Dhawan Space Centre anchors commercial launch activity with technology transfer agreements expanding domestic capacity.
France
ESA member-state frameworks mandate indigenous launch capability procurement for institutional missions. Arianespace competes through Vega C reliability and European backlog security. Guiana Space Centre provides equatorial access for communications constellations seeking optimal inclination deployment.
Japan
Scientific research payloads with flexible schedule tolerance leverage ride-share economics for technology validation. METI and JAXA coordination governs commercial launch firm licensing. Tanegashima and Uchinoura space centers support responsive defense architectures and rapid-response launch contracts.
Small Satellite Launch Market Vendor Landscape
Reusable heavy-lift aggregators and dedicated small-lift specialists split the market between cost-minimized ride-share volume and premium orbital specificity. The vendor base organizes around three strategic archetypes: vertically integrated constellation operators, pure-play launch service providers, and defense-anchored prime contractors. Consolidation pressures concentrate around multi-launch service agreements and anchor tenancy arrangements. Competitive moves center on reusability engineering and production scale expansion.
Within the reusable heavy-lift tier, SpaceX exemplifies cost leadership through flight-proven Falcon 9 architectures sustaining dedicated and ride-share missions. Rocket Lab occupies a position as the dedicated small-lift anchor with Electron production scale. Arianespace represents the European institutional backlog security model through Vega C reliability.
| Leading Market Players |
|---|
| SpaceX |
| Rocket Lab |
| Arianespace |
| Northrop Grumman |
| Lockheed Martin |
| Sierra Nevada Corporation |
| Blue Origin |
| United Launch Alliance |
| Orbital ATK |
| Others |
Supply Flow & Price Mechanics
Ammonium perchlorate supply concentration in the United States and China determines both the spread between dedicated and ride-share launch tiers and the geographic clustering of propulsion system suppliers. Solid propellant feedstock bottlenecks force hybrid motor manufacturers to absorb volatility through long-term offtake contracts or premium spot pricing, compressing margins at the small-lift vehicle tier while ride-share aggregators amortize fixed propulsion costs across multi-manifest missions.
Pricing Analysis
US-East Asian price spreads for dedicated small-lift missions run 40-60% above ride-share per-kilogram baselines due to range congestion premiums at Cape Canaveral and Vandenberg. Three-tier pricing structure across dedicated premium, ride-share standard, and mobile-launch economy levels reflects orbital specificity, schedule certainty, and payload integration complexity as primary differentiation drivers. Pricing pressure stems from SpaceX flight-proven booster reuse collapsing the cost floor for orbital insertion services. University and startup CubeSat operators exhibit highest price sensitivity, while defense agencies and commercial SAR constellation deployers accept substantial premiums for orbital phasing precision.
Supply Chain Analysis
Extended payment terms from prime vehicle manufacturers to specialty propulsion subcontractors now stretch 90-120 days, straining liquidity for turbopump and combustion chamber fabricators. Supply concentrates in the United States, China, and India for liquid oxygen-kerosene engines, with Ukraine and Russia historically contributing titanium alloys and cryogenic valves now subject to procurement redirection. Raw material dependencies span aerospace-grade aluminum-lithium alloys, Inconel superalloys for regenerative cooling, and radiation-hardened avionics components. Single-source vulnerability in ammonium perchlorate production creates tariff exposure for Western hybrid motor developers. Distribution runs through vertically integrated primes with captive satellite manufacturing arms or through pure-play launch brokers aggregating university and government payloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Small satellite launch services fragment across mission architectures, creating specialization niches as constellation operators diverge between premium dedicated slots and cost-minimized ride-share aggregation. Earth observation procurement from precision agriculture and logistics sectors drives demand-side heterogeneity that rewards focused positioning.
For Market Incumbents: Pre-empt emerging mobile sea-launch competitors by securing equatorial range access through partnership with maritime platform operators or accelerated Guiana Space Centre slot allocation. Anchor tenancy contracts with commercial SAR constellation deployers provide cash flow visibility against ride-share aggregator price compression. Backward integration into satellite bus manufacturing captures margin from payload integration services.
For New Entrants and Emerging Players: Build out air-launch capabilities from regional airports to serve responsive defense architectures and rapid-replenishment scenarios where weather scrub tolerance commands premium pricing. Polar orbit insertion for Australian and Brazilian agriculture monitoring represents the most penetrable white space, as incumbent capacity concentrates at mid-latitude sites. Go-to-market positioning around 72-hour call-up responsiveness differentiates against fixed-range scheduling constraints.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated launch-satellite platforms over pure-play vehicle operators. Long-term viability hinges on multi-launch service agreement backlogs extending across the analysis window. Acquisition targets should demonstrate flight-proven reusability engineering or captive constellation anchor demand. The signal to watch is FAA licensing velocity for new vehicle configurations, as regulatory throughput constraints determine effective supply expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
| Strategic Initiative | Industry Significance |
|---|---|
| Reusability Engineering Investment | Propulsive landing development at SpaceX and Rocket Lab collapses per-launch economics and extends competitive moats. |
| Mobile Sea-Launch Platform Deployment | Marine operations from international waters circumvent Eastern and Western US range saturation for equatorial access. |
| Multi-Launch Service Agreement Structuring | Anchor tenancy with commercial Earth observation operators locks in schedule priority and cash flow visibility. |
| Regulatory Licensing Acceleration | FAA streamlined permitting reduces vehicle development cycles and attracts venture capital into new programs. |
| Vertical Satellite Manufacturing Integration | In-house payload production at Rocket Lab enables rapid constellation replenishment and margin capture from integration services. |
Methodological Framework
Cross-validation between primary interviews with launch vehicle program managers, constellation procurement leads, and range safety officers and secondary validation through FAA launch licensing databases, ESA procurement disclosures, and ISRO commercial mission records anchors the qualitative findings. Bottom-up triangulation aggregates vehicle production rates, manifest backlogs, and per-kilogram pricing benchmarks by mission architecture. Top-down calibration cross-checks against national space agency budget allocations and venture capital flow into propulsion technology.
Calibration against historical launch cadence and announced vehicle development programs shapes the projection framework across the modeling period. Segmentation dimensions include service type architecture, payload application, launch platform category, and orbital destination. CAGRs derive from fitted growth curves applied to manifest volume and contract value trajectories. Industry-specific inputs incorporate reusability engineering maturity, regulatory licensing velocity, and solid propellant supply elasticity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed commercial launch firms or breakthrough air-launch system maturation would shift outcomes. Forecasts reflect assumptions regarding FAA regulatory continuity, ITAR export control stability, and ammonium perchlorate supply security. Macroeconomic contraction affecting venture capital availability, geopolitical disruption of component trade flows, or propulsion technology discontinuities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Small Satellite Market
Satellite
Advanced Satellite Market
Satellite
Low-Cost Satellite Market
Satellite
All-Electric Propulsion Satellites Market
Satellite
LEO Satellite Constellation Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Satellite Amplifier Market
Satellite
Russia Satellite Communications Market
Satellite
India Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
Israel Satellite Communications Market
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
Middle East Satellite Imagery Services Market
Satellite
Italy Satellite Communication Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Satellite Link Emulator Market