
 LEO Satellite Constellation Market | 2026-2036
LEO Satellite Constellation Market Size, Share, and Industry Trends Forecast 2026-2036
LEO Satellite Constellation Market Insights
Defense contractor demand is realigning around sovereign connectivity mandates, fragmenting historically concentrated government procurement into multi-vendor programs. SpaceX leverages vertical integration across launch and satellite manufacturing to compress deployment timelines. Lockheed Martin Corporation anchors high-reliability military payloads through specialized bus architectures. OneWeb competes on polar coverage density for maritime and aviation routes.
Low Earth orbit constellations operate at altitudes below 2,000 kilometers, utilizing Ka-band and Ku-band frequencies for high-throughput data relay with sub-50 millisecond latency. Communications satellite types dominate current deployment volumes, while Earth observation platforms capture expanding margin pools from analytics layering. Broadband connectivity applications lead segment value, though disaster management procurement is accelerating fastest as climate resilience budgets harden across government agencies.
The FCC governs spectrum allocation and orbital debris mitigation requirements for US operators, while the FAA coordinates launch licensing and spaceport operations. ESA member states apply CE marking and frequency coordination standards through national regulators. ITU filing deadlines and deorbit rules directly shape constellation sizing and capital deployment schedules. Stakeholders must monitor evolving debris remediation liabilities and spectrum auction structures to calibrate fleet scaling decisions.
Market Dynamics
The FCC's streamlined NGSO licensing framework is compressing deployment timelines and triggering capital redeployment toward larger constellation footprints. This regulatory acceleration, combined with sovereign connectivity mandates fragmenting government procurement, is restructuring competitive positioning across launch, satellite manufacturing, and ground segment supply tiers.
Growth Catalysts
- Broadband demand from rural telecom operators:Unserved and underserved subscriber bases in remote geographies are forcing terrestrial carriers to procure satellite backhaul, redirecting capex toward LEO infrastructure.
- FCC streamlined licensing:Accelerated spectrum allocation and orbital debris compliance pathways reduce regulatory friction, enabling faster fleet scaling and earlier service revenue recognition.
- Ka-band and Ku-band frequency utilization:High-throughput payload architectures deliver sub-50 millisecond latency, opening addressable markets previously reserved for fiber and microwave relay.
Market Restraints
- Launch capacity concentration:Heavy reliance on a limited supplier base for rideshare and dedicated launch services creates bottleneck risk for constellation deployment schedules.
- Orbital debris mitigation compliance:ITU deorbit rules and national remediation liabilities impose non-negotiable capital costs that escalate with fleet size.
- Terrestrial 5G fixed wireless access:Improving last-mile coverage from ground-based networks presents a substitute threat for rural broadband satellite applications in certain geographies.
Strategic Opportunities
- Disaster management procurement acceleration:Climate resilience budget hardening across government agencies is creating dedicated satellite communications procurement streams for emergency response.
- Maritime and aviation route coverage:Polar orbit density advantages position specialized operators to capture connectivity contracts from shipping lines and commercial airlines operating high-latitude routes.
- Earth observation analytics layering:Value-added data services built on imaging constellances are capturing expanding margin pools beyond raw sensor data sales.
Industry Challenges
- RF engineering talent scarcity:Specialist workforce gaps in phased array antenna design and spectrum coordination are extending product development cycles.
- Ground segment integration complexity:Multi-constellation user terminals must interoperate with legacy geostationary systems, complicating firmware and hardware certification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LEO Satellite Constellation Market |
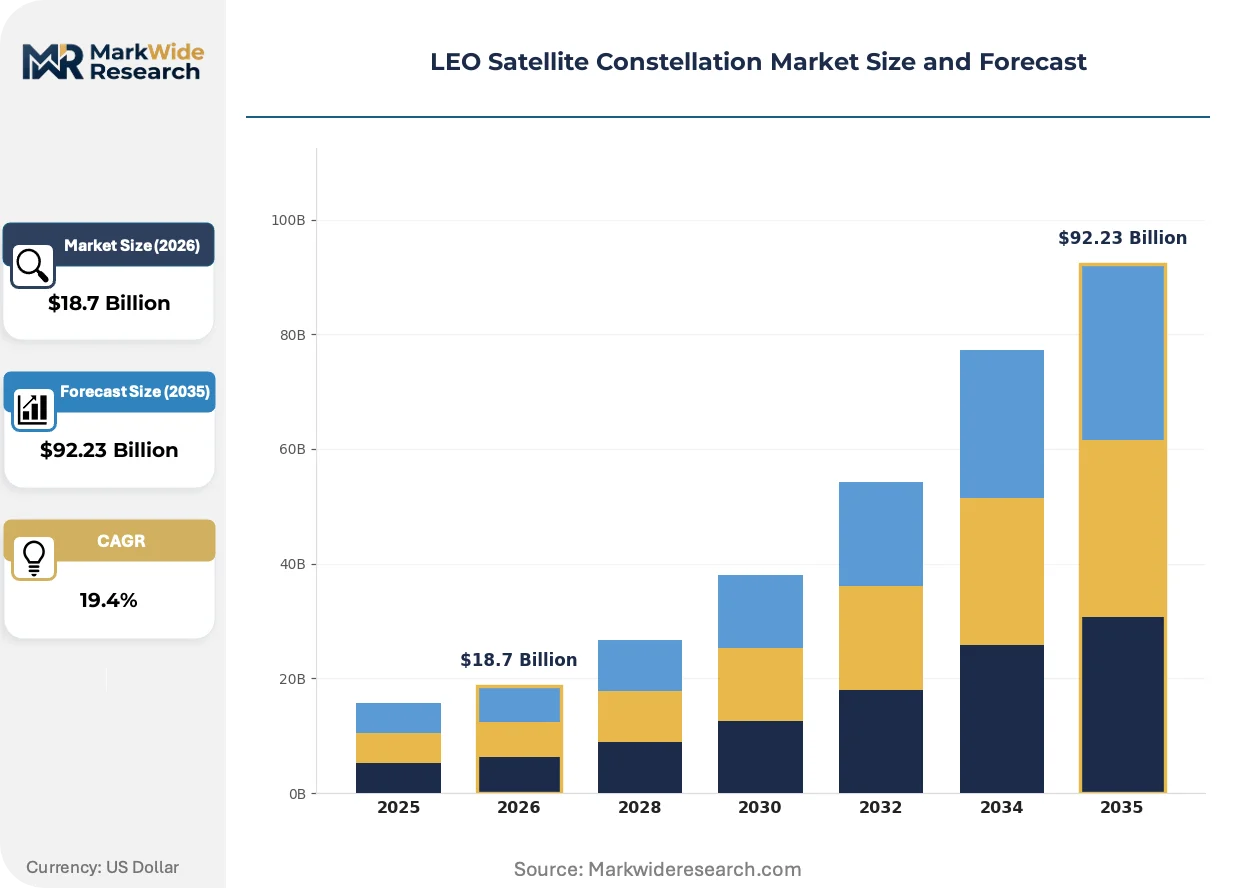
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Crosslink, Ground Station, Inter-Satellite Link, Hybrid Network, Direct-to-User Satellite Type: Communications, Earth Observation, Scientific, Navigation, Technology Demonstration Application: Broadband Connectivity, Disaster Management, Environmental Monitoring, Maritime Surveillance, Asset Tracking End User: Telecommunications Operators, Government Agencies, Scientific Research Organizations, Defense Contractors, Space Agencies |
| Companies Covered | SpaceX, Lockheed Martin Corporation, OneWeb, Amazon Project Kuiper, China Aerospace Science and Technology Corporation, Thales Alenia Space, Iridium Communications, Planet Labs PBC, Telesat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LEO Satellite Constellation Market Trends and Innovations
Payload architectures and manufacturing processes are undergoing fundamental restructuring as constellation operators pursue cost-per-kilogram reductions and deployment velocity. Three interconnected developments are reshaping how satellites are designed, regulated, and procured.
Flat-panel phased array antennas are replacing parabolic dish architectures for user terminals and gateway earth stations. Maritime operators and commercial airlines are adopting these systems for low-profile installation requirements. The shift is modularizing ground segment supply chains, separating RF front-end production from integrated terminal assembly.
ITU filing deadlines and deorbit rules are tightening across ESA member states and the United States, with CE marking and FCC orbital debris requirements now dictating satellite bus design specifications. These mandates are forcing propulsion system upgrades and end-of-life maneuver capability into baseline platform configurations. Smaller constellation operators lacking vertical manufacturing control face disproportionate compliance cost burdens.
Service bundling is displacing standalone capacity leases as the dominant commercial model. Enterprise customers and government buyers are negotiating managed connectivity contracts that integrate terminals, data allowances, and priority access tiers. This pattern is most pronounced in United States defense procurement, where multi-vendor program structures now favor integrated service providers over pure satellite operators.
LEO Satellite Constellation Market Segmentation
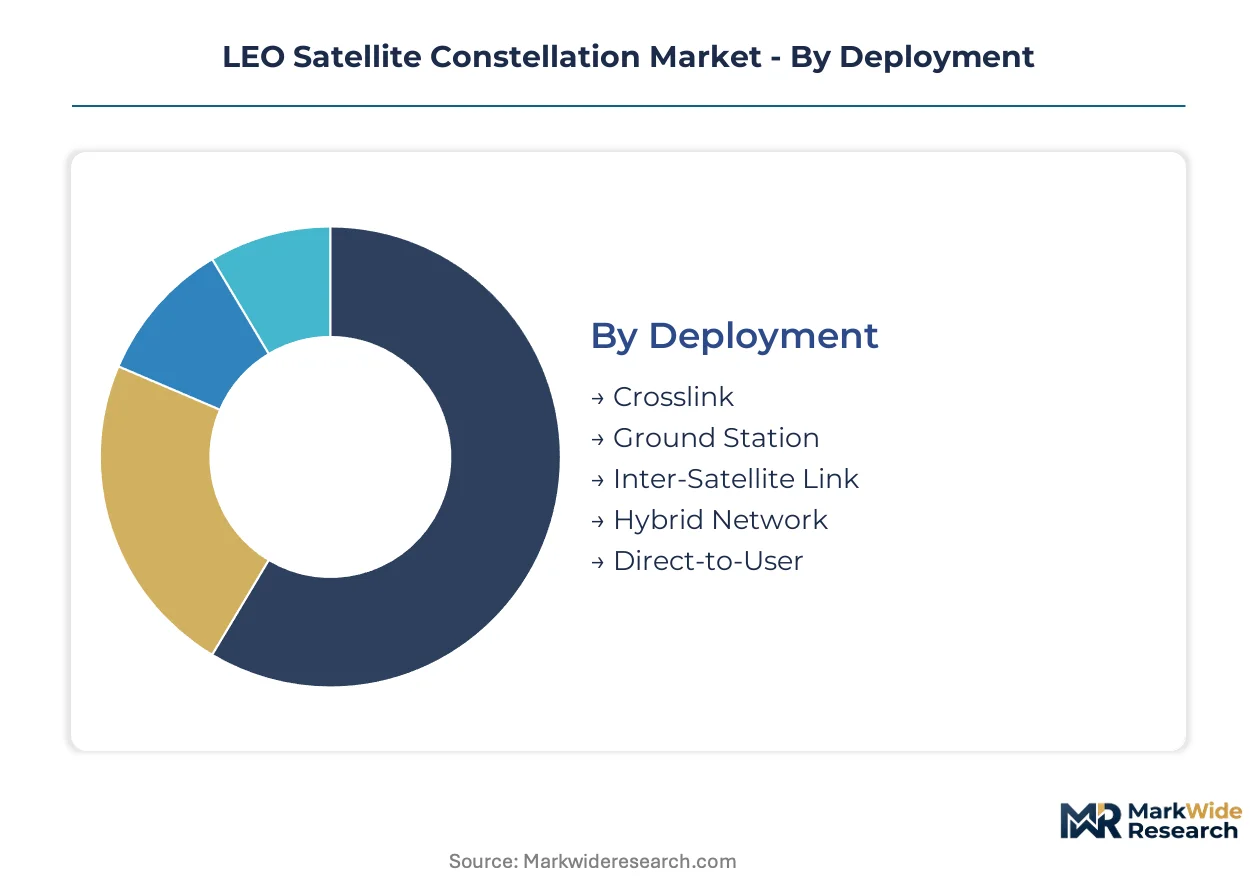
LEO constellation architectures fragment across deployment topology, payload function, and customer procurement structure. Each segmentation axis reveals distinct margin profiles, regulatory exposure, and capital intensity requirements that shape vendor positioning.
Deployment:
Ground infrastructure integration depth separates standalone terminal sales from embedded network services, with hybrid architectures commanding premium positioning.
- Crosslink:Laser-based inter-satellite relays enable mesh routing without ground gateway dependency. Defense contractors in the United States prioritize this architecture for contested environment resilience, driving procurement toward hardened optical terminals.
- Ground Station:Terrestrial gateway networks aggregate traffic for backhaul to fiber points of presence. Rural telecom operators concentrate demand here, procuring managed hub services rather than capital-intensive infrastructure ownership.
- Inter-Satellite Link:Radio-frequency cross-satellite bridges supplement optical systems in degraded atmospheric conditions. Maritime surveillance applications favor this redundancy for polar route continuity.
- Hybrid Network:Combined space-ground routing optimizes latency for latency-sensitive enterprise workloads. Asset tracking platforms embed these capabilities for real-time fleet coordination across dispersed geographies.
- Direct-to-User:Terminal-to-satellite links bypass intermediate aggregation layers. Broadband connectivity providers deploy flat-panel phased arrays to reduce subscriber equipment footprints.
Ground Station leads volumes today; Crosslink is gaining share fastest.
Satellite Type:
Cost tier stratification separates mass-manufactured communications platforms from specialized scientific payloads with discrete supply chains.
- Communications:High-throughput Ka-band and Ku-band payloads dominate fleet deployment. Broadband connectivity applications absorb the majority of manufacturing capacity, with Ka-band utilization expanding for sub-50 millisecond latency service tiers.
- Earth Observation:Multi-spectral and synthetic aperture radar sensors capture imagery for analytics layering. Environmental monitoring agencies drive procurement, layering AI-derived change detection atop raw sensor feeds.
- Scientific:Precision instrumentation buses support space weather and fundamental physics missions. Space agencies fund these through dedicated budget lines with extended development timelines.
- Navigation:Augmentation payloads enhance GNSS accuracy for aviation and maritime safety systems. Technology demonstration programs validate next-generation signal architectures before operational deployment.
- Technology Demonstration:Experimental bus configurations test novel propulsion, power, or thermal management approaches. Defense contractors utilize these for risk reduction ahead of operational constellation commitments.
Communications anchors current fleet value; Earth Observation shows steepest margin expansion from data services.
Application:
Customer type concentration varies sharply, with government procurement fragmentation creating multi-vendor opportunities distinct from consolidated telecom operator sourcing.
- Broadband Connectivity:Consumer and enterprise internet access via LEO relay constitutes the primary revenue pool. Telecommunications operators in unserved rural geographies procure managed capacity agreements rather than satellite ownership.
- Disaster Management:Emergency communications restoration for climate-driven events attracts hardened budget allocations. Government agencies are accelerating dedicated procurement streams as resilience mandates harden.
- Environmental Monitoring:Deforestation, ice sheet, and ocean condition tracking serves regulatory compliance and research objectives. Scientific research organizations coordinate multi-sensor constellations through international partnership frameworks.
- Maritime Surveillance:Automatic identification system integration and dark vessel detection support coastal security and fisheries enforcement. Polar route density advantages position specialized operators for shipping line contracts.
- Asset Tracking:Low-data-rate messaging for logistics fleets extends connectivity to terrestrial network gaps. Defense contractors embed these capabilities for supply chain visibility in denied areas.
Broadband Connectivity commands current segment value; Disaster Management procurement is expanding most quickly.
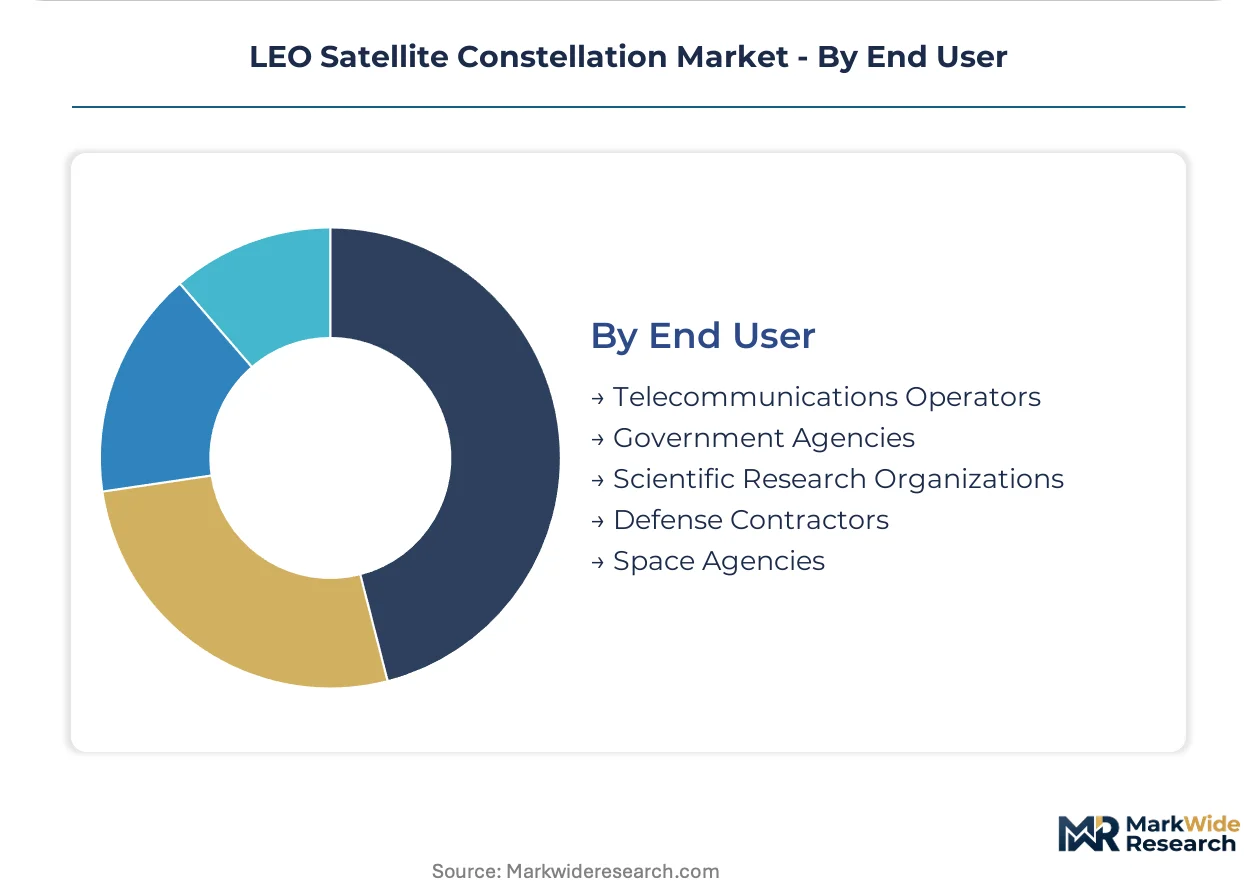
End User:
Maturity differentiation separates established procurement frameworks from emerging customer segments with evolving technical specifications.
- Telecommunications Operators:Terrestrial carriers procure satellite backhaul for rural network extension. These buyers negotiate service-level agreements with guaranteed availability tiers rather than capacity leases.
- Government Agencies:Civilian departments source connectivity for remote offices and emergency response. FCC licensing compliance and ITU coordination requirements structure vendor selection criteria.
- Scientific Research Organizations:Academic and institutional users prioritize data continuity for long-duration studies. International partnership frameworks distribute mission costs across multiple national space agencies.
- Defense Contractors:Sovereign connectivity mandates fragment historically concentrated procurement into multi-vendor programs. These buyers require specialized bus architectures with anti-jam and low-probability-of-intercept capabilities.
- Space Agencies:National programs fund technology demonstration and flagship science missions. ESA member states coordinate through CE marking and frequency coordination standards.
Telecommunications Operators dominate current procurement volumes; Defense Contractors are climbing the fastest as sovereign mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent clusters in the United States, Germany, and Japan anchor constellation development. Regulatory frameworks in these jurisdictions directly shape fleet deployment schedules and capital allocation patterns across the sector.
United States
SpaceX and Amazon Project Kuiper drive manufacturing scale in California and Washington state. The FCC's streamlined NGSO licensing compresses deployment timelines while imposing orbital debris mitigation requirements. Houston and Denver host ground station clusters serving rural telecom backhaul contracts.
China
China Aerospace Science and Technology Corporation leads state-backed constellation deployment for broadband and navigation augmentation. MIIT spectrum allocation and GB standards govern Ka-band utilization and satellite bus specifications. Beijing-Tianjin-Hebei corridor concentrates manufacturing for high-throughput payloads.
France
Thales Alenia Space anchors European satellite manufacturing in Toulouse and Cannes. ESA frequency coordination standards and CE marking requirements structure procurement for government and commercial buyers. The Sud-Ouest region hosts specialized suppliers for optical inter-satellite link terminals.
United Kingdom
OneWeb maintains polar coverage operations from London and satellite manufacturing partnerships in Glasgow. UK Space Agency funding supports sovereign connectivity mandates fragmenting defense procurement. Cornwall spaceport development targets dedicated small-launch services for constellation replenishment.
Canada
Telesat advances Lightspeed constellation deployment from Ottawa with government-backed financing. Canadian Space Agency coordination with FCC and ITU filing deadlines shapes spectrum strategy. Montreal and Toronto house ground segment engineering teams for enterprise managed services.
LEO Satellite Constellation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across launch, satellite manufacturing, and ground segment tiers. The vendor base stratifies into three layers: vertically integrated operators controlling launch through service delivery; specialized bus and payload manufacturers supplying multi-vendor programs; and ground segment integrators managing multi-constellation terminal interoperability. Capacity expansion through dedicated launch manifests and strategic partnerships for spectrum coordination represent the dominant competitive moves.
Among vertically integrated operators, SpaceX exemplifies the archetype of launch-captive constellation deployment, while Amazon Project Kuiper occupies a position as a diversified technology conglomerate entering satellite services. OneWeb represents the focused pure-play model competing on polar coverage density for maritime and aviation routes.
| Leading Market Players |
|---|
| SpaceX |
| Lockheed Martin Corporation |
| OneWeb |
| Amazon Project Kuiper |
| China Aerospace Science and Technology Corporation |
| Thales Alenia Space |
| Iridium Communications |
| Planet Labs PBC |
| Telesat |
| Others |
Pricing and Supply Chain Analysis
Sovereign connectivity mandates from defense contractors are forcing satellite bus manufacturers to absorb propulsion system upgrades and end-of-life maneuver capabilities into baseline configurations, compressing margins for operators lacking captive manufacturing control.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for managed connectivity contracts as SpaceX and Amazon Project Kuiper scale manufacturing. Three-tier pricing structure across premium, standard, and economy levels segments enterprise buyers by guaranteed availability tiers and priority access rights. Cost compression in ground segment hardware is intensifying because flat-panel phased array antennas modularize RF front-end production from terminal assembly. Rural telecom operators exhibit highest price sensitivity, while defense contractors prioritize anti-jam specifications over unit economics.
Supply Chain Analysis
ITU filing deadlines and FCC orbital debris requirements are gating supplier qualification for US constellation operators, forcing propulsion system certifications and end-of-life maneuver documentation. Manufacturing concentrates in the United States, China, and France for high-throughput payloads and specialized bus architectures. Supply chains draw from gallium nitride semiconductors, carbon fiber composite structures, and Hall-effect thruster propulsion modules. Single-source vulnerability runs through limited qualified suppliers for laser-based inter-satellite optical terminals. Distribution runs through vertically integrated operators controlling launch through service delivery, specialized bus manufacturers supplying multi-vendor programs, and ground segment integrators managing multi-constellation terminal interoperability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flat-panel antenna cost curves and captive launch economics are expanding addressable margins for operators controlling manufacturing through service delivery, while tier-2 suppliers face qualification cost barriers.
For Market Incumbents: Deepen backward integration into phased array antenna manufacturing to capture ground segment margin pools and reduce dependency on modular RF front-end suppliers. Accelerate dedicated launch manifest commitments to secure deployment slots amid capacity concentration bottlenecks. Lockheed Martin Corporation and Thales Alenia Space anchor positions through specialized military payload architectures that emerging competitors cannot replicate without multi-year certification investments. For New Entrants and Emerging Players: Launch via managed service bundling rather than standalone capacity leases to bypass upfront infrastructure ownership barriers and capture enterprise procurement preference for integrated contracts. White-space targets include polar route maritime coverage where OneWeb maintains density advantages, and disaster management procurement streams hardened by climate resilience budget allocations across civilian government agencies. Target earth observation analytics layering for fastest margin expansion beyond raw sensor data sales. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized optical inter-satellite link terminal manufacturers serving defense multi-vendor programs. Long-term viability hinges on spectrum coordination capabilities and ITU filing execution speed rather than manufacturing scale alone. Acquisition target archetypes include ground segment integrators with multi-constellation firmware certification pathways. The signal to watch is FCC enforcement action on orbital debris remediation liabilities as fleet sizes expand.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Integration into Launch Services | Captive Falcon 9 and Starship capacity compresses deployment timelines for SpaceX Starlink against rideshare-dependent competitors. |
| Flat-Panel Phased Array Manufacturing Scale-Up | Thales Alenia Space and specialized suppliers modularize ground segment production for maritime and aviation terminal markets. |
| Optical Inter-Satellite Link Deployment | Laser-based crosslink architectures enable contested environment resilience for US defense contractor procurement. |
| Managed Connectivity Service Bundling | Integrated terminal, data allowance, and priority access contracts displace standalone capacity leases in enterprise and government segments. |
| Polar Orbit Density Expansion | OneWeb leverages UK Space Agency backing to capture high-latitude maritime and aviation route contracts. |
Research Methodology
Bottom-up broadband connectivity and defense procurement modeling reconciled against top-down satellite manufacturing capacity tracking forms the analytical core. Primary interviews with constellation program directors, FCC licensing attorneys, ground segment procurement officers, and optical terminal engineering leads combined with secondary validation from FCC NGSO licensing databases, ITU satellite network filings, ESA procurement records, and SEC 10-K disclosures from publicly traded operators. Triangulation across demand-side service contract values and supply-side manufacturing throughput yields volume and value estimates.
Input-output matrices map deployment topology, payload function, and end-user procurement structure against capital deployment schedules and regulatory filing deadlines across the analysis window. Segmentation dimensions include crosslink versus ground station architecture, communications versus earth observation payload type, broadband versus disaster management application, and telecommunications operator versus defense contractor end user. CAGRs derive from fleet deployment trajectories, service revenue recognition timing, and pricing evolution for managed connectivity contracts. Industry-specific inputs include ITU coordination timeline assumptions and FCC orbital debris compliance cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ITU filing deadline slippage or launch capacity disruption scenarios. Forecasts reflect documented assumptions regarding spectrum allocation timelines, deorbit rule enforcement intensity, and sovereign connectivity mandate proliferation. A model refresh is warranted upon material change in FCC licensing velocity or ITU regulatory posture.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Military Satellite Market
Satellite
Satellite Link Emulator Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
ASEAN Satellite-Based Earth Observation Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
Satellite Manufacturing Market
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Spain Satellite Imagery Services Market
Satellite
Optical Satellite Communication Market
Satellite
Advanced Satellite Market
Satellite
North America Remote Sensing Satellites Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Nano and Microsatellite Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
France Satellite Imagery Services Market