
 Europe Polypropylene Compounds Market | 2026-2036
Europe Polypropylene Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polypropylene Compounds Market Insights
Modular material sourcing is restructuring how European automotive Tier-1s configure their polypropylene supply. Borealis AG leverages its integrated Austrian production complex to sustain long-term contracts with German OEMs. Lyondellbasell Industries Holdings B.V. anchors its position through specialized high-flow compounds for thin-wall packaging. TotalEnergies differentiates via its European compounding network that navigates divergent national recycling mandates.
Europe Polypropylene Compounds are thermoplastic formulations combining polypropylene resin with mineral fillers, glass fibers, elastomer modifiers, or flame retardants to achieve specified melt flow indices, impact resistance, and thermal stability. These materials serve primarily to reduce component weight while maintaining structural integrity in injection-molded and extruded parts. Copolymer grades lead volume consumption in automotive bumper and interior applications where low-temperature ductility commands premium positioning. Homopolymer compounds dominate rigid packaging segments where stiffness and clarity requirements align with established processing infrastructure. Blends and alloys represent the fastest-expanding category as formulators respond to OEM demands for paintable surfaces and recycled-content integration.
REACH compliance and the EU Green Deal's carbon-border adjustment mechanisms shape compound formulations by restricting certain additive chemistries and incentivizing bio-based feedstock adoption. ECHA substance evaluations and the F-Gas Regulation further constrain blowing-agent selections in expanded polypropylene applications. Manufacturers must monitor evolving Extended Producer Responsibility frameworks across France, Germany, and Italy where packaging recovery targets directly affect compound specification requirements.
Market Dynamics
Automotive OEMs in Germany, France, and Italy are consolidating polypropylene compound specifications to reduce supplier complexity while meeting divergent national recycling mandates under the EU Green Deal.
Growth Catalysts
- EU Green Deal carbon-border mechanisms:The regulation incentivizes bio-based feedstock adoption, pushing compounders to reformulate with recycled-content integration.
- Automotive lightweighting mandates:German OEMs specify glass-fiber-reinforced grades for bumper and interior applications to meet emissions targets.
- Thin-wall packaging expansion:High-flow compounds gain traction in French and Italian rigid packaging hubs seeking processing efficiency gains.
Market Restraints
- Propylene feedstock volatility:Naphtha-derived monomer costs fluctuate with crude oil benchmarks, compressing compounder margins.
- REACH additive restrictions:ECHA substance evaluations constrain flame-retardant and blowing-agent chemistries in expanded polypropylene.
- Specialized compounding concentration:Austrian and Belgian production clusters create geographic supply vulnerability for southern European converters.
Strategic Opportunities
- Spanish automotive supplier base:Underpenetrated relative to German clusters, offering volume expansion for copolymer grades in seat structures.
- Paintable surface alloys:Formulators blend thermoplastic olefins with polypropylene to eliminate primer steps in exterior trim.
- Extended Producer Responsibility differentiation:Italian packaging recovery targets create premium positioning for traceable recycled-content compounds.
Industry Challenges
- Multi-jurisdiction compliance staffing:Compounders maintain separate formulation databases for French, German, and Italian EPR reporting requirements.
- Recycled feedstock certification timelines:ISCC PLUS and EuCertPlast validation delays compound qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polypropylene Compounds Market |
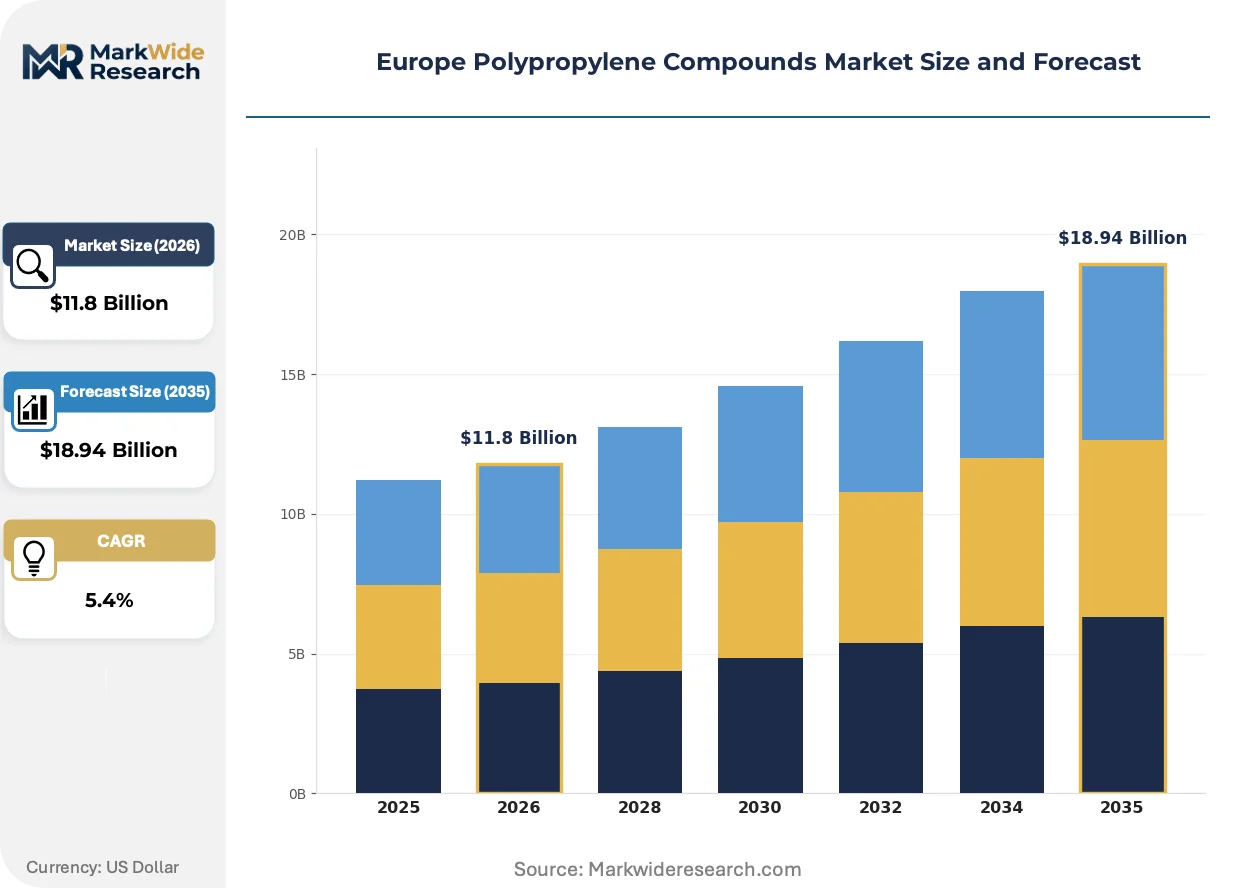
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Blends, Alloys Application: Automotive Parts, Packaging, Consumer Goods, Electrical Components End User: OEMs, Retailers, Distributors, Manufacturers Form: Granules, Sheets, Films, Fibers |
| Companies Covered | Lyondellbasell Industries Holdings B.V., Borealis AG, SABIC, Exxon Mobil Corporation, Sumitomo Chemical Co., Ltd, TotalEnergies, Repsol, Trinseo, Rialti S.P.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polypropylene Compounds Market Trends and Innovations
Compound formulation is pivoting from performance-only specifications to integrated sustainability credentials, with mechanical recycling streams and bio-attributed feedstocks now treated as core design variables rather than aftermarket additives.
Distributed mechanical recycling systems are decentralizing compound supply chains across Europe. Post-industrial scrap from German automotive injection molders feeds regional recompounding facilities in Bavaria and Baden-Württemberg. This proximity reduces transport emissions and enables just-in-time recycled-content delivery to Tier-1 suppliers.
REACH authorization procedures are compressing the available additive palette for flame-retardant grades. ECHA's SVHC candidate list expansion forces reformulation of expanded polypropylene used in automotive seating and protective packaging. German compounders are accelerating halogen-free phosphorus-based alternatives to maintain automotive OEM approvals.
Specification consolidation is compressing supplier rosters at major automotive OEMs. Procurement teams at German and French manufacturers now mandate single-source accountability for recycled-content claims across bumper, dashboard, and door panel applications. Tier-1 molders respond by qualifying fewer compounders with pan-European certification coverage.
Europe Polypropylene Compounds Market Segmentation
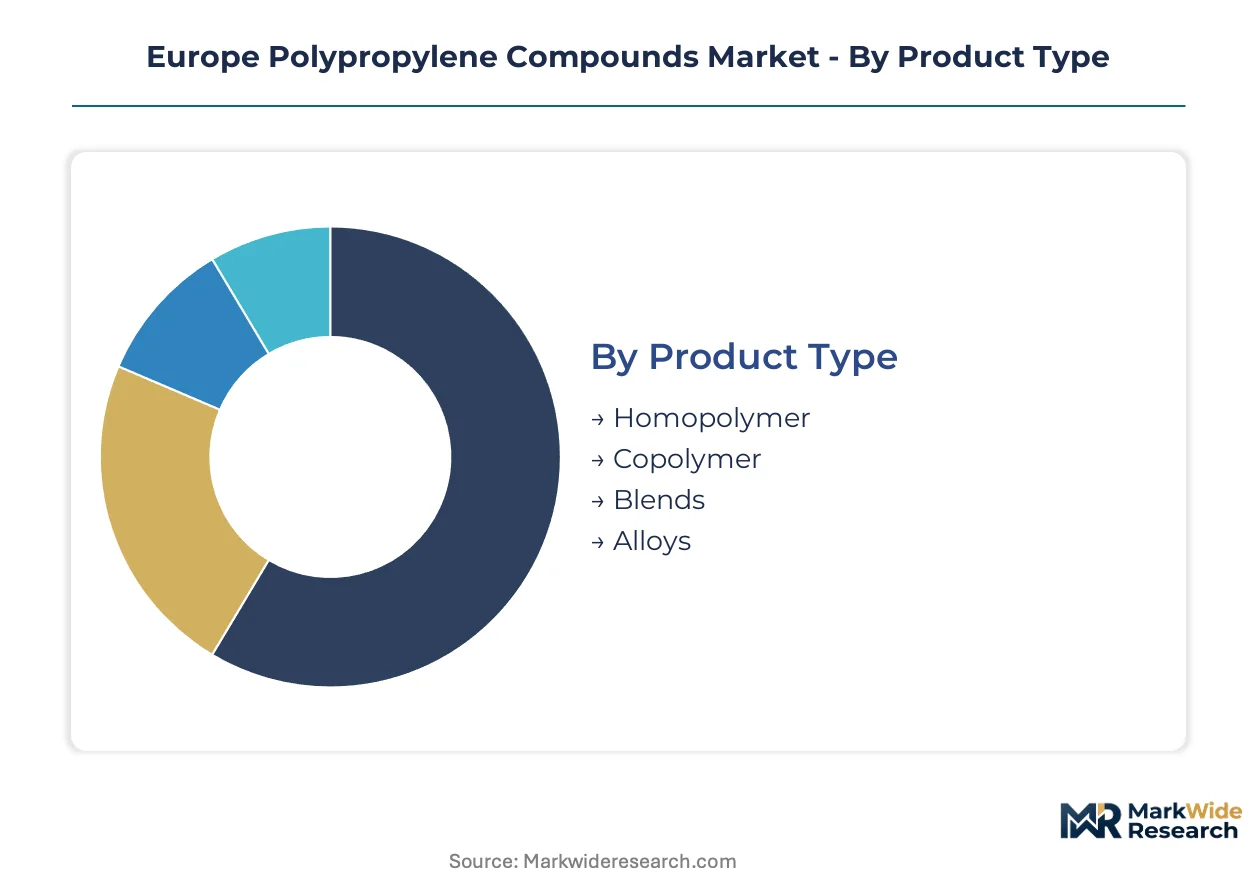
Polypropylene compound specifications diverge sharply across European manufacturing verticals, with automotive OEMs in Germany and packaging converters in France driving incompatible performance requirements that fragment supplier portfolios. Each segmentation dimension reveals distinct margin structures and certification barriers that reshape competitive positioning.
Product Type:
Supply concentration in Austrian and Belgian production clusters favors homopolymer and copolymer grades, while specialty blends and alloys remain dispersed across smaller compounders.
- Homopolymer:High crystallinity formulations deliver superior stiffness and heat resistance for rigid packaging applications. German injection molders in Bavaria specify these grades for thin-wall containers where processing speed commands premium pricing under Extended Producer Responsibility frameworks.
- Copolymer:Ethylene-modified structures provide low-temperature ductility critical for automotive bumper and interior components. Demand concentrates at Tier-1 suppliers serving Stuttgart and Munich OEM clusters, where REACH-compliant additive packages determine qualification timelines.
- Blends:Thermoplastic olefin combinations target paintable surface applications in French automotive exterior trim.
- Alloys:Engineered formulations integrate recycled-content streams for Italian packaging recovery targets.
Today's leader: Copolymer. Tomorrow's challenger: Alloys.
Application:
Cost tier differentiation separates commodity packaging compounds from automotive grades requiring ISO 9001 and IATF 16949 certification.
- Automotive Parts:Glass-fiber-reinforced and mineral-filled compounds reduce component weight for emissions compliance. German OEMs consolidate specifications around bumper, dashboard, and door panel applications, mandating pan-European recycled-content traceability that favors large compounders with ISCC PLUS coverage.
- Packaging:High-flow grades enable thin-wall rigid container production with reduced cycle times. French and Italian converters drive demand for clarified homopolymers where EU Green Deal carbon-border mechanisms incentivize bio-attributed feedstock adoption.
- Consumer Goods:Impact-modified formulations serve appliance housings and furniture components across Benelux manufacturing.
- Electrical Components:Flame-retardant grades face ECHA SVHC constraints that compress available additive chemistries.
Volume concentrates in Automotive Parts. Margin expansion sits with Electrical Components.
End User:
Customer type determines contract structure, with OEMs demanding long-term volume commitments and retailers prioritizing spot-market flexibility.
- OEMs:German automotive manufacturers specify compounds through approved supplier lists with embedded recycled-content minimums. Procurement teams mandate single-source accountability across component categories, compressing qualified compounder rosters to pan-European operators.
- Retailers:Private-label packaging buyers in France and Italy source through distributors with rapid formulation switching capabilities.
- Distributors:Pan-European logistics networks aggregate demand from fragmented converter bases in Spain and Eastern Europe.
- Manufacturers:Tier-2 and Tier-3 component producers access compounds through regional recompounding facilities.
OEMs anchor contract value. Distributors capture volume growth.
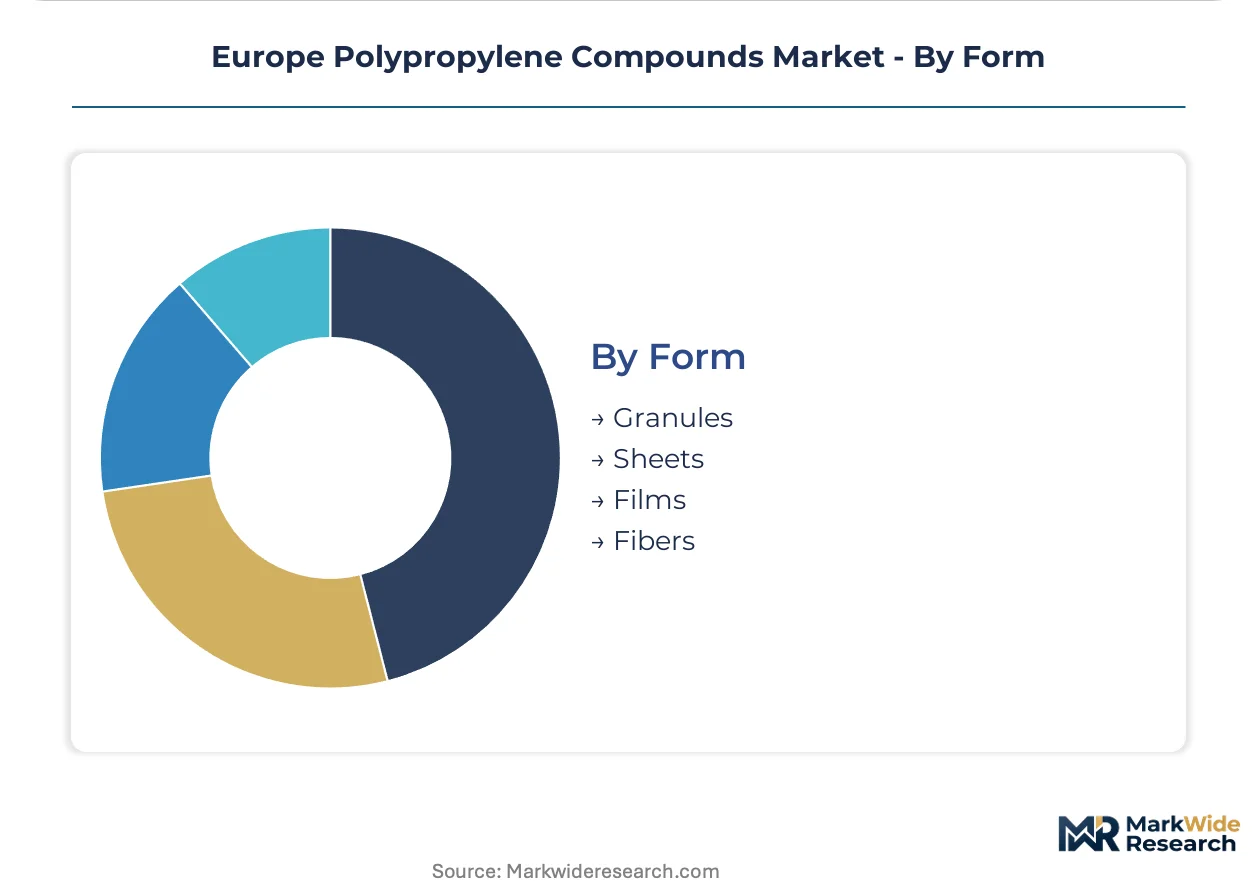
Form:
Processing infrastructure legacy across European converter bases locks in granule dominance while film and fiber formats face substitution pressure.
- Granules:Standard pelletized feedstock serves injection molding and extrusion across all major applications. Austrian compounders leverage integrated steam cracker proximity to supply German automotive clusters with just-in-time delivery.
- Sheets:Thermoformed applications in French food packaging require clarified copolymer grades with specific gauge tolerances.
- Films:Biaxially oriented variants compete with PET in premium packaging segments.
- Fibers:Staple and filament grades serve nonwoven applications in hygiene and filtration.
Granules dominate throughput. Films offer the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene compounding originated in post-war European petrochemical complexes, with German and Belgian integrated sites establishing the foundational production architecture that now spans the continent. The current landscape reflects this legacy through clustered manufacturing nodes serving distinct national regulatory environments.
Germany
Automotive OEMs in Stuttgart and Munich drive specification consolidation for glass-fiber-reinforced grades meeting emissions targets. The KBA enforces type-approval standards that cascade into compound qualification requirements. Bavarian and Baden-Württemberg injection molders anchor demand through just-in-time supply contracts with Austrian producers.
France
Packaging converters in Île-de-France prioritize high-flow homopolymers for thin-wall rigid containers under Extended Producer Responsibility frameworks. ANSM and environmental agencies coordinate recycled-content traceability mandates. Lyon-area food packaging specialists specify clarified copolymer grades with bio-attributed feedstock credentials.
Italy
Automotive exterior trim manufacturers in Piedmont and Lombardy source paintable thermoplastic olefin blends eliminating primer processing steps. National packaging recovery targets under EU Green Deal implementation create premium positioning for certified recycled-content compounds. Milan-based compounders navigate divergent regional EPR reporting requirements.
Spain
Underpenetrated automotive supplier bases in Catalonia and the Basque Country offer expansion vectors for seat structure applications. Spanish regulators align with EU REACH and F-Gas Regulation frameworks while maintaining distinct national waste management protocols. Barcelona-area Tier-2 molders represent latent demand for copolymer grades.
Belgium
Antwerp-Rotterdam petrochemical corridor hosts integrated steam cracker and compounding complexes supplying pan-European automotive clusters. Belgian environmental authorities enforce stringent additive disclosure requirements under REACH Article 33. Flemish recompounding facilities process post-industrial scrap from neighboring German molders.
Europe Polypropylene Compounds Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification coverage and recycled-content integration capabilities. The vendor base stratifies between pan-European operators with ISCC PLUS accreditation and regional specialists serving single-country markets. Three archetypes dominate: integrated petrochemical majors with captive monomer supply, independent compounders with formulation agility, and distributed mechanical recyclers with proximity logistics. Capacity expansion and strategic partnerships constitute the primary competitive vectors as procurement teams compress approved supplier lists.
Within the integrated major tier, Borealis AG and Lyondellbasell Industries Holdings B.V. exemplify divergent strategic positioning. Borealis represents Austrian production complex integration serving German OEM long-term contracts. Lyondellbasell occupies a position anchored through specialized compound portfolios. TotalEnergies sits within the network-optimization archetype, navigating fragmented national recycling mandates through distributed European compounding assets.
| Leading Market Players |
|---|
| Lyondellbasell Industries Holdings B.V. |
| Borealis AG |
| SABIC |
| Exxon Mobil Corporation |
| Sumitomo Chemical Co., Ltd |
| TotalEnergies |
| Repsol |
| Trinseo |
| Rialti S.P.A. |
| Others |
Pricing and Supply Chain Analysis
Specialized polymer formulation chemists in the Antwerp-Rotterdam corridor command wage premiums that compress margins for southern European compounders, widening the spread between Austrian-integrated premium grades and Spanish spot-market alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the European polypropylene compounds landscape. Price differentiation rests on ISCC PLUS certification status and glass-fiber loading percentages, with automotive OEMs paying premiums for traceable recycled-content grades. Cost compression in economy-tier homopolymers is intensifying because naphtha feedstock volatility transfers directly to converter contracts. Retail packaging buyers exhibit highest price sensitivity, while German Tier-1 automotive suppliers prioritize qualification stability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through long-term offtake agreements with Austrian and Belgian integrated producers. Geographic supply concentrates in Austria, Belgium, and Germany, with peripheral dependence on Italian specialty blenders. Raw material flows draw from North Sea naphtha crackers, Saudi propane dehydrogenation units, and post-industrial scrap collection networks. Single-source vulnerability around Austrian steam cracker complexes exposes downstream compounders to force majeure disruption. Distribution runs through pan-European logistics networks with regional recompounding facilities in Bavaria and Baden-Württemberg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Polypropylene Compounds Market functions as a stable compounder, with EU Green Deal carbon-border mechanisms providing durable demand tailwinds for certified sustainable grades.
For Market Incumbents: To counter specification consolidation at German OEMs, deepen backward integration into bio-attributed feedstock supply and accelerate ISCC PLUS certification coverage across southern European compounding assets. Prioritize pan-European accountability structures that satisfy French, German, and Italian EPR reporting through unified formulation databases. For New Entrants and Emerging Players: Enter via Spanish automotive seat structure applications, where Tier-2 molder density remains below German saturation levels. Target paintable thermoplastic olefin blends for Italian exterior trim manufacturers seeking primer elimination. Pursue distributed mechanical recycling models with proximity logistics to Bavarian injection molders. For Investors and Strategic Acquirers: Petrochemical majors seeking circular economy positioning are the most active acquirer in this space, prioritizing targets with EuCertPlast validation and regional recompounding footprints. Five-to-ten-year viability hinges on recycled feedstock certification capabilities rather than virgin resin access. Monitor ISCC PLUS accreditation timelines as the inflection indicator for compound qualification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Attributed Feedstock | Captures EU Green Deal carbon-border premium pricing for Austrian and German compounders. |
| ISCC PLUS Certification Expansion | Unlocks German OEM approved supplier list qualification for recycled-content minimum mandates. |
| Regional Recompounding Facility Buildout | Reduces transport emissions and enables just-in-time delivery to Bavarian automotive clusters. |
| Halogen-Free Flame-Retardant Reformulation | Maintains automotive seating approvals under ECHA SVHC candidate list constraints. |
| Long-Term Supply Agreement with Tier-1 Molders | Secures volume commitments through specification consolidation at Stuttgart and Munich OEMs. |
Research Methodology
Coverage spans Western Europe and select Eastern European markets, with primary inputs from each. The analysis combines structured interviews with polymer chemists at compounding facilities, procurement directors at German Tier-1 automotive suppliers, technical sales managers at distribution networks, and regulatory compliance officers navigating REACH frameworks. Secondary validation draws from ECHA substance evaluation databases, Cefic industry statistics, customs trade flow records, and SEC filings of listed petrochemical majors. Bottom-up volume modeling triangulates with top-down demand aggregation from end-use sector consumption patterns.
Segmentation granularity extends to product type, application vertical, end-user category, and physical form across the projection horizon. The analytical framework models automotive content per vehicle, packaging wall-thickness trends, and recycled-content integration rates as industry-specific demand drivers. CAGRs derive from regression analysis of historical consumption patterns against regulatory mandate implementation schedules. Pricing trajectories incorporate feedstock cost pass-through elasticities and certification premium sustainability.
Inputs from ECHA regulatory filings and OEM specification databases were available through the study window; gaps in real-time recycled feedstock spot pricing introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and automotive emissions target stringency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Superacids Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Saudi Arabia Collagen Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Toner Resins Market
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
China Collagen Market
Specialty Compounds
Lauramidopropyl Betaine Market