
 Chlorzoxazone Market | 2026-2036
Chlorzoxazone Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorzoxazone Market Analysis
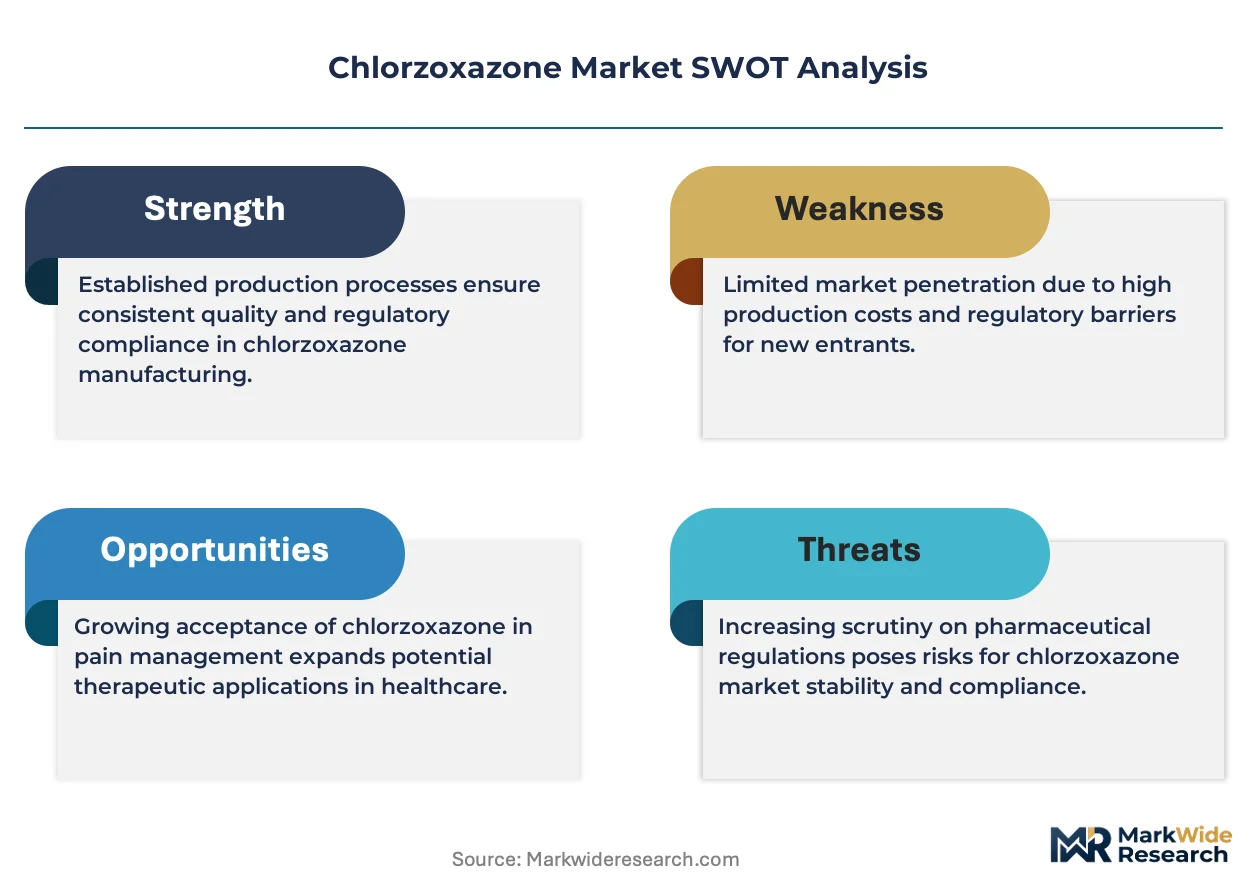
The FDA's Current Good Manufacturing Practice enforcement for oral solid dosage forms is expanding compliance burdens across generic muscle relaxant suppliers. Lupin Limited leverages integrated API-to-tablet operations to sustain cost competitiveness in North American tenders. Teva Pharmaceutical Industries Limited anchors its position through broad retail pharmacy distribution networks. Glenmark Pharmaceuticals Limited differentiates via specialized pain-relief portfolio depth across emerging markets.
Chlorzoxazone is a centrally acting skeletal muscle relaxant, chemically classified as a benzoxazolone derivative with the molecular formula C7H4ClNO2, primarily manufactured through condensation of 2-amino-4-chlorophenol with urea followed by cyclization. It functions by inhibiting reflex arcs at the spinal cord and subcortical levels, reducing muscle spasms without directly impacting skeletal muscle contractility. Tablet formulations dominate volume due to established bioequivalence profiles and patient compliance advantages, while hospital procurement of injections is accelerating for acute postoperative spasticity management. The muscle relaxant application commands the largest revenue pool, though pain relief co-formulations with analgesics are capturing margin concentration in retail channels.
The FDA's bioequivalence standards for generic chlorzoxazone tablets shape formulation development costs and ANDA approval timelines, while the EMA's Good Manufacturing Practice inspections for active pharmaceutical ingredient sites determine European market access eligibility. India's CDSCO mandates dissolution profile documentation that filters out subscale domestic manufacturers from export-oriented production. Stakeholders must monitor evolving pharmacovigilance requirements for centrally acting muscle relaxants, as regulatory agencies tighten surveillance on sedation-related adverse event reporting across all dosage forms.
Market Dynamics
FDA's tightened Current Good Manufacturing Practice enforcement for oral solid dosage forms is redrawing supplier qualification thresholds, forcing generic manufacturers to absorb compliance costs or exit hospital procurement channels entirely.
Growth Catalysts
- Hospital formulary expansion:Acute postoperative spasticity management protocols in US inpatient settings are expanding chlorzoxazone injection procurement volumes.
- Aging demographics:Rising physical therapy referral rates among Medicare populations sustain tablet prescription velocity in retail pharmacy networks.
- Pain-relief co-formulations:Fixed-dose combinations with analgesics are capturing retail margin concentration through pharmacist-driven substitution.
Market Restraints
- API supply concentration:China and India host over 80% of benzoxazolone intermediate production, exposing formulators to geopolitical shipping disruptions.
- ANDA approval timelines:FDA bioequivalence study requirements for generic chlorzoxazone tablets extend development cycles by 18-24 months versus historical baselines.
- Substitution by tizanidine:Centrally acting alpha-2 agonists with shorter half-lives are displacing chlorzoxazone in chronic spasticity regimens.
Strategic Opportunities
- Brazilian hospital sector:ANVISA's streamlined generic registration pathway for essential medicines opens tender access for muscle relaxant suppliers.
- Transdermal delivery systems:Patch formulations bypass first-pass metabolism and address sedation compliance issues in elderly polypharmacy patients.
- EMA pharmacovigilance alignment:Centralized adverse event reporting harmonization reduces duplicate compliance costs for EU-27 market entry.
Industry Challenges
- Analytical method transfer:Dissolution profile documentation per India's CDSCO specifications requires specialized equipment investments that filter subscale domestic manufacturers from export production.
- Legacy ERP integration:Serialization compliance for FDA track-and-trace mandates forces mid-tier formulators to replace inventory management systems entirely.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorzoxazone Market |
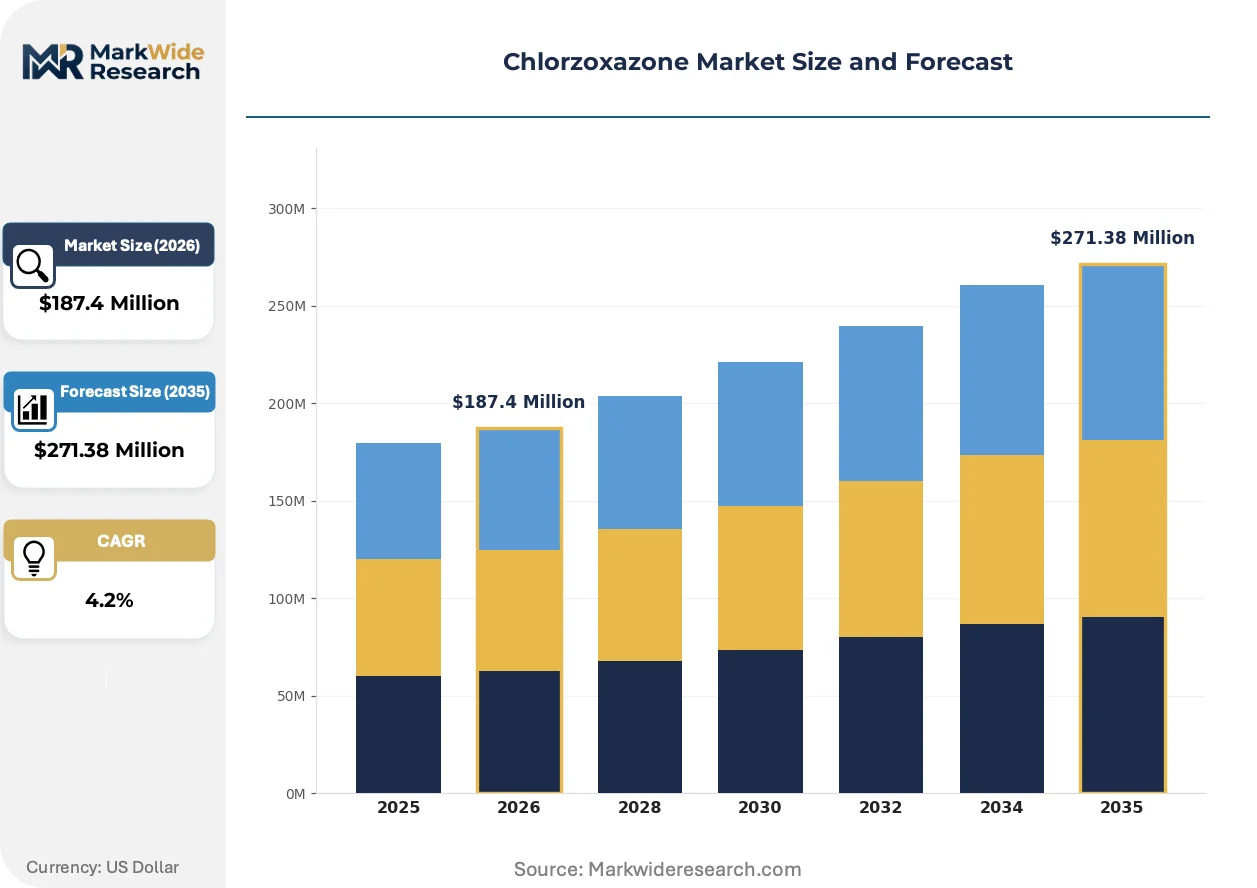
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injections, Powders End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Retail, Wholesale, Online, Direct Sales Application: Muscle Relaxant, Pain Relief, Neurological Disorders, Sports Injuries |
| Companies Covered | Lupin Limited, Apotex Inc., Teva Pharmaceutical Industries Limited, Dr. Reddy’s Laboratories Limited, Cadila Healthcare Limited, Sun Pharmaceutical Industries Limited, Glenmark Pharmaceuticals Limited, Cipla Limited, Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorzoxazone Market Emerging Trajectories
Formulation science and regulatory data architectures are converging to compress development timelines while tightening quality assurance standards across generic muscle relaxant supply chains.
Continuous manufacturing technology is integrating real-time release testing protocols into tablet production lines. Hospital procurement groups in the United States are qualifying suppliers with in-process analytical technology capabilities. This shift is integrating quality assurance directly into manufacturing workflow, reducing batch rejection rates and shortening tender response cycles.
EMA's revised Good Manufacturing Practice Annex 1 for sterile products is mandating barrier isolation systems for injectable chlorzoxazone production. European contract manufacturers are retrofitting fill-finish lines with restricted access barrier systems. Hospital buyers in Germany and France are now requiring EMA inspection certificates as prequalification criteria, excluding non-EU sites from acute care tenders.
Retail pharmacy chains are consolidating generic sourcing through central procurement entities. Independent pharmacies in the United States are losing direct wholesaler relationships as CVS Health and Walgreens Boots Alliance negotiate exclusive distribution agreements. This concentration is compressing available supplier slots and rewarding integrated API-to-tablet manufacturers with volume guarantees.
Chlorzoxazone Market Segmentation
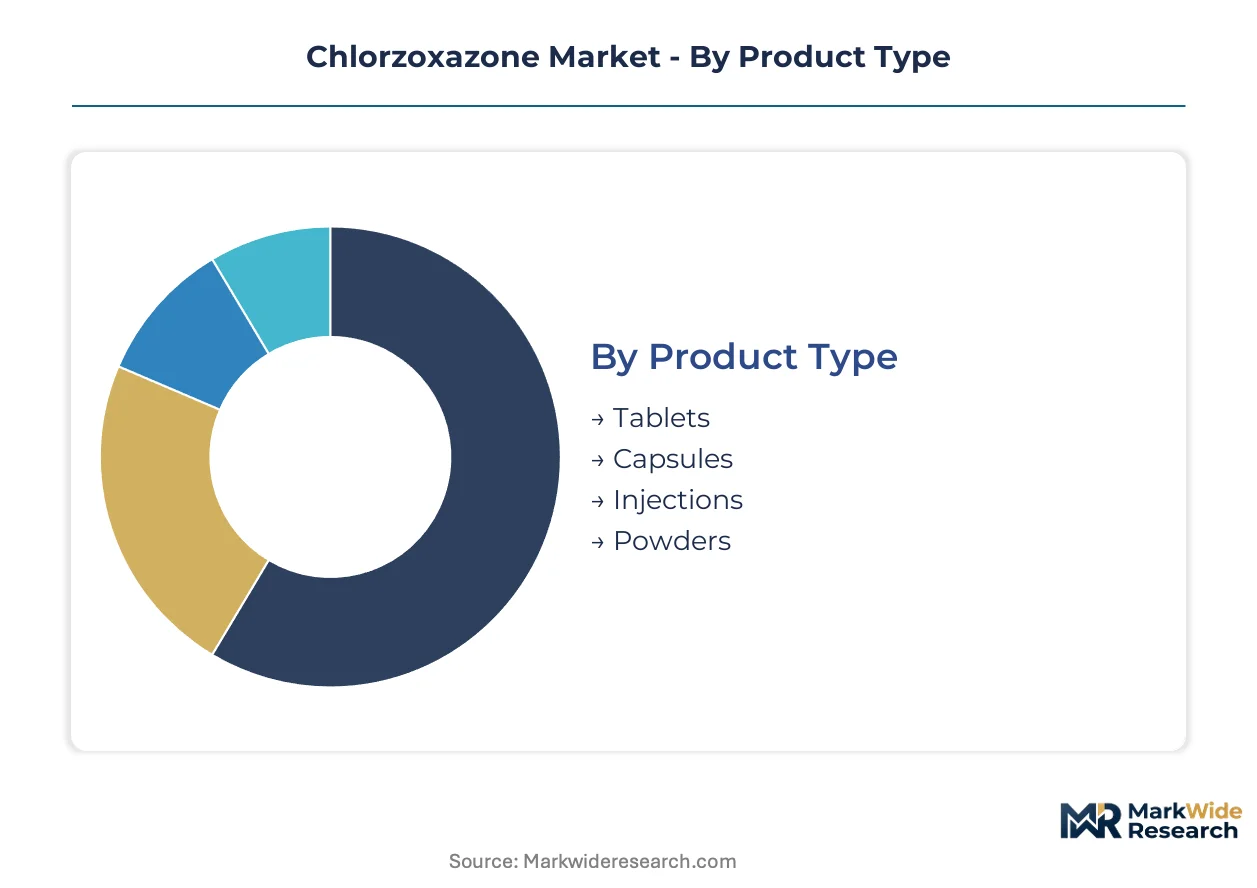
Chlorzoxazone demand fragments across formulation technologies, care settings, and procurement channels that impose distinct compliance and margin requirements. Understanding these splits reveals where integrated manufacturers can defend position against specialized competitors.
Product Type:
Hospital procurement teams prioritize bioequivalence documentation and batch-to-batch consistency when selecting formulation formats.
- Tablets:Oral solid dosage forms containing 250mg or 500mg chlorzoxazone with established dissolution profiles dominate retail pharmacy dispensing. Medicare physical therapy referrals in the United States sustain prescription velocity for this format.
- Injections:Parenteral formulations for acute postoperative spasticity management are accelerating in US inpatient settings where rapid onset overrides oral bioavailability concerns. FDA's Current Good Manufacturing Practice enforcement for sterile products elevates supplier qualification thresholds.
- Capsules:Gelatin-encapsulated variants offer taste masking for geriatric polypharmacy patients.
- Powders:Bulk active pharmaceutical ingredient for compounding pharmacies and regional formulators.
Tablets lead volumes today; injections are gaining share fastest.
End User:
Procurement authority and reimbursement pathways determine margin capture across patient care locations.
- Hospitals:Acute care facilities with centralized pharmacy committees negotiate tender contracts based on EMA inspection certificates and serialization compliance. German and French hospital buyers now exclude non-EU manufacturing sites from muscle relaxant procurement.
- Clinics:Outpatient rehabilitation centers with direct physician dispensing relationships favor fixed-dose combinations with analgesics.
- Pharmacies:Retail chains with central procurement entities compress supplier slots and reward API-to-tablet integrated manufacturers.
- Home Care:Long-term care facilities and visiting nurse services managing chronic musculoskeletal conditions.
Hospitals command the largest revenue pool; home care is climbing the fastest as aging-in-place policies expand.
Distribution Channel:
Channel concentration is reshaping which manufacturers retain direct customer relationships versus ceding margin to intermediaries.
- Retail:CVS Health and Walgreens Boots Alliance negotiate exclusive distribution agreements that eliminate independent pharmacy direct wholesaler access.
- Wholesale:McKesson and Cardinal Health consolidate generic muscle relaxant sourcing through volume guarantees with integrated manufacturers.
- Online:Telehealth-integrated pharmacies with e-prescribing workflows.
- Direct Sales:Hospital system-owned specialty distributors bypassing traditional wholesale.
Wholesale still handles the majority of unit flow; direct sales are expanding most quickly as health systems vertically integrate supply chains.
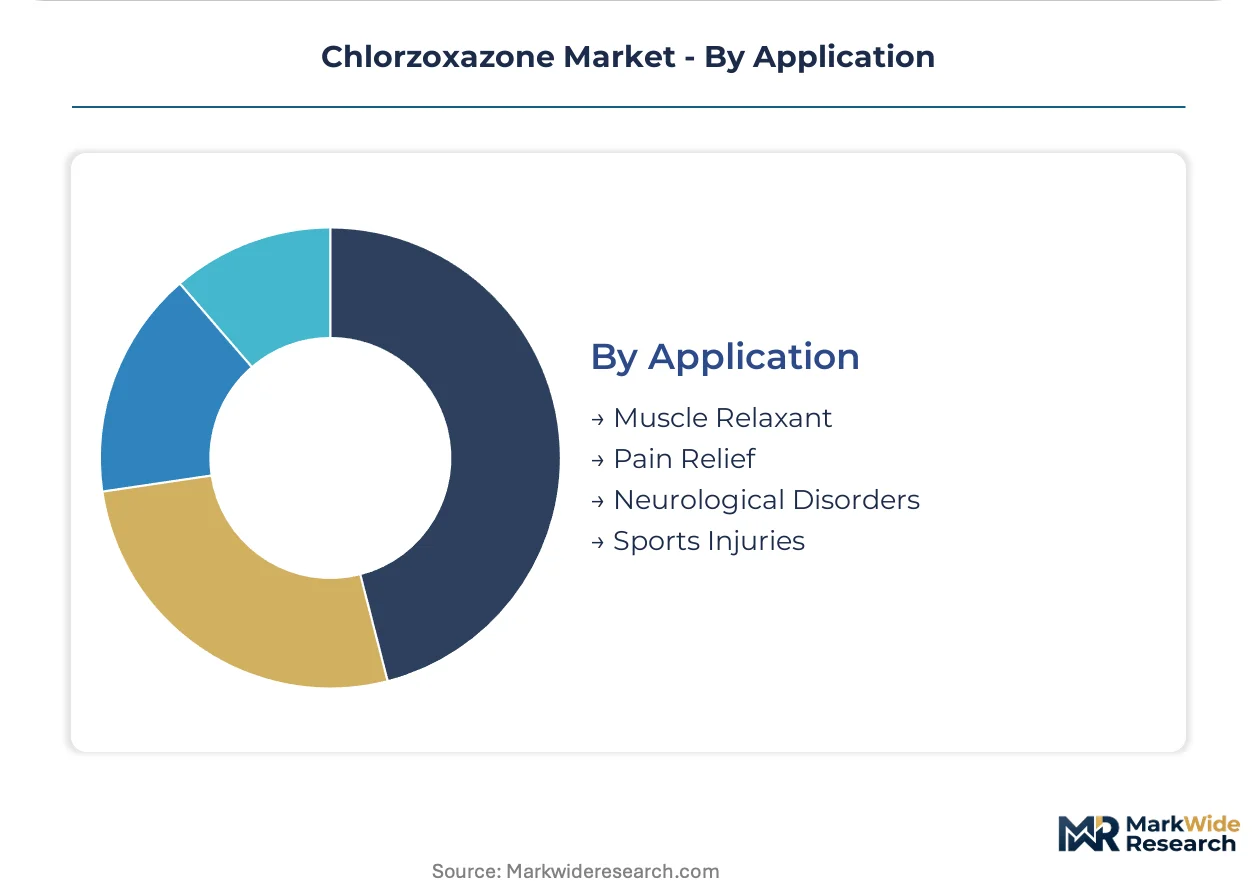
Application:
Therapeutic positioning determines whether chlorzoxazone competes on price against generic muscle relaxants or captures premium through combination formulations.
- Muscle Relaxant:Centrally acting skeletal muscle relaxation for acute spasticity commands the foundational indication with established reimbursement codes.
- Pain Relief:Co-formulations with acetaminophen or NSAIDs capture retail margin concentration through pharmacist-driven substitution and higher per-unit pricing.
- Neurological Disorders:Off-label use in multiple sclerosis and cerebral palsy spasticity management.
- Sports Injuries:Athletic training facility dispensing for acute strain and sprain recovery protocols.
Muscle relaxant applications anchor current demand; pain relief combinations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical chemists and formulation scientists in India, the United States, and Germany anchor the geographic concentration of chlorzoxazone manufacturing expertise. Hospital procurement networks and retail pharmacy chains in these markets drive demand segmentation across oral solids and injectable formats.
United States
Medicare physical therapy referrals and aging-in-place policies sustain tablet prescription velocity through CVS Health and Walgreens Boots Alliance networks. FDA's Current Good Manufacturing Practice enforcement for oral solid dosage forms elevates supplier qualification thresholds for hospital formulary inclusion. New Jersey and Pennsylvania host contract manufacturing organizations retrofitting lines for serialization compliance.
Germany
Hospital pharmacy committees in Bavaria and North Rhine-Westphalia mandate EMA inspection certificates for muscle relaxant procurement. EMA's revised Good Manufacturing Practice Annex 1 for sterile products forces barrier isolation retrofits at injectable fill-finish facilities. Frankfurt-Rhine-Main cluster manufacturers are qualifying for centralized EU tender access.
India
Integrated API-to-tablet operations in Maharashtra and Gujarat supply North American and European tender markets. CDSCO mandates dissolution profile documentation that filters subscale domestic manufacturers from export-oriented production. Hyderabad and Mumbai house formulation specialists with captive benzoxazolone intermediate capabilities.
Brazil
ANVISA's streamlined generic registration pathway for essential medicines accelerates muscle relaxant tender access for international suppliers. São Paulo hospital networks expand postoperative spasticity management protocols. The São Paulo-Minas Gerais corridor concentrates regional distribution infrastructure for Latin American market reach.
Japan
PMDA pharmacovigilance requirements for centrally acting muscle relaxants tighten sedation-related adverse event surveillance. Kansai region manufacturers serve domestic geriatric polypharmacy demand with taste-masked capsule formulations. Osaka-based distributors navigate reimbursement code complexity for muscle relaxant indications.
Chlorzoxazone Market Vendor Landscape
Capital-heavy producers with integrated API-to-tablet operations compete with asset-light formulators dependent on merchant benzoxazolone supply. The supplier base concentrates around three strategic archetypes: vertically integrated Indian pharmaceutical conglomerates, North American generic distributors with retail channel dominance, and European contract manufacturers with EMA-certified sterile capabilities. Competitive positioning hinges on backward integration into benzoxazolone intermediates and serialization-ready supply chain infrastructure. M&A activity targets CDSCO-compliant manufacturing assets in India and EMA-inspected sterile facilities in Germany.
Among Indian integrated pharmaceutical manufacturers, Lupin Limited and Sun Pharmaceutical Industries Limited exemplify the API-captive archetype with domestic intermediate production. Teva Pharmaceutical Industries Limited occupies a position representing North American generic distribution scale. These three anchors illustrate the geographic segmentation of competitive advantage across manufacturing cost structures, regulatory compliance depth, and channel access concentration.
| Leading Market Players |
|---|
| Lupin Limited |
| Apotex Inc. |
| Teva Pharmaceutical Industries Limited |
| Dr. Reddy's Laboratories Limited |
| Cadila Healthcare Limited |
| Sun Pharmaceutical Industries Limited |
| Glenmark Pharmaceuticals Limited |
| Cipla Limited |
| Viatris Inc. |
| Others |
Supply Flow & Price Mechanics
Benzoxazolone intermediate spot prices in India and China cascade through API conversion costs into three-tier pricing stratification across tablet, injection, and co-formulation segments. Hospital procurement committees leverage volume guarantees to compress margins on generic oral solids, while retail pharmacy chains extract rebates that shift margin concentration toward pain-relief combinations with analgesics.
Pricing Analysis
Bundled tender contracts with hospital systems separate from unbundled spot purchases by independent pharmacies. Three-tier pricing structure across premium, standard, and economy levels reflects EMA inspection certification, serialization compliance depth, and API-to-tablet integration. Cost compression in standard-tier tablets is intensifying because of ANDA approval timeline extensions and bioequivalence study requirements. Independent retail pharmacies exhibit highest price sensitivity; hospital systems with centralized procurement show lowest sensitivity due to formulary lock-in advantages.
Supply Chain Analysis
Single-source vulnerability sits with benzoxazolone intermediate production concentrated in Maharashtra and Gujarat, India, and Jiangsu province, China. Captive API manufacturing draws from 2-amino-4-chlorophenol feedstock, urea condensation reagents, and cyclization catalysts. Tariff exposure on Chinese intermediates threatens margin stability for non-integrated formulators. Distribution runs through McKesson and Cardinal Health wholesale networks with direct sales expanding through hospital-owned specialty distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chlorzoxazone offers margin expansion through captive benzoxazolone production and EMA-certified sterile capacity premiums. Cost-down drivers include continuous manufacturing adoption and serialization-ready ERP consolidation.
For Market Incumbents: Extend backward integration into benzoxazolone intermediates to neutralize API supply concentration risk from China and India. Secure EMA Annex 1 compliance for injectable fill-finish lines before German and French hospital procurement committees finalize supplier prequalification criteria. Tizanidine substitution in chronic spasticity regimens threatens tablet volume; defend through pain-relief co-formulation portfolio depth. For New Entrants and Emerging Players: Brazilian hospital networks represent an underserved buyer archetype with ANVISA's streamlined generic registration pathway reducing tender access barriers. Target transdermal delivery development for geriatric polypharmacy patients in Japan's Kansi region where taste-masked alternatives command premium positioning. Pursue licensing partnerships with Indian CDSCO-compliant manufacturers to bypass dissolution profile documentation investments. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier Indian formulators possessing captive benzoxazolone capacity and pending EMA inspection schedules. Long-term viability hinges on serialization infrastructure readiness and barrier isolation retrofit completion for sterile product expansion. Watch FDA Current Good Manufacturing Practice enforcement intensity as inflection indicator for supplier qualification threshold elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzoxazolone Intermediates | Captive supply of 2-amino-4-chlorophenol derivatives neutralizes geopolitical shipping disruption exposure for North American tender participants. |
| EMA Annex 1 Compliance Retrofit | Barrier isolation systems at German fill-finish facilities unlock centralized EU hospital procurement access excluding non-EU competitors. |
| Continuous Manufacturing Technology Deployment | Real-time release testing integration at New Jersey and Pennsylvania contract manufacturers reduces batch rejection rates for FDA oral solid enforcement. |
| Pain-Relief Co-Formulation Pipeline Expansion | Fixed-dose combinations with acetaminophen capture retail margin concentration through CVS Health and Walgreens Boots Alliance central procurement. |
| ANVISA Registration Pathway Utilization | São Paulo hospital network tender access accelerates Latin American volume buildout for essential medicines muscle relaxant suppliers. |
Methodological Framework
Bottom-up hospital and retail pharmacy dispensing modeling reconciled against top-down API production and intermediate trade tracking forms the analytical core. Primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads at Indian and North American manufacturers, and pharmacy chain category buyers combined with secondary validation against FDA ANDA filings, EMA GMP inspection databases, CDSCO dissolution specifications, and ANVISA registration records. Triangulation across supply-side capacity assessments and demand-side prescription velocity data ensures cross-verification.
Historical trendline analysis of Medicare physical therapy referral rates, hospital inpatient spasticity protocol adoption, and generic substitution patterns informs projection architecture. Segmentation dimensions span formulation technology, care setting procurement authority, distribution channel concentration, and therapeutic application positioning. CAGRs derive from regression-adjusted prescription volume trajectories and tender contract value analysis across the projection horizon. Industry-specific inputs include FDA bioequivalence study completion timelines and EMA pharmacovigilance reporting frequency for centrally acting muscle relaxants.
Underlying measurement precision varies by segment; tablet and injection volume data carry tighter precision than transdermal development pipeline assessments. Forecasts reflect assumptions regarding regulatory enforcement continuity, intermediate trade flow stability, and hospital formulary inclusion velocity. API supply disruption, accelerated tizanidine substitution, or pharmacovigilance requirement tightening could revise trajectory projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Pharmaceutical Hot Melt Extrusion Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Pemetrexed Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market