
 Tiapride Hydrochloride API Market | 2026-2036
Tiapride Hydrochloride API Market Size, Share, and Industry Trends Forecast 2026-2036
Tiapride Hydrochloride API Market Insights
Buyer concentration among generic pharmaceutical manufacturers is realigning procurement dynamics for tiapride hydrochloride API. Sanofi leverages its established neuropsychiatric portfolio to sustain offtake volumes across European markets. Olon S.p.A anchors European supply through large-scale active pharmaceutical ingredient manufacturing capabilities. Manus Aktteva Biopharma LLP competes on cost-efficient production tailored to emerging market formulators.
Tiapride hydrochloride API is the hydrochloride salt form of a substituted benzamide compound, characterized by a molecular structure containing a methoxy group and a sulfonamide moiety that confers dopamine D2 receptor antagonism; manufacturers synthesize it via multi-step organic routes involving sulfonation, amination, and salt formation, with final purity typically exceeding 99.0% by HPLC for pharmaceutical-grade material. The compound serves primarily as an active moiety in antipsychotic and anti-dyskinetic drug products targeting psychiatric and movement disorders. Bulk API dominates volume flows as the foundational input for downstream formulation, while Injectable Solutions commands premium positioning due to sterility requirements and hospital-centric administration protocols. Therapy area demand concentrates in Psychiatric Disorders and Movement Disorders, where tiapride's favorable extrapyramidal side-effect profile sustains clinical preference over typical antipsychotics.
EMA enforces ICH Q11 guidelines on API development and manufacturing that elevate documentation burdens for tiapride hydrochloride producers seeking European market access. FDA inspections under ICH Q7 good manufacturing practice standards determine supplier qualification for US-bound shipments, directly filtering the contract manufacturer pool. China's NMPA and India's CDSCO apply convergent purity and impurity profiling standards that shape export-oriented production strategies. Stakeholders must monitor evolving pharmacopeial monograph revisions and regulator inspection calendars to secure uninterrupted supply chain positioning.
Market Dynamics
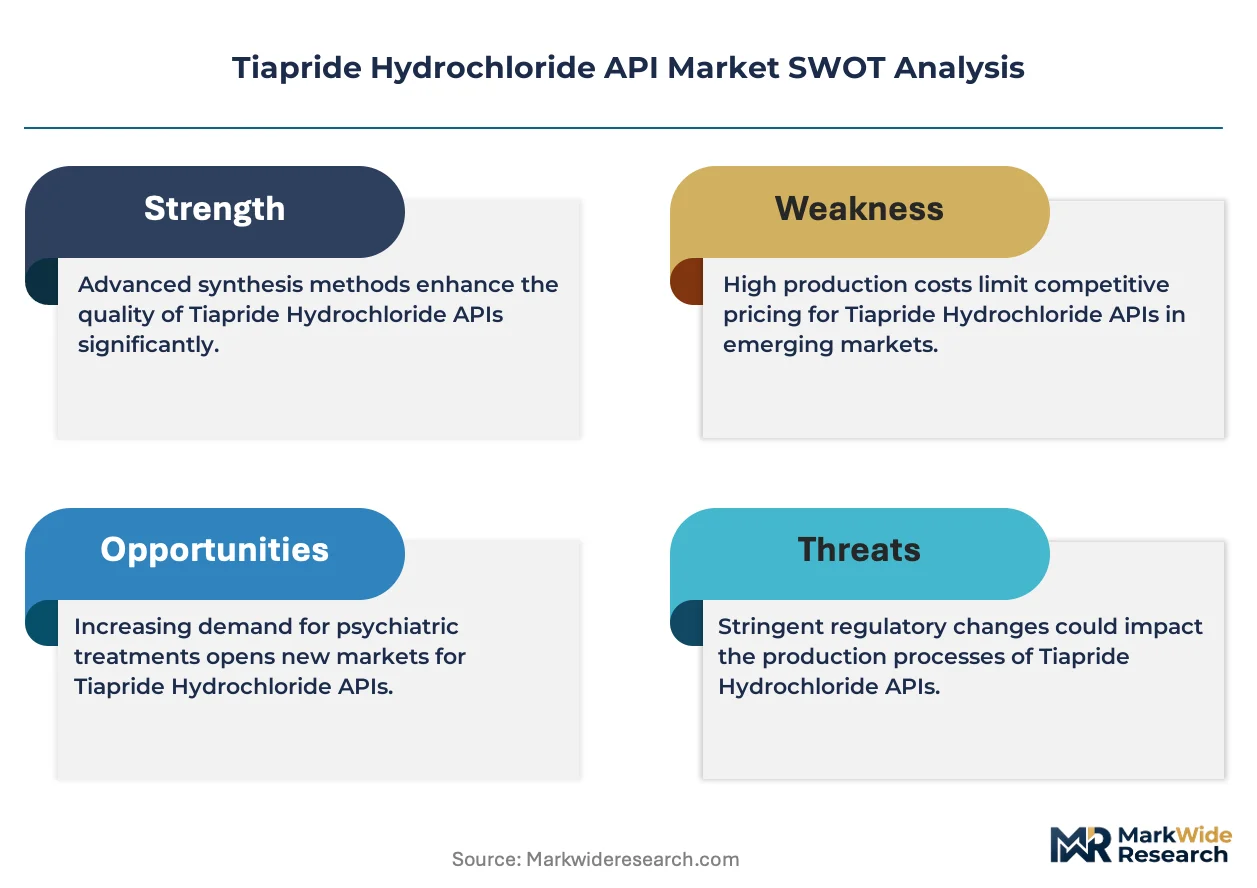
REACH and ICH Q7 guideline convergence is compressing the qualified supplier pool for tiapride hydrochloride API, forcing generic pharmaceutical manufacturers to consolidate procurement around CDSCO-registered contract manufacturers with demonstrated regulatory inspection histories.
Growth Catalysts
- Psychiatric disorder prevalence:Expanding patient populations requiring antipsychotic therapy sustain offtake volumes for dopamine D2 antagonist APIs across hospital and retail pharmacy channels.
- ICH Q11 documentation standards:EMA-mandated development and manufacturing data packages elevate barriers for new entrants, protecting incumbent supplier relationships.
- Movement disorder applications:Tiapride's favorable extrapyramidal side-effect profile drives preference over typical antipsychotics in Parkinson's disease-related dyskinesia management.
Market Restraints
- Starting material cost volatility:Sulfonamide and benzamide precursor chemicals face petrochemical feedstock price swings that compress API manufacturer margins.
- European supply concentration:Olon S.p.A's large-scale manufacturing dominance creates single-source vulnerability for EMA-compliant material.
- Impurity profiling burden:ICH Q3D elemental impurities and nitrosamine risk assessments add analytical validation costs without commensurate price recovery.
Strategic Opportunities
- India CDSCO export pathway:Contract manufacturers in Hyderabad and Ahmedabad clusters can capture regulated market share through FDA and EMA pre-approval inspection readiness.
- Injectable formulation premium:Sterile API production capabilities command price multiples over oral-grade material due to aseptic processing requirements.
- PLI scheme alignment:India's production-linked incentive framework for active pharmaceutical ingredients reduces capital intensity for greenfield tiapride manufacturing investments.
Industry Challenges
- Multi-step synthesis expertise:Sulfonation, amination, and salt formation chemistry requires specialized organic synthesis talent that concentrates in legacy pharmaceutical manufacturing regions.
- Regulatory inspection backlog:FDA and EMA site visit queue delays extend supplier qualification timelines, freezing procurement decisions for 18-24 month windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tiapride Hydrochloride API Market |
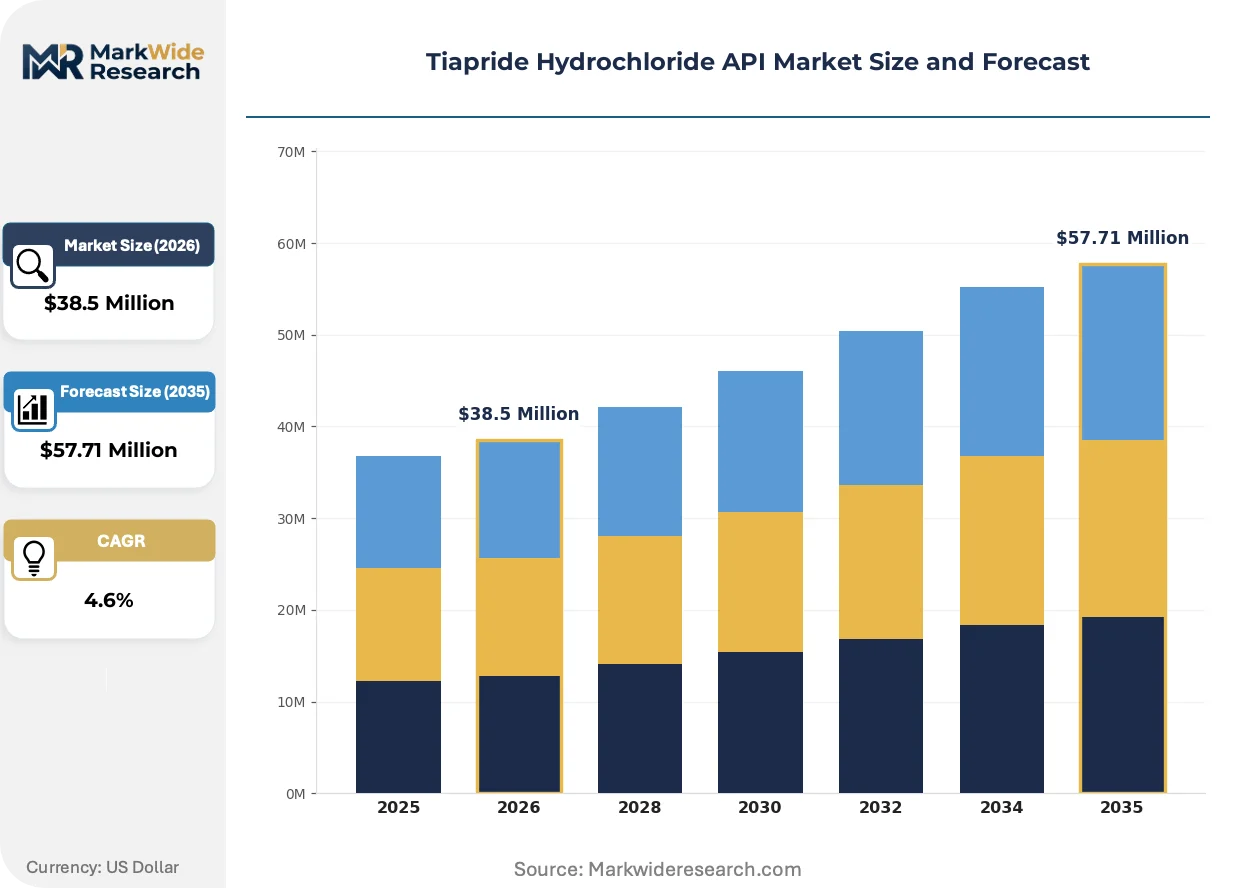
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $57.71 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk API, Formulations, Finished Drugs, Injectable Solutions Therapy Area: Psychiatric Disorders, Neurological Disorders, Cognitive Impairments, Movement Disorders End User: Pharmaceutical Manufacturers, Contract Research Organizations, Academic Institutions, Hospitals Delivery Mode: Oral, Injectable, Transdermal, Intranasal |
| Companies Covered | Lebsa, Sanofi, Tokyo Chemical Industry, Manus Aktteva Biopharma LLP, ICROM, Olon S.p.A, Century Pharmaceuticals, Daito Pharmaceutical, Guangzhou Tosun Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tiapride Hydrochloride API Market Trends and Innovations
Continuous manufacturing technologies and real-time release testing protocols are displacing batch-oriented production paradigms in neuroactive API synthesis, compressing cycle times while tightening quality assurance standards.
Flow chemistry systems are expanding into tiapride hydrochloride synthesis routes, enabling precise temperature and stoichiometry control during exothermic sulfonation steps. Mid-tier API manufacturers in India and Italy are piloting these platforms to reduce solvent consumption and improve yield consistency. The technology is expanding into commercial-scale validation, with CDSCO-registered facilities leading regulatory submission pathways for continuous process dossiers.
EMA's updated nitrosamine risk assessment guidelines now require comprehensive survey data for all chemically synthesized APIs, including benzamide derivatives. This policy shift forces manufacturers to retrofit existing processes with dedicated nitrosamine control strategies and enhanced analytical detection methods. European generic pharmaceutical buyers are now screening supplier quality agreements for documented nitrosamine risk management plans before contract execution.
Hospital formulary committees are consolidating antipsychotic procurement around pre-qualified injectable suppliers, displacing fragmented oral-solid purchasing patterns. This concentration favors API manufacturers with dedicated sterile processing lines and documented endotoxin control capabilities. The shift is most visible in France and Germany, where regional purchasing cooperatives now mandate single-source injectable tiapride agreements for multi-year contract periods.
Tiapride Hydrochloride API Market Segmentation
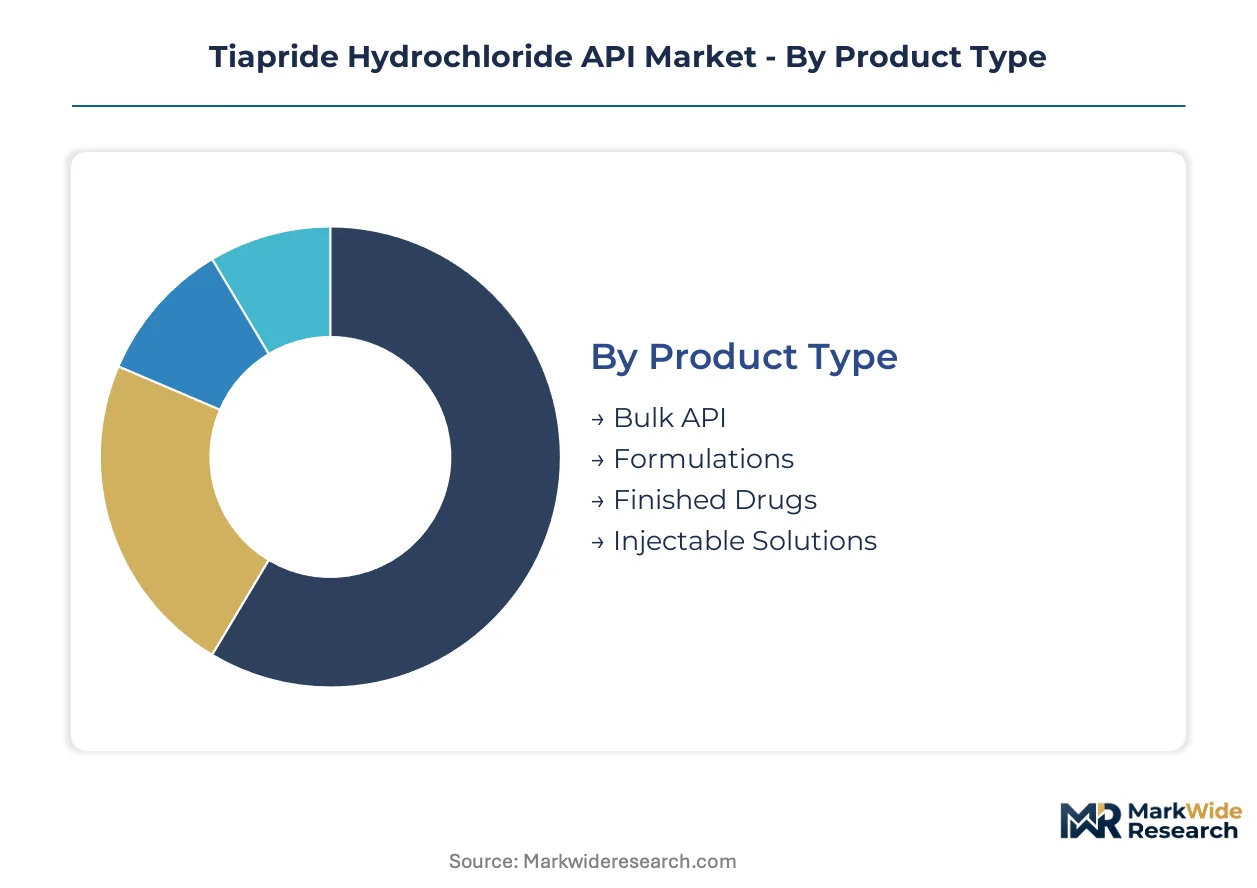
Tiapride hydrochloride API demand fragments across four distinct segmentation dimensions. Each category carries unique capital requirements and regulatory burdens that reshape supplier competitive positioning. Understanding these splits reveals where margin pools concentrate and where procurement power is shifting.
Product Type:
Bulk API manufacturing demands the heaviest upfront capital outlays, with multi-step organic synthesis requiring dedicated sulfonation reactors and salt formation vessels.
- Bulk API:Foundation material synthesized via sulfonation, amination, and hydrochloride salt formation routes. Pharmaceutical manufacturers in India and Italy concentrate procurement here for downstream formulation flexibility, though REACH-compliant purification adds validation costs.
- Injectable Solutions:Sterile liquid formulations requiring aseptic processing and endotoxin control. Hospital procurement cooperatives in France and Germany are consolidating purchasing around pre-qualified injectable suppliers, creating single-source contract structures.
- Formulations:Oral-solid dosage forms including tablets and capsules for retail pharmacy distribution.
- Finished Drugs:Packaged drug products ready for direct dispensing or institutional use.
Bulk API absorbs the bulk of installed capacity; Injectable Solutions is expanding most quickly.
Therapy Area:
Clinical application patterns split procurement volumes between psychiatric and movement disorder indications, with reimbursement pathways diverging sharply across European markets.
- Psychiatric Disorders:Antipsychotic therapy for schizophrenia and acute agitation. Demand concentrates in hospital and retail pharmacy channels across Spain and Italy, where tiapride's favorable extrapyramidal profile sustains preference over haloperidol.
- Movement Disorders:Anti-dyskinetic applications in Parkinson's disease management. German and French neurologists favor tiapride for L-DOPA-induced dyskinesia, driving offtake through specialist hospital networks.
- Neurological Disorders:Broader central nervous system indications beyond movement pathology.
- Cognitive Impairments:Adjunctive therapy in dementia-related behavioral disturbances.
Psychiatric Disorders commands the largest revenue share; Movement Disorders shows the steepest expansion trajectory.
End User:
Customer type determines contract structure complexity, with pharmaceutical manufacturers demanding full ICH Q11 documentation while academic buyers accept simplified quality agreements.
- Pharmaceutical Manufacturers:Generic drug companies requiring multi-ton API volumes with complete regulatory dossiers. CDSCO-registered Indian contract manufacturers supply this segment through FDA and EMA pre-approval inspection pathways.
- Contract Research Organizations:Clinical trial material suppliers needing small-batch GMP production with rapid turnaround.
- Hospitals:Direct procurement of finished injectable products through regional purchasing cooperatives.
- Academic Institutions:Research-grade material for non-clinical pharmacology studies.
Pharmaceutical Manufacturers dominate volume flows; Contract Research Organizations are gaining share fastest.
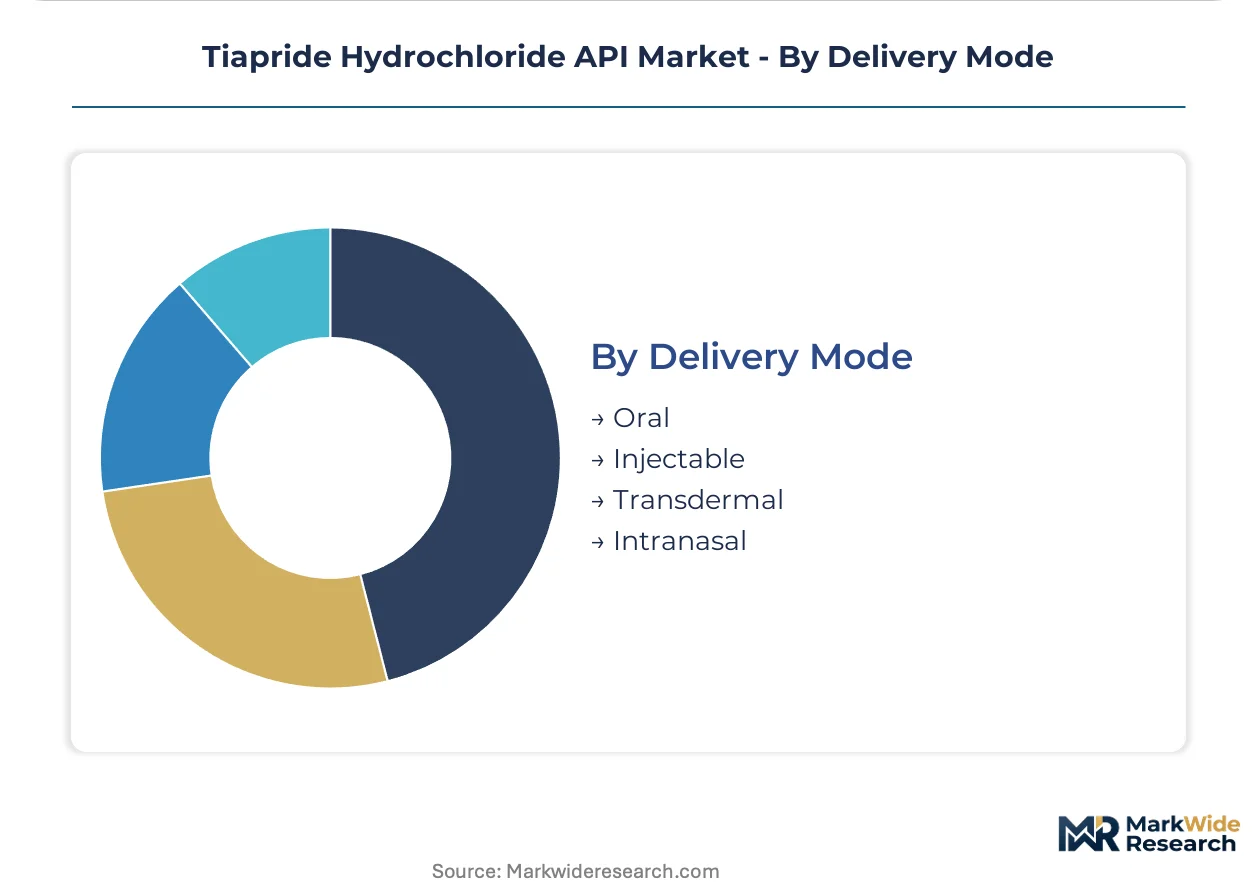
Delivery Mode:
Route of administration splits the market between commoditized oral formats and premium-positioned parenteral systems with sterility-assured supply chains.
- Oral:Tablet and capsule formulations for chronic outpatient therapy. Retail pharmacy distribution in Spain and Portugal sustains volume, though generic substitution pressures compress pricing.
- Injectable:Intravenous and intramuscular solutions for acute hospital administration. Aseptic processing requirements and endotoxin testing command price multiples over oral-grade material.
- Transdermal:Patch-based delivery systems under development for sustained release.
- Intranasal:Nasal spray formulations for rapid onset in agitation management.
Oral delivery maintains the widest installed base; Injectable formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Generic pharmaceutical manufacturers in India and Europe absorb the majority of tiapride hydrochloride API procurement volumes, with hospital purchasing cooperatives in France and Germany driving premium-grade demand through consolidated tender structures.
India
CDSCO-registered contract manufacturers in Hyderabad and Ahmedabad clusters supply regulated markets through FDA and EMA pre-approval inspection pathways. The PLI scheme for active pharmaceutical ingredients reduces capital intensity for greenfield investments in tiapride synthesis capacity. Domestic formulators in Mumbai and Bangalore expand offtake for psychiatric and movement disorder indications.
Germany
Regional purchasing cooperatives in Bavaria and North Rhine-Westphalia mandate single-source injectable tiapride agreements for multi-year contract periods. EMA's updated nitrosamine risk assessment guidelines force manufacturers to retrofit processes with dedicated control strategies. Frankfurt and Hamburg serve as distribution hubs for EMA-compliant material across Central Europe.
France
ANSM oversight of neuroactive API purity specifications elevates documentation burdens for imported material. Hospital formulary committees in Paris and Lyon consolidate antipsychotic procurement around pre-qualified injectable suppliers. Toulouse and Strasbourg manufacturing sites specialize in sterile processing for acute hospital administration.
Italy
Olon S.p.A anchors European supply through large-scale active pharmaceutical ingredient manufacturing capabilities in Milan and Bergamo. EMA ICH Q11 guidelines on API development protect incumbent supplier relationships against new entrants. Turin and Bologna clusters concentrate formulation expertise for movement disorder applications.
Japan
PMDA inspections under ICH Q7 standards filter the contract manufacturer pool for domestic-bound shipments. Tokyo Chemical Industry and Daito Pharmaceutical sustain offtake through established neuropsychiatric portfolios. Osaka and Kobe serve as import gateways for CDSCO-registered Indian material meeting Japanese pharmacopeial standards.
Tiapride Hydrochloride API Market Competitive Landscape
European producers anchor one tier; Indian specialists hold cost-efficient production positions for emerging market formulators. The supplier base concentrates around CDSCO-registered contract manufacturers with demonstrated regulatory inspection histories and legacy pharmaceutical manufacturers with established neuropsychiatric portfolios. Strategic archetypes include large-scale API synthesizers with EMA compliance capabilities, mid-tier Indian manufacturers competing on production economics, and integrated pharmaceutical companies with captive demand. Dominant competitive moves encompass regulatory pre-approval inspection readiness investments and sterile processing line expansions for injectable-grade material.
Within the European large-scale synthesis tier, Olon S.p.A and Sanofi exemplify archetypes of regulatory-compliant volume producers. Olon S.p.A occupies a position as an EMA-anchored manufacturer with dedicated sulfonation reactor infrastructure. Sanofi represents the integrated pharmaceutical model with established neuropsychiatric portfolio demand. Among Indian contract manufacturers, Manus Aktteva Biopharma LLP sits within the cost-efficient production archetype tailored to generic formulators in regulated and emerging markets. These three companies illustrate the geographic and strategic bifurcation shaping procurement decisions for tiapride hydrochloride API.
| Leading Market Players |
|---|
| Lebsa |
| Sanofi |
| Tokyo Chemical Industry |
| Manus Aktteva Biopharma LLP |
| ICROM |
| Olon S.p.A |
| Century Pharmaceuticals |
| Daito Pharmaceutical |
| Guangzhou Tosun Pharmaceutical |
| Others |
Pricing and Supply Chain Analysis
Continuous manufacturing adoption in Hyderabad and Ahmedabad clusters compresses unit economics while concentrating production among CDSCO-registered facilities with validated flow chemistry infrastructure. This technology shift simultaneously reduces solvent consumption and elevates capital barriers, reshaping how generic pharmaceutical manufacturers negotiate long-term offtake agreements.
Pricing Analysis
Injectable-grade material commands three-to-four-fold premiums over oral-grade bulk API due to sterility assurance and endotoxin validation requirements. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier and volume scale, with EMA-compliant sterile batches at the apex. Pricing pressure stems from REACH-aligned purification costs that manufacturers struggle to pass through to hospital purchasing cooperatives. Generic formulators in emerging markets exhibit highest price sensitivity, while European hospital procurement committees prioritize supply security over unit cost.
Supply Chain Analysis
Specialized organic synthesis talent shortages in Milan, Bergamo, and legacy European pharmaceutical regions constrain expansion of sulfonation reactor capacity. Supply concentrates in India, Italy, and Japan, with CDSCO-registered contract manufacturers and EMA-anchored volume producers anchoring opposite tiers. Raw material dependencies center on sulfonamide precursors, benzamide intermediates, and petrochemical-derived feedstocks. Single-source vulnerability persists around Olon S.p.A's large-scale European infrastructure. Distribution runs through pharmaceutical manufacturer direct procurement and regional hospital purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flow chemistry validation represents a technology-transition phase displacing batch-oriented synthesis paradigms, with regulatory dossiers for continuous processes becoming the new competitive moat.
For Market Incumbents: To counter nitrosamine risk assessment retrofit costs, deepen backward integration into sulfonamide precursor supply and expand sterile processing lines in CDSCO-registered facilities. EMA inspection readiness investments protect incumbent positioning against mid-tier Indian challengers. For New Entrants and Emerging Players: The premium-to-economy price-point gap in injectable-grade material creates entry space for aseptic-capable manufacturers targeting French and German hospital cooperatives. Focus initial capacity on movement disorder applications where reimbursement pathways favor newer suppliers. Pursue PLI scheme alignment to reduce capital intensity for greenfield investments. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier Indian contract manufacturers achieving FDA pre-approval inspection status given EMA's tightening qualified supplier pool. Five-to-ten year viability hinges on continuous manufacturing regulatory acceptance. Monitor nitrosamine control strategy documentation in supplier quality agreements as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Regulatory Submission | CDSCO-registered facilities pioneering flow chemistry dossiers capture EMA preference for reduced cycle times. |
| Sterile Processing Line Expansion | Dedicated aseptic infrastructure commands injectable-grade price multiples from hospital purchasing cooperatives. |
| Backward Integration into Precursors | In-house sulfonamide production buffers margin compression from petrochemical feedstock volatility. |
| Nitrosamine Control Strategy Retrofit | Enhanced analytical detection methods satisfy EMA guidelines and preserve European market access. |
| PLI Scheme Capacity Buildout | Indian production-linked incentives reduce capital intensity for greenfield tiapride synthesis investments. |
Research Methodology
EMA regulatory filings, CDSCO registration databases, and hospital procurement contract records formed the secondary backbone, supplemented by FDA inspection observation reports and pharmacopeial monograph revisions. Primary fieldwork encompassed regulatory affairs leads at API manufacturers, procurement directors at generic pharmaceutical companies, and formulary committee members at French and German hospital systems. Bottom-up and top-down triangulation validated volume estimates across product type, therapy area, and end user segments.
Bottom-up modeling anchored forecast outputs, with top-down macro checks against psychiatric disorder prevalence trends and movement disorder diagnosis rates. Segmentation dimensions spanned product type, therapy area, end user archetype, and delivery mode, with regional regulatory cluster as an overlay. CAGRs derived from weighted average of historical volume trajectories and forward-looking capacity expansion announcements, incorporating ICH Q11 documentation burden effects and continuous manufacturing adoption curves.
Inputs from EMA inspection calendars and CDSCO registration portals were available through the study window; gaps in real-time nitrosamine survey data from private manufacturers introduce uncertainty bands around purity specification compliance timelines. Forecasts reflect assumptions on regulatory inspection queue resolution and PLI scheme disbursement continuity. Material deviation in FDA pre-approval inspection timelines or REACH guideline revision schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Metformin Hydrochloride API Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Pharmaceutical Hot Melt Extrusion Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market