
 Built-In Large Cooking Appliance Market | 2026-2036
Built-In Large Cooking Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Built-In Large Cooking Appliance Market Outlook
Consolidation among luxury home developers and high-end hospitality groups is recalibrating procurement volumes for built-in cooking suites. BSH Hausgeräte GmbH leverages its captive component manufacturing to control margin pools in premium wall oven categories. Whirlpool Corporation competes through scale advantages across standard electric range segments in North American builder channels. Electrolux AB anchors its position in European commercial kitchens with durable gas cooktop platforms.
Built-in large cooking appliances comprise permanently installed cooking equipment designed for seamless cabinet integration, typically featuring convection airflow systems, sealed burner configurations, or electromagnetic induction coils rated at 2,400 to 3,700 watts. These units serve residential and foodservice operators requiring space-efficient, aesthetically unified kitchen environments. Wall ovens and induction cooktops capture expanding margin pools as electrification preferences shift residential demand away from gas fuel types. The commercial end user segment sustains durable replacement cycles, while kitchen remodel installations outpace new construction volumes in mature housing stock regions.
The EU Ecodesign Directive and CE marking requirements enforce minimum energy efficiency indices for electric ovens sold across European member states, directly influencing R&D allocation toward convection optimization and insulation upgrades. The US Department of Energy appliance standards and EPA ENERGY STAR certification shape product access in North American retail and builder channels by disqualifying sub-threshold models. China's GB standards and MIIT circular economy guidelines impose material recovery rates on domestic manufacturers, altering component sourcing for gas cooktops. Stakeholders must monitor regulatory divergence between electrification mandates in Europe and persistent gas infrastructure dependence in select US states when allocating regional production capacity.
Market Dynamics
Electrification mandates across multiple jurisdictions are compressing gas appliance replacement cycles while rerouting R&D budgets toward induction coil efficiency and power electronics miniaturization. This structural shift is redrawing competitive advantage around electromagnetic heating expertise rather than legacy burner engineering.
Growth Catalysts
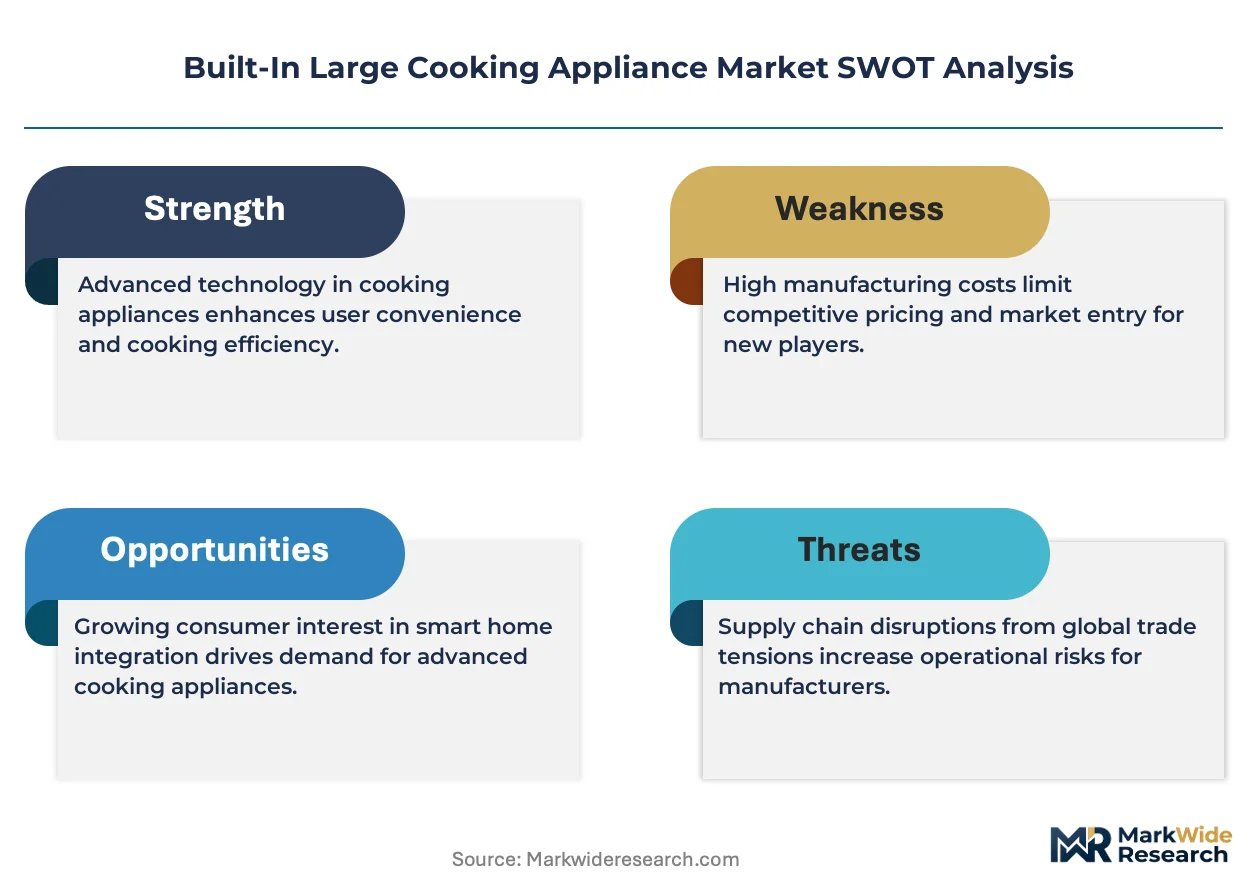
- EU Ecodesign Directive thresholds:Tightening energy efficiency indices for electric ovens force manufacturers to invest in convection airflow optimization and advanced insulation materials, accelerating product refresh cycles across member states.
- Luxury residential clusters:Premium developers in Dubai and Riyadh are specifying built-in induction suites for high-end apartment deliveries, creating concentrated demand pockets for 3,500-watt plus cooktop configurations.
- Induction coil wattage escalation:Power density improvements enabling boil times competitive with gas flames are converting skeptical home cooks in China's tier-one renovation markets.
Market Restraints
- Copper and rare earth magnet cost volatility:Induction cooktop production depends on neodymium-iron-boron magnets and heavy-gauge copper windings, exposing margin structures to mining supply disruptions and export quota shifts.
- Legacy gas infrastructure lock-in:Persistent pipeline networks in select US states create regulatory friction against electrification mandates, fragmenting product portfolio requirements by jurisdiction.
- Electrical panel upgrade requirements:Residential 240-volt circuit availability limits induction adoption in older housing stock, particularly in mature suburbs where kitchen renovation spending concentrates.
Strategic Opportunities
- Commercial kitchen electrification:Foodservice operators facing Scope 3 emissions targets present untapped demand for high-duty-cycle induction ranges with sealed ceramic surfaces.
- Smart home integration convergence:Combining induction power management with voice-activated recipe guidance and automated ventilation coordination opens premium positioning adjacent to connected appliance ecosystems.
- India BIS energy labeling expansion:Proposed mandatory efficiency grades for cooking appliances would create first-mover advantage for brands with existing inverter-based induction platforms.
Industry Challenges
- Power electronics engineering talent scarcity:Designing reliable IGBT and MOSFET control systems for residential induction requires specialized expertise concentrated in automotive and industrial inverter sectors.
- Multi-jurisdiction certification timelines:Securing CE marking, UL listings, and China's CCC approval simultaneously extends product launch schedules and strains testing laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Built-In Large Cooking Appliance Market |
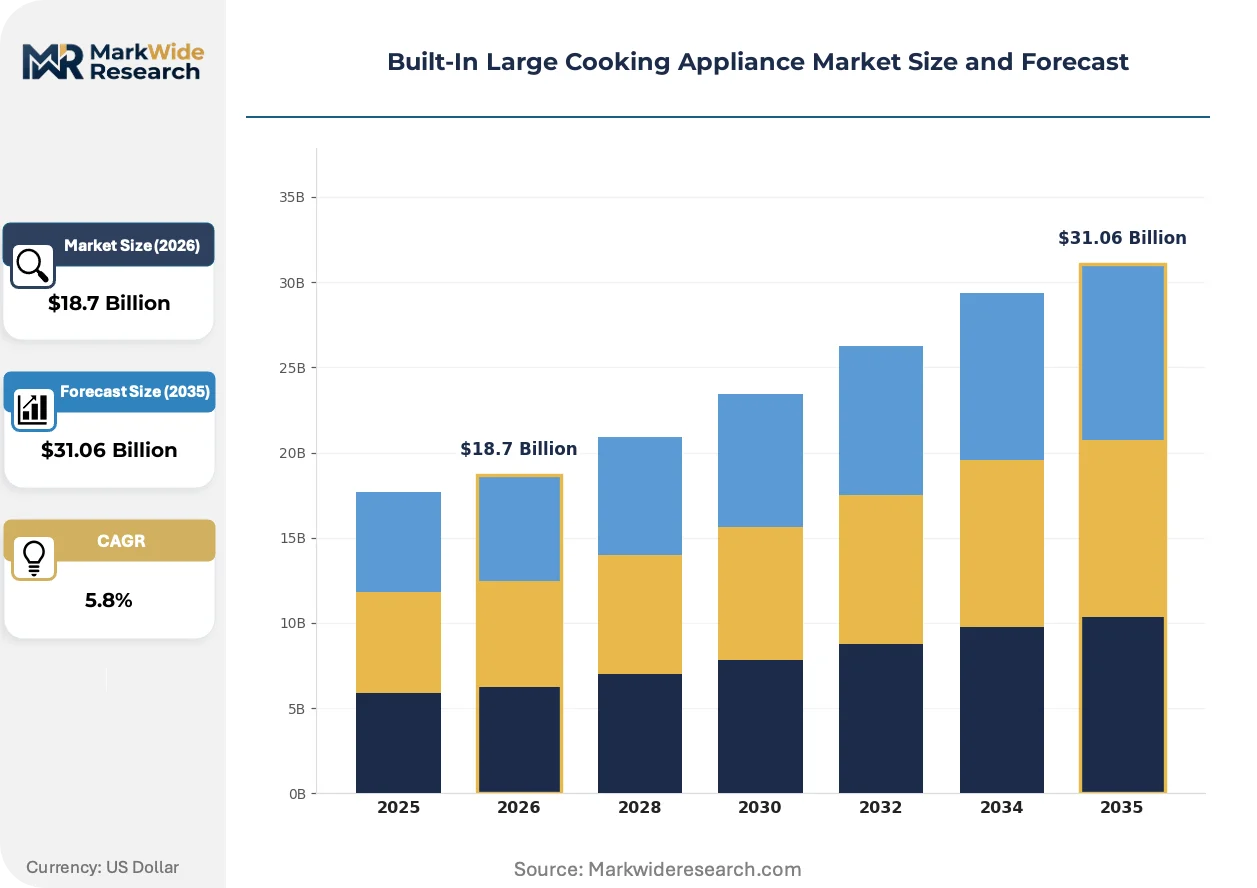
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ovens, Ranges, Cooktops, Wall Ovens Installation Type: Kitchen Remodel, New Construction, Luxury Homes, Rental Properties Fuel Type: Electric, Gas, Induction, Dual Fuel End User: Residential, Commercial, Hospitality, Catering |
| Companies Covered | BSH Hausgeräte GmbH, Whirlpool Corporation, Electrolux AB, Miele & Cie. KG, Samsung Electronics Co., Ltd., LG Electronics Inc., Robert Bosch GmbH, Haier Smart Home Co., Ltd., Fisher & Paykel Appliances Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Built-In Large Cooking Appliance Market Strategic Shifts
Product development trajectories in built-in cooking appliances center on thermal performance optimization, embedded intelligence, and compliance automation. These vectors are compressing traditional hardware refresh timelines while elevating software and sensor content in bill-of-materials.
Induction technology is electrifying residential cooking infrastructure by replacing open-flame gas burners with precision electromagnetic heating. Luxury kitchen renovators and premium hospitality specifiers are specifying these systems at accelerating rates. This transition is electrifying margin pool redistribution toward power electronics suppliers and away from legacy gas valve and burner component manufacturers.
REACH substance restrictions and pending PFAS limitations in Europe are forcing reformulation of non-stick coatings and high-temperature gaskets used in oven cavities. Manufacturers are qualifying ceramic-based and silicone alternatives that maintain thermal stability without fluorinated compounds. Wall oven categories destined for EU markets are absorbing the bulk of compliance engineering hours and material qualification costs.
Builder channel consolidation is compressing procurement decision cycles and elevating specification authority toward national purchasing agreements. Regional distributors and local appliance dealers are losing share to direct manufacturer relationships with large development groups. This pattern is most visible in North American production homebuilding where national accounts now dictate standard appliance packages across multiple states.
Built-In Large Cooking Appliance Market Segmentation
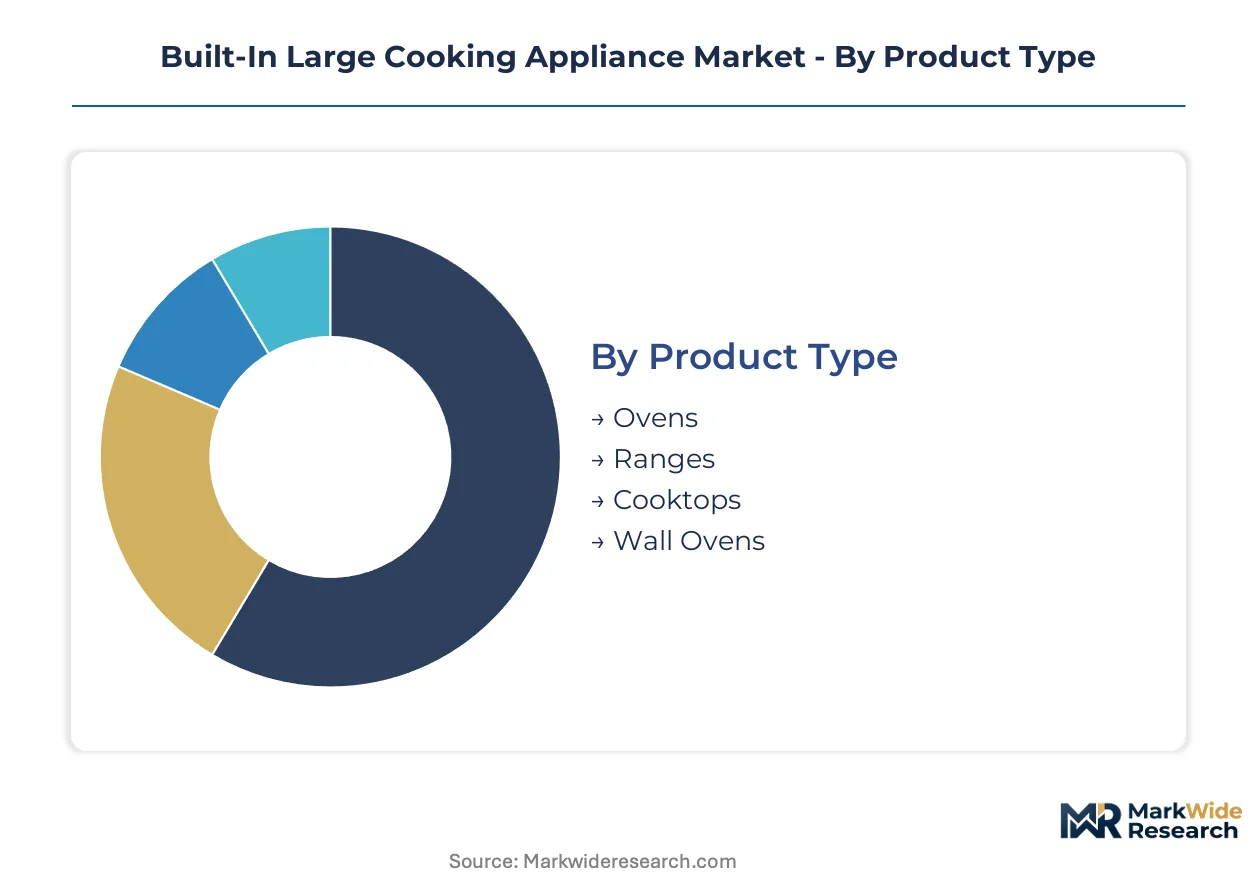
Segmentation in built-in cooking appliances reveals how installation context and fuel infrastructure shape procurement patterns. Developers, renovators, and foodservice operators each impose distinct technical specifications and margin expectations on manufacturers.
Product Type:
Integration depth varies sharply: wall ovens and cooktops embed permanently into cabinetry, while ranges function as semi-standalone anchor units.
- Wall Ovens:These units install at eye level within custom cabinetry, requiring precise ventilation integration and convection airflow engineering. Demand clusters in kitchen remodels across China's tier-one cities where vertical space optimization drives specification. The EU Ecodesign Directive's tightening efficiency thresholds force continuous insulation and heating element upgrades.
- Cooktops:Surface-mounted units with sealed burners or induction coils integrate flush with countertops. Luxury residential developers in Dubai and Riyadh specify 3,500-watt induction configurations for premium apartment deliveries. Power electronics miniaturization and coil efficiency improvements are redirecting R&D budgets from legacy burner engineering.
- Ovens:Freestanding cavity units with lower cabinet integration serve budget-conscious renovation segments. BIS energy labeling in India is elevating efficiency requirements for cavity insulation standards.
- Ranges:Combined cooktop-oven units occupy intermediate integration depth, popular in North American builder channels where single-appliance solutions reduce installation complexity.
Volume placements concentrate in wall ovens; the faster expansion belongs to cooktops.
Installation Type:
Project timing determines specification authority: remodels prioritize aesthetic matching and fuel conversion flexibility, while new construction locks in infrastructure decisions early.
- Kitchen Remodel:Existing housing stock renovations dominate mature markets, with homeowners replacing gas infrastructure with induction during electrical panel upgrades. This segment absorbs the bulk of premium product mix in European and North American markets.
- New Construction:Production homebuilding and multi-family developments specify standardized appliance packages through national purchasing agreements. Builder channel consolidation is compressing procurement cycles and elevating manufacturer-direct relationships.
- Luxury Homes:Custom residential projects in Gulf Cooperation Council cities specify imported European brands with bespoke finishing options.
- Rental Properties:Institutional landlords prioritize durability and standardized maintenance protocols over performance features, favoring electric resistance over induction for tenant-proofing.
Procurement volume tilts toward kitchen remodel; steepest expansion trajectory appears in luxury homes.
Fuel Type:
Regulatory divergence between electrification mandates and gas infrastructure persistence fragments portfolio requirements by jurisdiction.
- Induction:Electromagnetic coil systems deliver precision heating without open flame. China's tier-one renovation markets and European residential new construction are specifying these at accelerating rates as boil times match gas performance.
- Electric:Resistance-element systems serve markets with limited electrical capacity or lower renovation budgets. ENERGY STAR certification requirements in the US disqualify sub-threshold models from retail and builder channels.
- Gas:Open-flame burner systems retain share in markets with established pipeline infrastructure. Persistent gas networks in select US states create regulatory friction against electrification mandates.
- Dual Fuel:Hybrid configurations combining gas cooktops with electric ovens serve transitional markets and chef-preference segments unwilling to abandon flame cooking entirely.
Shipments concentrate in electric systems; induction is climbing the fastest as efficiency regulations tighten.
End User:
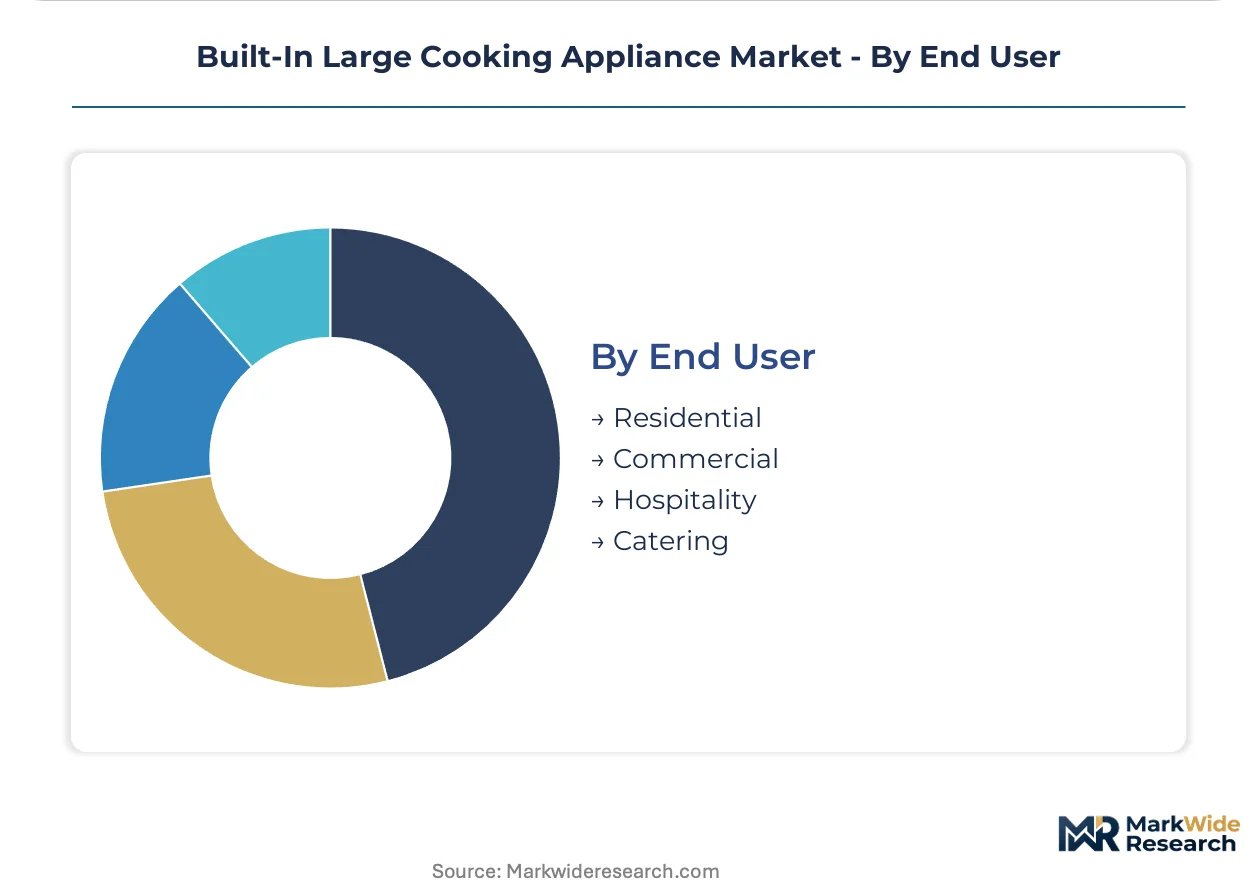
Usage intensity and aesthetic requirements diverge: residential users prioritize smart integration and finish matching, while commercial operators emphasize duty cycle durability and emissions compliance.
- Residential:Homeowners and landlords specify built-in appliances for space efficiency and kitchen aesthetic unity. This segment absorbs connected appliance features and voice-activated recipe guidance integration.
- Commercial:Foodservice operators facing Scope 3 emissions targets present emerging demand for high-duty-cycle induction ranges with sealed ceramic surfaces.
- Hospitality:Hotel and resort kitchen specifications balance durability with guest-visible design, often importing European brands for back-of-house installations in premium properties.
- Catering:Mobile and event foodservice requires portable-compatible equipment, limiting built-in penetration to permanent commissary installations.
Order volume concentrates in residential; commercial applications are gaining share fastest as electrification mandates reach foodservice operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium mining deposits in Inner Mongolia and copper refining capacity in Jiangxi Province anchor Asia-Pacific supply chains for induction coil manufacturing. These raw material localities shape regional production economics and component sourcing strategies across the built-in appliance sector.
China
MIIT circular economy guidelines enforce material recovery rates on domestic manufacturers, altering gas cooktop component sourcing. Tier-one cities including Shanghai and Beijing concentrate kitchen renovation spending where induction boil times now match gas performance. Yangtze River Delta manufacturing clusters supply electromagnetic coils to regional appliance assemblers.
Germany
The EU Ecodesign Directive's tightening efficiency thresholds force continuous insulation upgrades in wall oven engineering. KBA-adjacent industrial standards influence commercial kitchen equipment durability specifications. Bavarian engineering centers develop convection airflow optimization systems for premium European brands.
United States
EPA ENERGY STAR certification shapes product access in retail and builder channels by disqualifying sub-threshold electric models. Persistent gas pipeline networks in Texas and Pennsylvania create regulatory friction against electrification mandates. Southeast production homebuilding corridors specify standardized appliance packages through national purchasing agreements.
United Arab Emirates
MOHAP product safety frameworks govern imported appliance standards for Gulf Cooperation Council markets. Luxury residential developers in Dubai specify 3,500-watt induction configurations for premium apartment deliveries. Riyadh-based hospitality groups anchor demand for imported European cooking suites in Saudi Arabia.
India
BIS energy labeling expansion is elevating efficiency requirements for cavity insulation standards in domestic manufacturing. Maharashtra and Gujarat industrial zones produce inverter-based induction platforms for emerging middle-class demand. Delhi-NCR renovation markets absorb growing volumes of built-in cooktop installations.
Built-In Large Cooking Appliance Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue smart home integration and commercial electrification niches. The vendor base stratifies across three tiers: captive-component manufacturers controlling margin pools, scale-driven suppliers dominating builder channels, and premium specialists serving luxury residential specifications. Two dominant competitive moves define current positioning: backward integration into power electronics manufacturing and direct national account relationships with consolidated developer groups.
Among Germany-based producers, BSH Hausgeräte GmbH and Miele & Cie. KG exemplify the captive-component archetype through in-house control over premium wall oven engineering. Whirlpool Corporation anchors the scale-driven tier, occupying a position across North American builder channels. These three entities represent distinct strategic postures: precision manufacturing depth, volume procurement leverage, and brand premiumization respectively.
| Leading Market Players |
|---|
| BSH Hausgeräte GmbH |
| Whirlpool Corporation |
| Electrolux AB |
| Miele & Cie. KG |
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Robert Bosch GmbH |
| Haier Smart Home Co., Ltd. |
| Fisher & Paykel Appliances Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Electromagnetic coil manufacturing migration toward automated winding and in-house magnet assembly is compressing production economics while concentrating supply leverage among producers with captive neodymium sourcing. This dual shift elevates pricing power for integrated manufacturers and exposes non-integrated assemblers to margin volatility when rare earth export quotas tighten.
Pricing Analysis
Warranty bundling and extended service contracts separate premium wall oven configurations from standard-tier offerings, with BSH and Miele embedding multi-year coverage into list pricing. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and coil wattage density, with CE-marked induction cooktops commanding measurable premiums over basic electric resistance units. Cost compression in economy-tier electric ranges is intensifying because Southeast Asian contract manufacturers are absorbing copper price volatility to maintain builder channel share. National homebuilders exhibit highest price sensitivity, while luxury residential developers in Gulf Cooperation Council markets prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns for finished appliance logistics, with last-mile delivery resting on dedicated fleet contracts with national retail chains. Component manufacturing concentrates in China, Germany, and Mexico, with neodymium-iron-boron magnets drawing from Inner Mongolia mining deposits and heavy-gauge copper windings sourcing from Jiangxi Province refineries. Single-source vulnerability in rare earth magnet supply creates structural exposure to export quota shifts by Chinese regulators. Distribution runs through direct manufacturer relationships with consolidated developer groups, bypassing traditional regional distributor networks in North American builder channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics engineering talent scarcity props pricing for induction platforms, constraining capacity expansion and sustaining margin pools for incumbents with captive expertise. Supply-side bottlenecks in IGBT and MOSFET control system design limit competitive entry and reinforce incumbent pricing leverage.
For Market Incumbents: Hedge against rare earth supply disruption by securing long-term magnet procurement agreements with Inner Mongolia producers or qualifying alternative ferrite-based coil designs for mid-tier segments. Deepen backward integration into power electronics manufacturing to defend margin pools as electromagnetic heating expertise displaces legacy burner engineering competence. Monitor BIS energy labeling expansion in India as a regulatory shift requiring preemptive inverter platform certification investment. For New Entrants and Emerging Players: The price-point gap between premium European induction suites and economy electric ranges creates white-space opportunity for mid-tier brands with certified efficiency and connected feature integration. Target India's emerging middle-class renovation demand in Delhi-NCR and Maharashtra as the most penetrable geography, where BIS labeling expansion favors first-movers with existing inverter platforms. Pursue direct e-commerce distribution with installation service bundling as the primary go-to-market angle, bypassing consolidated builder channel gatekeepers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified appliance conglomerates seeking electromagnetic heating capability, with strategic value hinging on captive coil manufacturing or power electronics engineering depth. Long-term viability favors producers with integrated supply chains and regional certification breadth across CE marking, UL listings, and China's CCC approval. Watch induction boil-time parity with gas flames in Chinese tier-one renovation markets as the signal indicating inflection toward mass-market electrification adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive IGBT and MOSFET production secures margin pools as electromagnetic heating displaces gas burner engineering. |
| Direct National Account Relationships | Bypassing regional distributors captures specification authority with consolidated luxury developers in Dubai and Riyadh. |
| Multi-Jurisdiction Certification Investment | Simultaneous CE marking, UL listing, and CCC approval accelerates product launch velocity across priority markets. |
| Smart Home Platform Integration | Voice-activated recipe guidance and automated ventilation coordination opens premium positioning adjacent to connected ecosystems. |
| Commercial Kitchen Electrification Focus | High-duty-cycle induction ranges address Scope 3 emissions targets for foodservice operators seeking sealed ceramic surfaces. |
Study Parameters
Trade association filings, customs and import records, and regulatory submission databases formed the secondary backbone, supplemented by SEC 10-K disclosures and energy efficiency certification registries. Primary interviews with product development executives at major appliance manufacturers, procurement leads at national homebuilder groups, power electronics engineering directors, and commercial kitchen equipment specifiers provided operational validation. Bottom-up shipment estimates by product type and fuel category were cross-checked against top-down market value reconstructions to establish triangulation integrity.
Historical trendline analysis of replacement cycle patterns, renovation spending correlations, and regulatory compliance cost absorption informed the projection framework across the analysis window. Segmentation modeling incorporated product type, installation context, fuel infrastructure, and end-user intensity dimensions. CAGRs were derived from fitted trend extrapolation adjusted for electrification mandate implementation schedules and copper price volatility assumptions. Industry-specific inputs included MIIT circular economy guideline enforcement timelines and EU Ecodesign Directive threshold escalation pathways.
Inputs from trade associations and regulatory certification bodies were available through the study window; gaps in real-time commercial kitchen operator procurement data introduce uncertainty bands around foodservice electrification adoption rates. Forecasts reflect documented assumptions regarding electrification mandate enforcement consistency and rare earth supply quota stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
France Household Side by Side Refrigerator Market
Appliances
North America Personal Care Appliances Market
Appliances
US Portable Washing Machines Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
GCC Microwave Oven Market
Appliances
Egypt Dishwashers Market
Appliances
Small Electric Kettles Market
Appliances
Oman Microwave Ovens Market
Appliances
Household Beauty Appliances Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
Body Dryer Market
Appliances
Refrigerated Cabinet Market
Appliances
Portable Mini Fridge Market
Appliances
Mini Refrigerator Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Global Home Ice Maker Market