
 Commercial Microwave Ovens Market | 2026-2036
Commercial Microwave Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Microwave Ovens Market Analysis
The EU Ecodesign Directive is pivoting procurement standards across European foodservice chains toward lower standby power consumption and improved energy efficiency in commercial kitchen equipment. Panasonic Corporation leverages its inverter technology leadership to sustain premium positioning in high-wattage segments. Midea Group anchors volume production through manufacturing scale across multiple capacity tiers. Sharp Corporation differentiates through specialized designs targeting hospital and institutional cafeterias with strict sanitation protocols.
A commercial microwave oven is an electrically powered food-heating appliance designed for continuous-duty cycles in professional kitchens, typically operating at power levels from 1,000 to 3,000 watts with stainless steel interiors and programmable control interfaces. Its primary commercial purpose is rapid thermal processing of prepared foods, defrosting, and reheating across high-throughput foodservice environments. Countertop configurations dominate installed base due to flexibility in kitchen layout and lower capital outlay, while combination units integrating convection and microwave energy represent the fastest-growing product type as operators seek equipment consolidation. Sensor cooking technology commands margin premiums by reducing operator training requirements and standardizing output quality across variable load conditions.
The US Department of Energy appliance standards, EU Ecodesign Directive, and China's GB national energy efficiency standards collectively shape product development priorities and market access requirements across major manufacturing and consumption geographies. Compliance with overlapping efficiency and safety frameworks now determines which product portfolios gain distribution in regulated channels versus remaining confined to secondary markets. Stakeholders must monitor evolving efficiency tier thresholds and harmonization gaps between regional certification regimes to anticipate redesign cycles and inventory obsolescence risks.
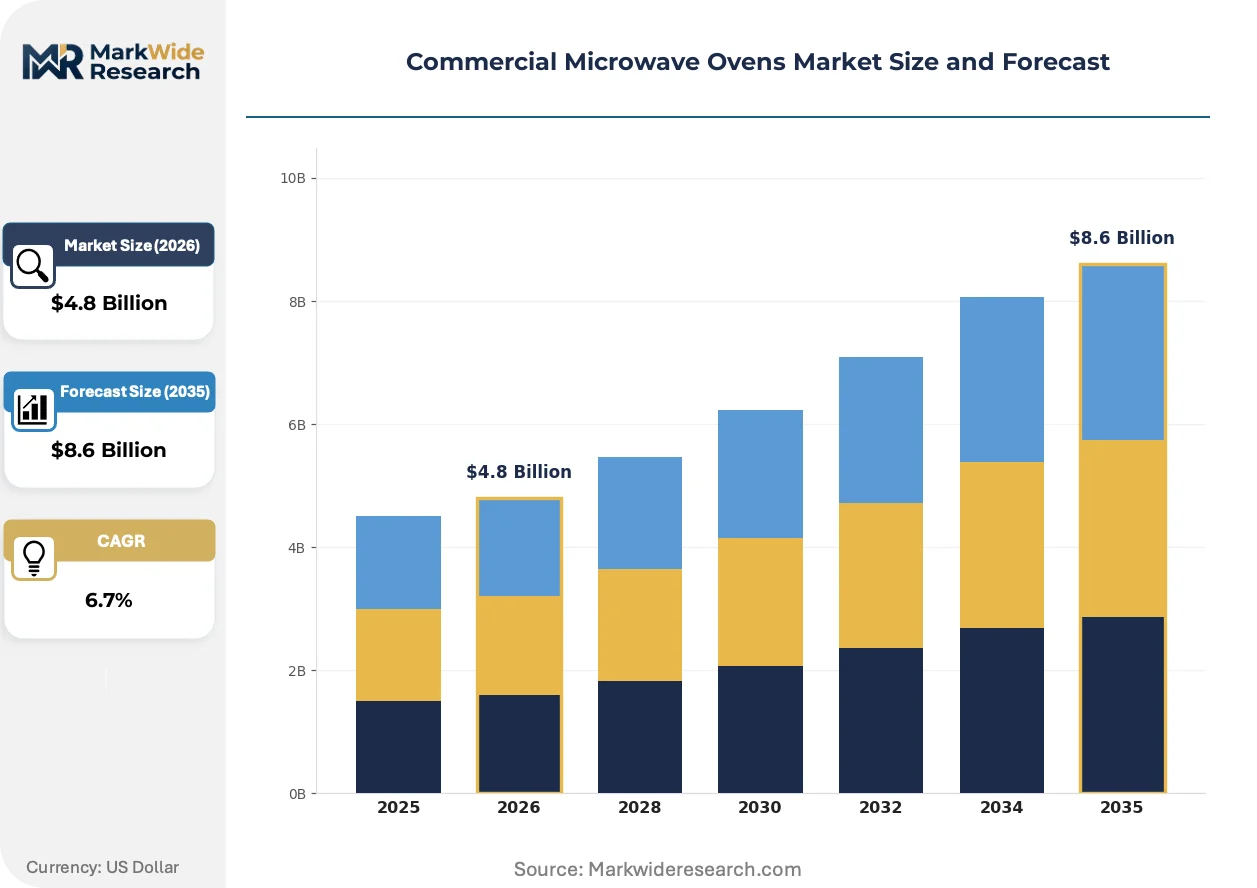
Market Dynamics
The EU Ecodesign Directive's standby power limits are compressing redesign cycles across commercial kitchen equipment portfolios, forcing manufacturers to revalidate inverter architectures and control systems ahead of regulatory deadlines.
Growth Catalysts
- Quick-service restaurant expansion:High-throughput chains in the United States are standardizing on 1,800-3,000 watt units to reduce ticket times during peak hours.
- China's GB energy efficiency standards:Tier-1 certification requirements are filtering import portfolios and elevating domestic inverter-based models in procurement specifications.
- Sensor cooking adoption:Load-recognition algorithms are reducing operator training burdens in institutional cafeterias with high staff turnover.
Market Restraints
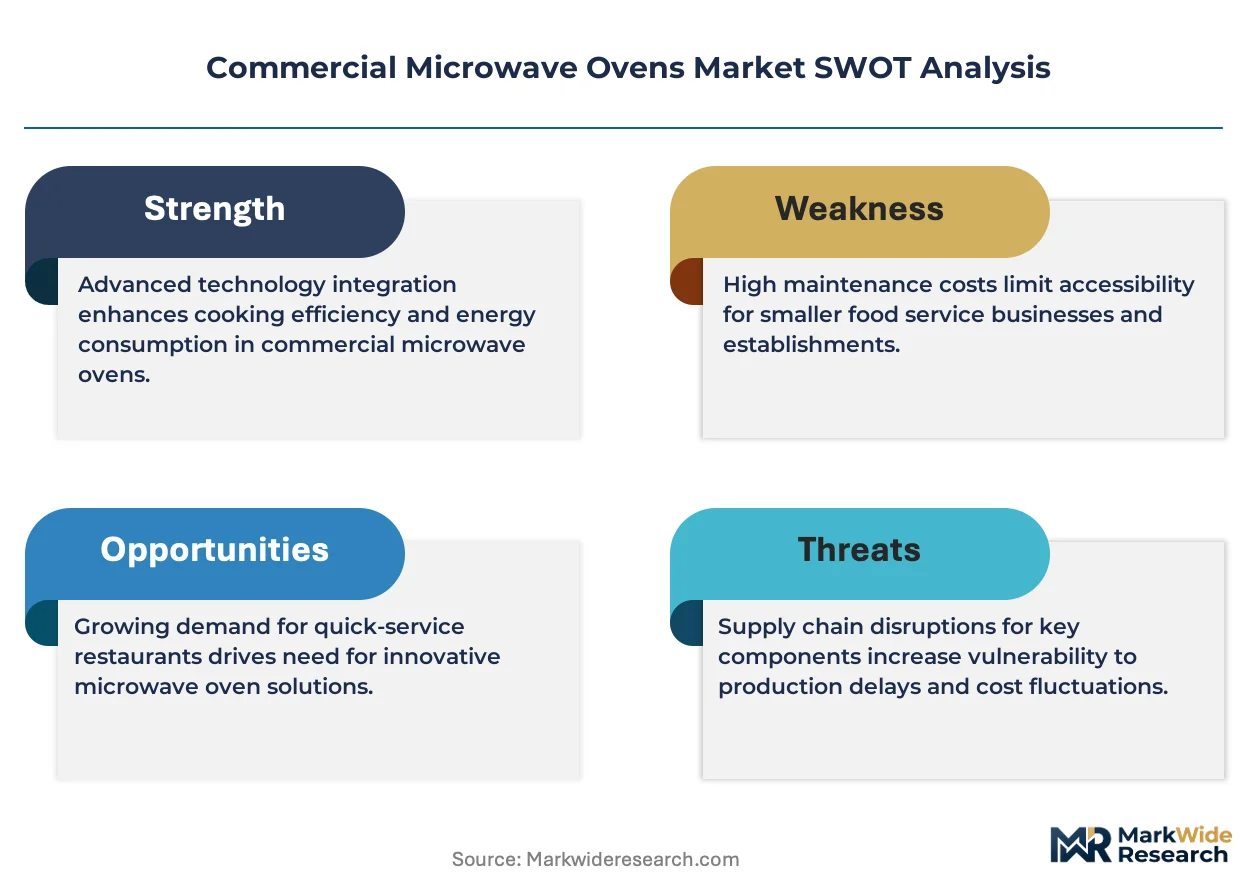
- Magnetron supply concentration:Specialist component fabrication clusters in East Asia create single-source vulnerability for high-wattage tube assemblies.
- Stainless steel input volatility:Grade 304 sheet price swings directly compress margin structures for mid-tier equipment manufacturers.
- Combination unit technical complexity:Dual-energy calibration requirements extend field service training timelines and increase warranty exposure.
Strategic Opportunities
- Germany's building energy efficiency incentives:Commercial kitchen retrofit subsidies are accelerating replacement demand in aging hotel and hospital facilities.
- Cloud-connected diagnostics convergence:IoT-enabled fault prediction is creating recurring revenue streams alongside hardware sales.
- India's FSSAI commercial kitchen certification:Emerging food safety mandates in tier-1 cities are opening specification windows for stainless-steel, programmable units.
Industry Challenges
- Cross-regional certification timelines:Simultaneous UL, CE, and GB mark pursuit stretches engineering bandwidth and delays product launches.
- Legacy control interface integration:Kitchen management system APIs lack standardization, forcing custom middleware development for enterprise accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Microwave Ovens Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Stand-alone, Built-in, Combination End User: Restaurants, Cafeterias, Hospitals, Catering Services Technology: Convection, Grilling, Conventional, Sensor Cooking Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Panasonic Corporation, Midea Group, Sharp Corporation, Amana Commercial, Whirlpool Corporation, TurboChef Technologies, Merrychef, Samsung Electronics, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Microwave Ovens Market Emerging Trajectories
Inverter power control architectures are displacing traditional transformer-based designs across wattage tiers, while regulatory pressure on standby consumption accelerates firmware and hardware co-development cycles.
Variable-frequency inverter modules are replacing fixed-output magnetron drivers in commercial microwave ovens, enabling precise power modulation during multi-stage cooking programs. Quick-service chains with standardized menu portfolios are adopting these units fastest, recognizing reduced food waste from overcooking. The technology is modularizing equipment architectures, allowing manufacturers to reuse control platforms across countertop and built-in form factors.
The EU Ecodesign Directive's 2027 standby power thresholds are forcing control board redesigns and standby state optimization across imported and domestic equipment lines. Manufacturers serving European foodservice chains must recertify existing portfolios or face distribution channel exclusion. Combination microwave-convection units face the steepest compliance costs due to dual-circuit standby requirements.
Hospital and aged-care cafeteria operators are consolidating vendor relationships around equipment suppliers offering HACCP-aligned sanitation documentation and preventive maintenance contracts. Traditional distributor networks are losing share to direct manufacturer service agreements in this segment. Germany's institutional healthcare procurement frameworks are formalizing these bundled service requirements in tender specifications.
Commercial Microwave Ovens Market Segmentation
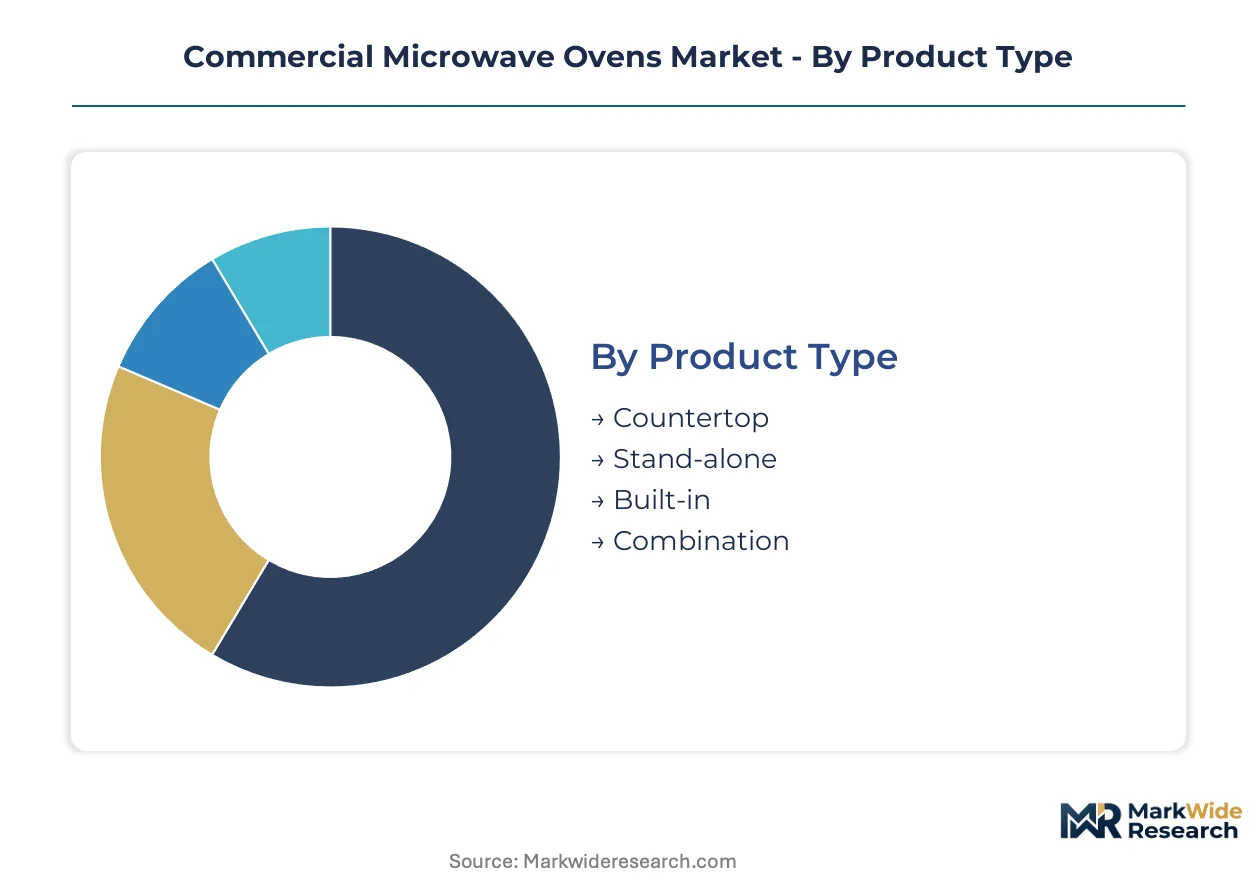
Commercial microwave ovens segment across multiple technical and operational dimensions, each carrying distinct certification burdens and margin profiles. Procurement specifications diverge sharply between high-throughput quick-service chains and institutional healthcare operators, creating tiered demand patterns that manufacturers must address through differentiated product architectures.
Product Type:
UL and CE mark requirements vary significantly across form factors, with built-in and combination units demanding additional safety validation for integrated ventilation and dual-energy systems. Countertop configurations face lighter recertification cycles but heavier price competition.
- Countertop:Portable stainless-steel chassis with 1,000–2,200 watt magnetrons dominate installed base in independent restaurants and small cafeterias. Flexibility in kitchen layout drives procurement across the United States and Germany, though operators absorb higher per-unit labor costs from manual loading and unloading.
- Combination:Integrated microwave-convection systems with programmable multi-stage profiles command specification in high-volume catering and hotel chains seeking equipment consolidation. Dual-circuit standby requirements under EU Ecodesign Directive compress margins fastest for this segment, yet sensor-enabled variants reduce food waste enough to justify premium positioning.
- Stand-alone:Heavy-duty floor units with 3,000+ watt output serve central commissary operations in large hospital systems.
- Built-in:Custom-integrated modules for architectural kitchen specifications carry extended lead times and specialized installation protocols.
Leading the category by volume: Countertop. Expanding most quickly: Combination.
End User:
Customer-type segmentation reveals diverging service intensity and replacement cycle expectations, with healthcare and institutional accounts demanding preventive maintenance bundling that reshapes vendor economics.
- Restaurants:Quick-service chains in the United States standardize on 1,800–3,000 watt inverter-based units to compress ticket times during peak hours, while full-service operators prioritize programmable consistency over raw throughput.
- Hospitals:HACCP-aligned sanitation documentation and stainless-steel construction dominate procurement in Germany's institutional healthcare frameworks, with tender specifications increasingly mandating direct manufacturer service agreements over traditional distributor relationships.
- Cafeterias:School and corporate feeding operations balance capital constraints against durability requirements in high-turnover staff environments.
- Catering Services:Mobile and event-focused operators prioritize lightweight, rapid-deployment configurations with generator-compatible power draws.
Highest service attachment rates: Hospitals. Steepest price sensitivity: Cafeterias.
Technology:
Power control architectures segment the market between legacy transformer systems and inverter-based platforms, with regulatory pressure on standby consumption accelerating firmware-hardware co-development investment.
- Sensor Cooking:Load-recognition algorithms with humidity and temperature feedback loops reduce operator training burdens in institutional cafeterias with high staff turnover, commanding margin premiums through standardized output quality.
- Convection:Forced-air circulation combined with microwave energy enables browning and crisping functions that expand menu versatility in hotel and catering applications.
- Grilling:Quartz or ceramic heating elements add surface searing capability for protein-focused menu items in steakhouse and casual dining segments.
- Conventional:Fixed-output magnetron systems retain share in cost-sensitive procurement channels despite efficiency disadvantages.
Widest installed base: Conventional. Gaining specification share fastest: Sensor Cooking.
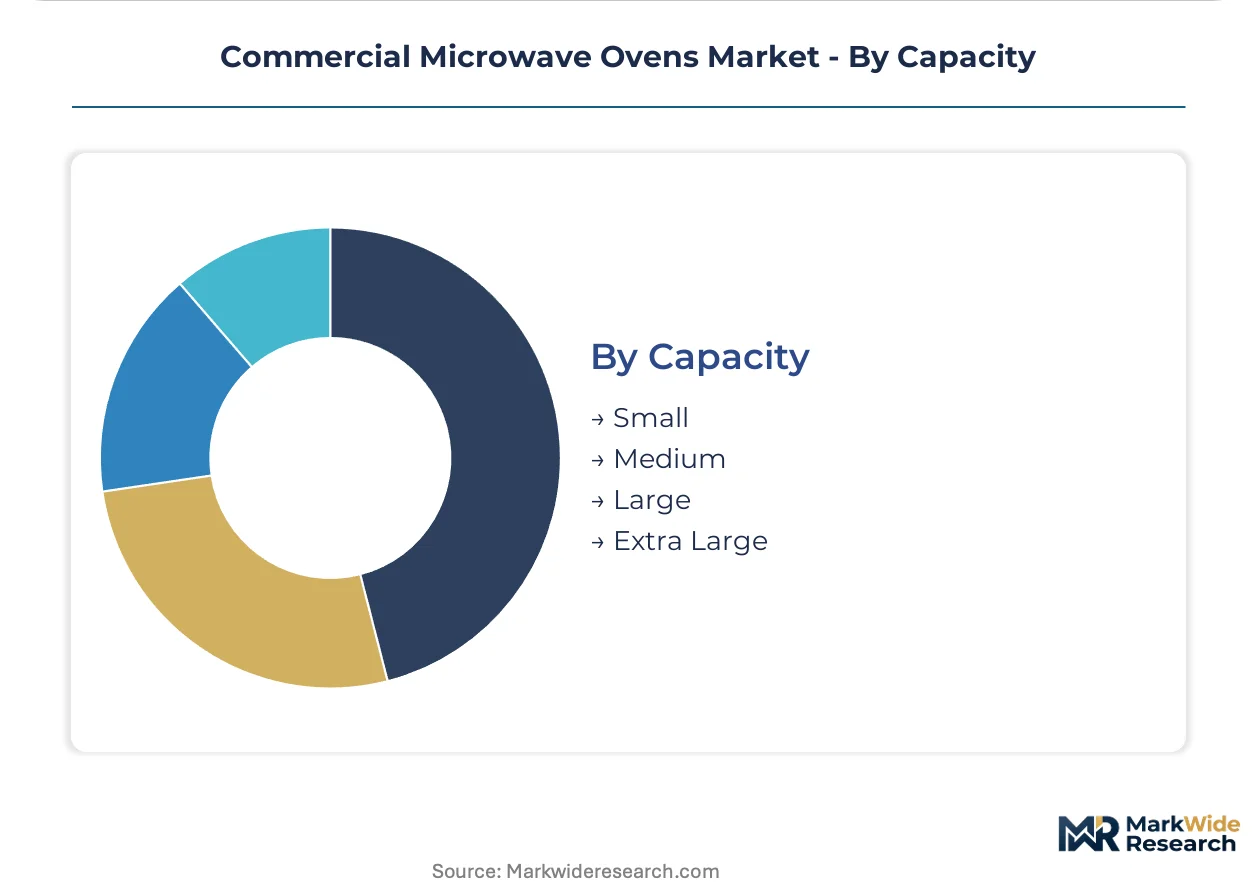
Capacity:
Volume-tier segmentation correlates directly with kitchen throughput requirements and electrical infrastructure investment, with extra-large units requiring three-phase power that limits addressable market in older building stock.
- Large:1.5–2.2 cubic foot cavities with 2,200–3,000 watt output anchor procurement in high-throughput quick-service chains across China and the United States, where batch processing of standardized menu items justifies dedicated electrical runs and ventilation hoods.
- Medium:1.0–1.4 cubic foot configurations balance throughput against space constraints in independent restaurants and small healthcare facilities.
- Small:Under 1.0 cubic foot units serve satellite warming stations and limited-menu kiosks with minimal footprint requirements.
- Extra Large:2.5+ cubic foot commercial chambers target central commissary and high-volume catering operations with continuous-duty cycles.
Highest unit economics: Large. Narrowest addressable market: Extra Large.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian electronics clusters while consumption spreads across North American quick-service chains and European institutional foodservice. China and South Korea anchor component fabrication for magnetrons and inverter modules. The United States, Germany, and China absorb the highest equipment volumes through diverging procurement channels.
United States
Quick-service restaurant chains standardize on 1,800–3,000 watt inverter units to compress ticket times during peak hours. The US Department of Energy appliance standards shape efficiency tier thresholds for imported equipment. Dallas-Fort Worth and Atlanta host distribution hubs serving high-throughput regional chains with rapid replacement cycles.
Germany
Hospital and aged-care cafeteria operators consolidate vendor relationships around HACCP-aligned sanitation documentation and preventive maintenance contracts. The EU Ecodesign Directive's 2027 standby power thresholds force control board redesigns across imported portfolios. North Rhine-Westphalia's institutional healthcare procurement frameworks formalize bundled service requirements in tender specifications.
China
Tier-1 certification under GB national energy efficiency standards filters import portfolios and elevates domestic inverter-based models in procurement specifications. The country's dual carbon goals accelerate efficiency mandates for commercial kitchen equipment. Guangdong Province's manufacturing clusters dominate magnetron and control module fabrication for global supply.
Japan
METI efficiency guidelines and JIS standards shape product development priorities for domestic and export-oriented manufacturers. Sensor cooking technology commands margin premiums in institutional cafeterias with high staff turnover. Osaka-based electronics clusters specialize in precision inverter module production for premium equipment tiers.
India
FSSAI commercial kitchen certification mandates in tier-1 cities open specification windows for stainless-steel, programmable units. Central Electricity Authority regulations on commercial building energy consumption influence equipment selection in new foodservice developments. Maharashtra's Mumbai-Pune corridor hosts emerging distribution networks targeting hospital and hotel retrofit demand.
Commercial Microwave Ovens Market Vendor Landscape
The competitive structure tilts toward diversified electronics conglomerates with captive component supply. Panasonic Corporation, Midea Group, and Sharp Corporation anchor the tiered vendor base alongside specialized foodservice equipment fabricators. Scale-driven players leverage manufacturing breadth across multiple capacity tiers, while premium specialists differentiate through inverter technology leadership and institutional sanitation protocols. Competitive moves center on firmware-hardware co-development for standby efficiency compliance and direct service agreement expansion in healthcare verticals.
Within the diversified electronics tier, Panasonic Corporation and Midea Group exemplify contrasting scale-versus-specialization strategies, while Sharp Corporation occupies a position bridging premium technology and institutional market focus. TurboChef Technologies and Merrychef represent the specialized foodservice equipment archetype with concentrated quick-service and hospitality exposure. Samsung Electronics and LG Electronics sit within the broader appliance conglomerate category, leveraging distribution scale across multiple commercial product categories. Amana Commercial and Whirlpool Corporation anchor the North American heritage brand segment with established service infrastructure.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Midea Group |
| Sharp Corporation |
| Amana Commercial |
| Whirlpool Corporation |
| TurboChef Technologies |
| Merrychef |
| Samsung Electronics |
| LG Electronics |
| Others |
Supply Flow & Price Mechanics
Grade 304 stainless steel sheet price volatility cascades through commercial microwave oven manufacturing into three distinct pricing tiers, with raw material swings compressing margins most severely for mid-tier equipment producers lacking captive metal supply or long-term contract hedging.
Pricing Analysis
Throughput-based value anchors segment pricing across quick-service, institutional, and independent restaurant buyer archetypes. Three-tier pricing structure across premium, standard, and economy levels separates inverter-equipped sensor units from conventional magnetron systems and basic fixed-output models. Cost compression in the mid-tier is intensifying because stainless steel input volatility and dual-circuit compliance costs for combination units squeeze manufacturers without scale advantages. Independent restaurants and small cafeteria operators exhibit steepest price sensitivity, while hospital procurement frameworks in Germany prioritize sanitation documentation and service bundling over unit cost.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Atlanta anchor North American hub-and-spoke patterns serving quick-service chains with rapid replacement cycles. Magnetron and inverter module fabrication concentrates in Guangdong Province, Osaka-based electronics clusters, and South Korean component foundries. Supply chains draw from specialist-grade 304 stainless steel mills, high-voltage capacitor suppliers, and programmable control board fabricators. Single-source vulnerability for high-wattage tube assemblies in East Asian clusters creates structural risk. Distribution runs through manufacturer-direct service agreements in healthcare verticals and traditional foodservice equipment distributors in independent restaurant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive control over inverter module production and magnetron supply determines margin defense against raw material volatility and certification compliance costs.
For Market Incumbents: Cement inverter technology leadership through firmware-hardware co-development cycles targeting EU Ecodesign Directive standby thresholds ahead of regulatory deadlines. Deepen backward integration into magnetron fabrication or secure long-term offtake agreements with East Asian tube specialists to mitigate single-source exposure. Defend against emerging domestic champions in China by accelerating direct service agreement penetration in Germany's institutional healthcare procurement frameworks.
For New Entrants and Emerging Players: Cloud-connected diagnostics platforms offer the most penetrable white-space entry route, enabling recurring revenue streams alongside hardware sales in underserved hospital and aged-care cafeteria segments. Target India's tier-1 cities where FSSAI commercial kitchen certification mandates are opening specification windows for stainless-steel, programmable units. Pursue OEM partnerships with quick-service chains seeking standardized menu portfolio equipment with sensor cooking capabilities to reduce operator training burdens.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier equipment manufacturers with established UL and CE certification portfolios but strained working capital from stainless steel price volatility, particularly those with installed base concentration in Germany's retrofit-driven institutional market. Long-term viability hinges on inverter technology migration and service revenue attachment rates rather than pure hardware shipment volumes. Watch for inflection signals in combination unit specification share within European foodservice chain procurement tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Module Backward Integration | Captive production of variable-frequency drivers insulates margin structures from East Asian component supply volatility. |
| Cloud-Connected Diagnostics Launch | IoT-enabled fault prediction creates recurring revenue streams alongside hardware sales in healthcare verticals. |
| EU Ecodesign Pre-Compliance Certification | Early standby power validation secures distribution channel access ahead of 2027 regulatory deadlines. |
| Direct Service Agreement Expansion | Manufacturer-controlled maintenance contracts displace traditional distributors in Germany's hospital procurement frameworks. |
| Sensor Cooking Platform Standardization | Load-recognition algorithm reuse across countertop and built-in form factors accelerates R&D efficiency. |
Methodological Framework
Trade databases, regulatory filing repositories, and foodservice equipment industry associations formed the secondary backbone, supplemented by primary interviews with quick-service chain procurement directors, hospital biomedical engineering managers, commercial kitchen equipment distributors, and aftermarket service technicians. Bottom-up and top-down triangulation validated shipment volumes and pricing tiers across capacity segments and technology architectures.
Bottom-up modeling anchored forecasts in unit-level demand patterns across quick-service, institutional, and independent restaurant end-use segments, while top-down cross-checks incorporated macroeconomic indicators and commercial construction activity indices. Segmentation dimensions spanned product type, end-user vertical, power control technology, and cavity capacity tier. CAGRs were derived from regression analysis of historical shipment trajectories and regulatory-driven replacement cycle acceleration.
Inputs from customs records and manufacturer shipment disclosures were available through the study window; gaps in real-time distributor inventory positions and spot stainless steel pricing introduce uncertainty bands around near-term margin projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Digital Showers Market
Appliances
Smart Dishwasher Market
Appliances
Oman Dishwashers Market
Appliances
Electric Iron Market
Appliances
Small Appliances Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Smart Washing Machine Market
Appliances
Hair Removal Appliances Market
Appliances
Saudi Arabia Dishwasher Market
Appliances
Qatar Microwave Ovens Market
Appliances
Asia Pacific Water Heater Market
Appliances
Microwave Market
Appliances
Egypt Dishwashers Market
Appliances
Washing Appliances Market
Appliances
Mini Washing Machine Market
Appliances
Refrigerated Cabinet Market