
 Mini Washing Machine Market | 2026-2036
Mini Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Washing Machine Market Foresight
Smart inverter motor technology is rewriting the engineering economics of mini washing machines, replacing fixed-speed induction motors with variable-frequency drives that cut energy draw and mechanical noise. Midea leverages its vertical manufacturing footprint in Guangdong to control costs across compressor and motor assembly. Samsung competes through connected-home integration, embedding Wi-Fi modules that sync wash cycles with utility rate signals. Bosch anchors its position in European markets through precision German engineering and extended warranty programs that reduce replacement frequency.
Mini washing machines are self-contained laundry appliances engineered for loads typically under 6 kg, utilizing direct-drive or belt-drive drum systems with spin speeds ranging from 600 to 1400 RPM to extract moisture in confined installations. Their primary purpose is delivering garment cleaning functionality where floor space, plumbing connections, or electrical capacity constrain standard appliance deployment. Portable and fully automatic product types command divergent margin structures, with portable units targeting price-sensitive transient consumers while fully automatic models capture premium positioning through integrated drying and programmable cycles. The 3-4 kg capacity band occupies the commercial sweet spot, balancing load utility against shipping cube efficiency for e-commerce channels serving dormitory and RV owner end users.
ENERGY STAR certification from the EPA and EU Ecodesign Directive efficiency tiers shape product development roadmaps, forcing redesign of heating elements and pump architectures to meet tightening consumption thresholds. China's GB standards for household appliance safety and water efficiency ratings from the national quality administration further fragment compliance requirements for exporters. India's BIS mandatory certification for electronic goods adds another gate for market entry, particularly affecting compact models with heating functions. Stakeholders must monitor how regional efficiency benchmarks diverge, as harmonization failures between North American and European test protocols multiply SKU complexity and inventory carrying costs.
Market Dynamics
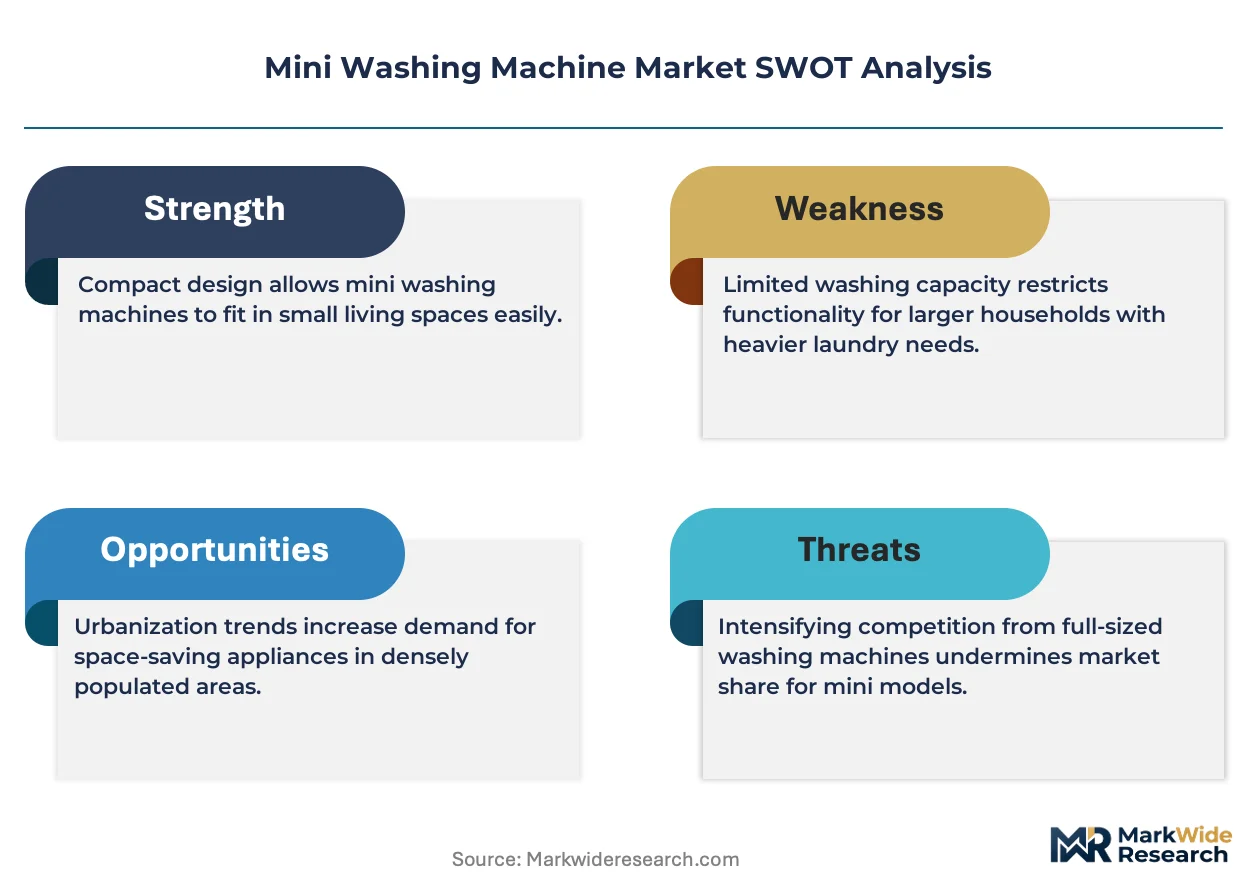
Smart inverter motor technology is compressing the cost-performance frontier for mini washing machines, forcing fixed-speed induction architectures into rapid obsolescence while redistributing margin pools toward motor-control firmware and power electronics suppliers.
Growth Catalysts
- EPA ENERGY STAR efficiency mandates:Water consumption thresholds for compact washers tightened in 2024, pulling forward replacement cycles among rental property portfolios seeking compliance certification.
- Urban micro-living proliferation:Young professionals in China's tier-two cities occupy sub-40 square meter apartments lacking built-in laundry infrastructure, creating installed-base gaps.
- Direct-drive drum systems:Elimination of belt-and-pulley mechanisms reduces mechanical failure rates and noise signatures, expanding deployment into bedroom-adjacent installations previously excluded.
Market Restraints
- Copper and rare-earth magnet cost volatility:Inverter motor production depends on neodymium supply concentrated in Chinese processing facilities, exposing BOM costs to export quota fluctuations.
- Fragmented certification requirements:Divergent test protocols between EPA ENERGY STAR and EU Ecodesign multiply SKU proliferation, inflating inventory carrying costs for cross-border manufacturers.
- Shared laundry facility substitution:Apartment complexes in dense German and Dutch cities maintain centralized machine rooms, limiting addressable household penetration.
Strategic Opportunities
- India's BIS certification expansion:Mandatory safety testing for electronic goods with heating functions creates first-mover advantage for pre-certified exporters before enforcement hardens.
- RV and marine aftermarket channels:12V DC-native mini washers bypass inverter conversion losses, aligning with lithium battery system upgrades in recreational vehicle retrofits.
- Wi-Fi module integration with utility demand-response:Connected-home synchronization with time-of-use electricity pricing opens subscription revenue streams for cycle-optimization services.
Industry Challenges
- Firmware talent scarcity:Variable-frequency drive control algorithms require embedded systems expertise concentrated in automotive and industrial automation sectors, compressing hiring pipelines.
- Acoustic engineering bottlenecks:Spin speeds above 1000 RPM in sub-6 kg drums generate harmonic resonance requiring simulation-driven design cycles that extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Washing Machine Market |
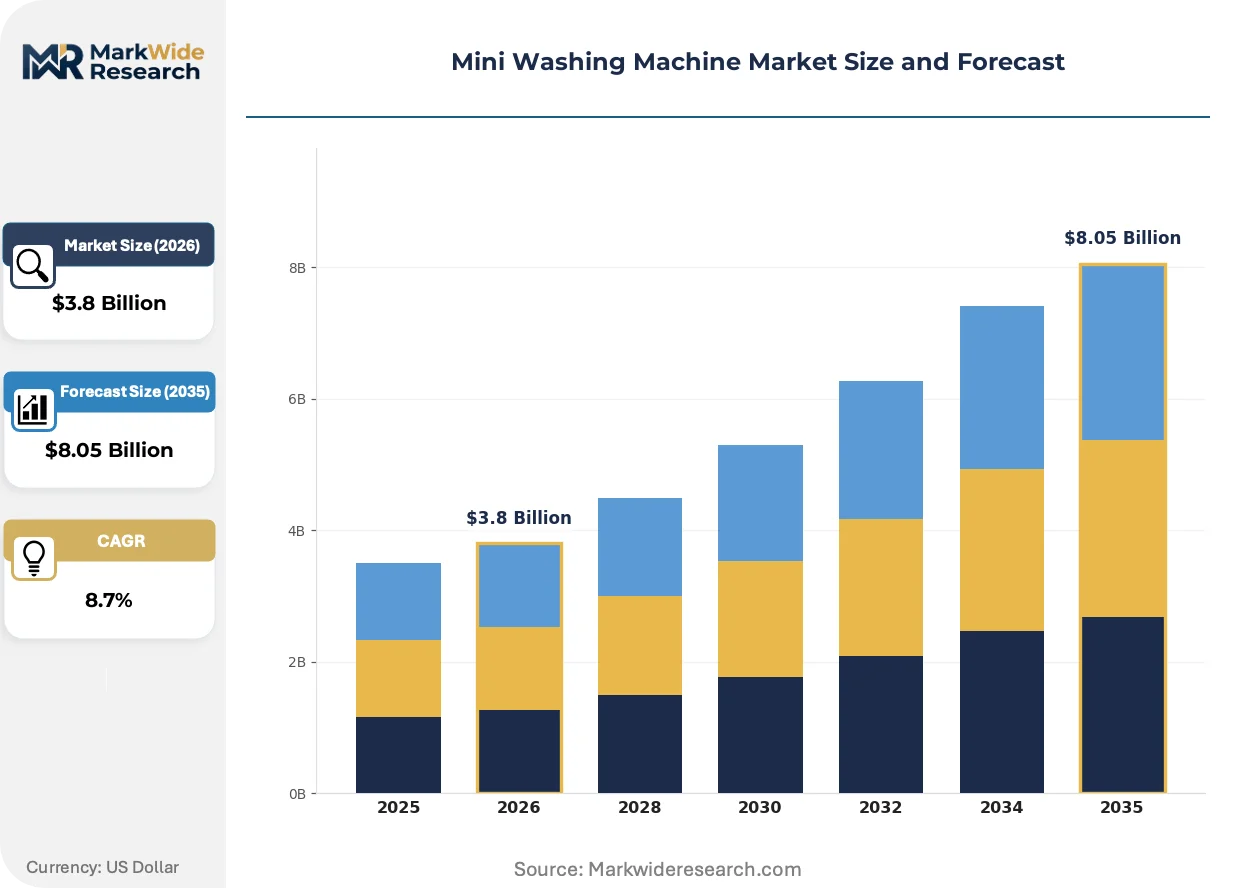
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Semi-Automatic, Fully Automatic, Compact End User: Households, Dormitories, RV Owners, Laundromats Capacity: 1-2 kg, 3-4 kg, 5-6 kg, 7-8 kg Power Rating: 500 W, 700 W, 800 W, 1000 W |
| Companies Covered | Electrolux, Midea, LG, COMFEE, Costway, Samsung, Miele, Giantex, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Washing Machine Market Shifts & Advancements
Three forces are restructuring competitive advantage in mini washing machines: motor electrification, regulatory fragmentation, and channel disintermediation toward direct-to-renter platforms.
Brushless DC motor platforms with integrated variable-frequency drives are rendering obsolete fixed-speed induction motors across the 3-4 kg capacity band. Dormitory housing operators and RV fleet managers are specifying inverter-equipped units for 2025 procurement cycles. This technology shift is compressing warranty cost structures and enabling spin-speed tiering as a price segmentation lever.
The EU Ecodesign Directive's 2025 efficiency tiers are forcing redesign of heating element architectures and drain pump duty cycles. Manufacturers serving European markets must retest entire product families under revised load profiles. Compact models with integrated drying functions face the steepest compliance cost escalation due to combined wash-dry energy budgets.
Apartment renters increasingly source appliances through property management procurement portals rather than retail channels. This disintermediation concentrates buying power among multi-unit housing operators who negotiate bulk service contracts bundling installation, maintenance, and end-of-life removal. The shift is most advanced in Australia's build-to-rent developments and US single-family rental aggregators.
Mini Washing Machine Market Segmentation
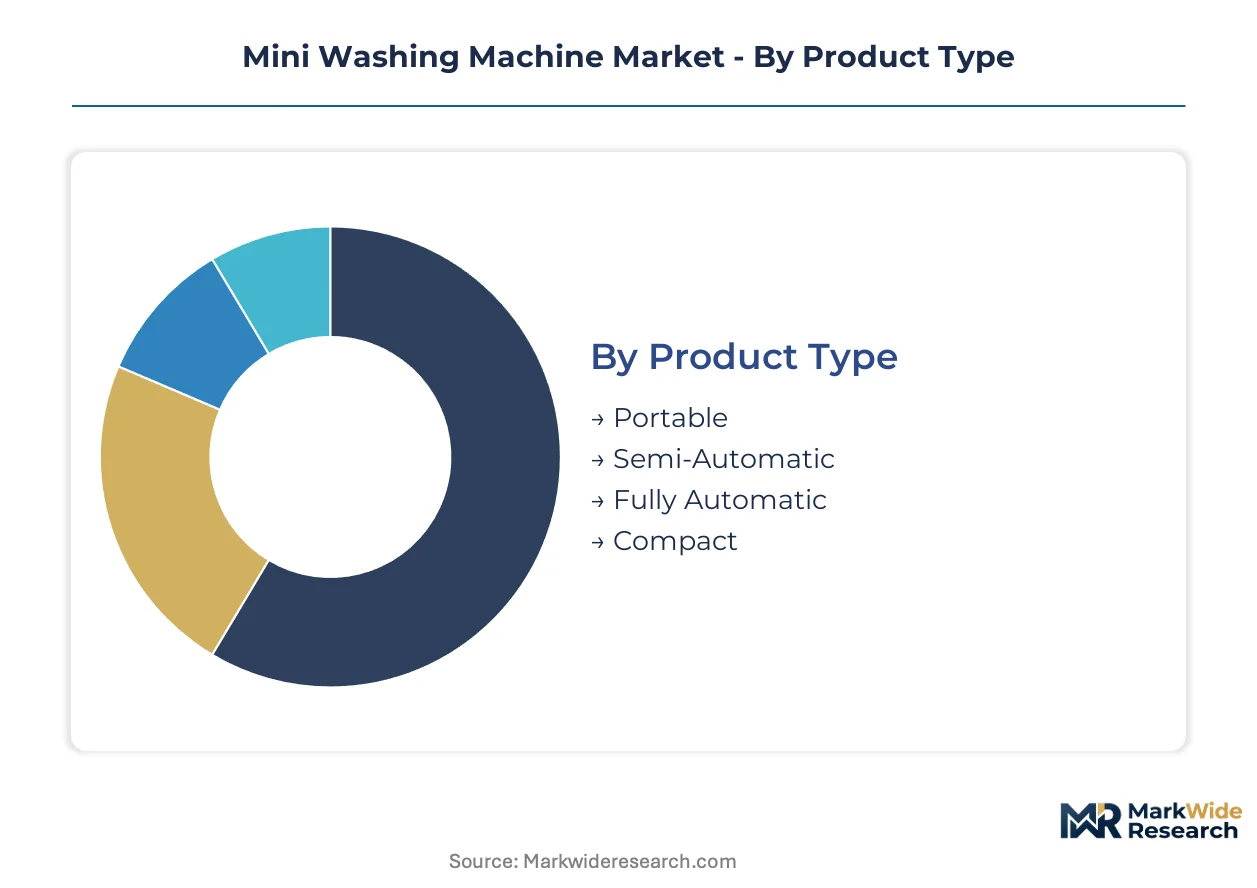
Mini washing machine manufacturers face divergent service obligations across product architectures. Portable units require minimal installation support while fully automatic systems demand ongoing maintenance contracts. Segmentation clarity enables targeted warranty structures and spare parts forecasting.
Product Type:
After-sales-service intensity varies sharply across mechanical complexity tiers, with electronic control modules driving multi-year service revenue in premium configurations.
- Fully Automatic:Integrated wash-dry cycles with programmable microcontrollers and sensor-driven load balancing command the highest service attachment rates. China's tier-two city rental complexes specify these units for tenant retention programs despite elevated capital outlay.
- Portable:Gravity-drain mechanisms and manual water filling eliminate electronic failure modes entirely. Demand concentrates among transient RV owners and seasonal dormitory residents who prioritize relocation flexibility over cycle sophistication.
- Semi-Automatic:Dual-tub designs separate washing and spin functions through mechanical timers requiring periodic replacement. India's BIS certification mandates for heating elements add compliance layers to export-bound production.
- Compact:Fixed-installation units under 50 cm width integrate direct-drive drums with reduced vibration profiles. European build-to-rent developers specify these for space-optimized apartment conversions.
Fully automatic holds the largest share; momentum sits with portable configurations.
End User:
Procurement authority is shifting from individual consumers toward institutional buyers with consolidated maintenance contracts and standardized replacement cycles.
- Households:Urban micro-living adopters in China's tier-two cities and Australia's build-to-rent developments drive replacement demand. EPA ENERGY STAR efficiency thresholds pull forward upgrade cycles among compliance-conscious property managers.
- Dormitories:University housing operators negotiate fleet-level service agreements bundling installation and preventive maintenance. 3-4 kg capacity bands dominate procurement specifications for load utility against shipping cube efficiency.
- RV Owners:12V DC-native configurations bypass inverter conversion losses for lithium battery system compatibility. Marine aftermarket channels command premium positioning through corrosion-resistant chassis designs.
- Laundromats:Commercial-duty cycles with reinforced drum bearings and coin-op payment modules require specialized field service networks. EU Ecodesign Directive efficiency tiers force heating element redesigns for European market entry.
Households represent the dominant volume base; dormitories are expanding most quickly through institutional procurement consolidation.
Capacity:
Shipping economics and installation constraints create distinct margin profiles across load-size bands, with mid-range capacities optimizing logistics density against functional utility.
- 3-4 kg:The commercial sweet spot balances single-person laundry loads against e-commerce packaging efficiency. Direct-drive drum systems at this scale minimize mechanical complexity while enabling bedroom-adjacent deployment.
- 1-2 kg:Ultracompact formats target specialized applications including baby garment care and delicate item separation. China's GB standards for appliance safety impose testing burdens disproportionate to unit economics.
- 5-6 kg:Small-family configurations approach standard washing machine territory while retaining space-constrained installation compatibility. Spin speeds above 1000 RPM in this band generate acoustic engineering challenges.
- 7-8 kg:Maximum load formats for mini classification appeal to multi-occupant households without built-in appliance infrastructure. Neodymium magnet requirements for inverter motors expose BOM costs to Chinese export quota volatility.
3-4 kg configurations command the largest installed base; 1-2 kg formats are gaining share fastest among niche application specialists.
Power Rating:
Electrical infrastructure limitations in dense urban housing and off-grid installations constrain feasible power envelopes, with inverter motor technology compressing consumption curves across ratings.
- 500 W:Gravity-drain portable units operate on standard residential circuits without dedicated grounding. India's BIS mandatory certification for electronic goods with heating functions creates entry barriers for non-compliant exporters.
- 700 W:Semi-automatic twin-tub designs achieve functional parity with reduced heating element duty cycles. EU Ecodesign Directive 2025 efficiency tiers force pump architecture redesigns in this band.
- 800 W:Fully automatic entry points balance cycle completion time against utility rate optimization. Wi-Fi module integration enables demand-response synchronization with time-of-use pricing signals.
- 1000 W:Premium rapid-wash and integrated drying functions require dedicated circuit installation. Firmware talent scarcity for variable-frequency drive algorithms compresses hiring pipelines for control system development.
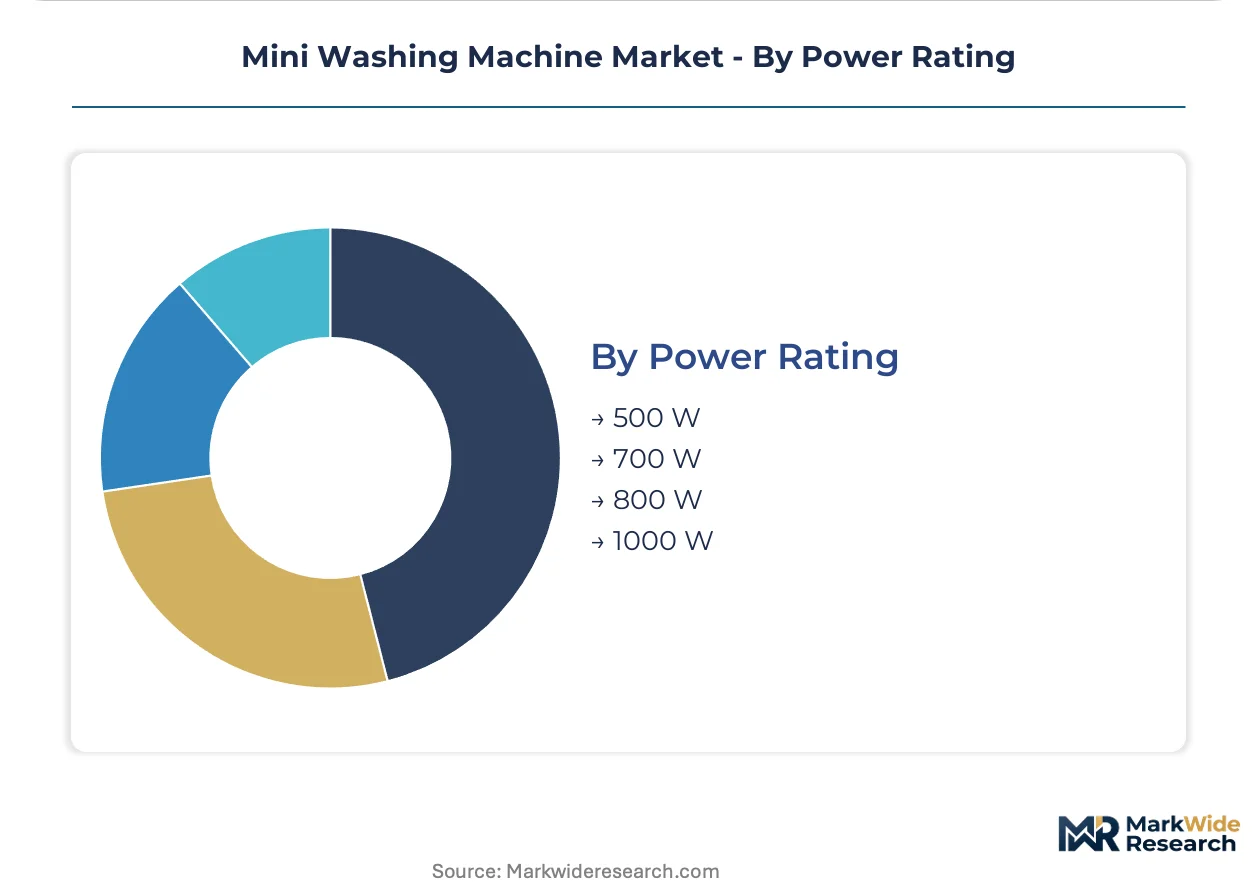
800 W ratings hold the largest share; 500 W configurations are climbing the fastest through off-grid and RV channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters supply mini washing machines to rental housing operators across Australia, Europe, and North America, with Guangdong-based exporters dominating cross-border e-commerce channels into dormitory and RV aftermarket segments.
China
Young professionals in tier-two cities occupy sub-40 square meter apartments lacking built-in laundry infrastructure, creating installed-base gaps for compact appliances. GB standards from the national quality administration impose safety and water efficiency testing requirements that fragment compliance for export-bound production. Guangdong province anchors manufacturing concentration, with vertical integration across compressor and motor assembly lines serving both domestic and overseas demand.
United States
Single-family rental aggregators and build-to-rent developers consolidate procurement through property management portals rather than retail channels. EPA ENERGY STAR water consumption thresholds for compact washers tightened in 2024, pulling forward replacement cycles among compliance-conscious portfolios. The Southeast and Southwest regions concentrate multi-unit housing construction where space-constrained laundry solutions address floor-plan limitations.
Germany
Apartment complexes in dense urban centers maintain centralized machine rooms that limit household-level penetration, though build-to-renovation projects specify compact units for space-optimized conversions. EU Ecodesign Directive 2025 efficiency tiers force heating element redesigns and retesting under revised load profiles. North Rhine-Westphalia and Bavaria host precision engineering clusters supplying direct-drive drum systems to European appliance assemblers.
Australia
Build-to-rent developments advance fastest among institutional procurement consolidators, bundling installation, maintenance, and end-of-life removal into multi-year service contracts. State-level water efficiency labeling schemes align with federal equipment standards for rental property certification. New South Wales and Victoria concentrate urban micro-living adoption where sub-50 square meter apartments lack traditional laundry infrastructure.
India
BIS mandatory certification for electronic goods with heating functions creates entry barriers for non-compliant exporters while rewarding pre-certified market entrants before enforcement hardens. Semi-automatic twin-tub designs dominate price-sensitive segments in urban rental markets. Maharashtra and Gujarat house assembly operations serving domestic distribution through organized retail and e-commerce channels.
Mini Washing Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures, with consolidated buying power among property management platforms compressing pricing for standardized specifications while premium tiers retain differentiation through connected-home integration and extended warranty programs. The vendor base organizes into three archetypes: diversified appliance conglomerates with captive component production, specialist compact appliance fabricators serving RV and marine aftermarket channels, and private-label assemblers leveraging Guangdong manufacturing access for e-commerce distribution. Dominant competitive moves include backward integration into motor and control system production, plus strategic partnerships with lithium battery system suppliers for 12V DC-native product development.
Among diversified appliance conglomerates, Electrolux and Midea exemplify scale-driven archetypes with manufacturing footprints spanning multiple geographies, while Bosch GmbH anchors precision-engineering positioning in European markets. LG Electronics Inc. and Samsung Electronics Co., Ltd. occupy positions defined by connected-home ecosystem integration and Wi-Fi module deployment for utility demand-response synchronization. Specialist players including COMFEE and Giantex represent compact-appliance-focused fabricators targeting price-sensitive transient consumers through direct-to-consumer channels.
| Leading Market Players |
|---|
| Electrolux |
| Midea |
| LG |
| COMFEE |
| Costway |
| Samsung |
| Miele |
| Giantex |
| Bosch |
| Others |
Supply & Pricing Matrix
Guangdong province's concentration of compressor and motor assembly lines concentrates upstream margin capture among Chinese component suppliers, forcing downstream brand owners to compete through firmware differentiation and service bundling rather than hardware economics. This geographic lock on electromechanical inputs reshapes where pricing power accumulates across the value chain.
Pricing Analysis
Inverter-motor-equipped units command substantial premiums over fixed-speed induction models, while next-generation Wi-Fi-integrated configurations target subscription-revenue positioning. Three-tier pricing structure across premium, standard, and economy levels separates connected-home models with demand-response capability from basic automatic cycles and gravity-drain portables. Cost compression in portable segments is intensifying because cross-border e-commerce sellers bypass traditional distributor markups. RV fleet operators and dormitory housing managers exhibit lowest price sensitivity due to total-cost-of-ownership procurement frameworks, while individual transient renters in China's tier-two cities drive economy-tier volume.
Supply Chain Analysis
Neodymium magnet feedstock draws from Chinese rare-earth processing facilities, with secondary sourcing from Vietnamese and Australian mining operations. Plastic resin housings and stamped steel drums rest on petrochemical and metallurgical inputs concentrated in East Asian manufacturing corridors. Single-source vulnerability in motor-control chip supply exposes assembly schedules to semiconductor foundry allocation decisions. Distribution runs through property management procurement portals and direct-to-consumer e-commerce channels, bypassing traditional appliance retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Property management platform consolidation is shifting procurement authority toward institutional buyers with standardized specifications and multi-year service contracts, compressing pricing leverage for undifferentiated manufacturers.
For Market Incumbents: Build firmware moats around variable-frequency drive algorithms to defend against commodity motor suppliers entering downstream assembly. Deepen backward integration into power electronics production to secure component allocation during semiconductor supply constraints. Electrolux and Midea already anchor captive compressor manufacturing in Guangdong, but control system development remains outsourced to automotive-tier suppliers. For New Entrants and Emerging Players: Establish a beachhead in 12V DC-native configurations for lithium battery RV retrofits before incumbent appliance brands reconfigure product architectures. India's BIS certification expansion for heating-element-equipped electronics creates regulatory runway for pre-certified exporters ahead of enforcement hardening. Direct-to-renter platforms serving Australia's build-to-rent developments offer channel access without retail slotting fee burdens. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed compact appliance specialists lacking connected-home integration capabilities but holding established marine and RV aftermarket distribution. Long-term viability hinges on firmware talent acquisition and utility partnership structures for demand-response revenue streams. Watch for EPA ENERGY STAR threshold revisions as inflection indicators pulling forward replacement demand among compliance-focused rental portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Motor Platform Standardization | Variable-frequency drive adoption renders fixed-speed architectures obsolete across 3-4 kg capacity bands. |
| Wi-Fi Module Integration for Demand-Response | Utility rate synchronization opens subscription revenue streams through cycle-optimization services. |
| 12V DC-Native Product Development | Lithium battery compatibility captures RV and marine aftermarket channels with premium positioning. |
| BIS Certification Pre-Positioning | India's mandatory safety testing for heating functions rewards compliant exporters before enforcement hardens. |
| Property Management Portal Partnerships | Build-to-rent procurement consolidation concentrates volume among institutional buyers with service bundling requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and appliance manufacturer technical documentation. Interviews with product development executives at diversified appliance conglomerates, procurement managers at university housing operators, and aftermarket distributors serving RV fleet owners informed demand-side validation. EPA ENERGY STAR certification databases, EU Ecodesign Directive implementation guidance, and China's GB standards publications provided regulatory boundary conditions. Bottom-up unit economics modeling triangulated against top-down market sizing from production capacity disclosures.
Forecast inputs span product type evolution, power rating migration, and regional regulatory enforcement timelines across the analysis window. Segmentation dimensions include capacity band, automation level, end-user procurement authority, and geographic certification cluster. CAGRs derive from installed-base replacement cycle analysis and new household formation patterns in space-constrained urban housing. Inverter motor adoption curves and Wi-Fi module penetration rates inform technology-transition timing.
Stress conditions across neodymium export quota volatility, semiconductor foundry allocation constraints, and EPA efficiency threshold revision timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding rental housing construction rates and regulatory harmonization failures. Cross-checking against customs shipment data and property management procurement survey benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
North America Compact Dishwasher Market
Appliances
Glass Ceramic Cooktop Market
Appliances
Household Beauty Appliances Market
Appliances
Microwave Market
Appliances
Electric Ranges Market
Appliances
Europe Tumble Dryers Market
Appliances
Under Counter Dishwasher Market
Appliances
Mexico Washing Machine Market
Appliances
Europe Microwave Oven Market
Appliances
Electrical Appliances Plastics Market
Appliances
Water Dispenser Market
Appliances
Fully Integrated Dishwasher Market
Appliances
Personal Care Appliances Market
Appliances
APAC White Goods Market
Appliances
US Portable Washing Machines Market
Appliances
Portable Mini Fridge Market