
 Hair Removal Appliances Market | 2026-2036
Hair Removal Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Removal Appliances Market Insights
The gap between premium and commodity tiers is shifting from price alone to wavelength precision, cooling systems, and clinical-grade safety certifications. Braun sustains its edge through German-engineered sensor technology and dermatological partnerships. Philips dominates the mass-market channel with broad retail distribution and accessible price positioning. Ulike anchors the direct-to-consumer premium segment with sapphire cooling technology and influencer-driven marketing.
Hair removal appliances encompass electrically powered devices designed for temporary or permanent hair reduction through optical, thermal, or mechanical means, typically operating at wavelengths between 600 and 1200 nanometers for light-based systems and incorporating skin tone sensors to prevent burns. These appliances serve both aesthetic consumer markets and professional dermatology clinics seeking repeatable, non-invasive alternatives to waxing or shaving. Laser devices command the highest margin pools due to semiconductor and optical component costs, while IPL technology leads in unit volume through lower manufacturing complexity and broader skin-type compatibility. The salon and clinic end-user segment retains premium pricing power despite home-user growth accelerating through e-commerce subscription models.
FDA clearance requirements for light-based devices under 510(k) pathways and CE marking under the EU Medical Device Regulation shape product development timelines and market access costs for manufacturers. REACH compliance in Europe and GB standards in China further constrain material choices for housings and electrical components. Stakeholders must monitor evolving medical device reclassification proposals that could shift at-home appliances into stricter regulatory categories.
Market Dynamics
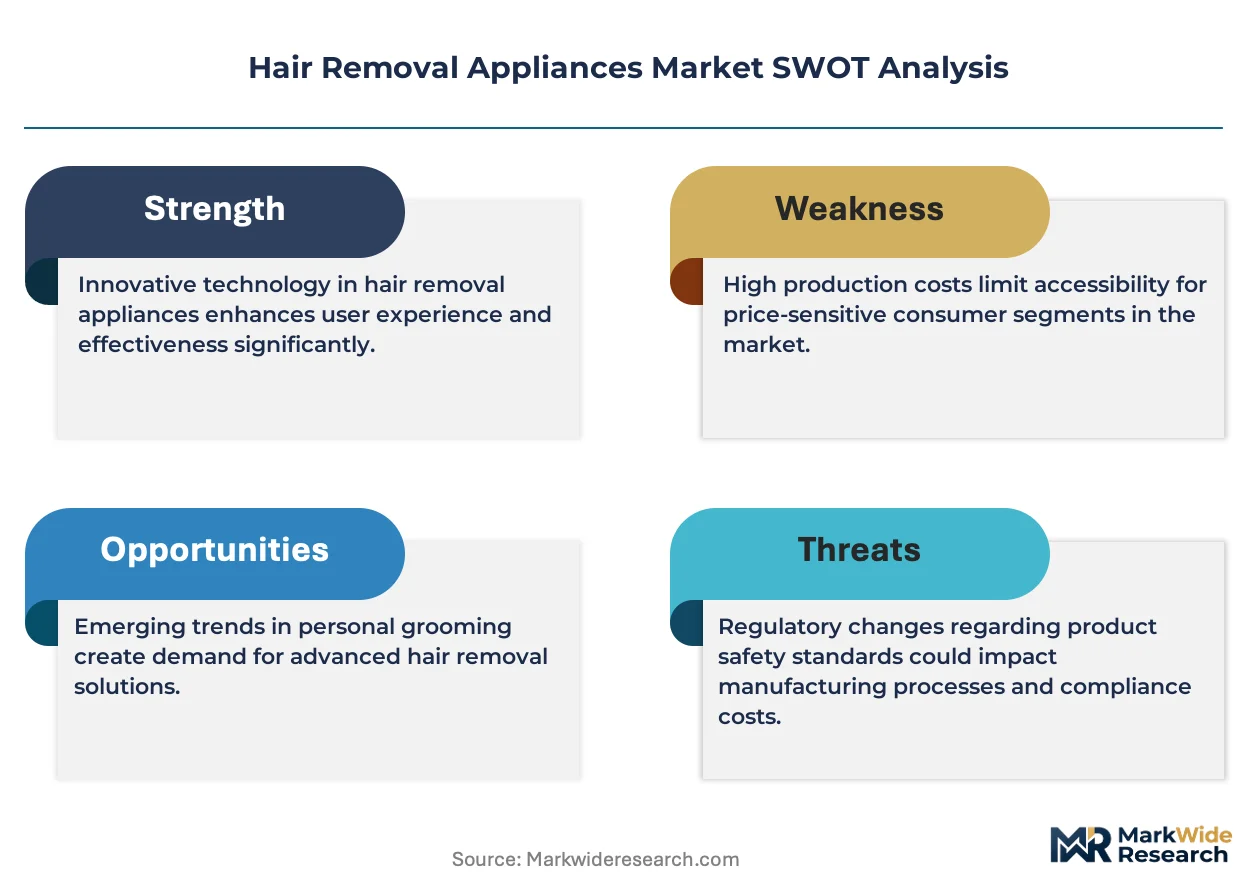
Home-use IPL devices are compressing professional clinic margins as wavelength-stable semiconductor arrays reach consumer price points, while FDA 510(k) clearance timelines extend development cycles for new entrants.
Growth Catalysts
- CE Marking under EU MDR:Stricter clinical evidence requirements for light-based devices are filtering out low-quality competitors and elevating certified manufacturers' pricing power across European markets.
- Sapphire cooling systems:Contact-cooling technology reduces epidermal heating risk, expanding treatable skin tone ranges and unlocking previously excluded consumer segments.
- China's GB standards compliance:Harmonized electrical safety and optical output regulations accelerate domestic manufacturing scale while raising export readiness for Chinese OEMs.
Market Restraints
- GaAs semiconductor wafer supply:Laser diode fabrication depends on concentrated gallium arsenide substrate production, creating input cost volatility when foundry capacity tightens.
- Technical limitation on Fitzpatrick Type VI skin:Melanin absorption at 755-1064nm wavelengths elevates burn risk, excluding the deepest skin tones from most home-use device protocols.
- REACH substance restrictions:ECHA-listed phthalates and flame retardants in polymer housings force reformulation of legacy product lines, extending redesign timelines.
Strategic Opportunities
- India's underpenetrated metro markets:Rising disposable income in Mumbai, Delhi, and Bangalore creates first-mover advantage for brands establishing dermatologist partnerships and clinic-channel presence.
- Subscription-based consumable models:Cartridge-replacement programs for IPL devices generate recurring revenue streams and reduce customer acquisition costs through locked-in user bases.
- AI-powered skin tone detection:Machine vision integration with automatic fluence adjustment bridges the safety gap between professional and at-home treatment outcomes.
Industry Challenges
- Biomedical optics engineering talent:Shortage of specialists combining laser physics with dermatological safety protocols extends R&D timelines for next-generation devices.
- FDA 510(k) predicate device navigation:Substantial equivalence determinations for novel wavelength combinations require extensive clinical documentation, delaying market entry by 18-24 months.
- Optical component traceability:Multi-tier supplier networks for lenses, filters, and fiber couplers complicate quality assurance under ISO 13485 medical device standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Removal Appliances Market |
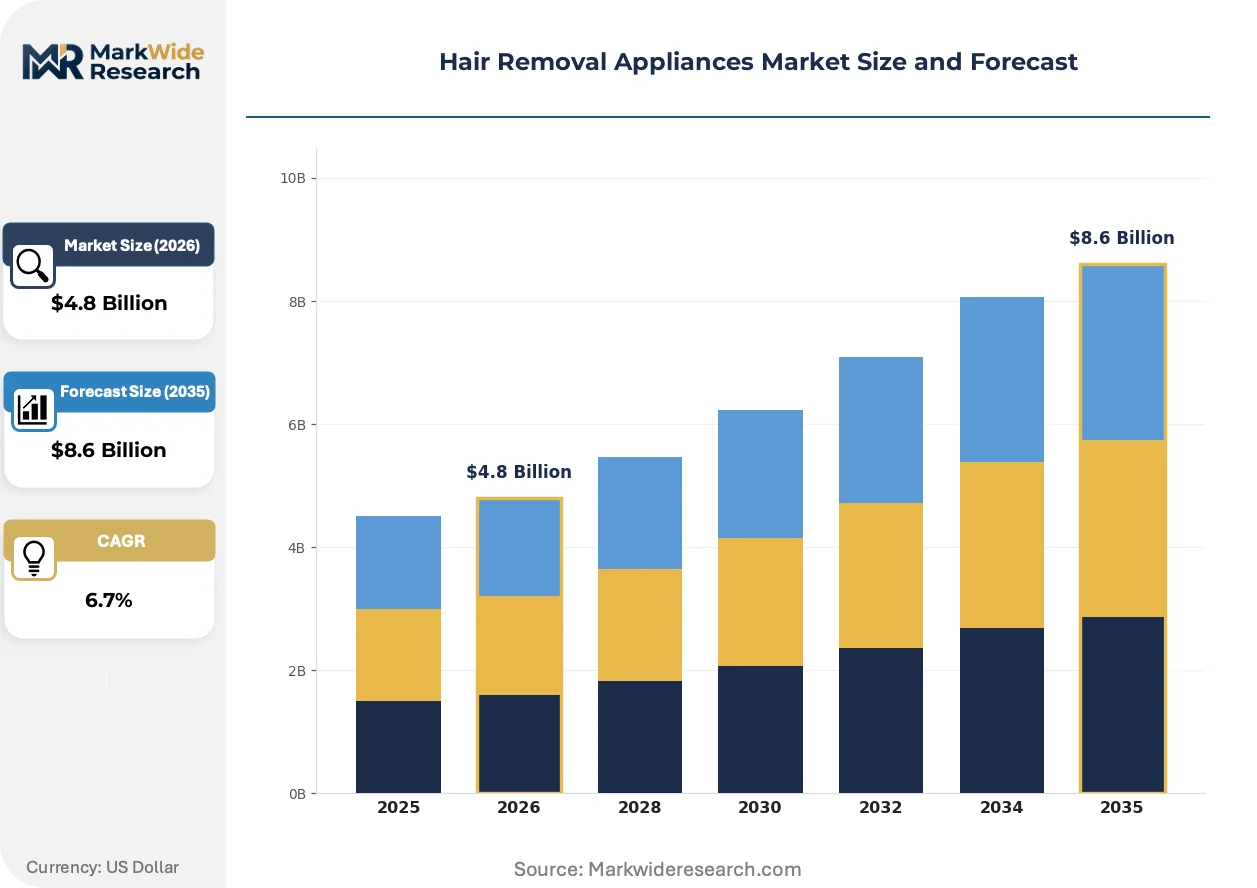
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Epilators, Waxing Kits, Shavers Technology: IPL, LED, Electrolysis, Thermolysis End User: Home Users, Salons, Clinics, Spa Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | RoseSkinCo, Epilaser, Braun, Silk'n, SmoothSkin, Philips, Innza, Michael Todd Beauty, Ulike, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Removal Appliances Market Trends and Innovations
Device intelligence and treatment personalization are compressing the performance gap between salon-grade systems and consumer appliances, while regulatory convergence across major markets is reshaping competitive entry barriers.
Multi-wavelength platform technology is consolidating previously separate laser and IPL modalities into single handheld units. Home users in Germany and the United States are adopting these hybrid devices at accelerating rates. Market structure is consolidating around manufacturers capable of integrating 755nm, 808nm, and 1064nm outputs with real-time skin feedback loops.
EU Medical Device Regulation reclassification proposals are tightening clinical evidence requirements for at-home light-based systems. Manufacturers face expanded biocompatibility testing and post-market surveillance obligations. The direct-to-consumer segment is responding by pre-submission engagement with notified bodies and earlier-stage clinical trial investment.
After-sales service unbundling is fragmenting traditional warranty models into subscription-based maintenance tiers. E-commerce channels in China and South Korea are displacing retail-centric support structures with video-guided troubleshooting and remote diagnostic apps. Dermatology clinics in Japan remain the exception, where bundled service contracts retain preference among professional buyers.
Hair Removal Appliances Market Segmentation
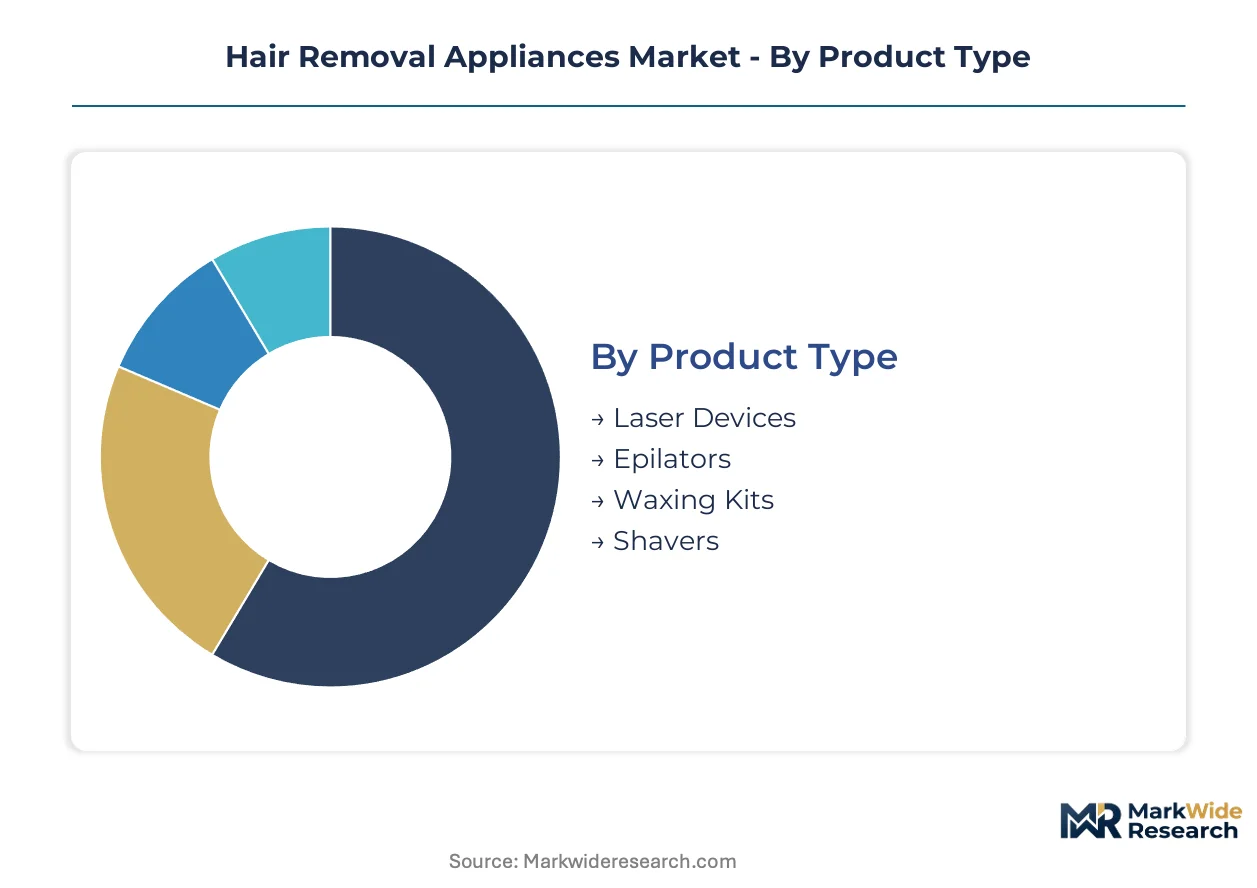
Hair removal appliances fragment across four distinct axes, each revealing divergent margin structures and regulatory exposure. Technology sophistication and end-use setting determine pricing power more than brand equity alone.
Product Type:
Wavelength precision and energy delivery mechanisms create four distinct hardware categories with fundamentally different cost structures.
- Laser Devices:Semiconductor diode arrays operating at 755-1064nm wavelengths deliver permanent hair reduction through selective photothermolysis. FDA 510(k) clearance requirements in the United States and CE marking under EU MDR constrain new entrants to documented clinical evidence.
- Epilators:Mechanical tweezing systems with rotating discs or plates remove hair at the root through traction force. German and Japanese manufacturers dominate precision motor engineering for these devices.
- Waxing Kits:Thermal or ready-to-use depilatory systems combine natural or synthetic resins with fabric strips for root-level extraction.
- Shavers:Rotary or foil-based electric cutting systems trim hair at skin level without root disruption, serving daily grooming routines.
Shavers lead on scale; laser devices lead on momentum.
Technology:
Energy delivery modalities separate professional-grade outcomes from consumer-accessible maintenance.
- IPL:Broadband flash lamps emitting 500-1200nm wavelengths target melanin with lower per-pulse energy than lasers, enabling safer home-use protocols. China's GB standards compliance has accelerated domestic manufacturing scale for export-ready OEMs.
- LED:Narrow-spectrum light-emitting diodes operate at insufficient energy densities for permanent reduction, serving primarily as adjunct skin conditioning or temporary hair retardation.
- Electrolysis:Galvanic current destroys individual follicles through chemical decomposition, remaining the only FDA-recognized permanent method for all hair colors including white and gray.
- Thermolysis:High-frequency alternating current generates localized heat for follicular destruction, preferred in professional settings for precision work on small treatment areas.
IPL dominates unit economics; electrolysis retains clinical authority.
End User:
Purchase setting determines safety certification requirements and service bundling expectations.
- Home Users:Consumers operating devices without professional supervision drive demand for skin-tone sensors, contact cooling, and simplified protocols. Sapphire cooling technology from direct-to-consumer brands has expanded treatable skin tone ranges.
- Salons:Licensed aestheticians performing non-medical hair removal require durable equipment with replaceable consumables and vendor training programs.
- Clinics:Physician-supervised or medical spa environments utilize higher-fluence systems with documented clinical outcomes for liability protection.
- Spa:Wellness-oriented hospitality venues prioritize treatment experience and ambient design over maximum efficacy specifications.
Home users expand most quickly; clinics retain pricing power.
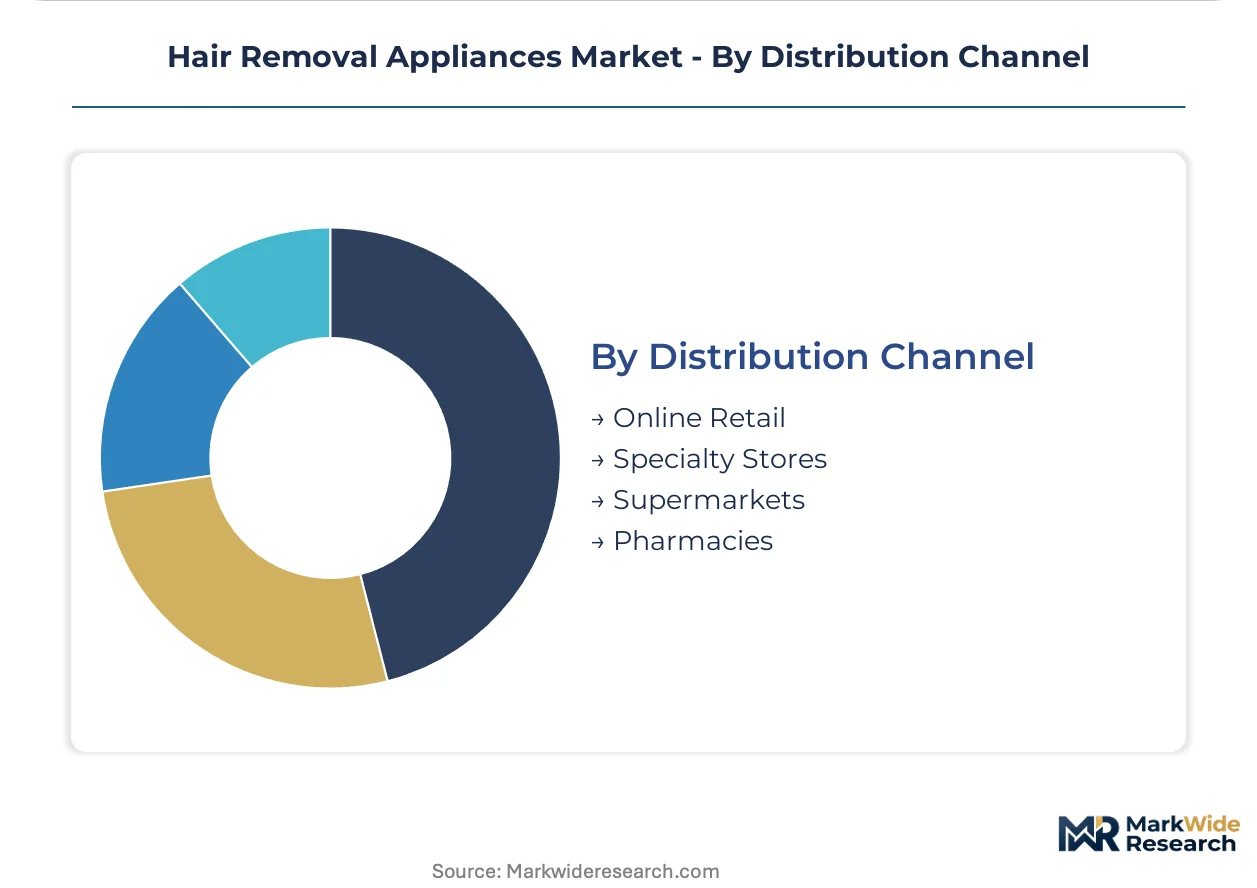
Distribution Channel:
Channel selection shapes warranty terms, after-sales support architecture, and customer acquisition economics.
- Online Retail:Direct-to-consumer platforms and marketplace listings enable subscription-based cartridge replenishment and video-guided troubleshooting. South Korean and Chinese e-commerce ecosystems have displaced traditional retail support structures.
- Specialty Stores:Beauty-focused retailers provide hands-on demonstration and immediate product comparison, particularly important for first-time IPL purchasers assessing device ergonomics.
- Supermarkets:Mass-market placement drives impulse purchases of shavers and disposable waxing systems with lower consideration cycles.
- Pharmacies:Healthcare-adjacent positioning supports medical-grade device credibility and reimbursement documentation in selective markets.
Online retail climbs the fastest; specialty stores anchor premium conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumers prioritize long-term hair reduction solutions, while German buyers emphasize engineering precision and dermatological safety certifications. This divergence shapes distinct regulatory and commercial strategies across major markets.
United States
FDA 510(k) clearance timelines for light-based devices extend development cycles, yet home-use IPL adoption accelerates through e-commerce subscription models. The agency's predicate device navigation requirements demand extensive clinical documentation. California and New York metro areas concentrate direct-to-consumer brand headquarters and influencer marketing infrastructure.
Germany
CE marking under EU MDR filters low-quality competitors and elevates certified manufacturers' pricing power. REACH substance restrictions force reformulation of legacy polymer housings. Bavaria and Baden-Württemberg host precision motor engineering clusters serving epilator manufacturers.
China
GB standards compliance accelerates domestic manufacturing scale while raising export readiness for OEMs. NMPA harmonization with international optical output regulations supports outbound market access. Yangtze River Delta and Pearl River Delta production hubs supply wavelength-stable semiconductor arrays reaching consumer price points.
India
Rising disposable income in Mumbai, Delhi, and Bangalore creates first-mover advantage for brands establishing dermatologist partnerships. CDSCO medical device classification frameworks remain under development for light-based systems. Maharashtra and Karnataka concentrate private clinic expansion and aesthetic medicine training centers.
South Korea
E-commerce ecosystems displace traditional retail support structures with video-guided troubleshooting and remote diagnostic apps. MFDS regulates at-home devices under cosmetic appliance frameworks rather than medical device categories. Seoul Capital Area anchors subscription-based consumable model innovation and AI-powered skin tone detection development.
Hair Removal Appliances Market Competitive Landscape
Top-tier vendors anchor premium positioning through sapphire cooling technology and dermatological partnerships, while mid-tier competitors compete on manufacturing scale and retail distribution breadth. The vendor base stratifies across German-engineered sensor specialists, mass-market channel dominators, and direct-to-consumer premium challengers. Three archetypes prevail: precision engineering houses, volume-scale consumer electronics firms, and influencer-driven digital-native brands. Strategic moves concentrate on M&A for optical component capabilities and geographic expansion into underpenetrated metro markets.
Among the precision engineering tier, Braun exemplifies sensor-integrated safety systems developed through dermatological collaboration. Philips occupies a position within mass-market channel architecture, leveraging broad retail distribution and accessible price positioning. Ulike anchors the direct-to-consumer premium segment, representing sapphire cooling technology deployment and social media-driven customer acquisition. These three archetypes illustrate divergent paths to margin defense: engineering differentiation, scale economies, and digital-native brand velocity.
| Leading Market Players |
|---|
| RoseSkinCo |
| Epilaser |
| Braun |
| Silk'n |
| SmoothSkin |
| Philips |
| Innza |
| Michael Todd Beauty |
| Ulike |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) clearance timelines for new wavelength combinations are forcing manufacturers to front-load clinical documentation costs, which compresses margins for mid-tier players and pushes supply chains toward vertically integrated semiconductor fabrication partners in China and Germany.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for IPL flash lamp assemblies, enabling domestic OEMs to undercut European competitors on bill-of-materials while maintaining GB standards compliance. Three-tier pricing structure across premium, standard, and economy levels separates sapphire-cooled laser devices with dermatological certifications from basic IPL units and entry-level epilators. Price differentiation hinges on FDA clearance tier and cooling system sophistication. Cost compression in the standard tier is intensifying because wavelength-stable semiconductor arrays have reached consumer price points. Home users exhibit highest price sensitivity; dermatology clinics demonstrate lowest sensitivity due to liability-driven procurement protocols.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns for finished-device fulfillment, with cross-border e-commerce platforms increasingly bypassing traditional wholesale tiers. Manufacturing concentration centers on China for IPL assemblies, Germany for precision epilator motors, and Japan for optical lens grinding. Raw material dependencies draw from gallium arsenide wafers for laser diodes, sapphire substrates for cooling windows, and medical-grade polymers compliant with REACH substance restrictions. Single-source vulnerability pervades GaAs semiconductor foundry capacity. Distribution runs through direct-to-consumer platforms for premium devices and mass retail for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as recurring cartridge-replacement revenue locks in user bases and reduces customer acquisition costs for established brands.
For Market Incumbents: Deepen dermatological partnership networks to defend premium positioning against direct-to-consumer challengers leveraging influencer marketing velocity. Invest in backward integration into sapphire cooling component fabrication to secure supply continuity and margin protection. Prioritize pre-submission engagement with FDA and notified bodies to compress 510(k) clearance timelines for next-generation multi-wavelength platforms. For New Entrants and Emerging Players: Dermatologist partnerships in India's Maharashtra and Karnataka clusters offer the most penetrable white-space entry point, as CDSCO classification frameworks remain under development and private clinic expansion accelerates. AI-powered skin tone detection represents a differentiable technology wedge for bridging professional-at-home safety gaps. Pursue clinic-channel presence before mass retail to establish clinical credibility and command premium pricing. For Investors and Strategic Acquirers: Asymmetric upside sits with precision optics engineering houses possessing captive semiconductor packaging capabilities and existing FDA predicate device portfolios. Long-term viability favors manufacturers with demonstrated 510(k) navigation expertise and dermatologist endorsement networks. Watch FDA medical device reclassification proposals as the critical inflection signal for at-home appliance regulatory burden expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements filter low-quality competitors and elevate certified manufacturers' pricing power across European markets. |
| Backward Integration | In-house production of wavelength-stable semiconductor arrays reduces GaAs wafer supply volatility and protects margin pools for laser device tiers. |
| Dermatologist Partnership | Clinical endorsement networks differentiate premium devices from mass-market alternatives and support reimbursement documentation in selective markets. |
| Direct-to-Consumer Launch | Influencer-driven customer acquisition and subscription-based cartridge replenishment compress traditional retail support cost structures. |
| AI Skin Tone Detection | Machine vision integration with automatic fluence adjustment bridges safety gaps between professional clinic and at-home treatment outcomes. |
Research Methodology
Coverage spans the United States, Germany, China, India, and South Korea, with primary inputs from each market's stakeholder ecosystem. Primary interviews engaged biomedical optics engineers, dermatology clinic procurement managers, regulatory affairs specialists at device manufacturers, and e-commerce platform category directors. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, NMPA registration databases, and customs trade records for optical component flows. Bottom-up unit economics modeling triangulated against top-down market sizing from national medical device registries.
Granularity-level modeling tracked product type, technology modality, end-user setting, and distribution channel across the analysis window, with wavelength specification and cooling system architecture as industry-specific dimensions. CAGRs were derived from installed base growth, replacement cycle compression, and premium-tier mix shift assumptions. Forecast inputs incorporated semiconductor foundry capacity expansion schedules, regulatory reclassification proposal timelines, and e-commerce penetration curves by geography.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA medical device reclassification decisions, GaAs wafer supply disruptions, and AI-powered competitive entry. Outputs reflect documented assumptions around regulatory pathway stability and consumer willingness-to-pay for clinical-grade safety certifications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Industrial Gas Stove Market
Appliances
Japan Massage Equipment Market
Appliances
Triple Barrel Waver Market
Appliances
Household Beauty Appliances Market
Appliances
Qatar Microwave Ovens Market
Appliances
Bahrain Microwave Ovens Market
Appliances
Residential Space Heater Market
Appliances
Israel Laundry Appliances Market
Appliances
Body Dryer Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
Smart Refrigerator Market
Appliances
Electric Iron Market
Appliances
North America Compact Dishwasher Market
Appliances
UAE Gas Hobs Market
Appliances
Refrigerated Cabinet Market
Appliances
UK Residential Vacuum Cleaner Market