
 Washing Appliances Market | 2026-2036
Washing Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Washing Appliances Market Analysis
Appliance technician shortages across developed economies is unwinding service-network capacity and pushing manufacturers toward predictive-diagnostics platforms. Whirlpool Corporation leverages its North American installed-base data to preempt component failures before dispatch. LG Electronics sustains competitive pressure through in-house production of direct-drive motor systems. Samsung Electronics anchors its premium positioning with AI-powered wash-cycle optimization embedded across its Bespoke lineup.
Washing appliances encompass electromechanical systems designed for automated textile cleaning through programmed agitation, spin extraction, and thermal or chemical treatment cycles, typically operating at drum speeds between 800 and 1600 revolutions per minute and water consumption rates now governed by regional efficiency mandates. These units serve residential dwellings, commercial laundromats, industrial linen processors, and hospitality operators requiring validated hygiene outcomes. Front-load configurations command the dominant share of replacement value in mature economies due to superior water and energy coefficients, while smart technology integration represents the fastest-expanding feature dimension as OEMs embed IoT connectivity for remote monitoring and utility-demand response. Energy-efficient certification tiers concentrate margin pools in markets where utility rebates or carbon-labeling schemes reward verified performance thresholds.
The US Department of Energy maintains minimum efficiency standards through revised test procedures that compress allowable energy factors, while the EU Ecodesign Directive and associated energy labeling framework enforce progressive tightening of water consumption and noise emission limits. China's GB standards and MIIT circular economy directives impose comparable efficiency floors and recyclability requirements for domestic manufacturers. Stakeholders must monitor divergence between regional test protocols and certification costs, as compliance fragmentation threatens to partition product architectures and complicate platform-standardization strategies.
Market Dynamics
Urban rental housing operators are compressing refresh cycles across multi-unit properties while the EU Ecodesign framework tightens minimum performance thresholds, forcing simultaneous adaptation to demand concentration and regulatory stringency.
Growth Catalysts
- EU Ecodesign Directive:Progressive tightening of water consumption and noise emission limits accelerates replacement demand for non-compliant legacy units across European housing stock.
- Connected laundry systems:IoT-enabled remote monitoring and utility-demand response capabilities are pulling middle-income households toward upgrade cycles in China.
- Urban rental housing expansion:Multi-unit property operators across Germany, the United Kingdom, and France are standardizing appliance packages to reduce maintenance dispatch frequency.
Market Restraints
- Steel and copper input volatility:Drum assemblies and motor windings face cost pressure from commodity price swings, compressing OEM margin buffers on economy-tier platforms.
- Appliance technician shortages:Developed economies lack sufficient trained service personnel to maintain expanding installed bases, constraining aftermarket revenue capture.
- Regional test protocol divergence:Separate US DOE, EU Ecodesign, and China GB standards threaten platform standardization and inflate certification overhead.
Strategic Opportunities
- Predictive-diagnostics platforms:Preemptive component failure detection enabled by installed-base data analytics opens recurring revenue streams independent of unit sales.
- India rental housing growth:Urbanization and co-living expansion in Mumbai, Bangalore, and Delhi create concentrated demand for durable commercial-grade washing systems.
- Carbon-labeling schemes:Utility rebate programs in California, Germany, and South Korea reward verified efficiency tiers, concentrating margin pools in certified product lines.
Industry Challenges
- Embedded systems integration:Legacy property management software in hospitality and student housing blocks resists API connectivity with smart appliance fleets.
- Water-efficiency certification timelines:Extended validation periods for new drum geometries and spray patterns delay product launches against tightening regional mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Washing Appliances Market |
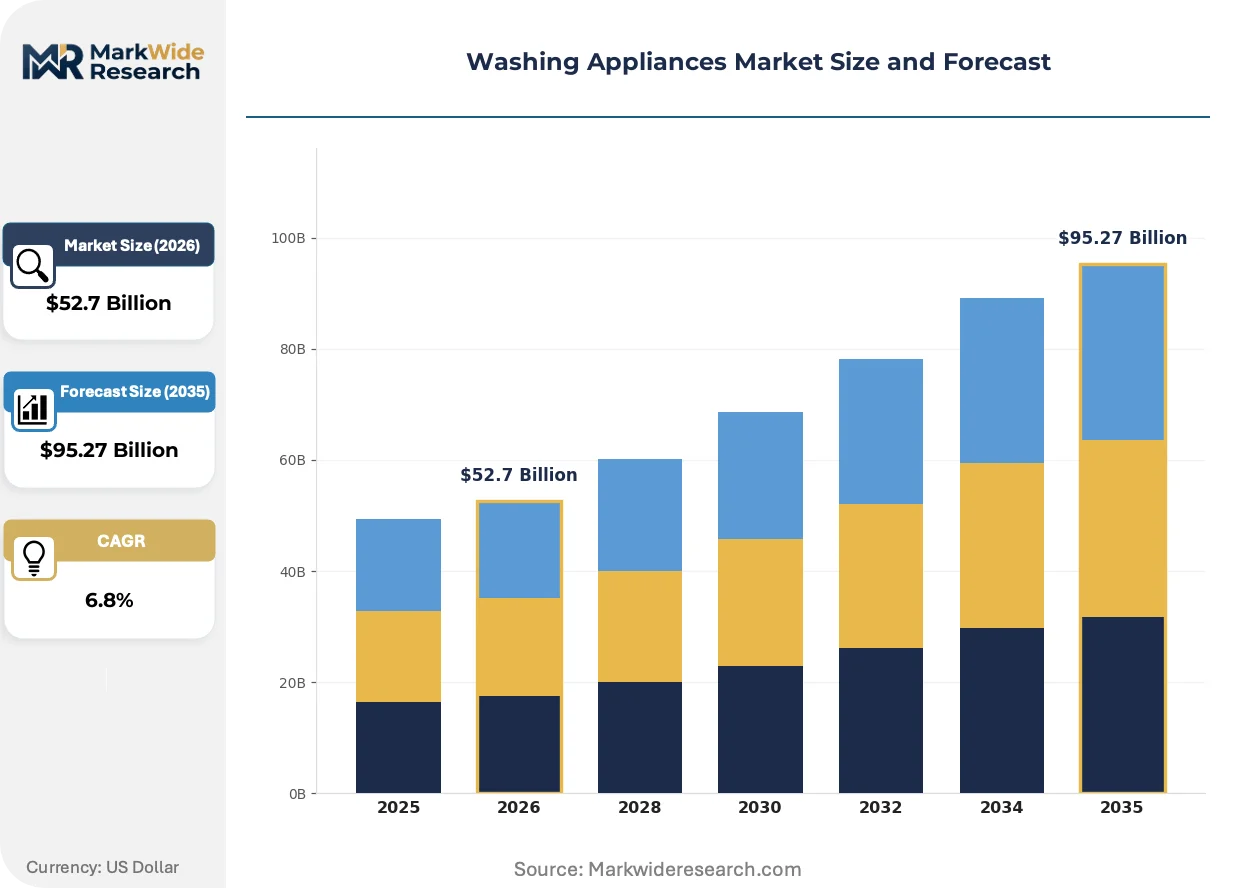
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front-Load, Top-Load, Washer-Dryer Combo, Portable Washers Feature: Smart Technology, Energy Efficient, High Capacity, Quick Wash End User: Residential, Commercial, Industrial, Hospitality Installation: Built-In, Freestanding, Under-Counter, Stackable |
| Companies Covered | Whirlpool Corporation, LG Electronics, Samsung Electronics, Haier Group Corporation, Electrolux AB, Bosch, GE Appliances, Midea, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Washing Appliances Market Emerging Trajectories
Smart technology integration is expanding fastest through IoT connectivity layers, while regulatory pressure and buyer behavior shifts are compressing traditional equipment lifecycle assumptions across residential and commercial segments.
Direct-drive motor systems are eliminating belt-and-pulley architectures through permanent-magnet synchronous designs that reduce mechanical wear and enable precise drum speed modulation. Multi-unit housing operators and commercial laundromats in Japan and South Korea are specifying these configurations for 24-hour operational duty cycles. The technology is bifurcating the replacement market between premium platforms with extended service intervals and economy units facing accelerated obsolescence.
The EU Ecodesign framework and associated energy labeling regulations are enforcing progressive tightening of water consumption limits and noise emission thresholds for new washing appliances entering European markets. OEMs must redesign drum geometries and thermal systems to meet compressed allowable energy factors, raising R&D intensity for platforms targeting EU member states. Front-load configurations with superior water coefficients capture disproportionate replacement value as housing associations and municipal procurement bodies mandate certified performance tiers.
After-sales service unbundling is separating maintenance contracts from equipment sales as technician scarcity forces buyers to evaluate total cost of ownership over warranty periods. Commercial linen processors and hospitality operators in the United States are negotiating standalone service agreements with third-party providers rather than OEM-captive networks. This shift concentrates negotiating leverage with national service aggregators and compresses brand loyalty effects in replacement decisions.
Washing Appliances Market Segmentation
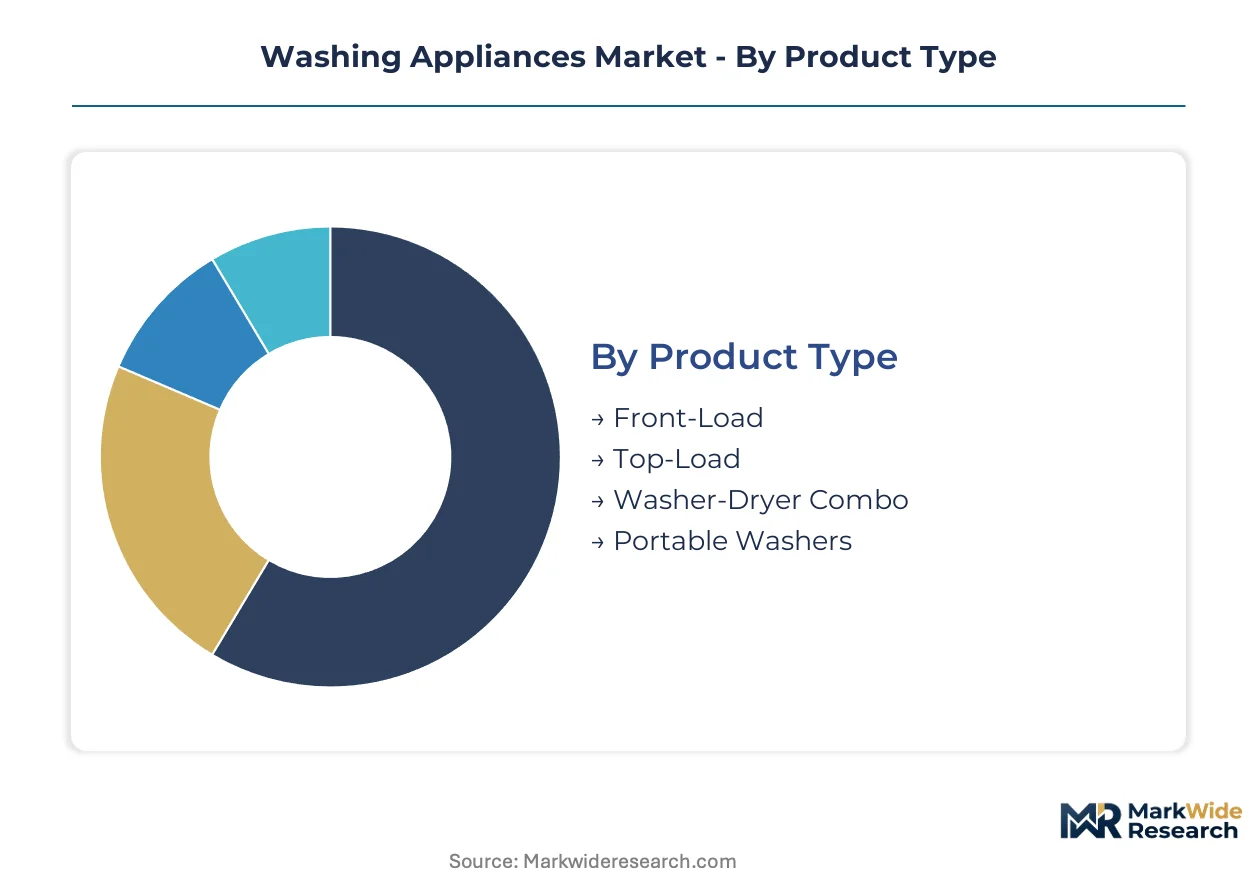
Segmentation in washing appliances reveals how margin pools concentrate around efficiency certification tiers and installation constraints. Product architecture choices cascade through feature bundling, end-use durability requirements, and property-type installation limits.
Product Type:
Margin pools concentrate in front-load platforms where water-efficiency certifications command price premiums across European and East Asian markets.
- Front-Load:Horizontal-axis drum orientation enables superior water extraction at 1200-1600 RPM spin speeds, reducing residual moisture and drying energy. Housing associations in Germany and the Netherlands specify these configurations for multi-unit properties to meet EU Ecodesign water consumption thresholds.
- Top-Load:Vertical-axis agitator or impeller systems dominate replacement cycles in North American single-family housing stock where installation depth constraints limit front-load adoption. The configuration sacrifices water efficiency for faster cycle completion and ergonomic loading height.
- Washer-Dryer Combo:Condensing or ventless drying integration addresses space-constrained urban apartments in Tokyo, London, and Paris where separate appliance allocation is impossible.
- Portable Washers:Compact countertop or wheeled units serve transient rental populations and recreational vehicle operators requiring temporary laundry capacity without permanent utility connections.
Front-Load holds installed capacity. Washer-Dryer Combo is rotating up the share rankings.
Feature:
Volume concentrates in energy-efficient certification tiers where utility rebate programs and carbon-labeling schemes concentrate purchasing decisions.
- Smart Technology:IoT connectivity layers enable remote cycle monitoring, utility-demand response, and predictive maintenance alerts. Middle-income households in China and South Korea are upgrading to connected laundry systems as domestic OEMs scale production of WiFi-enabled control boards.
- Energy Efficient:Certification tiers verified under US DOE test procedures or EU energy labeling frameworks qualify for rebate programs in California, Germany, and South Korea. These tiers capture disproportionate margin as procurement bodies mandate documented performance thresholds.
- High Capacity:Drum volumes exceeding 10 kilograms address commercial laundromats and large-family residential segments in the United States and Australia.
- Quick Wash:Accelerated cycle programs under 30 minutes target time-constrained urban professionals in Japan and the United Kingdom.
Energy Efficient holds installed capacity. Smart Technology is rotating up the share rankings.
End User:
Customer type determines durability specifications and service interval expectations across divergent utilization intensities.
- Residential:Single-family and multi-unit households drive replacement cycles tied to housing turnover and efficiency regulation compliance. Urban rental housing operators in the United Kingdom and France are compressing refresh cycles to reduce maintenance dispatch frequency.
- Commercial:Laundromats and linen services require 24-hour operational duty cycles with modular component access for field serviceability.
- Industrial:Continuous-batch processing systems for healthcare and food-service textiles impose validated hygiene outcomes and thermal disinfection protocols.
- Hospitality:Hotels and extended-stay properties balance guest-facing aesthetics with back-of-house throughput requirements and property management software integration.
Residential holds installed capacity. Commercial is rotating up the share rankings.
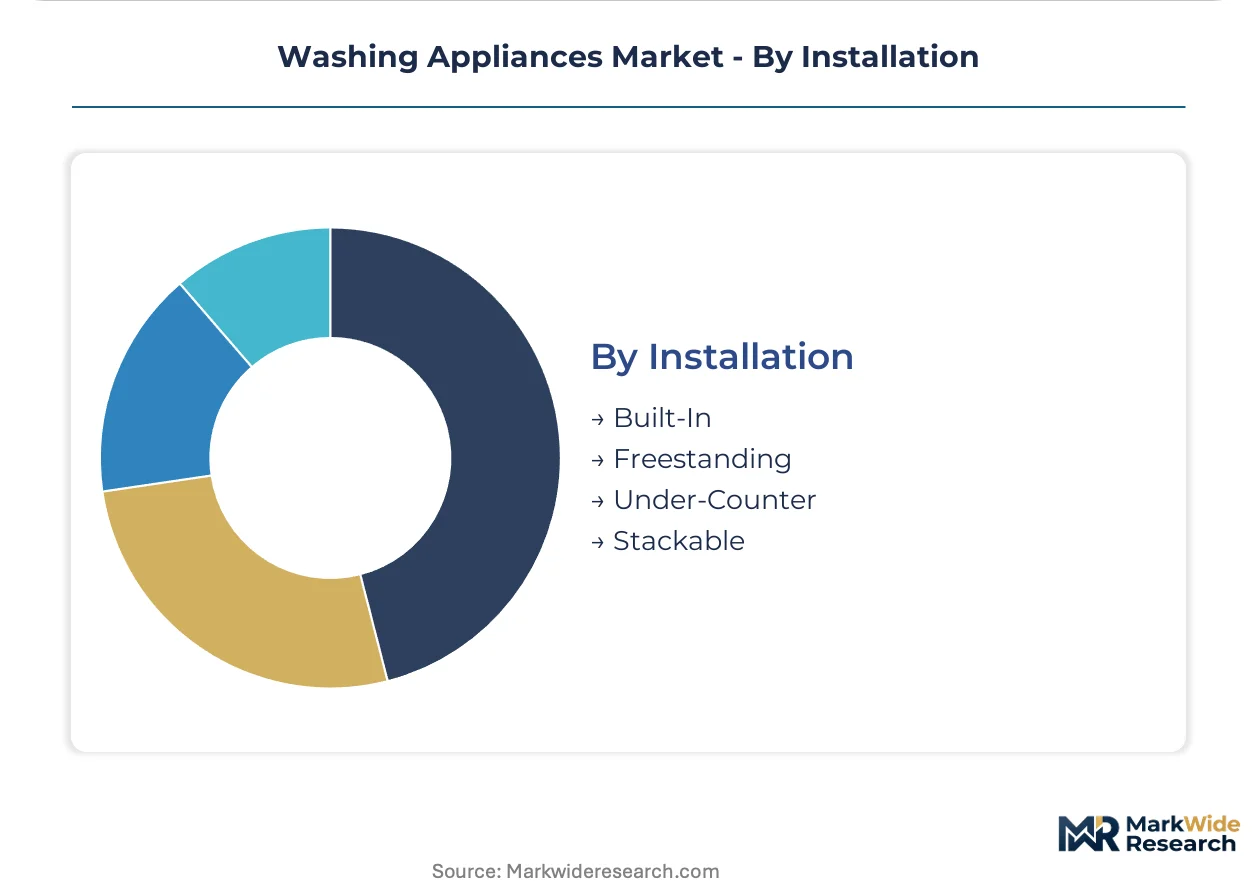
Installation:
Supply concentration follows property-type constraints that dictate dimensional limits and utility access configurations.
- Freestanding:Standard 600mm width platforms accommodate the majority of replacement demand across detached housing and retrofit installations. The configuration permits flexible placement and simplified utility connection.
- Built-In:Panel-ready or fully integrated cabinetry matching dominates kitchen-laundry combination spaces in European markets where open-plan living compresses dedicated utility room allocation.
- Under-Counter:Reduced-height dimensions serve compact apartments and recreational vehicles where vertical clearance is constrained.
- Stackable:Vertical dryer pairing maximizes floor area efficiency in multi-unit housing and laundromat configurations across Japan and South Korea.
Freestanding holds installed capacity. Built-In is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Energy anchors the regulatory landscape that shapes replacement cycles across the largest developed market, while efficiency mandates in Europe and Asia-Pacific concentrate production decisions toward certified performance tiers.
United States
Single-family housing stock drives front-load adoption constraints, while multi-unit operators compress refresh cycles to reduce maintenance dispatch frequency. The US Department of Energy revised test procedures compress allowable energy factors, forcing redesigns of thermal systems and drum geometries. California's utility rebate programs for verified efficiency tiers concentrate margin pools in certified product lines across Los Angeles and San Francisco housing associations.
Germany
Housing associations mandate certified performance tiers for multi-unit properties, accelerating replacement demand for non-compliant legacy units. The EU Ecodesign Directive enforces progressive tightening of water consumption and noise emission limits for new washing appliances entering European markets. Industrial clusters around Stuttgart and Munich host OEM engineering centers redesigning drum geometries to meet compressed allowable energy factors.
China
Middle-income households upgrade to connected laundry systems as domestic OEMs scale production of WiFi-enabled control boards. MIIT circular economy directives impose efficiency floors and recyclability requirements for domestic manufacturers. Production concentrates in the Yangtze River Delta and Pearl River Delta where supply chains for direct-drive motor systems and smart control modules cluster around Shanghai and Shenzhen.
Japan
Commercial laundromats and multi-unit housing operators specify direct-drive configurations for 24-hour operational duty cycles. METI efficiency standards and JIS certification frameworks validate performance thresholds for domestic and export markets. Tokyo and Osaka metropolitan areas drive demand for compact, stackable configurations addressing space-constrained urban apartments.
India
Urbanization and co-living expansion in Mumbai, Bangalore, and Delhi create concentrated demand for durable commercial-grade washing systems. BIS standards impose minimum efficiency and safety requirements for domestic manufacturing and imports. Gujarat and Maharashtra industrial corridors attract component suppliers serving both domestic replacement cycles and export assembly operations.
Washing Appliances Market Vendor Landscape
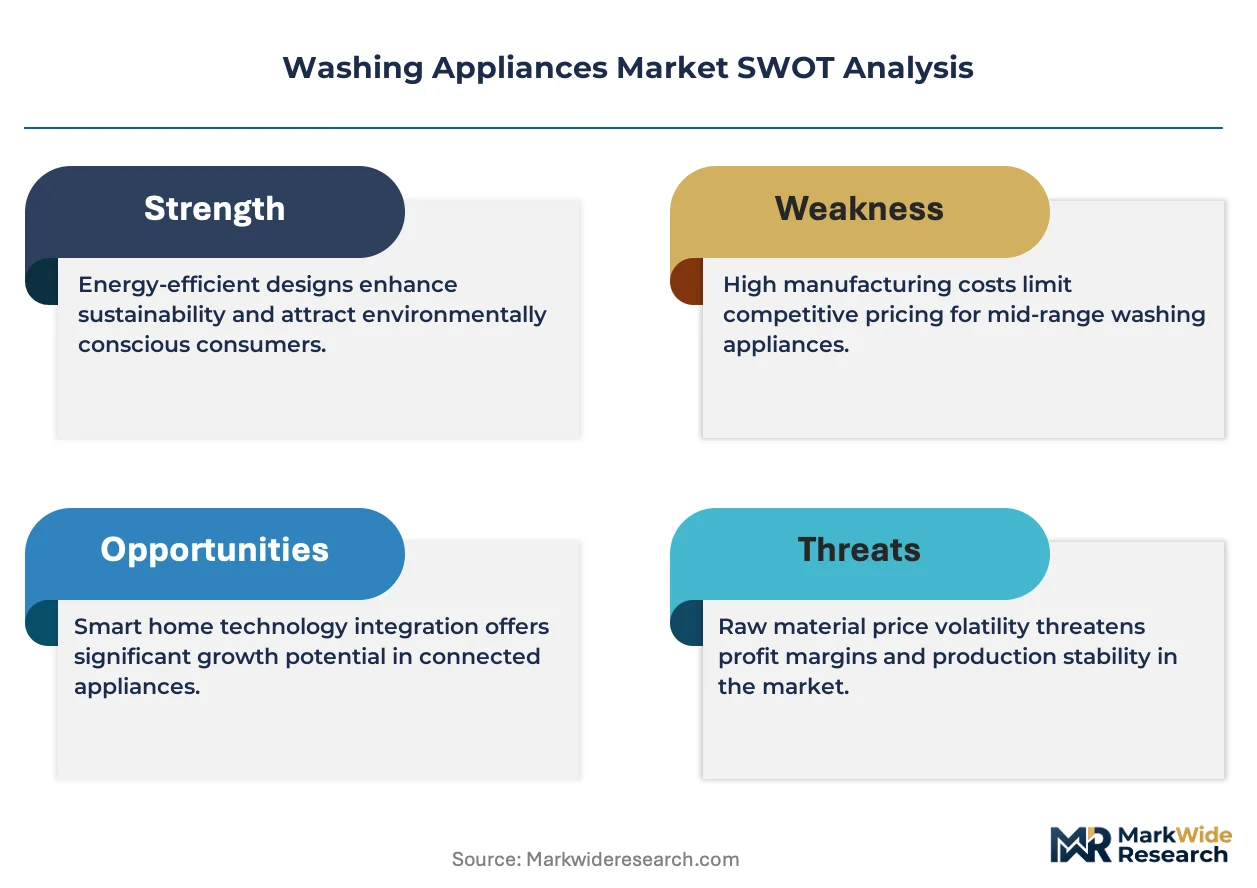
A small set of integrated leaders sits above a broader specialist tier, with the upper tier capturing disproportionate margin through captive control over motor systems and installed-base data analytics. The middle tier competes on manufacturing scale and regional distribution density. Two strategic archetypes dominate: vertically integrated OEMs with in-house component production, and platform-agnostic assemblers sourcing standardized subsystems. Competitive moves concentrate on predictive-diagnostics platform development and efficiency certification pre-positioning ahead of regulatory tightening.
Among North American and European integrated manufacturers, Whirlpool Corporation, LG Electronics, and Samsung Electronics exemplify the vertically integrated archetype through captive motor production and smart platform development. These companies occupy positions where installed-base scale enables recurring revenue streams from service and data analytics independent of unit sales velocity. Chinese manufacturers including Haier Group Corporation and Midea represent the scale-driven tier with manufacturing concentration serving both domestic replacement cycles and export assembly demand. Electrolux AB and Bosch anchor the European specialist position with engineering focus on efficiency certification and built-in configuration leadership.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| LG Electronics |
| Samsung Electronics |
| Haier Group Corporation |
| Electrolux AB |
| Bosch |
| GE Appliances |
| Midea |
| Panasonic |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty days of steel and copper inventory now separate OEMs with captive motor production from assemblers exposed to spot-market volatility, concentrating pricing power among vertically integrated manufacturers while compressing margins for tier-two suppliers dependent on commodity-exposed drum and winding purchases.
Pricing Analysis
Front-load platforms in Germany command thirty to forty percent premiums over comparable top-load configurations in North American markets, reflecting EU Ecodesign certification tiers and water-efficiency rebates. Three-tier pricing structure across premium connected systems, certified standard platforms, and economy agitator units differentiates on smart feature bundling and energy-label grade. Cost compression in economy segments intensifies due to Chinese OEM export pricing, while commercial laundromat operators show lowest price sensitivity given total-cost-of-ownership calculations over warranty periods.
Supply Chain Analysis
Sixty-day motor winding lead times from Chinese permanent-magnet suppliers currently constrain production scheduling for European and North American assembly plants. Manufacturing gravity centers on China, South Korea, and Germany for direct-drive systems, control modules, and precision drum stampings respectively. Raw material dependencies span electrical steel, neodymium magnets, and thermoplastic resins, with tariff exposure on Chinese magnet imports threatening cost structures for non-integrated OEMs. Distribution runs through national appliance retailers, direct-to-builder channels for multi-unit housing, and OEM-captive service networks for commercial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technician scarcity across developed economies now constrains aftermarket revenue capture, rewarding manufacturers who preempt component failures through installed-base analytics rather than dispatch-dependent service models.
For Market Incumbents: Consolidate predictive-diagnostics platform development ahead of regulatory tightening on water-efficiency certification timelines, while securing captive supply of direct-drive motor systems to defend against Chinese OEM scale advantages in connected laundry segments. Backward integration into permanent-magnet sourcing mitigates tariff exposure on neodymium supply chains. For New Entrants and Emerging Players: Anchor in India's co-living and rental housing expansion across Mumbai, Bangalore, and Delhi, where commercial-grade durability specifications remain underserved by incumbent service networks. Target commercial laundromat operators with modular field-serviceable architectures and standalone maintenance contracts unbundled from equipment sales. For Investors and Strategic Acquirers: Long-term, this sits as a data-annuity play because installed-base scale enables recurring revenue from predictive maintenance and utility-demand response platforms independent of replacement cycle velocity. Acquisition focus should target OEMs with captive motor production and smart-platform deployment. Monitor technician union density and training pipeline capacity as inflection signals for service-network profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Diagnostics Platform Launch | Transforms aftermarket from dispatch-dependent to data-recurring revenue, addressing technician scarcity in Germany and the United States. |
| Direct-Drive Motor Backward Integration | Secures supply chain control over permanent-magnet synchronous designs against Chinese export pricing pressure. |
| EU Ecodesign Pre-Certification Investment | Positions product lines ahead of progressive water consumption threshold tightening across housing association procurement. |
| India Commercial Distribution Partnership | Captures co-living and rental housing growth in Mumbai and Bangalore through localized service infrastructure. |
| Smart Control Module Production Scale-Up | Enables WiFi-enabled utility-demand response features pulling middle-income Chinese household upgrade cycles. |
Methodological Framework
Initial hypotheses were tested against primary input from appliance engineering directors, multi-unit housing procurement managers, commercial laundromat operators, and aftermarket service network heads, then refined through secondary validation against US DOE test procedure filings, EU Ecodesign implementing measure texts, China MIIT circular economy directives, and customs trade data on steel and copper drum assemblies. Bottom-up unit economics triangulated against top-down housing stock and replacement cycle estimates.
Variance decomposition across product type, feature tier, end-user intensity, and installation configuration shaped volume and value outputs over the projection horizon. CAGRs derived from segment-level replacement cycle modeling and regulatory compliance deadline phasing, with specific inputs including housing turnover rates in urban rental markets and efficiency mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of steady regulatory tightening pace and commodity price band stability; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
North America Microwave Oven Market
Appliances
United States Microwave Oven Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Asia Pacific Household Side by Side Refrigerator Market
Appliances
Cooler Connected to the Mains Market
Appliances
Europe Household Electric Grills Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Global Home Ice Maker Market
Appliances
Commercial Microwave Ovens Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
Mini Washing Machine Market
Appliances
AI Washing Machine Market
Appliances
Household Side by Side Refrigerator Market
Appliances
Electric Rice Cooker Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Egypt Dishwashers Market