
 Global Water Softeners Market | 2026-2036
Global Water Softeners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water Softeners Market Outlook
Salt-free conditioning technology is fragmenting the traditional ion-exchange equipment landscape as manufacturers race to meet consumer preference for reduced sodium discharge. Culligan International Company leverages its dealer network density to sustain service-contract revenue across North American suburbs. Pentair PLC anchors its portfolio with commercial-grade dual-tank systems that dominate hospitality and healthcare verticals. BWT AG differentiates through magnesium enrichment technology that competes on health-positioning rather than pure softening metrics.
Water softeners remove calcium and magnesium ions from hard water through ion-exchange resin beds regenerated with sodium chloride brine, typically processing 20,000 to 80,000 grains of hardness before regeneration cycles. These systems protect plumbing infrastructure, extend appliance lifespan, and reduce detergent consumption in residential, commercial, and industrial settings. Salt-based systems occupy the largest installed base due to proven efficacy and lower upfront cost, though salt-free alternatives are capturing faster growth among environmentally conscious residential buyers. Whole-house installations generate the steadiest replacement demand, while point-of-use units concentrate margin pools in compact urban dwellings where space constraints limit conventional equipment.
The EPA's secondary maximum contaminant levels for water hardness influence municipal treatment priorities and consumer awareness in the United States, while REACH compliance in Europe restricts certain resin chemistries and brine disposal pathways. India's BIS certification mandates performance testing for imported softener assemblies, creating a barrier for unvalidated equipment entering that market. Stakeholders must monitor evolving salt discharge regulations across multiple jurisdictions, as brine restriction policies will determine whether salt-free technologies achieve cost parity with conventional ion-exchange systems.
Market Dynamics
Salt discharge regulations across multiple jurisdictions are forcing equipment manufacturers to reengineer regeneration cycles and brine management systems, compressing margins for conventional ion-exchange architectures while elevating development budgets for salt-free alternatives.
Growth Catalysts
- REACH compliance in Europe:Restrictions on certain resin chemistries accelerate replacement demand for certified equipment upgrades in Germany and France.
- Residential housing developers:Suburban North American new-construction specifications increasingly mandate whole-house softener pre-installation.
- Magnesium enrichment technology:Health-positioned systems attract premium buyers seeking mineral-retaining alternatives to traditional sodium-exchange methods.
Market Restraints
- Sodium chloride price volatility:Brine input costs fluctuate with agricultural and de-icing demand cycles, pressuring operating economics for salt-based systems.
- Resin supply concentration:Specialty ion-exchange resin production clusters in China and Germany, creating vulnerability to trade flow disruptions.
- Template-assisted crystallization limitations:Salt-free conditioning shows reduced efficacy above 25 grains per gallon hardness, restricting addressable market scope.
Strategic Opportunities
- India BIS certification pathway:Validated imported assemblies gain preferential access to underserved tier-2 and tier-3 municipal markets.
- Commercial hospitality vertical:Hotels and restaurants seek compact dual-tank configurations for continuous soft water during peak occupancy periods.
- EPA secondary standard evolution:Anticipated guidance updates on aesthetic water quality parameters drive preemptive consumer replacement cycles.
Industry Challenges
- Cross-connection control certification:Plumber licensing boards in multiple US states impose additional training requirements for softener installation permits.
- Legacy plumbing integration:Retrofit installations in pre-1980s housing stock require costly copper line modifications and pressure vessel upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water Softeners Market |
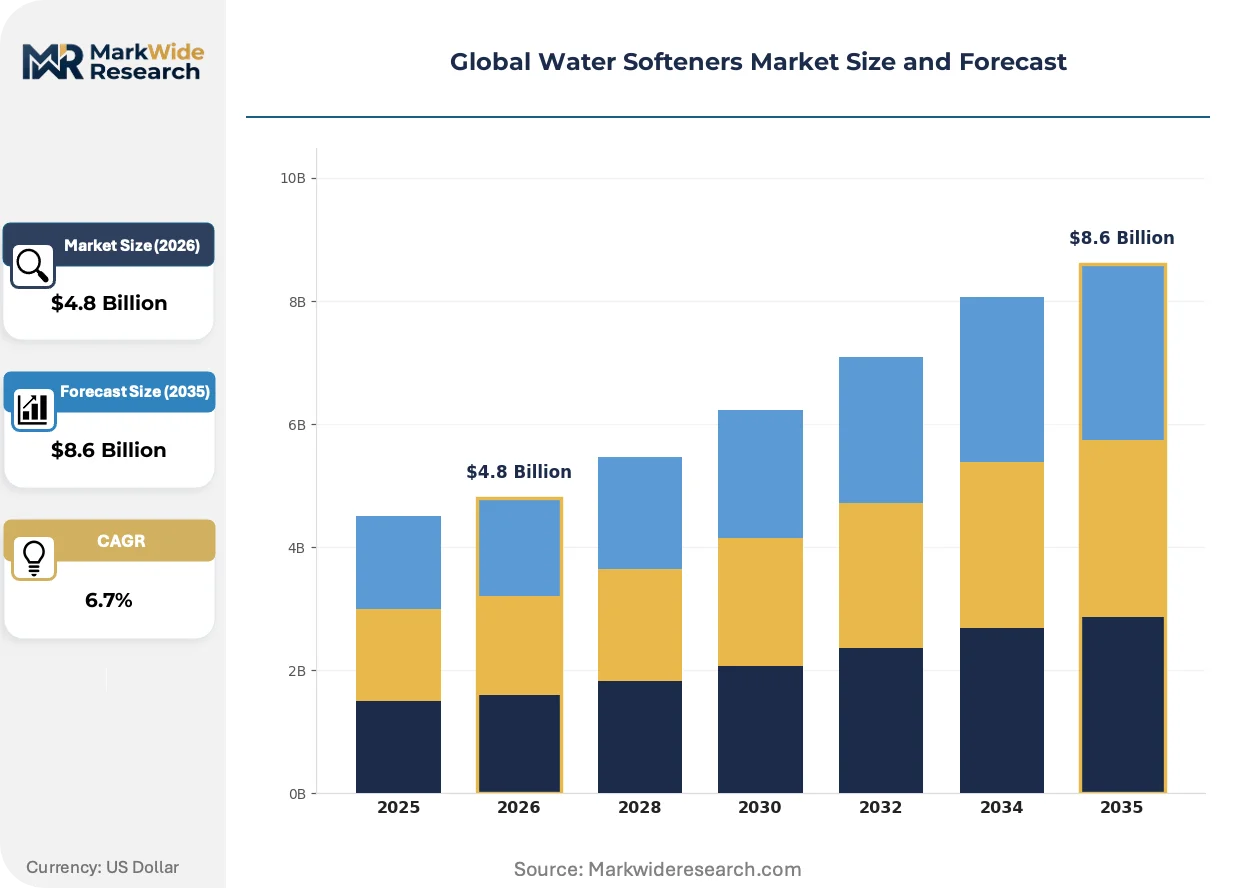
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt-Based, Salt-Free, Dual-Tank, Magnetic End User: Residential, Industrial, Commercial, Agricultural Installation Type: Point-of-Use, Whole House, Portable, Wall-Mounted Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Culligan International Company, EcoWater Systems LLC, Kinetico Incorporated, A.O. Smith Corporation, Pentair PLC, Whirlpool Corporation, BWT AG, Watts Water Technologies Inc., Water-Right Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water Softeners Market Strategic Shifts
Equipment architectures are converging around connected monitoring capabilities and multi-stage treatment trains, blurring traditional boundaries between softening, filtration, and conditioning functions.
Electrochemical scale prevention is hybridizing with conventional resin-based systems in premium product tiers. These hybrid units combine electrode-based mineral precipitation with reduced-salt regeneration protocols. Hospitality operators in Arizona and Nevada are piloting these configurations to meet corporate sustainability targets. The technology is hybridizing equipment categories, forcing manufacturers to recalibrate service revenue models around consumables rather than periodic resin replacement.
ECHA's expanding restrictions on persistent organic pollutants in polymer manufacturing are tightening resin supply chains. European manufacturers must reformulate cross-linked polystyrene matrices to eliminate legacy stabilizer compounds. German OEMs face compressed certification timelines as REACH substance evaluation deadlines accelerate, pushing R&D budgets toward bio-based alternative chemistries.
After-sales service unbundling is fragmenting traditional dealer-contract relationships. North American big-box retailers now offer direct-to-consumer installation networks, bypassing legacy authorized service channels. This disintermediation concentrates in Sun Belt states where seasonal population influx creates temporary demand spikes that independent dealers cannot staff.
Global Water Softeners Market Segmentation
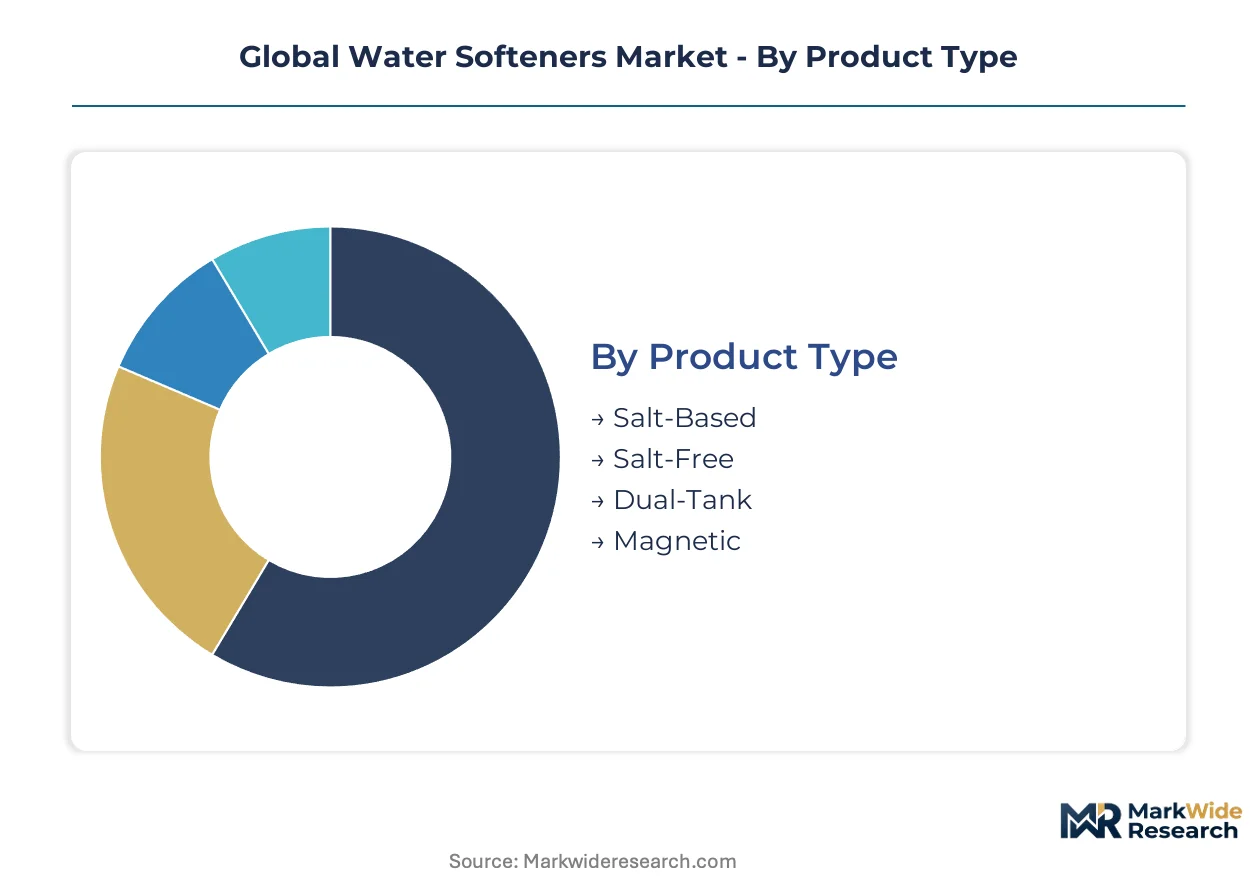
Water softener procurement patterns diverge sharply across product architectures and installation contexts. Equipment specifications, regulatory constraints, and end-use durability requirements create distinct margin pools within each segment category.
Product Type:
Cost tier differentiation separates established ion-exchange systems from emerging conditioning alternatives.
- Salt-Based:Ion-exchange resin beds regenerated with sodium chloride brine deliver proven hardness removal across 20,000 to 80,000 grain capacities. Residential developers in suburban United States specify these for new construction plumbing protection. Sodium chloride price volatility compresses operating margins for price-sensitive buyers.
- Salt-Free:Template-assisted crystallization and electromagnetic conditioning alter mineral structure without chemical discharge. REACH compliance in Europe accelerates specification in Germany and France where brine discharge faces tightening restrictions. Efficacy limitations above 25 grains per gallon restrict deployment in Arizona and Nevada municipal zones.
- Dual-Tank:Continuous-operation configurations with alternating resin vessels serve hospitality and healthcare verticals requiring uninterrupted soft water supply.
- Magnetic:Coil-based scale prevention targets compact urban installations where space constraints preclude vessel-based equipment.
Salt-based systems command the established base. The steepest expansion runs through salt-free alternatives.
End User:
Application durability requirements and water throughput volumes determine equipment specification intensity.
- Residential:Whole-house installations protect appliances and plumbing infrastructure in single-family dwellings. Suburban North American housing stock drives replacement cycles as EPA secondary standard awareness elevates. BIS certification requirements in India create compliance barriers for unvalidated imported assemblies entering tier-2 and tier-3 municipal markets.
- Commercial:Hotels and restaurants in Arizona and Nevada deploy compact dual-tank systems for continuous operation during peak occupancy. Corporate sustainability targets accelerate pilot programs for electrochemical hybrid configurations.
- Industrial:Process water treatment for manufacturing facilities demands high-capacity regeneration cycles with automated brine management.
- Agricultural:Irrigation system protection concentrates in regions with groundwater hardness exceeding 15 grains per gallon.
Residential installations anchor volume. Commercial verticals are climbing the fastest.
Installation Type:
Customer site constraints and water consumption patterns dictate physical equipment configuration.
- Whole House:Centralized treatment at main water entry protects all downstream fixtures and appliances. Pre-1980s housing stock in United States legacy suburbs requires costly copper line modifications and pressure vessel upgrades during retrofit deployment.
- Point-of-Use:Under-sink and countertop units concentrate margin pools in compact urban dwellings where space constraints limit conventional equipment. Sun Belt states experience seasonal demand spikes from temporary population influx that strain independent dealer installation capacity.
- Portable:Temporary deployment configurations serve recreational vehicles and rental properties.
- Wall-Mounted:Vertical space utilization addresses utility room footprint limitations in multi-unit residential construction.
Whole-house systems dominate replacement revenue. Point-of-use configurations gain share fastest in dense urban markets.
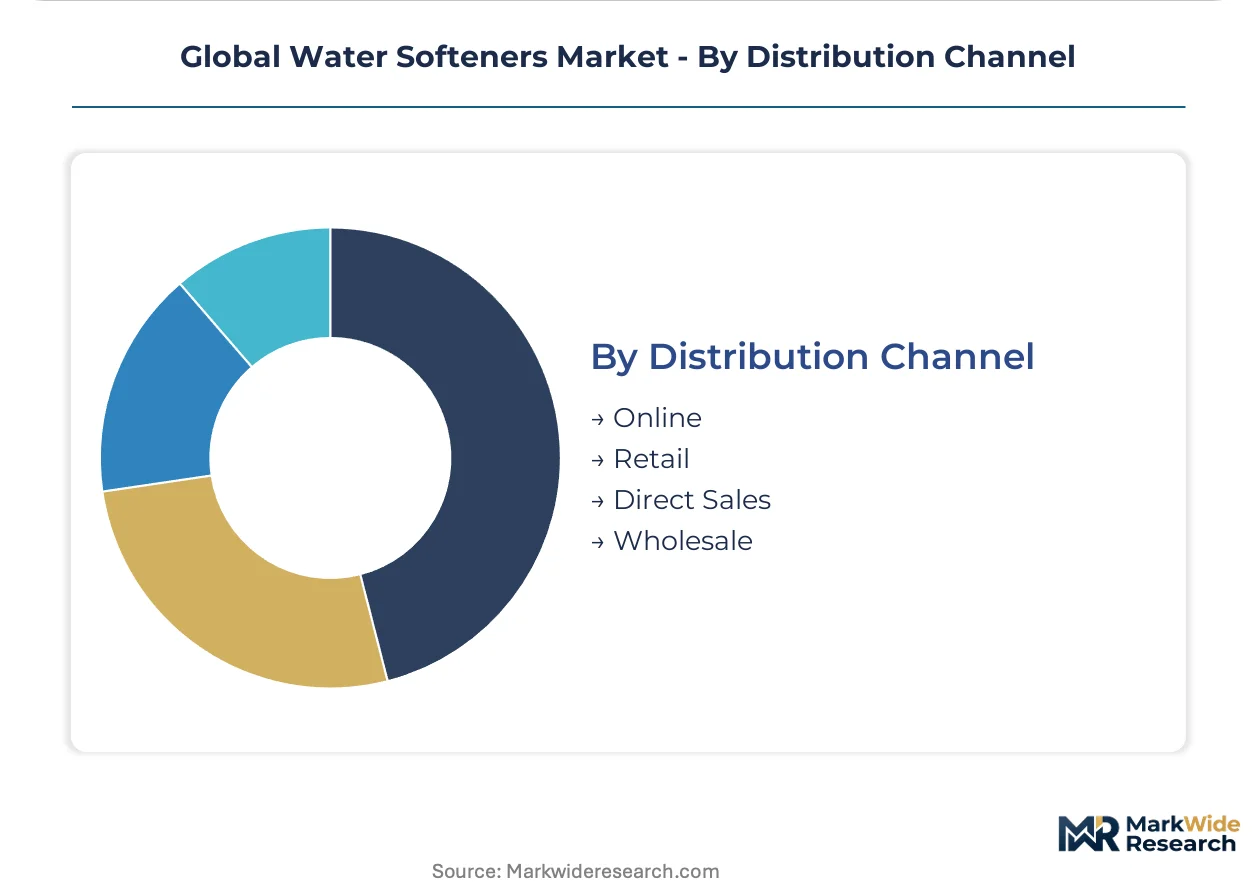
Distribution Channel:
Supply chain configuration separates authorized service networks from direct-to-consumer fulfillment.
- Retail:Big-box home improvement channels in United States Sun Belt states concentrate seasonal volume. After-sales service unbundling fragments traditional dealer-contract relationships as retailers build direct installation networks.
- Online:E-commerce platforms bypass legacy authorized service channels, capturing environmentally conscious residential buyers researching salt-free alternatives. Product reviews and certification transparency influence specification decisions.
- Direct Sales:Manufacturer-owned service contracts sustain recurring revenue through resin replacement and system maintenance scheduling.
- Wholesale:Plumbing contractor supply houses serve new construction specifications and commercial project bidding.
Retail channels command the established base. Online distribution is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in water softener equipment tilt toward net imports in hardness-intensive regions while manufacturing clusters in Germany and the United States supply technology-intensive components to Asia-Pacific markets. Trade balances reflect divergent regulatory stringency on brine discharge and resin chemistry standards.
United States
Suburban housing developers in Arizona, Nevada, and Texas specify whole-house softener pre-installation in new construction. EPA secondary maximum contaminant level guidance shapes product certification requirements and consumer awareness campaigns. The Sun Belt corridor from Phoenix to Orlando experiences seasonal demand spikes that strain independent dealer installation capacity.
Germany
Municipal water hardness variation between Bavaria and North Rhine-Westphalia drives replacement cycles and premium system upgrades. ECHA REACH compliance deadlines accelerate certified equipment demand and compress OEM certification timelines. Stuttgart and Munich industrial clusters host reformulation R&D for bio-based resin alternative chemistries.
India
Tier-2 and tier-3 municipal markets in Maharashtra and Gujarat present untapped replacement demand as BIS certification mandates filter unvalidated imported assemblies. Bureau of Indian Standards performance testing creates compliance barriers for low-cost equipment entrants. Bangalore and Hyderabad technology corridors drive specification-grade demand from commercial facilities.
China
Specialty ion-exchange resin production concentrates in Jiangsu and Zhejiang provinces, creating supply vulnerability to trade flow disruptions. GB standards alignment with REACH substance restrictions shapes export-oriented manufacturer compliance investments. The Yangtze River Delta cluster supplies resin bed components to European and North American OEMs.
Canada
Groundwater hardness in Prairie Provinces exceeds 20 grains per gallon in Saskatchewan and Manitoba well systems. Health Canada and PMRA coordination on drinking water quality parameters influences provincial treatment priorities. Calgary and Edmonton commercial sectors deploy high-capacity regeneration systems for hospitality and healthcare verticals.
Global Water Softeners Market Competitive Environment
On the supply side, the industry is tiered between multinational diversified industrials with captive distribution networks and regional specialists competing on service density. The vendor base spans water treatment conglomerates, appliance manufacturers, and dedicated softener OEMs with dealer-centric business models. Two strategic archetypes dominate: integrated platform players leveraging cross-category scale and focused specialists monetizing service-contract recurrence. Competitive moves concentrate on geographic expansion through authorized dealer acquisition and technology licensing for salt-free conditioning alternatives.
Among diversified industrial platform players, Pentair PLC and A.O. Smith Corporation exemplify scale-driven positioning across residential and commercial verticals. BWT AG occupies a differentiated niche within the European specialist tier, anchoring health-positioned magnesium enrichment technology. Culligan International Company represents the service-contract archetype, sustaining recurring revenue through dealer network density rather than equipment margin alone.
| Leading Market Players |
|---|
| Culligan International Company |
| EcoWater Systems LLC |
| Kinetico Incorporated |
| A.O. Smith Corporation |
| Pentair PLC |
| Whirlpool Corporation |
| BWT AG |
| Watts Water Technologies Inc. |
| Water-Right Inc. |
| Others |
Value Chain & Pricing Dynamics
Jiangsu and Zhejiang provinces anchor specialty ion-exchange resin production capacity, concentrating upstream supply power among Chinese chemical manufacturers who dictate input pricing to downstream softener OEMs in Germany and the United States. This geographic clustering amplifies pricing leverage during agricultural and de-icing demand cycles that spike sodium chloride costs, compressing margins for salt-based system assemblers who lack captive brine supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, while residential procurement stratifies across premium, standard, and economy tiers differentiated by certification grade and after-sales service bundling. Price differentiation hinges on NSF/ANSI 44 certification tier and geographic delivery cost from manufacturing clusters to end markets. Cost compression in economy-tier residential equipment is intensifying because big-box retailers disintermediate legacy dealer networks. Municipal procurement teams demonstrate highest price sensitivity due to budget cycle constraints, whereas hospitality operators prioritize continuous-operation reliability over unit economics.
Supply Chain Analysis
Styrene-divinylbenzene copolymer feedstock draws from petrochemical complexes in China, Germany, and the United States, with specialty resin functionalization concentrated in Jiangsu province and the Stuttgart industrial cluster. Cross-linked polystyrene matrices and sodium chloride brine inputs rest on agricultural and chemical sector demand cycles. Single-source vulnerability concentrates in Chinese resin finishing capacity, where ECHA REACH compliance deadlines threaten export-oriented manufacturer throughput. Distribution runs through authorized dealer networks for service-contract revenue capture, though direct-to-consumer e-commerce channels are fragmenting traditional fulfillment structures in North American Sun Belt states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from resin replacement and system maintenance scheduling expands faster than hardware unit sales, positioning after-sales service density as the primary value capture mechanism in this market. Equipment margin pools are compressing as salt-free alternatives commoditize at the low end, while service-contract stickiness sustains incumbent profitability.
For Market Incumbents: Build certification moats around BIS validation for Indian tier-2 municipal access and REACH-compliant resin reformulation for European retention. Salt-free conditioning technology threatens ion-exchange installed base erosion; defend through backward integration into specialty resin production in Germany to secure supply continuity during ECHA substance evaluation deadlines. Channel control via authorized dealer acquisition in Arizona and Nevada Sun Belt corridors limits disintermediation risk from big-box retail installation networks. For New Entrants and Emerging Players: Tier-2 and tier-3 municipal markets in Maharashtra and Gujarat present the most penetrable white-space, given BIS certification barriers filtering low-cost unvalidated imports. Electrochemical hybrid configurations for Arizona and Nevada hospitality corporate sustainability targets offer application-specific entry with premium positioning. Direct-to-consumer e-commerce paired with third-party installation network partnerships bypasses legacy dealer density requirements in seasonal demand spike geographies. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because replacement resin and brine consumables generate predictable cash flows decoupled from new construction cyclicality. Acquisition targets should display service-contract recurrence above hardware attachment rates and geographic density in hardness-intensive groundwater regions. Monitor EPA secondary standard guidance evolution as the signal for preemptive consumer replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Captive supply of REACH-compliant ion-exchange matrices secures German OEM certification timelines against ECHA restrictions. |
| Direct-to-Consumer Installation Network Buildout | Bypasses legacy dealer channels in Sun Belt states where seasonal population influx strains independent capacity. |
| BIS Certification Investment for Indian Market Entry | Validated assemblies gain preferential access to underserved tier-2 and tier-3 municipal procurement in Maharashtra and Gujarat. |
| Electrochemical Hybrid Product Launch | Corporate sustainability targets in Arizona and Nevada hospitality verticals pilot reduced-salt regeneration protocols. |
| Service Contract Recurrence Platform | Consumables-based revenue models displace periodic resin replacement dependence in premium product tiers. |
Study Parameters
A spread of perspectives from plant engineers at softener OEMs, procurement leads at hospitality and healthcare facilities, aftermarket service heads at dealer networks, and regulatory affairs specialists at resin manufacturers converged on the working assumptions. Primary interview insights combined with secondary validation from EPA secondary standard guidance documents, ECHA REACH substance evaluation databases, BIS certification registries, and customs trade flow data. Bottom-up equipment shipment analysis and top-down addressable market sizing triangulated volume estimates.
Demand-supply-balance framing structured the analytical framework across the analysis window, modeling segmentation dimensions including product architecture, end-use vertical, installation type, and distribution channel. CAGRs derived from regression analysis against historical replacement cycles, new construction permitting data, and regulatory compliance deadline clustering. Forecast inputs incorporated sodium chloride price volatility indices and municipal water hardness variation patterns by geographic cluster.
Practitioners should monitor ECHA persistent organic pollutant restriction expansion, EPA secondary standard guidance updates, and Indian BIS certification enforcement intensity for early signals requiring forecast revision. Cross-checking against customs resin import volume data and regional plumbing permit filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Wastewater Treatment Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Enzymes for Water Treatment Market