
 Kitchen Storage Organization Market | 2026-2036
Kitchen Storage Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Storage Organization Market Insights
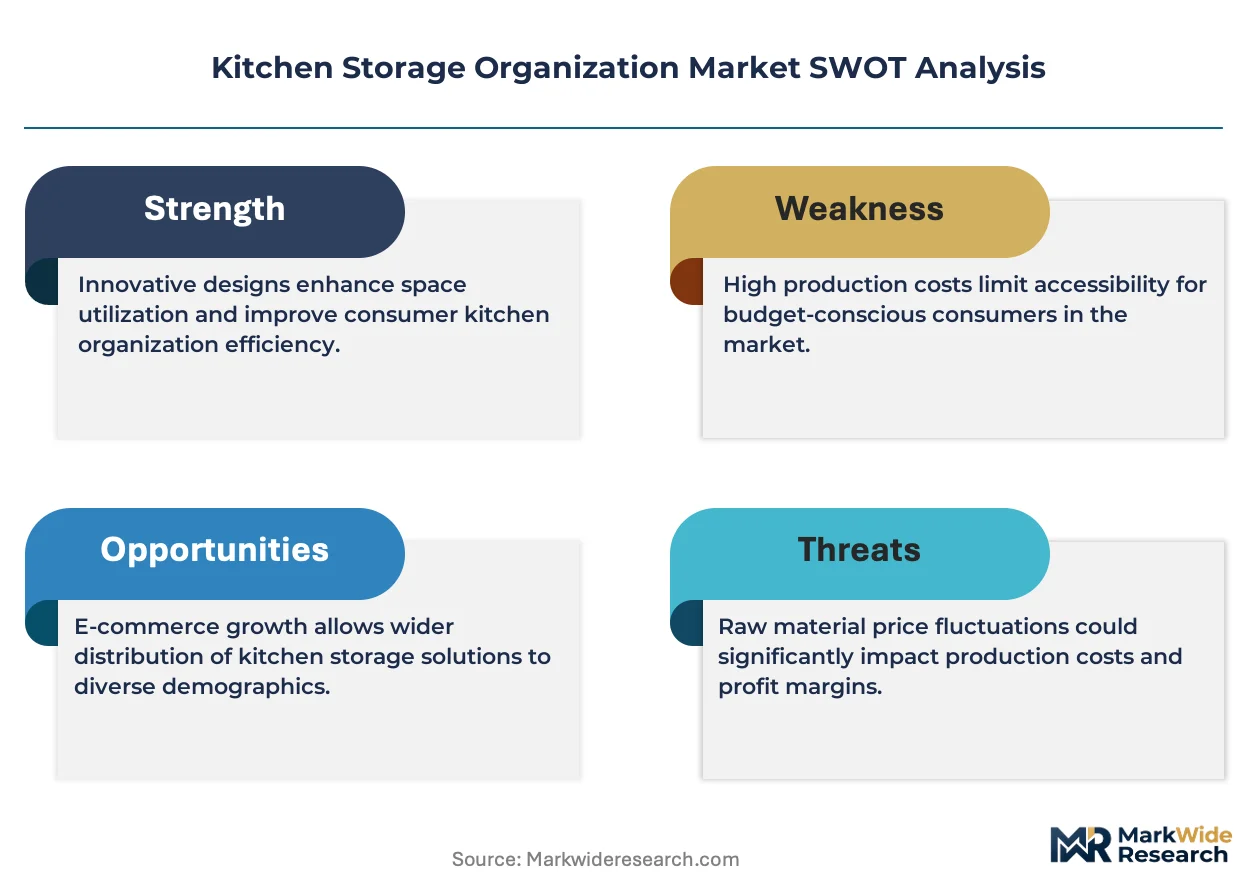
The kitchen storage organization market is restructuring around a sharp split between premium custom-built systems and mass-produced commodity units. Inter IKEA Systems B.V. leverages flat-pack logistics and global retail footprint to dominate accessible price tiers. The Container Store competes through specialty retail experience and exclusive product curation. Williams-Sonoma, Inc. anchors the premium segment with chef-grade materials and design-forward aesthetics.
Kitchen storage organization encompasses engineered systems for containing, accessing, and preserving food, cookware, and utensils within residential and commercial food preparation environments, typically fabricated from moisture-resistant substrates with load ratings between 15 and 50 kilograms per shelf. These systems serve the primary commercial purpose of maximizing cubic efficiency while maintaining sanitation compliance and ergonomic workflow. Cabinets and racks represent the largest installed base, though bins are recording the fastest growth in e-commerce channels where consumers purchase modular add-ons. Metal and wood materials command margin premiums over plastic alternatives due to durability claims and aesthetic upgrade cycles.
The EPA oversees formaldehyde emissions standards for composite wood products used in cabinet construction, while California Air Resources Board regulations extend those limits to finished goods sold in the state. The EU Ecodesign Directive and REACH chemical restrictions shape export compliance for manufacturers sourcing hardware and finishes from Asian suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks that could shift end-of-life collection costs onto original equipment manufacturers.
Market Dynamics
The kitchen storage organization market is bifurcating sharply between premium custom-built systems and mass-produced commodity units, with California's Title 24 energy standards and Germany's sustainability mandates accelerating this structural split by penalizing material waste and rewarding modular design.
Growth Catalysts
- Urban Density Pressures:Residential apartment dwellers in dense metropolitan clusters across Germany, Japan, and the Netherlands are driving demand for space-efficient modular storage systems that maximize cubic efficiency in compact kitchens.
- REACH Chemical Restrictions:The EU's regulatory framework on hazardous substances is compelling manufacturers to reformulate finishes and adhesives, creating competitive advantage for compliant suppliers exporting to European markets.
- Flat-Pack Logistics Innovation:Advanced packaging engineering and last-mile optimization are reducing freight costs and damage rates, enabling direct-to-consumer distribution of previously retail-dependent storage categories.
Market Restraints
- Composite Wood Input Volatility:Fluctuating particleboard and MDF prices, tied to resin chemistry and timber harvest cycles, compress margins for mid-tier cabinet producers unable to pass through cost swings.
- Asian Hardware Concentration:Hinge, slide, and connector manufacturing clusters in Zhejiang and Guangdong provinces create single-source dependency risks for European and North American assemblers.
- Formaldehyde Emission Caps:EPA standards for composite wood products and California Air Resources Board extensions to finished goods impose testing and certification burdens that disadvantage smaller fabricators.
Strategic Opportunities
- Underpenetrated Indian Urban Housing:India's expanding metro apartment stock and PLI scheme incentives for domestic manufacturing create whitespace for modular kitchen storage systems adapted to tropical humidity conditions.
- Smart Sensor Convergence:Integration of IoT-enabled inventory tracking with traditional cabinet systems is opening premium price tiers for connected kitchen ecosystems in tech-forward residential developments.
- Extended Producer Responsibility Tailwinds:Emerging EU frameworks shifting end-of-life collection costs onto original equipment manufacturers favor durable metal and solid wood constructions over disposable polymer alternatives.
Industry Challenges
- Cross-Border Certification Timelines:Dual compliance with EPA formaldehyde rules and EU Ecodesign Directive requirements extends product launch cycles and strains quality assurance staffing.
- Legacy Kitchen Retrofit Complexity:Non-standard cabinet dimensions and irregular wall planes in existing residential stock complicate modular system installation, requiring costly field customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Storage Organization Market |
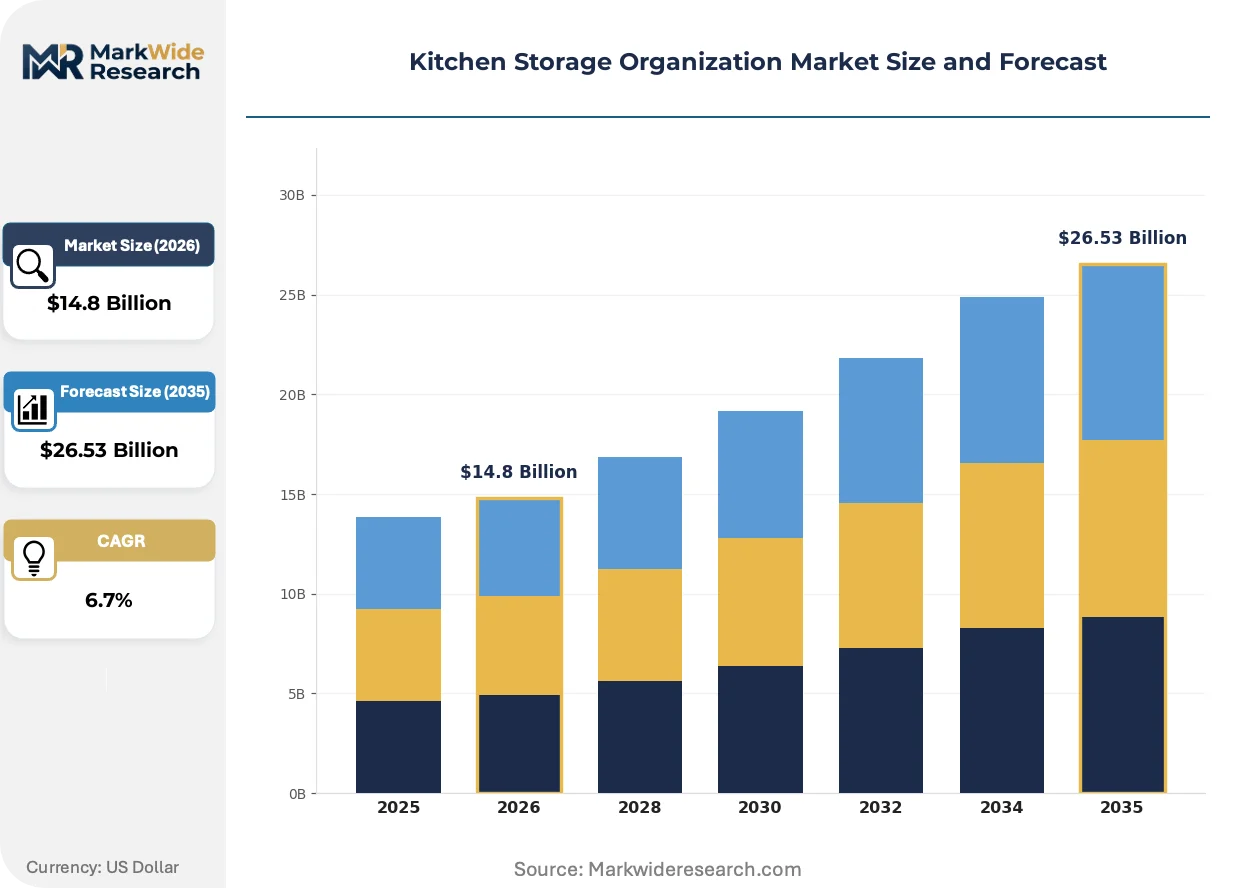
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Shelves, Racks, Bins Material: Wood, Plastic, Metal, Glass Application: Residential, Commercial, Modular, Custom Distribution Channel: Online Stores, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Inter IKEA Systems B.V., Newell Brands Inc., The Container Store, Knape & Vogt Manufacturing Company, Rev-A-Shelf, Blum, OXO, Williams-Sonoma, Inc., Sterilite Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Storage Organization Market Trends and Innovations
Active experimentation with sensor-enabled inventory management, bio-based material substitutions, and direct-to-consumer channel structures is compressing traditional retail intermediaries and reshaping how storage systems are specified, purchased, and installed.
Bamboo-epoxy composite substrates are integrating moisture-resistant performance with carbon-sequestration marketing claims. Premium residential developers in Scandinavia and the Pacific Northwest are specifying these materials for kitchen casework at accelerating rates. The technology is integrating aesthetic upgrade cycles with sustainability credentialing that commands measurable price premiums over conventional particleboard.
California's Title 24 building energy standards are mandating reduced material waste through built-in organization systems in new residential construction. Developers face compliance penalties for inefficient kitchen layouts that require aftermarket retrofit storage. The regulation is concentrating specification authority with architectural firms and general contractors rather than end-user consumers.
Subscription-based storage refresh programs are displacing traditional ownership models among urban millennial and Gen-Z cohorts. Rental-focused platforms in Berlin, Amsterdam, and Copenhagen now offer modular kitchen system swaps on 24-month cycles. The behavior is most visible in markets with high tenant turnover and strict security-deposit regulations that penalize permanent fixture modifications.
Kitchen Storage Organization Market Segmentation
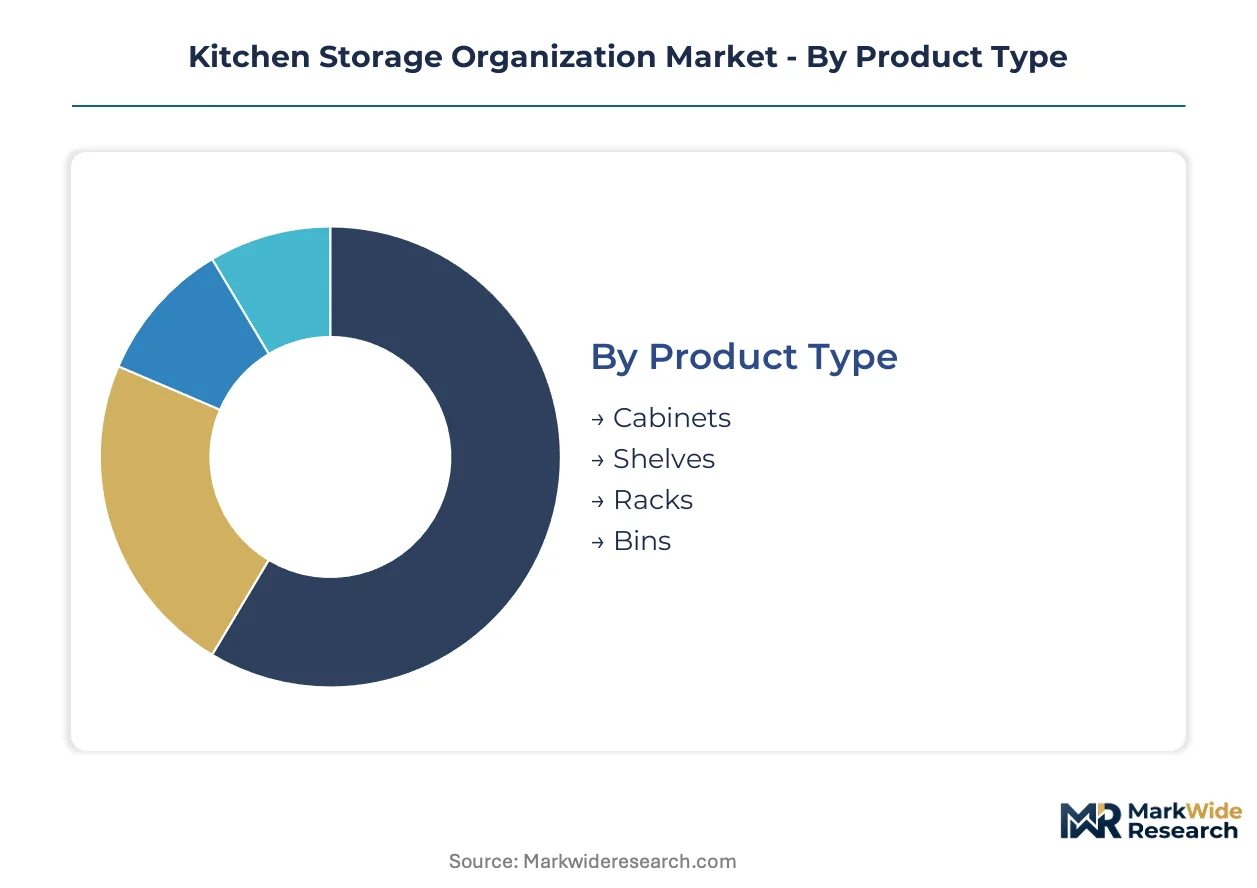
Kitchen storage organization markets fragment across four critical dimensions that determine manufacturing scale, margin structure, and channel strategy. Product type and material selection drive capital intensity and regulatory exposure, while application and distribution channel choices shape customer acquisition costs and brand positioning.
Product Type:
Supply concentration clusters around cabinet systems where engineered wood panel processing demands continuous production runs and formaldehyde compliance testing infrastructure.
- Cabinets:Engineered from moisture-resistant composite substrates with load ratings between 15 and 50 kilograms per shelf. Demand concentrates in Germany and California where building energy standards mandate built-in organization systems that reduce material waste in new residential construction.
- Shelves:Fabricated as wall-mounted or freestanding units with adjustable bracket systems. Apartment dwellers in dense Dutch and Japanese urban centers are driving specification of space-efficient modular shelf configurations that maximize cubic efficiency in compact kitchens.
- Racks:Freestanding vertical storage systems for cookware and utensil access. Metal rack production concentrates in Zhejiang province manufacturing clusters.
- Bins:Modular container systems for pantry and countertop organization. E-commerce channels in Berlin and Amsterdam are recording the steepest expansion trajectory for bin category sales.
Today's leader: Cabinets. Tomorrow's challenger: Bins.
Material:
Cost tier stratification separates premium substrates from commodity alternatives, with metal and wood constructions commanding measurable price premiums over polymer options.
- Wood:Solid hardwood and bamboo-epoxy composite substrates integrate carbon-sequestration marketing claims with moisture-resistant performance. Scandinavian and Pacific Northwest developers specify these materials at accelerating rates for kitchen casework.
- Metal:Powder-coated steel and aluminum systems deliver durability claims and aesthetic upgrade cycles. Extended producer responsibility frameworks in the EU favor metal constructions over disposable alternatives.
- Plastic:Injection-molded polymer containers and modular systems. REACH chemical restrictions are compelling reformulation of plastic finishes and adhesives for European market access.
- Glass:Tempered glass shelving and display storage for premium residential applications. Glass commands niche positioning in chef-grade kitchen specifications.
Wood and metal capture margin premiums. Plastic retains volume leadership in mass-market channels.
Application:
Customer type bifurcation between end-user consumers and specification professionals determines sales cycle length and technical documentation requirements.
- Residential:Direct-to-consumer sales of modular and custom systems for single-family and apartment installations. California Title 24 standards are concentrating specification authority with architectural firms rather than end-user consumers.
- Commercial:Food service and hospitality storage systems requiring sanitation compliance and ergonomic workflow optimization. Commercial applications demand higher load ratings and institutional-grade hardware.
- Modular:Standardized dimension systems for rapid installation in new construction and renovation. Subscription-based refresh programs in Copenhagen and Amsterdam are displacing traditional ownership models.
- Custom:Built-to-specification casework for non-standard kitchen dimensions and irregular wall planes. Legacy retrofit complexity creates field customization costs that compress margins.
Modular systems scale fastest. Custom work defends margin in premium tiers.
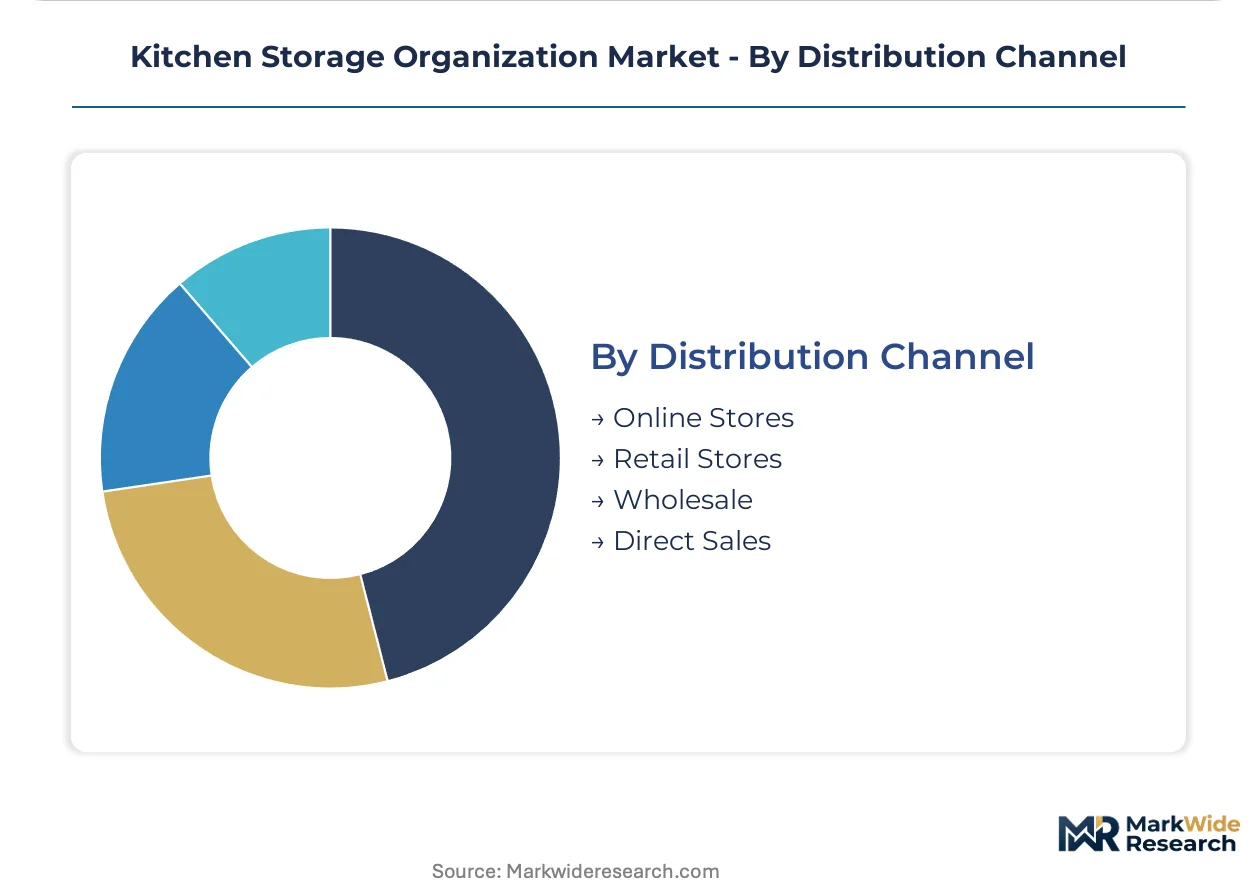
Distribution Channel:
Channel maturity varies sharply, with direct-to-consumer platforms compressing traditional retail intermediaries through flat-pack logistics innovation.
- Online Stores:Direct-to-consumer platforms leveraging advanced packaging engineering and last-mile optimization. E-commerce is reducing freight costs and damage rates for previously retail-dependent storage categories.
- Retail Stores:Specialty and mass-market brick-and-mortar channels with physical product curation and installation services. Retail concentration persists in markets where consumers demand tactile evaluation before purchase.
- Wholesale:Builder and contractor supply channels for new construction specification. Wholesale volumes track residential housing starts and renovation activity cycles.
- Direct Sales:Manufacturer-owned showrooms and design consultation services for premium custom installations. Direct channels capture full margin but require higher customer acquisition investment.
Online stores are gaining share fastest. Retail stores retain influence in complex purchase decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Design talent clusters in Copenhagen, Berlin, and Milan anchor kitchen storage innovation. These cities export modular system specifications to housing developers worldwide. Regional demand patterns diverge sharply between legacy retrofit markets and new construction corridors.
United States
California Title 24 building energy standards mandate built-in kitchen organization systems that reduce material waste in new residential construction. The EPA oversees formaldehyde emissions standards for composite wood products used in cabinet fabrication. Specification authority concentrates with architectural firms in Los Angeles and San Francisco rather than end-user consumers.
Germany
Compact kitchen design traditions align with EU Ecodesign Directive sustainability mandates, driving specification of space-efficient modular systems. REACH chemical restrictions compel manufacturers to reformulate finishes and adhesives for European market access. Production gravity centers on Baden-Württemberg and North Rhine-Westphalia, where hardware manufacturing clusters supply hinge and slide components.
India
Expanding metro apartment stock in Mumbai and Delhi-NCR creates whitespace for modular kitchen storage adapted to tropical humidity conditions. The PLI scheme incentivizes domestic manufacturing of engineered wood substrates and metal hardware. Bangalore and Pune are emerging as assembly hubs for flat-pack distribution to tier-2 cities.
Japan
Residential apartment dwellers in dense Tokyo and Osaka metropolitan clusters demand space-efficient modular configurations maximizing cubic efficiency. METI efficiency standards shape product specifications for domestic market entry. Manufacturing concentrates in Aichi Prefecture, where precision metalworking traditions support premium hardware production.
Netherlands
Subscription-based storage refresh programs in Amsterdam displace traditional ownership models among urban millennial cohorts. Strict security-deposit regulations penalize permanent fixture modifications, favoring modular rental systems. Rotterdam serves as the logistics hub for flat-pack distribution across Northern European markets.
Kitchen Storage Organization Market Competitive Landscape
Capital-heavy producers compete with asset-light designers and brand licensors across tiered market positions. The vendor base fragments between integrated substrate processors controlling particleboard supply and specialty assemblers sourcing components from Asian hardware clusters. Three archetypes dominate: flat-pack logistics specialists, premium custom casework fabricators, and direct-to-consumer platform operators. M&A activity targets complementary material capabilities, while strategic partnerships secure distribution access in underpenetrated housing corridors.
Among flat-pack logistics specialists, Inter IKEA Systems B.V. exemplifies the archetype through global retail footprint and packaging engineering. The Container Store and Williams-Sonoma, Inc. occupy differentiated positions on the specialty curation and premium aesthetic vectors respectively. These three anchors represent the structural split between accessible price tiers and design-forward specifications.
| Leading Market Players |
|---|
| Inter IKEA Systems B.V. |
| Newell Brands Inc. |
| The Container Store |
| Knape & Vogt Manufacturing Company |
| Rev-A-Shelf |
| Blum |
| OXO |
| Williams-Sonoma, Inc. |
| Sterilite Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap cabinet fabricators in Baden-Württemberg and North Rhine-Westphalia anchor supply discipline through multi-generational capital allocation that resists price wars despite particleboard cost volatility. Their ownership structure insulates pricing from quarterly earnings pressure while concentrating procurement leverage over Zhejiang hinge suppliers.
Pricing Analysis
The bundled-vs-unbundled service split separates installation-inclusive project pricing from flat-pack direct-to-consumer transactions. Three-tier pricing structure across premium, standard, and economy levels tracks material grade and California Air Resources Board certification tier. Cost compression in the economy tier is intensifying because resin chemistry fluctuations in composite wood substrates compress assembler margins. First-time apartment buyers in Berlin and Amsterdam exhibit highest price sensitivity, while Pacific Northwest premium developers show minimal elasticity for bamboo-epoxy composite specifications.
Supply Chain Analysis
Engineered wood substrate supply rests on German particleboard processors, Chinese MDF manufacturers in Shandong province, and Austrian laminate specialists. Hinge, slide, and connector hardware draws from Zhejiang and Guangdong manufacturing clusters. Single-source vulnerability concentrates in Asian hardware components where geopolitical friction threatens just-in-time delivery schedules. Distribution runs through Rotterdam logistics hubs for Northern European flat-pack fulfillment and direct-to-consumer platforms for North American e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification authority is migrating toward architectural firms and general contractors demanding chef-grade materials and design-forward aesthetics over commodity alternatives.
For Market Incumbents: Anticipate margin compression from subscription-based refresh programs displacing traditional ownership models in Copenhagen and Amsterdam. Consolidate position through backward integration into bamboo-epoxy composite substrate production in Scandinavia. Prioritize certification investment for California Title 24 compliance to capture new residential construction specification channels.
For New Entrants and Emerging Players: California Title 24 in the United States opens a window for built-in organization system specialists who can demonstrate material waste reduction through modular design. Target underpenetrated Indian metro apartment stock in Mumbai and Delhi-NCR with humidity-adapted engineered wood formulations. Pursue go-to-market partnerships with Bangalore and Pune assembly hubs for tier-2 city flat-pack distribution.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialty hardware assemblers lacking direct-to-consumer channel control. Long-term viability favors producers with captive supply of moisture-resistant substrates and REACH-compliant finishes. Watch for inflection when extended producer responsibility frameworks in the EU shift end-of-life collection costs onto original equipment manufacturers, favoring durable metal and solid wood constructions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bamboo-Epoxy Substrates | Captures carbon-sequestration marketing premiums in Pacific Northwest and Scandinavian specification channels. |
| REACH-Compliant Finish Reformulation | Secures European market access as ECHA restrictions tighten on hazardous substance thresholds. |
| Direct-to-Consumer Platform Launch | Bypasses retail intermediaries through Rotterdam-based flat-pack logistics optimization. |
| Smart Sensor Inventory Integration | Opens premium price tiers in tech-forward residential developments with IoT-enabled cabinet ecosystems. |
| Subscription-Based Refresh Program | Captures urban millennial demand in high-turnover rental markets with strict security-deposit regulations. |
Research Methodology
Direct dialogue with kitchen cabinet procurement managers at architectural firms, flat-pack logistics directors, composite wood substrate plant engineers, and retail category buyers combined with secondary validation from EPA formaldehyde emission filings, EU Ecodesign Directive documentation, California Air Resources Board regulatory databases, and customs trade records for particleboard and hardware imports. Bottom-up channel volume estimates triangulate against top-down construction spending allocations across residential and commercial application segments.
Segment-level value outputs across the analysis window reflect modeled projections for cabinets, shelves, racks, and bins by material substrate and distribution channel. Wood, metal, plastic, and glass material tiers intersect with online, retail, wholesale, and direct sales channels to generate install-base and replacement-cycle forecasts. CAGRs derive from housing start correlations, renovation activity indices, and e-commerce penetration trajectories in modular storage categories.
Revisions become necessary when California Title 24 enforcement intensity shifts, EU extended producer responsibility frameworks accelerate, or Asian hardware supply disruptions materialize. Forecasts reflect assumptions about continued urban density pressures and sustainability mandate alignment. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Cabinet & Furniture Drawer Slides Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
United Kingdom Home Decor Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market