
 Clothes Closets Market | 2026-2036
Clothes Closets Market Size, Share, and Industry Trends Forecast 2026-2036
Clothes Closets Market Analytics
The capital-intensity gap between mass-market flat-pack producers and custom-built closet specialists is collapsing as automated panel processing and CNC routing democratize precision manufacturing. IKEA leverages its global retail footprint and captive supply chains to sustain price leadership in ready-to-assemble wardrobes. California Closets competes through design consultation networks that anchor premium positioning in North American metropolitan markets.
Clothes closets are enclosed storage systems engineered to organize, protect, and display apparel through configurable shelving, hanging rods, and drawer assemblies typically fabricated from engineered wood substrates, extruded aluminum, or thermoformed polymers with load ratings between 15 and 50 pounds per linear foot. Their primary commercial purpose spans residential space optimization, retail merchandise presentation, and hospitality guest-room functionality. Modular closets lead product-type demand as consumers prioritize reconfigurable layouts for rental and compact dwellings. Wood materials dominate value capture in premium residential segments, while metal and composite substrates gain traction in commercial hospitality installations where durability standards exceed residential baselines.
ISO 9001 quality management frameworks govern manufacturing consistency across export-oriented producers, while the EU Ecodesign Directive and California Air Resources Board composite wood emissions standards shape material specifications and market access for cross-border suppliers. The US EPA formaldehyde emission limits and China's GB standards for indoor air quality collectively constrain substrate sourcing decisions for multinational brands. Stakeholders must monitor evolving circular-economy packaging mandates and digital design-to-installation platforms that are compressing project timelines and reshaping contractor relationships.
Market Dynamics
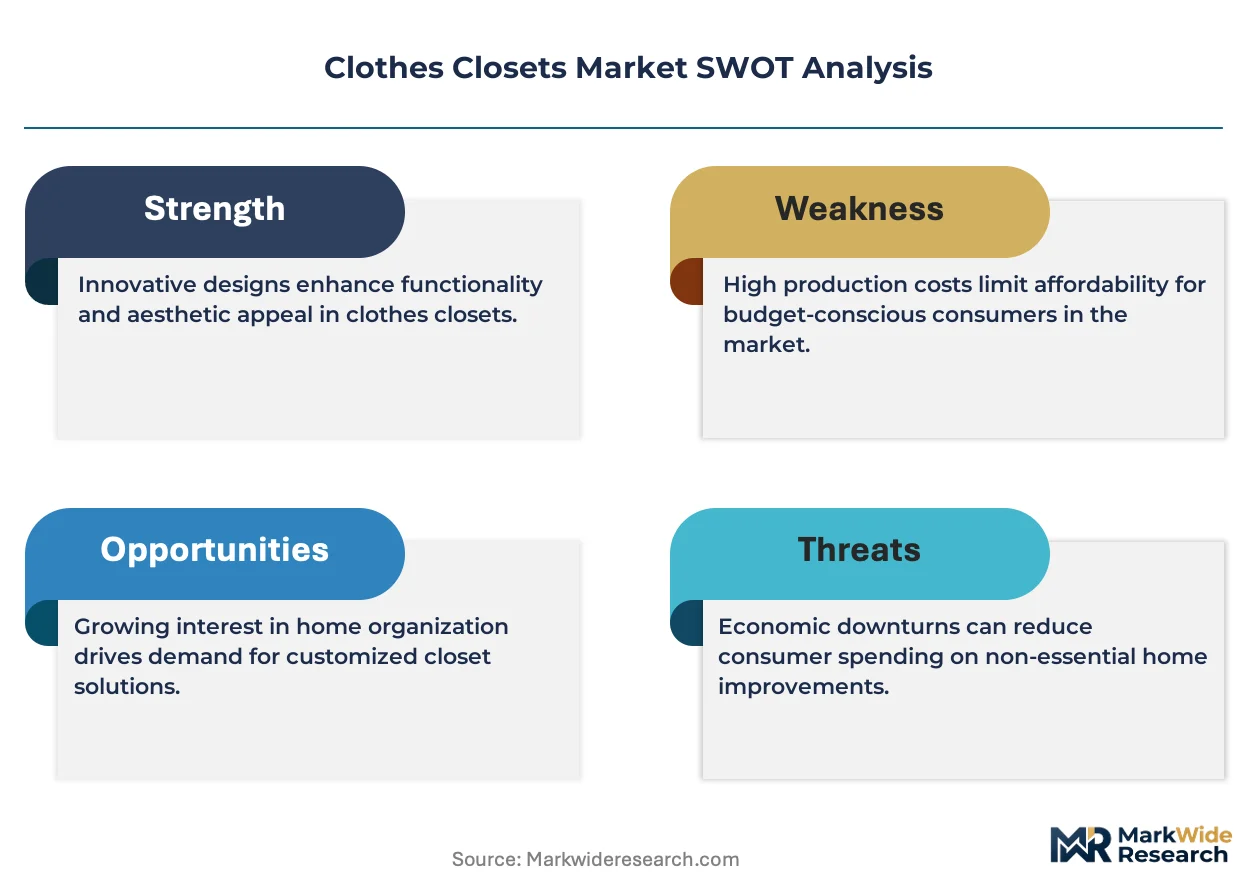
Automated panel processing and CNC routing are collapsing the capital barrier between mass-market flat-pack and custom-built closet production, forcing incumbents to defend margin positions through design consultation networks rather than manufacturing scale alone.
Growth Catalysts
- California Title 24 standards:Building energy codes mandating efficient space utilization accelerate built-in storage adoption in new residential construction across the state.
- Urban apartment densification:Shrinking living spaces in metropolitan China drive demand for modular, reconfigurable closet systems optimized for rental flexibility.
- Engineered wood substrates:Advances in moisture-resistant particleboard and medium-density fiberboard enable thinner, stronger panel construction at lower material cost.
Market Restraints
- Formaldehyde emission compliance:US EPA and EU Ecodesign Directive limits on composite wood emissions constrain substrate sourcing and raise qualification costs for cross-border suppliers.
- Aluminum price volatility:Extruded aluminum frame components face input cost swings tied to energy-intensive smelting operations and regional electricity tariffs.
- Flat-pack logistics concentration:IKEA's captive supply chains and retail footprint create procurement scale advantages that compress margin recovery for competing ready-to-assemble producers.
Strategic Opportunities
- India residential construction:Underpenetrated built-in storage adoption in urbanizing tier-2 cities offers first-mover positioning before local manufacturing scales.
- Digital design-to-installation platforms:Software integrating 3D visualization with automated cut-list generation compresses project timelines and displaces traditional contractor relationships.
- Circular-economy packaging mandates:EU and California regulations driving recyclable, reduced-waste delivery formats favor regional producers with localized fulfillment networks.
Industry Challenges
- Skilled installation labor scarcity:Certified closet system installers command premium wages in dense metropolitan markets, constraining service expansion velocity.
- ISO 9001 certification timelines:Quality management framework implementation delays market access for export-oriented producers targeting EU and North American retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clothes Closets Market |
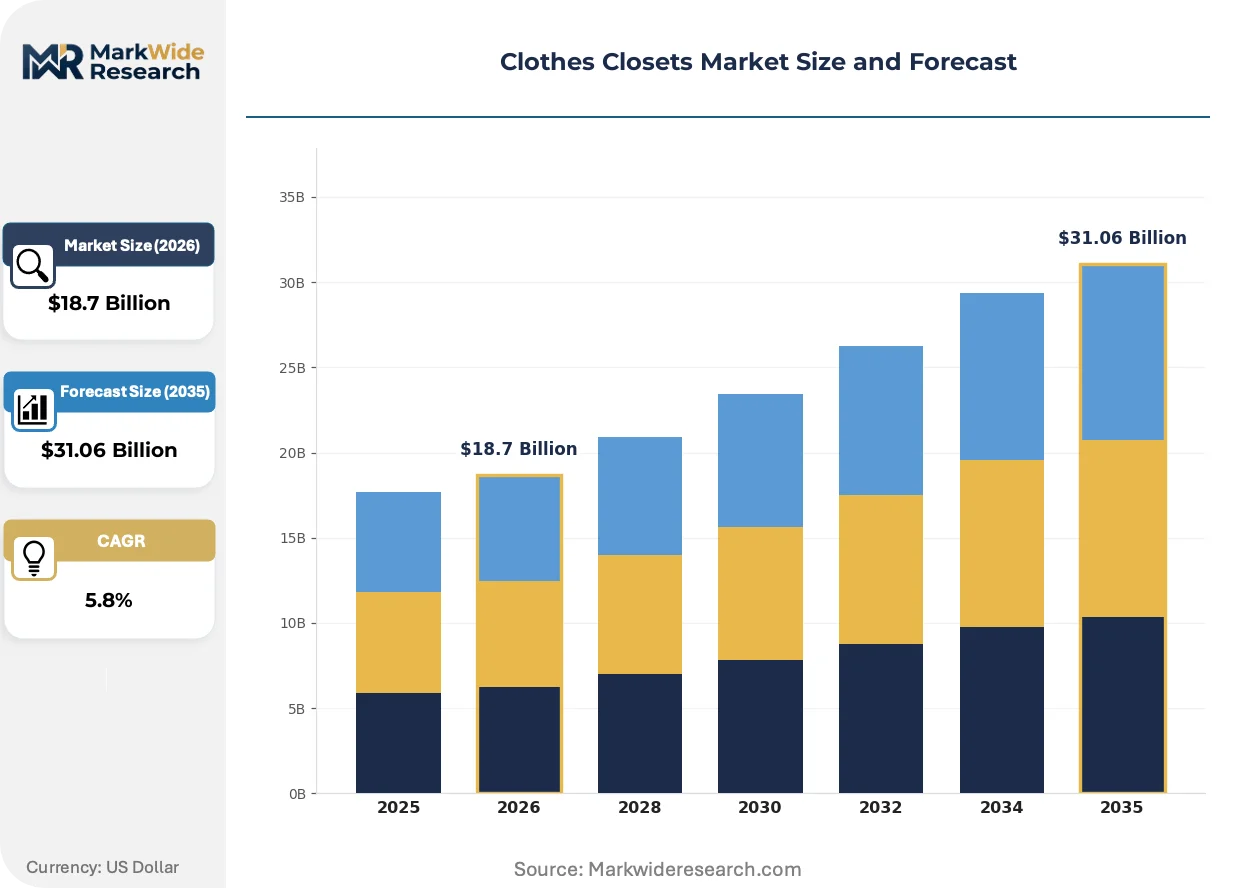
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-in Closets, Reach-in Closets, Wardrobes, Modular Closets Material: Wood, Metal, Plastic, Composite End User: Residential, Commercial, Retail, Hospitality Design Style: Contemporary, Traditional, Minimalist, Eclectic |
| Companies Covered | IKEA, Stanley, Sauder Woodworking, Oppein Home Group, Molteni, California Closets, Suofeiya, Holike, Shangpin Home, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clothes Closets Market Evolving Landscape
Three intersecting forces—manufacturing automation, emissions compliance tightening, and rental-market procurement evolution—are restructuring how closet systems are specified, produced, and delivered across residential and commercial end-uses.
Thermoformed polymer shelving and drawer fronts are fragmenting the traditional wood-dominant material mix in mid-market residential segments. Property developers in China's Pearl River Delta specify these substrates for standardized apartment fit-outs where cost predictability outweighs premium aesthetics. The shift enables faster production cycles but compresses supplier differentiation to hardware and finish options alone.
REACH chemical restrictions and the EU Ecodesign Directive are tightening material specifications for composite wood products sold in European markets. Manufacturers must reformulate adhesives and surface treatments to maintain market access, with certification costs disproportionately burdening small and mid-cap producers. German and French retail channels now require third-party emissions testing documentation as a procurement prerequisite.
Corporate housing operators and build-to-rent developers are unbundling closet system specification from general contractor procurement, establishing direct relationships with modular furniture specialists. This channel disintermediation is most advanced in London and New York metropolitan areas where institutional rental ownership concentrates purchasing power. Traditional distributor networks face margin compression as volume shifts to project-direct contracts with 36-48 month lifecycle commitments.
Clothes Closets Market Segmentation
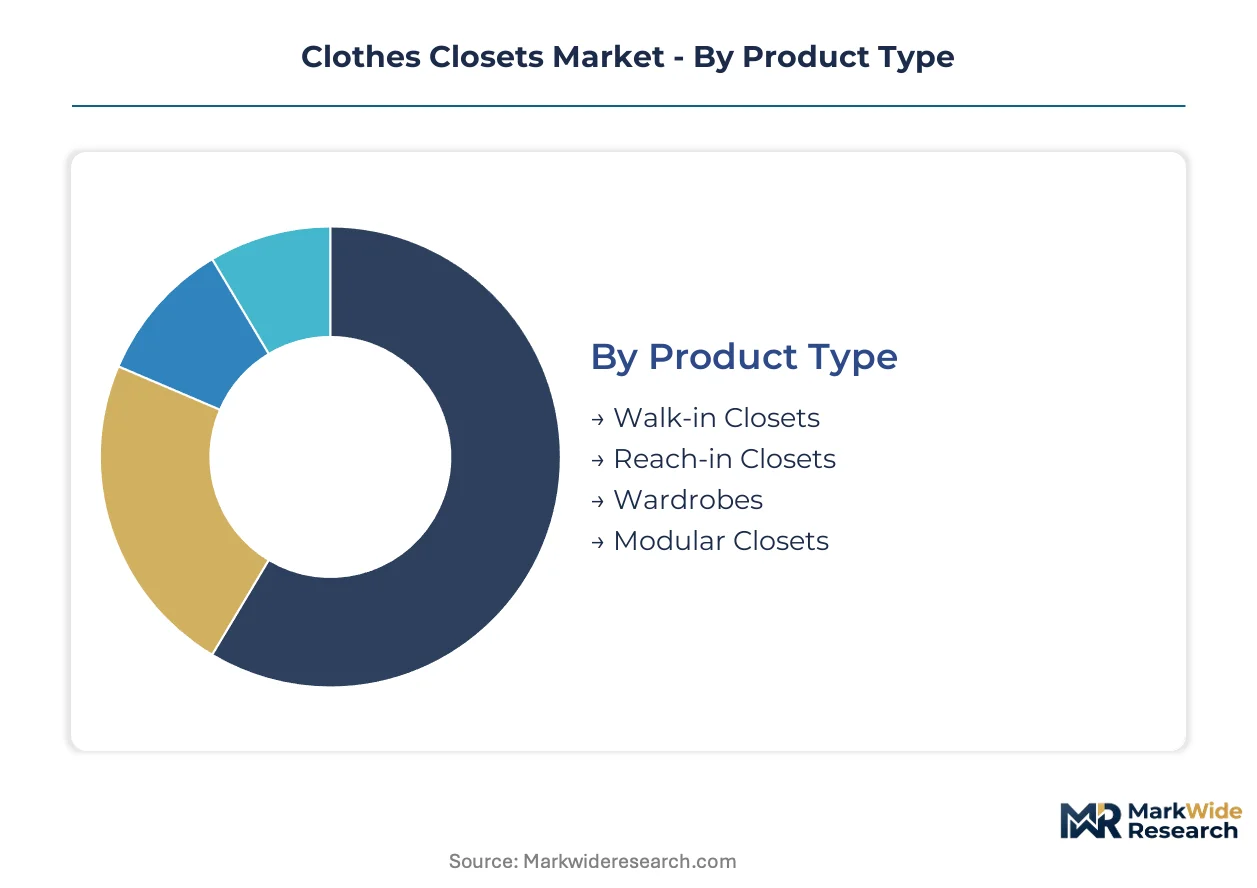
Closet system specifications diverge sharply across end-use contexts, with regulatory emissions standards and installation labor constraints creating tiered market access barriers. Material choices and product architectures determine which producers can serve premium residential versus high-volume commercial contracts.
Product Type:
California Title 24 energy standards and similar building codes in Germany and China favor built-in configurations that optimize floor-area ratio in dense urban construction.
- Modular Closets:Reconfigurable panel-and-hardware systems engineered for tool-free assembly and disassembly. Demand concentrates in China's tier-1 cities and New York metropolitan rentals where lease turnover drives procurement cycles. GB standards for indoor air quality and CARB emissions limits constrain substrate selection for cross-border suppliers.
- Walk-in Closets:Permanent built-in installations requiring structural integration with wall and flooring systems. High-end residential developments in California and London specify these for master suite differentiation. EPA formaldehyde limits and EU Ecodesign Directive compliance add qualification costs that filter out smaller fabricators.
- Reach-in Closets:Shallow-depth enclosures optimized for corridor and secondary bedroom placement.
- Wardrobes:Freestanding furniture-style units with finished exterior panels.
Modular closets handle the majority of throughput; walk-in closets are gaining share fastest in premium residential new construction.
Material:
Cost tier differentiation separates commodity suppliers from certified producers capable of meeting multi-jurisdiction emissions protocols.
- Wood:Engineered substrates—moisture-resistant particleboard and medium-density fiberboard—dominate value capture in premium segments. CARB Phase 2 and EPA TSCA Title VI limits on formaldehyde emissions force adhesive reformulation, raising costs for North American and European market entry. Solid hardwood and veneer-wrapped panels anchor luxury residential specifications in Germany and Japan.
- Metal:Extruded aluminum framing and wire shelving systems serve commercial hospitality and retail fixtures where load ratings exceed residential baselines. Energy-intensive smelting operations tie input costs to regional electricity tariffs, creating margin volatility for producers without long-term supply contracts.
- Composite:Thermoformed polymer and mineral-composite panels gaining traction in standardized multifamily fit-outs.
- Plastic:Injection-molded components for budget-tier accessories and hardware housings.
Wood materials command the highest unit economics; metal systems are expanding most quickly in commercial hospitality retrofit cycles.
End User:
Customer type determines installation complexity, with direct-to-developer procurement displacing traditional distributor channels in institutional rental ownership.
- Residential:Single-family and multifamily owner-occupied dwellings specifying built-in storage for space optimization. California's Title 24 standards and similar codes in British Columbia accelerate adoption in new construction. Design consultation networks anchor premium positioning in metropolitan markets with scarce certified installation labor.
- Commercial:Corporate housing operators and build-to-rent developers establishing direct supplier relationships. London and New York institutional owners concentrate purchasing power through 36-48 month lifecycle contracts that bypass traditional distribution.
- Retail:Merchandise presentation systems requiring adjustable configurations for seasonal turnover.
- Hospitality:Guest-room functionality standards driving durability-focused material specifications.
Residential end users generate the largest absolute volume; commercial direct procurement is climbing the fastest as institutional ownership concentrates.
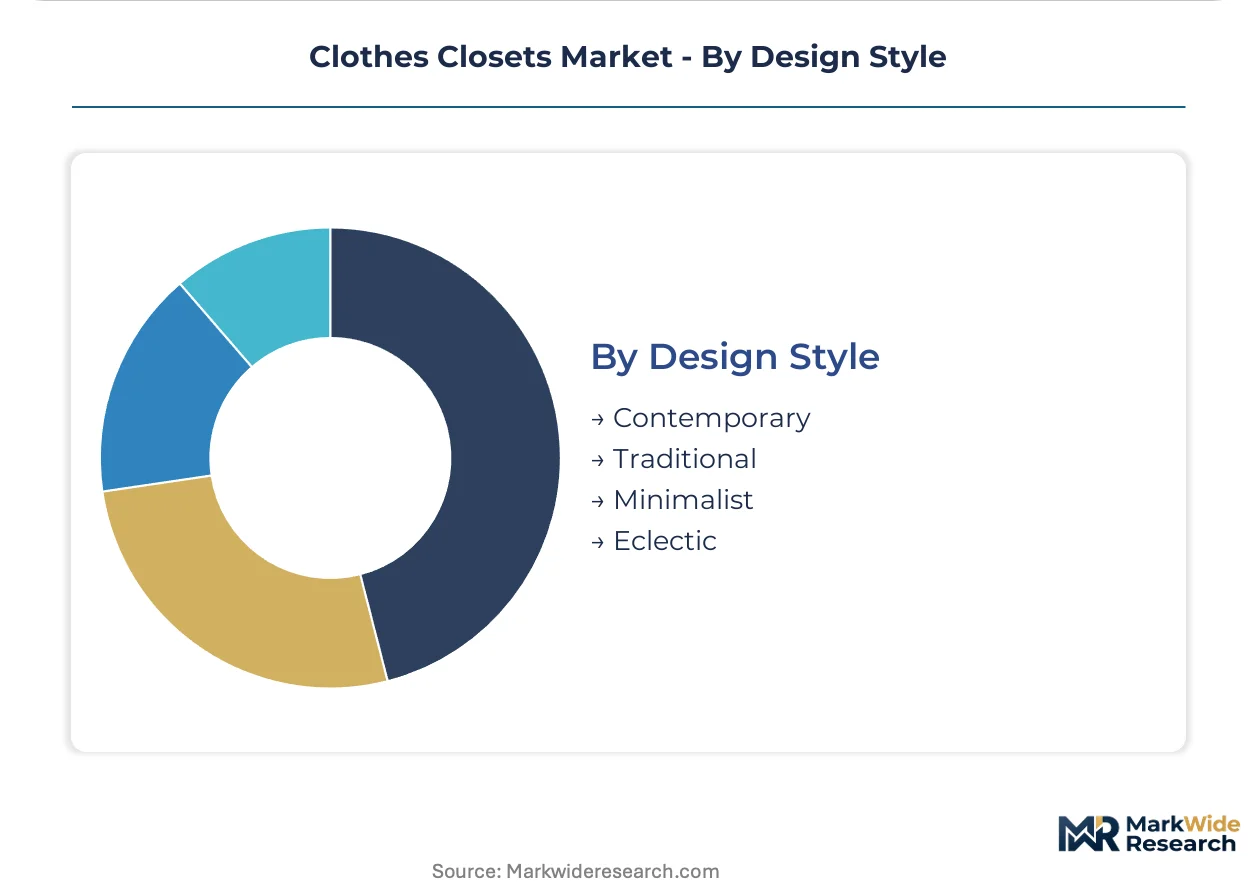
Design Style:
Regional aesthetic preferences and local manufacturing capabilities shape which styles achieve production scale.
- Contemporary:Clean lines, frameless construction, and integrated lighting systems. German and Italian manufacturers lead technical execution, with Chinese producers scaling cost-competitive alternatives for domestic and export markets. Flat-pack logistics favor panel-minimal designs that reduce shipping cube.
- Minimalist:Open-concept hanging systems and reduced enclosure volumes. Japanese residential architecture and Nordic influence drive specification in compact urban dwellings where visual lightness outweighs storage density.
- Traditional:Raised-panel doors, crown molding, and decorative hardware profiles.
- Eclectic:Mixed-material assemblies and customizable finish combinations.
Contemporary styling handles the majority of new construction specification; minimalist designs are gaining share fastest in rental-market renovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's tier-1 cities show the lowest price elasticity as premium residential developments absorb cost premiums for certified substrates, while India's emerging urban markets remain acutely sensitive to landed cost differentials between local and imported panel systems.
United States
California's Title 24 building energy standards mandate efficient space utilization in new residential construction, accelerating built-in storage adoption across the state's metropolitan corridors. EPA TSCA Title VI formaldehyde emission limits constrain substrate sourcing for cross-border suppliers, elevating qualification costs for entry. The Los Angeles-San Diego corridor anchors premium closet system demand as multifamily developers specify CARB-compliant engineered wood for master suite installations.
China
Urban apartment densification in Shanghai, Beijing, and Shenzhen drives procurement of modular, reconfigurable closet systems optimized for rental turnover and compact floor plans. GB standards for indoor air quality and composite wood emissions shape material specifications for domestic and export-bound production. The Pearl River Delta manufacturing cluster—anchored by Guangzhou and Shenzhen—hosts the densest concentration of panel processing and CNC routing capacity serving both domestic fit-out and international flat-pack export channels.
Germany
REACH chemical restrictions and the EU Ecodesign Directive tighten material specifications for composite wood products, forcing adhesive reformulation among suppliers targeting German retail channels. The country's national building energy regulator enforces stringent efficiency standards that favor built-in storage in new construction. The Stuttgart-Munich industrial corridor concentrates precision manufacturing of frameless contemporary systems, with Bavarian fabricators leading technical execution for premium residential export markets.
United Kingdom
Institutional build-to-rent ownership in London concentrates purchasing power through direct supplier relationships, bypassing traditional distribution networks for 36-48 month lifecycle contracts. The country's national emissions trading scheme and building regulations push material transparency in residential fit-outs. Greater London's corporate housing operators unbundle closet specification from general contractor procurement, establishing project-direct contracts with modular furniture specialists.
India
Underpenetrated built-in storage adoption in urbanizing tier-2 cities offers positioning opportunities before local manufacturing scales to serve price-sensitive residential construction. The Bureau of Indian Standards governs quality benchmarks for imported panel systems, though enforcement remains uneven across states. The Mumbai-Pune and Delhi-NCR corridors concentrate demand from mid-market apartment developers seeking cost-competitive modular alternatives to carpentry-on-site installation.
Clothes Closets Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding captive supply chains and retail footprints while the latter defend margin positions through design consultation networks and certified installation capabilities. The market structure reflects this bifurcation: flat-pack producers leverage procurement scale advantages against custom-built specialists who anchor premium positioning in metropolitan markets with scarce certified labor. Three archetypes dominate—global retail-format operators, regional panel-processing specialists, and design-forward consultation networks. Competitive moves concentrate on geographic expansion into underpenetrated urbanizing markets and backward integration into substrate production to offset aluminum and engineered wood cost volatility.
Among Asia-Pacific-based fabricators, Oppein Home Group, Suofeiya, and Holike occupy positions within the regional specialist tier, each representing the scale-driven archetype that has consolidated domestic supply chain relationships to serve China's dense urban corridor demand. These Chinese producers exemplify the capital-efficient panel-processing model that automated CNC routing has democratized, enabling precision manufacturing at cost points that compete with mass-market flat-pack alternatives. Their positioning reflects the broader industry shift where manufacturing scale alone no longer guarantees defensible margins, and where design consultation capabilities increasingly separate premium-tier competitors from commodity substrate suppliers.
| Leading Market Players |
|---|
| IKEA |
| Stanley |
| Sauder Woodworking |
| Oppein Home Group |
| Molteni |
| California Closets |
| Suofeiya |
| Holike |
| Shangpin Home |
| Others |
Value Network & Pricing Analysis
Panel-processing scale economies in China's Pearl River Delta compress unit costs for engineered wood substrates, creating price floors that smaller regional fabricators cannot match without sacrificing CARB Phase 2 or EPA TSCA Title VI compliance margins. This concentration of CNC routing capacity simultaneously anchors global supply availability and exerts downward pressure on mid-market pricing tiers.
Pricing Analysis
Installation service contracts and extended warranty coverage drive lifetime value for custom closet specialists, with project-based pricing stratifying across premium, standard, and economy tiers based on substrate certification grade and design consultation depth. Price differentiation hinges on CARB compliance tier and volume scale, with cost compression in ready-to-assemble segments intensifying due to IKEA's captive procurement advantages. Margins are tightening for non-certified entrants as formaldehyde emission standards elevate qualification barriers. Commercial build-to-rent developers show lowest price sensitivity, while India's tier-2 residential buyers remain most acutely responsive to landed cost differentials.
Supply Chain Analysis
China and Germany anchor global panel processing and precision manufacturing respectively, with Vietnam emerging as a secondary hub for flat-pack assembly and export logistics. The industry draws from engineered wood substrates, extruded aluminum framing, and thermoformed polymer resins as core inputs. Single-source vulnerability concentrates in China's Pearl River Delta manufacturing cluster, where energy-intensive smelting operations tie aluminum component costs to regional electricity tariffs. Distribution runs through project-direct contracts with institutional developers, bypassing traditional wholesale channels in London, New York, and Shanghai metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as urban apartment densification across China's tier-1 cities and India's emerging metros accelerates built-in storage penetration before local manufacturing scales to saturation.
For Market Incumbents: Shield margin positions by deepening backward integration into moisture-resistant particleboard production and securing long-term aluminum supply contracts to offset energy tariff volatility. Design consultation networks remain the priority defensive lever against automated panel-processing democratization that erodes manufacturing-scale advantages.
For New Entrants and Emerging Players: Anchor in India's underpenetrated tier-2 cities where carpentry-on-site still dominates residential fit-outs, offering cost-competitive modular alternatives with localized installation partnerships. Direct-to-developer procurement channels in corporate housing and build-to-rent segments provide the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among design-forward consultation networks with certified installation capabilities in metropolitan markets with scarce skilled labor. Long-term viability favors acquisition targets with established ISO 9001 frameworks and multi-jurisdiction emissions compliance infrastructure. The signal to watch is acceleration of project-direct contract volumes with 36-48 month lifecycle commitments in London and New York institutional ownership.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive engineered wood supply insulates margins from CARB compliance cost volatility. |
| Digital Design-to-Installation Platform Launch | 3D visualization software compresses project timelines and displaces traditional contractor relationships. |
| Certified Installation Network Expansion | Scarce skilled labor in dense metros commands premium positioning for quality-assured service delivery. |
| Direct Developer Partnership Program | Project-direct contracts with build-to-rent operators bypass distributor margin compression. |
| Circular-Economy Packaging Transition | EU and California recyclable delivery mandates favor regional producers with localized fulfillment networks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with closet system manufacturers, certified installation contractors, multifamily developers, and retail channel buyers; and secondary validation through customs trade records, EPA and CARB regulatory filings, and SEC disclosures from publicly traded furniture producers. Bottom-up demand modeling triangulated against top-down construction permit data and residential square footage trends across the analysis window.
Across the projection horizon, the analytical framework segmented volume and value outputs by product architecture, material substrate, end-use application, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for policy inflection points including Title 24 adoption timelines and EU Ecodesign Directive implementation phases. Modeled inputs incorporated urban apartment construction permits, rental turnover rates, and certified installer wage indices as industry-specific demand proxies.
Underlying assumptions cover sustained urban densification trends and emissions standard enforcement continuity, with deviation risk concentrated in aluminum price volatility and trade policy shifts affecting cross-border substrate sourcing. Recalibration cycles align with material shifts in building energy code adoptions and automated manufacturing technology diffusion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Kitchen Storage Organization Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
United Kingdom Home Decor Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Smart Shoe Cabinet Market