
 Deluge Valve Market | 2026-2036
Deluge Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Deluge Valve Market Analysis
The EU Green Deal is decoupling fire suppression procurement from legacy carbon-intensive supply chains, pushing industrial buyers toward certified low-emission deluge valve systems. Johnson Controls leverages its building technology integration to capture commercial and industrial retrofit cycles. Viking Group Inc. anchors its position through specialized marine and offshore product lines. Victaulic competes on grooved mechanical joining expertise that reduces installation labor in large-scale fire protection projects.
A deluge valve is a hydraulically or pneumatically actuated control valve designed to open fully upon fire detection, releasing water or foam through an open piping network without fusible elements at individual outlets; typical units operate at pressures ranging from 175 to 300 psi and incorporate corrosion-resistant bronze or ductile iron bodies with stainless steel trim. Electromechanical actuation leads product type demand due to faster response integration with addressable fire alarm panels, while pneumatic variants retain share in explosion-risk zones where electrical ignition must be eliminated. Floor mounted installation dominates industrial facilities where maintenance access and seismic bracing requirements favor ground-level valve assemblies.
NFPA standards in the United States, EN 12259 European product norms, and BIS fire safety certifications in India collectively define pressure ratings, flow coefficients, and material compliance thresholds that determine market access for manufacturers. The EPA and OSHA jointly influence demand through process safety management rules that mandate tested deluge coverage for flammable liquid handling areas. Stakeholders must monitor evolving harmonization between regional certification regimes to avoid duplication in multi-country project bids.
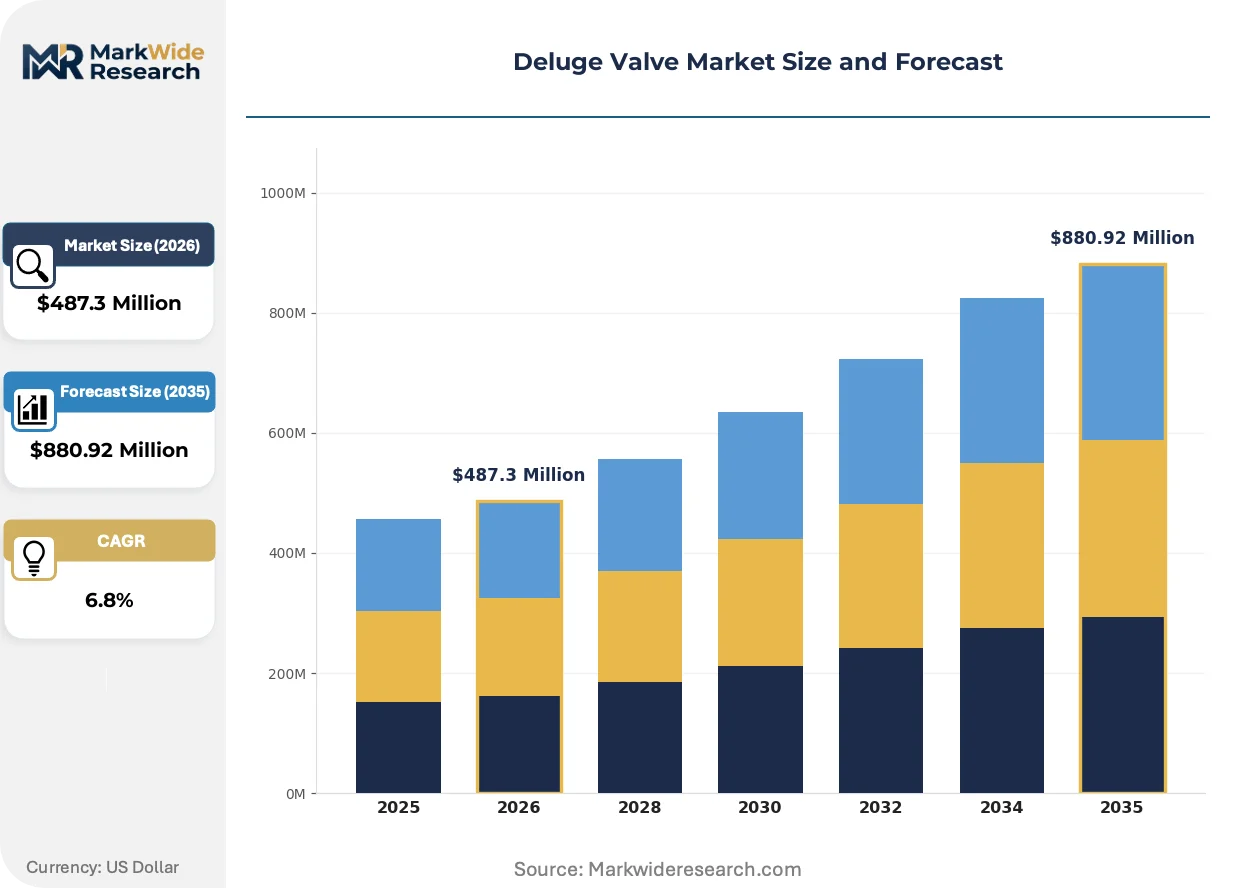
Market Dynamics
The Deluge Valve Market is undergoing structural recalibration as the EU Green Deal forces industrial buyers to decouple from carbon-intensive supply chains, creating procurement friction between legacy certification paths and emerging low-emission standards.
Growth Catalysts
- Offshore Expansion:Gulf of Mexico and North Sea oil and gas platforms are mandating deluge coverage for hazardous area fire suppression, driving specification upgrades across floating production units.
- REACH Compliance:European chemical manufacturers must retrofit flammable liquid handling areas with tested deluge systems under tightened process safety management rules.
- Electromechanical Integration:Addressable fire alarm panels are accelerating specification of electronically actuated valves over pneumatic alternatives in non-explosion-risk zones.
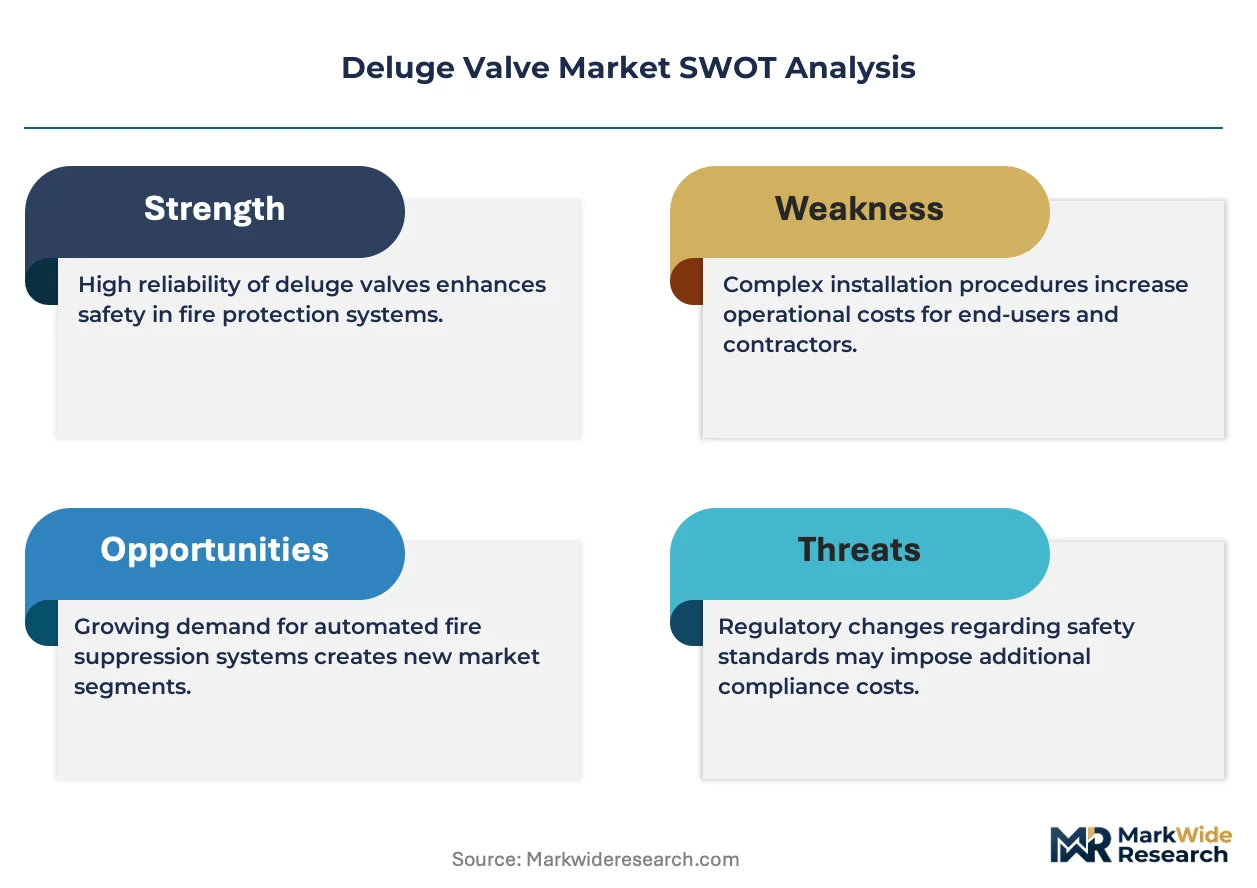
Market Restraints
- Bronze Input Volatility:Corrosion-resistant valve body materials face price instability tied to copper and tin commodity swings, compressing margin predictability for ductile iron alternatives.
- Certification Duplication:Divergent NFPA 16, EN 12259, and BIS testing protocols force manufacturers to maintain parallel validation tracks for multi-country project bids.
- Seismic Bracing Costs:Floor-mounted installations in earthquake-prone zones require expensive structural reinforcement that pneumatic retrofits often cannot accommodate.
Strategic Opportunities
- Indian Industrial Corridor:Petroleum, Chemicals and Petrochemicals Investment Regions along Gujarat and Andhra Pradesh coastlines lack adequate fire suppression infrastructure.
- CE-MDR Convergence:Harmonized pressure equipment and medical device regulations in Europe create single-certification pathways for valves serving pharmaceutical cleanrooms.
- Digital Twin Integration:IoT-enabled valve monitoring converging with building management systems opens predictive maintenance revenue streams in commercial retrofit cycles.
Industry Challenges
- Hydraulic Engineer Scarcity:Specialized expertise in pneumatic-to-electromechanical conversion is concentrating among aging technician cohorts in marine servicing hubs.
- Legacy Piping Compatibility:Grooved mechanical joining standards from Victaulic and competing systems create specification lock-in that complicates multi-vendor project execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deluge Valve Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Hydraulic, Pneumatic, Manual Installation Type: Floor Mounted, Wall Mounted, Ceiling Mounted, Outdoor End User: Industrial Facilities, Warehouses, Power Plants, Commercial Buildings Delivery Mode: Direct Sale, Online Retail, Distributor Networks, Others |
| Companies Covered | Johnson Controls, Viking Group Inc., Victaulic, BERMAD, NAFFCO, Reliable Automatic Sprinkler, Cla-Val, HD Fire Protect, Minimax GmbH & Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deluge Valve Market Emerging Trajectories
Smart actuation and material science are compressing traditional valve lifecycles while regulatory fragmentation forces buyers into parallel compliance investments across certification regimes.
Stainless steel trim configurations are absorbing specification share from bronze alternatives as offshore salt-exposure durability becomes non-negotiable. North Sea platform operators are adopting these variants on compressed replacement cycles. The technology is absorbing maintenance budget allocations that previously covered corrosion-related field repairs.
EPA process safety management rules are tightening deluge coverage mandates for flammable liquid storage above threshold quantities. Chemical terminals along the Houston Ship Channel are expanding system footprints to meet revised risk assessment protocols. Terminal operators are responding by consolidating valve procurement under single-source agreements to streamline compliance documentation.
Buyer concentration among integrated energy majors is compressing vendor negotiation leverage. Engineering-procurement-construction firms are unbundling valve supply from installation contracts, forcing manufacturers to compete on component pricing rather than system integration. This pattern is most visible in Gulf Coast petrochemical expansions where owner-operators have centralized technical specifications.
Deluge Valve Market Segmentation
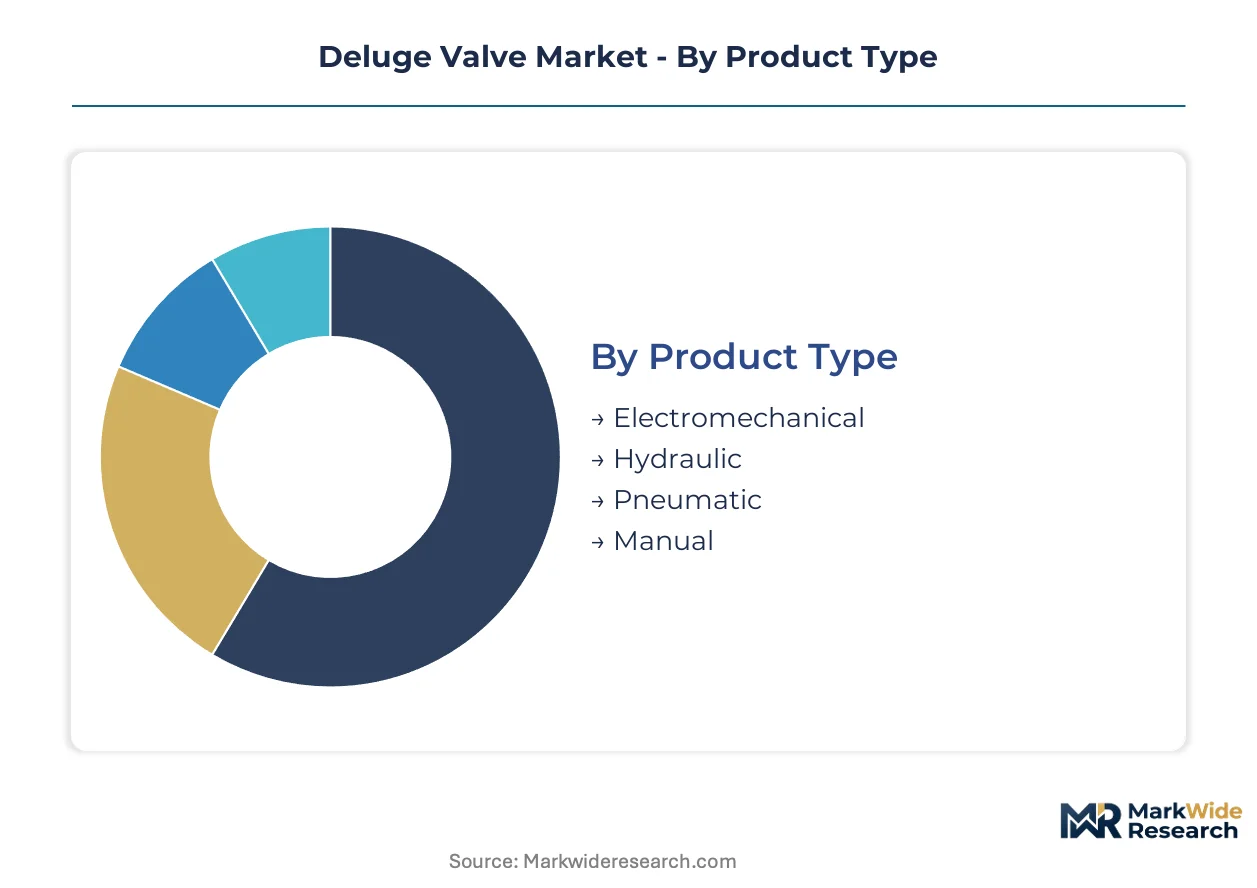
Deluge valve procurement cycles diverge sharply across actuation technologies and facility types, forcing manufacturers to align product portfolios with distinct replacement timelines and compliance triggers. Specification patterns in offshore energy, chemical processing, and commercial retrofit each demand tailored valve configurations.
Product Type:
Upgrade cycles favor electromechanical systems in facilities modernizing fire alarm integration, while pneumatic retention persists in explosion-risk zones where electrical ignition hazards override response speed advantages.
- Electromechanical:Electronic actuation interfaces directly with addressable fire alarm panels through low-voltage signaling, enabling sub-second response coordination. Gulf Coast petrochemical terminals specify these units for non-classified areas under EPA process safety management mandates, though salt-air corrosion accelerates stainless steel trim replacement schedules.
- Hydraulic:Pressure-balanced piston mechanisms operate independently of external power, maintaining fail-safe functionality during electrical outages. North Sea platform operators favor hydraulic systems for subsea equipment enclosures where actuator sealing integrity determines operational lifespan.
- Pneumatic:Compressed air actuation eliminates ignition sources in Zone 1 hazardous areas per ATEX directives.
- Manual:Mechanical pull-station override provides backup activation for maintenance isolation procedures.
Electromechanical sits at the top of the volume ranking, with hydraulic climbing the fastest as offshore durability specifications tighten.
Installation Type:
Facility engineering constraints and seismic code variations create divergent hardware requirements across mounting configurations, with floor assemblies dominating capital-intensive industrial greenfield projects.
- Floor Mounted:Ground-level valve assemblies accommodate seismic bracing requirements and maintenance access in heavy industrial environments. California refineries and Japan chemical complexes specify floor-mounted configurations to meet stringent earthquake resistance standards without overhead structural loading.
- Wall Mounted:Vertical surface mounting conserves floor space in congested process areas and enables gravity drainage of test water. European pharmaceutical cleanrooms prefer wall installations to preserve classified floor space and simplify CIP protocol compliance.
- Ceiling Mounted:Overhead positioning suits atrium protection and aircraft hangar applications where floor obstructions are unacceptable.
- Outdoor:Weatherized enclosures with heated valve chambers protect against freeze damage in arctic pipeline stations.
Floor mounted commands the largest installed base, while outdoor configurations gain share fastest from pipeline infrastructure expansion.
End User:
Process hazard classification and insurance underwriting intensity create tiered specification standards across facility types, with industrial buyers demanding the most rigorous certification documentation.
- Industrial Facilities:Chemical processing, oil and gas, and heavy manufacturing operations require deluge coverage for flammable liquid handling areas above EPA threshold quantities. Texas and Louisiana petrochemical corridors drive specification volume through combined EPA and OSHA process safety management enforcement.
- Power Plants:Turbine hall protection and transformer oil containment demand high-flow deluge systems with foam compatibility. Indian ultra-mega power projects along coastal Gujarat specify corrosion-resistant variants for coastal humidity exposure.
- Warehouses:High-piled storage protection focuses on commodity classification and sprinkler system integration rather than standalone deluge deployment.
- Commercial Buildings:Atrium smoke control and architectural feature protection represent niche applications with limited specification frequency.
Industrial facilities anchor procurement volume, with power plants expanding most quickly from capacity additions in Asia-Pacific coastal zones.
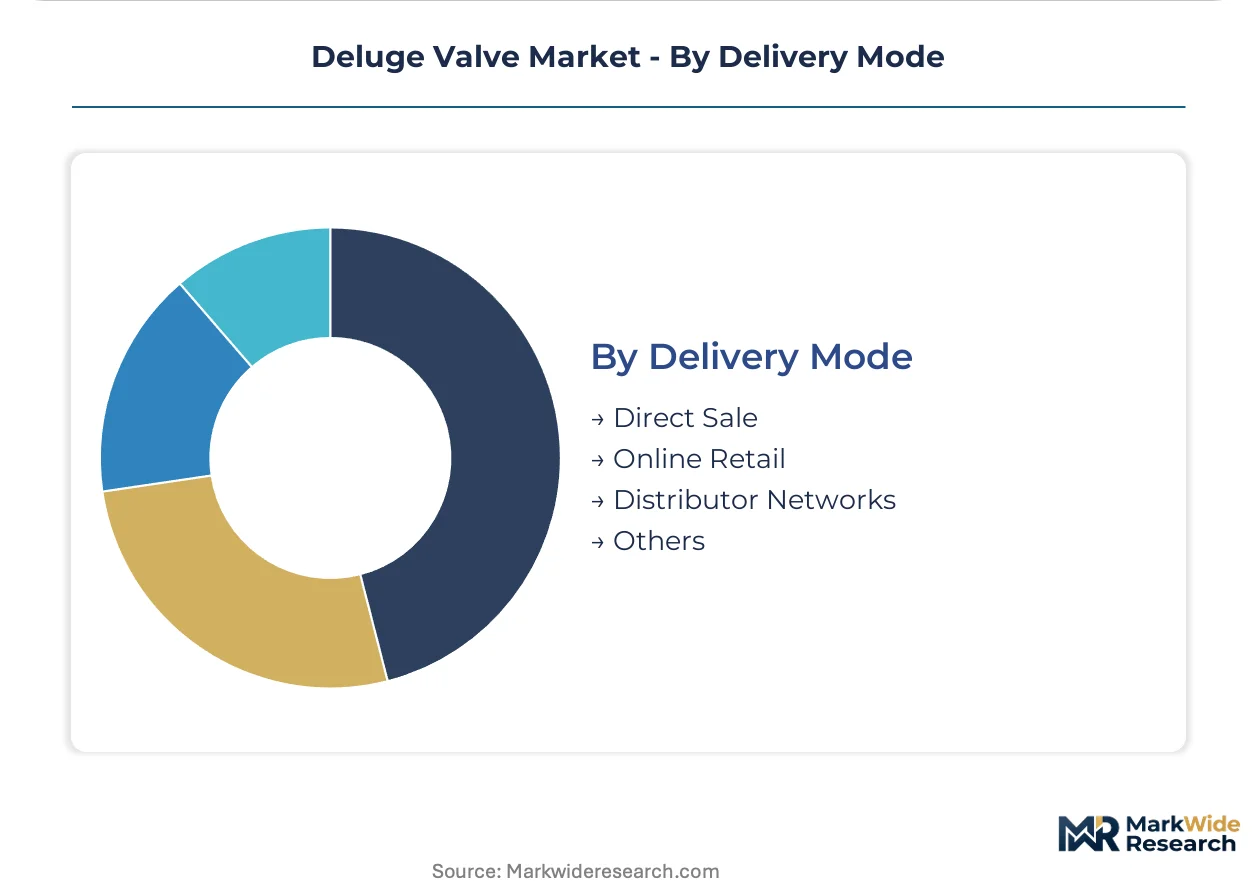
Delivery Mode:
Procurement channel selection tracks project scale and technical support requirements, with integrated energy majors consolidating supply under framework agreements to streamline compliance documentation.
- Direct Sale:Manufacturer-direct procurement serves large owner-operators with centralized engineering standards and recurring replacement programs. Saudi Aramco and ADNOC maintenance divisions negotiate direct supply contracts to secure dedicated technical support and batch-consistent certification packages.
- Distributor Networks:Regional stocking distributors provide local inventory and field service capabilities for mid-size contractors. U.S. Gulf Coast fire protection contractors rely on distributor networks for same-day valve availability during turnaround maintenance windows.
- Online Retail:E-commerce channels capture small replacement orders and standard catalog configurations with minimal customization.
- Others:Engineering-procurement-construction consortium arrangements bundle valve supply with installation and commissioning services.
Direct sale leads transaction value, with distributor networks gaining ground fastest among regional contractor bases seeking localized support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hydraulic engineers and marine fire protection technicians concentrate in Houston, Aberdeen, and Singapore, anchoring regional service capabilities for offshore deluge system deployment.
United States
Gulf Coast petrochemical terminals and offshore platform operators drive specification volume through combined EPA and OSHA process safety enforcement. The EPA mandates tested deluge coverage for flammable liquid handling above threshold quantities. Texas and Louisiana chemical corridors see terminal operators consolidating valve procurement under single-source agreements to streamline compliance documentation.
Norway
North Sea floating production units and subsea equipment enclosures demand corrosion-resistant stainless steel trim configurations. Norwegian regulators enforce stringent offshore safety standards through the Petroleum Safety Authority. Stavanger and Bergen serve as technical hubs where platform operators compress replacement cycles for salt-exposure durability.
Germany
Chemical manufacturers face REACH compliance deadlines for retrofitting flammable liquid handling areas with certified deluge systems. The EU Green Deal tightens emissions standards for industrial fire protection equipment procurement. Ludwigshafen and Leverkusen chemical clusters see buyers decoupling from carbon-intensive supply chains toward low-emission valve specifications.
India
Petroleum, Chemicals and Petrochemicals Investment Regions along Gujarat and Andhra Pradesh coastlines lack adequate fire suppression infrastructure. BIS fire safety certifications determine market access for manufacturers bidding on industrial projects. Hazira and Visakhapatnam industrial zones see ultra-mega power projects specifying corrosion-resistant variants for coastal humidity exposure.
United Arab Emirates
ADNOC maintenance divisions negotiate direct supply contracts to secure dedicated technical support for offshore platform deluge coverage. The country's national oil company centralizes engineering standards across floating production units. Abu Dhabi and Dubai serve as procurement hubs for Middle East petrochemical expansions requiring hazardous area fire suppression systems.
Deluge Valve Market Vendor Landscape
Capital-heavy foundry operators compete with asset-light system integrators across the deluge valve supply base. The market structure tilts toward consolidation among integrated fire protection conglomerates with captive distribution networks. Three archetypes dominate: diversified building technology conglomerates with retrofit service capabilities, specialized marine and offshore product specialists, and grooved mechanical joining system providers. Competitive moves center on unbundling valve supply from installation contracts and consolidating procurement under framework agreements with integrated energy majors.
Among diversified building technology conglomerates, Johnson Controls represents the integrated retrofit cycle archetype through building management system convergence. Viking Group Inc. and Victaulic exemplify contrasting specialization vectors—Viking anchors the marine-offshore product line niche, while Victaulic occupies a position centered on grooved mechanical joining expertise that reduces installation labor requirements. These three companies illustrate how vendor positioning fragments across electromechanical integration, salt-exposure durability, and mechanical joining standardization respectively.
| Leading Market Players |
|---|
| Johnson Controls |
| Viking Group Inc. |
| Victaulic |
| BERMAD |
| NAFFCO |
| Reliable Automatic Sprinkler |
| Cla-Val |
| HD Fire Protect |
| Minimax GmbH & Co KG |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap foundry operators in Italy and Germany anchor bronze and ductile iron casting capacity, concentrating upstream supply leverage among legacy European metalworkers who dictate raw material pass-through terms to valve assemblers across the Gulf Coast and North Sea procurement corridors.
Pricing Analysis
The bundled-vs-unbundled service split between component supply and installation commissioning defines transaction structures across the market. Three-tier pricing structure across marine-certified, industrial-standard, and economy-catalog levels segments buyers by certification burden and aftermarket service requirements. Cost compression in economy-catalog tiers is intensifying because engineering-procurement-construction firms are unbundling valve supply from installation contracts. Mid-size regional contractors exhibit the highest price sensitivity, while integrated energy majors prioritize batch-consistent certification packages over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's Petroleum, Chemicals and Petrochemicals Investment Regions are reshaping sourcing patterns for multinational valve manufacturers bidding on coastal refinery expansions. Foundry capacity concentrates in Italy, Germany, and China, with stainless steel trim components drawing from specialized Austrian and Swedish metallurgical suppliers. Single-source vulnerability around corrosion-resistant bronze alloys creates procurement risk during copper commodity spikes. Distribution runs through regional stocking distributors who maintain Gulf Coast and Singapore hub inventories for offshore turnaround windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Deluge Valve Market functions as a regulatory compounder where EPA process safety management mandates and EU Green Deal procurement standards continuously refresh replacement cycles and specification upgrades across installed bases.
For Market Incumbents: Extend certification coverage into harmonized CE-MDR pathways for pharmaceutical cleanroom applications, capturing single-certification efficiency gains as European chemical clusters decouple from carbon-intensive supply chains. Deepen captive foundry relationships to secure bronze alloy allocation priority during commodity volatility spikes. Address the threat of unbundled procurement by embedding IoT-enabled monitoring into valve assemblies to rebuild system integration value. For New Entrants and Emerging Players: Capture specification share in India's Gujarat and Andhra Pradesh coastal corridors where fire suppression infrastructure lags behind petrochemical capacity additions. The most penetrable segment lies in corrosion-resistant outdoor configurations for arctic pipeline stations, where incumbent service networks remain thin. Pursue direct sale relationships with national oil company maintenance divisions to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among hydraulic actuation specialists with North Sea platform service contracts but limited electromechanical product development. The five-to-ten year viability window favors targets with marine-offshore certification depth and aging technician workforce relationships that concentrate in Aberdeen, Houston, and Singapore. Monitor ADNOC and Saudi Aramco framework agreement renewal cycles as inflection indicators for procurement consolidation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Harmonization Investment | CE-MDR convergence reduces parallel validation costs for European pharmaceutical cleanroom bids. |
| IoT-Enabled Predictive Maintenance Platform | Digital twin integration with Johnson Controls building management systems opens recurring revenue streams. |
| Corrosion-Resistant Material Vertical Integration | Captive stainless steel trim production insulates margin predictability from Austrian metallurgical supply volatility. |
| Indian Industrial Corridor Direct Sales Expansion | BIS certification acquisition enables specification capture in Gujarat Petroleum Investment Region greenfield projects. |
| Hydraulic-to-Electromechanical Conversion Service Capability | Specialized technician training addresses scarcity concentration in Aberdeen and Singapore marine servicing hubs. |
Methodological Framework
Multiple input streams — fire protection contractor interviews, petrochemical terminal procurement lead consultations, and foundry operator capacity assessments — were reconciled against customs trade data, NFPA technical committee filings, and SEC 10-K equipment supplier disclosures. Plant engineers at Gulf Coast refineries, marine fire protection technicians in Aberdeen and Singapore, EPC project managers, and aftermarket service heads provided primary intelligence. Bottom-up unit shipment estimates triangulated against top-down capital expenditure flows across offshore platform and chemical processing installations.
Data-stream reconciliation across electromechanical and pneumatic actuation technologies, floor-mounted versus wall-mounted installation configurations, and industrial facility versus power plant end-use segments anchored the analytical framework over the projection horizon. CAGRs were derived from replacement cycle timing, regulatory compliance trigger analysis, and capacity expansion announcements across the Gulf of Mexico and North Sea. Offshore platform specification upgrades and REACH retrofit deadlines in European chemical clusters served as industry-specific demand calibration inputs.
Commodity price volatility in copper and tin markets, regulatory harmonization delays between NFPA and EN standards, and engineering-procurement-construction procurement unbundling acceleration are the dominant revision risks that could compress or extend replacement cycle assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Curb Valves Market
Valves
Valve Manifold Box (VMB) Market
Valves
Choke Valves Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Global Compression Packing Market
Valves
Industrial Hydraulic Filters Market
Valves
Asia-Pacific Medium Voltage Switchgear Market
Valves
North America Valves Market
Valves
Portable Valve Actuator Market
Valves
Steam Trap Valve Market
Valves
Emergency Venting System Market
Valves
Middle East and Africa Machined Seals Market
Valves
Subsea Valves Market
Valves
Servo Valves Market
Valves
Industrial Valves Market
Valves
Air Jet Ejectors Market