
 Dynamic Electrograph Market | 2026-2036
Dynamic Electrograph Market Size, Share, and Industry Trends Forecast 2026-2036
Dynamic Electrograph Market Insights
IEC 60601-2-25 certification for electrocardiograph safety and performance is rotating vendor eligibility, filtering out suppliers lacking dedicated cardiac-device testing infrastructure. Siemens Healthineers leverages its imaging ecosystem to bundle electrograph hardware with PACS integration. GE Healthcare anchors North American hospital procurement through long-term service contracts. Schiller AG specializes in compact, point-of-care electrograph designs for ambulatory settings.
Dynamic electrograph instruments capture, amplify, and record time-varying electrical potentials from biological or engineered systems, typically sampling at 500–1000 Hz with 12- to 16-bit resolution for clinical-grade fidelity. Waveform generators and digital converters together constitute the core hardware stack, with software-defined architectures displacing analog legacy platforms in new installations. Medical imaging applications command premium pricing due to diagnostic liability requirements, while research laboratories represent the fastest-growing end-user category as neuroscience and materials-science funding expands.
FDA 510(k) premarket notification and the EU Medical Device Regulation (MDR) impose divergent clinical-evidence thresholds, forcing manufacturers to maintain dual compliance architectures. The EU AI Act's risk-classification framework for diagnostic algorithms will further constrain how machine-learning-enhanced electrograph software enters European healthcare providers. Stakeholders must decide whether to pursue modular software certifications or integrated hardware-software submissions as regulatory fragmentation deepens.
Market Dynamics
Software-defined architectures are decomposing legacy analog electrograph platforms, forcing vendors to rebuild hardware-software stacks around modular digital cores while navigating divergent FDA 510(k) and EU MDR evidence requirements.
Growth Catalysts
- EU MDR streamlined pathways:The Medical Device Regulation's harmonized conformity assessment is compressing multi-national certification timelines for electrograph manufacturers targeting European hospital procurement.
- Neuroscience laboratory expansion:Research institutions in Germany, Switzerland, and the United States are scaling electrograph deployments for brain-computer interface development and materials characterization studies.
- Point-of-care migration:Ambulatory clinics and emergency departments are demanding compact, battery-operated electrograph systems that bypass centralized imaging department workflows.
Market Restraints
- ASIC foundry concentration:Specialized analog-to-digital converter chips for clinical-grade electrographs rely on a concentrated Taiwan-based semiconductor fabrication base.
- IEC 60601-2-25 testing infrastructure:Dedicated cardiac-device safety certification facilities in Germany and Switzerland create bottlenecks for smaller manufacturers lacking captive testing labs.
- Portable ultrasound substitution:Handheld echocardiography devices are capturing some cardiac diagnostic workflows previously served by resting electrograph systems.
Strategic Opportunities
- EU AI Act diagnostic algorithm classification:The risk-tiering framework for machine-learning-enhanced waveform analysis creates first-mover advantage for vendors securing modular software certifications ahead of hardware-software integration mandates.
- India CDSCO Class B device registration:The streamlined pathway for moderate-risk diagnostics is opening public hospital procurement channels previously blocked by complex import licensing.
- Cloud-native PACS convergence:Electrograph data streams integrated with vendor-neutral archive architectures are enabling subscription-based telemetry services for remote patient monitoring networks.
Industry Challenges
- Firmware cybersecurity validation:FDA premarket submission requirements for connected device software assurance are extending development cycles and demanding specialized embedded security engineering talent.
- Dual compliance architecture maintenance:Manufacturers must sustain parallel clinical evidence packages for FDA 510(k) substantial equivalence and EU MDR clinical evaluation report standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dynamic Electrograph Market |
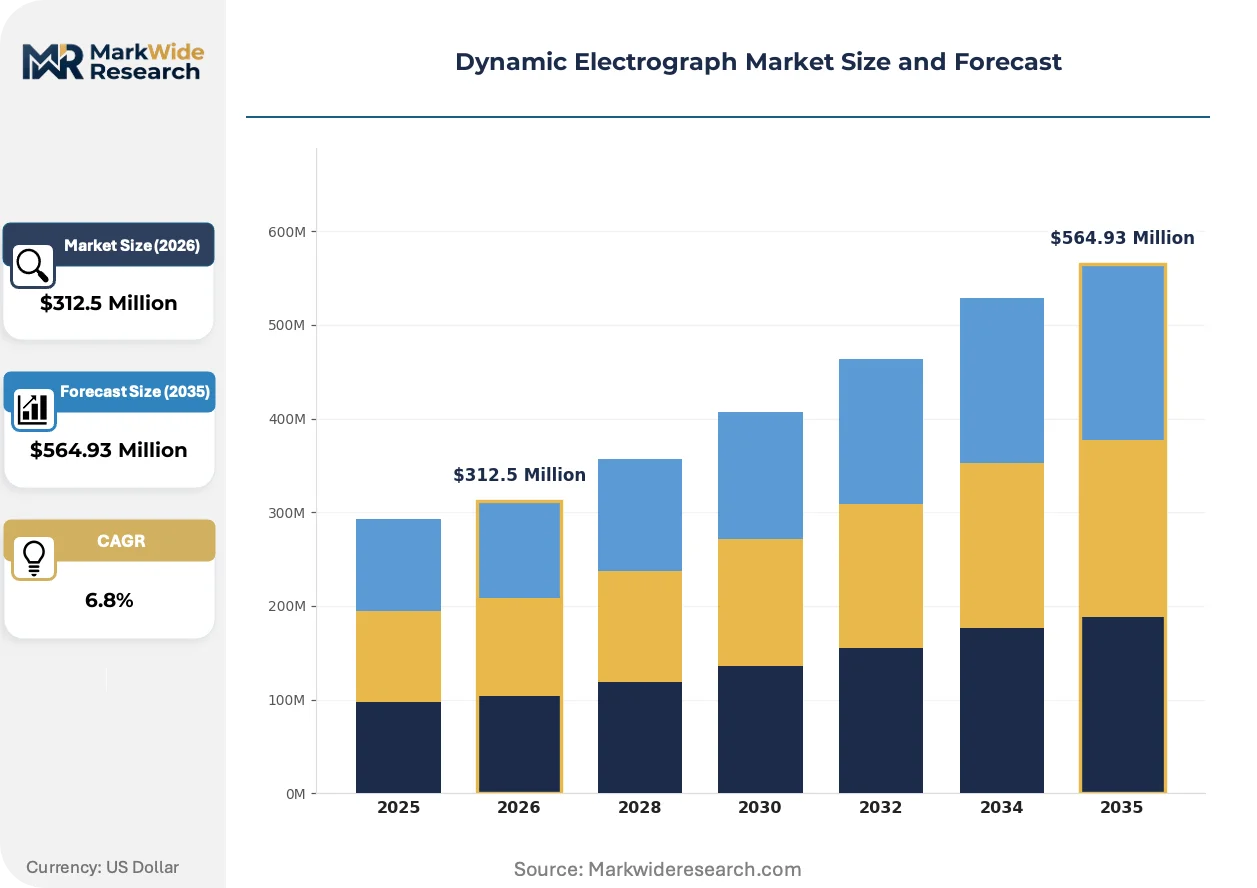
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waveform Generators, Signal Processors, Digital Converters, Pulsed Power Supplies Technology: Analog, Digital, Hybrid, Software-Defined Application: Telecommunications, Medical Imaging, Industrial Automation, Research Laboratories End User: Healthcare Providers, Research Institutions, Manufacturing Plants, Telecommunication Firms |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Nihon Kohden, Medtronic, Abbott, Schiller AG, Fukuda Denshi, Biosense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dynamic Electrograph Market Trends and Innovations
Waveform processing pipelines are migrating from fixed-function analog front-ends to reconfigurable digital signal processing chains, enabling real-time algorithm updates without hardware replacement cycles.
Field-programmable gate arrays with integrated analog-to-digital converters are decomposing traditional electrograph signal conditioning architectures. University hospital imaging departments in Germany and Switzerland are piloting these reconfigurable platforms for multi-modal physiological monitoring. The technology is compressing capital equipment refresh cycles from seven-year hardware replacement to three-year firmware subscription models.
The EU AI Act's risk-classification framework for diagnostic algorithms is restructuring software submission strategies across European markets. Manufacturers now face explicit clinical validation requirements for machine-learning-enhanced arrhythmia detection that exceed traditional 510(k) predicate pathways. Cardiology device divisions are responding by segregating AI-enabled feature sets into standalone software-as-a-medical-device certifications.
Hospital procurement committees are unbundling electrograph hardware from long-term service agreements that previously locked maintenance revenue to original equipment manufacturers. Independent service organizations in the United States and Germany are capturing calibration and repair contracts through ISO 13485-certified quality management credentials. This disintermediation is most advanced in academic medical centers with dedicated clinical engineering departments capable of in-house preventive maintenance protocols.
Dynamic Electrograph Market Segmentation
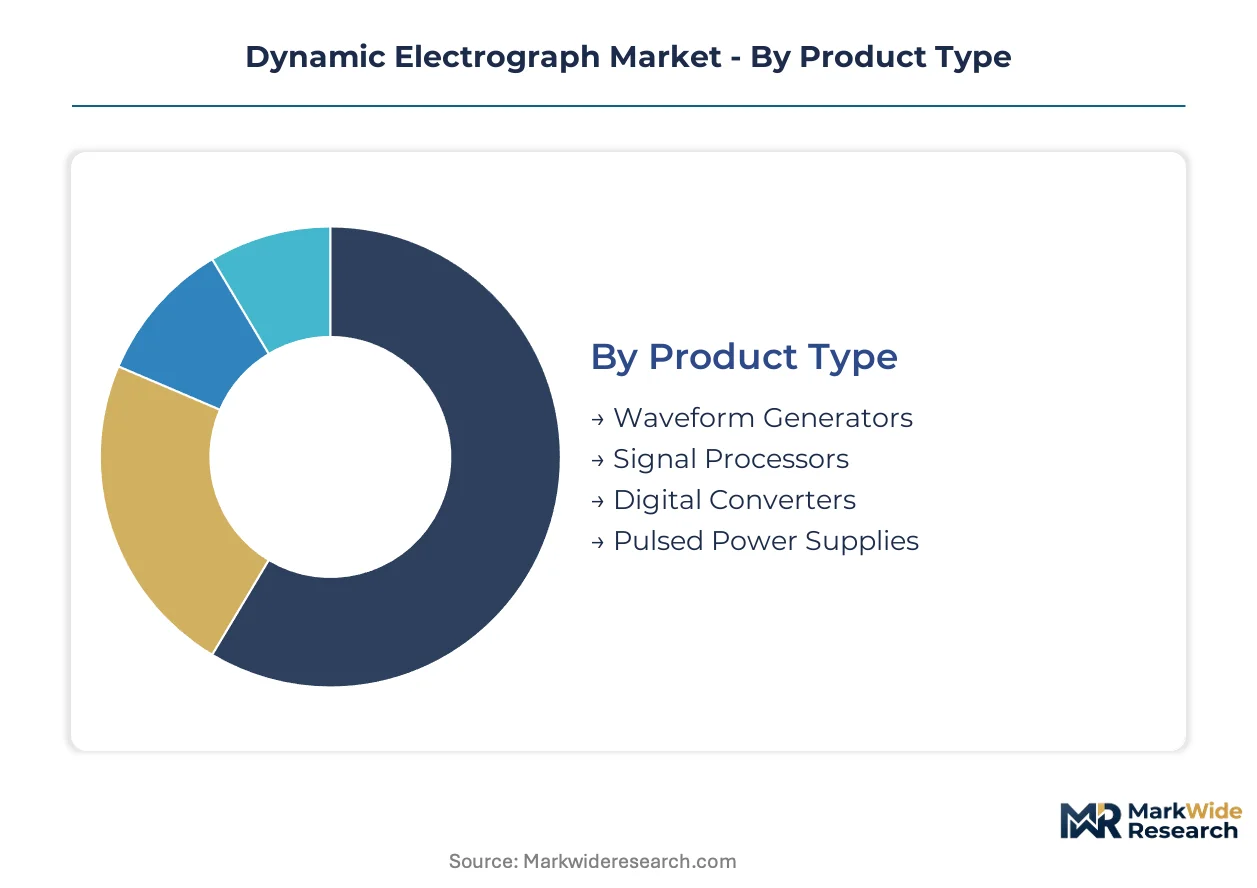
Electrograph procurement patterns diverge sharply across hardware configurations and deployment contexts. Segment boundaries determine which vendors capture maintenance revenue versus one-time equipment sales.
Product Type:
Portable ultrasound devices and handheld diagnostic tools exert substitution pressure most acutely on basic waveform generation hardware, forcing electrograph manufacturers to differentiate through embedded software capabilities.
- Waveform Generators:These units produce calibrated electrical signals with programmable amplitude and frequency parameters for stimulus-response testing. University hospital imaging departments in Germany prioritize generators with IEC 60601-2-25 certification for cardiac safety compliance, compressing vendor eligibility to suppliers with dedicated testing infrastructure.
- Signal Processors:Real-time filtering and noise-reduction engines extract diagnostic-quality waveforms from noisy biological sources. Research institutions in Switzerland are scaling deployments for brain-computer interface development, driving demand for multi-channel architectures with sub-microvolt resolution.
- Digital Converters:High-resolution ADC modules translate analog physiological signals into discrete data streams.
- Pulsed Power Supplies:Specialized units deliver controlled energy bursts for electroporation and materials characterization applications.
Waveform generators retain volume leadership; signal processors hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive hardware platforms from subscription-based software models, with mid-range hybrid systems capturing ambulatory clinic budgets.
- Analog:Legacy transistor-based architectures persist in cost-sensitive installations where electromagnetic interference is minimal. Maintenance-dependent revenue streams from long-life installations in India public hospitals sustain limited production lines despite declining new unit sales.
- Digital:FPGA-based signal chains enable firmware-upgradable performance without hardware replacement. FDA 510(k) clearance pathways favor established predicate devices, advantaging incumbents with substantial equivalence documentation libraries.
- Hybrid:Combined analog front-ends with digital back-ends balance signal fidelity against processing flexibility.
- Software-Defined:Fully reconfigurable architectures separate hardware acquisition from feature licensing.
Analog systems retain installed-base dominance; software-defined platforms gain share fastest among new installations.
Application:
Customer type concentration varies by liability exposure, with medical imaging commanding premium pricing and research laboratories driving volume expansion.
- Medical Imaging:Diagnostic-grade electrographs require clinical validation and regulatory clearance for arrhythmia detection algorithms. EU MDR clinical evaluation report standards exceed FDA 510(k) evidence thresholds, forcing dual compliance investments from vendors targeting European hospital procurement.
- Research Laboratories:Neuroscience and materials-science funding expansion in the United States and Germany is accelerating electrograph deployment for non-clinical applications. Reduced regulatory burden enables faster technology refresh cycles compared to diagnostic installations.
- Telecommunications:Signal integrity testing for fiber-optic infrastructure drives specialized waveform analysis requirements.
- Industrial Automation:Predictive maintenance applications monitor electrical signatures from rotating machinery and power distribution systems.
Medical imaging commands revenue per unit; research laboratories drive shipment volume expansion.
End User:
Geography shapes procurement authority, with concentrated manufacturing bases in Germany and Switzerland influencing regional vendor selection criteria.
- Healthcare Providers:Hospital procurement committees are unbundling hardware from long-term service agreements, enabling independent service organizations to capture calibration contracts through ISO 13485 credentials. Academic medical centers with dedicated clinical engineering departments lead this disintermediation.
- Research Institutions:Federal funding agency priorities in neuroscience and advanced materials directly determine equipment acquisition timelines. Grant-driven procurement cycles create demand spikes aligned with fiscal year appropriations.
- Manufacturing Plants:Industrial quality control departments integrate electrograph testing into production line automation.
- Telecommunication Firms:Network infrastructure operators deploy specialized units for signal propagation analysis.
Healthcare providers dominate current revenue; research institutions show the steepest budget growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways in the United States and EU MDR harmonization in Germany are redirecting procurement budgets toward certified digital electrograph platforms. National reimbursement policies and hospital infrastructure investments determine regional adoption velocity.
United States
Academic medical centers in Boston and the Research Triangle are expanding electrograph deployments for neuroscience research. FDA premarket notification requirements for connected device cybersecurity are extending vendor qualification timelines. The Minneapolis-St. Paul corridor hosts concentrated clinical engineering expertise that enables in-house preventive maintenance protocols.
Germany
University hospital imaging departments in Munich and Heidelberg are bundling electrograph hardware with PACS integration contracts. EU MDR clinical evaluation report standards exceed prior evidence thresholds, filtering vendor eligibility. The Baden-Württemberg manufacturing cluster anchors Siemens Healthineers and Schiller AG supply chains.
Switzerland
Brain-computer interface research at ETH Zurich and EPFL is driving demand for multi-channel signal processors with sub-microvolt resolution. Swissmedic certification requirements for Class II diagnostic devices maintain stringent quality benchmarks. The Basel pharmaceutical corridor generates cross-border procurement spillover into adjacent German and French hospital networks.
India
Public hospital procurement through the Central Government Health Scheme is opening to CDSCO Class B device registrations with streamlined import licensing. CDSCO's moderate-risk diagnostic pathway is compressing multi-year approval timelines. Manufacturing clusters in Bengaluru and Hyderabad are developing domestic assembly capabilities for portable electrograph systems.
Japan
PMDA consultation pathways for software-as-a-medical-device are restructuring submission strategies for AI-enhanced waveform analysis. METI funding for geriatric care infrastructure is channeling electrograph procurement toward community hospital networks. The Osaka-Kobe medical device corridor concentrates PMDA-registered quality management expertise.
Dynamic Electrograph Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification capabilities, creating tiered market access based on dual FDA-EU compliance infrastructure. The vendor landscape separates into consolidated imaging-system conglomerates, mid-scale cardiac-device specialists, and emerging software-defined platform developers. Strategic differentiation centers on modular hardware-software architectures versus integrated legacy platforms. Competitive moves concentrate on unbundling hardware from long-term service agreements and securing standalone software certifications ahead of EU AI Act implementation.
Within the imaging-system conglomerate tier, Siemens Healthineers and GE Healthcare occupy positions defined by predicate device libraries and substantial equivalence documentation. Schiller AG exemplifies the mid-scale cardiac-device specialist archetype, leveraging compact point-of-care designs for ambulatory penetration. These three anchors represent divergent strategic postures: ecosystem bundling, North American service-contract anchoring, and portable-form-factor specialization.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Nihon Kohden |
| Medtronic |
| Abbott |
| Schiller AG |
| Fukuda Denshi |
| Biosense |
| Others |
Pricing and Supply Chain Analysis
IEC 60601-2-25 certification gates both supplier qualification and price differentiation simultaneously, compressing vendor eligibility to firms with captive cardiac-device testing infrastructure while stratifying hardware premiums across compliance tiers.
Pricing Analysis
Certification level (IEC 60601-2-25/FDA 510(k)/CE MDR-grade) creates the primary spread across three-tier pricing structures separating diagnostic-grade systems from research-laboratory units and cost-sensitive analog legacy platforms. Subscription-based firmware licensing for software-defined architectures commands recurring revenue premiums against transactional hardware sales. Cost compression in mid-range hybrid systems intensifies as portable ultrasound substitution erodes resting electrograph volumes. Academic medical centers with in-house clinical engineering capabilities exhibit lowest price sensitivity; ambulatory clinics in India public hospital procurement show highest.
Supply Chain Analysis
Strategic stockpiling of specialized analog-to-digital converter chips dominates inventory strategy given Taiwan-based foundry concentration and geopolitical exposure. Semiconductor fabrication draws from TSMC's specialty analog lines in Hsinchu and UMC's mixed-signal capacity in Tainan, with secondary sourcing from GlobalFoundries in Malta, New York. FPGA supply rests on Xilinx and Intel programmable logic inventory channels. Single-source vulnerability concentrates in 16-bit clinical-grade ADC die supply. Distribution runs through authorized medical-device distributors holding ISO 13485 credentials and direct hospital procurement committees unbundling service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as neuroscience laboratory funding accelerates electrograph deployment for brain-computer interface development ahead of clinical diagnostic saturation.
For Market Incumbents: Fortify predicate device libraries to accelerate FDA 510(k) substantial equivalence pathways against software-defined platform entrants. Deepen backward integration into FPGA supply through preferred allocation agreements with programmable logic vendors, insulating production from foundry bottlenecks. Lock hospital procurement committees into bundled PACS integration contracts before independent service organizations capture calibration revenue. For New Entrants and Emerging Players: CDSCO Class B device registration fast-tracks public hospital procurement in India with compressed approval timelines relative to multi-year legacy pathways. Target research institutions in Germany and Switzerland where reduced regulatory burden enables faster technology refresh cycles than diagnostic installations. Pursue standalone software-as-a-medical-device certifications ahead of EU AI Act hardware-software integration mandates. For Investors and Strategic Acquirers: EU AI Act diagnostic algorithm classification reshapes the acquisition landscape toward modular software certification capabilities ahead of integrated platform mandates. Long-term viability centers on vendors with dual FDA-EU compliance infrastructure spanning 5-10 year regulatory fragmentation. Target acquisition archetype: mid-scale cardiac-device specialists with compact point-of-care form factors and captive IEC 60601-2-25 testing labs. Watch for inflection when cloud-native PACS convergence crosses threshold penetration in academic medical center procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Software Certification | EU AI Act risk-tiering creates first-mover advantage for standalone algorithm validations ahead of integration mandates. |
| CDSCO Registration Fast-Track | India's streamlined Class B pathway opens public hospital procurement previously blocked by complex import licensing. |
| Cloud-Native PACS Integration | Vendor-neutral archive convergence enables subscription telemetry services for remote patient monitoring networks. |
| Backward Integration into FPGA Supply | Preferred allocation agreements with programmable logic vendors insulate production from Taiwan foundry concentration. |
| Independent Service Organization Certification | ISO 13485 credentials capture calibration contracts as hospital committees unbundle hardware from long-term maintenance. |
Research Methodology
Initial hypotheses were tested against primary input from hospital biomedical engineers, clinical engineering directors, GPO contracts managers, and regulatory affairs leads at electrograph manufacturers, then refined through secondary validation against FDA 510(k) premarket notification databases, EU MDR clinical evaluation report filings, hospital procurement contract repositories, and semiconductor foundry capacity disclosures. Bottom-up shipment estimates triangulated with top-down market sizing across hardware configuration tiers.
Variance decomposition across the projection horizon isolates volume drivers (research laboratory funding cycles, point-of-care migration rates) from value drivers (software-defined architecture penetration, AI-enhanced algorithm pricing premiums). Segmentation modeling spans product type, technology tier, application liability exposure, and end-user procurement authority. CAGRs derive from logistic adoption curves fitted to historical regulatory clearance timelines and capital equipment refresh patterns.
The analysis sits within stated boundaries; outcomes outside sustained neuroscience funding expansion or stable Taiwan semiconductor fabrication capacity would require recalibration. Forecasts reflect documented assumptions regarding EU AI Act implementation pacing and FDA cybersecurity guidance evolution. Revision becomes warranted when portable ultrasound substitution crosses diagnostic workflow threshold penetration or when ASIC foundry concentration shifts geographically.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Global Bipolar Power Transistor Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Flip Chip Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Data Processing Unit Market