
 Ampoule Cream Market | 2026-2036
Ampoule Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Ampoule Cream Market Analysis
Aftermarket service revenue from beauty clinic consultation and protocol customization is fragmenting across regional dermatology chains and independent aesthetic practices. L'Oréal S.A. leverages its dermatological science division to anchor professional-grade ampoule distribution through clinic partnerships. Amorepacific Corporation dominates the Korean domestic channel with heritage brand strength in hanbang-derived formulations. Shiseido Company, Limited extends its position through J-beauty precision manufacturing standards that command premium positioning in Asian specialty retail.
Ampoule cream denotes a highly concentrated, single-dose or small-batch skincare delivery system with active ingredient loads typically ranging from 30% to 90% higher than standard serums, engineered for targeted epidermal penetration through liposomal or nanocapsule encapsulation technologies. Anti-aging formulations lead product type revenue pools due to sustained dermatologist endorsement and clinic-channel markup structures, while peptide ingredient types capture accelerating demand from male end users entering professional skincare routines. Online distribution channels are fragmenting price architecture as direct-to-consumer peptide ampoules undercut traditional retail markups by bypassing wholesaler intermediaries.
South Korea's Ministry of Food and Drug Safety enforces strict active ingredient disclosure thresholds that shape formulation transparency requirements for cross-border e-commerce shipments. The EU Cosmetics Regulation and REACH compliance frameworks govern preservative limits and nanomaterial safety assessments for European market entry, while the FDA oversees cosmetic versus drug classification boundaries that determine whether retinol-based ampoules trigger pharmaceutical oversight in the United States. Stakeholders must monitor evolving peptide classification debates across regulators to anticipate whether concentrated signaling molecules will face pharmaceutical-grade testing mandates.
Market Dynamics
Peptide concentration thresholds enforced by South Korea's MFDS are compressing formulation margins while accelerating R&D differentiation among contract manufacturers serving clinic-channel distributors.
Growth Catalysts
- MFDS Peptide Standards:South Korea's Ministry of Food and Drug Safety mandates elevated active disclosure thresholds that force transparency upgrades, benefiting compliant cross-border e-commerce shipments into Southeast Asian markets.
- Post-Treatment Protocol Integration:Dermatology clinics in Seoul's Gangnam district embed ampoule creams into laser and injectable aftercare regimens, creating institutional purchasing habits that extend to satellite clinic networks.
- Liposomal Encapsulation:Nanocapsule delivery systems improve epidermal penetration rates for high-molecular-weight actives, enabling peptide loads previously unstable in aqueous formulations.
Market Restraints
- Raw Material Concentration:Peptide synthesis capacity clusters with three specialized biochemical suppliers in Switzerland and South Korea, exposing brands to batch allocation delays during fermentation scale-ups.
- EU Nanomaterial Assessment:REACH compliance frameworks require extended safety dossiers for liposomal carriers under 100nm, extending European market entry timelines by 14-18 months for reformulated products.
- Retinol Regulatory Friction:FDA cosmetic-drug classification boundaries trigger pharmaceutical oversight for retinol concentrations exceeding 0.3%, forcing dual-track development budgets for US market entry.
Strategic Opportunities
- Male Skincare Penetration:Professional skincare adoption among male end users in South Korea's corporate districts remains underdeveloped relative to female per-capita consumption, offering volume expansion without geographic expansion.
- Direct-to-Consumer Peptide Ampoules:Online distribution channels bypass traditional wholesaler markups, enabling price positioning that captures price-sensitive segments without eroding clinic-channel premium tiers.
- Hanbang Formulation Heritage:Traditional Korean herbal extraction methods command authenticity premiums in Asian specialty retail, creating defensive positioning against synthetic peptide commoditization.
Industry Challenges
- Formulation Chemist Scarcity:Liposomal stability expertise concentrates among senior researchers at established K-beauty houses, constraining new entrant product development velocity.
- Multi-Regulatory Certification Burden:Simultaneous MFDS, REACH, and FDA filing requirements fragment quality assurance teams and extend commercialization timelines for global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ampoule Cream Market |
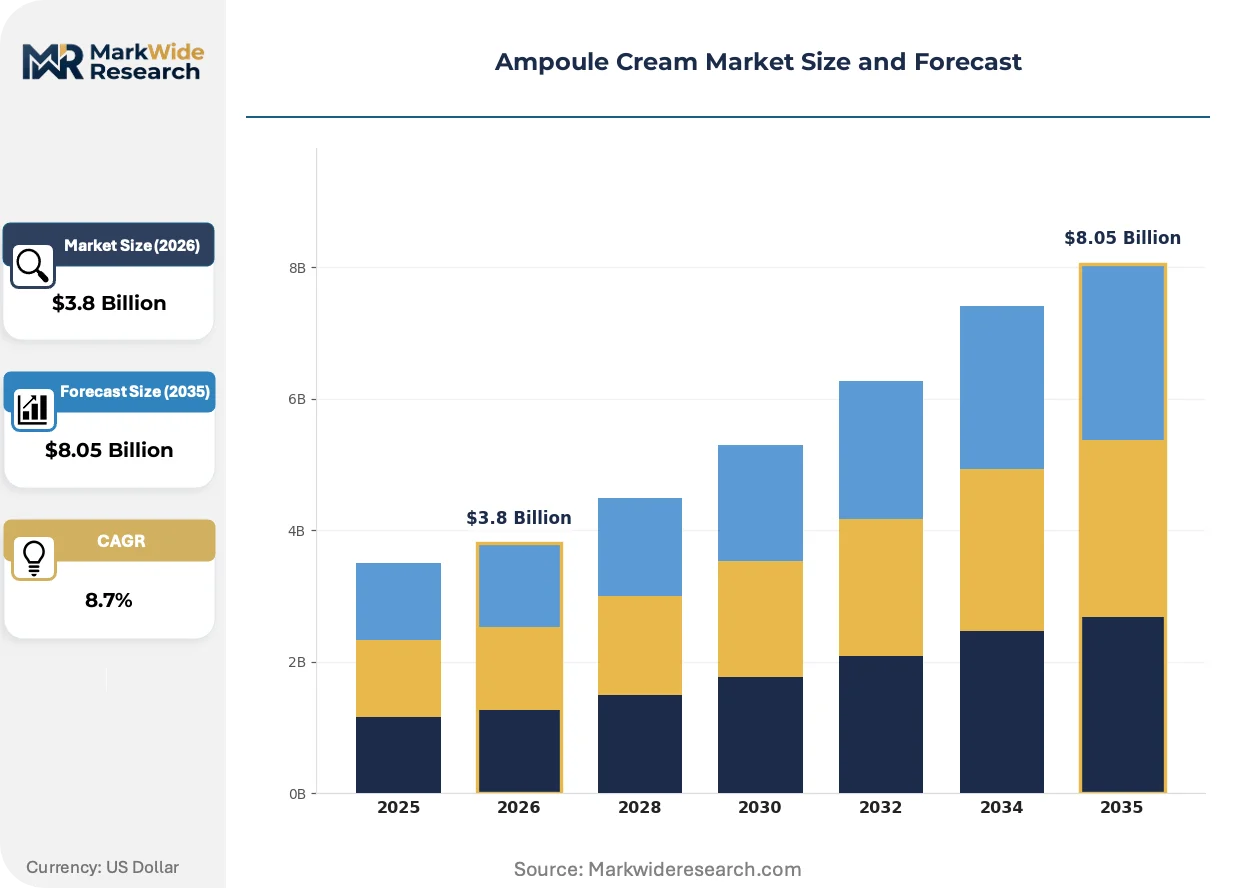
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizing, Anti-aging, Brightening, Repairing Ingredient Type: Vitamin C, Hyaluronic Acid, Peptides, Retinol End User: Women, Men, Salons, Dermatologists Distribution Channel: Online, Retail, Beauty Clinics, Wholesalers |
| Companies Covered | L'Oréal S.A., Amorepacific Corporation, The Estée Lauder Companies Inc., LG H&H Co., Ltd., Cosmax Inc., Amway Corp., Shiseido Company, Limited, Beiersdorf AG, Coreana Cosmetics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ampoule Cream Market Emerging Trajectories
Encapsulation technology maturation is collapsing traditional serum-ampoule efficacy gaps while regulatory transparency mandates reshape competitive disclosure standards across export markets.
Microfluidic manufacturing is collapsing batch-to-batch variability in liposome size distribution. Premium dermatology chains in Seoul and Tokyo are adopting these precision-engineered ampoules for post-laser protocols. The technology is collapsing quality assurance overhead previously required for manual encapsulation validation.
REACH nanomaterial safety assessments now require chronic dermal exposure data for carriers below 50nm. European contract manufacturers are consolidating testing capabilities in-house to protect formulation confidentiality. Ampoule brands targeting EU distribution are reformulating toward 80-120nm particle ranges to bypass extended assessment timelines.
Subscription-based replenishment models are displacing clinic-exclusive purchasing for maintenance-phase skincare. Male professionals in South Korea's financial districts are driving this shift through mobile-first direct ordering. The behavior is most visible in Seoul's Yeouido business cluster where time-constrained executives bypass aesthetic consultation for algorithm-matched product curation.
Ampoule Cream Market Segmentation
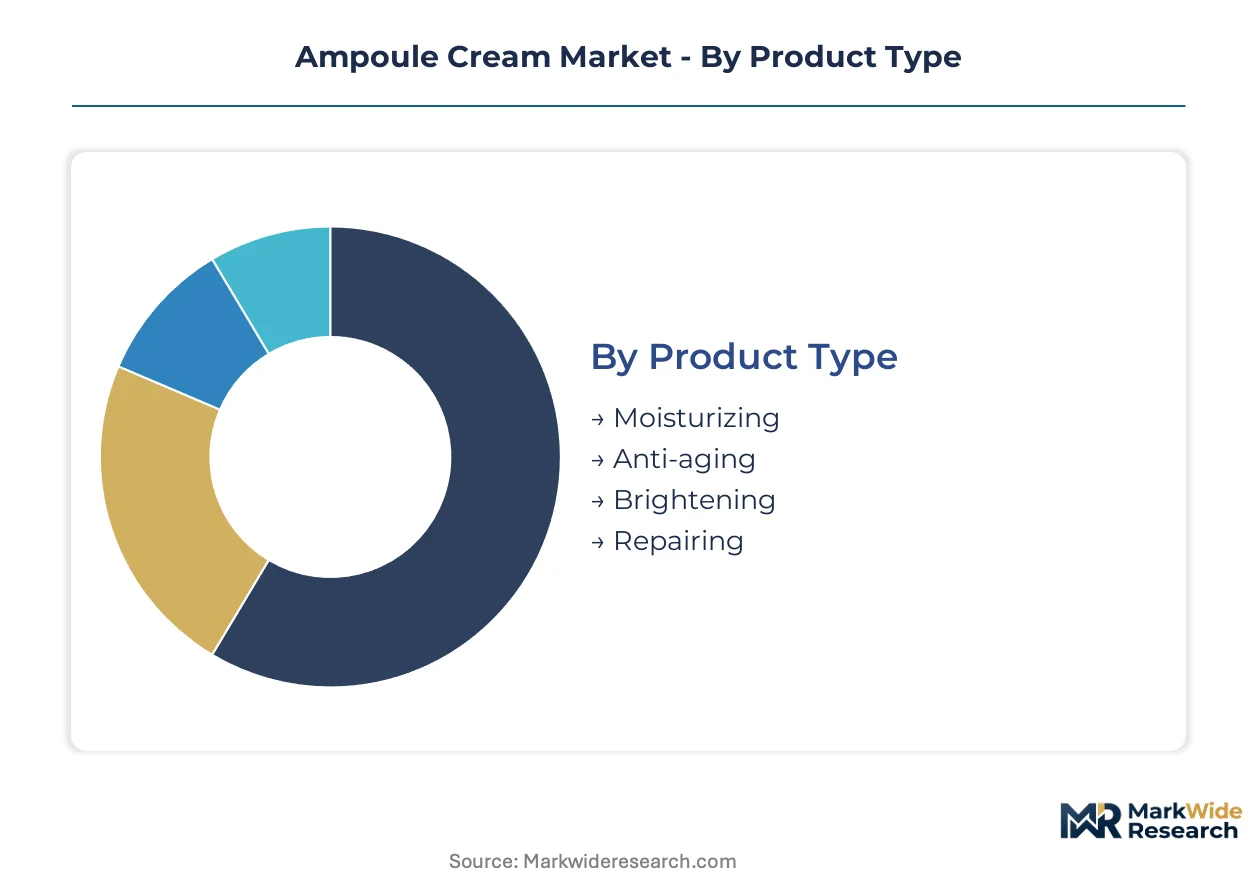
Ampoule cream segmentation reflects divergent formulation philosophies between clinical-grade precision and accessible daily skincare. Manufacturers optimize concentration thresholds, delivery mechanisms, and channel positioning differently across each dimension.
Product Type:
Mature categories anchor revenue stability while emerging formulations capture protocol-driven substitution from traditional serums.
- Anti-aging:High-concentration peptide and retinol complexes target collagen synthesis and cellular turnover. Seoul's Gangnam district aesthetic cluster drives institutional procurement through post-laser and injectable aftercare regimens. Dermatologist endorsement sustains premium markup structures unavailable to mass-market alternatives.
- Moisturizing:Hyaluronic acid and ceramide blends prioritize barrier repair over active treatment. South Korea's corporate districts show accelerating adoption among male professionals seeking streamlined routines without multi-step layering. Convenience positioning supports subscription replenishment models.
- Brightening:Niacinamide and arbutin formulations address hyperpigmentation from UV exposure and hormonal triggers. Asian specialty retail channels command authenticity premiums for hanbang-derived botanical extracts.
- Repairing:Centella asiatica and madecassoside concentrates target compromised skin barriers. Post-procedure protocols in dermatology clinics create concentrated demand spikes following seasonal aesthetic treatment peaks.
Anti-aging retains volume leadership; repairing holds the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates pharmaceutical-grade synthesis from commodity botanical extraction.
- Peptides:Signaling molecules engineered for targeted cellular communication require liposomal encapsulation for epidermal penetration. South Korea's MFDS mandates elevated disclosure thresholds that compress formulation margins while accelerating R&D differentiation among contract manufacturers. Male end users entering professional skincare routines drive accelerating demand.
- Retinol:Vitamin A derivatives trigger FDA cosmetic-drug classification scrutiny above 0.3% concentration. Dual-track development budgets become necessary for US market entry, fragmenting commercialization timelines against peptide alternatives.
- Vitamin C:L-ascorbic acid and stabilized derivatives address oxidative stress with established efficacy documentation. Oxidation sensitivity constrains packaging requirements toward amber glass and airless pump systems.
- Hyaluronic Acid:Molecular weight variants determine dermal penetration depth and hydration mechanism. Cross-linked formulations command medical-grade pricing in clinic channels.
Peptides retain volume leadership; retinol holds the steepest expansion curve.
End User:
Customer type segmentation separates institutional procurement from individual purchasing behavior.
- Women:Established per-capita consumption in South Korea's domestic market sets baseline volume expectations. Multi-step layering traditions support specialized ampoule integration within comprehensive routines.
- Men:Underdeveloped relative penetration in South Korea's corporate districts offers expansion without geographic diversification. Yeouido business cluster executives drive mobile-first direct ordering for algorithm-matched curation.
- Salons:Service-based application protocols require bulk procurement with professional training support. Regional dermatology chains fragment aftermarket service revenue across independent aesthetic practices.
- Dermatologists:Prescriptive authority shapes post-treatment regimen standardization. Seoul clinic networks extend institutional purchasing habits to satellite locations.
Women retain volume leadership; men hold the steepest expansion curve.
Distribution Channel:
Channel economics determine price architecture and margin protection.
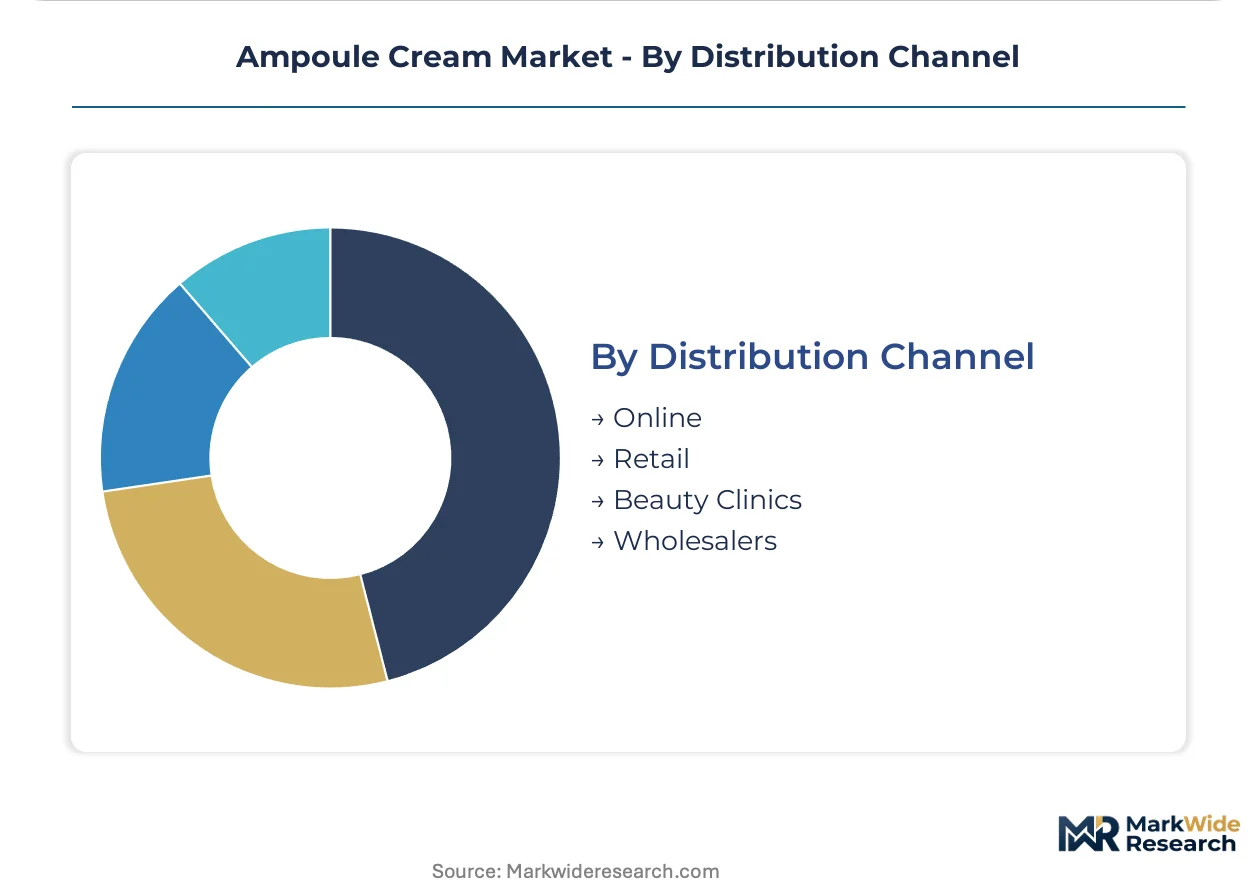
- Beauty Clinics:Professional-grade distribution anchors premium positioning through dermatologist endorsement. L'Oréal's dermatological science division leverages clinic partnerships for protocol integration.
- Online:Direct-to-consumer peptide ampoules bypass traditional wholesaler markups. Price positioning captures cost-sensitive segments without eroding clinic-channel premium tiers.
- Retail:Asian specialty stores command J-beauty precision manufacturing premiums. Physical presence enables sensory evaluation of texture and absorption characteristics.
- Wholesalers:Intermediary consolidation faces displacement from brand-direct fulfillment infrastructure. Margin compression accelerates channel bypass strategies.
Beauty clinics retain volume leadership; online holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: Seoul's aesthetic clinics institutionalize ampoule protocols as medical-grade aftercare, while European consumers access comparable formulations through retail channels with stricter nanomaterial oversight. This structural difference shapes regulatory compliance burdens and channel economics across markets.
South Korea
Seoul's Gangnam district aesthetic cluster drives per-capita consumption premiums through dermatology clinic procurement. MFDS peptide disclosure mandates compress formulation margins while accelerating R&D differentiation among contract manufacturers. Busan-Ulsan manufacturing corridors supply liposomal encapsulation capacity for export-oriented brands.
United States
Direct-to-consumer peptide ampoules fragment price architecture through online channel expansion. FDA cosmetic-drug classification boundaries trigger pharmaceutical oversight for retinol concentrations exceeding threshold levels. Greater Boston biotech corridors supply specialized peptide synthesis for premium domestic brands.
Japan
J-beauty precision manufacturing standards command premium positioning in Asian specialty retail. METI guidelines on quasi-drug classification shape brightening ingredient disclosure requirements. Kansai/Osaka industrial clusters concentrate precision fermentation capacity for high-purity active production.
Germany
REACH nanomaterial safety assessments extend market entry timelines for liposomal carriers below specified particle thresholds. ECHA compliance frameworks require chronic dermal exposure dossiers that reformulate product specifications. Bavaria-based contract manufacturers consolidate in-house testing capabilities to protect formulation confidentiality.
China
Cross-border e-commerce shipments from South Korea face NMPA registration requirements for peptide concentration disclosures. Yangtze River Delta logistics hubs concentrate import distribution for premium K-beauty ampoules. Shanghai's free-trade zone infrastructure accelerates customs clearance for compliant cosmetic formulations.
Ampoule Cream Market Vendor Landscape
Capability concentration sits with heritage K-beauty houses possessing liposomal stability expertise; scale advantage sits with multinational dermatological science divisions with clinic-channel infrastructure. The market structures around three tiers: integrated beauty conglomerates with professional-grade distribution, specialized contract manufacturers serving private-label demand, and direct-to-consumer disruptors leveraging algorithm-matched curation. Consolidation pressure operates through M&A targeting encapsulation technology assets and strategic partnerships securing peptide synthesis allocation.
Among integrated beauty conglomerates, L'Oréal S.A. and Amorepacific Corporation exemplify divergent geographic anchoring strategies. The former leverages dermatological science division assets for clinic-channel professional distribution; the latter dominates Korean domestic channels through heritage brand positioning in hanbang-derived formulations. Shiseido Company, Limited occupies a position bridging J-beauty precision manufacturing standards with Asian specialty retail premium positioning.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Amorepacific Corporation |
| The Estée Lauder Companies Inc. |
| LG H&H Co., Ltd. |
| Cosmax Inc. |
| Amway Corp. |
| Shiseido Company, Limited |
| Beiersdorf AG |
| Coreana Cosmetics Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Peptide synthesis capacity clustering with three specialized biochemical suppliers in Switzerland and South Korea compresses formulation margins while forcing tiered pricing spreads that separate clinic-grade from direct-to-consumer channels. This single-source dependency for high-purity signaling molecules determines both the premium markup structures in Seoul's Gangnam aesthetic cluster and the supply chain redundancy investments required for global brand expansion.
Pricing Analysis
Long-term offtake contracts between K-beauty houses and Swiss fermentation specialists anchor premium tier pricing, while spot market peptide procurement serves mid-tier direct-to-consumer brands. Price differentiation hinges on MFDS certification grade and liposomal encapsulation precision, with clinic-channel buyers showing lowest sensitivity due to institutional procurement budgets. Cost compression in the subscription tier is intensifying as algorithm-matched curation platforms bypass traditional wholesaler markups, though male professionals in Seoul's Yeouido district demonstrate higher willingness-to-pay for convenience-optimized replenishment models.
Supply Chain Analysis
Peptide feedstock production concentrates in Switzerland and South Korea, with Busan-Ulsan manufacturing corridors supplying liposomal encapsulation capacity for export-oriented brands. Raw material dependencies span fermentation-derived signaling molecules, pharmaceutical-grade hyaluronic acid, and nanocarrier phospholipids. Single-source vulnerability in specialized biochemical synthesis exposes brands to batch allocation delays during scale-ups. Distribution runs through dermatology clinic networks for premium tiers and direct-to-consumer fulfillment infrastructure for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ampoule cream represents a high-growth disruption as MFDS peptide disclosure mandates and liposomal encapsulation maturation simultaneously elevate formulation barriers and collapse traditional serum efficacy gaps. This regulatory-technological inflection favors players with captive R&D infrastructure and clinic-channel anchoring.
For Market Incumbents: Insulate clinic-channel premium positioning by securing long-term peptide synthesis offtake with Swiss fermentation specialists and embedding proprietary protocols within Seoul dermatology network expansion. Threats from direct-to-consumer algorithmic curation platforms demand counterinvestment in subscription infrastructure that preserves brand equity without eroding institutional markup structures.
For New Entrants and Emerging Players: South Korea's corporate district male skincare penetration offers white-space expansion without geographic diversification, with Yeouido business cluster executives driving mobile-first replenishment adoption. Target hanbang-derived formulation authenticity as defensive positioning against synthetic peptide commoditization, leveraging traditional Korean herbal extraction methods that command premiums in Asian specialty retail.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors acquisition of liposomal stability expertise and encapsulation technology assets over brand portfolios. Long-term viability hinges on vertical integration into peptide synthesis or captive contract manufacturer relationships. Watch MFDS peptide classification debates as the critical inflection signal for pharmaceutical-grade testing mandate exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Synthesis Backward Integration | Captive fermentation capacity in Switzerland or South Korea insulates against batch allocation delays and margin compression. |
| Clinic Protocol Partnership Expansion | Dermatology network embedding in Seoul's Gangnam district aesthetic cluster institutionalizes procurement habits across satellite locations. |
| Direct-to-Consumer Subscription Launch | Algorithm-matched curation platforms capture male professionals in Yeouido without eroding clinic-channel premium tiers. |
| Hanbang Formulation Heritage Investment | Traditional Korean herbal extraction methods command authenticity premiums against synthetic peptide commoditization in Asian specialty retail. |
| Multi-Regulatory Certification Buildout | Simultaneous MFDS, REACH, and FDA filing capabilities accelerate commercialization timelines for global product launches. |
Methodological Framework
Operator-level perspectives from dermatology clinic procurement managers, K-beauty contract manufacturing executives, peptide synthesis specialists, and cross-border e-commerce platform operators anchored the qualitative base. Secondary validation drew from MFDS regulatory filings, REACH nanomaterial safety dossiers, FDA cosmetic-drug classification determinations, and Seoul aesthetic cluster institutional procurement records. Bottom-up volume modeling triangulated against top-down market sizing across product type, ingredient concentration tier, end-user demographic, and distribution channel dimensions.
Scenario-bracketing around regulatory classification uncertainty and peptide synthesis capacity constraints framed the analytical approach across the projection horizon. Segmentation dimensions modeled included anti-aging versus repairing formulation philosophy, peptide versus retinol versus vitamin C active type, clinic versus online versus retail channel positioning, and geographic regulatory cluster. CAGRs derived from trend extrapolation of institutional procurement velocity and male skincare adoption curves, with inputs from liposomal encapsulation technology maturation timelines and MFDS disclosure mandate compliance costs.
Practitioners should monitor MFDS peptide pharmaceutical-grade reclassification debates and REACH nanomaterial threshold adjustments for early signals of margin structure disruption. Forecasts reflect assumptions around sustained clinic-channel premium anchoring and direct-to-consumer channel expansion velocity without regulatory chokepoint intervention. Material shifts in peptide synthesis capacity allocation or nanomaterial safety assessment timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Algae Skincare Products Market
Skincare
Anti-Acne Dermal Patch Market
Skincare
Hand Eczema (HE) Treatment Market
Skincare
Global Healthcare Wipes Market
Skincare
Skin Toner Market
Skincare
Global Cosmetic Skin Care Market
Skincare
Bangladesh Skin Care Products Market
Skincare
Dermocosmetics Market
Skincare
Vitamin C Serum Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Peel Off Face Mask Market
Skincare
United Kingdom Skincare Market
Skincare
Asia-Pacific Skincare Market
Skincare
Facial Cleansing Balm Market
Skincare
CBD Skin Care Market
Skincare
Hand Care Market