
 Skincare Cdmo and Cmo Market | 2026-2036
Skincare Cdmo and Cmo Market Size, Share, and Industry Trends Forecast 2026-2036
Skincare Cdmo and Cmo Market Analytics
South Korea is rewriting capacity dynamics in skincare contract manufacturing. Kolmar Korea anchors high-volume production for K-beauty exports across Asia and North America. Cosmax leverages integrated R&D-to-manufacturing platforms that compress development timelines for serum and moisturizer lines. Intercos S.P.A competes through color-cosmetics crossover expertise that extends into tinted sunscreen and treatment-makeup hybrids.
Skincare CDMO and CMO services encompass outsourced formulation development, stability testing, regulatory filing support, and commercial-scale manufacturing of topical dermatological and cosmetic products, typically operating under GMP conditions with validated cleanroom environments and documented batch records. The primary purpose is enabling brand owners to access specialized manufacturing capabilities without capital-intensive facility investment. Serums now command premium manufacturing slots due to complex active-ingredient handling requirements and shorter product lifecycles. Cream formulations sustain the largest volume base across client types, while startup clients represent the fastest-growing demand segment as venture-funded skincare brands prioritize asset-light launch strategies.
FDA cosmetic facility registration requirements under the Modernization of Cosmetics Regulation Act reshape market access timelines for US-bound production. REACH and the EU Green Deal constrain preservative and fragrance ingredient palettes, forcing reformulation cycles that CDMOs must absorb. South Korea's MFDS and China's NMPA maintain divergent testing standards for whitening and sunscreen claims, fragmenting regulatory pathways. Stakeholders must monitor which CDMOs build dual-approval capabilities across FDA and MFDS frameworks before committing long-term manufacturing partnerships.
Market Dynamics
Asset-light brand strategies are compressing captive manufacturing footprints as venture-funded skincare labels outsource end-to-end development to specialized contract partners with validated GMP infrastructure.
Growth Catalysts
- EU MDR and REACH frameworks:Tightened ingredient disclosure mandates push independent beauty brands toward compliant CDMO partners rather than self-managed facilities.
- Serum formulation complexity:Active-ingredient handling requirements for retinoids and peptides demand specialized cleanroom capabilities that contract manufacturers already possess.
- South Korea's K-beauty export engine:Concentrated manufacturing scale in Seoul-Incheon corridor enables rapid turnaround for North American and Southeast Asian brand clients.
Market Restraints
- Dual-approval burden:Divergent MFDS and FDA testing standards for whitening and sunscreen claims force redundant stability studies that extend commercialization timelines.
- Cleanroom capex concentration:South Korea and Italy host limited validated facilities, creating queue bottlenecks for premium manufacturing slots.
- Preservative palette constraints:EU Green Deal restrictions on traditional antimicrobials necessitate costly reformulation cycles without guaranteed efficacy equivalence.
Strategic Opportunities
- India's emerging brand ecosystem:Domestic venture capital in Mumbai and Bangalore is spawning skincare startups lacking captive production infrastructure.
- Tinted treatment-makeup hybrids:Cross-category demand for color-cosmetics expertise within skincare CDMOs opens margin expansion in sunscreen-BB cream formulations.
- China's NMPA pathway specialization:CDMOs building dual MFDS-NMPA filing capabilities capture mainland market access premiums.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in encapsulation technologies and emulsion stability commands salary premiums that strain mid-tier CDMO margins.
- Batch record digitization friction:Legacy paper-based quality systems resist integration with cloud-based client portals, slowing real-time collaboration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skincare Cdmo and Cmo Market |
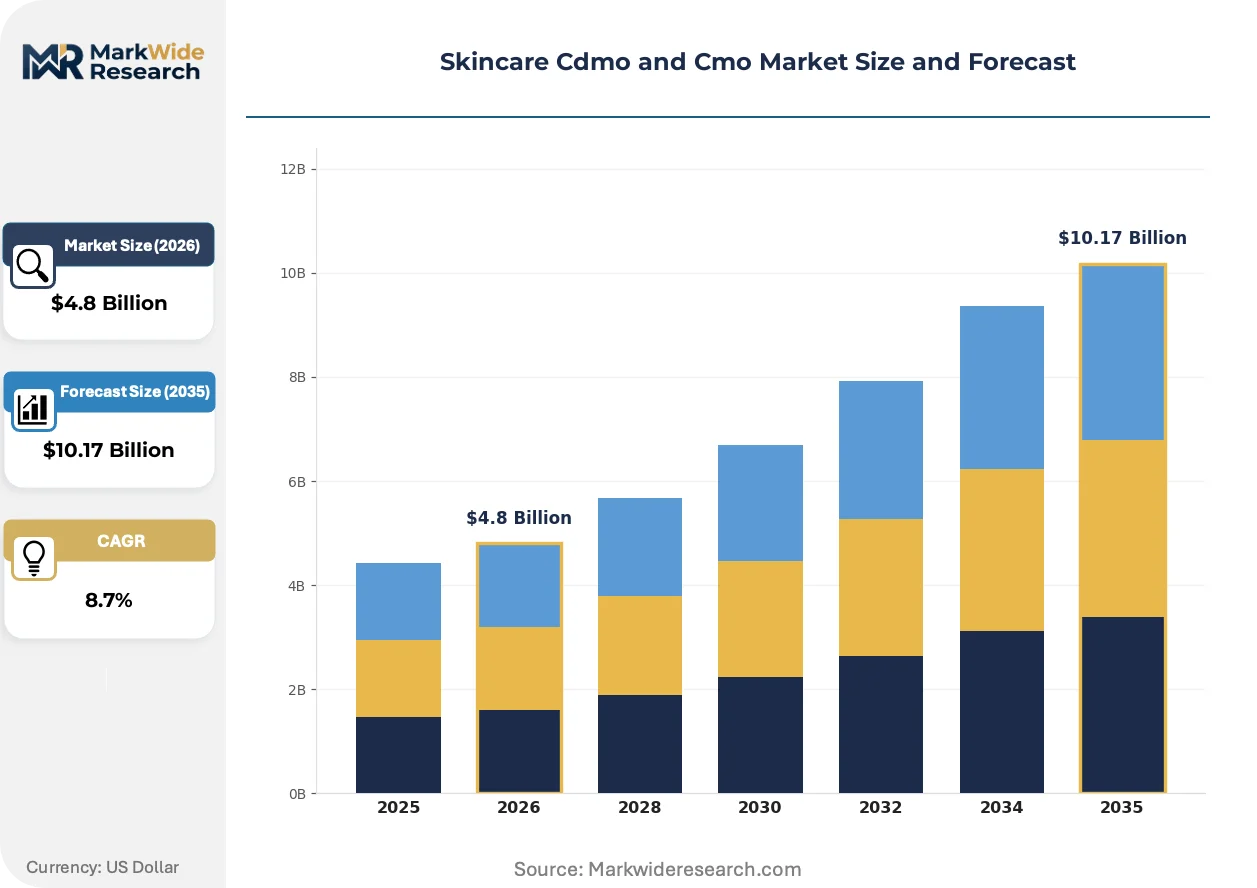
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Exfoliators, Sunscreens Formulation Type: Creams, Gels, Lotions, Oils Client Type: Brands, Retailers, Distributors, Startups Development Stage: Concept, Prototype, Clinical, Commercial |
| Companies Covered | Nutrix International LLC, Swiss American CDMO, Intercos S.P.A, Fareva Group, Kolmar Korea, Cosmax, Cosmetic Solutions, BPI Labs, Akums Drugs and Pharmaceuticals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skincare Cdmo and Cmo Market Evolving Landscape
Biotechnology-derived actives and modular manufacturing platforms are redefining how skincare CDMOs structure development timelines and capacity allocation across client tiers.
Encapsulation technology for sensitive actives is migrating from premium serum lines toward mass-market moisturizer formulations. Mid-tier brands in Germany and France now specify liposome and niosome delivery systems previously reserved for luxury positioning. This migration from high-end to mainstream applications compresses development cycle premiums that CDMOs historically captured.
REACH authorization requirements for novel cosmetic ingredients now mandate extended toxicity dossiers before commercial use. The industrial consequence is pre-formulation partnerships where CDMOs absorb early-stage safety testing costs to secure exclusive manufacturing rights. Sunscreen actives and preservative alternatives face the steepest documentation burdens.
Brand procurement teams now specify outcome-based development contracts with milestone payments tied to stability test completion rather than time-and-materials billing. CDMOs in South Korea and Switzerland are restructuring fee schedules to align with regulatory submission timelines. This model concentrates risk with manufacturers while accelerating client cash-to-market velocity.
Skincare Cdmo and Cmo Market Segmentation
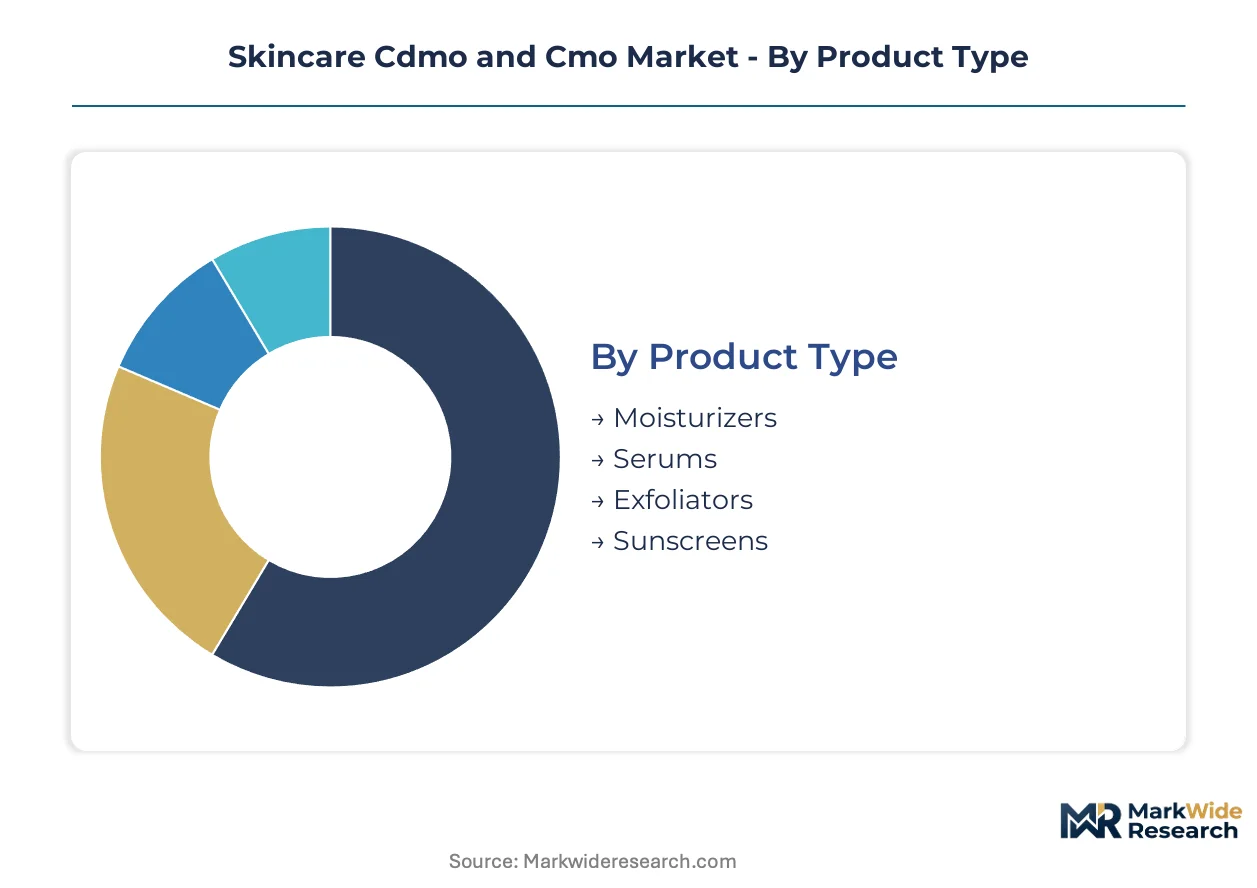
Segmentation in skincare contract manufacturing reveals distinct capability requirements across formulation complexity and client maturity. CDMOs must align cleanroom infrastructure, regulatory filing support, and batch scale with specific segment demands rather than offering uniform service tiers.
Product Type:
Mature segments dominate current manufacturing volumes while emerging categories reshape capacity allocation and technical investment priorities.
- Moisturizers:Emulsion-based formulations with varying oil-water ratios constitute the foundational production base across CDMO facilities. Mass-market brands in Germany and France sustain steady demand for standard cream and lotion variants with established preservative systems.
- Serums:High-actives concentrates require specialized handling for retinoids, peptides, and antioxidant complexes in validated cleanroom environments. South Korean CDMOs command premium slots for K-beauty export serums targeting North American and Southeast Asian markets, with compressed development timelines driving queue competition.
- Exfoliators:Alpha-hydroxy acid and beta-hydroxy acid formulations demand precise pH control and stability testing protocols.
- Sunscreens:Mineral and chemical UV filter blends face divergent MFDS and FDA testing standards that extend regulatory pathways.
Moisturizers retain volume leadership; serums hold the steepest expansion curve.
Formulation Type:
Cost tier differentiation separates premium positioning from mass-market production runs across CDMO client portfolios.
- Creams:Oil-in-water and water-in-oil emulsions represent the largest production volume across contract manufacturing facilities. European brands specify cream bases for anti-aging and barrier-repair positioning, with REACH-compliant preservative alternatives forcing reformulation cycles.
- Gels:Water-based, polymer-thickened systems enable lightweight sensorial profiles for humid climate markets. Southeast Asian brand clients prioritize gel moisturizers and serum vehicles that avoid occlusive residue in tropical conditions.
- Lotions:Lower viscosity emulsions serve body-care and daily facial applications with faster throughput rates.
- Oils:Anhydrous formulations for cleansing and facial treatment applications require oxygen-excluded processing environments.
Creams dominate manufacturing throughput; gels are expanding most quickly in tropical market formulations.
Client Type:
Customer type determines service model intensity, with venture-funded entrants demanding end-to-end development support distinct from established brand procurement patterns.
- Brands:Established beauty labels with existing formulation libraries seek manufacturing scale and regulatory filing assistance. Premium indie brands now outsource complete development to CDMO partners rather than building captive facilities, compressing traditional vertical integration strategies.
- Startups:Venture-funded skincare labels prioritize asset-light launch strategies with outsourced formulation, stability testing, and commercial production. Mumbai and Bangalore venture capital is spawning domestic Indian startups lacking captive infrastructure, creating concentrated demand for turnkey CDMO relationships.
- Retailers:Private-label programs for pharmacy and specialty chains require rapid formulation adaptation to trend cycles.
- Distributors:Regional market intermediaries commission localized variants of global formulations with adapted claims.
Brands retain volume leadership; startups hold the steepest expansion curve.
Development Stage:
Application maturity across the innovation pipeline determines CDMO revenue recognition timing and risk allocation structures.
- Commercial:Validated, scaled production of market-established formulations generates recurring manufacturing revenue. CDMOs in South Korea and Switzerland now structure outcome-based contracts with milestone payments tied to regulatory submission timelines rather than time-and-materials billing.
- Concept:Early-stage ideation and ingredient screening services absorb upfront R&D costs to secure exclusive manufacturing rights. REACH authorization requirements for novel cosmetic ingredients mandate extended toxicity dossiers, pushing CDMOs into pre-formulation partnerships for sunscreen actives and preservative alternatives.
- Prototype:Bench-scale batch development and initial stability screening precede clinical validation.
- Clinical:Safety and efficacy testing support for regulated claims including whitening and sun protection factor verification.
Commercial-stage production retains volume leadership; concept-stage services hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS oversight in South Korea anchors the most concentrated skincare manufacturing corridor, with Seoul-Incheon validated facilities serving K-beauty export demand across North America and Southeast Asia. The country's regulatory framework for whitening and sunscreen claims creates specialized compliance expertise that attracts multinational brand clients seeking dual-approval pathways.
South Korea
K-beauty export momentum drives specialized manufacturing scale in the Seoul-Incheon corridor, with CDMOs commanding premium slots for serum formulations targeting North American markets. MFDS maintains divergent testing standards for whitening claims that fragment regulatory pathways. Kolmar Korea and Cosmax anchor high-volume production with integrated R&D-to-manufacturing platforms.
United States
MoCRA facility registration requirements reshape market access timelines for domestic and foreign manufacturers supplying US-bound production. FDA cosmetic facility mandates push independent beauty brands toward compliant contract partners rather than self-managed facilities. New Jersey and California host validated GMP infrastructure serving venture-funded skincare labels prioritizing asset-light launch strategies.
Italy
Color-cosmetics crossover expertise extends into tinted sunscreen and treatment-makeup hybrids, with Lombardy-based manufacturers leveraging formulation heritage. REACH and EU Green Deal constraints on preservative and fragrance ingredient palettes force reformulation cycles that CDMOs must absorb. Milan's industrial cluster concentrates cleanroom capex for premium manufacturing slots.
Switzerland
Outcome-based development contracts with milestone payments tied to regulatory submission timelines restructure fee schedules for precision skincare brands. Swissmedic frameworks for novel cosmetic ingredients mandate extended toxicity dossiers before commercial use. Basel and Geneva regions host CDMOs building dual MFDS-FDA filing capabilities for multinational clients.
India
Domestic venture capital in Mumbai and Bangalore spawns skincare startups lacking captive production infrastructure, creating concentrated demand for turnkey CDMO relationships. CDSCO and BIS regulatory pathways for cosmetic manufacturing require validated facility compliance that emerging brands outsource to contract partners. Maharashtra and Karnataka industrial zones attract capacity investment serving both domestic and export markets.
Skincare Cdmo and Cmo Market Competitive Landscape
Capability concentration sits with integrated R&D-to-manufacturing platforms; scale advantage sits with high-volume export-oriented facilities. The market structures around three tiers: full-service CDMOs with regulatory filing support, specialized manufacturers focused on serum and active-ingredient handling, and regional players serving domestic brand ecosystems. Strategic moves concentrate on cleanroom capacity expansion in South Korea and Switzerland, plus pre-formulation partnerships that absorb early-stage safety testing costs to secure exclusive manufacturing rights.
Within the integrated platform tier, Kolmar Korea and Cosmax exemplify the Seoul-Incheon concentration that anchors K-beauty export manufacturing. Intercos S.P.A occupies a position representing European color-cosmetics crossover expertise extending into skincare hybrids. These three entities sit within distinct geographic and capability archetypes rather than direct head-to-head competition, with each representing a regional model that competitors elsewhere must adapt or counter.
| Leading Market Players |
|---|
| Nutrix International LLC |
| Swiss American CDMO |
| Intercos S.P.A |
| Fareva Group |
| Kolmar Korea |
| Cosmax |
| Cosmetic Solutions |
| BPI Labs |
| Akums Drugs and Pharmaceuticals Ltd. |
| Others |
Value Network & Pricing Analysis
Seoul-Incheon freight corridors carry K-beauty serum exports to North American distribution hubs, with per-kilogram logistics costs compressing margin structures for mid-tier contract manufacturers while premium cleanroom slots in South Korea command 40-60% price premiums over Italian equivalents. This geographic cost asymmetry feeds directly into how brands segment procurement between high-complexity active-ingredient formulations and standard emulsion bases.
Pricing Analysis
Price spreads between South Korean and European CDMOs now exceed three-to-one for validated serum manufacturing slots. Three-tier pricing structure across premium, standard, and economy levels reflects cleanroom certification grade and MFDS dual-approval status. Pricing pressure stems from venture-funded startups demanding milestone-based contracts that transfer stability-testing risk to manufacturers. Startup clients exhibit highest price sensitivity; multinational brands with existing formulation libraries prioritize compliance assurance over unit cost.
Supply Chain Analysis
EU REACH authorization requirements for novel cosmetic ingredients restrict cross-border flows of encapsulated retinoid technologies and preservative alternatives not yet cleared under extended toxicity dossiers. Manufacturing capacity concentrates in South Korea, Italy, and Switzerland, with raw material dependencies on Chinese peptide suppliers, German specialty chemical houses, and Japanese encapsulation technology providers. Single-source vulnerability sits with Seoul-Incheon cleanroom clusters where queue bottlenecks extend lead times. Distribution runs through brand-owned quality systems rather than third-party logistics, with batch-record digitization enabling direct client portal access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skincare contract manufacturing sits in early-cycle expansion as asset-light brand strategies displace captive facility investment among venture-funded entrants. K-beauty export momentum and REACH compliance burdens together accelerate outsourcing adoption beyond historical vertical integration patterns.
For Market Incumbents: Build regulatory filing moats by securing dual MFDS-FDA approval capabilities before competitors consolidate premium manufacturing slots. Kolmar Korea and Cosmax already anchor this positioning in Seoul-Incheon. Incumbents must absorb early-stage safety testing costs for novel sunscreen actives to lock exclusive manufacturing rights, while expanding cleanroom capacity in Switzerland to capture precision skincare brands demanding outcome-based contracts. The threat is mid-tier CDMOs in India undercutting on cost for standard emulsion formulations. For New Entrants and Emerging Players: Establish a beachhead in India's Mumbai-Bangalore startup corridor where domestic venture capital spawns skincare labels lacking captive infrastructure. White-space targets include turnkey CDMO relationships for concept-to-commercial development and NMPA pathway specialization serving China market access. The most penetrable segment is mid-market moisturizer lines where formulation complexity remains manageable without premium cleanroom investment. Go-to-market should emphasize rapid stability testing turnaround as competitive differentiator against established South Korean queues. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CDMOs with integrated R&D-to-manufacturing platforms over pure-play manufacturing assets. Long-term viability rests on capturing pre-formulation partnerships that absorb REACH authorization costs to secure exclusive rights. Acquisition targets should demonstrate dual-approval filing capabilities across MFDS and FDA frameworks. The signal to watch is queue depth for premium serum slots in validated Seoul-Incheon facilities, which indicates pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | South Korean CDMOs adding validated facilities in Seoul-Incheon corridor capture K-beauty export premiums. |
| Dual-Approval Filing Investment | MFDS-FDA pathway capabilities attract multinational brands seeking streamlined regulatory submission. |
| Pre-Formulation Partnership | Absorbing REACH toxicity dossier costs locks exclusive manufacturing rights for novel sunscreen actives. |
| Outcome-Based Contract Restructuring | Milestone payments tied to stability completion accelerate client cash-to-market velocity in Switzerland. |
| India Market Entry | Turnkey CDMO relationships target Mumbai-Bangalore venture-funded startups lacking captive infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand development executives, CDMO procurement leads, regulatory affairs specialists, and venture capital investors in Mumbai and Bangalore. Secondary validation drew from MFDS filing databases, FDA MoCRA facility registrations, REACH authorization dossiers, and EU Green Deal implementation guidance. Bottom-up capacity utilization data from Seoul-Incheon industrial zones was triangulated against top-down brand outsourcing expenditure patterns across North American and Southeast Asian markets.
Calibration anchored on historical capacity expansion timelines and regulatory approval pathway durations across the analysis window. Segmentation dimensions modeled include product type complexity, client maturity stage, formulation technology tier, and regional regulatory cluster. CAGRs were derived from capacity build-out announcements and queue depth indicators for premium manufacturing slots. Industry-specific forecast inputs incorporated K-beauty export volume trajectories and REACH authorization backlogs for novel cosmetic ingredients.
Sensitivities concentrate around MFDS-FDA testing standard convergence timelines and EU Green Deal preservative restriction implementation schedules. Forecasts reflect assumptions on cleanroom capex deployment rates and formulation chemist availability. Material shifts in REACH authorization requirements or K-beauty export tariff structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Cosmeceuticals Market
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Skin Antiseptic Market
Skincare
Anti-Acne Dermal Patch Market
Skincare
Sun-Care Wipes Market
Skincare
United Kingdom Skincare Market
Skincare
Herbal Skincare Products Market
Skincare
Personalized Skin Care Products Market
Skincare
Skin Care Emulsion Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
Mineral Sunscreen Market
Skincare
Body Scrub Market
Skincare
Skin Toner Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Sensitive Skin Care Products Market
Skincare
DNA-Based Skin Care Products Market