

Encapsulated Retinol Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulated Retinol Market Insights
Phospholipid-based delivery systems are recalibrating cost structures across the encapsulated retinol supply base as manufacturers trade synthetic polymer shells for biomaterial alternatives. BASF SE leverages its lipid chemistry portfolio to anchor European supply chains for liposomal retinol grades. DSM-Firmenich sustains R&D intensity in microsphere stabilization protocols that extend shelf life under variable temperature conditions. Croda International dominates specialty emulsion manufacturing for mid-tier personal care brands seeking turnkey encapsulation services.
Encapsulated retinol denotes vitamin A derivatives enclosed within protective carriers—typically 50-500 nanometer lipid bilayers or polymer matrices—to prevent oxidative degradation and enable targeted dermal release. The technology permits incorporation of retinol at concentrations previously incompatible with cosmetic stability requirements, primarily serving anti-aging and acne treatment formulations. Liposomes and microspheres capture disproportionate margin pools due to their established clinical validation and manufacturing scalability, while nanoparticle formats compete on bioavailability claims despite higher regulatory scrutiny. Anti-aging applications occupy the largest revenue share among therapeutic indications, though acne treatment segments are accelerating as dermatology clinics adopt prescription-strength encapsulated protocols.
The FDA oversees cosmetic ingredient safety through the Federal Food, Drug, and Cosmetic Act, while the EU REACH framework governs chemical registration and nanomaterial disclosure obligations for retinol-containing products entering European markets. ISO 16128 standards on natural and organic cosmetic ingredients further constrain formulation claims and raw material sourcing transparency for encapsulated actives. Stakeholders must monitor evolving nanomaterial classification protocols, as regulatory redefinitions of particle size thresholds could abruptly reshape compliance costs and market access conditions for several encapsulation formats.
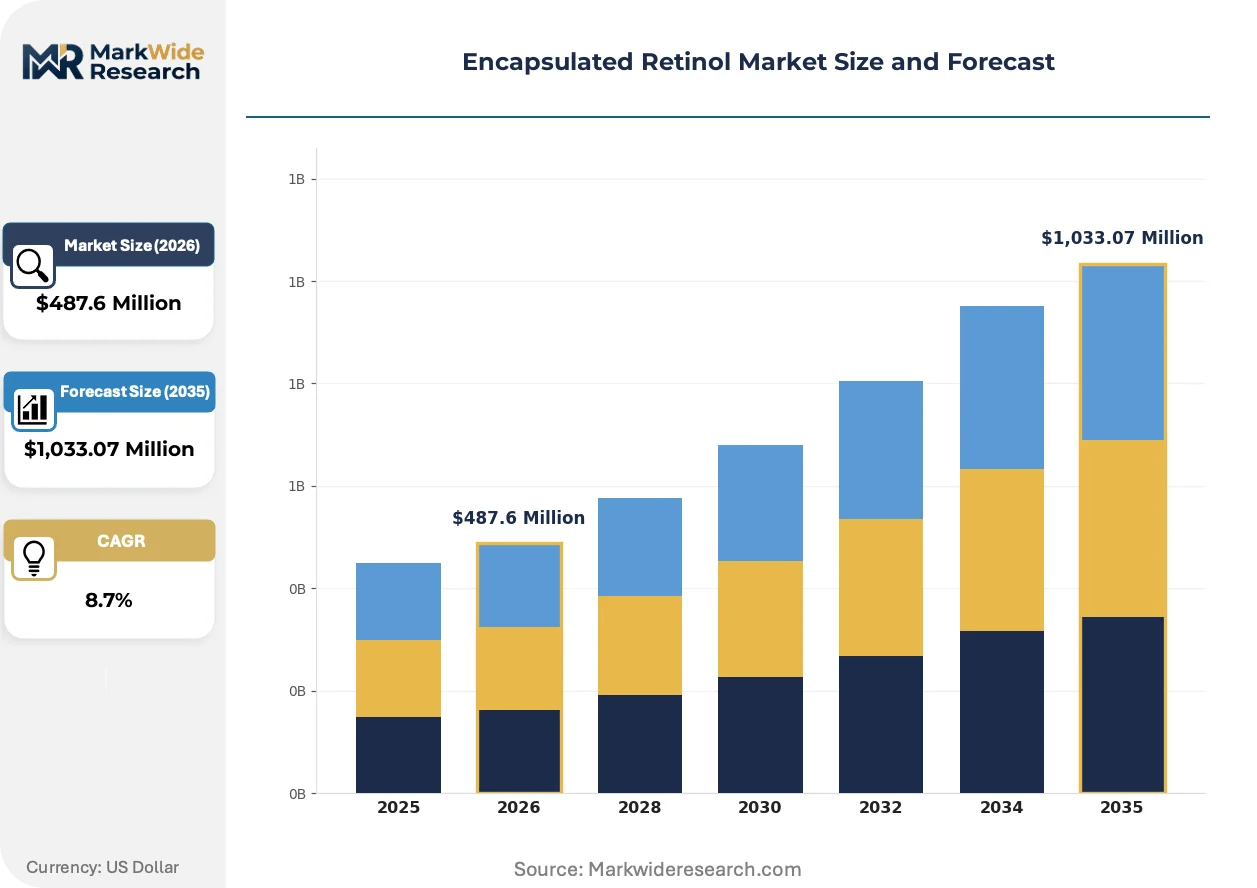
Market Dynamics
Phospholipid-based encapsulation systems are compressing synthetic polymer margins as cosmetic formulators prioritize biomaterial compatibility with ISO 16128 natural ingredient standards. This substrate transition is redrawing procurement relationships between raw material suppliers and turnkey encapsulation service providers.
Growth Catalysts
- Liposome manufacturing scale-up:European contract manufacturers are expanding liposomal production capacity to serve mid-tier personal care brands seeking stabilized retinol without in-house formulation expertise. REACH nanomaterial disclosure protocols have validated these formats for EU market entry.
- Dermatology clinic adoption:Prescription-strength encapsulated retinol protocols are penetrating medical aesthetics practices in the United States, creating pull-through demand for consumer-grade maintenance products. FDA oversight of cosmetic-drug distinction boundaries has clarified compliance pathways.
- Anti-aging serum premiumization:Direct-to-consumer skincare brands are reformulating flagship products with encapsulated actives to justify price positioning above mass-market alternatives. This concentrates volume in specialized emulsion manufacturing channels.
Market Restraints
- Phospholipid input cost volatility:Soy-derived and synthetic phospholipid feedstocks fluctuate with agricultural commodity cycles and oleochemical processing capacity constraints in Southeast Asia.
- Single-source encapsulation equipment:High-shear microfluidizer and extrusion systems for sub-200 nanometer particle production concentrate among German and Swiss precision engineering suppliers, creating procurement bottlenecks.
- Retinol oxidation shelf-life ceiling:Even encapsulated formats face 18-24 month stability limits under accelerated testing protocols, constraining inventory management flexibility for global distribution networks.
Strategic Opportunities
- Acne treatment protocol expansion:Combination therapies pairing encapsulated retinol with microbiome-targeted actives are entering clinical validation pipelines for adolescent and adult persistent acne segments.
- EU Green Deal biobased mandates:Encapsulation formats utilizing fermented lipid feedstocks qualify for preferential regulatory treatment under emerging EU sustainable chemistry frameworks, accelerating substitution of petroleum-derived polymer shells.
- Professional channel verticalization:Medical spa and aesthetic clinic dispensing models bypass traditional retail margin structures, enabling direct relationships between encapsulation specialists and treatment providers.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in lipid-phase behavior and particle size distribution control concentrates among aging technical workforces in European and North American cosmetic science programs.
- ISO 16128 compliance documentation:Natural and organic certification claims require extensive supply chain transparency for encapsulated actives, extending product development timelines by 8-14 months for brands seeking dual certification.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulated Retinol Market Trends and Innovations
Encapsulation technology platforms are bifurcating between established liposomal formats and next-generation polymer-lipid hybrid systems, with regulatory validation timelines becoming the primary competitive differentiator rather than technical performance alone.
Multilamellar liposome architectures are consolidating market share in premium anti-aging formulations as the dominant stabilized delivery format. Specialty personal care brands in France and Germany are adopting these structures at accelerated procurement rates compared to unilamellar alternatives. The technology is consolidating supplier relationships around European lipid chemistry specialists with integrated manufacturing capabilities.
EU REACH nanomaterial threshold revisions are forcing reformulation investments across the encapsulated retinol supply base. The proposed 1-100 nanometer particle size definition expansion would reclassify numerous microsphere formats, triggering new registration obligations and safety data requirements. German and French cosmetic manufacturers are pre-emptively adjusting encapsulation protocols to maintain market access continuity.
Subscription-based skincare replenishment models are concentrating demand forecasting complexity among encapsulation service providers. Direct-to-consumer brands in California and New York are compressing order cycle variability through predictive algorithms, forcing contract manufacturers to reconfigure batch scheduling around smaller, more frequent production runs. This operational shift is most visible in United States West Coast manufacturing clusters serving digitally native beauty brands.
Encapsulated Retinol Market Segmentation
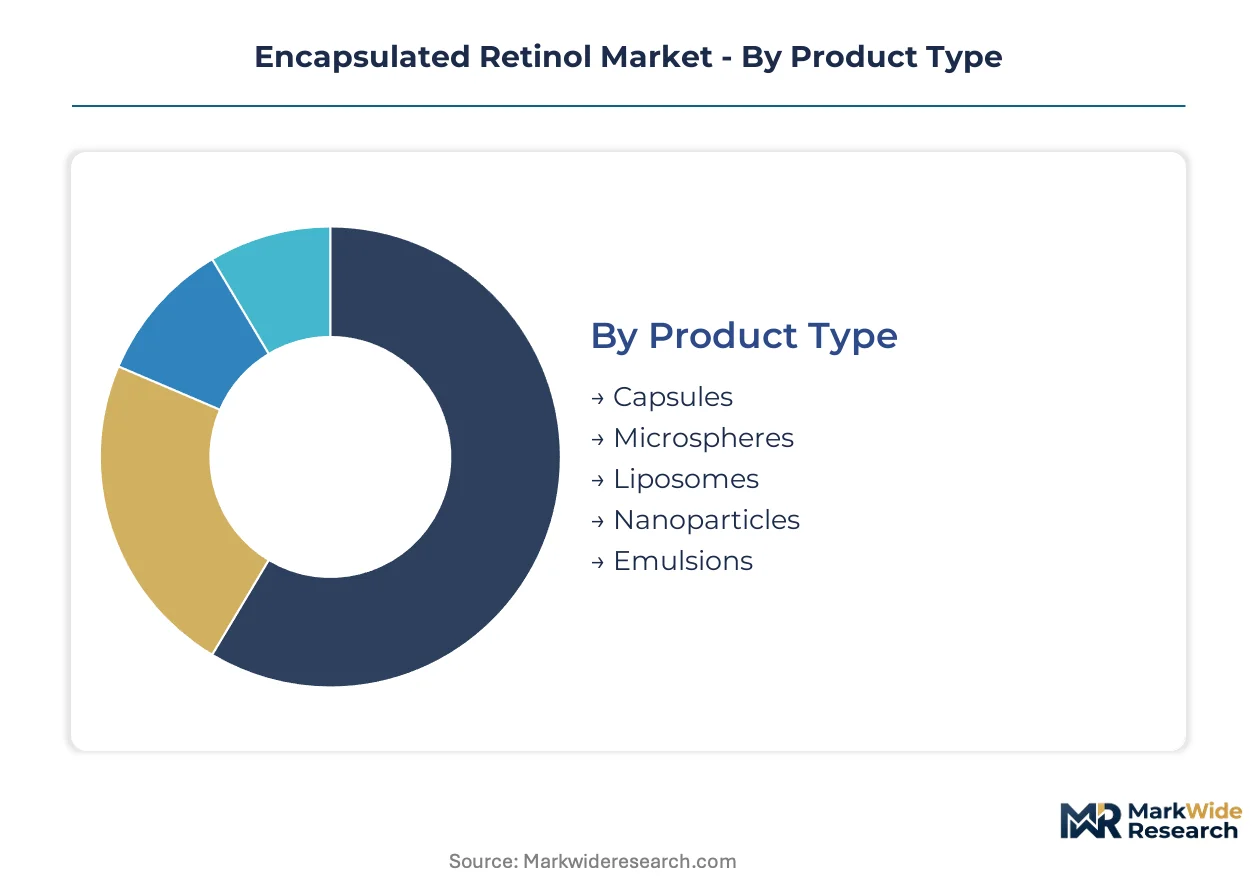
Encapsulated retinol markets fragment across delivery technology, therapeutic target, procurement channel, and preservation format. Each segmentation axis reveals distinct margin structures, regulatory exposure, and formulation complexity that determine supplier positioning.
Product Type:
Customization intensity spans turnkey liposomal solutions to proprietary nanoparticle architectures requiring dedicated R&D investment.
- Liposomes:Phospholipid bilayer carriers ranging 100-400 nanometers dominate premium anti-aging serums. Demand concentrates among French and German specialty brands seeking ISO 16128-compliant natural delivery systems, constrained by soy-derived phospholipid price volatility.
- Microspheres:Polymer-matrix encapsulation extends shelf stability to 24 months under accelerated testing protocols. United States dermatology clinics specify these formats for prescription-strength protocols, driving volume through medical aesthetics channels.
- Capsules:Single-dose gelatin or cellulose shells enable precise potency dosing for professional treatment settings.
- Nanoparticles:Sub-100 nanometer solid lipid carriers face heightened REACH disclosure scrutiny in European markets.
- Emulsions:Oil-in-water dispersions serve mass-market personal care brands prioritizing manufacturing simplicity over targeted release kinetics.
Leading the category by volume: Liposomes. Growing fastest: Microspheres.
Application:
Therapeutic indication determines concentration thresholds, clinical validation requirements, and channel access permissions.
- Anti-Aging:Collagen synthesis stimulation at 0.3-1.0% retinol equivalent concentrations commands premium pricing in direct-to-consumer subscription models. California and New York digitally native brands concentrate procurement for flagship serum reformulations.
- Acne Treatment:Keratinocyte turnover acceleration combined with sebaceous gland modulation drives adoption in adolescent and adult persistent acne protocols. United States medical spas are expanding dispensing relationships with encapsulation specialists for combination therapies.
- Skin Brightening:Melanin dispersion enhancement targets East Asian personal care markets with specific tone-evening claims.
- Wrinkle Reduction:Fine-line diminishment formulations compete with neuromodulator alternatives in aesthetic clinic menus.
- Hyperpigmentation:Post-inflammatory mark fading applications require stability under UV exposure conditions.
Anti-aging generates the largest revenue pool. Acne treatment is expanding most quickly.
End User:
Channel structure separates regulated medical dispensing from unrestricted retail distribution.
- Cosmetic Manufacturers:Mid-tier personal care brands in the United States source turnkey encapsulation services to bypass in-house formulation expertise gaps. Procurement concentrates among contract manufacturers with integrated emulsion capabilities.
- Dermatology Clinics:Prescription-strength protocols require FDA cosmetic-drug distinction compliance, creating barrier to entry for unvalidated encapsulation formats. United States medical aesthetics practices are consolidating supplier relationships around validated liposomal grades.
- Personal Care Brands:Direct-to-consumer marketers prioritize biomaterial compatibility for clean beauty positioning.
- Spa Centers:Professional treatment environments demand single-dose packaging for hygiene protocols.
- Beauty Salons:Retail-adjacent service providers seek consumer-grade maintenance product partnerships.
Cosmetic manufacturers dominate procurement volume. Dermatology clinics are gaining share fastest.
Packaging Type:
Oxygen and light exposure protection determines stability outcomes across distribution timelines.
- Airless Pumps:Vacuum-dispensing systems eliminate oxidation from air contact, extending encapsulated retinol efficacy through 18-month retail cycles. Premium United States skincare brands specify these formats for subscription replenishment models.
- Glass Bottles:Amber and cobalt UV-blocking containers serve pharmacy-positioned anti-aging lines in European markets with stringent stability labeling requirements.
- Plastic Jars:Wide-mouth containers accommodate cream textures despite repeated air exposure risks.
- Sachets:Single-use foil laminates enable sampling and travel formats with minimal preservation burden.
- Tubes:Collapsible aluminum or laminate structures balance portability with barrier properties.
Airless pumps lead by volume. Glass bottles are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dermatology clinics and direct-to-consumer skincare brands command the largest procurement volumes for stabilized retinol formats. European cosmetic manufacturers prioritize REACH-compliant phospholipid encapsulation systems. Asian markets concentrate demand in professional treatment channels.
United States
Medical aesthetics practices in California and New York are expanding prescription-strength encapsulated retinol protocols, creating pull-through demand for consumer maintenance products. FDA oversight of cosmetic-drug distinction boundaries has clarified compliance pathways for dermatology clinic dispensing models. West Coast manufacturing clusters serving digitally native beauty brands are reconfiguring batch scheduling around subscription replenishment algorithms.
Germany
Specialty personal care brands in Bavaria and North Rhine-Westphalia are adopting multilamellar liposome architectures at accelerated procurement rates. REACH nanomaterial disclosure protocols have validated liposomal formats for EU market entry, though proposed 1-100 nanometer threshold expansions are forcing preemptive reformulation investments. Precision engineering suppliers in Baden-Württemberg dominate high-shear microfluidizer production for sub-200 nanometer particle systems.
France
Paris-based cosmetic houses are prioritizing ISO 16128-compliant natural delivery systems for premium anti-aging serums. ANSM oversight of nanomaterial classification intersects with ECHA registration obligations for retinol-containing formulations. The Île-de-France region anchors European lipid chemistry specialists with integrated liposomal manufacturing capabilities.
Japan
Shiseido and domestic competitors are advancing polymer-lipid hybrid encapsulation systems for skin-brightening applications targeting East Asian tone-evening claims. METI guidance on functional cosmetic labeling shapes formulation claims and clinical validation requirements. The Kanto region concentrates R&D intensity in microsphere stabilization protocols for extended shelf-life performance.
South Korea
Seoul Capital Area beauty brands are compressing product development cycles for K-beauty export markets, prioritizing biomaterial compatibility for clean beauty positioning. MFDS regulation of functional cosmetics creates barrier-to-entry dynamics for unvalidated encapsulation formats. Busan-Ulsan manufacturing corridors are expanding contract encapsulation capacity for mid-tier personal care brands.
Encapsulated Retinol Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with turnkey encapsulation service providers capturing mid-tier personal care volume while integrated chemical houses dominate premium liposomal grades. The supplier base concentrates around European lipid chemistry specialists and German precision engineering fabricators, creating tiered procurement relationships based on formulation complexity and regulatory validation depth. Three archetypes define competitive positioning: integrated chemical conglomerates with lipid chemistry portfolios, specialty emulsion contract manufacturers, and vertically integrated beauty houses with captive encapsulation capabilities. Capacity expansion and strategic technology licensing represent the dominant competitive moves, with players securing phospholipid feedstock relationships and high-shear processing equipment access.
Among European chemical conglomerates, BASF SE and DSM-Firmenich exemplify integrated players leveraging lipid chemistry and stabilization protocol expertise respectively. Evonik Industries occupies a position within the specialty materials tier, while Croda International represents the contract manufacturing archetype serving mid-tier brands without in-house formulation capabilities.
| Leading Market Players |
|---|
| BASF SE |
| DSM-Firmenich |
| Givaudan |
| Merck KGaA |
| Evonik Industries |
| Croda International |
| Symrise |
| Shiseido Company |
| Estée Lauder Companies |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal biobased mandates gate qualified phospholipid supply and premium-tier pricing access for cosmetic manufacturers seeking ISO 16128-compliant encapsulation formats. Fermented lipid feedstock certification separates contract manufacturers commanding stability premiums from commodity emulsion suppliers facing margin compression.
Pricing Analysis
Volume concentrates in mass-market emulsion tiers while margin pools accrue to liposomal and microsphere specialists serving dermatology clinics and direct-to-consumer subscription brands. Price differentiation hinges on ISO 16128 natural certification status and REACH nanomaterial disclosure validation, with phospholipid input cost volatility pressuring mid-tier contract manufacturers most acutely. Subscription-based replenishment models exhibit lowest price sensitivity, while mass-market personal care brands face acute cost compression from soy-derived feedstock fluctuations.
Supply Chain Analysis
Phospholipid supply rests on German and French lipid chemistry specialists with integrated manufacturing capabilities, while high-shear microfluidizer equipment concentrates among Baden-Württemberg and Swiss precision engineering fabricators. Soy-derived and synthetic phospholipid feedstocks, sub-200 nanometer particle production systems, and REACH-compliant formulation documentation constitute critical input dependencies. Single-source encapsulation equipment vulnerability creates procurement bottlenecks for sub-200 nanometer production. Distribution runs through turnkey contract manufacturers serving mid-tier brands and direct relationships between encapsulation specialists and United States dermatology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulated retinol supply is tightening around qualified phospholipid feedstock relationships and high-shear processing equipment access, with single-source equipment concentration propping pricing power for validated European suppliers.
For Market Incumbents: Anchor phospholipid supply relationships through backward integration into fermented lipid feedstock production or long-term offtake agreements with EU Green Deal-certified suppliers. Expand liposomal manufacturing capacity in Bavaria and North Rhine-Westphalia to capture dermatology clinic volume migrating from unencapsulated alternatives. Defend against polymer-lipid hybrid entrants by accelerating multilamellar architecture clinical validation. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable route for encapsulated retinol market entry, bypassing retail margin structures that favor incumbent scale. Target acne treatment protocol expansion in United States medical spas seeking combination therapy partners. Pursue white-label encapsulation services for mid-tier personal care brands lacking in-house formulation expertise. For Investors and Strategic Acquirers: REACH nanomaterial threshold revision announcements are the leading indicator that regulatory validation depth will separate acquirees from stranded asset risks. Five-to-ten year viability favors turnkey encapsulation service providers with integrated emulsion capabilities and established FDA cosmetic-drug distinction compliance. Monitor ECHA registration obligation expansions for microsphere format reclassification signals.| Strategic Initiative | Industry Significance |
|---|---|
| Phospholipid Feedstock Backward Integration | Fermented lipid supply agreements with EU Green Deal-certified producers secure ISO 16128 compliance and margin protection. |
| High-Shear Microfluidizer Capacity Expansion | Sub-200 nanometer liposomal production scale-up in Baden-Württemberg addresses dermatology clinic demand concentration. |
| REACH Preemptive Reformulation Investment | Particle size protocol adjustments ahead of ECHA threshold expansions preserve European market access continuity. |
| Direct-to-Consumer Channel Partnership | Subscription replenishment algorithm integration with California and New York digitally native brands concentrates volume forecasting. |
| Acne Treatment Clinical Validation Program | Combination therapy protocols with microbiome-targeted actives penetrate adolescent and adult persistent acne segments. |
Research Methodology
Trade databases, ECHA registration filings, and FDA cosmetic ingredient safety guidance formed the secondary backbone for supply chain mapping and regulatory pathway analysis. Primary interviews with encapsulation service provider technical directors, cosmetic manufacturer procurement leads, dermatology clinic dispensing managers, and phospholipid feedstock suppliers combined with secondary validation through SEC filings and REACH disclosure records. Bottom-up and top-down triangulation cross-referenced contract manufacturing capacity announcements with downstream brand formulation procurement patterns.
Bottom-up modeling anchored volume projections in individual encapsulation service provider capacity configurations, while top-down validation assessed aggregate cosmetic manufacturer R&D spending patterns across the projection horizon. Segmentation dimensions spanned delivery technology, therapeutic indication, procurement channel, and preservation format, with CAGRs derived from weighted average growth rates across liposomal, microsphere, and nanoparticle technology trajectories. Phospholipid price indices and REACH nanomaterial classification protocol evolution served as industry-specific forecast inputs.
The model holds under stable REACH nanomaterial threshold definitions and continued EU Green Deal biobased mandate enforcement; deviation in ECHA particle size reclassification or phospholipid feedstock supply disruption would shift volume-mix assumptions. Forecasts reflect documented assumptions regarding liposomal manufacturing scale-up timelines and dermatology clinic adoption curves. REACH threshold revisions, phospholipid commodity cycles, and formulation chemist workforce availability constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.