
 Global Anti-Aging Products and Services Market | 2026-2036
Global Anti-Aging Products and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Aging Products and Services Market Foresight
Biotechnology-driven ingredient synthesis is reconfiguring formulation architectures across the anti-aging sector, replacing traditional emollient bases with peptide-infused delivery systems and microbiome-targeted actives. L'Oréal S.A. leverages extensive dermal science archives to sustain patent-protected molecule pipelines, while Estée Lauder Companies Inc. anchors prestige positioning through controlled distribution in dedicated retail environments. Shiseido Company, Limited differentiates via East Asian skin biology specialization, occupying research niches that Western competitors navigate less effectively.
Anti-aging products and services encompass topical formulations, ingestible nutraceuticals, energy-based devices, and professional protocols engineered to retard or reverse visible and functional markers of senescence, with active concentrations typically measured in peptide mass fractions or retinoid potency equivalents (e.g., 0.3–1.0% retinol standardization) and laser systems calibrated to specific dermal penetration depths measured in nanometers. Injectable fillers and laser devices capture disproportionate margin pools as clinic-based delivery commands premium pricing over retail topicals, while dietary supplements represent the fastest-expanding category as consumers integrate systemic approaches to cellular maintenance. Medical spa treatments and cosmetic dermatology services now structure revenue allocation across the service type dimension, with wellness coaching emerging as a high-frequency, lower-ticket attachment offering.
FDA premarket notification (510(k)) requirements for laser and light-based devices, combined with EU MDR Class IIa/IIb certification obligations and REACH compliance for cosmetic ingredient safety dossiers, elevate barriers for new entrants while mandating clinical evidence portfolios that incumbent firms must maintain. Japan's PMDA and South Korea's MFDS impose additional localized testing protocols that fragment approval pathways for device manufacturers seeking multi-regional deployment. Stakeholders must monitor regulatory divergence between aesthetic device classification systems and cosmetic ingredient restriction lists as these frameworks determine which innovation pipelines warrant capital commitment versus geographic abandonment.
Market Dynamics
Professional-grade energy-based devices are migrating from hospital settings to outpatient aesthetic centers, compressing treatment delivery timelines while elevating safety documentation burdens under converging FDA 510(k) and EU MDR pathways.
Growth Catalysts
- EU MDR Class IIa/IIb certification:Tightened safety documentation requirements for laser devices are accelerating consolidation among incumbent manufacturers with established clinical evidence portfolios.
- Seoul's Gangnam district:Consumer willingness to pay premium prices for preventive aesthetic protocols anchors both innovation clusters and early adoption curves for peptide-infused delivery systems.
- Microbiome-targeted actives:Biotechnology-driven ingredient synthesis is reconfiguring formulation architectures and opening patent-protected molecule pipelines across topical and ingestible categories.
Market Restraints
- Input cost volatility in rare-earth laser components:Supply concentration for ytterbium and erbium doped fibers in Chinese processing facilities creates margin pressure on device manufacturers.
- FDA premarket notification timelines:Extended 510(k) review cycles for novel wavelength systems delay multi-regional deployment and compress competitive windows.
- Technical limitation in dermal penetration depth control:Nanometer-precision calibration requirements for fractional lasers restrict formulation flexibility in home-use device segments.
Strategic Opportunities
- Underpenetrated Brazil aesthetic clinic networks:ANVISA regulatory harmonization with FDA pathways is reducing approval friction for professional-grade laser systems in outpatient settings.
- Wellness coaching attachment models:High-frequency, lower-ticket service offerings are expanding addressable spend per patient across medical spa treatment protocols.
- Convergence of ingestible nutraceuticals and topical peptide systems:Systemic cellular maintenance approaches are opening cross-category bundling opportunities in preventive aesthetic protocols.
Industry Challenges
- Photonics engineering talent scarcity:Specialized expertise in fractional laser calibration and dermal depth mapping remains concentrated in South Korean and German device manufacturers.
- REACH compliance documentation burden:Cosmetic ingredient safety dossiers for novel microbiome actives require multi-year toxicology investment before EU market entry.
- Integration complexity with legacy clinic management systems:Energy-based device manufacturers face friction connecting treatment-parameter logging to existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Aging Products and Services Market |
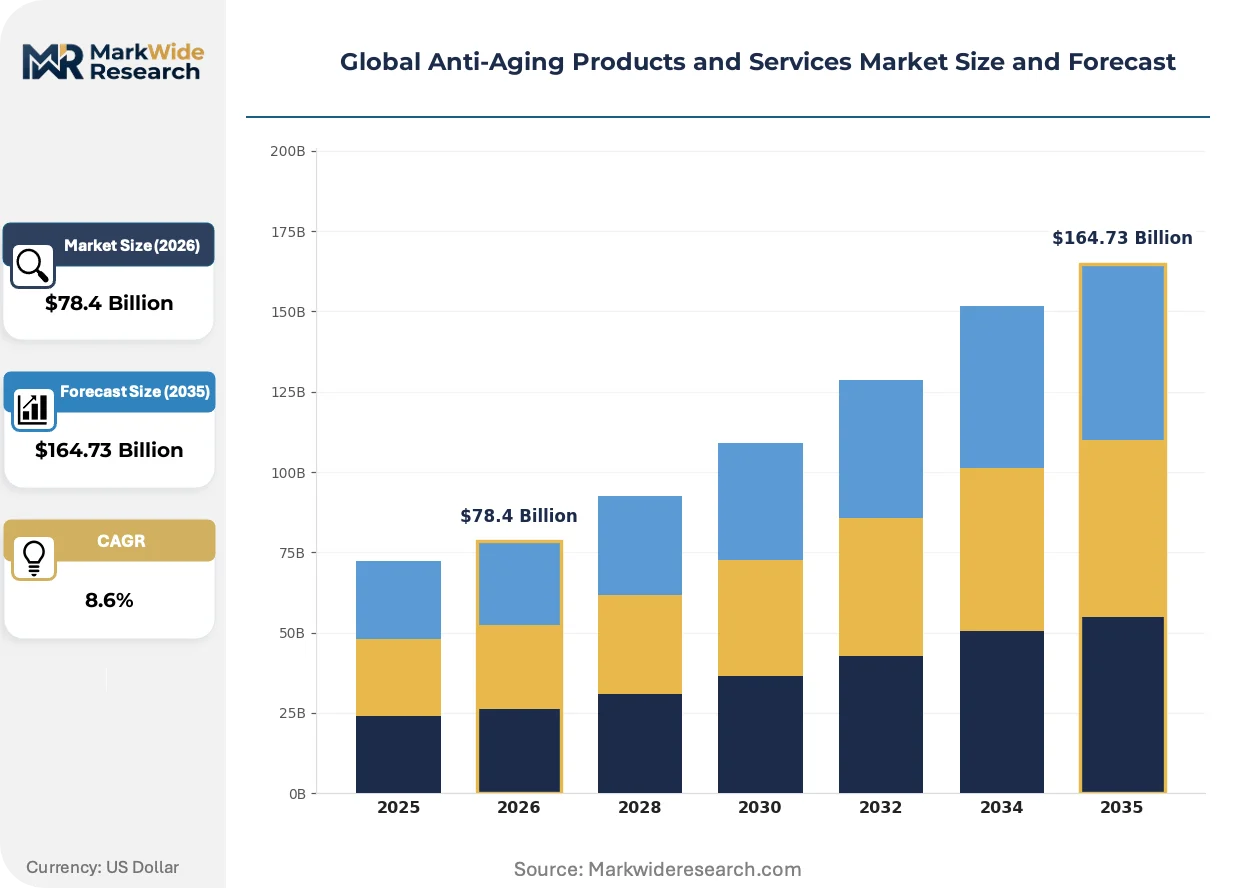
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Serums, Dietary Supplements, Injectable Fillers, Laser Devices, Facial Masks Service Type: Medical Spa Treatments, Cosmetic Dermatology, Nutritional Consulting, Personalized Therapy, Fitness Programs, Wellness Coaching Application: Wrinkle Reduction, Skin Firming, Age Spot Treatment, Hair Thinning, Joint Support, Stress Management Customer Type: Individual Consumers, Dermatology Clinics, Aesthetic Centers, Wellness Resorts, Fitness Enthusiasts, Pharmacies |
| Companies Covered | L'Oréal S.A., Procter & Gamble Company, Unilever PLC, Estée Lauder Companies Inc., Beiersdorf AG, Shiseido Company, Limited, AbbVie Inc., Merck KGaA, Lumenis Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Aging Products and Services Market Shifts & Advancements
Artificial intelligence is digitizing treatment-parameter optimization across energy-based devices while regulatory frameworks fragment across major economies and consumer procurement patterns shift toward bundled preventive protocols.
AI-driven skin analysis platforms are digitizing diagnostic workflows in dermatology clinics. Aesthetic centers in South Korea and the United States are deploying these systems to calibrate laser penetration depths and peptide delivery protocols in real-time. This capability is compressing consultation-to-treatment cycles while elevating outcome consistency standards across professional service tiers.
REACH restrictions on persistent organic pollutants are forcing reformulation of traditional emollient bases in European markets. Cosmetic ingredient suppliers must submit enhanced safety dossiers for retinoid potency equivalents above 0.5% standardization. Professional-grade topical manufacturers are responding by accelerating peptide-infused delivery system development to maintain efficacy claims under tightened chemical safety thresholds.
Subscription-based preventive aesthetic protocols are displacing episodic treatment purchases in urban consumer segments. Medical spa operators in Seoul and Los Angeles are bundling quarterly laser maintenance with monthly nutraceutical deliveries and digital skin-monitoring access. This model concentrates patient lifetime value while requiring clinic operators to reconfigure inventory management and staffing cadences around recurring revenue patterns.
Global Anti-Aging Products and Services Market Segmentation
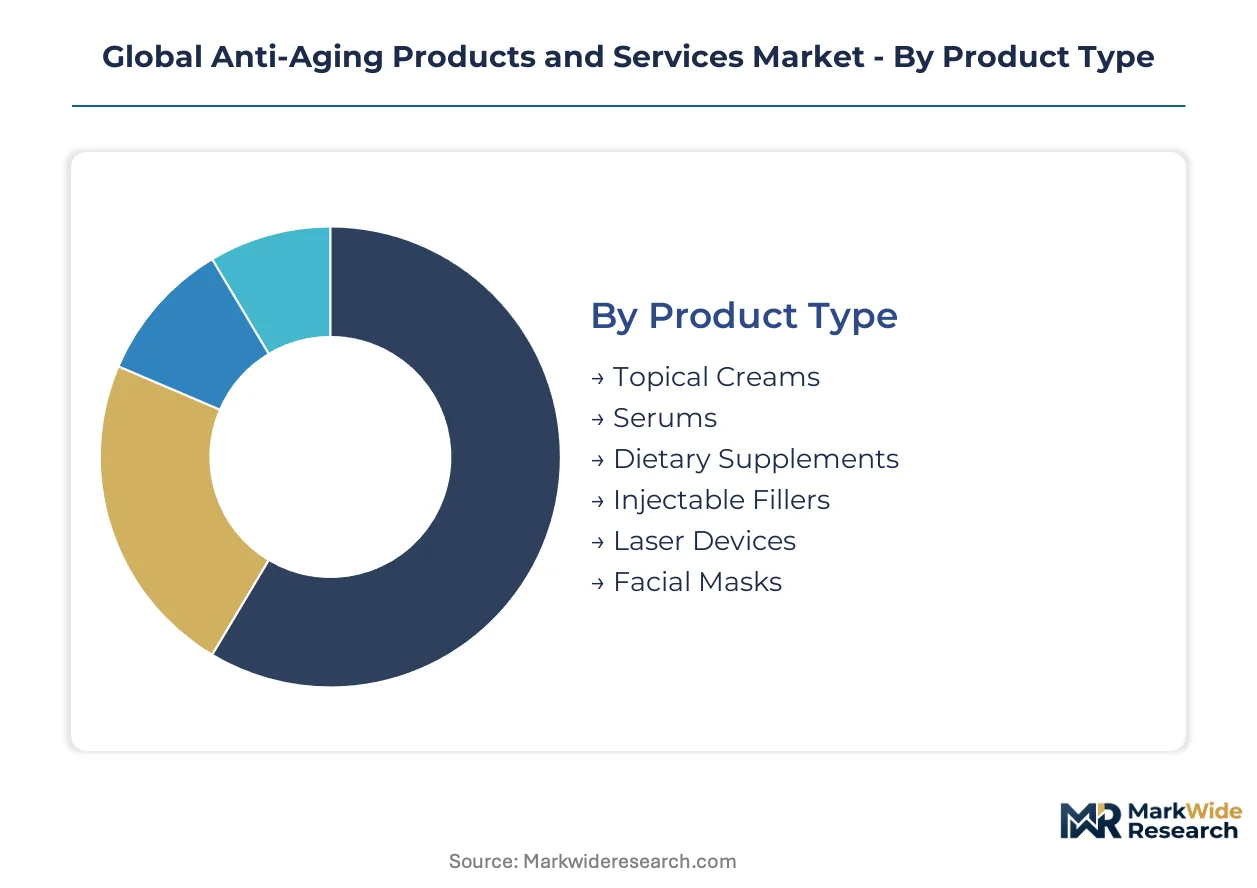
Anti-aging market segmentation reflects divergent consumer sophistication levels, from mass-market topical users to clinic-based protocol adopters seeking calibrated outcomes. Understanding these partitions clarifies where formulation innovation, device engineering, and service bundling concentrate investment returns.
Product Type:
Mature emollient formats coexist with emerging biotechnology delivery systems across this dimension, revealing a market in generational transition.
- Topical Creams:Traditional emollient bases incorporating retinoid potency equivalents between 0.3–1.0% dominate mass retail distribution. Demand concentrates in North American pharmacy chains where consumers prioritize accessible price points over clinical-grade outcomes.
- Laser Devices:Energy-based systems calibrated to nanometer-precision dermal penetration depths command premium positioning in outpatient aesthetic centers. Seoul's Gangnam district anchors both innovation clusters and early adoption curves for fractional laser protocols, though FDA 510(k) and EU MDR Class IIa/IIb certification requirements compress competitive windows for new entrants.
- Serums:Peptide-infused delivery systems with microbiome-targeted actives are gaining traction among prestige consumers seeking concentrated bioactive formulations.
- Dietary Supplements:Ingestible nutraceuticals represent the fastest-expanding category as consumers integrate systemic cellular maintenance approaches into preventive aesthetic routines.
- Injectable Fillers:Clinic-based delivery commands disproportionate margin pools through professional administration requirements and immediate visible outcomes.
- Facial Masks:Sheet and hydrogel formats serve as entry-point products for younger demographics building skincare adherence before upgrading to active serums.
Topical Creams retain volume leadership; Dietary Supplements hold the steepest expansion curve.
Service Type:
Margin tiering separates high-frequency wellness attachments from capital-intensive clinical interventions across this dimension.
- Medical Spa Treatments:Outpatient aesthetic centers bundle energy-based device protocols with recovery amenities, compressing hospital-to-clinic migration timelines. Brazil's ANVISA regulatory harmonization with FDA pathways is reducing approval friction for professional-grade laser deployment.
- Wellness Coaching:High-frequency, lower-ticket service offerings expand addressable spend per patient through digital skin-monitoring access and recurring nutraceutical deliveries. Los Angeles medical spa operators are reconfiguring inventory management around these subscription-based preventive aesthetic protocols.
- Cosmetic Dermatology:Physician-supervised interventions including injectable administration and laser calibration maintain premium positioning through outcome liability concentration.
- Nutritional Consulting:Systemic cellular maintenance guidance bridges topical and ingestible product categories for integrated protocol adoption.
- Personalized Therapy:Genomic and microbiome-based customization commands price premiums from early adopters seeking individualized senescence retardation strategies.
- Fitness Programs:Physical conditioning protocols are attaching to aesthetic service bundles as consumers pursue functional longevity alongside visible anti-aging outcomes.
Cosmetic Dermatology captures the highest per-transaction value; Wellness Coaching is climbing the fastest as operators pivot toward recurring revenue architectures.
Application:
Customer age demographics and concern severity stratify demand concentration across functional outcome targets.
- Wrinkle Reduction:Peptide-infused delivery systems and fractional laser protocols target dermal collagen remodeling, with professional-grade treatments migrating from hospital settings to outpatient aesthetic centers. EU REACH restrictions on persistent organic pollutants are forcing reformulation of traditional emollient bases in European markets.
- Skin Firming:Energy-based devices with nanometer-precision calibration requirements restrict formulation flexibility in home-use segments while elevating clinic-based service premiums.
- Age Spot Treatment:Laser wavelength specificity for melanin targeting differentiates professional protocols from retail topical alternatives.
- Hair Thinning:Topical and ingestible convergence is opening cross-category bundling opportunities in preventive aesthetic protocols addressing follicular senescence.
- Joint Support:Systemic cellular maintenance approaches through collagen peptides and anti-inflammatory nutraceuticals expand the addressable consumer base beyond dermatological concerns.
- Stress Management:Cortisol regulation protocols are emerging as attachment offerings within comprehensive wellness coaching frameworks.
Wrinkle Reduction retains volume leadership; Joint Support is gaining share fastest as demographic aging expands functional longevity priorities beyond cosmetic outcomes.
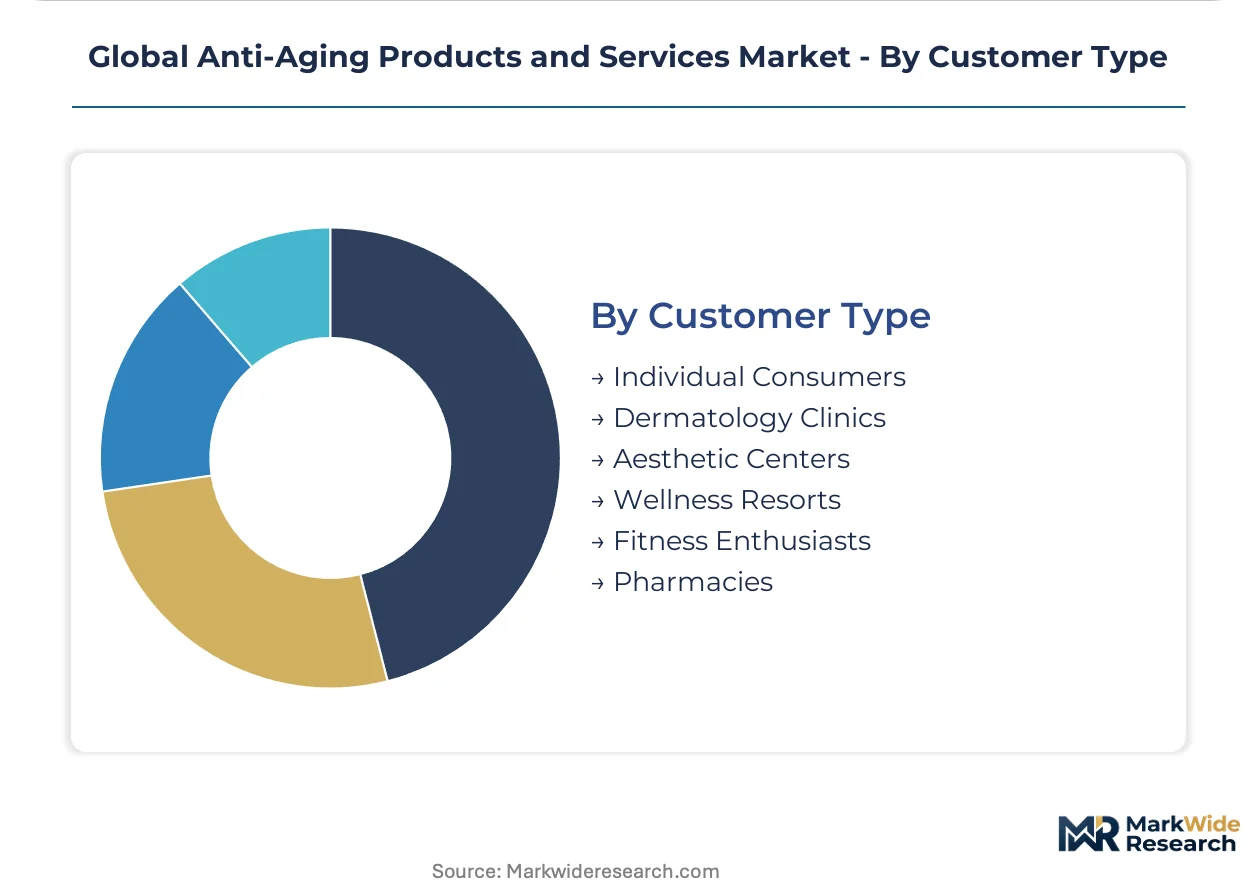
Customer Type:
Procurement sophistication and regulatory exposure diverge sharply between individual consumers and institutional buyers across this dimension.
- Dermatology Clinics:Professional-grade energy-based device purchasers face converging FDA 510(k) and EU MDR safety documentation burdens while commanding premium pricing through calibrated outcome delivery. Photonics engineering talent scarcity in fractional laser calibration remains concentrated among South Korean and German device manufacturers.
- Aesthetic Centers:Outpatient facilities are deploying AI-driven skin analysis platforms to compress consultation-to-treatment cycles and elevate outcome consistency standards across service tiers.
- Individual Consumers:Mass retail purchasers drive volume through pharmacy and e-commerce channels, with peptide-infused delivery systems displacing traditional emollient bases among prestige segments.
- Wellness Resorts:Destination facilities bundle preventive aesthetic protocols with hospitality amenities, requiring inventory management reconfiguration around guest stay durations.
- Fitness Enthusiasts:Performance-oriented consumers are adopting ingestible nutraceuticals for systemic cellular maintenance alongside physical conditioning regimens.
- Pharmacies:Retail pharmacy networks serve as gatekeepers for mass-market topical accessibility, with retinoid potency standardization influencing shelf placement decisions.
Individual Consumers retain volume leadership; Aesthetic Centers hold the steepest expansion curve as professional-grade treatments accelerate outpatient migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean device manufacturers export fractional laser systems to outpatient aesthetic centers in Brazil and the United States, establishing Seoul's Gangnam district as the primary innovation corridor for energy-based treatment protocols.
United States
Outpatient aesthetic centers in Los Angeles and New York Metro deploy AI-driven skin analysis platforms to compress consultation cycles. FDA 510(k) premarket notification requirements for novel wavelength systems extend review timelines and compress competitive windows for device entrants. Greater Boston anchors photonics engineering talent clusters concentrated in fractional laser calibration expertise.
South Korea
Seoul's Gangnam district commands premium pricing for preventive aesthetic protocols and peptide-infused delivery systems. MFDS localized testing protocols fragment approval pathways for manufacturers seeking multi-regional deployment. Busan-Ulsan corridor houses concentrated rare-earth laser component processing facilities for ytterbium-doped fiber production.
Germany
EU MDR Class IIa/IIb certification obligations elevate safety documentation burdens for laser device manufacturers. ECHA REACH compliance mandates multi-year toxicology investment for novel microbiome actives before EU market entry. Baden-Württemberg hosts precision photonics engineering clusters specializing in nanometer-precision dermal depth calibration.
Brazil
ANVISA regulatory harmonization with FDA pathways reduces approval friction for professional-grade laser systems in outpatient settings. São Paulo aesthetic clinic networks represent underpenetrated expansion opportunities for energy-based device protocols. Rio de Janeiro medical spa operators pilot subscription-based preventive aesthetic bundling models.
Japan
PMDA imposes additional localized testing protocols that complicate multi-regional deployment for device manufacturers. METI standards guide cosmetic ingredient safety dossier preparation for peptide mass fraction formulations. Kanto/Tokyo region concentrates demand for ingestible nutraceuticals addressing systemic cellular maintenance.
Global Anti-Aging Products and Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation pressures favor incumbent manufacturers with established clinical evidence portfolios under converging FDA and EU MDR pathways. Three archetypes dominate: multinational beauty conglomerates with dermal science archives, pharmaceutical-device hybrids with regulatory navigation capabilities, and regional specialists with East Asian skin biology expertise. Competitive moves concentrate on strategic partnerships for AI-driven diagnostic integration and portfolio diversification into ingestible nutraceutical categories.
Among multinational beauty conglomerates, L'Oréal S.A. and Estée Lauder Companies Inc. occupy positions sustained by patent-protected molecule pipelines and controlled prestige distribution. Shiseido Company, Limited exemplifies regional specialization archetypes leveraging East Asian skin biology research niches. These three anchors represent divergent strategic postures: archive-driven formulation innovation, retail environment control, and geographic research specialization.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Procter & Gamble Company |
| Unilever PLC |
| Estée Lauder Companies Inc. |
| Beiersdorf AG |
| Shiseido Company, Limited |
| AbbVie Inc. |
| Merck KGaA |
| Lumenis Ltd. |
| Others |
Supply & Pricing Matrix
Underutilization in South Korean fractional laser manufacturing facilities is compressing margins for device producers while simultaneously elevating pricing power for concentrated rare-earth fiber suppliers in the Busan-Ulsan corridor. This asymmetry between downstream overcapacity and upstream supply control reshapes procurement strategies for aesthetic clinic operators seeking equipment financing flexibility.
Pricing Analysis
Next-generation AI-integrated laser systems command premium positioning at roughly double the per-session economics of prior-generation fractional platforms, while current-gen devices face accelerating price erosion in secondary markets. Three-tier pricing structure across premium, standard, and economy levels segments buyers by outcome liability tolerance and certification requirements, with FDA 510(k) clearance tier commanding substantial premiums over CE-marked equivalents. Pricing pressure stems from extended FDA premarket notification timelines compressing competitive windows for novel wavelength entrants. Individual consumers in pharmacy channels exhibit highest price sensitivity, while dermatology clinics demonstrate lowest sensitivity due to outcome-based revenue models.
Supply Chain Analysis
Export controls on dual-use photonics technologies limit cross-border flows of precision dermal depth calibration equipment between German and South Korean manufacturers. Geographic supply concentration centers on South Korea, Germany, and China for ytterbium-doped fiber production, nanometer-precision optical components, and rare-earth processing respectively. Raw material dependencies include erbium and ytterbium rare-earth elements, high-purity fused silica substrates, and specialized semiconductor lasers for control systems. Single-source vulnerability in Chinese rare-earth processing creates structural exposure for device manufacturers. Distribution runs through authorized medical equipment distributors with clinical training obligations in major metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of photonics engineers capable of fractional laser calibration is concentrating value capture among South Korean and German device manufacturers while constraining expansion timelines for competitors. This capability gap defines competitive durability across the analysis window.
For Market Incumbents: Pre-empt emerging AI-driven diagnostic platforms by acquiring software specialists with real-time skin analysis capabilities before regulatory pathways consolidate. Backward integration into rare-earth fiber production in the Busan-Ulsan corridor mitigates input cost volatility from Chinese processing concentration. FDA 510(k) portfolio breadth remains the critical defensive moat against emerging entrants with novel wavelength systems. For New Entrants and Emerging Players: Mid-market aesthetic clinic networks in Brazil represent the most penetrable entry point given ANVISA harmonization with FDA pathways reducing approval friction. Wellness coaching subscription models in Los Angeles and Seoul offer lower capital intensity entry with recurring revenue architecture. Partnership with established photonics engineering consultancies accelerates time-to-certification without captive R&D investment. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with East Asian skin biology research archives and established MFDS approval track records. Long-term viability favors asset-light service operators with recurring revenue models over capital-intensive device manufacturers facing input cost volatility. Watch for FDA 510(k) clearance acceleration or deceleration as the primary inflection signal for competitive window expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Diagnostic Integration | Real-time skin analysis platforms from South Korean developers compress consultation-to-treatment cycles in outpatient aesthetic centers. |
| Peptide-Infused Delivery System Development | Biotechnology-driven formulation architectures replace traditional emollient bases under EU REACH persistent organic pollutant restrictions. |
| Subscription-Based Preventive Protocol Bundling | Los Angeles medical spa operators reconfigure inventory management around quarterly laser maintenance with monthly nutraceutical deliveries. |
| Rare-Earth Fiber Supply Security | Captive ytterbium-doped fiber production in the Busan-Ulsan corridor insulates margin structures from Chinese processing concentration. |
| Multi-Regional Regulatory Harmonization | ANVISA alignment with FDA 510(k) pathways reduces approval friction for professional-grade laser deployment in Brazilian outpatient settings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic operators, aesthetic center procurement managers, photonics engineering directors at device manufacturers, cosmetic formulation scientists, and regulatory affairs specialists navigating FDA and EU MDR pathways. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR Class IIa/IIb certification registries, MFDS and PMDA approval records, REACH compliance documentation for cosmetic ingredients, and customs trade data on rare-earth laser component flows. Bottom-up segment sizing triangulated against top-down market aggregation across product type, service type, application, and customer type dimensions.
Calibration approaches anchored volume and value outputs to installed base modeling for energy-based devices, patient throughput assumptions for clinic-based services, and retail channel velocity for topical and ingestible categories. Segmentation dimensions modeled include product format, delivery setting, functional outcome target, and procurement sophistication tier. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory pathway timelines and technology substitution patterns. Industry-specific inputs incorporated laser device replacement cycles, peptide formulation patent expiration schedules, and wellness coaching subscription retention benchmarks.
Practitioners should monitor FDA 510(k) review timeline shifts, EU MDR Class IIa/IIb certification backlogs, and rare-earth export control adjustments for early signals of competitive window compression or expansion. Forecasts reflect assumptions regarding continued outpatient migration of professional-grade treatments, sustained consumer willingness to pay premium prices for preventive protocols in Seoul's Gangnam district, and stable regulatory divergence between aesthetic device classification systems. Material shifts in photonics engineering talent mobility, REACH restriction scope expansion, or AI diagnostic platform regulatory classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
CBD Skincare Products Market
Skincare
Facial Mask Market
Skincare
Cystic Acne Market
Skincare
Global Skin Tears Treatment Market
Skincare
Ampoule Cream Market
Skincare
Pseudo Collagen Market
Skincare
Skin Barrier Market
Skincare
Skin Care Body Products Market
Skincare
Sensitive Skin Care Products Market
Skincare
Africa Cosmeceutical Market
Skincare
Skincare Cdmo and Cmo Market
Skincare
Hand Care Market
Skincare
Organic Skincare Products Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
Medicine Skin Care Market
Skincare
Global Scar Removal Treatment Market