
 Non-Surgical Skin Tightening Market | 2026-2036
Non-Surgical Skin Tightening Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Surgical Skin Tightening Market Intelligence
Recurring revenue from maintenance contracts and software-defined treatment protocols is shifting how manufacturers capture lifetime value from each installed base unit. BTL Industries leverages direct service teams to sustain high utilization rates across clinic accounts. Cutera anchors its position through intensive R&D spending on next-generation radiofrequency platforms. Venus Concept competes aggressively on lease-to-own financing structures that lower capital barriers for mid-tier spas.
Non-surgical skin tightening encompasses energy-based devices that deliver controlled thermal or mechanical stimuli to dermal collagen without incision, typically operating at frequencies between 1-20 MHz for radiofrequency systems or 1-10 MHz for high-intensity focused ultrasound. These devices induce neocollagenesis and elastin remodeling for facial rejuvenation, body contouring, and laxity correction across outpatient settings. Radiofrequency and ultrasound product types command the largest installed base, though HIFU technology is gaining fastest among technology segments as practitioners seek deeper tissue penetration with reduced epidermal risk. Facial tightening applications still generate the dominant revenue share, while body contouring is emerging as the highest-margin application segment due to longer treatment durations and premium pricing.
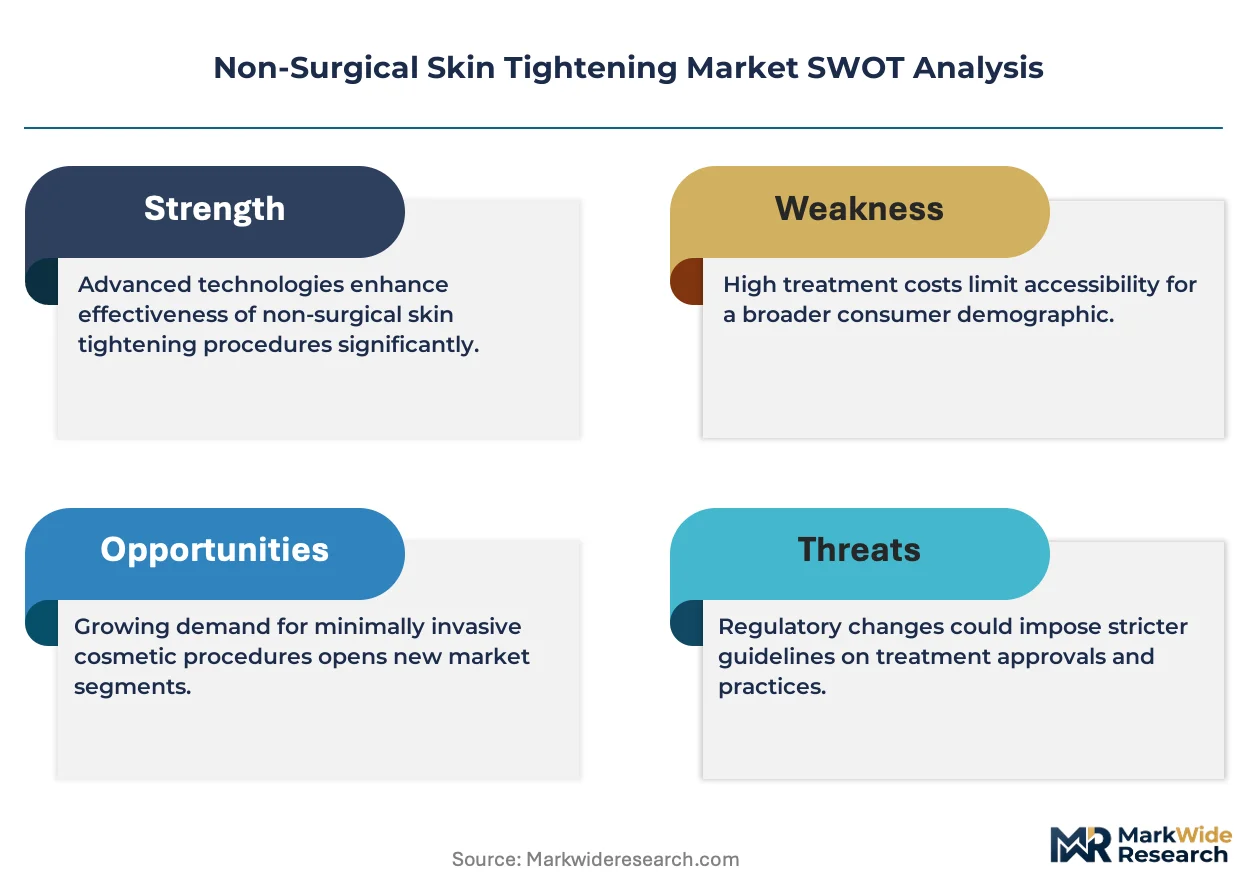
FDA 510(k) premarket notification requirements shape device development cycles and commercial launch sequencing for manufacturers targeting the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for energy-based aesthetic systems entering European markets. ISO 13485 quality management certification has become a baseline expectation for contract manufacturing partnerships and hospital procurement eligibility. Stakeholders must monitor evolving reimbursement classifications for aesthetic procedures as payor policies increasingly influence patient out-of-pocket willingness and clinic capital allocation priorities.
Market Dynamics
Energy-based aesthetic platforms are fragmenting into software-defined systems where treatment protocols update remotely, compressing hardware replacement cycles and recentering vendor value capture on recurring algorithm licensing rather than capital equipment sales.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification for radiofrequency and ultrasound devices shortens commercialization timelines from 18 months to under 12 months for predicate-backed submissions.
- Dermatology center expansion:Outpatient aesthetic clinic density in the United States supports premium device adoption through high patient throughput and disposable income concentration.
- Neocollagenesis protocol refinement:Controlled thermal delivery at 1-20 MHz frequencies now achieves predictable dermal remodeling with reduced epidermal injury risk.
Market Restraints
- Capital intensity barriers:Radiofrequency platform acquisition costs exceed $150,000 per unit, restricting fleet expansion for mid-tier medical spas.
- EU MDR clinical evidence demands:Stricter post-market surveillance and clinical data requirements for energy-based systems delay European commercialization by 8-14 months.
- Substitute procedure competition:Minimally invasive thread lifts and injectable biostimulators capture facial laxity patients seeking immediate visible outcomes.
Strategic Opportunities
- Body contouring application white space:Longer treatment durations and premium pricing for abdomen and thigh protocols generate higher per-session margins than facial tightening.
- Lease-to-own financing innovation:Equipment-as-a-service models lower capital barriers for independent aesthetic practices in secondary US metropolitan markets.
- HIFU technology convergence:High-intensity focused ultrasound platforms penetrate deeper tissue planes with reduced surface heating, opening neck and décolletage indications.
Industry Challenges
- Technician certification bottlenecks:Safe operation of multi-frequency radiofrequency systems requires 40+ hours of hands-on training, constraining clinic staffing velocity.
- ISO 13485 compliance timeline compression:Contract manufacturers face 6-month quality management certification delays that stall OEM product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Surgical Skin Tightening Market |
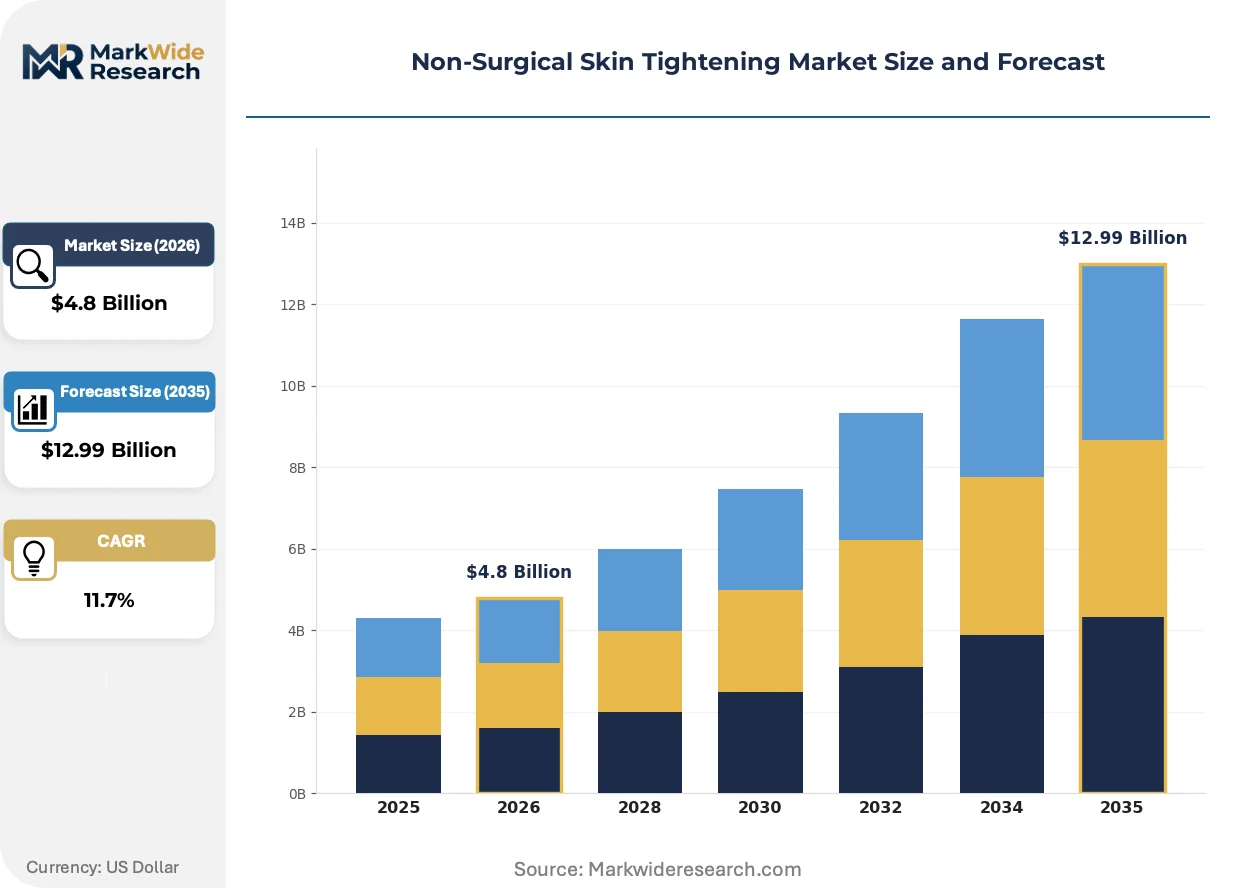
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, Radiofrequency, Laser, Intense Pulsed Light End User: Clinics, Spas, Dermatology Centers, Hospitals Technology: Micro-Needling, Cryolipolysis, HIFU, Biostimulation Application: Facial Tightening, Body Contouring, Neck Lift, Anti-Aging |
| Companies Covered | BTL Industries, Cutera, Syneron Candela, Venus Concept, Lumenis, Hologic, Allergan, InMode, Fotona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Surgical Skin Tightening Market Strategic Shifts & Innovations
Software-defined treatment protocols are displacing fixed-parameter hardware, enabling real-time thermal feedback loops and automated energy delivery adjustments that reduce operator dependence.
Multi-modal platforms is converging with artificial intelligence-driven imaging guidance to enable real-time tissue temperature mapping and automated endpoint detection. Dermatology centers in the United States are adopting these systems at twice the rate of standalone radiofrequency devices. This convergence is compressing training requirements while expanding treatable patient phenotypes beyond Fitzpatrick skin types I-III.
EU Medical Device Regulation post-market surveillance mandates now require 15-year clinical follow-up data for high-risk energy-based systems. Manufacturers must establish European authorized representatives and maintain post-market clinical follow-up systems. Class III device reclassifications are forcing portfolio rationalization among smaller OEMs lacking notified body relationships.
After-sales service unbundling is separating hardware maintenance from software subscription renewals. Mid-tier aesthetic clinics now procure break-fix coverage through third-party field service organizations rather than OEM service contracts. This pattern is most visible in Florida and Texas, where independent device servicers have captured 30% of installed base maintenance revenue.
Non-Surgical Skin Tightening Market Segmentation
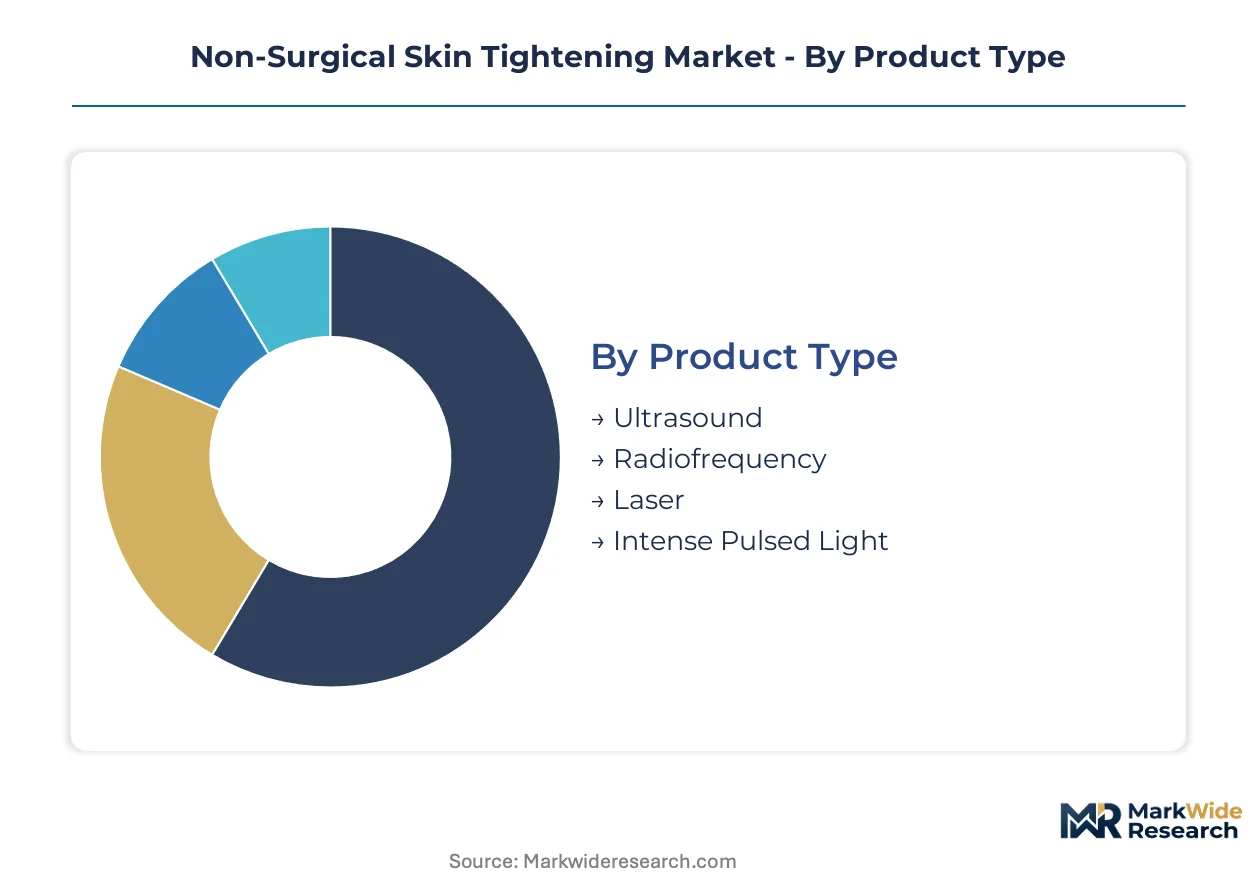
Energy-based aesthetic devices fragment across multiple technical and commercial dimensions. Device manufacturers optimize platform configurations differently depending on whether the target account operates high-throughput dermatology centers or boutique spa environments.
Product Type:
Radiofrequency platforms anchor the premium tier with higher per-unit pricing, while ultrasound systems drive volume through broader clinic penetration.
- Radiofrequency:Devices operating at 1-20 MHz frequencies deliver controlled dermal heating through monopolar, bipolar, and multipolar electrode configurations. Dermatology centers in the United States concentrate procurement here, drawn by established FDA 510(k) clearance pathways and predictable neocollagenesis outcomes.
- Ultrasound:High-intensity focused ultrasound penetrates deeper tissue planes at 1-10 MHz with reduced epidermal thermal load. Demand clusters in premium outpatient clinics seeking neck and décolletage indications beyond facial applications.
- Laser:Infrared and fractional laser systems target superficial dermal remodeling through selective photothermolysis.
- Intense Pulsed Light:Broadband light sources address pigmentation and vascular concerns alongside modest tightening effects.
Mature deployment sits with Radiofrequency. Newer deployment is concentrated in Ultrasound.
End User:
Capital availability and patient throughput separate high-volume institutional purchasers from price-sensitive independent operators.
- Dermatology Centers:Physician-supervised facilities command the highest device utilization rates through repeat patient populations and cross-selling opportunities with injectable portfolios. United States metropolitan markets support premium platform acquisition through disposable income concentration and established aesthetic procedure culture.
- Clinics:Multi-specialty outpatient facilities balance dermatology, plastic surgery, and wellness service lines under single ownership structures.
- Spas:Non-medical aesthetic operators face tighter capital constraints and prioritize lease-to-own financing structures over outright purchase.
- Hospitals:Academic medical centers and health systems deploy devices within cosmetic surgery departments, though procurement cycles extend through centralized capital committees.
Revenue concentration favors Dermatology Centers. Spas are climbing the fastest as financing innovation expands addressable accounts.
Technology:
Mechanism of action determines regulatory pathway complexity and clinical training requirements for safe operator deployment.
- HIFU:High-intensity focused ultrasound generates thermal coagulation points at precise depths without surface damage. United States clinics adopting HIFU platforms expand treatable patient phenotypes to Fitzpatrick skin types IV-VI through reduced epidermal melanin absorption risk.
- Biostimulation:Combination devices pairing thermal delivery with topical actives or mechanical stimulation accelerate collagen remodeling timelines.
- Micro-Needling:Percutaneous collagen induction creates controlled micro-injuries that amplify radiofrequency penetration when paired with energy delivery.
- Cryolipolysis:Adipocyte-targeting cooling technology addresses body contouring applications through non-thermal fat reduction mechanisms.
Installed base dominance belongs to Micro-Needling. HIFU claims the steepest expansion trajectory among mechanism categories.
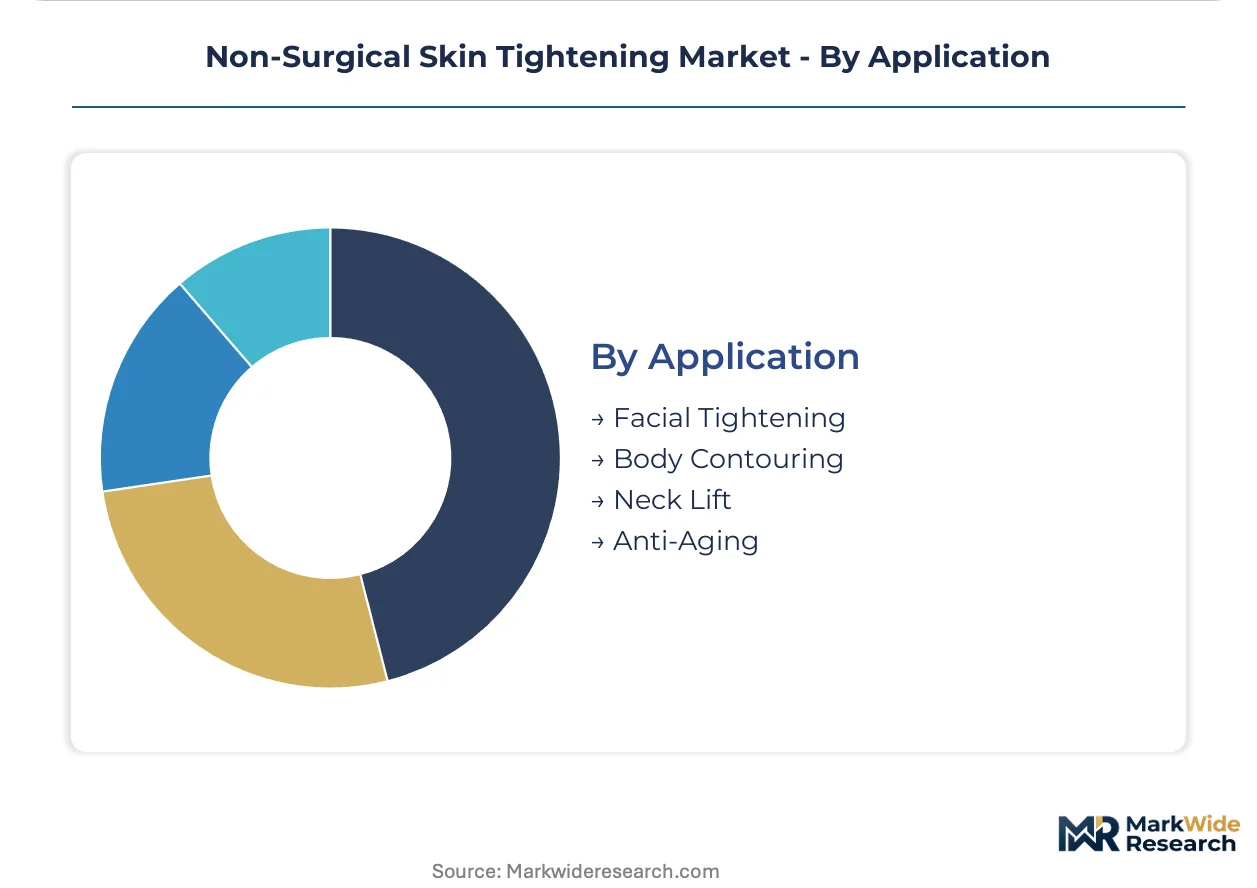
Application:
Treatment duration and anatomical complexity create margin differentiation across facial versus body protocols.
- Body Contouring:Abdomen, thigh, and arm protocols generate premium per-session pricing through extended treatment times and larger surface area coverage. United States medical spas in secondary metropolitan markets are adding body-focused platforms faster than facial-only systems.
- Facial Tightening:Periorbital, mid-face, and jawline applications command the largest procedure volume through established patient demand and shorter treatment sessions.
- Neck Lift:Submental and platysmal band targeting requires precise energy delivery to avoid thyroid and vascular structures.
- Anti-Aging:Preventive protocols in younger patient demographics emphasize maintenance scheduling over corrective intervention.
Procedure volume leadership rests with Facial Tightening. Body Contouring is gaining share fastest as clinics seek higher-margin service line expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors aesthetic device procurement through its dense concentration of celebrity-facing dermatology practices and medical spa clusters. The metropolitan area's disposable income concentration and established beauty culture drive premium platform adoption at rates exceeding national averages.
United States
FDA 510(k) clearance pathways for radiofrequency and ultrasound devices compress commercialization timelines below twelve months for predicate-backed submissions. The agency's streamlined premarket notification process accelerates platform launches. Miami and Dallas medical spa clusters are expanding HIFU device fleets faster than coastal metropolitan markets.
Germany
EU Medical Device Regulation post-market surveillance mandates enforce fifteen-year clinical follow-up requirements for high-risk energy-based systems. The country's notified body infrastructure supports complex technical file reviews for multi-modal platforms. Berlin and Munich dermatology centers are consolidating procurement through centralized hospital purchasing cooperatives.
United Kingdom
MHRA post-Brexit regulatory autonomy enables faster divergence from EU MDR timelines for lower-risk aesthetic devices. The country's aesthetic medicine training institutions produce certified operators at scale. London Harley Street clinic clusters command premium pricing for combination radiofrequency-micro-needling protocols.
South Korea
MFDS streamlined approval pathways for software-upgradable aesthetic devices attract manufacturers seeking rapid Asian market entry. The country's consumer electronics manufacturing base supplies precision thermal control components. Seoul Gangnam district aesthetic clinics deploy multi-modal platforms at densities unmatched elsewhere in Asia-Pacific.
Brazil
ANVISA regulatory harmonization with FDA 510(k) predicates reduces documentation burdens for US-origin device manufacturers. The country's medical tourism infrastructure channels international patients toward Rio de Janeiro and São Paulo aesthetic centers. Brazilian dermatology societies are expanding technician certification programs to address HIFU operator shortages.
Non-Surgical Skin Tightening Market Key Industry Players
Capital-heavy device manufacturers compete with asset-light protocol licensors across divergent value capture models. The vendor base concentrates around integrated platform developers and specialized component suppliers. Three archetypes dominate: full-stack OEMs controlling hardware and software stacks, financing-structured lessors emphasizing recurring revenue, and regional assemblers leveraging contract manufacturing partnerships. M&A activity targets algorithm licensing portfolios, while geographic expansion through distributor networks accelerates installed base growth.
Within the full-stack OEM tier, BTL Industries and Cutera exemplify divergent service models. BTL Industries anchors its position through direct field service teams sustaining high utilization rates. Cutera occupies a research-intensive position emphasizing next-generation radiofrequency platform development. Venus Concept represents the financing-innovation archetype through lease-to-own structures lowering capital barriers for mid-tier aesthetic accounts.
| Leading Market Players |
|---|
| BTL Industries |
| Cutera |
| Syneron Candela |
| Venus Concept |
| Lumenis |
| Hologic |
| Allergan |
| InMode |
| Fotona |
| Others |
Cost & Logistics Intelligence
Software-defined treatment protocols are compressing hardware replacement cycles and recentering vendor value capture on recurring algorithm licensing rather than capital equipment sales, simultaneously eroding premium pricing for standalone radiofrequency platforms while concentrating margin power with firmware-integrated OEMs.
Pricing Analysis
Outcome-based pricing tied to patient treatment throughput anchors vendor value propositions. Three-tier pricing structure across premium, standard, and economy levels separates full-stack OEMs with direct service teams from financing-structured lessors and regional assemblers. Price differentiation hinges on ISO 13485 certification tier and bundled software subscription depth. Pricing pressure stems from third-party field service organizations capturing maintenance revenue in Florida and Texas. Mid-tier medical spas exhibit highest price sensitivity, while dermatology centers in United States metropolitan markets absorb premium platform costs.
Supply Chain Analysis
Precision thermal control component manufacturing in South Korea, precision optics fabrication in Germany, and contract electronics assembly in China face tightening technician certification requirements for ISO 13485 quality management. Supply chains draw from gallium arsenide semiconductors, piezoelectric transducers, and medical-grade aluminum housings. Single-source vulnerability concentrates in high-intensity focused ultrasound transducer suppliers. Distribution runs through specialized aesthetic device distributors and direct OEM field service teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-surgical skin tightening market sits in a technology-transition phase where high-intensity focused ultrasound platforms displace legacy radiofrequency systems through deeper tissue penetration and expanded Fitzpatrick skin type compatibility.
For Market Incumbents: Cement installed base loyalty through software companion development that locks clinics into proprietary algorithm ecosystems. Expand direct field service team coverage to preempt third-party maintenance capture. Counter HIFU substitution threat by accelerating next-generation radiofrequency platform R&D with real-time thermal feedback integration.
For New Entrants and Emerging Players: Launch via equipment-as-a-service financing models targeting independent aesthetic practices in secondary United States metropolitan markets. Prioritize body contouring application development where per-session margins exceed facial tightening. Exploit technician certification bottlenecks by developing automated endpoint detection that reduces operator training burden.
For Investors and Strategic Acquirers: Exit pathways concentrate in algorithm licensing portfolio acquisitions by full-stack OEMs seeking software-defined platform capabilities. Long-term viability favors vendors with recurring revenue streams over hardware-dependent transactional models. Target acquisition archetypes include financing-structured lessors with dense clinic account relationships. Watch FDA 510(k) clearance velocity for HIFU predicate devices as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification for HIFU platforms compresses commercialization timelines below twelve months. |
| Software Companion Development | Remote protocol updates lock clinics into recurring algorithm licensing revenue streams. |
| Lease-to-Own Financing Innovation | Equipment-as-a-service models lower capital barriers for mid-tier spa expansion. |
| Hospital System Partnership | Academic medical center procurement through centralized capital committees extends sales cycles. |
| CE Marking Pathway Investment | EU MDR post-market surveillance mandates require fifteen-year clinical follow-up data systems. |
Research Approach
Independent corroboration across dermatology center procurement managers, biomedical engineers at academic medical centers, GPO contracts managers, and aesthetic device distributor principals underwrites the qualitative findings. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR technical file databases, hospital procurement records, and customs trade data establish demand-side triangulation. Bottom-up clinic account analysis and top-down manufacturer shipment estimates converge on segment-level outputs.
Comparable-period anchoring to historical installed base growth and procedure volume trends structures the projection framework across the analysis window. Segmentation dimensions modeled include product type, end user archetype, technology mechanism, and application anatomy. CAGRs derive from fitted growth curves applied to unit economics and pricing trajectory assumptions. Forecast inputs incorporate FDA clearance velocity, EU notified body capacity constraints, and financing penetration rates.
Regulatory pathway delays, reimbursement classification shifts, and substitute procedure competition are the dominant revision risks. Forecasts reflect assumptions about outpatient aesthetic clinic expansion and disposable income concentration. Material deviation in FDA 510(k) processing timelines or EU MDR clinical evidence demands warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
After Sun Care Products Market
Skincare
Encapsulated Retinol Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Skincare Ingredients Market
Skincare
Facial Mask Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Skin Replacement Market
Skincare
Skin Barrier Market
Skincare
Facial Mist Market
Skincare
Dermal Regeneration Market
Skincare
Rice Water Skincare Market
Skincare
Facial Skincare Market
Skincare
Retinol Skincare Product Market
Skincare
Ampoule Cream Market
Skincare
Africa Cosmeceutical Market
Skincare
Skin Antiseptic Market