
 Anti-Aging Services Market | 2026-2036
Anti-Aging Services Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Aging Services Market Analysis
Subscription-based financing and equipment leasing programs are reshaping competitive entry in aesthetic services, allowing independent clinics to deploy capital-intensive laser and radiofrequency platforms without full ownership burdens. L'Oréal Paris leverages its dermatology research partnerships to sustain brand credibility across professional and retail channels. Allergan anchors the injectables segment through its established neurotoxin and hyaluronic acid portfolios. Cynosure competes on technology leadership in picosecond and fractional laser modalities.
Anti-aging services encompass minimally invasive and non-invasive clinical procedures designed to reduce visible signs of skin aging through collagen stimulation, neuro-muscular modulation, or epidermal resurfacing, typically delivered via FDA-cleared or CE-marked devices and pharmaceutical formulations requiring trained operator certification. Botox and dermal fillers dominate revenue contribution due to repeat purchase behavior and low procedural downtime, while laser treatments capture premium positioning through capital intensity and outcome durability. The in-clinic delivery mode retains the largest margin pool given supervision requirements and upselling capacity, though telehealth consultations for treatment planning are gaining traction among younger adult segments.
FDA clearance pathways for aesthetic energy devices and EMA MDR compliance for injectable biologics shape product launch timelines and clinical evidence investment across the United States and European markets. The EU AI Act and emerging algorithmic oversight frameworks will extend to AI-powered skin analysis tools used in treatment recommendation engines. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate certification costs and market access sequencing.
Market Dynamics
Membership-based access models are compressing patient acquisition costs while concentrating demand among MedSpa chains capable of deploying capital-intensive laser platforms at scale. This structural shift privileges operators with balance-sheet capacity to absorb equipment depreciation and regulatory compliance investments.
Growth Catalysts
- Preventive treatment protocols:Younger adult cohorts in the United States and Brazil now initiate neurotoxin regimens before visible wrinkle formation, expanding addressable patient lifetime value.
- EMA MDR pathway harmonization:Streamlined biologics certification across EU member states accelerates hyaluronic acid filler commercialization timelines for compliant manufacturers.
- Picosecond laser diffusion:Tattoo removal indications drive device placement in dermatology networks, creating cross-sell pathways into aesthetic resurfacing applications.
Market Restraints
- Injector talent scarcity:Certified operator pipelines in South Korea and Brazil cannot match clinic expansion rates, creating wage inflation and treatment bottlenecks.
- Radiofrequency device input concentration:Precision optical components for fractional systems rely on German and Japanese specialty manufacturers, exposing procurement to currency volatility.
- FDA 510(k) evidentiary tightening:Energy-based device submissions now require larger patient cohorts and longer follow-up periods, extending capital recovery timelines.
Strategic Opportunities
- Telehealth treatment planning:Pre-procedure consultation digitization opens access to patients in secondary Brazilian cities lacking specialist density.
- Combination therapy protocols:Simultaneous neurotoxin and biostimulator administration protocols command premium positioning through outcome differentiation.
- EU AI Act compliance positioning:Early algorithmic transparency documentation for skin analysis tools creates regulatory moats against non-compliant competitors.
Industry Challenges
- Multi-jurisdiction certification complexity:Parallel FDA and EMA clinical trial requirements duplicate evidence generation costs for energy device manufacturers.
- Equipment leasing covenant enforcement:Independent clinics struggle to meet utilization minimums during demand seasonality, triggering renegotiation friction with capital providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Aging Services Market |
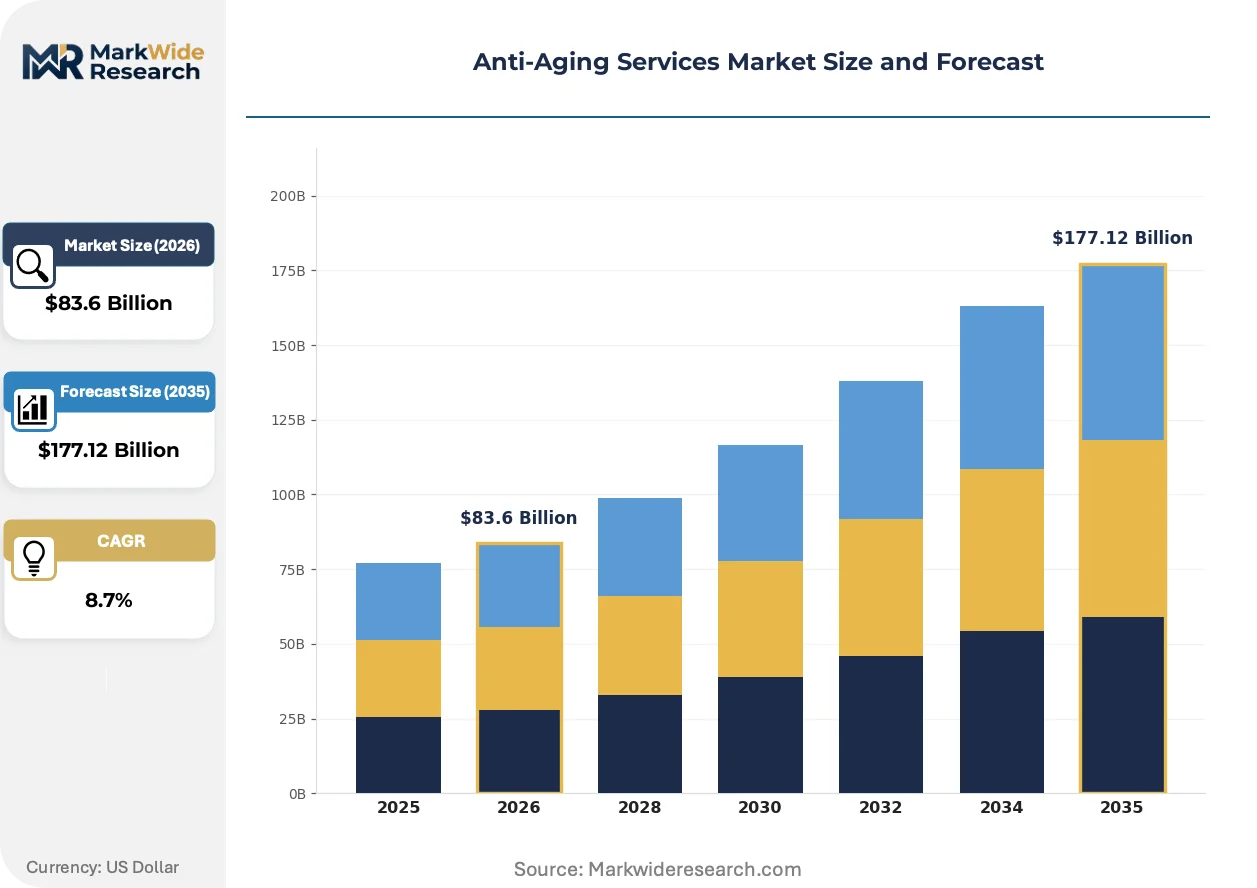
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $177.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Botox, Dermal Fillers, Laser Treatments, Chemical Peels Client Type: Men, Women, Seniors, Young Adults Delivery Mode: In-Clinic, At-Home, Mobile Services, Telehealth Market Segment: Luxury, Mid-Range, Affordable, Spa Treatments |
| Companies Covered | L'Oréal Paris, Allergan, Procter & Gamble, Unilever, Estée Lauder Inc., Beiersdorf AG, Shiseido Co., Ltd., Cynosure, Lumenis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Aging Services Market Emerging Trajectories
Clinical workflow digitization and biologic formulation advances are compressing treatment intervals while elevating outcome predictability. These developments reshape competitive differentiation from hardware specifications toward protocol standardization and patient data integration.
Picosecond laser technology delivers pigment-specific photomechanical disruption with reduced thermal diffusion, enabling darker skin type safety profiles previously excluded from laser resurfacing. Dermatology groups in the United States and South Korea are replacing nanosecond platforms within 18-month depreciation cycles. Shorter pulse durations are rendering obsolete the risk-averse treatment parameters that limited addressable patient demographics.
The EU AI Act's risk classification framework now captures algorithmic skin analysis tools used for treatment recommendation engines, mandating conformity assessment procedures for high-risk applications. Device manufacturers must document training data provenance and performance metrics across skin phototype diversity. This regulatory expansion most heavily affects multi-platform aesthetic systems sold into EU markets, forcing architectural redesign of embedded diagnostic modules.
Subscription financing for injectable biologics is displacing per-procedure purchasing among high-frequency patients in Brazilian and South Korean urban centers. Clinics bundle neurotoxin and filler access into annual memberships with priority scheduling guarantees. This model concentrates patient loyalty while compressing price transparency, with the strongest uptake among professionals aged 28-38 seeking predictable aesthetic maintenance budgets.
Anti-Aging Services Market Segmentation
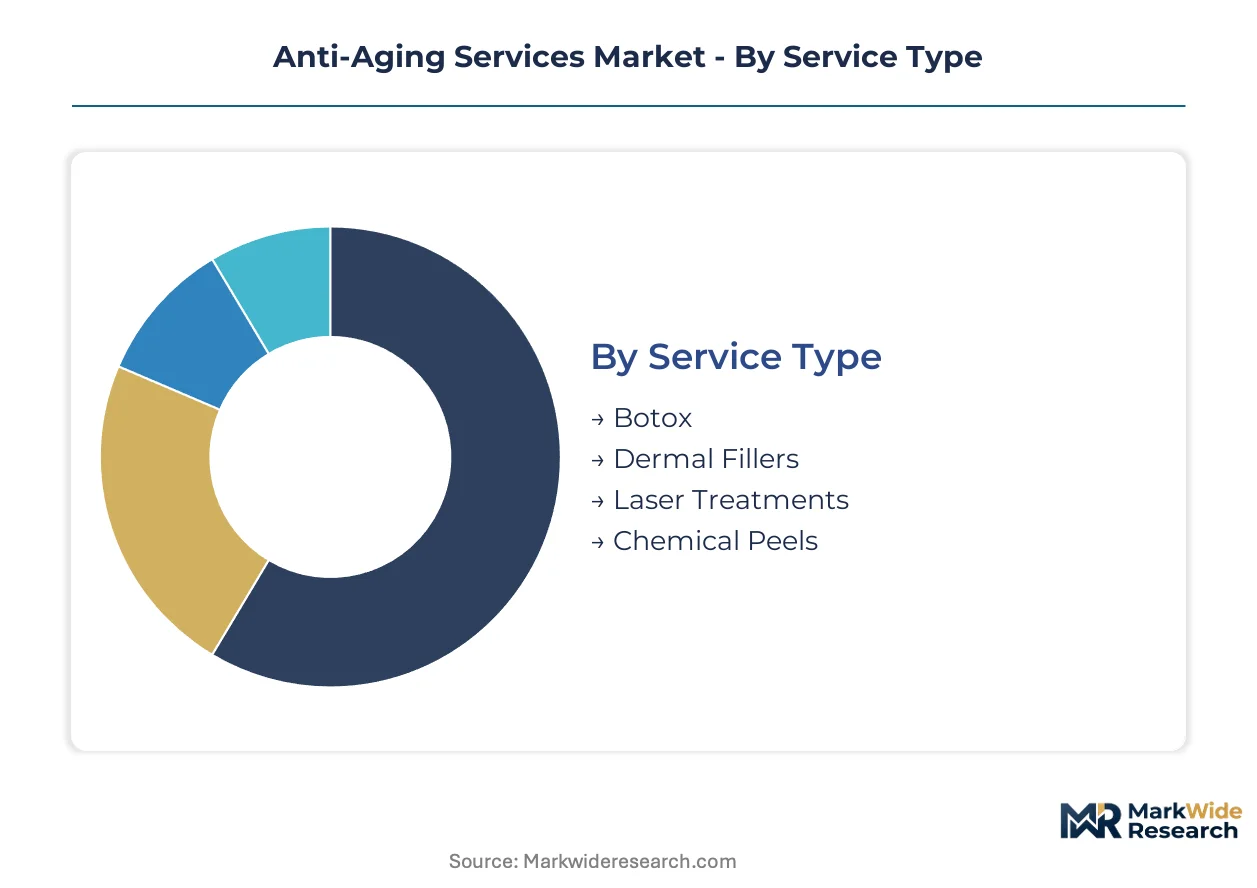
Segmentation in anti-aging services reveals divergent margin structures and operational intensity across service modalities. Each category carries distinct equipment depreciation profiles, certification requirements, and patient lifetime value curves that shape competitive positioning.
Service Type:
After-sales service intensity varies dramatically across modalities, with energy-based systems demanding scheduled maintenance contracts and injector-administered biologics requiring adverse event monitoring protocols.
- Botox:Neurotoxin formulations require cold chain integrity and precise reconstitution protocols. Demand concentrates among United States urban professionals seeking predictable maintenance schedules with minimal downtime intervals.
- Dermal Fillers:Cross-linked hyaluronic acid and biostimulator compounds enable volumetric facial contouring through varied rheological properties. Brazilian clinics report highest per-patient utilization rates driven by combination therapy preferences.
- Laser Treatments:Picosecond and fractional platforms demand technical calibration cycles.
- Chemical Peels:Acid concentration gradients determine penetration depth and recovery windows.
By volume, Botox leads. By growth pace, Laser Treatments are climbing the fastest.
Client Type:
Cost tier stratification separates preventive protocols from corrective interventions, with younger cohorts commanding lower per-session spend but extended treatment horizons.
- Women:Historically dominant patient base with established clinic relationships and cross-category purchasing patterns across neurotoxin, filler, and resurfacing modalities.
- Young Adults:Preventive neurotoxin regimens initiated before visible wrinkle formation. South Korean demand concentrates among professionals aged 25-34 seeking maintenance rather than correction.
- Men:Expanding segment with distinct anatomical targeting preferences for jawline definition and brow positioning.
- Seniors:Volume restoration and skin laxity correction dominate treatment planning.
Women account for the largest absolute volume. Young Adults represent the steepest expansion trajectory.
Delivery Mode:
Application context determines regulatory oversight intensity, with supervised clinical environments retaining premium positioning despite telehealth penetration in consultation phases.
- In-Clinic:Physician-supervised settings with full device portfolios and emergency response capacity. United States dermatology groups and MedSpa chains capture highest margins through upselling and membership bundling.
- Telehealth:Pre-procedure consultation and treatment planning digitization. Brazilian secondary cities leverage remote specialist access to overcome injector density gaps.
- At-Home:Consumer-grade device and topical formulations with limited penetration due to safety liability concerns.
- Mobile Services:Concierge delivery models for high-net-worth individuals in select metropolitan clusters.
In-Clinic retains margin leadership. Telehealth is gaining share fastest among younger demographics.
Market Segment:
Customer purchasing power and price sensitivity create distinct competitive arenas with varying brand loyalty and switching costs.
- Luxury:Bespoke protocol design with exclusive product formulations and dedicated provider relationships. South Korean celebrity-associated clinics command premium positioning through outcome exclusivity.
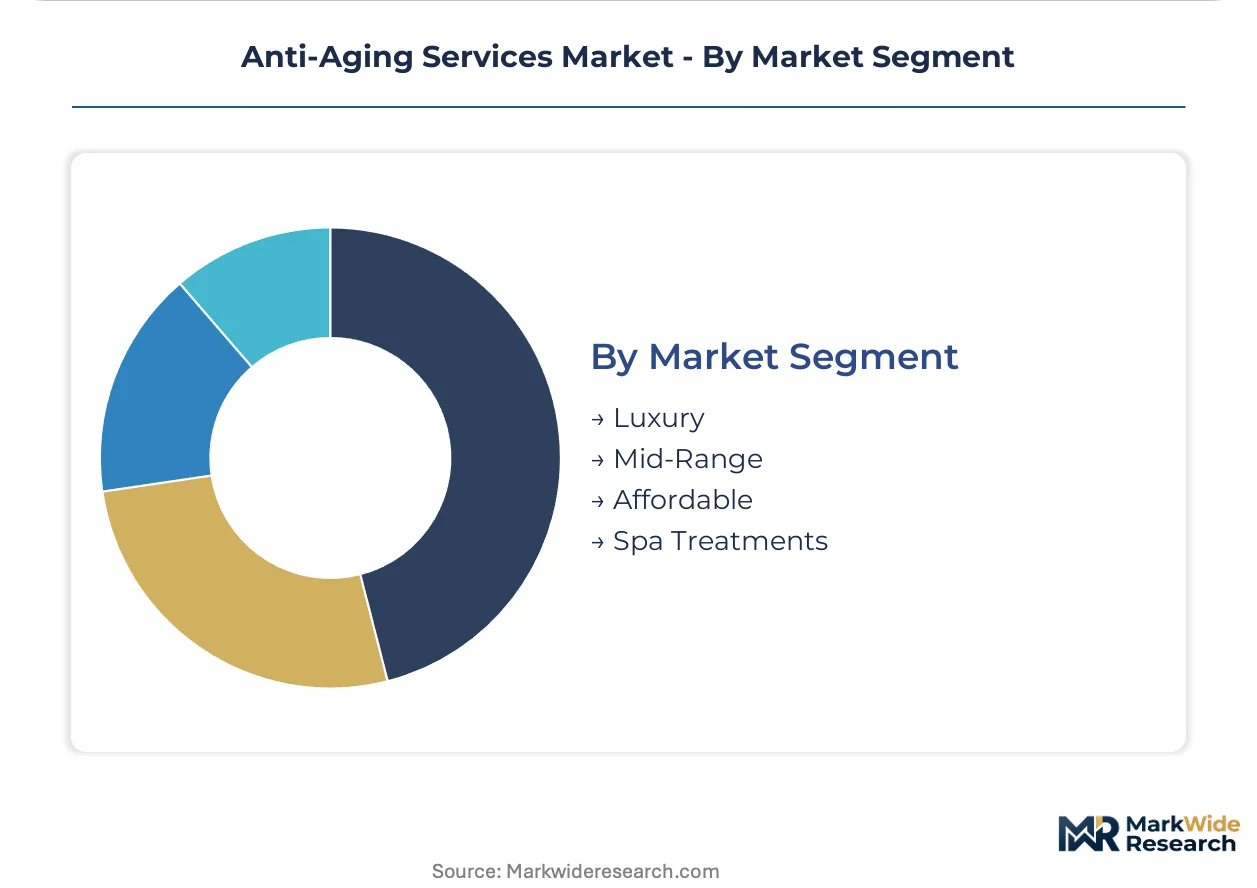
- Mid-Range:Standardized treatment packages with predictable pricing and membership incentives. United States suburban markets concentrate volume here.
- Affordable:Price-competitive access with reduced consultation depth and generic product alternatives.
- Spa Treatments:Wellness-integrated experiences emphasizing relaxation alongside aesthetic outcomes.
Mid-Range captures the highest patient volume. Luxury segments are expanding most quickly in metropolitan South Korea and Brazil.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service export capacity from South Korea and Brazil outpaces equipment import dependence in the United States, creating divergent trade balances across the aesthetic services value chain. Cross-border patient flows concentrate where regulatory recognition agreements streamline credential portability.
United States
MedSpa chains in Florida and California deploy membership models to capture younger preventive-treatment cohorts. FDA 510(k) clearance timelines for energy-based devices now demand extended clinical follow-up, delaying capital recovery for independent operators. Miami and Los Angeles anchor the highest injector density per capita, with suburban expansion accelerating into Texas and Arizona.
South Korea
Gangnam district clinics drive outbound medical tourism marketing through outcome documentation protocols. MFDS biologics registration pathways align with EMA standards, accelerating hyaluronic acid filler approvals for compliant manufacturers. Seoul Capital Area concentrates picosecond laser placement, with Busan-Ulsan emerging as secondary-hub for device servicing networks.
Brazil
ANVISA injectable registration backlogs constrain neurotoxin market entry despite surging demand from professionals aged 25-35. São Paulo and Rio de Janeiro dominate in-clinic volume, while telehealth consultations penetrate secondary cities lacking specialist density. Subscription financing models for biologics originated in Brazilian urban centers before diffusing regionally.
Germany
Precision optical component manufacturing for fractional laser systems concentrates in Baden-Württemberg and Bavaria. EMA MDR compliance investments burden smaller device assemblers, favoring consolidated manufacturers with regulatory affairs scale. Munich and Stuttgart host the primary technical service networks for aesthetic energy platforms deployed across EU markets.
Japan
PMDA marketing authorization for combination therapy protocols lags behind United States and South Korean regulatory precedent. Tokyo and Osaka dermatology groups import picosecond platforms through distributor relationships rather than direct manufacturer contracts. Domestic biostimulator development receives METI funding through medical device innovation programs.
Anti-Aging Services Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in optical and radiofrequency subsystems. The vendor base stratifies across three tiers: multinational conglomerates with dermatology research pipelines, dedicated aesthetic device manufacturers, and regional service chains with captive equipment deployment. Consolidation pressure intensifies as FDA evidentiary requirements raise capital barriers. Dominant competitive moves include vertical integration into biologics manufacturing and geographic licensing partnerships for device distribution.
Within the multinational tier, L'Oréal Paris and Allergan anchor divergent strategic positions. L'Oréal Paris leverages dermatology research partnerships to bridge professional and retail channel credibility. Allergan exemplifies the injectables-focused archetype through neurotoxin and hyaluronic acid portfolio concentration. Cynosure occupies a position within the technology-driven device segment, competing on picosecond and fractional laser modality leadership.
| Leading Market Players |
|---|
| L'Oréal Paris |
| Allergan |
| Procter & Gamble |
| Unilever |
| Estée Lauder Inc. |
| Beiersdorf AG |
| Shiseido Co., Ltd. |
| Cynosure |
| Lumenis |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's precision optical component clusters feed fractional laser manufacturers whose pricing power hinges on germanium lens supply security. Equipment lessors in São Paulo and Seoul translate this upstream concentration into subscription financing terms that compress independent clinic margins during currency volatility episodes.
Pricing Analysis
High-frequency patients anchor subscription-based pricing structures across Brazilian and South Korean urban centers. Three-tier pricing structure across premium concierge, standard membership, and per-procedure economy levels separates patients by scheduling priority and formulation exclusivity. Price differentiation stems from injector certification tier and cold chain integrity guarantees. Cost compression in the economy tier is intensifying because ANVISA registration backlogs delay generic neurotoxin entry. Young adults aged 25-34 exhibit lowest price sensitivity due to preventive protocol lock-in effects.
Supply Chain Analysis
Contract manufacturing for radiofrequency device assemblies concentrates with German and Japanese precision optics specialists. Supply draws from Germany, Japan, and South Korea for optical subsystems; hyaluronic acid raw material sourcing centers on European and Chinese fermentation capacity. Dependencies include germanium lenses, cross-linked polymer precursors, and neurotoxin bulk drug substance. Single-source vulnerability in picosecond laser crystal supply exposes manufacturers to export control disruptions. Distribution runs through manufacturer-direct sales for capital equipment and wholesale pharmaceutical channels for injectable biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified injector pipelines constitute the binding constraint across all major demand clusters, with training program throughput lagging clinic expansion by 30-40% in Brazil and South Korea. This scarcity dynamic privileges operators who control talent development pathways.
For Market Incumbents: Pre-empt emerging telehealth-native competitors by capturing exclusive injector training partnerships with Seoul and São Paulo dermatology residency programs. Consolidate position through backward integration into biostimulator manufacturing to offset hyaluronic acid margin compression. Lock in multi-year equipment leasing covenants before FDA 510(k) evidentiary tightening extends capital recovery timelines for independent rivals.
For New Entrants and Emerging Players: Secondary Brazilian cities lacking specialist density present the most penetrable white-space for telehealth-anchored treatment planning services. Target preventive neurotoxin regimens among professionals aged 28-38 through subscription financing originated via mobile-first consultation platforms. Partner with existing MedSpa chains for device access rather than deploying owned laser capital.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because membership models convert aesthetic services into predictable consumption bundles with high switching costs. Acquisition focus should center on regional injector networks with captive training academies. Monitor quarterly FDA 510(k) submission volumes and EMA MDR conformity assessment completion rates as inflection indicators for competitive entry velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Injector Training Academy Partnership | Secures certified operator pipelines ahead of clinic expansion waves in São Paulo and Seoul. |
| Telehealth Platform Integration | Extends specialist access to ANVISA-constrained Brazilian secondary cities lacking density. |
| Biostimulator Manufacturing Scale-Up | Reduces dependence on European hyaluronic acid suppliers facing EMA MDR compliance costs. |
| EU AI Act Conformity Documentation | Creates regulatory moats for algorithmic skin analysis tools ahead of competitor submissions. |
| Membership Model Geographic Licensing | Replicates Brazilian subscription financing success in South Korean preventive treatment cohorts. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with MedSpa chain executives, dermatology group medical directors, biomedical equipment procurement managers, and certified injector network coordinators. Secondary validation drew from FDA 510(k) premarket notification databases, EMA MDR technical documentation filings, ANVISA registration backlogs, and MFDS biologics approval records. Bottom-up service volume estimates triangulated against top-down equipment shipment data from German and Japanese optical component manufacturers.
Calibration across the analysis window employed cohort-based modeling of patient lifetime value curves segmented by service type, client demographic, delivery mode, and market tier. CAGRs were derived from fitted adoption curves incorporating preventive treatment protocol diffusion rates and membership model penetration assumptions. Forecast inputs included injector training program graduation rates, picosecond laser platform replacement cycles, and telehealth consultation adoption velocity among younger adult segments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed clinic rollups or cross-border telehealth platforms would shift outcomes beyond modeled ranges. Regulatory acceleration in FDA 510(k) timelines or EMA MDR harmonization completion represents primary revision triggers. Quarterly review of injector wage inflation indices and equipment leasing covenant default rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Bangladesh Skin Care Products Market
Skincare
Dermocosmetics Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
Natural Skin Care Products Market
Skincare
Self-Tanning Care Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Hand Care Market
Skincare
Facial Massage Cream Market
Skincare
Cosmeceuticals Market
Skincare
Skincare Cdmo and Cmo Market
Skincare
Global Skin Tears Treatment Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Sun-Care Wipes Market
Skincare
After Sun Care Products Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
Algae Skincare Products Market