
 Sensitive Skin Care Products Market | 2026-2036
Sensitive Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Sensitive Skin Care Products Market Analytics
Subscription-based replenishment programs is repositioning how sensitive skin care brands build lifetime value. L'Oréal S.A. leverages its dermatological testing infrastructure across European labs to validate tolerance claims. Beiersdorf AG anchors its portfolio through pharmacy-exclusive distribution in German-speaking markets. Johnson & Johnson Services Inc. competes via pediatric dermatologist endorsements that extend brand trust into adult sensitive skin segments.
Sensitive skin care products are topical formulations engineered with pH-balanced, fragrance-minimized compositions and barrier-supporting lipids designed to reduce transepidermal water loss without provoking irritant or allergic responses. Manufacturing requires validated patch-testing protocols and sterile filling conditions to preserve microbiome compatibility claims. Moisturizers and cleansers together occupy the largest volume share, though serums with hyaluronic acid concentrate the fastest margin expansion as consumers trade up from basic hydration to targeted barrier repair. Sunscreens remain underpenetrated relative to daily care applications, creating a structural gap that brands with photodermatology expertise can exploit.
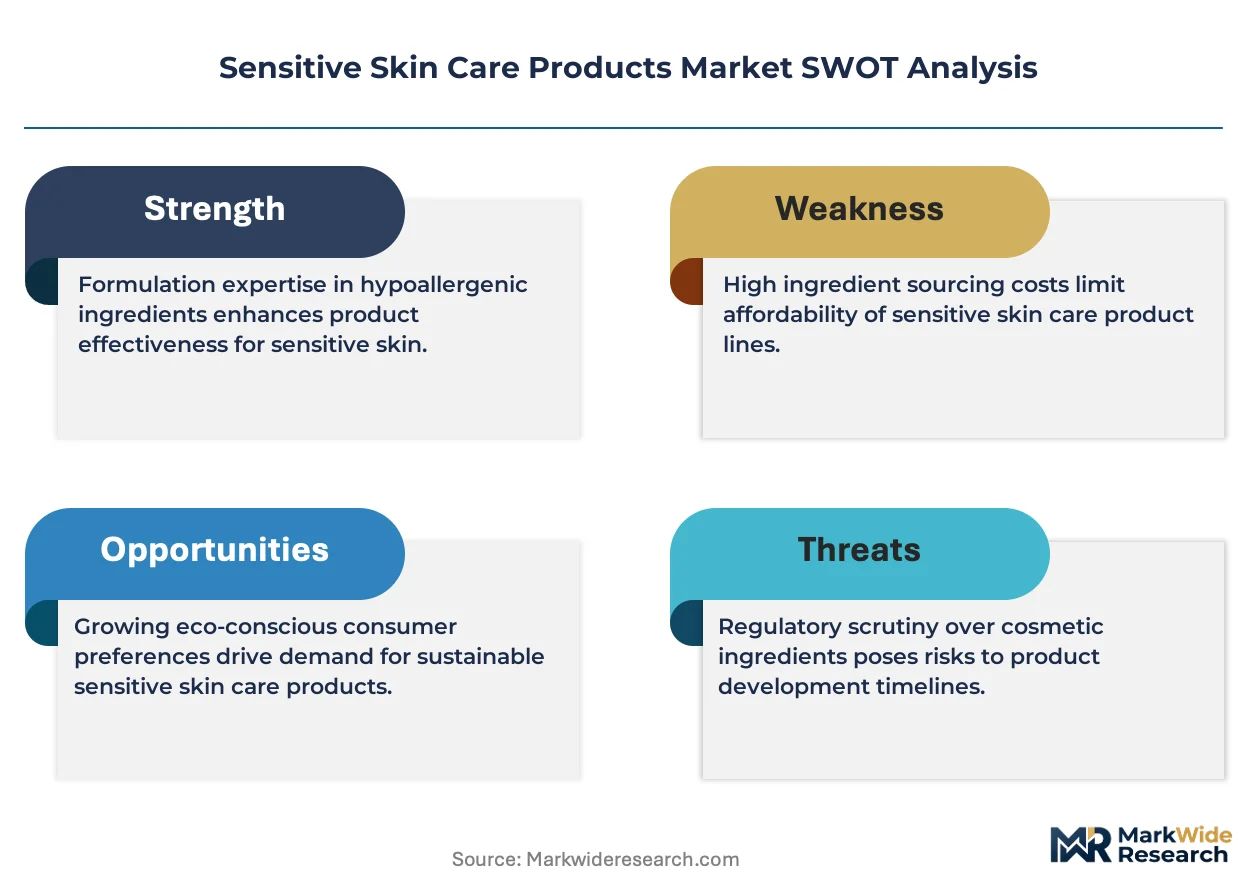
FDA oversight of cosmetic labeling and the EU REACH framework on fragrance allergens jointly determine which ingredient portfolios gain market access in North America and Europe. BIS certification requirements in India and China's NMPA cosmetic registration rules add further compliance layers for cross-border brands. Stakeholders must monitor how dermatology prescription patterns and regulator ingredient blacklists reshape formulation roadmaps ahead of consumer preference shifts.
Market Dynamics
Pharmacy-led distribution channels in Germany validate clinical efficacy claims, forcing brands to invest in dermatological testing infrastructure before market entry rather than after product development.
Growth Catalysts
- EU MDR and REACH restrictions:Regulatory pressure on fragrance allergens compels reformulation with documented hypoallergenic ingredients, creating competitive moats for compliant manufacturers.
- Dermatology prescription patterns:Clinics now prescribe barrier-repair moisturizers as first-line therapy for rosacea and eczema patients, expanding the reimbursable product universe.
- Subscription-based replenishment programs:These models capture recurring revenue streams and build lifetime value through automated reordering systems tied to skin condition monitoring.
Market Restraints
- High-purity lipid input costs:Ceramide and squalane supply concentrates among three specialized chemical suppliers, exposing margins to petrochemical feedstock volatility.
- Sterile filling capacity scarcity:Contract manufacturers with validated microbiome-compatible production lines operate at 90% utilization, extending lead times for new product launches.
- Biodegradability-performance tradeoff:Natural surfactants fail to match synthetic cleansing efficacy at equivalent concentrations, limiting claims in acne-prone sensitive skin segments.
Strategic Opportunities
- Photodermatology expertise gap:Daily sunscreen penetration lags moisturizers by 40 percentage points among diagnosed sensitive skin consumers, creating white space for mineral-filter innovations.
- Pediatric-to-adult brand extension:Trust capital built through pediatric dermatologist endorsements transfers into adult sensitive skin segments with minimal marketing reinvestment.
- Hyaluronic acid serum trading-up:Consumers migrate from basic hydration to targeted barrier repair, compressing moisturizer margins while expanding serum category value per unit.
Industry Challenges
- Patch-testing protocol standardization:Variability between European labs and FDA-recognized testing facilities creates conflicting tolerance claims that confuse pharmacy buyers.
- Microbiome claim substantiation:Lack of ISO standards for skin microbiome compatibility forces brands to fund proprietary clinical studies, extending time-to-market by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensitive Skin Care Products Market |
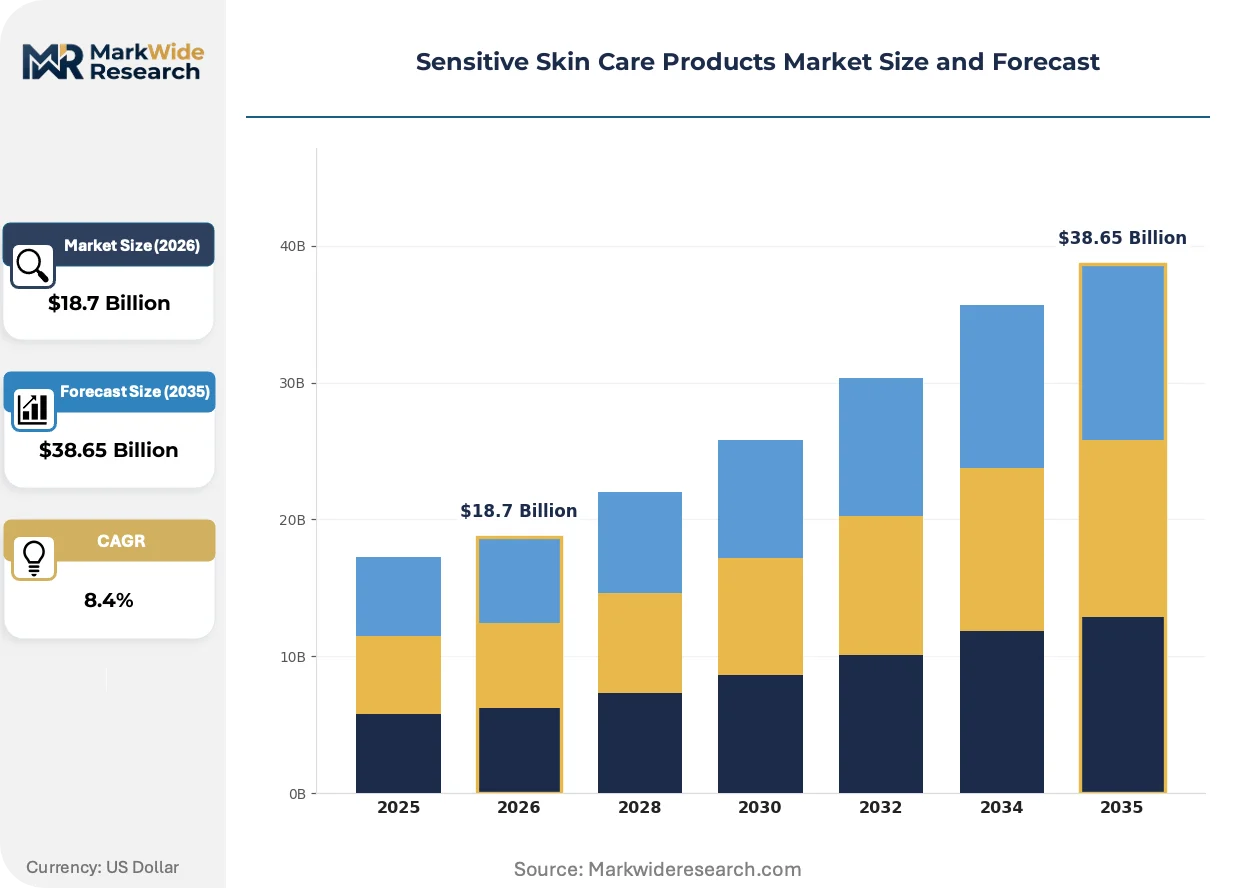
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Serums, Sunscreens Ingredient: Aloe Vera, Chamomile, Oat Extract, Hyaluronic Acid Application: Daily Care, After Sun Treatment, Anti-Aging, Hydration Packaging Type: Tubes, Jars, Pumps, Sachets |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies Inc., Johnson & Johnson Services Inc., Shiseido Co. Ltd., Beiersdorf AG, Procter & Gamble Company, Colgate-Palmolive Company, Kao Corporation, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensitive Skin Care Products Market Evolving Landscape
Formulation science is converging with digital skin diagnostics, creating feedback loops between biometric monitoring and personalized product adjustment that reshape how efficacy gets demonstrated and priced.
Biomimetic lipid matrices that replicate stratum corneum architecture are rewriting how barrier repair gets formulated and validated. Dermatology clinics in Germany and Switzerland adopt these compositions at twice the rate of general retail channels. The technology compresses the clinical trial timeline from 24 weeks to 12 weeks by demonstrating measurable transepidermal water loss reduction earlier.
REACH fragrance allergen restrictions now blacklist 26 additional compounds, forcing reformulation of legacy portfolios across the EU. Manufacturers face 18-month transition windows to exhaust existing inventory or absorb write-downs. Fragrance-free claims now dominate pharmacy shelf positioning in France and the Netherlands, displacing "hypoallergenic" as the primary purchase trigger.
Direct-to-consumer diagnostic tools that measure skin barrier function via capacitance sensors are fragmenting traditional channel control. These devices recommend specific ingredient concentrations based on individual lipid profiles, bypassing pharmacist consultation. Adoption concentrates among urban consumers in Germany and the UK, where digital health literacy intersects with willingness to pay premium prices for algorithm-matched formulations.
Sensitive Skin Care Products Market Segmentation
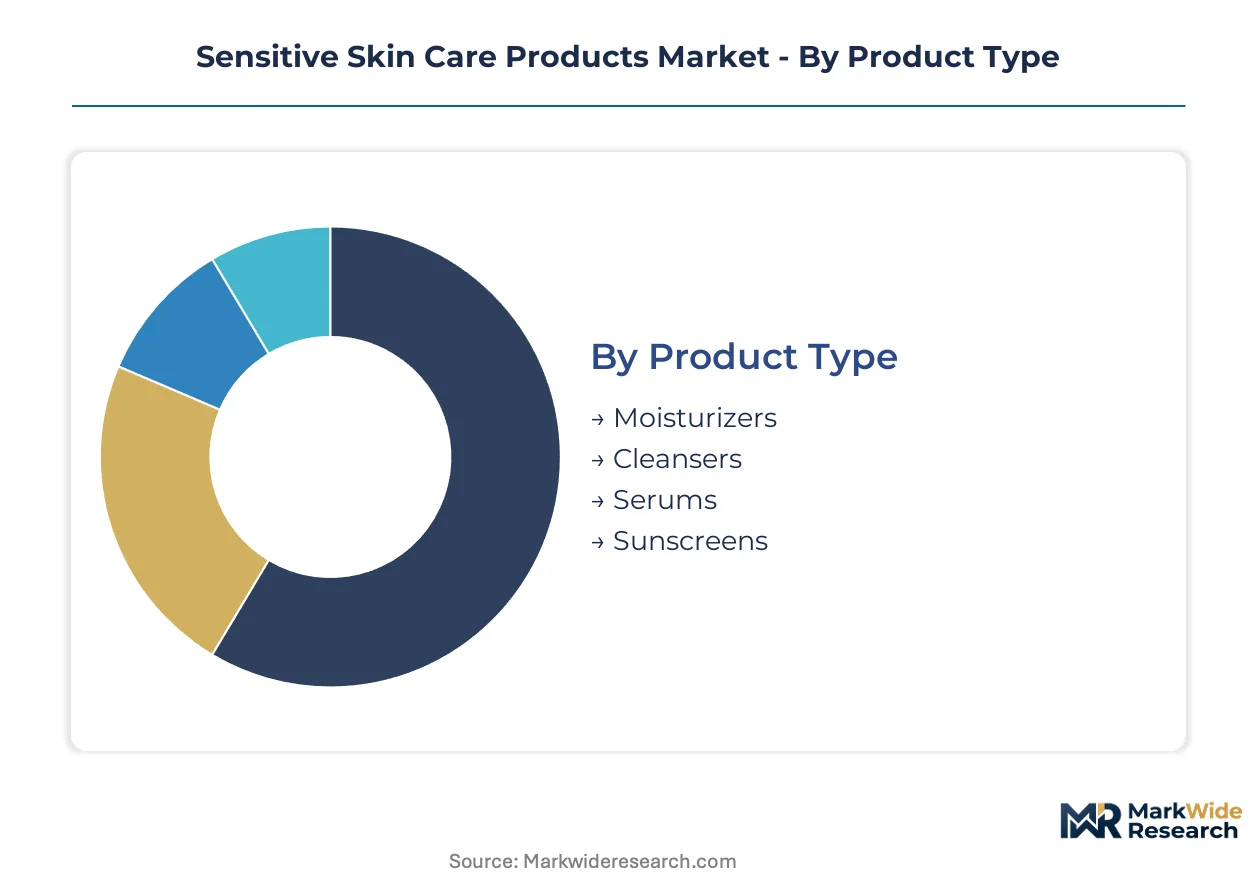
Segmentation in sensitive skin care determines formulation priorities, regulatory pathways, and channel economics. Product type and ingredient choices dictate clinical validation requirements, while packaging format influences pharmacy shelf placement and consumer compliance rates.
Product Type:
Usage frequency and clinical positioning separate buyers across this category, with daily-use staples commanding different margin structures than condition-specific treatments.
- Moisturizers:Barrier-repair formulations with ceramide and squalane concentrates dominate pharmacy prescriptions for rosacea and eczema management in Germany. Dermatology clinics in Switzerland now stock these as first-line therapy, expanding reimbursable demand beyond cosmetic retail.
- Serums:Hyaluronic acid concentrates with biomimetic lipid matrices deliver measurable transepidermal water loss reduction within 12-week clinical windows. Urban consumers in the UK trade up from basic hydration, compressing moisturizer margins while serum value per unit expands.
- Cleansers:pH-balanced, fragrance-minimized compositions reduce irritant responses without stripping stratum corneum lipids.
- Sunscreens:Mineral-filter innovations address the 40-percentage-point penetration gap versus daily moisturizers among diagnosed sensitive skin consumers.
Volume sits with moisturizers; growth tilts toward serums.
Ingredient:
Regulatory scrutiny of fragrance allergens and documented hypoallergenic claims now determines which botanical and synthetic inputs gain pharmacy access across EU markets.
- Hyaluronic Acid:Cross-linked polymer grades enable targeted barrier repair at concentrations that satisfy ECHA REACH documentation requirements. Formulators in France prioritize this ingredient for algorithm-matched personalized products recommended by direct-to-consumer diagnostic tools.
- Oat Extract:Colloidal oatmeal compositions with established pediatric dermatology endorsements transfer trust capital into adult segments with minimal marketing reinvestment. Johnson & Johnson leverages this ingredient family across European pharmacy channels.
- Aloe Vera:Standardized polysaccharide content supports microbiome compatibility claims pending ISO standard finalization.
- Chamomile:Bisabolol concentrates require batch-level allergen testing under expanded EU fragrance compound blacklists.
Formulation runs through oat extract for pediatric credibility; hyaluronic acid climbs the fastest for adult premium positioning.
Application:
Condition severity and reimbursement eligibility separate this category, with diagnosed dermatological conditions accessing pharmacy distribution while cosmetic hydration remains retail-dependent.
- Daily Care:Maintenance formulations with documented tolerance profiles sustain subscription-based replenishment program enrollment. German consumers show highest adoption of automated reordering systems tied to skin condition monitoring.
- Hydration:Basic moisture retention products face margin compression as consumers migrate toward targeted barrier repair serums with clinical validation.
- Anti-Aging:Retinoid-alternative peptides require extended patch-testing protocols that extend time-to-market.
- After Sun Treatment:Post-photodamage repair formulations concentrate in Mediterranean markets with seasonal demand spikes.
Revenue concentrates in daily care; steepest expansion trajectory belongs to anti-aging as biomimetic technologies mature.
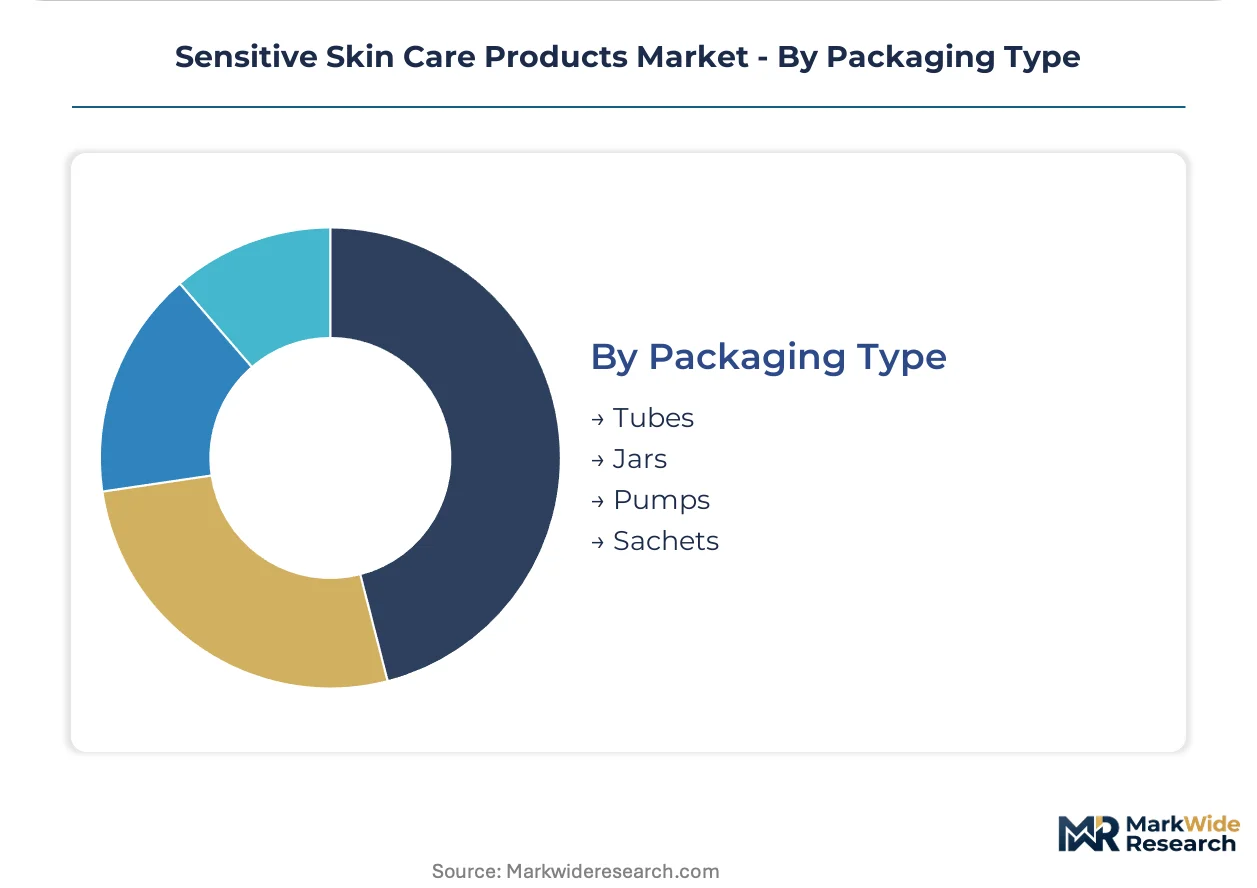
Packaging Type:
Preservation integrity and dosing precision drive pharmacy buyer preferences, with sterile filling capacity scarcity favoring formats that minimize contamination risk.
- Pumps:Airless dispensing systems preserve microbiome compatibility claims through sterile filling conditions. Contract manufacturers with validated production lines operate at 90% utilization, extending lead times for pump-format launches.
- Tubes:Aluminum-barrier laminates protect lipid stability for biomimetic formulations during shelf life. This format dominates German pharmacy shelf positioning for fragrance-free claims.
- Jars:Wide-mouth containers require enhanced preservative systems that complicate hypoallergenic certification.
- Sachets:Single-unit dosing supports trial conversion and travel-size compliance in direct-to-consumer channels.
Pharmacy procurement favors pumps; sachets gain share fastest in digital-native subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of barrier-repair lipids concentrates among German and Swiss chemical suppliers, while consumption spreads across pharmacy networks in Western Europe and direct-to-consumer channels in North America. The analysis tracks five countries where regulatory frameworks and distribution infrastructure create distinct competitive conditions.
Germany
Pharmacy-led distribution validates clinical efficacy claims for sensitive skin formulations, with dermatology clinics in Berlin and Munich prescribing barrier-repair moisturizers as first-line therapy. ECHA REACH restrictions on fragrance allergens force brands to reformulate with documented hypoallergenic ingredients before market entry. The Rhine-Ruhr industrial corridor hosts specialized sterile filling contractors operating at 90% utilization.
United States
Pediatric dermatologist endorsements transfer trust capital into adult sensitive skin segments, while subscription-based replenishment programs capture recurring revenue through automated reordering systems. FDA oversight of cosmetic labeling determines which ingredient portfolios gain market access. Greater Boston clusters digital health startups developing capacitance sensors for direct-to-consumer skin barrier diagnostics.
France
Fragrance-free claims dominate pharmacy shelf positioning in Paris and Lyon, displacing "hypoallergenic" as the primary purchase trigger among urban consumers. ANSM enforces batch-level allergen testing for bisabolol concentrates under expanded EU fragrance compound blacklists. The Île-de-France region concentrates algorithm-matched personalized product development tied to diagnostic tool recommendations.
Switzerland
Dermatology clinics in Zurich and Geneva adopt biomimetic lipid matrices at twice the rate of general retail channels, compressing clinical trial timelines through earlier transepidermal water loss demonstration. Swissmedic regulates cosmetic tolerability claims with stricter documentation requirements than neighboring jurisdictions. Basel anchors specialized chemical supply for ceramide and squalane production.
United Kingdom
Urban consumers in London and Manchester show highest adoption of direct-to-consumer diagnostic tools that bypass pharmacist consultation through algorithm-matched formulations. MHRA alignment with EU MDR frameworks maintains equivalent regulatory barriers for fragrance allergen documentation. The Southeast England corridor clusters contract manufacturers with validated microbiome-compatible production lines.
Sensitive Skin Care Products Market Competitive Landscape
Capital-heavy producers with in-house dermatological testing infrastructure compete with asset-light brands relying on contract manufacturing and licensed distribution. The market structure tilts toward consolidated multinational portfolios, though regional specialists maintain pharmacy channel access through regulatory compliance depth. Three archetypes dominate: integrated beauty conglomerates with European lab networks, pharmacy-exclusive dermatological houses, and pediatric-trust brands extending into adult segments. Competitive moves concentrate on sterile filling capacity acquisition and biomimetic formulation patent positioning.
Within the integrated conglomerate tier, L'Oréal S.A. and Beiersdorf AG exemplify divergent geographic anchoring strategies, with the former leveraging pan-European testing infrastructure and the latter concentrating pharmacy-exclusive distribution in German-speaking markets. Johnson & Johnson Services Inc. occupies a distinct position built on pediatric dermatology trust transfer, representing how endorsement capital migrates across life-stage segments without proportional marketing reinvestment. These three entities illustrate how regulatory compliance depth, channel control, and trust architecture separate sustainable positioning from commodity competition.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Johnson & Johnson Services Inc. |
| Shiseido Co. Ltd. |
| Beiersdorf AG |
| Procter & Gamble Company |
| Colgate-Palmolive Company |
| Kao Corporation |
| Unilever PLC |
| Others |
Value Network & Pricing Analysis
EU REACH fragrance allergen restrictions gate qualified supply and premium-tier pricing access, forcing manufacturers to absorb reformulation costs or forfeit pharmacy channel placement in Germany and France.
Pricing Analysis
Margin tightening in premium tiers reflects sterile filling capacity scarcity and specialized lipid input concentration. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-validated formulations from mass retail and private label alternatives. Price differentiation hinges on dermatological testing documentation and ECHA REACH compliance certification. Cost-down pressure on mid-tier products accelerates because consumers trade up to clinically validated serums, compressing basic moisturizer margins.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss chemical suppliers for ceramide and squalane concentrates. Production draws from the Rhine-Ruhr corridor, Basel chemical cluster, and limited Southeast England contract manufacturing. Raw material dependencies include petrochemical-derived lipids, cross-linked hyaluronic acid polymers, and colloidal oatmeal extracts. Tariff exposure on imported botanicals threatens margin stability. Distribution runs through pharmacy networks in German-speaking markets and direct-to-consumer channels in the UK and US.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with sterile filling capacity and biomimetic formulation patents as the decisive upstream levers.
For Market Incumbents: Lock in sterile filling capacity through long-term contracts with validated manufacturers in Germany and Switzerland before utilization rates breach capacity ceilings. Secure biomimetic lipid matrix patents to defend against peptide-alternative entrants. Deepen pharmacy channel control through exclusive distribution agreements in Berlin and Munich clinic networks. For New Entrants and Emerging Players: Launch via direct-to-consumer diagnostic tools in London and Manchester, where algorithm-matched formulations bypass established pharmacist gatekeepers. Target the sunscreen gap among diagnosed sensitive skin consumers, where mineral-filter innovation lags moisturizer penetration by substantial margins. Exploit pediatric-to-adult trust transfer with oat-extract positioning. For Investors and Strategic Acquirers: Swissmedic stricter documentation requirements than neighboring jurisdictions is the leading indicator that regulatory compliance depth will separate acquirable assets from stranded formulations. Five-to-ten-year viability favors manufacturers with captive dermatological testing infrastructure and REACH-validated ingredient portfolios. Watch for ECHA blacklist expansions as the signal for reformulation cost spikes that compress marginal competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Sterile Filling Capacity Lock-in | Long-term contracts with Rhine-Ruhr manufacturers secure microbiome-compatible production lines ahead of 90% utilization ceilings. |
| Biomimetic Patent Positioning | Stratum corneum-replicating lipid matrices compress clinical trial timelines and defend against peptide-alternative entrants. |
| Pharmacy Channel Expansion | Exclusive Berlin and Munich clinic agreements validate efficacy claims and block competitor shelf access. |
| Direct-to-Consumer Diagnostic Launch | Capacitance sensor tools in UK urban markets bypass pharmacist consultation and capture premium algorithm-matched pricing. |
| REACH Compliance Repositioning | Fragrance-free formulation portfolios displace legacy hypoallergenic claims in France and Netherlands pharmacy positioning. |
Research Methodology
Document review covered EU MDR implementation guidance, ECHA REACH substance databases, and FDA cosmetic labeling regulations, complemented by interviews with dermatology clinic procurement managers, pharmacy chain category buyers, sterile filling contract manufacturers, and biomimetic formulation R&D directors. Secondary sources included ANSM batch testing records, Swissmedic tolerability claim documentation, and customs trade data for ceramide and squalane imports. Bottom-up demand modeling triangulated against top-down regulatory impact assessments.
Cross-referencing historical prescription pattern shifts with panel input from German dermatology clinics anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, ingredient composition, application severity, and packaging format. CAGRs derived from reconciling pharmacy dispensing volume trends with consumer trade-up behavior in serum categories. Forecast inputs incorporated ECHA blacklist transition timelines and sterile filling capacity expansion announcements.
Regulatory blacklist expansions, petrochemical feedstock volatility, and microbiome claim standardization delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on REACH compliance transition costs and clinic prescription adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Germany Skincare Product Market
Skincare
Sheet Face Mask Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
DNA-Based Skin Care Products Market
Skincare
Algae Skincare Products Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Vitamin C Serum Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Sun-Care Wipes Market
Skincare
Dermal Regeneration Market
Skincare
Marine Retinol Market
Skincare
Dermocosmetics Skin Care Products Market
Skincare
Skincare Ingredients Market
Skincare
Medicine Skin Care Market
Skincare
Acne Treatment Market
Skincare
Global Physician Dispensed Cosmeceuticals Market