
 Hidradenitis Suppurativa Market | 2026-2036
Hidradenitis Suppurativa Market Size, Share, and Industry Trends Forecast 2026-2036
Hidradenitis Suppurativa Market Outlook
Biologic drug substance production is shifting from mammalian cell culture to microbial fermentation platforms for select cytokine inhibitors, reducing cost-of-goods by roughly one-third for early-phase molecules. AbbVie leverages its immunology manufacturing infrastructure to sustain Humira-derived supply chain efficiencies across its HS pipeline. Novartis AG competes through differentiated IL-17A positioning in dermatology beyond psoriatic indications. Johnson & Johnson anchors its HS franchise through deep TNF-alpha expertise carried forward from inflammatory bowel disease applications.
Hidradenitis suppurativa constitutes a chronic, recurrent inflammatory skin disorder characterized by painful nodules, abscesses, and sinus tract formation in apocrine gland-bearing regions, with Hurley staging (I-III) guiding clinical severity assessment and treatment selection. The condition demands sustained anti-inflammatory intervention to prevent irreversible tissue destruction and quality-of-life impairment. Biologics command the dominant margin pool within therapy area segmentation, while systemic therapies occupy the highest patient-volume tier due to payer step-therapy requirements. Injection delivery mode leads in revenue per patient, though oral medications sustain broader prescriber adoption in mild-to-moderate cases managed through dermatology clinics.
FDA accelerated approval designations and EMA conditional marketing authorizations are reshaping how developers construct Phase IIb pivotal trials for HS biologics, compressing evidence-generation timelines while elevating post-marketing surveillance obligations. The EU MDR framework imposes stricter clinical performance requirements on surgical device indications used in HS wound management, filtering market access for novel debridement technologies. Stakeholders must monitor how CMS national coverage determinations for biologics in dermatology evolve relative to commercial payer prior authorization stringency, as this divergence will dictate site-of-care economics and manufacturer channel investments.
Market Dynamics
The HS therapeutics landscape is restructuring around accelerated regulatory pathways that compress Phase IIb-to-approval timelines while elevating post-market surveillance obligations for biologic developers.
Growth Catalysts
- FDA Accelerated Approval:The pathway enables biologic developers to secure conditional market entry based on surrogate endpoints, reducing evidence-generation timelines for novel IL-17 and TNF-alpha inhibitors.
- Biologic Infusion Infrastructure:Dermatology clinics across the United States are expanding infusion suite capacity to capture moderate-to-severe patient volumes previously managed in hospital outpatient departments.
- Payer Coverage Expansion:Commercial insurers have broadened prior authorization criteria for dermatology biologics, reducing step-therapy burden for Hurley Stage II-III patients.
Market Restraints
- Cost-of-Goods Pressure:Mammalian cell culture platforms for biologic production impose input cost volatility that microbial fermentation alternatives only partially offset in early-phase molecules.
- Supply Concentration Risk:Contract manufacturing for sterile injectables concentrates among a limited supplier base in the United States and Switzerland, creating vulnerability for multi-product immunology portfolios.
- EU MDR Surgical Device Friction:Stricter clinical performance requirements under the Medical Device Regulation filter market access for novel debridement technologies used in HS wound management.
Strategic Opportunities
- Microbial Fermentation Transition:Platform shifts from mammalian to microbial systems for select cytokine inhibitors reduce production costs by roughly one-third, enabling margin expansion for pipeline assets.
- EMA Conditional Authorization:The framework allows European market entry with reduced initial evidence packages, creating competitive runway for developers willing to accept elevated post-marketing commitments.
- Telemedicine Triage Models:Virtual dermatology platforms are capturing mild-to-moderate HS cases for initial assessment, creating channel innovation opportunities for oral therapy distribution.
Industry Challenges
- Biostatistics Talent Scarcity:The compressed trial timelines demanded by accelerated pathways strain availability of specialists experienced in inflammatory disease endpoint design and adaptive trial structures.
- Legacy Site Integration:Electronic health record interoperability between dermatology clinics and infusion centers creates data fragmentation that complicates patient tracking across care settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hidradenitis Suppurativa Market |
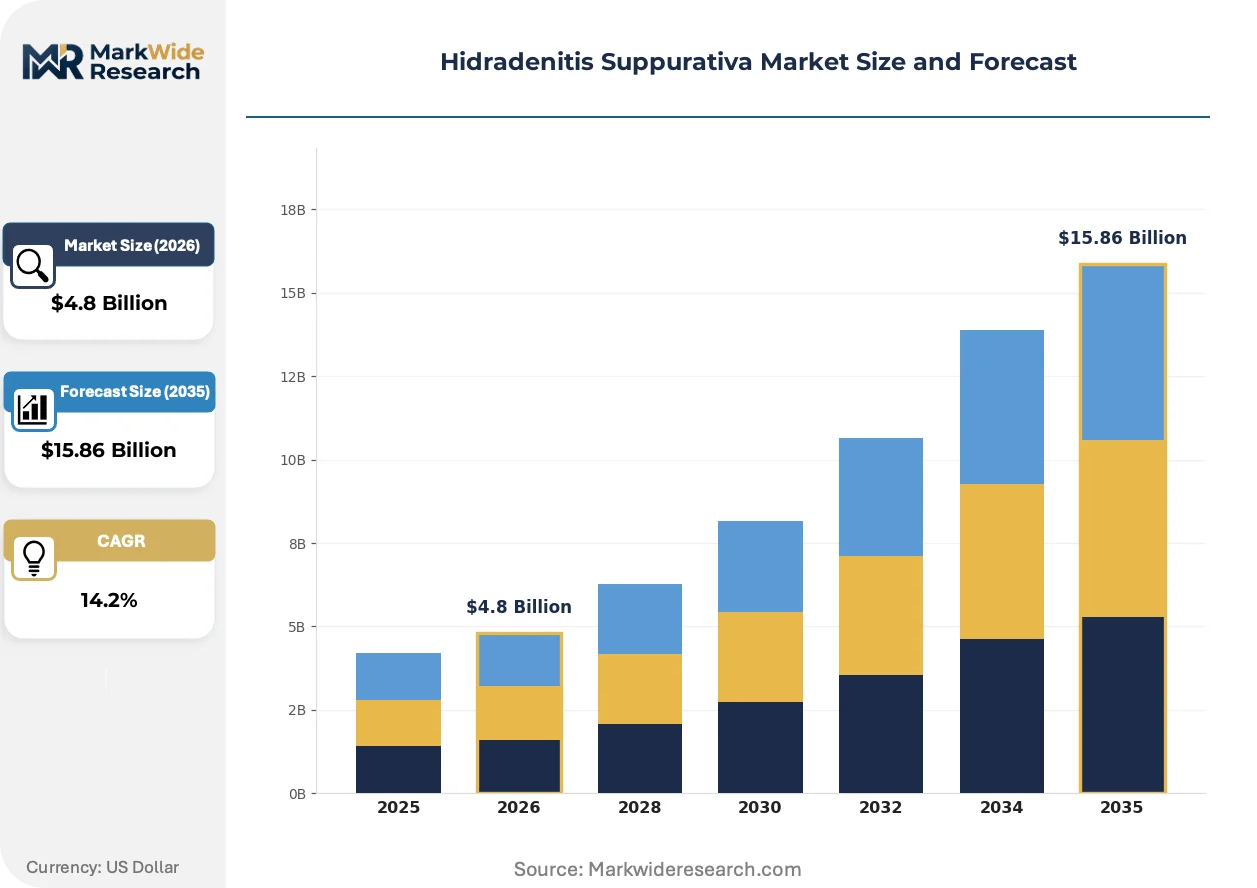
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Topical Treatments, Systemic Therapies, Biologics, Surgical Options Delivery Mode: Injections, Oral Medications, Creams, Surgical Procedures Patient Type: Severe Cases, Moderate Cases, Mild Cases, Refractory Cases End User: Hospitals, Dermatology Clinics, Home Care, Ambulatory Surgical Centers |
| Companies Covered | AbbVie, Novartis AG, Johnson & Johnson, Eli Lilly and Company, Pfizer Inc., UCB, Incyte Corporation, Sanofi, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hidradenitis Suppurativa Market Strategic Shifts
Three distinct vectors are reshaping competitive positioning in HS therapeutics: manufacturing platform evolution, regulatory pathway adaptation, and site-of-care redistribution.
Microbial fermentation technology is converging with single-use bioreactor systems to enable flexible, lower-cost production of cytokine inhibitors previously manufactured in stainless-steel mammalian facilities. Mid-cap developers with limited legacy infrastructure are adopting these platforms fastest, while established immunology players face capex decisions on facility retrofit versus greenfield investment. This convergence is compressing the cost structure for early-phase biologics and enabling competitive pricing headroom against entrenched TNF-alpha franchises.
The FDA's accelerated approval pathway for inflammatory disease therapies is reshaping how Phase IIb trials are constructed, with surrogate endpoint selection now determining commercial timeline viability. Developers are front-loading biomarker validation and accepting expanded post-marketing surveillance obligations to secure earlier revenue recognition. Dermatology biologics face the steepest evidentiary trade-offs under this framework, given the chronic, relapsing nature of HS and the extended follow-up required for definitive clinical outcome confirmation.
Patient triage patterns are rotating toward dermatology clinics with embedded infusion capabilities, displacing hospital outpatient departments as the default site for biologic administration. This channel shift concentrates volume in multi-specialty dermatology groups with capital to deploy infusion infrastructure, fragmenting prescribing influence away from academic medical centers. The United States exhibits this redistribution most visibly, where commercial payer site-of-care policies increasingly favor clinic-based administration with lower facility fees.
Hidradenitis Suppurativa Market Segmentation
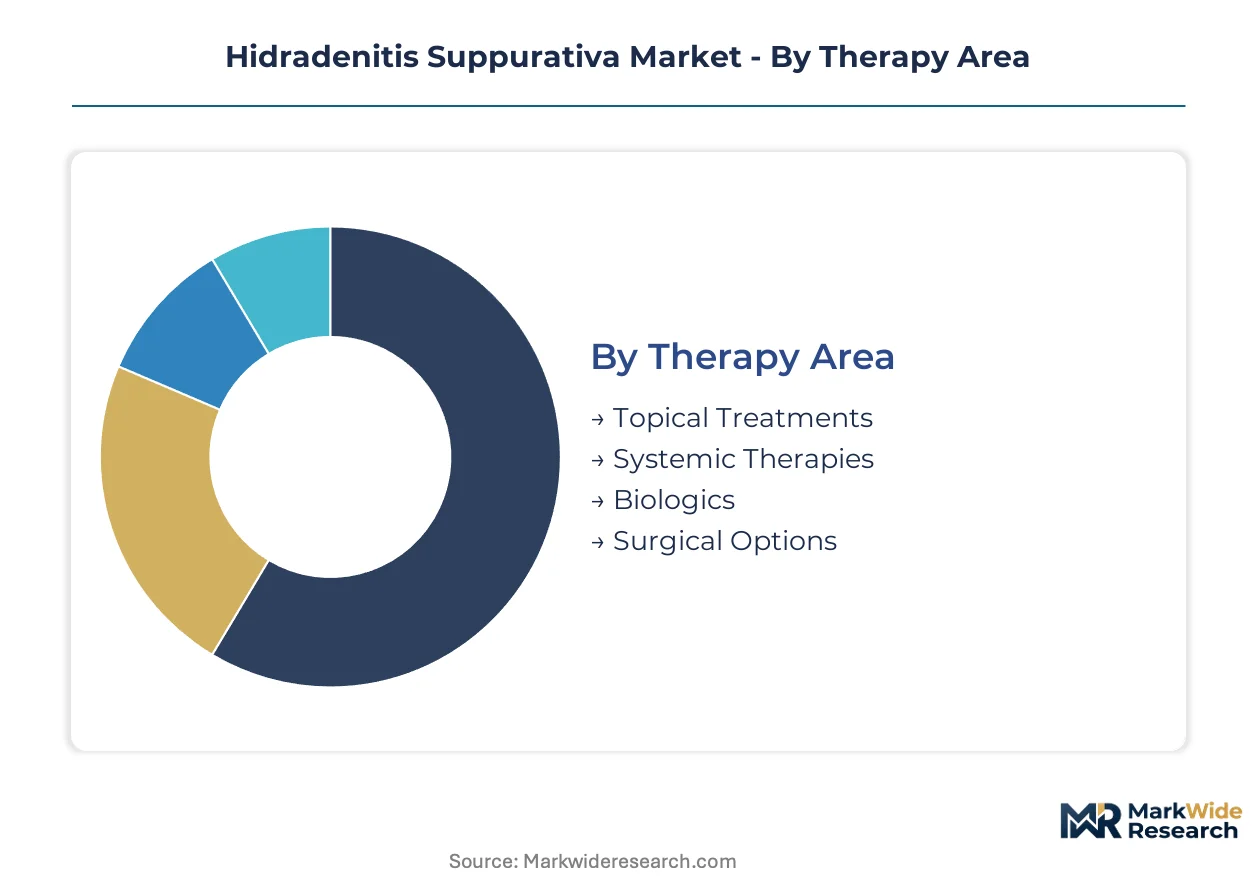
Therapy selection in hidradenitis suppurativa tracks Hurley staging severity, reimbursement pathways, and prescriber specialty. Segment boundaries blur as patients progress through treatment lines, creating portfolio overlap strategies for manufacturers.
Therapy Area:
Cost tier separates chronic maintenance regimens from acute intervention, with biologics commanding premium positioning against systemic alternatives.
- Biologics:Engineered cytokine inhibitors targeting IL-17 and TNF-alpha pathways deliver sustained anti-inflammatory suppression for Hurley Stage II-III patients. Demand concentrates in United States dermatology clinics with infusion capabilities, driven by broadened commercial payer prior authorization criteria.
- Systemic Therapies:Oral antibiotics and hormonal agents manage disease burden across broader patient populations with established safety profiles. Volume sits with United States managed care step-therapy requirements, though margin pressure from generic substitution limits manufacturer investment.
- Topical Treatments:Clindamycin and resorcinol preparations address localized inflammation in early-stage disease.
- Surgical Options:Wide local excision and deroofing procedures resolve refractory sinus tracts when medical therapy fails.
Volume sits with Systemic Therapies; growth tilts toward Biologics.
Delivery Mode:
Application context determines channel economics, with site-of-care policies favoring clinic administration over hospital outpatient settings.
- Injections:Subcutaneous and intravenous biologic formulations require cold-chain distribution and specialized administration infrastructure. Demand concentrates in dermatology clinics expanding infusion suite capacity, driven by CMS site-of-care differentials and commercial payer facility fee structures.
- Oral Medications:Systemic antibiotics, retinoids, and hormonal agents enable patient-managed chronic therapy with broad prescriber reach. Volume sits with primary care and teledermatology triage models, though adherence challenges limit long-term efficacy in moderate-to-severe cohorts.
- Creams:Topical antimicrobial and anti-inflammatory preparations serve first-line and maintenance therapy roles.
- Surgical Procedures:Operative interventions require sterile environments and specialized wound management protocols.
Revenue per patient peaks with Injections; expansion concentrates in Oral Medications via virtual care channels.
Patient Type:
Disease trajectory and treatment history define addressable populations, with refractory cohorts representing the highest unmet need concentration.
- Severe Cases:Hurley Stage III patients with extensive sinus tract formation and scarring require aggressive multimodal intervention. Demand concentrates in academic medical centers and specialized wound clinics, driven by quality-of-life impairment and surgical complication risks.
- Refractory Cases:Patients failing multiple therapy lines drive off-label biologic utilization and clinical trial enrollment. Volume sits with United States and European tertiary referral networks, though diagnostic delay often extends disease duration before specialist access.
- Moderate Cases:Hurley Stage II patients with recurrent abscesses represent the largest addressable biologic-eligible population.
- Mild Cases:Stage I disease managed through topical and lifestyle interventions with high spontaneous fluctuation.
Clinical trial investment targets Refractory Cases; commercial volume accumulates in Severe Cases.
End User:
Customer type shapes procurement patterns, with capital availability and payer mix determining therapy access tiers.
- Dermatology Clinics:Multi-specialty groups with embedded infusion capabilities capture moderate-to-severe biologic volumes previously managed in hospital settings. Demand concentrates in United States metropolitan markets, driven by commercial payer site-of-care policies favoring lower facility fees.
- Hospitals:Academic medical centers manage complex surgical cases and refractory cohorts requiring multidisciplinary coordination. Volume sits with Medicaid and uninsured populations, though biologic infusion migration to clinics erodes traditional revenue streams.
- Home Care:Self-administered subcutaneous biologics and oral therapies enable patient-managed chronic disease control.
- Ambulatory Surgical Centers:Specialized facilities perform elective excision procedures with streamlined reimbursement.
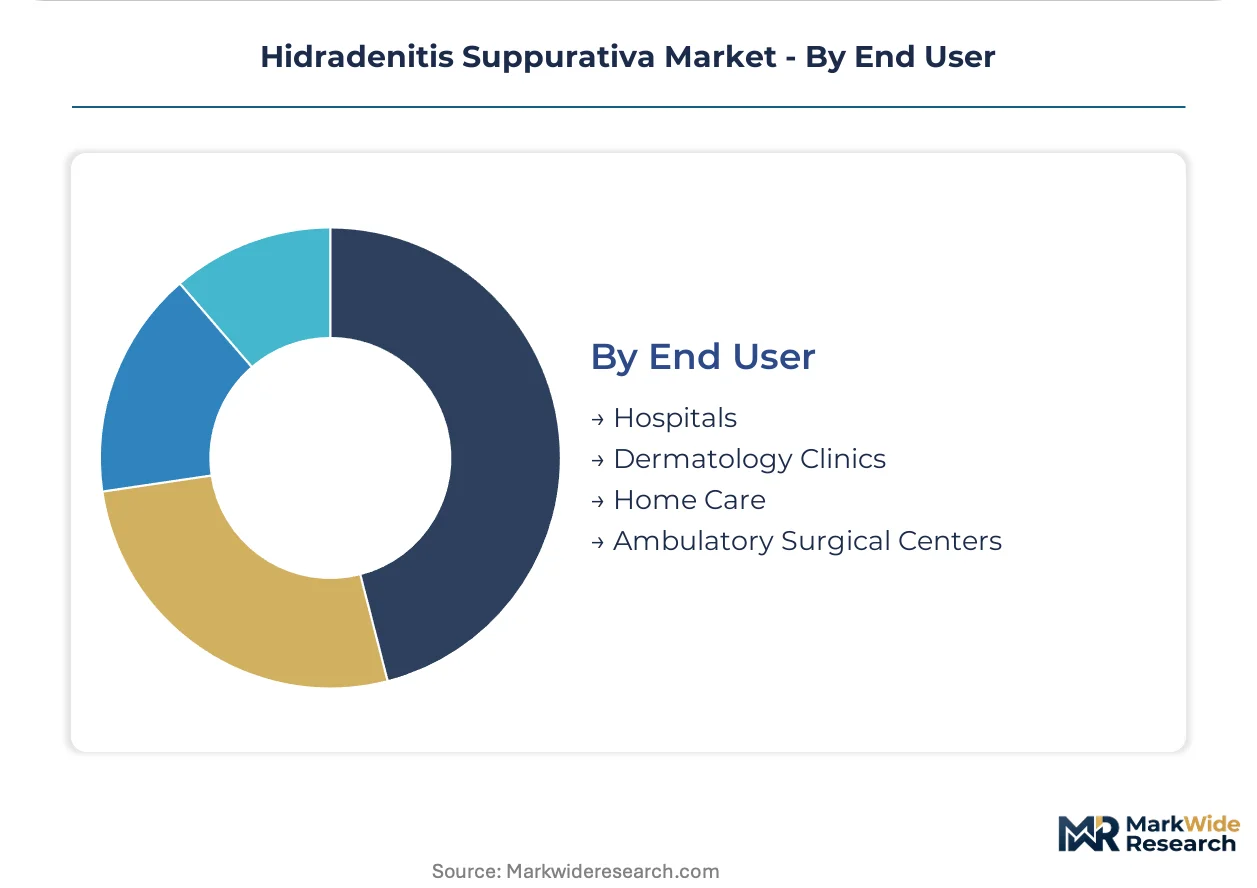
Biologic administration is shifting fastest into Dermatology Clinics; Hospitals retain surgical complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and state-level biotech incentives across the United States concentrate HS clinical trial infrastructure and biologic manufacturing investment, while European regulatory pathways accelerate market entry for inflammatory disease therapies.
United States
Massachusetts and North Carolina biotech corridors anchor Phase IIb trial enrollment for novel IL-17 inhibitors, supported by FDA accelerated approval pathways that compress development timelines. The IRA's Medicare price negotiation provisions reshape commercial payer contracting strategies for dermatology biologics. Philadelphia and San Francisco dermatology clinic networks expand infusion suite capacity to capture moderate-to-severe patient volumes.
Germany
EMA conditional marketing authorizations enable earlier European revenue recognition for pipeline TNF-alpha inhibitors, with post-marketing surveillance obligations accepted by developers seeking competitive runway. The country's statutory health insurance system maintains stringent cost-effectiveness thresholds for biologic reimbursement. Munich and Heidelberg academic medical centers coordinate multinational HS registry studies.
United Kingdom
NICE technology appraisals determine National Health Service access for biologic therapies in dermatology, with severity-based criteria restricting initial prescribing to tertiary referral centers. The MHRA's post-Brexit regulatory autonomy permits accelerated assessments aligned with FDA timelines. London and Manchester multi-specialty dermatology groups consolidate infusion services previously fragmented across hospital trusts.
Japan
PMDA's Sakigake designation system prioritizes review of novel HS biologics, reducing approval lag versus standard pharmaceutical applications. Pricing negotiations under the Chuikyo framework compress reimbursement premiums for follow-on cytokine inhibitors. Tokyo and Osaka dermatology departments lead Asia-Pacific investigator-initiated studies for refractory patient cohorts.
Switzerland
Swissmedic's reliance on EMA assessments streamlines market authorization for HS therapies while maintaining independent pharmacovigilance requirements. The country's contract manufacturing concentration supports sterile injectable production for multi-product immunology portfolios. Basel and Zurich anchor European supply chain coordination for biologic drug substance.
Hidradenitis Suppurativa Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated immunology portfolios commanding premium positioning in biologics while generic systemic therapies fragment among volume-driven suppliers. Large-cap pharmaceutical developers leverage existing manufacturing infrastructure and regulatory relationships to compress development timelines. Two strategic archetypes dominate: diversified immunology platforms extending TNF-alpha expertise into HS, and dermatology-focused biotechs prioritizing IL-17 differentiation. Competitive moves concentrate on manufacturing platform transitions and site-of-care channel investments.
Within the diversified immunology tier, AbbVie, Novartis AG, and Johnson & Johnson represent established infrastructure players. AbbVie occupies a position leveraging legacy manufacturing efficiencies across pipeline assets. Novartis AG exemplifies dermatology-focused IL-17 positioning beyond traditional indications. Johnson & Johnson anchors deep inflammatory disease expertise carried from adjacent therapeutic areas. These three entities collectively illustrate how manufacturing scale and regulatory experience concentrate competitive advantage in accelerated approval environments.
| Leading Market Players |
|---|
| AbbVie |
| Novartis AG |
| Johnson & Johnson |
| Eli Lilly and Company |
| Pfizer Inc. |
| UCB |
| Incyte Corporation |
| Sanofi |
| AstraZeneca |
| Others |
Value Chain & Pricing Dynamics
Captive biologic drug substance production anchors supply position and pricing power for established immunology portfolios, with AbbVie's manufacturing infrastructure sustaining cost advantages that microbial fermentation platforms only partially erode for pipeline competitors. This integration choice concentrates margin defense among legacy TNF-alpha franchises while forcing mid-cap developers toward outsourced sterile injectable manufacturing with attendant price vulnerability.
Pricing Analysis
Volume concentrates in systemic therapies while margin pools in biologics, with three-tier pricing structure across premium cytokine inhibitors, standard oral antibiotics, and economy topical generics. Price differentiation hinges on Hurley staging severity and payer step-therapy position, with Hurley Stage III patients showing lowest price sensitivity due to quality-of-life impairment. Pricing pressure stems from IRA Medicare negotiation provisions reshaping commercial contracting, though dermatology clinic site-of-care policies partially offset facility fee compression.
Supply Chain Analysis
Single-source vulnerability sits with sterile injectable contract manufacturing concentrated in the United States and Switzerland, creating concentration risk for multi-product immunology portfolios. Raw material dependencies center on mammalian cell culture media components, single-use bioreactor systems, and cold-chain distribution infrastructure. Tariff exposure runs through Swiss-based sterile fill-finish capacity. Distribution runs through dermatology clinic infusion suites displacing hospital outpatient departments as the dominant administration channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream manufacturing platform control and downstream site-of-care channel ownership determine competitive survival. Players are pursuing captive biologic production and clinic network partnerships as the decisive levers.
For Market Incumbents: Lock in manufacturing scale advantages through microbial fermentation retrofit or greenfield investment before cost structures invert. Defend against IL-17 pipeline entrants by deepening dermatology clinic infusion partnerships that capture patient volume before academic medical center referral. Prioritize formulary positioning with commercial payers reducing step-therapy burden. For New Entrants and Emerging Players: Refractory patient cohorts in European tertiary referral networks represent the most penetrable entry point, with EMA conditional authorization enabling revenue recognition ahead of full evidence packages. Target teledermatology triage models for oral therapy distribution to capture mild-to-moderate cases before biologic eligibility. Pursue licensing partnerships with established sterile injectable manufacturers to bypass capacity constraints. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap biotechs with IL-17 differentiation and manufacturing platform flexibility. Long-term viability favors assets with regulatory relationships compressing Phase IIb-to-approval timelines. Watch FDA accelerated approval designations for inflammatory disease therapies as the inflection signal determining portfolio valuation trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Platform Transition | Microbial fermentation adoption by mid-cap developers reduces cost-of-goods by roughly one-third for early-phase cytokine inhibitors. |
| Regulatory Approval Pathway | FDA accelerated approval compresses evidence-generation timelines while elevating post-marketing surveillance obligations for biologic developers. |
| Site-of-Care Channel Investment | Dermatology clinic infusion suite expansion captures moderate-to-severe patient volumes previously managed in hospital outpatient departments. |
| Pipeline Diversification | IL-17 positioning beyond psoriatic indications enables competitive differentiation against entrenched TNF-alpha franchises. |
| Licensing Agreement | Partnerships with sterile injectable contract manufacturers bypass single-source capacity constraints in the United States and Switzerland. |
Study Parameters
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, payer access specialists, and dermatology clinic operations directors. Secondary validation drew from CMS national coverage determinations, commercial payer prior authorization criteria, and hospital procurement databases. Bottom-up patient volume estimates and top-down therapy area revenue figures underwent cross-triangulation to resolve segmentation boundaries.
Market size and growth trajectory outputs reflect integrated modeling across therapy area, delivery mode, patient type, and end user dimensions over the projection horizon. CAGRs were derived from patient population epidemiology, treatment line progression rates, and pricing elasticity assumptions specific to dermatology biologics. Forecast inputs incorporated Hurley staging distribution, payer mix evolution, and site-of-care redistribution patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IRA Medicare negotiation implementation, microbial fermentation platform maturation, and FDA accelerated approval pathway evolution. Forecasts reflect documented assumptions regarding regulatory timeline compression and payer coverage expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Cystic Acne Market
Skincare
Global Scar Removal Treatment Market
Skincare
Facial Skincare Market
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Moisturizing Cream Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
Biological Skin Substitutes Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
Preoperative Skin Preparation Market
Skincare
Global Anti-Aging Market
Skincare
Skin Resurfacing Market
Skincare
Skin Boosters Market
Skincare
Facial Mask Market
Skincare
Hand Eczema (HE) Treatment Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Dermal Regeneration Market