
 CBD Skin Care Market | 2026-2036
CBD Skin Care Market Size, Share, and Industry Trends Forecast 2026-2036
CBD Skin Care Market Intelligence
Asset-light licensing and contract manufacturing is tilting competitive dynamics toward brands without captive cultivation. Charlotte's Web leverages vertical integration from seed to shelf, sustaining quality premiums across its direct-to-consumer channel. L'Oréal anchors mass-market credibility through Kiehl's, while Cannuka differentiates via Manuka honey-CBD hybrid formulations.
CBD skin care comprises topical formulations incorporating cannabidiol extract, typically at concentrations between 0.1% and 3% by weight, designed for anti-inflammatory, sebum-regulating, and barrier-repair functions. The ingredient source dimension segments into industrial hemp-derived full-spectrum extracts, which dominate current volume, and isolate-based formulations, which command pricing premiums in clean-beauty channels. Serums and oils capture disproportionate margin pools due to higher per-unit CBD content and concentrated dosing formats, while lotions compete on accessibility and daily-use frequency.
The FDA regulates topical CBD under the Federal Food, Drug, and Cosmetic Act, creating compliance friction for brands making therapeutic claims, while the USDA oversees hemp cultivation standards that determine raw material legality. State-level cosmetic safety boards in California and New York impose additional testing protocols for heavy metals and residual solvents. Stakeholders must monitor pending FDA rulemaking on CBD as a cosmetic ingredient, as final determinations will reshape permissible marketing language and retail channel access.
Market Dynamics
Millennial wellness consumption patterns are compressing traditional cosmetic distribution cycles, forcing brands to bypass wholesale intermediaries and build direct-to-consumer infrastructure with embedded education platforms.
Growth Catalysts
- Federal hemp legality under the US Farm Bill:Interstate commerce barriers collapsed for hemp-derived CBD, enabling national retail expansion without state-by-state botanical licensing.
- Clean-beauty certification pipelines:EWG Verified and Leaping Bunny standards now accommodate CBD formulations, opening premium shelf space previously restricted to conventional actives.
- Sebum-regulation clinical substantiation:Dermatology journals publishing CBD's TRPV1 and CB2 receptor modulation data are legitimizing acne and sensitive-skin positioning claims.
Market Restraints
- FDA therapeutic claim prohibition:Topical CBD marketed with drug-like efficacy language triggers enforcement under the Federal Food, Drug, and Cosmetic Act, chilling marketing investment.
- Colorado and Oregon cultivation concentration:Seventy percent of domestic hemp biomass originates from two states, creating climate and regulatory contagion risk for raw material supply.
- Isolate versus full-spectrum formulation uncertainty:Entourage-effect science remains contested, fragmenting R&D budgets across incompatible extraction methodologies.
Strategic Opportunities
- Pending FDA cosmetic ingredient rulemaking:Final determinations on CBD safety profiles would unlock mass-retail channel access currently restricted by liability concerns.
- Manuka honey-CBD hybrid formulations:Antimicrobial synergies between New Zealand-sourced honey and cannabidiol are opening professional spa and medical aesthetic channels.
- Subscription-based personalization platforms:AI-driven skin assessment tools paired with CBD concentration customization are capturing recurring revenue models in the direct-to-consumer segment.
Industry Challenges
- Analytical chemist scarcity for cannabinoid quantification:HPLC and mass spectrometry expertise specific to complex botanical matrices commands premium compensation, constraining quality control scaling.
- Batch-to-batch consistency verification:Natural hemp phytochemical variation requires costly third-party testing at multiple production stages, compressing margins on entry-price products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD Skin Care Market |
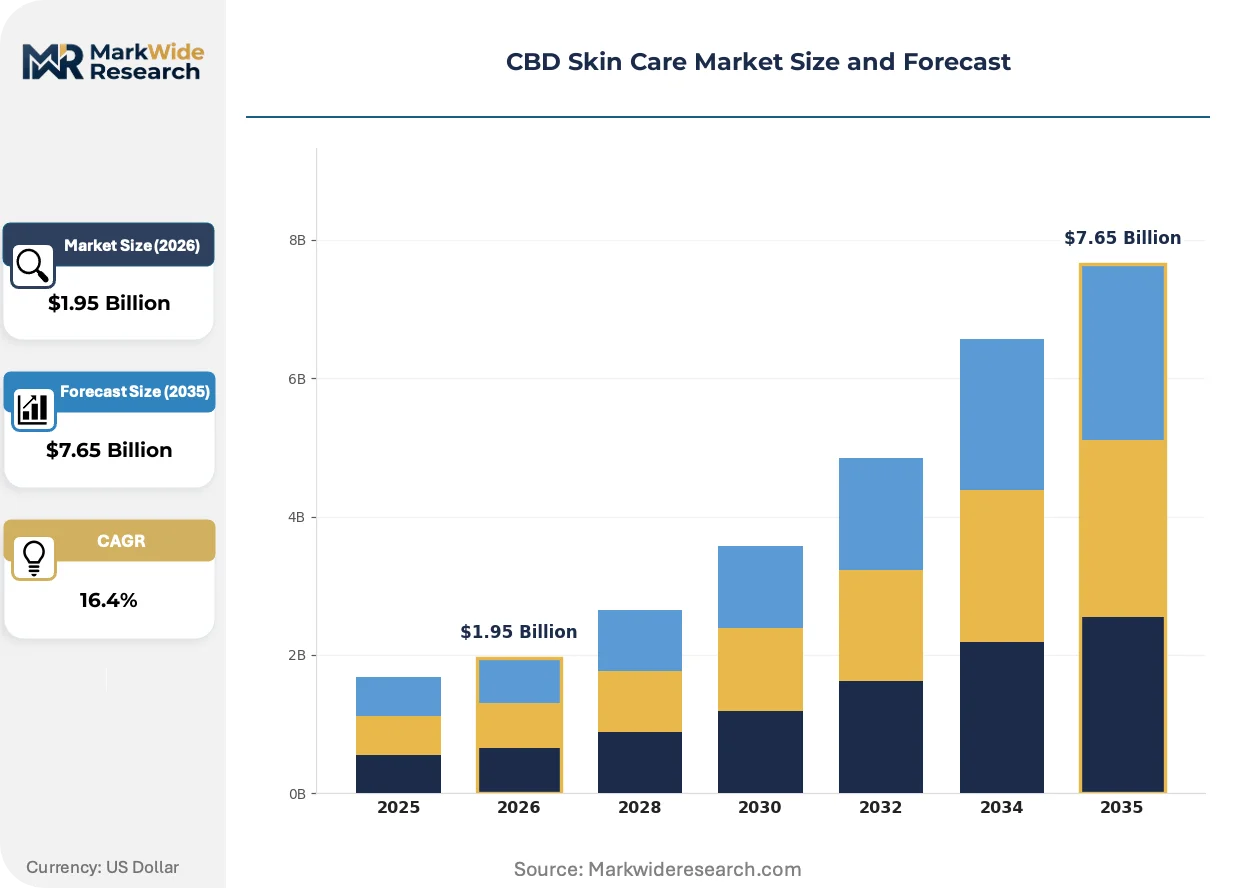
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $7.65 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotions, Creams, Serums, Oils Ingredient Source: Industrial Hemp, Cannabis Sativa, Isolates, Full Spectrum Formulation: Organic, Vegan, Non-GMO, Cruelty-Free Target Market: Millennials, Athletes, Individuals with Skin Conditions, Health-Conscious Consumers |
| Companies Covered | Charlotte's Web, Inc., L'Oréal (Kiehl's), CBD For Life, Elixinol, The CBD Skincare Co, Endoca, Earthly Body, Inc., Cannuka, LLC, Josie Maran Cosmetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD Skin Care Market Strategic Shifts & Innovations
Formulation science and channel architecture are diverging sharply between clinical-positioned and lifestyle-positioned CBD skin care, with technology investments clustering around traceability and personalization rather than manufacturing scale.
Nanoencapsulation technology using liposomal and ethosomal delivery systems is improving CBD bioavailability through dermal penetration enhancement. Premium serum manufacturers in California and New York are adopting these systems to justify concentration premiums. The technology is digitizing supply chain transparency by embedding batch-level potency data into QR-accessible consumer interfaces.
The FDA's pending enforcement discretion policy for topical CBD cosmetics is creating regulatory preemption risk for state-level labeling requirements. Brands are consolidating formulation standards to California's Proposition 65 heavy metal thresholds as a de facto national baseline. Mass-market entrants are delaying launch timelines pending final rule publication, while prestige players are accelerating medical-adjacent positioning to exploit current ambiguity.
Consumer education burden is shifting from retail associates to interactive digital content. Millennial and Gen Z buyers in the United States are completing purchase decisions through Instagram and TikTok tutorials rather than in-store sampling. This behavior is compressing traditional wholesale margins as brands reallocate trade spend to influencer partnerships and owned-community platforms.
CBD Skin Care Market Segmentation
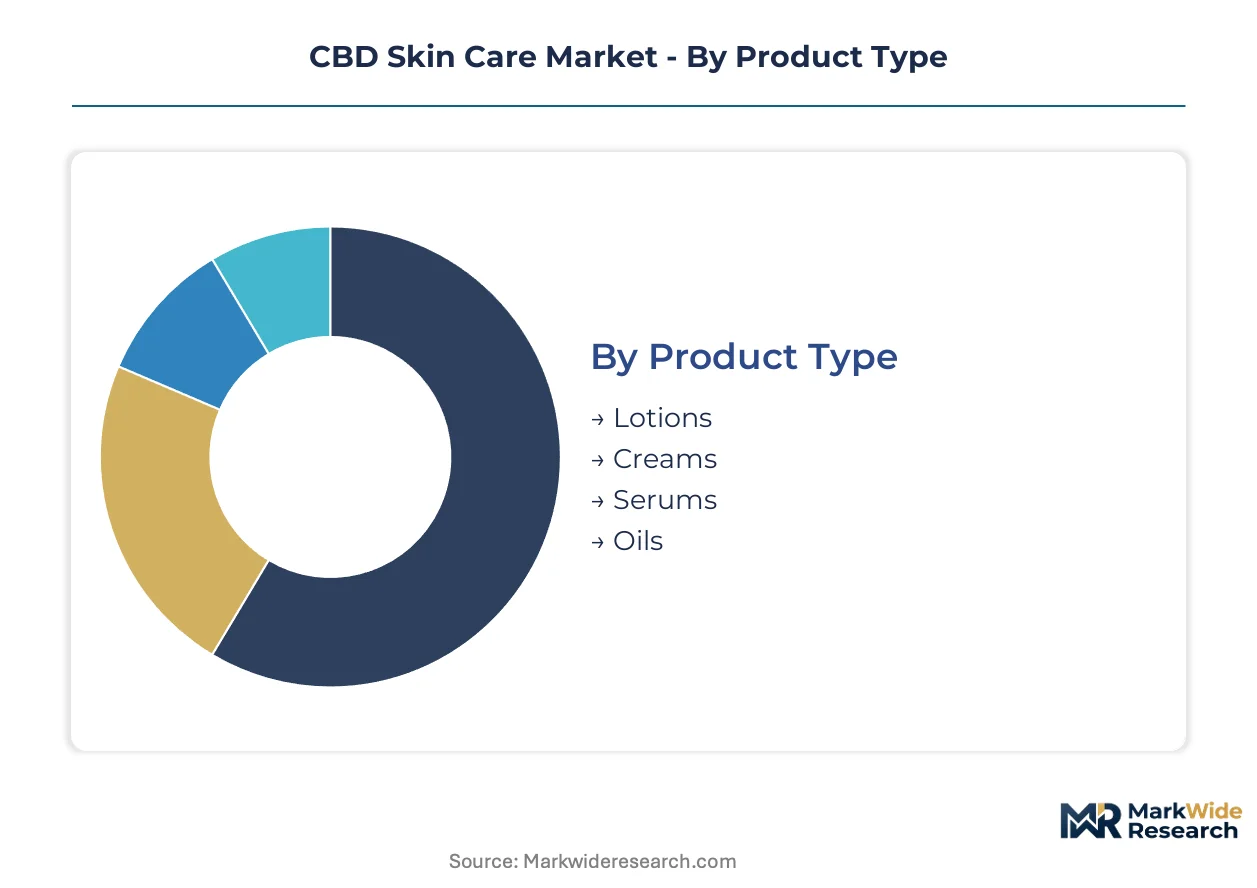
CBD skin care segmentation reflects divergent paths between clinical efficacy positioning and lifestyle wellness branding. Product formats and ingredient sourcing strategies determine margin architecture and regulatory exposure across distinct consumer cohorts.
Product Type:
Mature formats compete on accessibility while emerging concentrated formats command premium positioning.
- Lotions:Daily-use moisturizers with CBD concentrations typically below 0.5% serve mass-market entry points. Demand concentrates in United States drugstore and big-box retail channels where unit economics favor volume throughput over margin extraction.
- Serums:Highly concentrated formulations ranging 1-3% CBD leverage liposomal delivery systems for dermal penetration claims. Professional aesthetic clinics and direct-to-consumer subscription platforms in California and New York drive adoption through clinical positioning and personalized dosing protocols.
- Creams:Thicker emulsions targeting localized application for dry or irritated skin patches.
- Oils:Single-ingredient or minimalist blends emphasizing full-spectrum entourage effects for facial and body application.
Lotions handle the majority of throughput; serums are expanding most quickly on share.
Ingredient Source:
Supply chain geography and extraction methodology create tiered quality perceptions with direct regulatory implications.
- Industrial Hemp:Farm Bill-compliant biomass from Colorado and Oregon cultivation zones dominates domestic volume. USDA organic certification and state-level testing protocols for heavy metals and residual solvents determine interstate commerce eligibility.
- Full Spectrum:Whole-plant extracts retaining minor cannabinoids and terpenes command pricing premiums in clean-beauty channels. EWG Verified and Leaping Bunny certification pipelines now accommodate these formulations, opening previously restricted prestige retail placement.
- Cannabis Sativa:Botanical extracts from regulated marijuana programs face state-by-state distribution constraints.
- Isolates:Crystalline CBD powder enables precise dosing and THC-free labeling for conservative consumer segments and international export markets.
Industrial hemp handles the majority of throughput; full spectrum is gaining share fastest.
Formulation:
Certification stacking determines shelf placement and consumer willingness to pay across clean-beauty retail.
- Organic:USDA-certified hemp cultivation paired with organic carrier oils and emulsifiers satisfies the strictest clean-beauty retail requirements. Whole Foods Market and Sephora Clean standards mandate this certification for premium placement.
- Cruelty-Free:Leaping Bunny and PETA certification addresses the largest addressable ethical consumer segment in United States cosmetics. Mass-market brands leverage this designation to compete with prestige players on values alignment without organic price premiums.
- Vegan:Elimination of beeswax, lanolin, and other animal-derived ingredients targets the intersection of plant-based diet adherents and CBD-curious consumers.
- Non-GMO:Third-party verification of hemp genetics and carrier oil sourcing appeals to consumers skeptical of agricultural biotechnology.
Cruelty-free handles the majority of throughput; organic is climbing the fastest on share.
Target Market:
Demographic and psychographic targeting shapes channel strategy and educational content investment.
- Millennials:Digital-native consumers aged 28-43 complete purchase journeys through Instagram and TikTok tutorials rather than in-store sampling. Direct-to-consumer brands allocate trade spend to influencer partnerships and owned-community platforms to capture this cohort.
- Individuals with Skin Conditions:Eczema, psoriasis, and acne sufferers seek anti-inflammatory positioning substantiated by dermatology journal publications on TRPV1 and CB2 receptor modulation. Medical aesthetic clinics and telemedicine platforms serve as trusted distribution channels.
- Athletes:Post-workout recovery and muscle soothing applications drive sports-specific product development with higher CBD concentrations.
- Health-Conscious Consumers:General wellness positioning targets supplement-adjacent purchasing behavior in natural grocery and specialty retail.
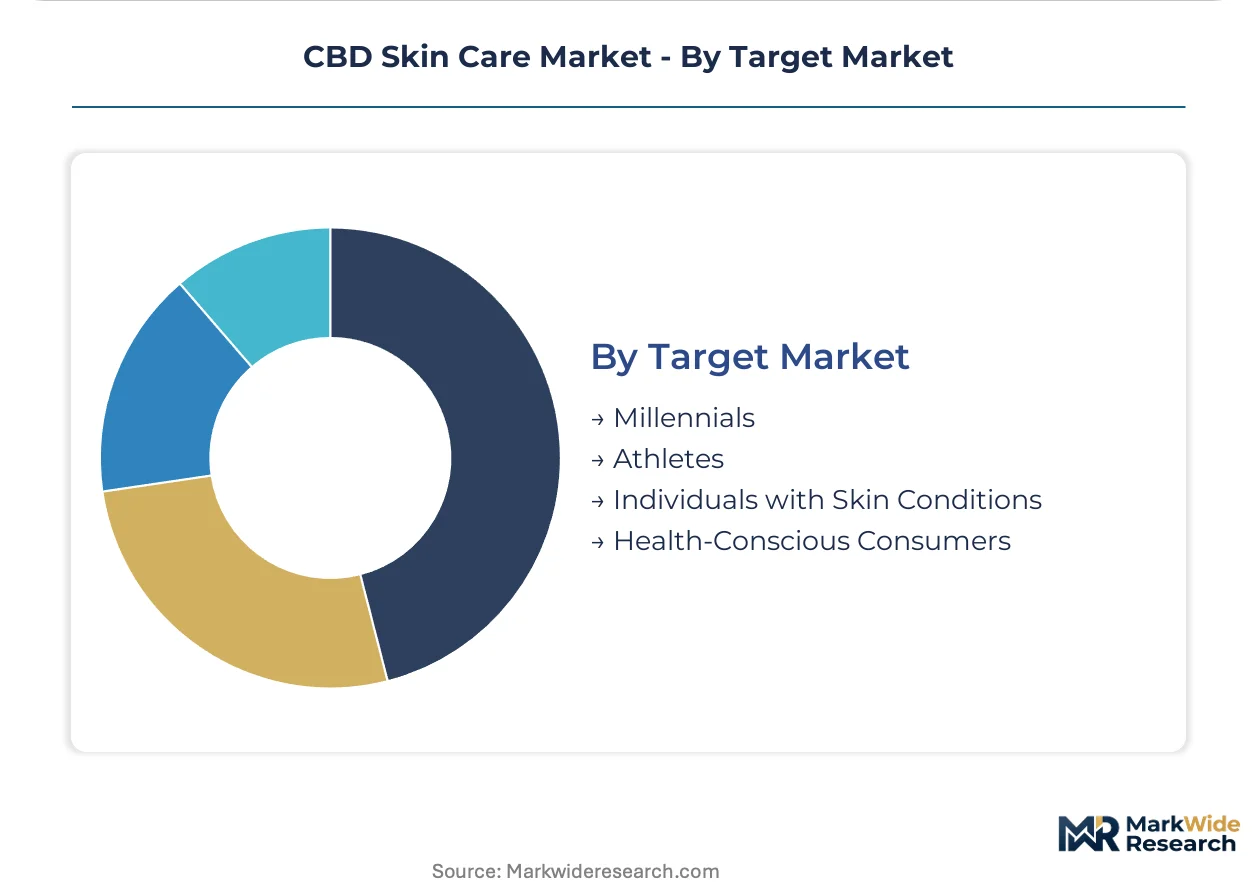
Millennials handle the majority of throughput; individuals with skin conditions represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial wellness buyers concentrate in coastal metropolitan areas, with demand clustering around cities with established clean-beauty retail infrastructure and progressive cosmetic regulatory environments.
United States
Direct-to-consumer subscription platforms and medical aesthetic clinics drive serum and oil adoption among eczema and acne sufferers. The FDA's pending cosmetic ingredient rulemaking on CBD safety profiles creates preemption uncertainty for state-level labeling requirements. Colorado and Oregon cultivation zones supply seventy percent of domestic hemp biomass, with Denver and Portland anchoring extraction and formulation clusters.
Germany
Clean-beauty certification adopters in Berlin and Munich fuel demand for EWG Verified and Leaping Bunny accredited formulations. The EU Cosmetics Regulation and BfR guidance on novel cosmetic ingredients determine permissible CBD concentration thresholds and marketing claims. The Cologne-Düsseldorf corridor hosts contract manufacturing facilities serving prestige European brands.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks creates formulation adaptation costs for brands serving both markets. The UK Food Standards Agency's novel food authorization process for ingestible CBD indirectly shapes topical product positioning strategies. London's Shoreditch and Soho districts concentrate independent CBD beauty retailers and influencer marketing agencies.
Canada
Health Canada's Cannabis Act framework permits cannabis-derived CBD in cosmetics, enabling broader formulation options than hemp-restrictive jurisdictions. Provincial retail monopolies in Ontario and British Columbia control shelf access, favoring established licensed producers with cosmetic diversification strategies. Toronto and Vancouver anchor formulation R&D clusters serving North American export markets.
Australia
The TGA's down-scheduling of low-dose CBD to pharmacist-only medicine status signals potential future cosmetic pathway liberalization. Sydney and Melbourne wellness consumers drive early adoption of imported premium hemp-derived serums through specialty retailers and telemedicine-adjacent platforms. The Therapeutic Goods Administration's ongoing safety review creates launch timing uncertainty for domestic brand entrants.
CBD Skin Care Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base spans vertically integrated cultivators, mass-market beauty conglomerates with CBD line extensions, and independent clean-beauty specialists. Three archetypes dominate: seed-to-shelf integrated operators, licensed brand licensors leveraging contract manufacturing, and prestige beauty houses adding CBD SKUs to existing distribution. Competitive moves concentrate on clean-certification stacking and direct-to-consumer platform acquisition.
Within the integrated cultivation tier, Charlotte's Web, Inc. exemplifies backward control over hemp supply chains. Among mass-market beauty houses, L'Oréal (Kiehl's) occupies a position leveraging existing prestige retail relationships for CBD line placement. On the independent specialist vector, Cannuka, LLC represents the hybrid-formulation archetype combining regional botanical sourcing with cannabinoid actives.
| Leading Market Players |
|---|
| Charlotte's Web, Inc. |
| L'Oréal (Kiehl's) |
| CBD For Life |
| Elixinol |
| The CBD Skincare Co |
| Endoca |
| Earthly Body, Inc. |
| Cannuka, LLC |
| Josie Maran Cosmetics |
| Others |
Cost & Logistics Intelligence
Colorado's Front Range extraction corridor anchors domestic CBD biomass processing, with Denver-area facilities converting Oregon and Colorado hemp harvests into isolate and full-spectrum inputs that determine downstream pricing power for finished skin care formulations.
Pricing Analysis
Cost-plus contracts indexed to USDA hemp spot prices govern raw material procurement between cultivators and formulators. Three-tier pricing structure across premium, standard, and economy levels separates EWG Verified organic serums from Leaping Bunny-certified mass lotions and unbranded private-label entry products. Pricing pressure stems from analytical chemist scarcity driving quality control premiums upward. Mass-market drugstore buyers exhibit highest price sensitivity, while medical aesthetic clinic procurement shows lowest elasticity due to clinical positioning requirements.
Supply Chain Analysis
Contract manufacturing concentrates among Colorado and New York-based facilities with USDA organic certification and Prop 65 compliance capabilities. Raw material dependencies draw from Colorado and Oregon hemp cultivation, New Zealand Manuka honey imports, and California-sourced organic carrier oils. Single-source vulnerability runs through the Denver-Portland biomass corridor where climate disruption threatens crop yields. Distribution runs through direct-to-consumer subscription platforms, Sephora and Whole Foods premium retail, and medical aesthetic clinic professional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as bakuchiol and other plant-derived anti-inflammatory actives capture clean-beauty formulation share previously reserved for CBD positioning.
For Market Incumbents: Insulate market position by deepening backward integration into USDA organic hemp cultivation in Colorado and Oregon to secure batch-to-batch consistency. Prioritize investment in liposomal delivery system R&D to sustain serum premium pricing against bakuchiol-based competitor formulations. Channel control through owned-community platforms reduces dependence on Instagram and TikTok algorithm shifts. For New Entrants and Emerging Players: Australia's pharmacist-only CBD scheduling creates underpenetration opportunity for premium hemp-derived serum imports before TGA cosmetic pathway liberalization. Target eczema and psoriasis sufferers through telemedicine-adjacent platforms with TRPV1 receptor modulation clinical substantiation. Leaping Bunny certification without organic price premium enables mass-market white-space entry. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory optionality play because FDA cosmetic ingredient rulemaking finalization will determine mass-retail channel access and valuation multiples. Acquisition targets should display seed-to-shelf integration or AI-driven personalization platform capabilities. Monitor FDA Federal Register notices and state-level cosmetic safety board rulemaking as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | USDA-certified hemp sourcing secures batch consistency and Prop 65 compliance for interstate commerce. |
| AI-Driven Personalization Platform Launch | Skin assessment tools with CBD concentration customization capture recurring direct-to-consumer revenue. |
| Leaping Bunny Certification Investment | Cruelty-free accreditation opens Sephora Clean and Whole Foods premium shelf placement. |
| Medical Aesthetic Channel Partnership | Professional clinic distribution legitimizes clinical positioning for eczema and acne formulations. |
| Liposomal Delivery System Adoption | Nanoencapsulation technology justifies serum concentration premiums through enhanced dermal penetration claims. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA Federal Register filings, USDA hemp cultivation reports, and state cosmetic safety board regulations. Conversations with brand formulation directors, contract manufacturing facility managers, Sephora category buyers, medical aesthetic clinic procurement officers, and clean-beauty certification auditors informed demand-side and supply-side assessments. Secondary validation drew from EWG Verified product databases, Leaping Bunny accreditation lists, and dermatology journal publications on cannabinoid receptor modulation. Bottom-up volume modeling triangulated against top-down market sizing.
Forecast inputs span product type segmentation across lotions, serums, creams, and oils; ingredient source tiers from industrial hemp to full-spectrum extracts; formulation certification stacking; and target demographic cohorts from millennials to skin condition sufferers. CAGRs derive from regression analysis against Farm Bill implementation trajectory and FDA rulemaking timeline assumptions. Model sensitivity tests FDA cosmetic ingredient determination scenarios and clean-beauty certification adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by mass-market beauty conglomerates or preemptive FDA clearance investments by seed-to-shelf operators would shift volume and value outcomes. Quarterly review of FDA enforcement discretion policy updates, state-level labeling requirement preemption actions, and EWG Verified pipeline approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Facial Skincare Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
Facial Erythema Treatment Market
Skincare
Revitalizing Skin Wands Market
Skincare
Skin Antiseptic Market
Skincare
Professional Skin Care Market
Skincare
Skin Boosters Market
Skincare
Skin Care Body Products Market
Skincare
Europe Functional Cosmetics Market
Skincare
Ampoule Cream Market
Skincare
Incontinence Skin Care Products Market
Skincare
Skin Care Emulsion Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Encapsulated Retinol Market
Skincare
Natural Skin Care Products Market