
 Skills Management Software Market | 2026-2036
Skills Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Skills Management Software Market Analytics
Subscription-based access to software-defined skills analytics is expanding the addressable base beyond traditional enterprise licensees. SAP SuccessFactors leverages deep ERP integration to anchor large-account retention across European manufacturing hubs. Workday competes through unified HCM-to-finance data architecture that sustains renewal rates in North American healthcare and technology sectors. AG5 specializes in shop-floor skills matrices, dominating industrial environments where compliance tracking intersects with operational safety protocols.
Skills management software comprises cloud-native and on-premise platforms that catalog workforce competencies, map proficiency levels against role requirements, and automate training gap closure through API-connected learning systems. The technology serves commercial and industrial employers seeking to reduce certification lag, optimize project staffing, and demonstrate regulatory readiness through auditable skills records. Cloud-based deployment leads solution uptake as mid-market buyers abandon capital-intensive infrastructure, while workforce planning modules capture disproportionate margin pools due to their strategic positioning in C-suite workforce transformation agendas. Employee training functionality remains mature with high penetration among large enterprises, whereas talent acquisition integrations represent the fastest-growing solution segment as recruiters demand seamless candidate-to-employee skills verification.
The EU AI Act and GDPR impose algorithmic transparency and data residency obligations on European skills platform vendors, forcing architectural investments that smaller providers struggle to fund. The U.S. Equal Employment Opportunity Commission and state-level privacy frameworks in California and New York create a fragmented compliance landscape requiring jurisdictional product variants. OSHA recordkeeping standards in industrial settings further shape feature roadmaps for frontline workforce applications. Buyers should evaluate vendor regulatory coverage breadth against their own geographic footprint expansion plans, as compliance gaps become deal-breakers in multi-national procurement cycles.
Market Dynamics
Cloud migration is compressing deployment cycles while EU AI Act compliance mandates force architectural rebuilds across European vendor portfolios.
Growth Catalysts
- GDPR Data Residency Mandates:European employers must maintain auditable skills records within jurisdictional boundaries, accelerating replacement of legacy on-premise systems.
- API-Connected Learning Ecosystems:Real-time synchronization between skills matrices and LMS platforms eliminates manual certification tracking in healthcare and aviation maintenance operations.
- German Industrial Manufacturing:Automotive and chemical producers deploy shop-floor skills verification to satisfy OSHA-equivalent safety protocols and reduce incident liability exposure.
Market Restraints
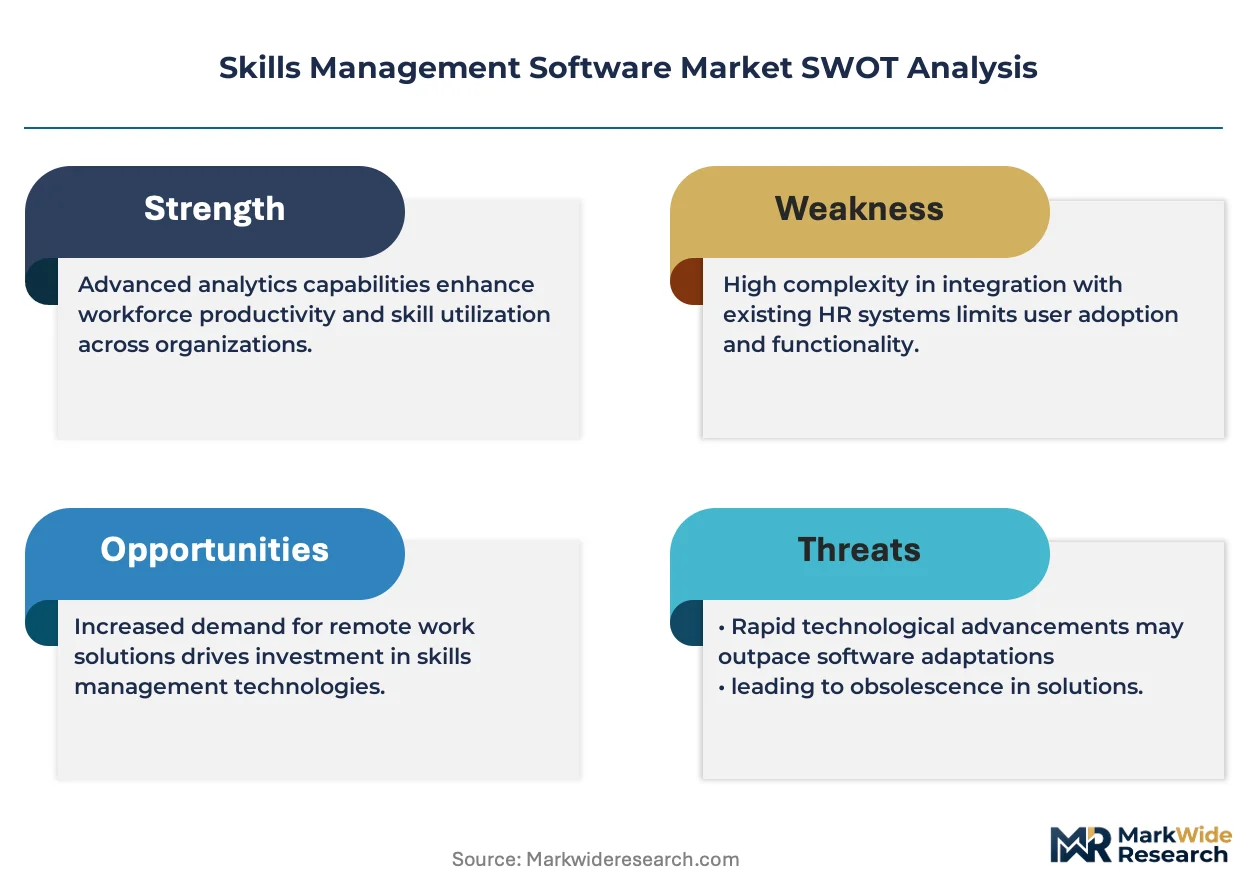
- Algorithmic Audit Costs:EU AI Act Article 10 conformity assessments impose six-figure certification burdens that exclude subscale SaaS providers from public-sector procurement.
- Cloud Infrastructure Concentration:AWS, Azure, and GCP dominance in hyperscale data centers creates single-point-of-failure risk for multi-tenant skills platforms serving critical infrastructure sectors.
- Skills Ontology Fragmentation:Incompatible competency frameworks across ISO, IEC, and national standards bodies force costly custom mapping for multinational deployments.
Strategic Opportunities
- Japan's METI Digital Talent Initiative:Government subsidies for workforce reskilling create procurement windows for platforms demonstrating JIS-compliant skills taxonomy support.
- Skills-Based Hiring Convergence:Integration of pre-hire assessment tools with post-hire development tracking collapses candidate-to-contributor verification gaps in technology and financial services.
- India's PLI Scheme Manufacturing:Electronics and pharmaceutical producers receiving production-linked incentives must demonstrate certified workforce capabilities, creating first-mover advantages for localized platform deployments.
Industry Challenges
- Legacy ERP Integration Complexity:SAP and Oracle system architectures require custom middleware development, extending implementation timelines and inflating professional services costs.
- AI Ethics Governance Talent Scarcity:Shortage of professionals capable of interpreting EU AI Act risk classifications slows product roadmap execution for automated skills-matching algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skills Management Software Market |
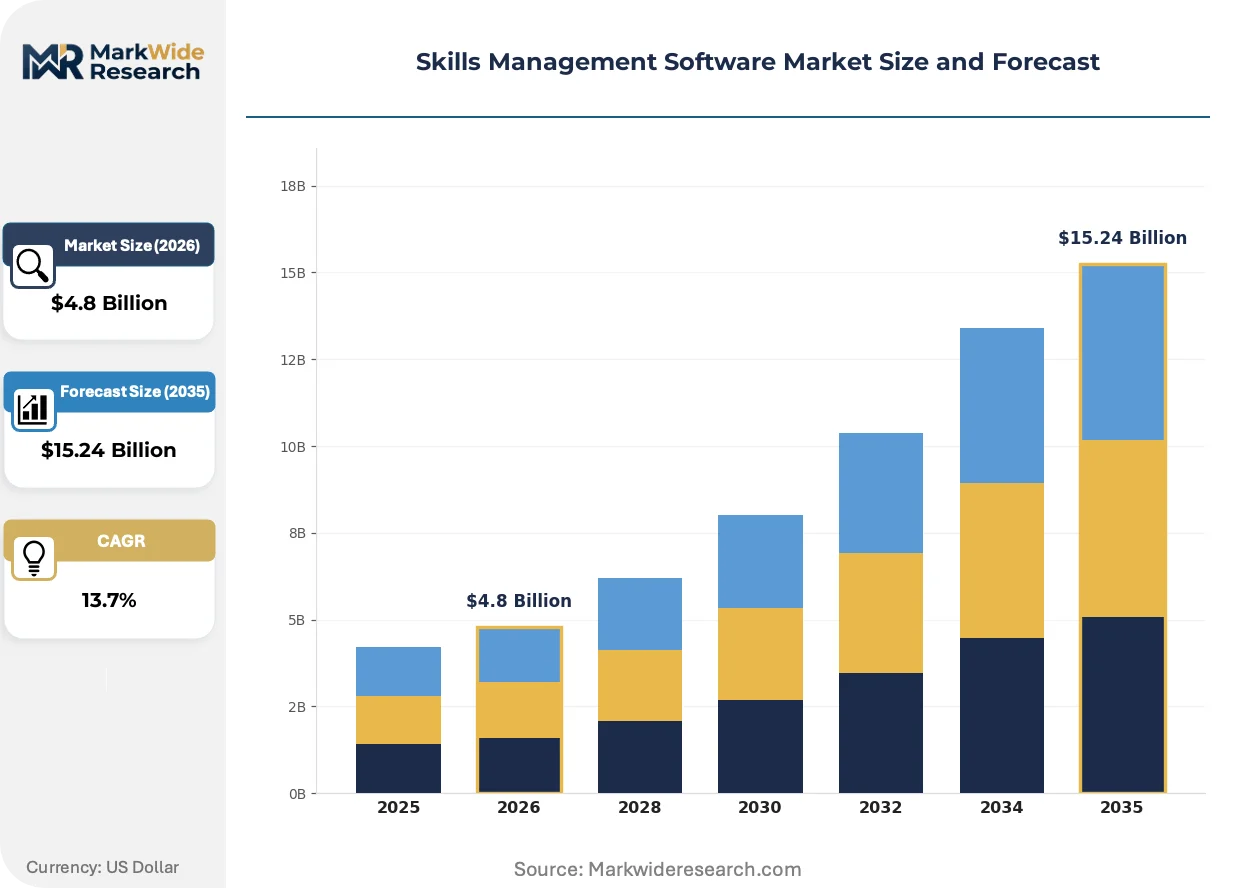
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Small Enterprises, Medium Enterprises, Large Enterprises, Government Solution: Employee Training, Performance Management, Talent Acquisition, Workforce Planning Feature: Analytics, Reporting, User Management, Integration |
| Companies Covered | Workday, AG5, SkillPanel, iMocha, SumTotal, SAP SuccessFactors, Skills Base, Lattice, Oracle HCM Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skills Management Software Market Evolving Landscape
Generative AI is rewriting competency mapping workflows while regulatory pressure on algorithmic decision-making forces transparency investments. Skills verification is shifting from periodic assessment to continuous credentialing.
Large language models are electrifying automated competency extraction from unstructured performance data. Fortune 500 HR departments in the United States and Germany are piloting these systems to reduce skills inventory latency from quarterly to real-time cycles. The compression is forcing legacy assessment vendors to reprice annual certification contracts or lose renewal battles.
EU AI Act risk classification requirements are mandating human-in-the-loop overrides for high-stakes staffing algorithms. Industrial employers in France and the Netherlands must document audit trails for automated project-team assignments affecting safety-critical roles. Vendors are responding by embedding explainability dashboards that trace competency-match logic to specific training records and supervisor validations.
Subscription fatigue among mid-market buyers is fragmenting procurement into modular point solutions rather than integrated suites. North American healthcare systems now acquire skills verification APIs separately from workforce planning modules, pressuring full-stack vendors to unbundle pricing. This disaggregation favors specialized providers with narrow but deep compliance feature sets over horizontal platforms with undifferentiated functionality breadth.
Skills Management Software Market Segmentation
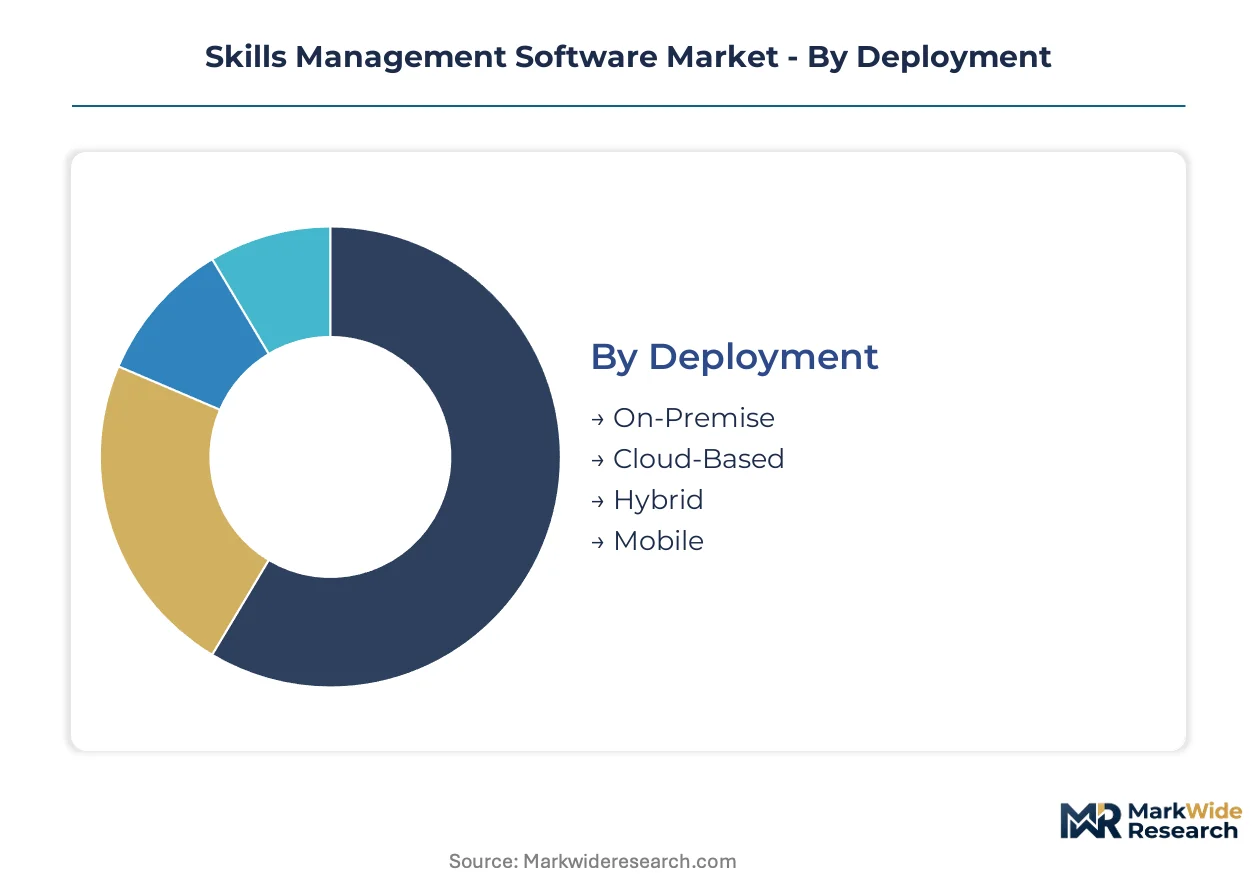
Deployment architecture determines total cost of ownership and compliance posture for skills platform buyers. Enterprise procurement teams weigh data residency mandates against scalability requirements when structuring vendor evaluations.
Deployment:
Cloud migration economics dominate buyer decision frameworks.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure and compress implementation timelines. German automotive manufacturers and United States healthcare systems prioritize these deployments to satisfy GDPR and HIPAA data processing requirements without on-site infrastructure.
- On-Premise:Single-tenant installations behind corporate firewalls address classified environments and legacy integration constraints. Defense contractors and financial institutions in Japan maintain these deployments for JIS-compliant skills taxonomy control.
- Hybrid:Split architectures isolate sensitive personnel records on-premise while leveraging cloud analytics for workforce planning modules.
- Mobile:Native iOS and Android applications extend skills verification to field technicians and distributed service teams.
Volume sits with Cloud-Based; growth tilts toward Hybrid as regulated industries seek architectural compromise.
End User:
Organizational scale dictates feature complexity and pricing tier access.
- Large Enterprises:Global workforces exceeding 10,000 employees require federated skills ontologies and multi-language competency frameworks. These buyers command dedicated customer success resources and API rate limits supporting millions of monthly transactions.
- Government:Public sector procurement imposes certification requirements and audit trail standards exceeding commercial norms. European agencies enforce EU AI Act algorithmic transparency for automated staffing recommendations.
- Medium Enterprises:Organizations between 500 and 5,000 employees favor pre-configured industry templates over custom implementations.
- Small Enterprises:Sub-500 employee operations prioritize self-service onboarding and per-seat pricing without professional services commitments.
Revenue concentrates in Large Enterprises; subscription expansion is climbing the fastest among Medium Enterprises adopting modular point solutions.
Solution:
Functional modules align with HR process maturity and strategic workforce planning sophistication.
- Workforce Planning:Scenario modeling tools project competency gaps against business expansion timelines. C-suite buyers in United States technology and financial services sectors commission these modules for board-level workforce transformation narratives.
- Talent Acquisition:Pre-hire assessment integration with post-hire development tracking eliminates candidate-to-employee verification discontinuities. Recruiters in India and Japan demand seamless skills credentialing as hiring velocity increases.
- Employee Training:LMS connectivity and certification expiration alerting serve mature compliance environments in aviation and healthcare.
- Performance Management:Competency-based evaluation workflows link individual development plans to organizational capability requirements.
Deployment breadth favors Employee Training; margin capture is expanding most quickly in Workforce Planning due to strategic buyer positioning.
Feature:
Technical capabilities differentiate vendor suitability for integration-heavy environments.
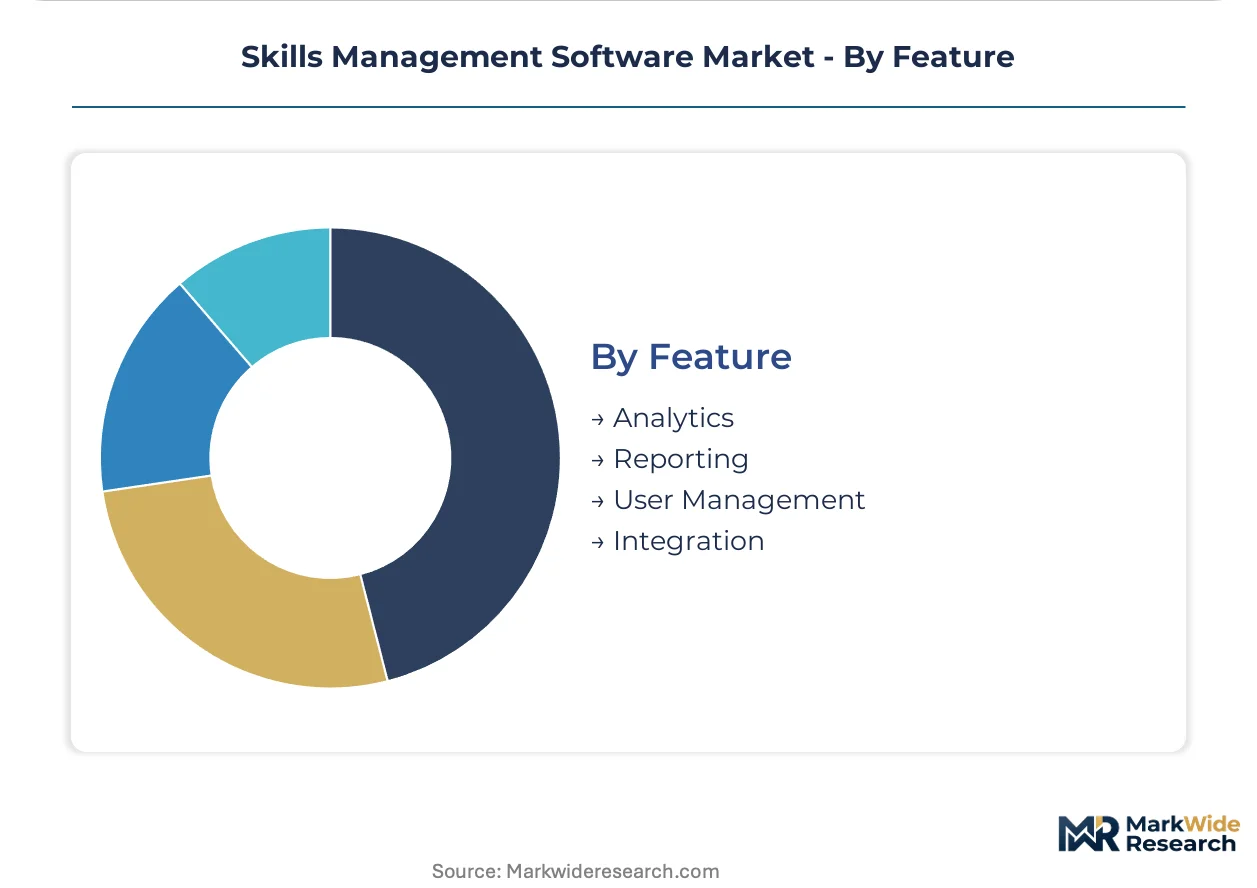
- Integration:API ecosystems and pre-built connectors to SAP, Workday, and Oracle HCM determine implementation success. Manufacturing employers in Germany prioritize shop-floor system interoperability for real-time skills verification.
- Analytics:Predictive models forecast certification expiration cascades and project staffing risks. These capabilities command premium pricing in safety-critical industries.
- Reporting:Configurable dashboards satisfy OSHA, FDA, and EMA audit documentation requirements without manual compilation.
- User Management:Role-based access controls and multi-factor authentication protect sensitive competency records in government and healthcare deployments.
Adoption depth centers on Integration; capability investment is gaining share fastest in Analytics as generative AI compresses insight generation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in the United States and Germany while consumption spreads across industrialized economies seeking workforce modernization. Cloud infrastructure investments in North America and Europe outpace deployment capacity in emerging markets, creating a supply-demand asymmetry that shapes vendor expansion priorities.
United States
Healthcare systems and technology firms drive platform adoption as HIPAA compliance mandates auditable skills documentation. The Department of Labor's apprenticeship modernization programs accelerate manufacturing sector procurement. Dallas-Fort Worth and Austin tech corridors host implementation centers serving Fortune 500 workforce transformation initiatives.
Germany
Automotive and chemical producers deploy shop-floor verification systems to satisfy OSHA-equivalent safety protocols under the Arbeitsschutzgesetz. EU AI Act algorithmic transparency requirements force architectural investments from domestic vendors. Stuttgart and Wolfsburg manufacturing clusters prioritize real-time skills matrices for assembly line safety-critical role assignments.
Japan
Government subsidies through METI's Digital Talent Initiative create procurement windows for JIS-compliant taxonomy support. Aging workforce demographics intensify reskilling urgency across precision manufacturing. Osaka and Nagoya industrial belts integrate skills platforms with legacy shop-floor control systems for seamless certification tracking.
India
Electronics and pharmaceutical producers under the PLI scheme must demonstrate certified workforce capabilities to maintain incentive eligibility. CDSCO regulatory documentation requirements extend to manufacturing personnel qualification records. Bengaluru and Hyderabad technology corridors adopt cloud-native platforms for rapid scaling of engineering talent pools.
United Kingdom
Financial services regulators emphasize demonstrable competency frameworks for risk management roles under Prudential Regulation Authority guidelines. Post-Brexit data residency considerations influence vendor selection for multinational headquarters. London's fintech and insurance clusters demand API-connected skills verification for regulatory audit preparedness.
Skills Management Software Market Competitive Landscape
Top-tier vendors anchor enterprise accounts through deep ERP integration, while mid-market specialists capture modular procurement with compliance-focused point solutions. The vendor base stratifies across three tiers: full-suite HCM platforms, industrial safety specialists, and API-native assessment tools. Strategic moves center on unbundling pressure responses and generative AI capability investments.
Within the ERP-integrated tier, SAP SuccessFactors and Workday occupy positions exemplifying deep enterprise system anchoring. AG5 represents the industrial specialization archetype with shop-floor compliance focus. Lattice sits within the modular talent management segment addressing mid-market subscription preferences. These three anchors illustrate the competitive divergence between horizontal platform breadth and vertical depth.
| Leading Market Players |
|---|
| Workday |
| AG5 |
| SkillPanel |
| iMocha |
| SumTotal |
| SAP SuccessFactors |
| Skills Base |
| Lattice |
| Oracle HCM Cloud |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up cloud infrastructure providers anchor supply behavior across the skills management software value chain, concentrating pricing power with hyperscale data center operators while compressing margins for mid-tier SaaS vendors unable to negotiate volume commitments.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects unbundling pressure from healthcare and manufacturing buyers seeking modular point solutions rather than integrated suites. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity and compliance certification grade, with GDPR and HIPAA-certified deployments commanding substantial premiums over baseline cloud offerings. Cost compression in standard tiers accelerates because subscription fatigue drives procurement toward API-only licensing with stripped-down professional services. Government and defense buyers exhibit lowest price sensitivity due to audit trail mandates, while small enterprises face acute budget constraints favoring per-seat self-service models.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure concentrated in the United States, Ireland, and Germany, where AWS, Azure, and GCP data center investments dominate multi-tenant hosting capacity for skills platform vendors. Software development draws from specialized AI ethics governance talent pools, API middleware engineering clusters, and legacy ERP integration specialists concentrated in Stuttgart, Dallas-Fort Worth, and Bengaluru. Tariff exposure on cross-border data transmission services threatens cost structures for vendors serving multinational deployments with jurisdictional residency requirements. Distribution runs through direct enterprise sales organizations for large accounts and cloud marketplace listings for mid-market self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance costs are forcing architectural consolidation, eliminating subscale vendors unable to fund six-figure algorithmic conformity assessments and creating acquisition opportunities for well-capitalized platforms.
For Market Incumbents: Lock in large-account retention through deep ERP integration investments that extend replacement cycles for SAP and Oracle HCM customers. Prioritize explainability dashboard development to satisfy EU AI Act Article 10 audit trail mandates in French and Dutch industrial deployments. Vertical integration into specialized AI ethics governance talent acquisition addresses the capability scarcity slowing automated skills-matching roadmap execution. For New Entrants and Emerging Players: Mid-market healthcare systems in North America present the most penetrable white-space target, as these buyers fragment procurement into modular skills verification APIs separate from workforce planning suites. India's PLI scheme electronics manufacturers offer second-mover advantages for JIS-compliant taxonomy platforms localized to CDSCO regulatory documentation requirements. A channel partnership strategy with existing LMS providers accelerates go-to-market velocity without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor industrial safety specialists with shop-floor compliance focus in German manufacturing clusters, where automotive and chemical producers prioritize real-time skills matrices for OSHA-equivalent liability reduction. Long-term viability hinges on generative AI competency extraction capabilities that compress skills inventory cycles from quarterly to real-time. Watch for EU AI Act enforcement actions against non-compliant vendors as the inflection indicator for accelerated consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP connectivity to SAP and Workday anchors renewal rates in Fortune 500 accounts. |
| Acquisition of Specialist Firm | Industrial safety compliance capabilities address shop-floor verification gaps in German automotive clusters. |
| Geographic Expansion | Localized deployments in India capture PLI scheme procurement windows for certified workforce demonstration. |
| Product Launch | Explainability dashboards satisfy EU AI Act Article 10 human-in-the-loop mandates for high-stakes staffing algorithms. |
| Strategic Partnership | LMS API ecosystems eliminate manual certification tracking in aviation and healthcare compliance environments. |
Research Methodology
Multi-period observation of vendor certification timelines, procurement cycle durations, and cloud deployment ratios anchored the trend analysis, supplemented by interviews with CTOs at North American healthcare systems, HR technology procurement officers at German automotive manufacturers, platform engineers specializing in ERP middleware, and integration specialists serving Japanese precision manufacturing. Secondary validation drew from SEC filings of publicly traded HCM vendors, hyperscaler capex disclosures revealing data center expansion patterns, EU AI Act regulatory guidance documents, and CDSCO manufacturing personnel qualification standards. Bottom-up deployment volume estimates triangulated against top-down enterprise software spending forecasts.
Segment-weighting approaches modeled deployment architecture, organizational scale, functional solution modules, and technical feature capabilities across the analysis window. CAGRs were derived from cohort-based growth trajectory analysis incorporating cloud migration velocity, regulatory compliance investment cycles, and workforce planning module adoption patterns. Industry-specific forecast inputs included METI Digital Talent Initiative subsidy disbursement rates and PLI scheme certification mandate enforcement intensity.
Revisions become necessary when EU AI Act enforcement timelines accelerate, hyperscale cloud infrastructure concentration triggers regulatory intervention, or generative AI competency extraction capabilities commoditize faster than projected. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Catalog Management Software Market
Software & Services
Course Authoring Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Quality Management Software Market
Software & Services
IT Services Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Petcare Software Market
Software & Services
Global Call Center Software Market
Software & Services
Stock Footage Software Market
Software & Services
Servicenow Tech Services Market
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Load Balancing Software Market
Software & Services
Urban Planning Software and Services Market
Software & Services
Business Activity Monitoring Software (BAM) Market