
 Urban Planning Software and Services Market | 2026-2036
Urban Planning Software and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Urban Planning Software and Services Market Intelligence
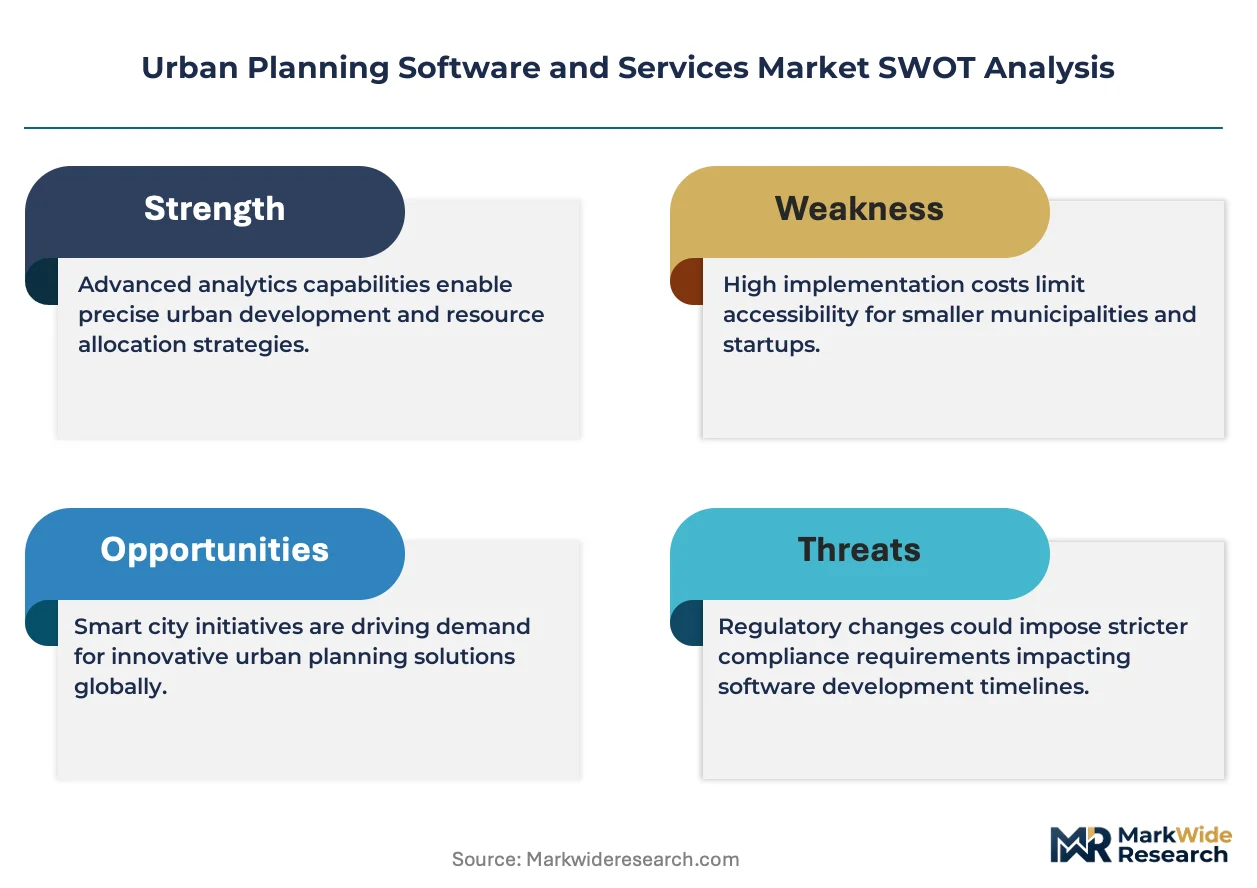
The capital-intensity divergence between legacy on-premise providers and cloud-native entrants is unwinding competitive assumptions across the sector. Autodesk leverages its design software heritage to anchor municipal accounts with bundled BIM-to-planning workflows. Esri dominates geospatial intelligence with proprietary spatial analytics engines that control the data layer for regional transportation authorities. Bentley Systems differentiates through infrastructure engineering depth, sustaining long-cycle engagements with state-level departments managing highway and utility corridors.
Urban Planning Software and Services encompasses digital platforms and professional services that enable spatial analysis, land-use modeling, infrastructure simulation, and stakeholder collaboration for built-environment decision-making. Core systems integrate GIS engines with demographic projection algorithms, 3D rendering pipelines, and real-time sensor feeds to optimize zoning, transportation networks, and environmental compliance. GIS Software and Simulation Tools represent the mature revenue base where government procurement cycles and federal grant dependencies shape margin predictability. Cloud-Based deployment is the fastest-expanding configuration as municipal IT departments retire legacy server farms and adopt subscription pricing for geospatial workloads. Consulting Services within the service-type dimension captures premium value where specialized firms embed climate-risk modeling and equity-impact analysis into master-planning engagements.
EPA emissions reporting requirements and FERC infrastructure permitting timelines in the United States compress planning cycles and force software upgrades that integrate regulatory compliance modules. The EU Green Deal and CSRD disclosure standards in Europe mandate granular carbon-footprint tracking for urban developments, redirecting procurement toward platforms with embedded sustainability dashboards. Stakeholders must monitor how emerging building-performance standards in multiple jurisdictions reshape the feature roadmap for simulation tools and whether vendor consolidation around cloud-native architectures alters pricing leverage for mid-sized municipal buyers.
Market Dynamics
Municipal IT departments are retiring legacy server infrastructure and migrating geospatial workloads to cloud-native architectures, compressing procurement cycles from multi-year capital commitments to annual subscription renewals. This shift restructures vendor relationships and pricing power across the sector.
Growth Catalysts
- EPA emissions mandates:Municipalities in the United States accelerate software procurement to embed carbon-footprint tracking into zoning and transportation planning workflows.
- Smart city infrastructure:Real-time demographic simulation platforms enable regional authorities to model population displacement and service demand before construction breaks ground.
- EU CSRD disclosure standards:European urban developers must document granular environmental impact data, redirecting procurement toward platforms with integrated sustainability dashboards.
Market Restraints
- Legacy system lock-in:Decades of accumulated spatial data in proprietary formats create migration friction and switching costs for established municipal accounts.
- Federal grant dependency:Budget cycles tied to infrastructure appropriations in the United States introduce revenue unpredictability for software vendors serving public-sector clients.
- Technical talent scarcity:Shortages of geospatial data scientists and BIM specialists constrain implementation velocity for complex master-planning engagements.
Strategic Opportunities
- Climate-risk modeling services:Specialized consulting firms embed flood-plain simulation and heat-island analysis into equity-focused master-planning contracts.
- India urbanization wave:Smart Cities Mission funding drives demand for integrated GIS platforms across tier-2 and tier-3 municipal corporations.
- Digital twin convergence:Real-time sensor feeds fused with 3D rendering pipelines enable continuous infrastructure performance monitoring for transportation authorities.
Industry Challenges
- Interoperability fragmentation:Proprietary spatial analytics engines resist data exchange with competing platforms, complicating multi-jurisdictional planning coordination.
- Cybersecurity certification delays:FedRAMP and equivalent state-level compliance timelines extend sales cycles for cloud-based deployments in government accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urban Planning Software and Services Market |
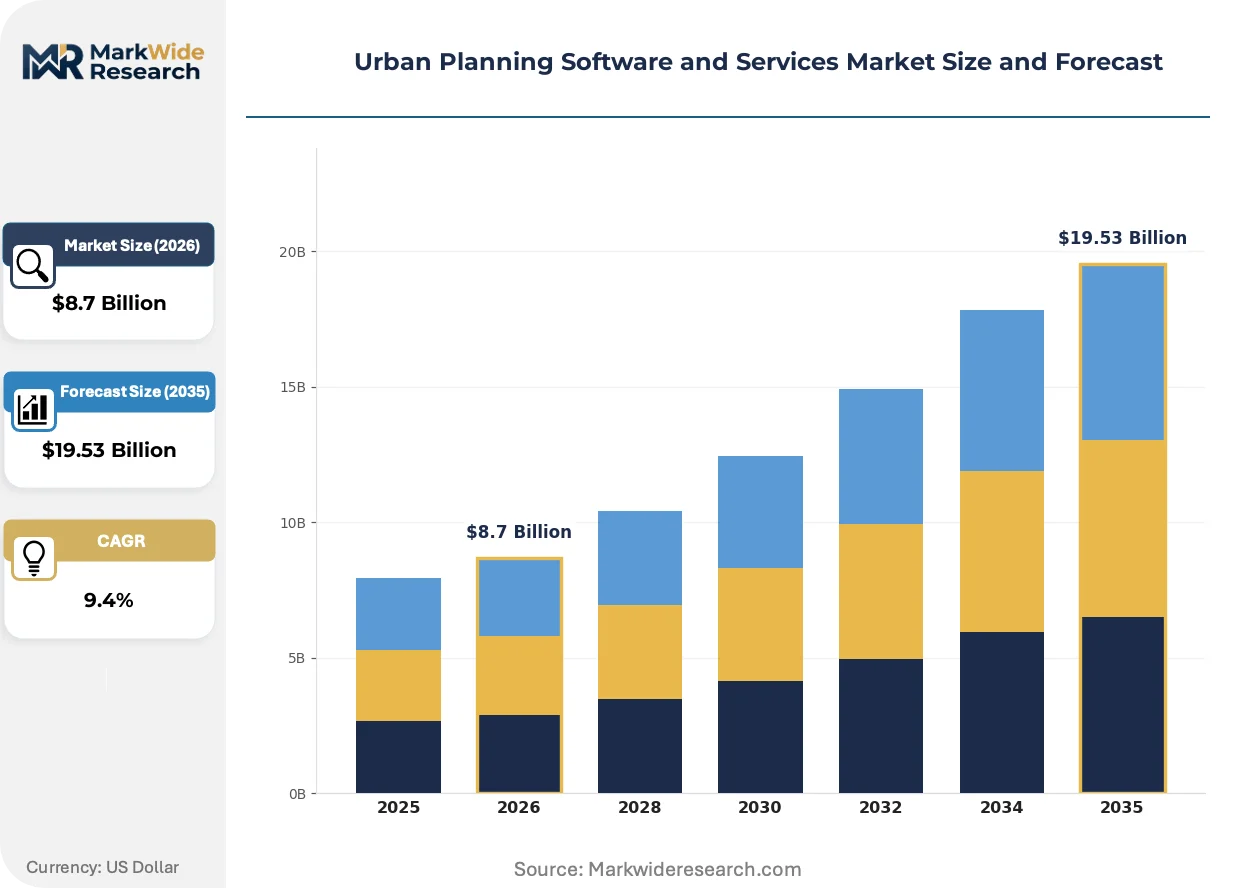
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GIS Software, Simulation Tools, Project Management Solutions, Data Analysis Tools End User: Government Agencies, Real Estate Developers, Urban Designers, Environmental Consultants Deployment: Cloud-Based, On-Premise, Hybrid Solutions, Mobile Platforms Service Type: Consulting Services, Custom Development, Training Programs, Support Services |
| Companies Covered | Autodesk Inc., Esri, Bentley Systems, AECOM, Trimble Inc., Hexagon AB, Stantec, UrbanFootprint, CityCAD Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urban Planning Software and Services Market Strategic Shifts & Innovations
Generative AI is penetrating spatial analysis workflows, automating scenario generation and compressing the time required for stakeholder visualization. This technological infusion is restructuring how planning departments allocate technical staff time.
Cloud-native GIS architectures are supplanting on-premise server farms as the default deployment model for municipal geospatial workloads. Mid-sized cities in the United States and Germany are completing migrations within 18-month windows. The shift enables real-time collaboration between planning departments and external engineering consultants without VPN bottlenecks.
The EU Green Deal and its implementing regulations mandate granular carbon-footprint disclosure for urban developments above threshold sizes. Planning software vendors must embed emissions calculation modules directly into simulation tools or risk disqualification from public tenders. French and Dutch municipalities have emerged as early adopters, requiring sustainability dashboards in all master-planning software evaluations.
Municipal procurement teams are consolidating vendor relationships and demanding bundled BIM-to-planning workflows rather than point solutions. Engineering departments in Canada and Australia now specify integrated design-to-analysis platforms in RFPs. This bundling pressure favors incumbent providers with broad product portfolios and squeezes specialized GIS vendors into niche applications.
Urban Planning Software and Services Market Segmentation
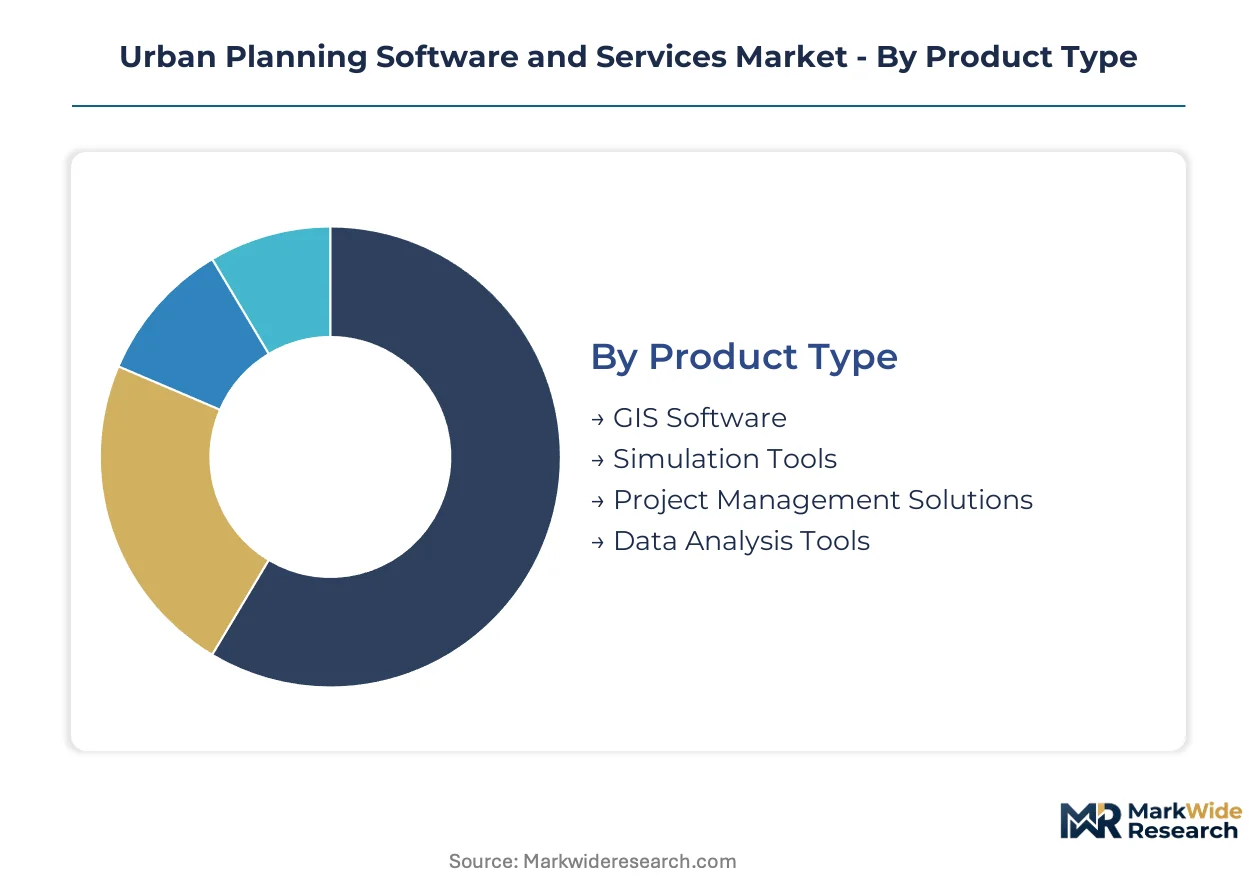
Segmentation in urban planning software reveals how procurement priorities diverge between legacy infrastructure replacement and cloud-native capability acquisition. Municipal buyers structure RFPs around deployment architecture and service integration depth rather than point-solution functionality alone.
Product Type:
GIS Software dominates export-led procurement from North American and European vendors serving Asian municipal markets. Simulation Tools concentrate domestically where specialized climate-risk modeling firms embed proprietary algorithms into regional planning contracts.
- GIS Software:Core spatial analytics engines process cadastral data, transportation networks, and zoning overlays through proprietary rendering pipelines. Municipal governments in Germany and the United States anchor demand as they modernize legacy ArcGIS deployments and comply with granular EPA emissions mapping requirements.
- Simulation Tools:Demographic projection and infrastructure performance modeling systems integrate real-time sensor feeds with 3D visualization capabilities. Demand clusters in flood-prone coastal regions of the Netherlands and Florida where authorities must model population displacement scenarios before construction authorization.
- Project Management Solutions:Workflow orchestration platforms coordinate multi-stakeholder master-planning engagements across extended timelines.
- Data Analysis Tools:Statistical processing modules extract planning insights from heterogeneous municipal datasets including census tracts and utility records.
GIS Software commands the established base. The steepest expansion runs through Simulation Tools.
End User:
Cost tier stratification separates enterprise-grade municipal deployments from mid-market consultant subscriptions. Government Agencies occupy premium pricing bands with multi-year bundled contracts. Environmental Consultants operate at lower per-seat costs with project-based licensing.
- Government Agencies:Federal, state, and municipal planning departments procure integrated platforms through formal RFP processes with FedRAMP or equivalent cybersecurity certification requirements. Procurement in the United States accelerates under EPA emissions reporting mandates and FERC infrastructure permitting timelines.
- Real Estate Developers:Private sector users leverage planning software for entitlement risk assessment and investor presentation materials. Demand concentrates in high-growth metropolitan corridors of Texas and Florida where development volume outpaces staff analytical capacity.
- Urban Designers:Boutique firms require visualization-heavy tools for stakeholder engagement and design competition submissions.
- Environmental Consultants:Specialized practices embed climate-risk and equity-impact analysis into master-planning deliverables for public-sector clients.
Government Agencies represent the revenue anchor. Real Estate Developers are gaining share fastest.
Deployment:
Application criticality determines architecture selection. Continuous monitoring systems for transportation networks demand cloud elasticity. Sensitive critical infrastructure data in defense-adjacent jurisdictions remains on-premise.
- Cloud-Based:Subscription-accessible platforms enable real-time collaboration between dispersed planning departments and external engineering consultants without VPN bottlenecks. Mid-sized cities in the United States and Germany complete migrations within 18-month procurement windows.
- On-Premise:Self-hosted installations persist where classified or sensitive spatial data requires air-gapped security environments. State-level departments managing highway and utility corridors in security-sensitive regions maintain captive server infrastructure.
- Hybrid Solutions:Split architectures process public demographic data in cloud environments while retaining proprietary cadastral records locally.
- Mobile Platforms:Field-accessible inspection and citizen engagement applications extend core platform functionality to non-desktop workflows.
On-Premise retains the legacy installed base. Cloud-Based shows the steepest adoption trajectory.
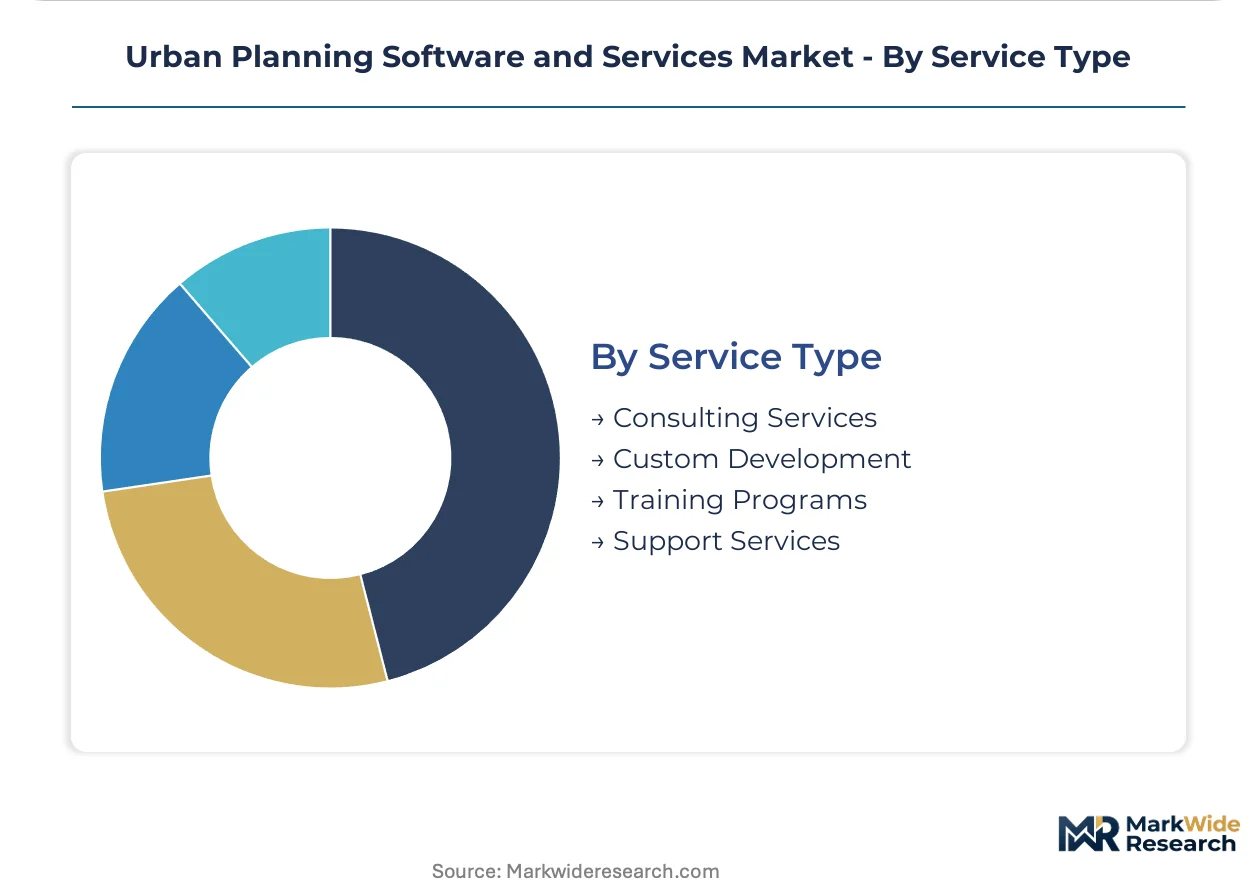
Service Type:
Customer maturity shapes service mix. Established municipal accounts with internal GIS teams minimize consulting dependency. New cloud adopters require implementation support and change management.
- Consulting Services:Specialized firms embed flood-plain simulation, heat-island analysis, and equity-impact assessment into climate-focused master-planning contracts. Premium engagements in the Netherlands and Denmark support EU Green Deal compliance documentation.
- Custom Development:Bespoke module creation extends standard platforms to jurisdiction-specific regulatory workflows and data integration requirements.
- Training Programs:Certification courses address technical talent scarcity by upskilling municipal staff in geospatial data science and BIM coordination.
- Support Services:Tiered maintenance contracts ensure platform availability and regulatory update compatibility for risk-averse public-sector buyers.
Support Services underpins recurring revenue. Consulting Services delivers the highest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage concentrates in German and Dutch municipal procurement offices where EU Green Deal compliance mandates create premium tolerance, while Indian tier-2 cities negotiate aggressively on per-seat costs despite Smart Cities Mission subsidies.
United States
EPA emissions reporting requirements and FERC infrastructure permitting timelines compress planning cycles and force software upgrades. Federal grant dependencies tied to infrastructure appropriations introduce revenue unpredictability for vendors. Procurement clusters in California, Texas, and Florida where metropolitan planning organizations model population displacement scenarios.
Germany
Mid-sized cities complete cloud-native GIS migrations within 18-month windows as municipal IT departments retire legacy server infrastructure. CSRD disclosure standards mandate granular carbon-footprint tracking for urban developments above threshold sizes. The Rhine-Ruhr and Munich metropolitan regions anchor demand for integrated BIM-to-planning workflows.
Netherlands
Flood-prone coastal authorities require simulation tools that model population displacement before construction authorization. EU Green Deal implementing regulations redirect procurement toward platforms with embedded sustainability dashboards. Amsterdam and Rotterdam municipal corporations specify climate-risk modeling capabilities in all master-planning software evaluations.
India
Smart Cities Mission funding drives demand for integrated GIS platforms across tier-2 and tier-3 municipal corporations. Technical talent scarcity constrains implementation velocity for complex engagements. Hyderabad, Pune, and Indore emerge as early adopters of cloud-based demographic simulation platforms.
United Kingdom
Engineering departments specify integrated design-to-analysis platforms in RFPs rather than point solutions. Cybersecurity certification timelines extend sales cycles for cloud-based deployments in government accounts. London and Greater Manchester planning authorities consolidate vendor relationships around bundled workflows.
Urban Planning Software and Services Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the sector, creating a tiered competitive structure where geospatial intelligence specialists, design software heritage providers, and infrastructure engineering depth players occupy distinct positioning bands. The market consolidates around three strategic archetypes: cloud-native platform builders, legacy on-premise incumbents with migration services, and specialized climate-risk consulting boutiques. Dominant competitive moves include portfolio diversification through bundled BIM-to-planning workflows and geographic expansion into Indian Smart Cities Mission procurement channels.
Within the geospatial intelligence tier, Esri anchors proprietary spatial analytics capabilities that control data layers for regional transportation authorities. Autodesk Inc. exemplifies the design software heritage archetype, leveraging bundled workflows to anchor municipal accounts. Bentley Systems occupies a position within infrastructure engineering depth, sustaining long-cycle engagements with state-level departments managing highway and utility corridors.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Esri |
| Bentley Systems |
| AECOM |
| Trimble Inc. |
| Hexagon AB |
| Stantec |
| UrbanFootprint |
| CityCAD Technologies |
| Others |
Cost & Logistics Intelligence
Eighteen-month procurement windows for cloud-native GIS migrations compress vendor negotiation timelines and concentrate pricing power with municipal IT departments capable of consolidated platform purchases. This lead-time compression rewards software vendors with FedRAMP-ready architectures while squeezing margins for legacy on-premise providers facing forced retirement cycles.
Pricing Analysis
Configured-to-order pricing for bespoke climate-risk modeling modules commands spreads of three to five times standard SaaS tiers across municipal master-planning contracts. Subscription-based SaaS tiers dominate government procurement, with price differentiation anchored in FedRAMP certification level and embedded sustainability dashboard depth. Pricing pressure stems from bundled BIM-to-planning RFP specifications that force point-solution vendors into concessionary positioning. Mid-sized municipal corporations in Germany and the United States exhibit highest price sensitivity, while Dutch flood-management authorities tolerate premium positioning for population-displacement simulation capabilities.
Supply Chain Analysis
The United States and Germany anchor cloud infrastructure provisioning for municipal geospatial workloads, while India supplies tier-2 implementation talent for Smart Cities Mission deployments. Proprietary spatial analytics engines draw from cadastral data feeds, real-time sensor networks, and demographic projection datasets. Single-source vulnerability concentrates in Esri's proprietary rendering pipelines that control regional transportation authority data layers. Distribution runs through direct enterprise sales teams for government agencies and value-added resellers serving environmental consulting boutiques.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring competitive boundaries as municipal procurement teams demand interoperability between GIS engines and BIM workflows, collapsing the historical separation between geospatial intelligence and design software ecosystems.
For Market Incumbents: Secure long-cycle engagements with state-level highway departments through captive infrastructure engineering depth, insulating against Autodesk's bundled workflow encroachment. Deepen backward integration into real-time sensor feed networks to anchor continuous monitoring contracts for transportation authorities. Prioritize FedRAMP Moderate certification investments to compress sales cycles in federal procurement channels. For New Entrants and Emerging Players: Differentiate on climate-risk modeling specialization for EU Green Deal compliance documentation, where incumbent platforms lack embedded flood-plain simulation depth. Target tier-2 Indian municipal corporations underserved by legacy vendor implementation capacity. Pursue white-label partnerships with established environmental consulting firms to bypass direct procurement friction. For Investors and Strategic Acquirers: Long-term, this sits as a vertical software consolidation play because bundled workflow demands are compressing point-solution viability windows. Acquisition targets should exhibit proprietary spatial analytics engines with transportation authority data layer control. Monitor EPA emissions mandate enforcement intensity as inflection indicator for compliance-module procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Autodesk's BIM-to-planning bundling anchors municipal accounts against Esri's geospatial dominance. |
| Geographic Expansion | Smart Cities Mission procurement channels in Hyderabad and Pune unlock tier-2 municipal demand. |
| Acquisition of Specialist Firm | Climate-risk modeling boutiques with Dutch flood-plain expertise command premium consulting margins. |
| Product Launch | Generative AI scenario-generation modules compress stakeholder visualization timelines for planning departments. |
| Strategic Partnership | Real-time sensor network alliances enable digital twin convergence for continuous infrastructure monitoring. |
Research Approach
Desk research of EPA emissions guidance documents, EU CSRD implementing regulations, and Smart Cities Mission procurement databases preceded structured interviews with municipal CIOs, regional transportation authority planning directors, environmental consulting firm partners, and geospatial data science team leads. Primary intelligence combined with secondary validation from vendor SEC filings, municipal RFP archives, and federal grant appropriation records. Bottom-up segment sizing triangulated against top-down market construction across deployment models and service types.
Variance decomposition across product type, end user, deployment architecture, and service integration depth structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro drivers including regulatory mandate enforcement timelines and cloud migration completion curves. Modeled inputs incorporated federal infrastructure appropriation volatility and technical talent scarcity constraints on implementation velocity.
Decision-makers should treat outputs as directional under assumptions of sustained EPA emissions reporting requirements and EU Green Deal regulatory continuity; material deviation in mandate enforcement intensity or federal grant funding levels would warrant model refresh. Recalibration cycles align with material shifts in municipal cloud procurement velocity and cybersecurity certification timeline compressions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Europe Business Software Market
Software & Services
Chromatography Data System (CDS) Software Market
Software & Services
Test Management Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Remote Desktop Software Market
Software & Services
Small Business Marketing Software Market
Software & Services
Global Auto Dealer Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
Sales Performance Management (SPM) Software Market
Software & Services
Admission Management Software Market
Software & Services
Attendance Management Software Market
Software & Services
LTFS Copy Software Market
Software & Services
Global ERP Software Market
Software & Services
Aviation Software Market
Software & Services
Middle East and Africa Automotive Software Market
Software & Services
Lab Automation Software Market