
 Global Pharmaceutical Manufacturing Software Market | 2026-2036
Global Pharmaceutical Manufacturing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Manufacturing Software Market Foresight
India's pharmaceutical corridor from Hyderabad to Ahmedabad is reconfiguring how contract manufacturers select enterprise software platforms. Siemens Healthineers anchors its position through manufacturing execution system specialization for sterile injectable lines. Oracle competes by extending cloud infrastructure across multi-site quality management deployments. SAP leverages deep ERP integration to control procurement-to-batch-release workflows for generic drugmakers.
Pharmaceutical manufacturing software encompasses validated digital systems that orchestrate recipe management, electronic batch records, equipment interfaces, and real-time process analytics within regulated drug production environments. These platforms enforce data integrity through audit trails, electronic signatures, and alarm management protocols that satisfy FDA 21 CFR Part 11 and EMA GMP Annex 11 requirements. Cloud-based deployment is capturing the fastest expansion as biotech companies prioritize scalable infrastructure without capital-intensive on-premise validation. Manufacturing execution systems occupy the deepest margin pools due to their direct integration with shop-floor instrumentation and regulatory documentation workflows. Enterprise resource planning retains structural importance for financial traceability across multi-currency API sourcing networks.
The FDA, EMA, and India's CDSCO collectively shape software procurement through divergent inspection protocols and data localization expectations. FDA warning letters for data integrity violations directly accelerate replacement cycles for legacy batch recording systems. Stakeholders must monitor how the EU AI Act's risk classification framework applies to machine learning modules embedded in process analytics platforms.
Market Dynamics
Cloud-native validation protocols are compressing deployment timelines for manufacturing execution systems, forcing incumbent vendors to re-architect legacy codebases while biotech startups bypass on-premise infrastructure entirely.
Growth Catalysts
- FDA 21 CFR Part 11 enforcement:Warning letters for data integrity violations trigger immediate replacement cycles for paper-based batch recording systems across sterile injectable facilities.
- Continuous manufacturing adoption:Real-time release testing requirements drive demand for process analytical technology integration within oral solid dosage lines.
- Hyderabad-Ahmedabad corridor expansion:Indian contract manufacturers prioritize multi-site ERP deployments to synchronize API sourcing with finished dose production across state borders.
Market Restraints
- Validation cost concentration:Computer system validation for cloud platforms consumes 40-60% of total implementation budgets, favoring established vendors with pre-validated infrastructure.
- Specialized talent scarcity:Qualified validation engineers with FDA inspection experience command premium compensation, constraining mid-tier software vendors.
- Legacy system entrenchment:Pharmaceutical facilities operate 15-20 year depreciation cycles for validated equipment, creating friction against rip-and-replace strategies.
Strategic Opportunities
- Brazilian ANVISA digitization:Emerging market regulators are mandating electronic submission formats, opening whitespace for compliance-focused software localization.
- AI-enabled process control:Machine learning modules for predictive batch failure detection are penetrating upstream bioprocessing where sensor density supports training data requirements.
- Subscription pricing penetration:SaaS delivery models reduce capital barriers for emerging biotechs, expanding addressable market beyond large pharmaceutical incumbents.
Industry Challenges
- CSV talent pipeline gaps:Pharmaceutical manufacturers struggle to recruit computer system validation specialists capable of bridging IT infrastructure and GMP quality assurance functions.
- Multi-regulatory divergence:Software vendors must maintain parallel validation documentation for FDA, EMA, and CDSCO inspection protocols, inflating quality management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Manufacturing Software Market |
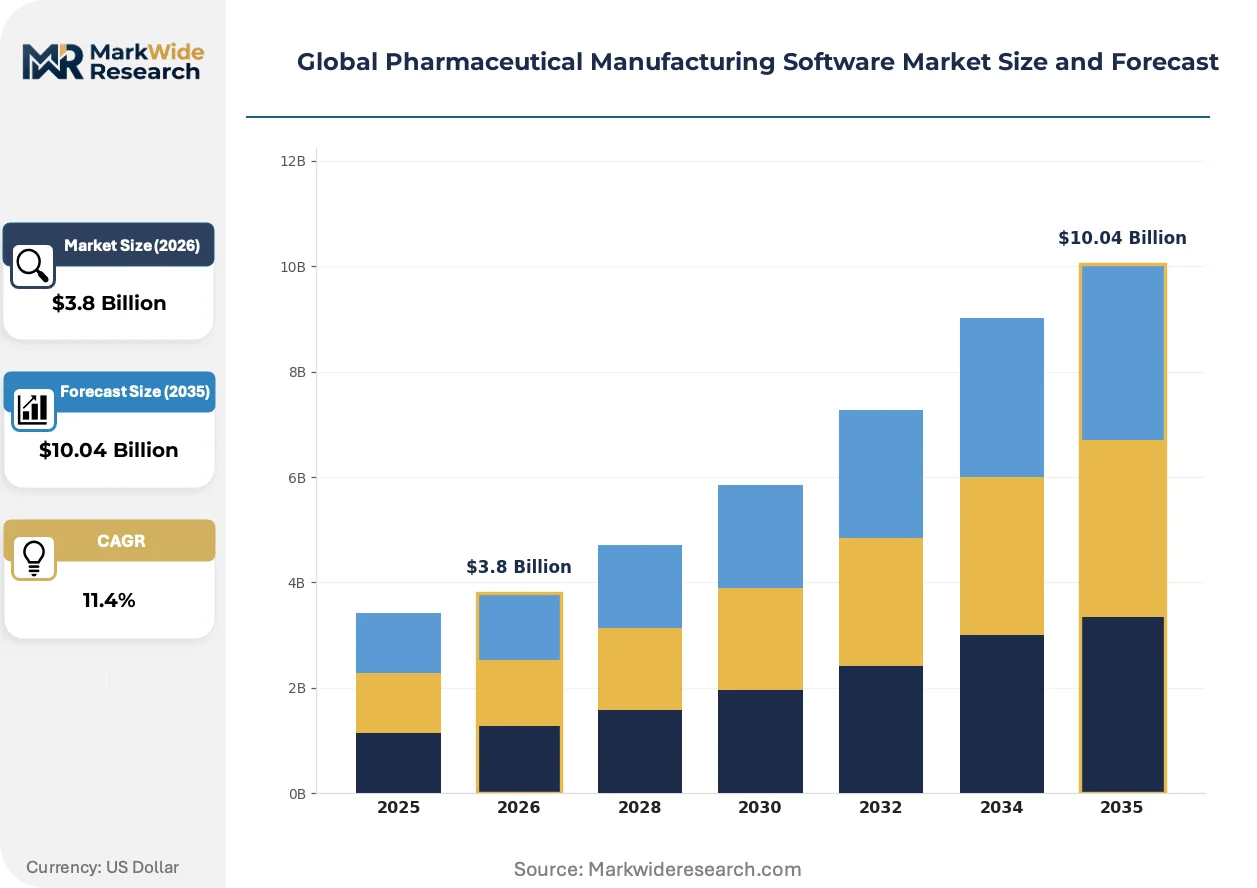
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Type: Quality Management, Manufacturing Execution System, Enterprise Resource Planning, Inventory Management, Regulatory Compliance Application: Batch Production, Continuous Manufacturing, Packaging Process, Supply Chain Optimization, Process Analytics End User: Contract Development, Biotech Companies, Generic Drugmakers, Research Laboratories, API Manufacturers |
| Companies Covered | Rockwell Automation, QT9 ERP, Oracle, Veeva Vault QMS, BatchMaster Software, SAP, MasterControl, Siemens Healthineers, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Manufacturing Software Market Shifts & Advancements
Digital twin architectures are migrating from conceptual pilots to production-grade deployments, compressing process development timelines while forcing vendors to integrate physics-based simulation with live manufacturing data streams.
Edge computing platforms for real-time batch analytics is migrating from on-premise server rooms to containerized micro-datacenters positioned adjacent to production lines. Biologics manufacturers with single-use bioreactor fleets are adopting these architectures fastest. The shift is migrating from capital-intensive centralized SCADA toward distributed intelligence that reduces latency for critical process parameter alarms.
EMA's Annex 11 revision emphasizes data integrity by design, compelling software vendors to embed audit trail functionality at the database layer rather than as configurable add-ons. This regulatory pressure is eliminating lightweight point solutions that lack native compliance architecture. European sterile manufacturers are responding by consolidating vendor relationships toward integrated MES-ERP platforms.
Buying committees for manufacturing software are expanding beyond IT directors to include quality assurance heads and regulatory affairs officers, extending sales cycles but reducing post-implementation rejection risk. This stakeholder expansion is most pronounced among CDMOs serving multiple sponsor companies with divergent quality agreements. German pharmaceutical clusters exhibit the most formalized multi-functional procurement protocols.
Global Pharmaceutical Manufacturing Software Market Segmentation
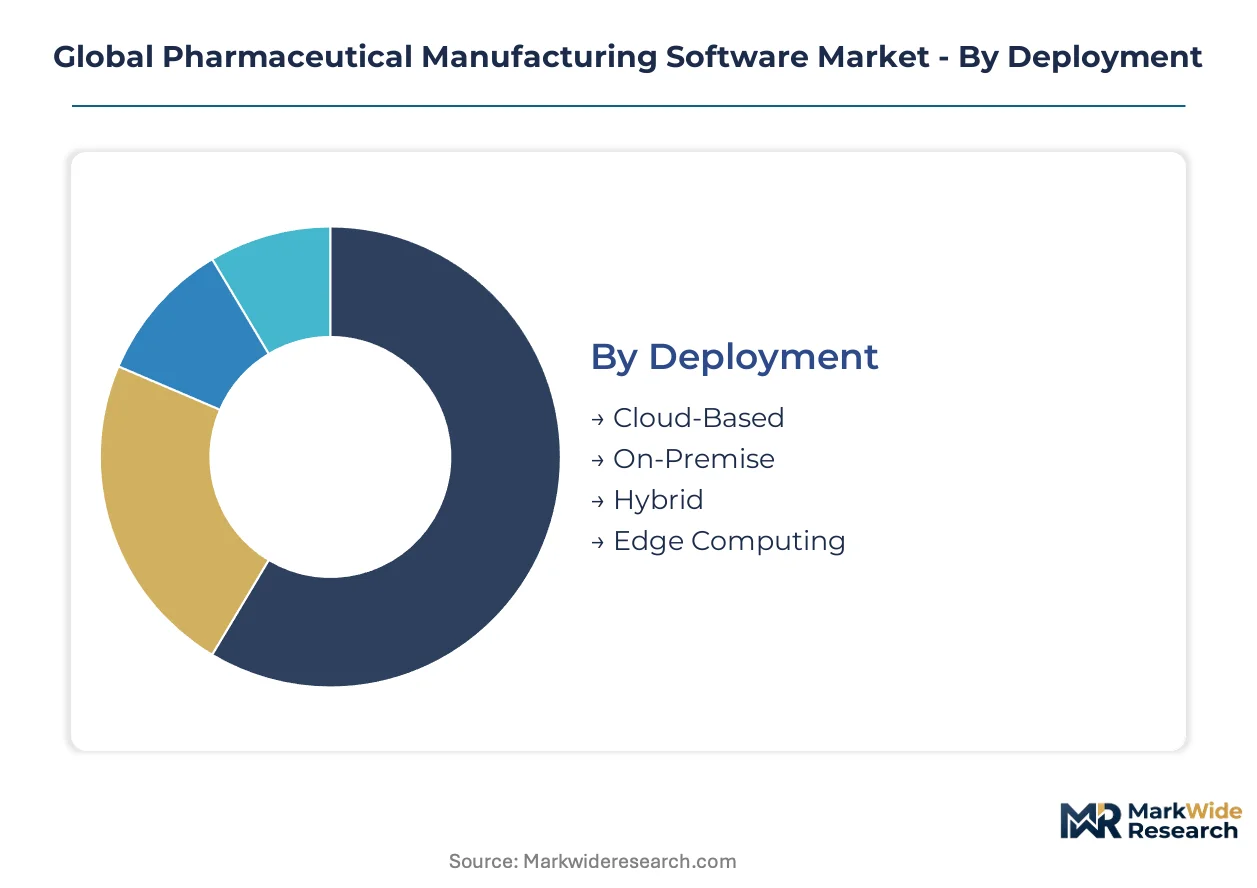
Deployment architecture determines validation burden and capital intensity for pharmaceutical software procurement. Solution type governs margin structure, with execution systems commanding premium pricing over planning modules. Application focus separates batch-oriented incumbents from continuous manufacturing pioneers.
Deployment:
Mature on-premise installations coexist with emerging edge-native architectures as biotechs bypass legacy infrastructure entirely.
- Cloud-Based:Multi-tenant SaaS platforms eliminate capital expenditure for validation infrastructure while accelerating FDA 21 CFR Part 11 compliance through pre-configured audit trails. Biotech startups in Boston and Basel deploy these systems fastest, prioritizing scalable infrastructure over depreciable assets.
- On-Premise:Validated server installations within facility firewalls maintain data sovereignty for highly sensitive biologics processes. Large sterile injectable manufacturers in North Carolina and Germany retain these deployments due to 15-20 year equipment depreciation cycles and conservative quality assurance protocols.
- Hybrid:Sensitive batch records reside on-premise while analytics workloads shift to cloud infrastructure. Contract manufacturers serving multiple sponsors favor this architecture to satisfy divergent data localization requirements.
- Edge Computing:Containerized micro-datacenters adjacent to production lines reduce latency for critical process parameter alarms. Single-use bioreactor fleets at Singapore biologics facilities adopt these architectures fastest.
On-premise deployments handle the majority of validated throughput; edge computing is gaining share fastest among new bioprocessing capacity.
Solution Type:
Cost tier stratification separates integrated suites from specialized point solutions with divergent implementation economics.
- Manufacturing Execution System:Shop-floor platforms orchestrate electronic batch records, equipment interfaces, and real-time process analytics with direct regulatory documentation integration. MES deployments in Hyderabad and Ahmedabad contract manufacturing corridors concentrate demand due to multi-site synchronization requirements.
- Quality Management:CAPA management, deviation tracking, and audit management modules enforce data integrity through closed-loop workflows. Generic drugmakers in India prioritize these systems to satisfy CDSCO inspection readiness.
- Enterprise Resource Planning:Financial traceability across multi-currency API sourcing networks retains structural importance for procurement-to-batch-release workflows. SAP-integrated deployments dominate among established pharmaceutical incumbents.
- Inventory Management:Serialized track-and-trace functionality supports drug authentication and anti-counterfeiting mandates. Brazilian ANVISA digitization requirements are accelerating localization investments.
- Regulatory Compliance:Pre-validated submission templates and inspection readiness dashboards reduce regulatory affairs overhead. EMA Annex 11 revisions are eliminating lightweight point solutions lacking native compliance architecture.
Manufacturing execution systems absorb the largest implementation budgets; regulatory compliance modules are expanding most quickly as inspection protocols tighten.
Application:
Volume concentration in batch production contrasts with margin expansion in continuous manufacturing adoption.
- Batch Production:Electronic batch recording systems manage recipe execution, material genealogy, and equipment cleaning validation for discrete manufacturing campaigns. Sterile injectable facilities across Massachusetts and Switzerland drive replacement cycles as FDA warning letters for data integrity violations accelerate system upgrades.
- Continuous Manufacturing:Real-time release testing platforms integrate process analytical technology for oral solid dosage lines. FDA quality assessment programs for continuous manufacturing submissions concentrate early adoption among innovative dosage form specialists.
- Packaging Process:Serialization and aggregation workflows support unit-level traceability through distribution networks. EU Falsified Medicines Directive enforcement maintains demand across European packaging operations.
- Supply Chain Optimization:Demand forecasting and distribution planning modules synchronize API sourcing with finished dose production. Indian manufacturers spanning Hyderabad to Ahmedabad prioritize multi-site ERP deployments for cross-border coordination.
- Process Analytics:Machine learning modules for predictive batch failure detection penetrate upstream bioprocessing where sensor density supports training data requirements. Biologics manufacturers with extensive single-use infrastructure lead adoption.
Batch production applications retain the dominant installed base; continuous manufacturing is climbing fastest as regulatory pathways mature.
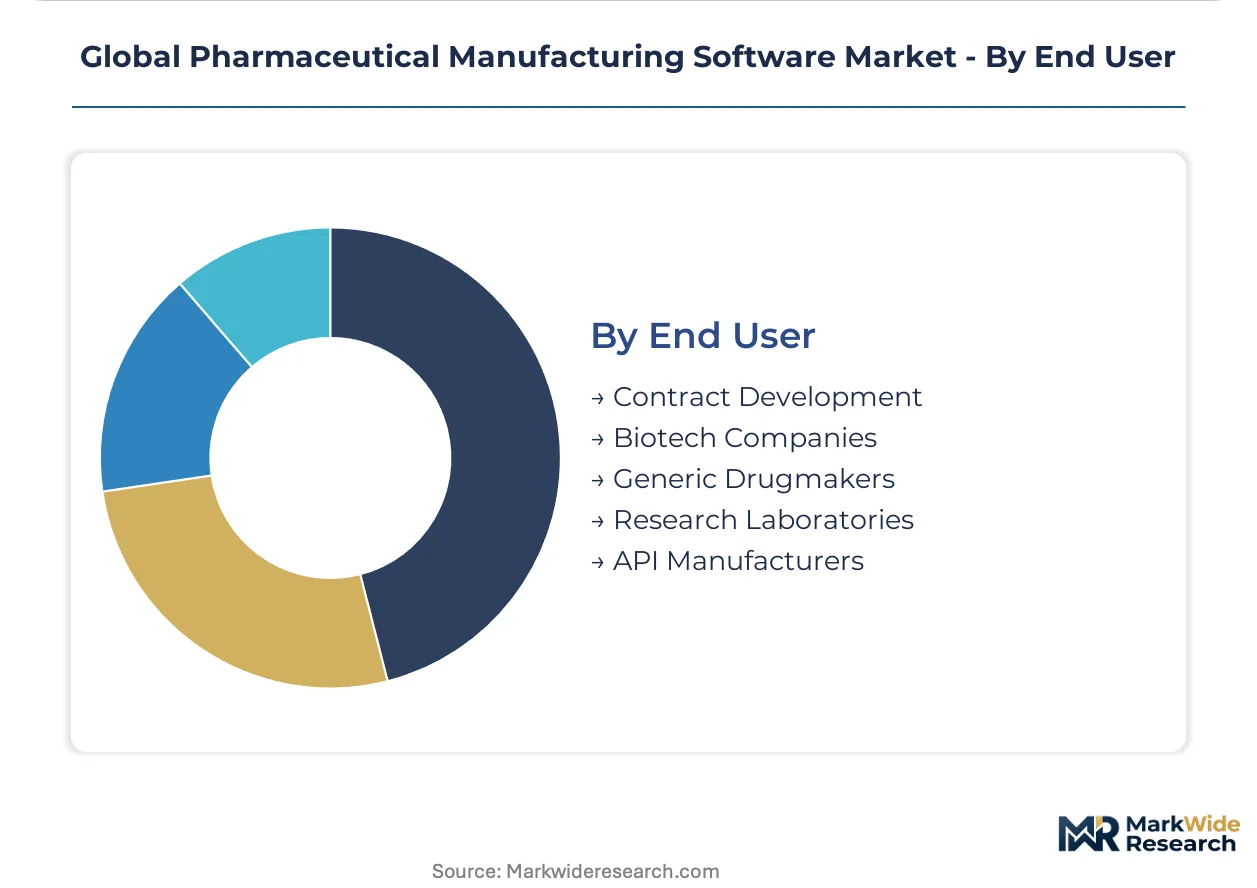
End User:
Customer type fragmentation separates capital-constrained emerging biotechs from depreciation-heavy established manufacturers.
- Biotech Companies:Venture-funded drug developers prioritize cloud-native validation protocols to compress deployment timelines and conserve capital for clinical programs. Massachusetts and San Francisco Bay Area clusters exhibit highest SaaS penetration.
- Contract Development:CDMOs serving multiple sponsor companies with divergent quality agreements require flexible multi-tenant platforms. German pharmaceutical clusters demonstrate the most formalized multi-functional procurement protocols including quality assurance and regulatory affairs stakeholders.
- Generic Drugmakers:Cost-pressured manufacturers leverage deep ERP integration to control procurement-to-batch-release workflows. Indian generic specialists dominate volume demand for standardized compliance modules.
- API Manufacturers:Active pharmaceutical ingredient producers require material genealogy tracking from starting materials through intermediates. Chinese and Indian API hubs drive demand for supply chain synchronization tools.
- Research Laboratories:Non-GMP development environments utilize scaled-down manufacturing execution functionality for process characterization and tech transfer preparation. Academic medical centers with integrated drug discovery programs represent a niche segment.
Generic drugmakers represent the largest addressable population; biotech companies are expanding most quickly as venture funding concentrates in platform therapeutics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of 21 CFR Part 11 data integrity requirements anchors demand concentration in the United States, where sterile injectable facilities drive replacement cycles for legacy batch recording systems. Software procurement patterns diverge sharply across regulatory jurisdictions, with validation protocols and data localization mandates reshaping vendor selection criteria.
United States
Massachusetts and North Carolina pharmaceutical clusters prioritize cloud-based manufacturing execution systems to compress deployment timelines for biotech startups. FDA warning letters for electronic record violations accelerate system upgrades across sterile injectable facilities. Greater Boston's venture-funded drug developers exhibit the highest SaaS penetration rates in regulated manufacturing software.
Germany
Baden-Württemberg and Bavaria pharmaceutical manufacturers favor integrated MES-ERP platforms following EMA Annex 11 revisions emphasizing data integrity by design. German clusters demonstrate the most formalized multi-functional procurement protocols, with quality assurance and regulatory affairs officers joining traditional IT buying committees. Siemens Healthineers anchors regional manufacturing execution system specialization.
India
The Hyderabad-Ahmedabad contract manufacturing corridor drives multi-site ERP deployments to synchronize API sourcing with finished dose production across state borders. CDSCO inspection readiness requirements concentrate demand for standardized compliance modules among generic drugmakers. Indian manufacturers prioritize procurement-to-batch-release workflow integration to satisfy divergent sponsor quality agreements.
Switzerland
Basel's biologics manufacturers adopt edge computing architectures fastest for single-use bioreactor fleet management. Swissmedic oversight of sterile manufacturing maintains stringent validation requirements favoring established vendors with pre-validated infrastructure. Containerized micro-datacenters adjacent to production lines reduce latency for critical process parameter alarms.
Brazil
ANVISA digitization mandates for electronic submission formats open whitespace for compliance-focused software localization investments. São Paulo pharmaceutical packaging operations drive serialized track-and-trace functionality adoption to support drug authentication requirements. Emerging market regulatory convergence creates demand for multi-jurisdictional validation documentation capabilities.
Global Pharmaceutical Manufacturing Software Market Competitive Landscape
Capability concentration sits with specialized manufacturing execution system vendors; scale advantage sits with diversified enterprise software incumbents. The vendor landscape stratifies across three tiers: integrated suite providers with deep ERP connectivity, pure-play MES specialists with shop-floor instrumentation expertise, and cloud-native challengers targeting capital-constrained biotechs. Dominant competitive moves include M&A to acquire validation-ready codebases and strategic partnerships to embed process analytical technology modules.
Within the integrated suite tier, Oracle and SAP occupy positions exemplifying divergent approaches to pharmaceutical workflow orchestration. Oracle extends cloud infrastructure across multi-site quality management deployments, while SAP leverages deep ERP integration to control procurement-to-batch-release workflows. Among specialized manufacturing execution system providers, Siemens Healthineers anchors sterile injectable line automation. Rockwell Automation represents the industrial automation conglomerate archetype, bridging process control hardware with regulatory-compliant software layers.
| Leading Market Players |
|---|
| Rockwell Automation |
| QT9 ERP |
| Oracle |
| Veeva Vault QMS |
| BatchMaster Software |
| SAP |
| MasterControl |
| Siemens Healthineers |
| Honeywell International |
| Others |
Supply & Pricing Matrix
The Hyderabad-Ahmedabad pharmaceutical corridor's logistics cost dynamics compress margin pools for contract manufacturers while amplifying price differentiation between cloud-native SaaS tiers and legacy on-premise installations. Supply concentration among Indian generic drugmakers and German sterile injectable specialists feeds downstream pricing power to established vendors with pre-validated infrastructure.
Pricing Analysis
Geographic price spreads between North American biotech clusters and Indian contract manufacturing corridors exceed three-to-one for equivalent manufacturing execution system functionality. Three-tier pricing structure across premium, standard, and economy levels segments by validation depth and regulatory jurisdiction coverage. Cost compression in the economy tier intensifies because mid-tier vendors lack FDA inspection-ready documentation libraries. Emerging biotechs in Massachusetts exhibit lowest price sensitivity due to venture-funded capital reserves; Indian generic drugmakers face acute sensitivity due to procurement-to-batch-release margin constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for pharmaceutical software vendors maintaining dual validation documentation streams. Development and quality assurance talent concentrates in India, Germany, and the United States, with Indian hubs feeding validation engineering capacity to global deployments. Raw material dependencies span qualified validation specialists, cloud infrastructure from hyperscalers, and legacy system integration expertise. Single-source vulnerability sits with FDA-experienced computer system validation engineers commanding premium compensation. Distribution runs through direct enterprise sales teams for large pharmaceutical incumbents and channel partners serving emerging biotechs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as cloud-native challengers displace legacy on-premise installations among capital-constrained drug developers. Incumbents must navigate the threat of biotech startups bypassing depreciable infrastructure entirely.
For Market Incumbents: Harden pre-validated infrastructure moats by embedding EMA Annex 11 revision requirements at the database layer rather than as configurable add-ons. Acquire validation-ready codebases from specialized regulatory compliance module vendors to compress computer system validation timelines. Vertical integration into edge computing hardware partnerships secures latency advantages for single-use bioreactor fleet management.
For New Entrants and Emerging Players: Brazilian ANVISA digitization mandates represent underpenetrated whitespace for compliance-focused software localization. Target São Paulo pharmaceutical packaging operations with serialized track-and-trace functionality supporting drug authentication requirements. Partner with established Indian contract manufacturers to embed multi-site ERP synchronization capabilities as the anchor go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial automation conglomerates seeking to monetize pharmaceutical-specialized software divisions. Long-term viability hinges on regulatory compliance module expansion as inspection protocols tighten across FDA, EMA, and CDSCO jurisdictions. Monitor FDA warning letter issuance rates for data integrity violations as the inflection indicator accelerating replacement cycle velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | MES-ERP unified deployments satisfy German multi-functional procurement protocols spanning quality assurance and regulatory affairs. |
| Acquisition of Specialist Firm | Validation-ready codebase purchases compress computer system validation timelines for cloud-native manufacturing execution systems. |
| Strategic Partnership | Process analytical technology module embedding enables real-time release testing for continuous manufacturing oral solid dosage lines. |
| Geographic Expansion | ANVISA compliance localization captures Brazilian electronic submission mandate whitespace in São Paulo packaging corridors. |
| Product Launch | Edge-native architectures reduce latency for critical process parameter alarms at Singapore single-use bioreactor facilities. |
Research Methodology
A spread of perspectives from manufacturing execution system vendors, pharmaceutical quality assurance directors, regulatory affairs officers, and CDSCO inspection readiness consultants converged on the working assumptions. Primary interviews with IT procurement leads at contract development organizations supplemented secondary validation against FDA warning letter databases, EMA Annex 11 revision drafts, and CDSCO compliance circulars. Bottom-up installation base modeling triangulated with top-down pharmaceutical capital expenditure disclosures across the analysis window.
Demand-supply-balance framing anchored the analytical framework across deployment architecture, solution type, application focus, and end-user segmentation dimensions. CAGRs derived from validated system replacement cycle velocity, cloud adoption curves among venture-funded biotechs, and continuous manufacturing regulatory pathway maturation. Forecast inputs incorporated FDA 21 CFR Part 11 enforcement intensity, EMA data integrity by design requirements, and Indian multi-site ERP synchronization demand patterns throughout the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native challengers or hyperscaler infrastructure entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Over the Air (OTA) Updates Market
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
Global Municipal Software Market
Software & Services
Balance Sheet Management Software Market
Software & Services
US Software Consulting Market
Software & Services
Digital Sculpture Software Market
Software & Services
Construction Simulation Software Market
Software & Services
Email Marketing Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Transient Analysis Software Market
Software & Services
Logistics Services Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Europe Application Modernization Services Market
Software & Services
Inventory Management Software Market