
 Mindfulness Meditation Application Market | 2026-2036
Mindfulness Meditation Application Market Size, Share, and Industry Trends Forecast 2026-2036
Mindfulness Meditation Application Market Analysis
Corporate wellness budgets are consolidating as the fastest-growing end-use vertical for mindfulness meditation applications. Headspace Inc. leverages its enterprise partnerships to anchor recurring revenue from large employers. Calm competes through celebrity-narrated content and brand strength in direct-to-consumer channels. Insight Timer differentiates via a community-driven model that sustains engagement without heavy paid marketing.
Mindfulness meditation applications are software platforms delivering structured mental training through audio, visual, and biometric feedback interfaces, typically requiring 5-20 minute daily user sessions to achieve measurable stress reduction outcomes. Their primary commercial purpose is to substitute or complement in-person behavioral health interventions at lower per-user cost. Mobile apps occupy the largest revenue pool due to frictionless distribution through Apple App Store and Google Play ecosystems, while wearable devices represent the fastest-growing segment as Apple Watch and Garmin integrate heart-rate-variability-guided breathing protocols. Freemium subscription models concentrate user acquisition economics, though annual subscriptions capture the highest lifetime value per subscriber.
FDA digital health guidance and HIPAA privacy requirements shape product development roadmaps for US-facing developers, while GDPR compliance in Europe constrains biometric data collection and cross-border analytics. Germany's DiGA fast-track pathway for digital therapeutics creates a reimbursement template that other European health technology assessors are studying. Stakeholders must monitor whether regulatory bodies classify mindfulness apps as wellness tools or medical devices, as this determination will dictate clinical validation requirements and pricing power.
Market Dynamics
Corporate wellness budgets are consolidating mindfulness meditation applications as standardized benefits, creating a structural shift from discretionary consumer subscriptions to contracted enterprise deployments with multi-year renewal cycles.
Growth Catalysts
- DiGA Fast-Track Pathway:Germany's digital therapeutics reimbursement framework validates app-based mental health interventions, prompting other European health technology assessors to develop parallel approval channels.
- Heart-Rate Variability Integration:Wearable manufacturers embed biometric-guided breathing protocols, expanding addressable use cases beyond passive audio content into real-time physiological feedback.
- Employer-Sponsored Wellness Mandates:Large enterprises in the United States designate mental health applications as essential benefits, locking in recurring revenue through annual corporate contracts.
Market Restraints
- GDPR Biometric Constraints:European data protection rules limit cross-border analytics and heart-rate data retention, complicating personalization algorithms for EU-facing developers.
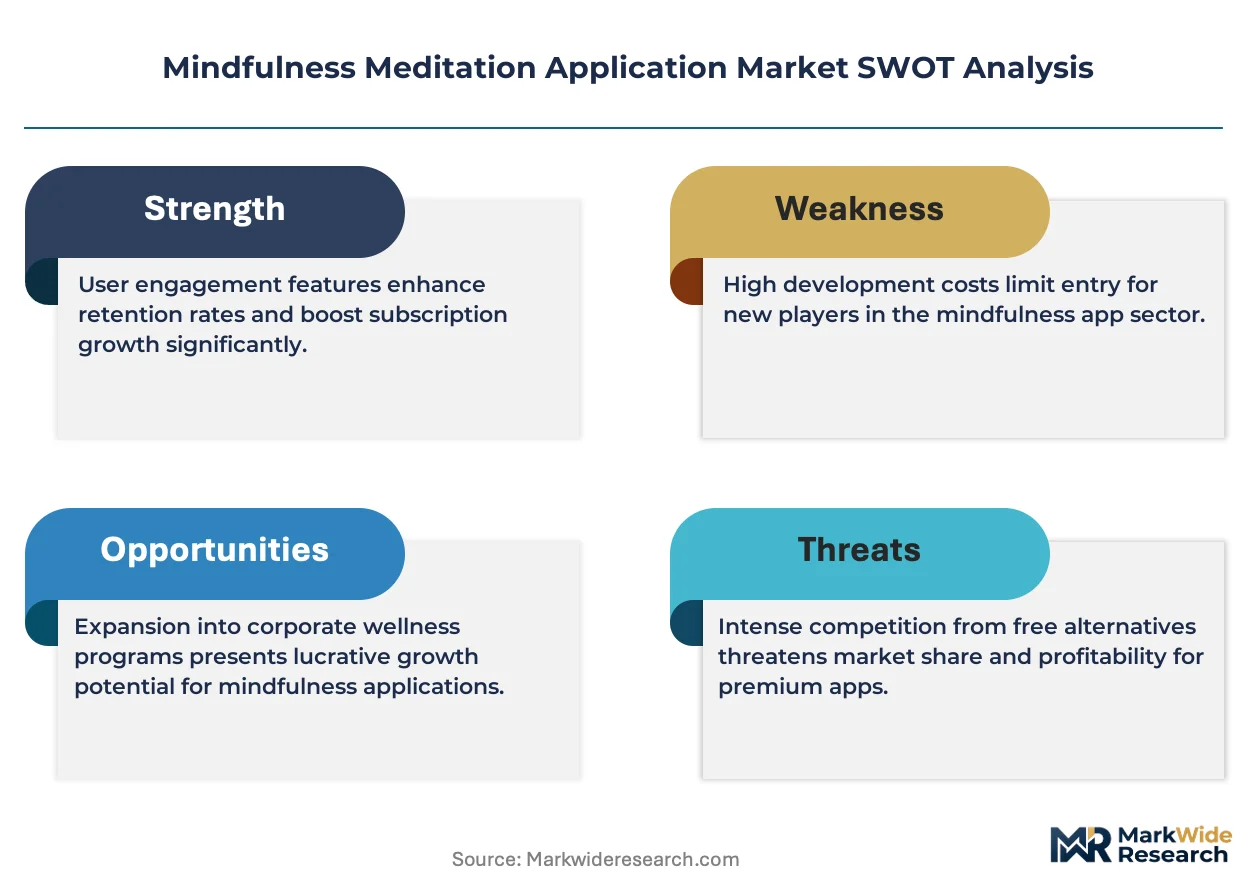
- Clinical Validation Costs:Randomized controlled trials required for medical device classification impose capital burdens that wellness-tier competitors cannot absorb.
- Freemium Conversion Ceiling:Low willingness-to-pay among consumer segments caps lifetime value per user, forcing heavy marketing spend to offset churn.
Strategic Opportunities
- Underpenetrated SME Wellness:Mid-sized employers in Australia lack dedicated mental health budgets, presenting white-space for tiered pricing models below enterprise thresholds.
- Digital Therapeutics Convergence:Prescription-grade mindfulness protocols paired with pharmaceutical adherence programs create reimbursement-eligible combination therapies.
- Insurance Partnership Channels:Health insurers in the United Kingdom integrate app subscriptions into policy benefits, bypassing direct consumer acquisition costs.
Industry Challenges
- Behavioral Science Talent Scarcity:Shortage of clinical psychologists with software product experience delays evidence-based content pipeline development.
- HIPAA Compliance Architecture:Enterprise buyers mandate audit-ready data infrastructure, requiring engineering resources that stretch mid-cap development teams.
- Interoperability with EHR Systems:Integration with electronic health record platforms demands custom API development for each hospital network procurement.
Report Scope
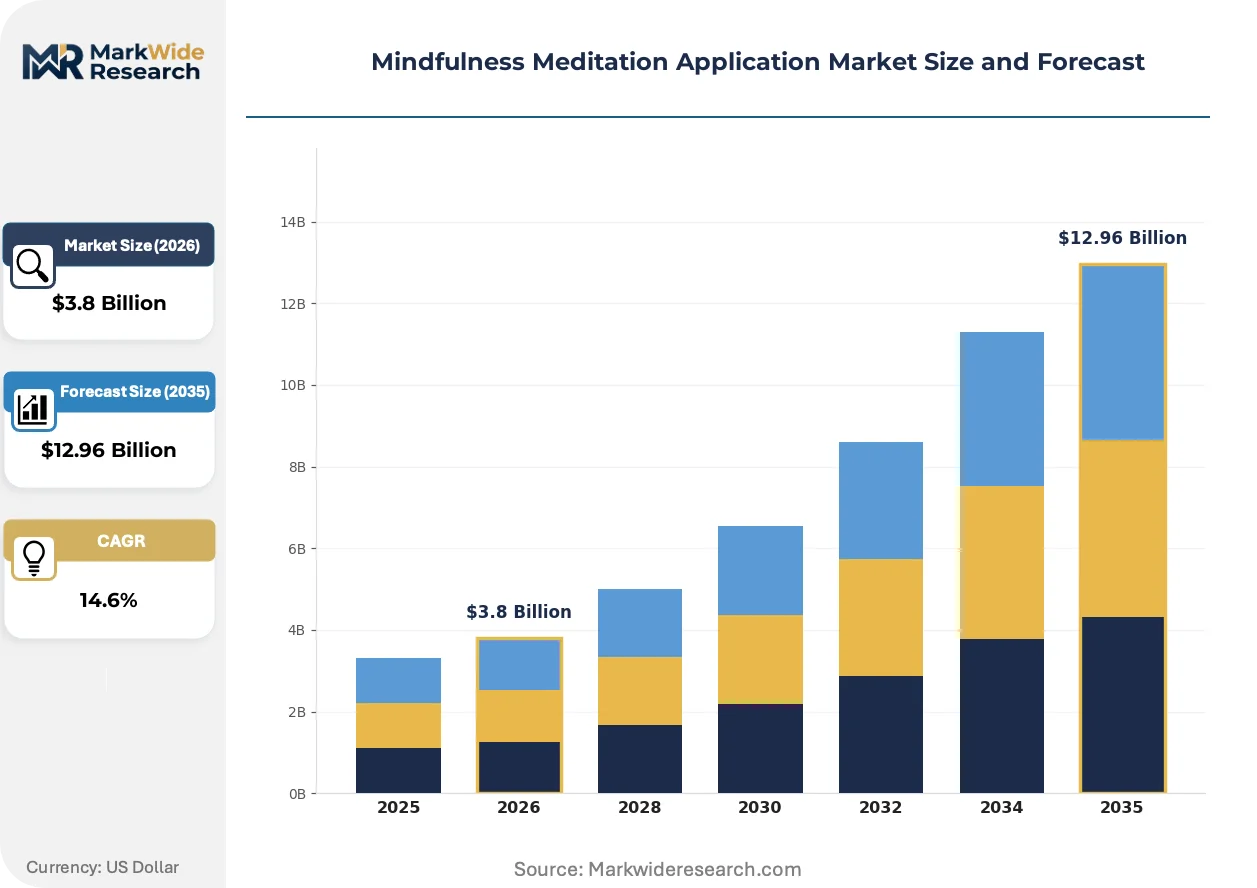
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mindfulness Meditation Application Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web Platforms, Wearable Devices, Audio Programs End User: Individuals, Healthcare Professionals, Educational Institutions, Corporate Clients Subscription Model: Free, Freemium, Monthly Subscription, Annual Subscription Content Type: Guided Meditations, Sleep Aids, Mindfulness Courses, Breathing Techniques |
| Companies Covered | Calm, Headspace Inc., Insight Timer, Simple Habit, Ten Percent Happier, Aura Health, Breethe, Smiling Mind, Meditation Moments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mindfulness Meditation Application Market Emerging Trajectories
Biometric sensing capabilities are reshaping how mindfulness applications measure and respond to physiological states, shifting competitive advantage from content libraries to real-time adaptive algorithms.
Heart-rate variability monitoring is converging with guided breathing interfaces to create closed-loop stress intervention systems. Apple Watch and Garmin device owners now expect personalized pacing based on autonomic nervous system feedback. This convergence is compressing differentiation timelines for audio-only competitors and forcing rapid sensor integration roadmaps.
EMA's evolving stance on software-as-medical-device classification is tightening clinical evidence requirements for stress-reduction claims. Developers targeting European reimbursement must now submit peer-reviewed efficacy data comparable to pharmaceutical trials. Wellness-tier applications without trial infrastructure are retreating to lifestyle-positioned marketing to avoid regulatory scrutiny.
Enterprise procurement teams are unbundling mental health benefits from broad wellness platforms, creating direct RFP processes for specialized mindfulness vendors. Benefits consultants in the United States now run competitive evaluations separate from general employee assistance programs. This disintermediation favors vendors with dedicated B2B sales operations over consumer-native applications attempting lateral expansion.
Mindfulness Meditation Application Market Segmentation
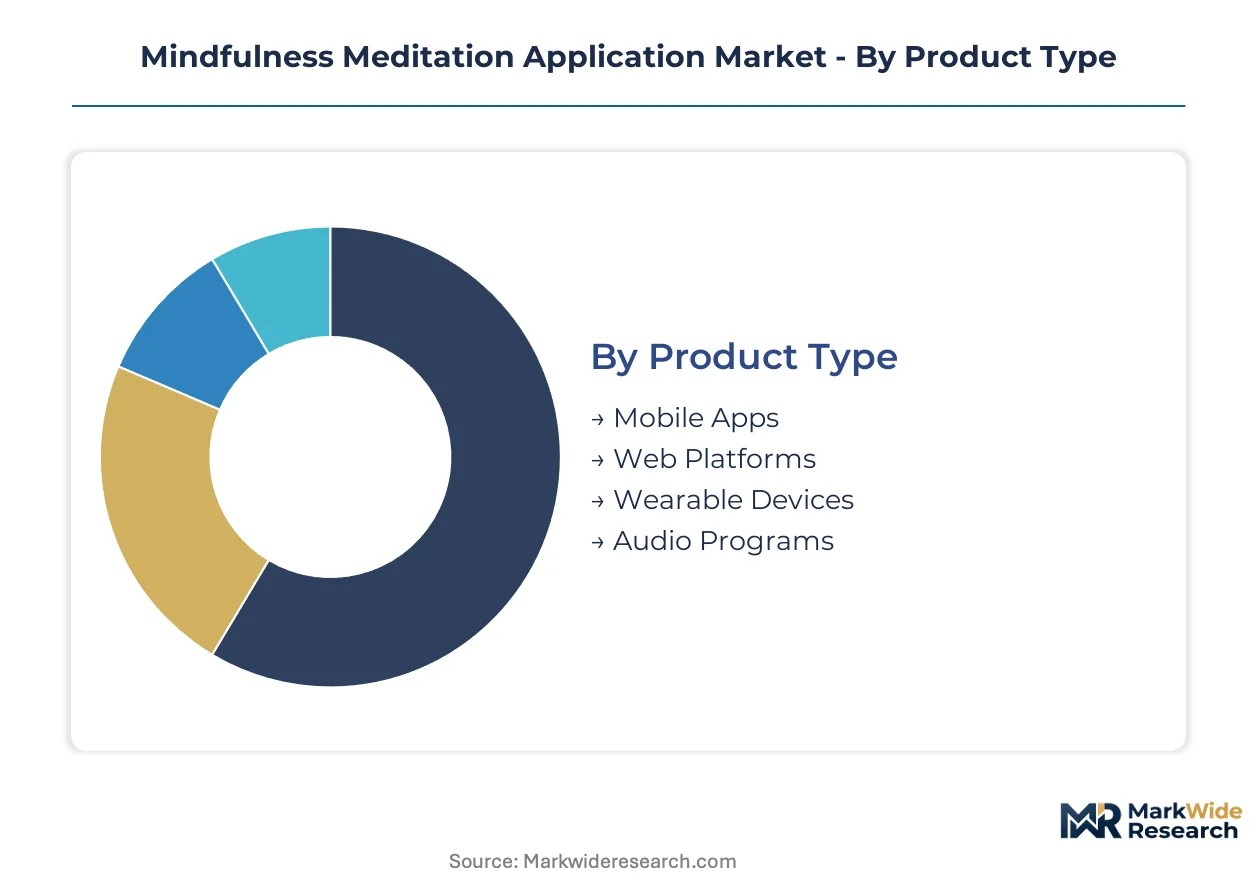
Segmentation in the mindfulness meditation application market reveals divergent monetization pathways and user engagement mechanics. Product architecture choices determine distribution economics, while subscription model selection governs customer lifetime value. Understanding these divides separates sustainable revenue models from high-churn consumer experiments.
Product Type:
Volume concentrates in mobile distribution channels, while premium pricing attaches to biometric-integrated hardware ecosystems.
- Mobile Apps:Native iOS and Android applications deliver audio-guided sessions through frictionless app store distribution. Demand clusters in the United States, the United Kingdom, and Australia where smartphone penetration and consumer willingness to pay for subscription services remain strongest. Freemium conversion economics dominate revenue architecture, though annual subscribers capture disproportionate lifetime value.
- Wearable Devices:Apple Watch and Garmin integrate heart-rate-variability-guided breathing protocols that adapt session pacing to real-time autonomic nervous system feedback. Germany's DiGA fast-track pathway for digital therapeutics validates reimbursement for biometric-validated interventions, prompting hardware manufacturers to embed clinical-grade sensors.
- Web Platforms:Browser-based interfaces serve enterprise deployments requiring SSO integration and administrative dashboards without mobile device management complexity.
- Audio Programs:Downloadable content libraries function in low-connectivity environments and support offline usage for aviation, maritime, and remote workforce applications.
Today's leader: Mobile Apps. Tomorrow's challenger: Wearable Devices.
End User:
Customer type determines procurement cycle length and pricing authority, with institutional buyers commanding volume discounts unavailable to individual subscribers.
- Individuals:Direct-to-consumer subscribers purchase through app stores with monthly or annual billing cycles. Churn rates exceed institutional contracts, forcing heavy paid marketing to maintain net revenue retention.
- Corporate Clients:Large enterprises in the United States designate mindfulness applications as essential benefits, locking in multi-year contracts with standardized per-employee pricing. Benefits consultants now run competitive RFP processes separate from general employee assistance programs, favoring vendors with dedicated B2B sales operations.
- Healthcare Professionals:Clinicians prescribe app-based interventions as adjuncts to pharmaceutical therapy, requiring FDA digital health guidance compliance and HIPAA audit-ready infrastructure.
- Educational Institutions:Universities and K-12 districts procure campus-wide licenses for student mental health support, with procurement timelines tied to academic budget cycles.
Corporate contracting commands pricing power. Individual subscription economics face margin compression.
Subscription Model:
Free acquisition funnels feed tiered conversion architecture, with annual commitments capturing superior unit economics against monthly churn.
- Freemium:Limited content libraries drive user acquisition before paywall conversion. This model sustains the largest installed bases but suffers from low willingness-to-pay ceilings among consumer segments.
- Annual Subscription:Prepaid annual billing reduces payment processing costs and improves cash flow predictability. Enterprise buyers mandate annual terms with renewal options, creating contracted revenue visibility.
- Free:Ad-supported or foundation-funded offerings serve public health objectives without direct user monetization, common in NHS partnerships and nonprofit deployments.
- Monthly Subscription:Flexible billing attracts trial users but exhibits higher cancellation rates and lower lifetime value per subscriber.
Annual subscriptions anchor sustainable economics. Freemium conversion rates dictate growth viability.
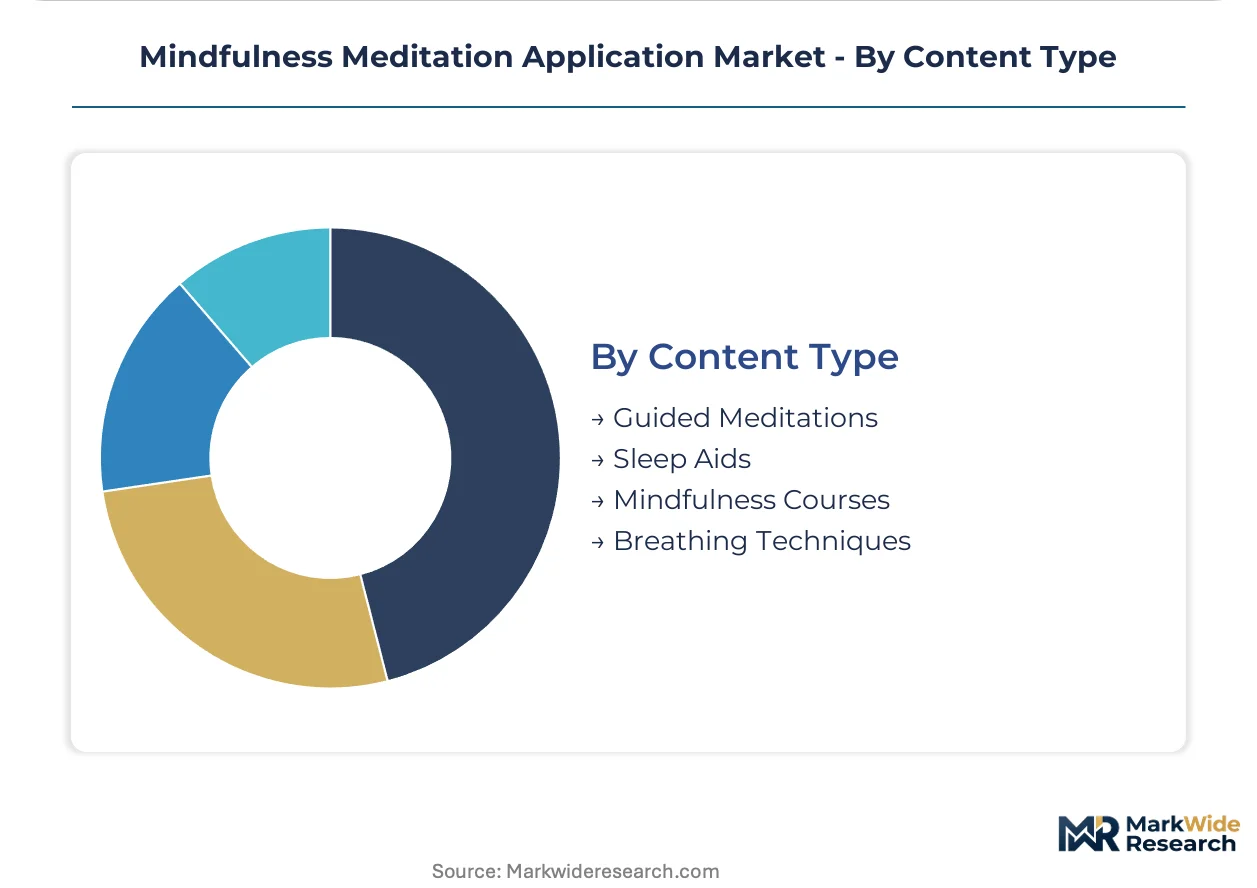
Content Type:
Functional use case specialization allows premium pricing for condition-specific protocols versus general wellness positioning.
- Sleep Aids:Narrated sleep stories and soundscapes command subscription premiums due to chronic insomnia prevalence and repeat nightly usage patterns. Clinical validation requirements tighten as EMA evaluates software-as-medical-device classification for sleep disorder claims.
- Guided Meditations:Structured audio sessions form the core content library across all platforms, with differentiation shifting from celebrity narration to biometric-adaptive pacing algorithms.
- Mindfulness Courses:Progressive curricula with completion certificates appeal to educational institutions and corporate learning budgets seeking measurable outcomes.
- Breathing Techniques:Physiological feedback protocols integrate with wearable sensors, expanding from passive content into real-time intervention systems.
Sleep specialization captures pricing premiums. Biometric breathing protocols are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of digital health venture capital anchors global mindfulness application development, with reimbursement policy divergence across national healthcare systems creating distinct market entry pathways.
United States
Employer-sponsored wellness budgets and mental health parity regulations drive enterprise contract expansion. FDA digital health guidance shapes clinical validation requirements for stress-reduction claims. Boston's digital health cluster hosts multiple behavioral science research partnerships with academic medical centers.
Germany
DiGA fast-track reimbursement validates app-based mental health interventions for statutory health insurance coverage. BfArM's digital therapeutics assessment framework creates regulatory precedent studied across Europe. Berlin's health technology startup ecosystem concentrates clinical trial infrastructure for software-as-medical-device pathways.
United Kingdom
NHS digital mental health programs integrate mindfulness applications into stepped-care models for anxiety and depression. MHRA's evolving software medical device classification tightens evidence requirements for therapeutic claims. London's corporate wellness procurement market commands premium pricing for enterprise deployments.
Australia
TGA's digital health regulatory framework and employer wellness budget expansion create dual demand channels. Mid-sized employer underpenetration presents white-space opportunity below enterprise pricing thresholds. Sydney's health technology investment community funds biometric-integrated wearable application development.
Mindfulness Meditation Application Market Vendor Landscape
Enterprise partnership formation dominates the current landscape, with competitive structure consolidating around three distinct strategic tiers. Venture-backed consumer applications anchor direct-to-consumer channels through celebrity content and freemium conversion architectures. Enterprise-native vendors capture multi-year corporate contracts through dedicated B2B sales operations and administrative dashboard integration. Community-driven platforms sustain engagement without heavy paid marketing through user-generated content ecosystems. Geographic expansion into underpenetrated SME wellness markets and biometric sensor integration represent the dominant competitive vectors reshaping positioning.
Within the venture-backed tier, Calm and Headspace Inc. exemplify divergent content strategies, with the former leveraging narrated sleep stories and the latter anchoring corporate wellness partnerships. Insight Timer occupies a distinct position within the community-driven archetype, sustaining user engagement through practitioner-generated content without reliance on paid acquisition channels.
| Leading Market Players |
|---|
| Calm |
| Headspace Inc. |
| Insight Timer |
| Simple Habit |
| Ten Percent Happier |
| Aura Health |
| Breethe |
| Smiling Mind |
| Meditation Moments |
| Others |
Supply Flow & Price Mechanics
Biometric sensor integration into wearable devices simultaneously compresses content production costs and concentrates hardware supply among Apple and Garmin ecosystems, creating asymmetric pricing power between software-native and hardware-integrated competitors. FDA digital health guidance and Germany's DiGA pathway impose divergent compliance cost structures that stratify pricing tiers across regulatory jurisdictions.
Pricing Analysis
Input-cost pass-through from clinical validation trials and HIPAA-compliant infrastructure investments anchors enterprise subscription premiums, while freemium consumer tiers absorb heavy customer acquisition spend without margin recovery. Three-tier pricing structure across premium biometric-integrated, standard mobile-app, and economy white-label offerings separates vendors by certification depth and data sovereignty architecture. Pricing pressure stems from low willingness-to-pay among individual subscribers forcing perpetual discounting. Corporate buyers exhibit lowest price sensitivity due to bundled wellness budget allocations, while SME segments demand per-employee rates below enterprise thresholds.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure and biometric sensor modules mandate multi-vendor qualification across AWS-Google Cloud and Apple-Garmin pairings, preventing single-point failure in enterprise deployments. Content production concentrates in the United States, the United Kingdom, and Australia where behavioral science talent clusters anchor curriculum development. Raw material dependencies include licensed music catalogs, voice actor talent pools, and heart-rate variability algorithm IP. Supply chain risk centers on GDPR biometric data restrictions limiting EU-US cross-border analytics. Distribution runs through Apple App Store and Google Play ecosystems for consumer segments, with direct API integration for enterprise SSO deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where employer-sponsored wellness budgets are consolidating around clinically validated platforms, shifting procurement criteria from content breadth to biometric feedback precision and audit-ready data infrastructure.
For Market Incumbents: Cement multi-year enterprise contract renewals by embedding administrative dashboards and EHR interoperability ahead of competitive RFP cycles. Prioritize backward integration into biometric sensor partnerships with Apple and Garmin to lock out audio-only competitors. Clinical validation investments for FDA digital health guidance compliance represent the critical defensive moat against wellness-tier challengers. For New Entrants and Emerging Players: Begin with white-space targeting of mid-sized Australian employers lacking dedicated mental health budgets but facing TGA regulatory tailwinds. Insurance partnership channels in the United Kingdom offer bypass around direct consumer acquisition costs. Community-driven content models without paid marketing dependence provide the most penetrable go-to-market angle against venture-backed incumbents. For Investors and Strategic Acquirers: Roll-up economics work for enterprise-native mindfulness platforms because employer procurement teams are unbundling mental health benefits from broad wellness suites, creating fragmented vendor bases ripe for consolidation. Target acquisition archetypes include HIPAA-audit-ready infrastructure plays and biometric algorithm specialists. Watch EMA software-as-medical-device classification rulings as the inflection signal separating reimbursement-eligible from lifestyle-positioned assets.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Sensor Integration | Apple Watch and Garmin partnerships enable real-time HRV-guided breathing protocols that differentiate from audio-only competitors. |
| DiGA Fast-Track Submission | Germany's BfArM reimbursement pathway validates prescription-grade mindfulness for statutory health insurance coverage. |
| Enterprise SSO Integration | Administrative dashboard deployment satisfies corporate procurement mandates for multi-year wellness contract renewals. |
| Clinical Trial Infrastructure | Randomized controlled trial investment satisfies FDA digital health guidance for stress-reduction therapeutic claims. |
| Insurance Channel Partnership | UK health insurer policy benefit integration eliminates direct consumer acquisition costs and improves unit economics. |
Methodological Framework
Multiple input streams — executive interviews with digital health platform CTOs, benefits consultants at US enterprise procurement teams, and behavioral science researchers at academic medical centers — were reconciled against secondary validation from FDA digital health guidance documents, Germany's BfArM DiGA assessment frameworks, and NHS digital mental health program evaluations. Bottom-up subscriber and revenue estimates by segment were triangulated against top-down market sizing from venture capital deployment patterns and enterprise wellness budget disclosures.
Data-stream reconciliation across mobile app store analytics, wearable device shipment reports, and corporate contract announcement tracking informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product architecture, end-user procurement type, subscription billing structure, and content functional specialization. CAGRs were derived from cohort retention analysis and enterprise renewal rate assumptions, with biometric sensor adoption curves and mental health parity regulation expansion as primary forecast inputs.
Several conditions sit outside the modeled scope, including potential FDA reclassification of wellness apps as medical devices, GDPR enforcement actions on biometric data retention, and macroeconomic compression of employer wellness budgets. Forecasts reflect assumptions about sustained corporate willingness to subsidize mental health benefits and continued smartphone penetration in target demographics. Deviation in EMA software-as-medical-device classification timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Retail Management Systems Software Market
Software & Services
Tenant Billing System Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
MES Software Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Device Tracking Software Market
Software & Services
CAM Software Market
Software & Services
Salon Booking Software Market
Software & Services
Air Cargo Software Market
Software & Services
Indoor Cycling Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Global Human Capital Management Software Market
Software & Services
ITSM Market
Software & Services
Ccaas Software Market
Software & Services
Course Authoring Software Market