
 Global Catalog Management Software Market | 2026-2036
Global Catalog Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Catalog Management Software Market Foresight
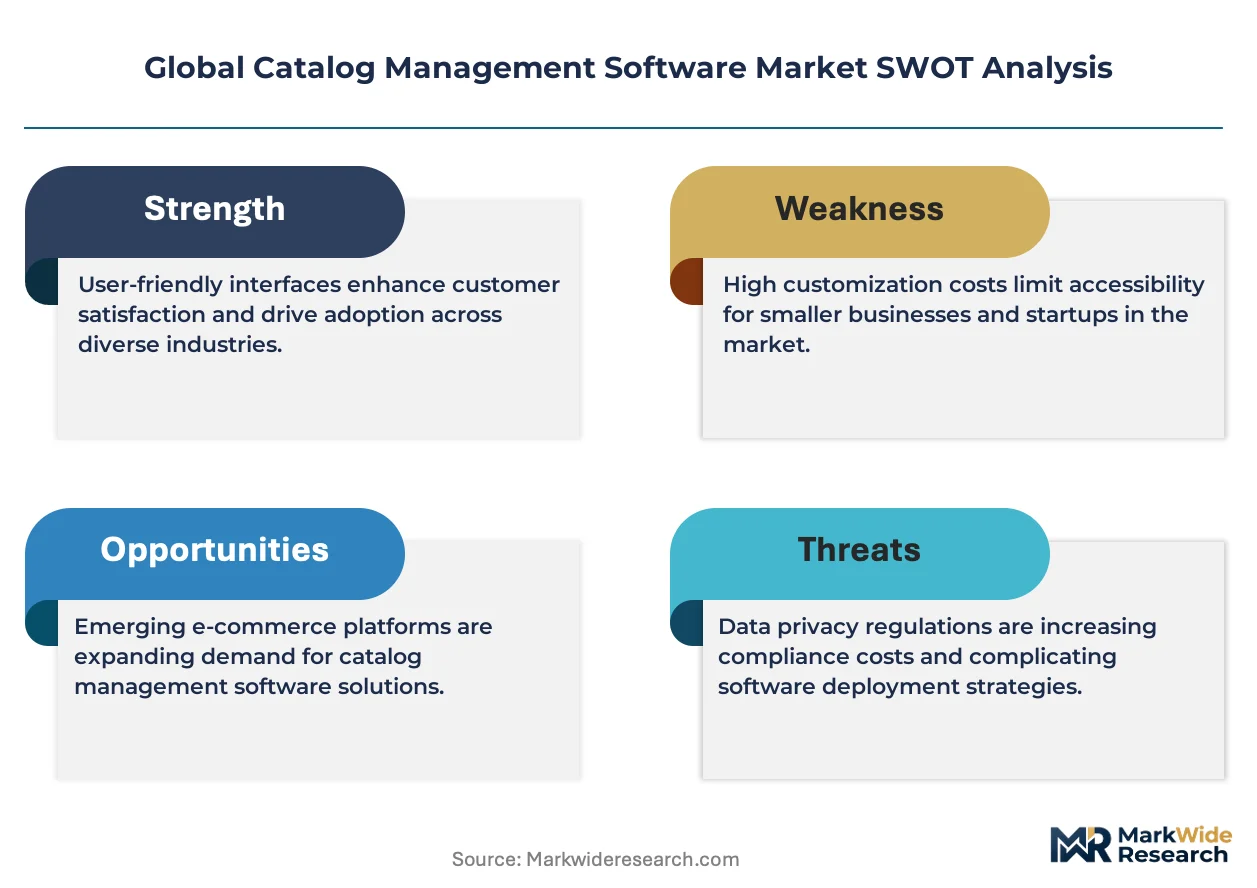
Subscription-based data quality management is decoupling catalog software from perpetual licensing models and reshaping vendor economics. SAP SE leverages its ERP installed base to bundle catalog modules into enterprise renewal cycles. Oracle Corporation anchors its strategy in cloud infrastructure integration, forcing rivals to compete on interoperability rather than standalone features. Salsify specializes in content syndication for consumer brands, occupying a defensible niche against horizontal platform providers.
Catalog management software governs the creation, enrichment, and distribution of structured product information across sales channels, typically operating through centralized repositories that enforce attribute validation rules and digital asset linking. Its primary commercial purpose is eliminating data fragmentation between suppliers, e-commerce platforms, and downstream distributors. Cloud-based deployment now leads spending as enterprises abandon on-premises maintenance overhead for elastic infrastructure. Product Information Management captures the largest solution share, though Data Quality Management is expanding fastest as retailers face penalties for inconsistent pricing and regulatory non-compliance across marketplaces.
The EU AI Act and GDPR shape European demand by mandating automated content classification and consent tracking within catalog workflows. The U.S. FCC and FTC influence data governance standards for telecommunications and consumer protection, while China's SAMR enforces product labeling accuracy on cross-border e-commerce platforms. Stakeholders must monitor whether regulatory divergence between jurisdictions forces vendors to maintain parallel compliance architectures or accelerates consolidation around modular, jurisdiction-swappable catalog engines.
Market Dynamics
Cloud-native catalog platforms are absorbing enterprise IT budgets previously allocated to on-premises data governance infrastructure, forcing vendors to rearchitect around elastic compute and API-first delivery models.
Growth Catalysts
- EU AI Act compliance mandates:Automated content classification workflows now embed algorithmic transparency checks, driving replacement cycles for legacy catalog engines across European retail and pharmaceutical distributors.
- Real-time inventory synchronization:Omnichannel retailers in the United States demand sub-second API latency for stock-level updates, compressing vendor selection criteria toward low-latency cloud architectures.
- Cross-border e-commerce expansion:China's SAMR enforcement of product labeling accuracy on import platforms forces exporters to adopt centralized catalog repositories with multi-jurisdiction attribute mapping.
Market Restraints
- Data migration complexity:Enterprises face eighteen-month average timelines to consolidate legacy product databases into modern catalog platforms, delaying contract renewals and inflating professional services costs.
- Concentrated hyperscaler dependency:Cloud infrastructure concentration in AWS, Azure, and Google Cloud creates single-point-of-failure risk for catalog availability during regional outages.
- GDPR territorial enforcement:Data residency requirements fragment catalog hosting architectures, preventing vendors from achieving true global scale economies in European deployments.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Localized production incentives attract component suppliers needing catalog systems compliant with BIS standards and DGFT export documentation.
- Generative AI content enrichment:Convergence of large language models with structured product data enables automated attribute extraction from unstructured supplier documents, reducing manual curation labor.
- Direct-to-consumer channel expansion:Brand manufacturers bypassing wholesale distributors require native catalog syndication to TikTok Shop and Instagram Commerce, opening subscription revenue for specialized content platforms.
Industry Challenges
- Master data stewardship talent scarcity:Organizations struggle to hire product information managers capable of bridging technical schema design with commercial category expertise.
- Legacy ERP integration friction:SAP and Oracle environments impose proprietary data models that resist standard API connectivity, extending implementation timelines and eroding SaaS margin profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Catalog Management Software Market |
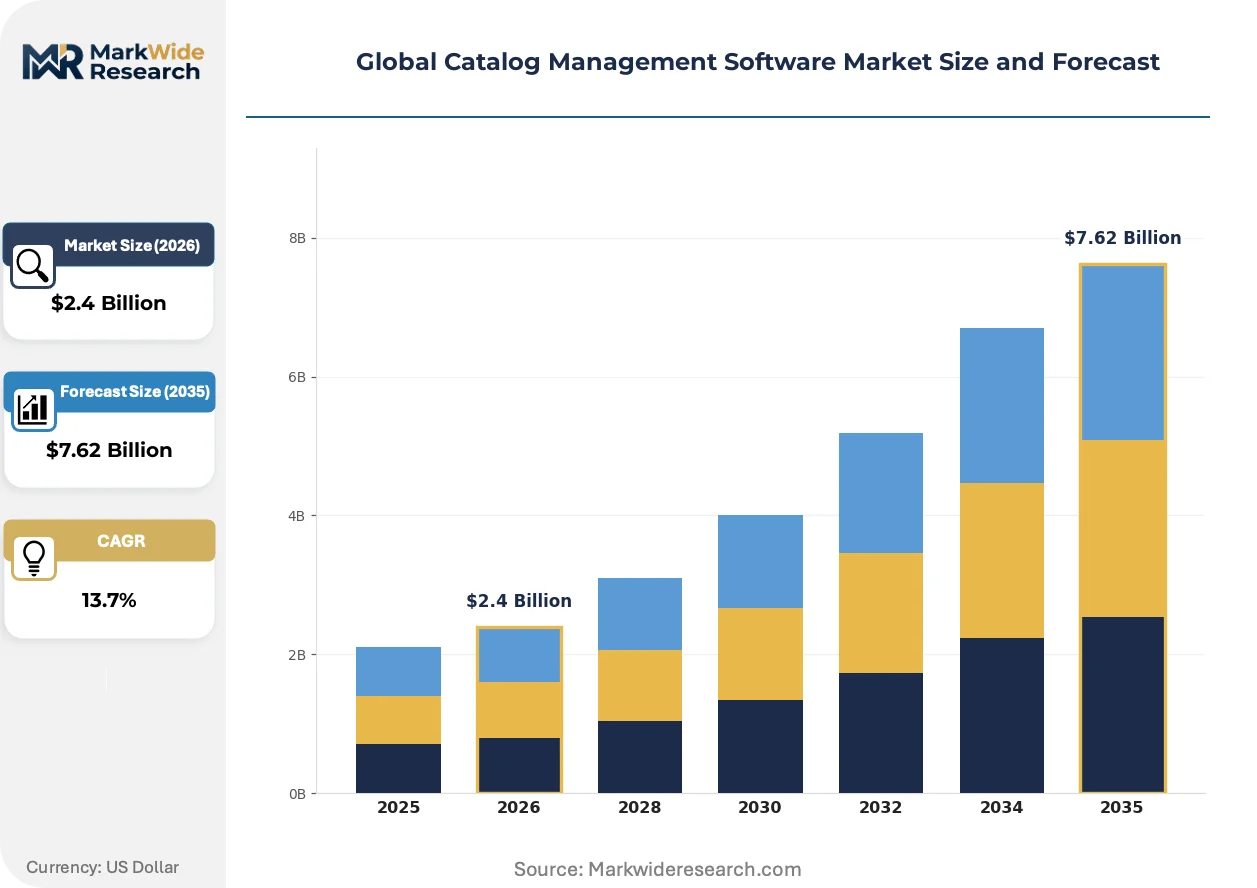
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud Solution/Offering: Product Information Management, Digital Asset Management, Content Syndication, Data Quality Management, Catalog Publishing Application: E-Commerce Platforms, Wholesale Distribution, Manufacturing, Publishing, Consumer Electronics End User Industry Vertical: Retail Chains, Distribution Centers, Software Providers, Content Creators, Technology Vendors |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, Salsify, Coupa Software Inc., ServiceNow Inc., Broadcom Inc., Fujitsu Limited, Amdocs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Catalog Management Software Market Shifts & Advancements
Generative AI and edge computing are restructuring how product data flows between suppliers and sales channels, compressing the traditional batch-update model toward continuous synchronization architectures.
Graph database technology is absorbing relational schema limitations in complex product hierarchies with multi-dimensional attribute inheritance. Industrial distributors managing millions of SKUs with interchangeable components are migrating from SQL-based catalogs to Neo4j and Amazon Neptune implementations. This shift is absorbing engineering resources previously allocated to custom middleware development, consolidating vendor value propositions around native graph query performance.
The EU AI Act's risk classification framework is mandating automated audit trails for algorithmic product recommendations in e-commerce environments. Vendors must now embed explainability modules that trace how catalog search rankings influence consumer purchasing decisions. German and French retailers are responding by procurement committees requiring ISO 42001 AI management system certification from catalog software providers.
Buyer committees are consolidating vendor relationships from point solutions toward integrated product experience platforms. Procurement teams at consumer goods manufacturers now bundle catalog management with digital asset management and syndication capabilities into single-source contracts. This pattern is most visible in North American enterprise accounts where CIOs prioritize vendor reduction over best-of-breed feature depth.
Global Catalog Management Software Market Segmentation
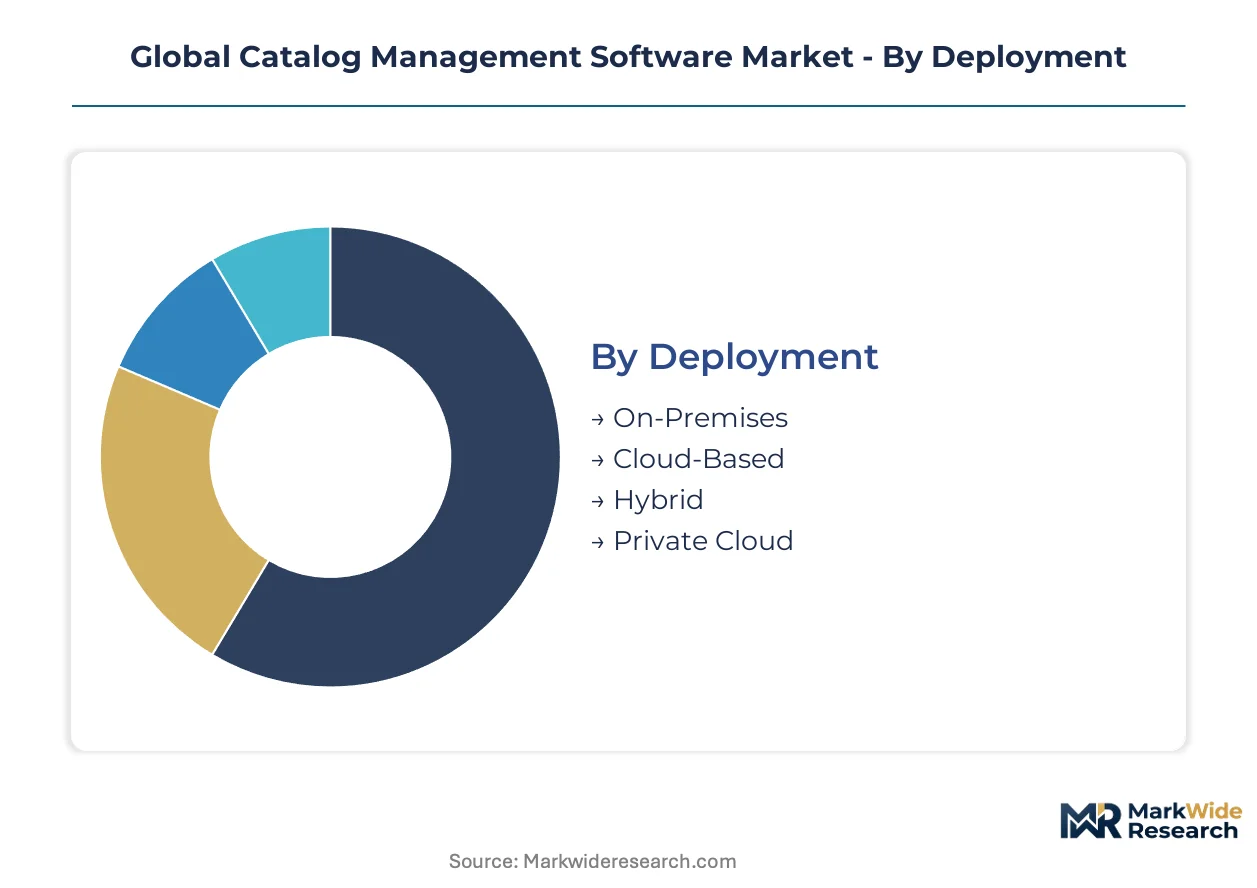
Catalog management software segments diverge sharply across infrastructure preferences and functional depth. Deployment models determine integration complexity, while solution types govern pricing architecture and renewal velocity.
Deployment:
Standardized cloud configurations dominate mid-market procurement, yet enterprise buyers demand customization across security boundaries and data residency requirements.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning serve retailers requiring sub-second inventory synchronization across dozens of sales channels. United States omnichannel operators prioritize API-first delivery models that bypass on-premises maintenance overhead entirely.
- Hybrid:Split architectures maintain sensitive product data on local servers while syndicating public-facing attributes through cloud gateways. German pharmaceutical distributors favor this model to satisfy GDPR territorial enforcement without sacrificing marketplace connectivity.
- On-Premises:Legacy ERP-integrated installations persist in regulated industries with audit trail mandates.
- Private Cloud:Single-tenant dedicated infrastructure addresses data sovereignty requirements in financial services and defense supply chains.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as European compliance mandates harden.
Solution/Offering:
Functional modules stratify by customer sophistication, with basic catalog publishing serving price-sensitive segments and integrated platforms capturing enterprise renewals.
- Product Information Management:Centralized repositories enforce attribute validation rules and digital asset linking across supplier hierarchies. Retail chains in the United States deploy these systems to unify SKU data fragmented across legacy warehouse management and e-commerce platforms.
- Data Quality Management:Automated cleansing engines flag inconsistent pricing and non-compliant labeling before marketplace publication. Cross-border exporters to China leverage these tools to preempt SAMR enforcement actions on product labeling accuracy.
- Digital Asset Management:Media workflow engines connect creative production to catalog enrichment pipelines.
- Content Syndication:Multi-channel formatting engines adapt product descriptions to platform-specific requirements.
- Catalog Publishing:Output generation tools produce print and digital catalogs from validated product records.
Product Information Management retains the largest revenue base. Data Quality Management is climbing the fastest as regulatory penalties intensify across jurisdictions.
Application:
Volume concentration varies by channel maturity, with e-commerce platforms consuming the most seats and manufacturing presenting the longest sales cycles.
- E-Commerce Platforms:Real-time catalog APIs power marketplace listings, search ranking optimization, and dynamic pricing engines. Direct-to-consumer brands in India require these integrations to satisfy BIS standards and DGFT export documentation under the PLI scheme for electronics manufacturing.
- Wholesale Distribution:Multi-supplier aggregation hubs consolidate millions of SKUs with interchangeable component relationships. Industrial distributors migrating from SQL schemas to graph databases like Neo4j and Amazon Neptune drive specialized procurement here.
- Manufacturing:Bill-of-materials linkage connects component catalogs to finished product configurations.
- Publishing:Metadata enrichment workflows support academic and trade publication distribution.
- Consumer Electronics:Rapid product lifecycle management accelerates time-to-market for seasonal device launches.
E-Commerce Platforms absorb the majority of new license bookings. Wholesale Distribution shows the steepest expansion trajectory as B2B marketplaces digitize.
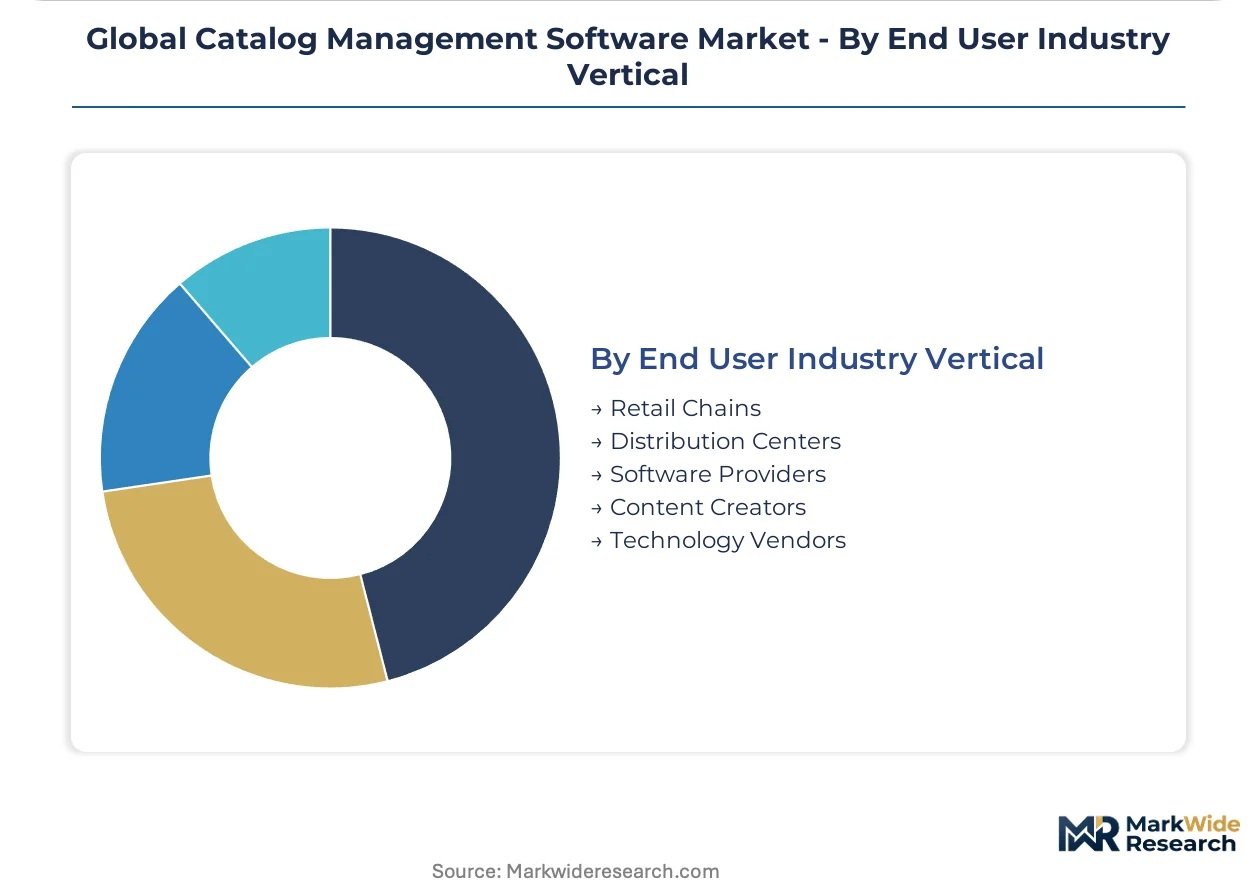
End User Industry Vertical:
Customer types separate by procurement authority, with technology vendors embedding catalog modules into broader platforms and retail chains demanding standalone best-of-breed solutions.
- Retail Chains:Omnichannel operators require unified product data spanning physical POS, e-commerce storefronts, and social commerce integrations. Procurement committees at North American consumer goods manufacturers now bundle catalog management with digital asset management into single-source contracts.
- Software Providers:Platform vendors embed catalog functionality into ERP, CRM, and commerce suites. SAP SE leverages its installed base to bundle catalog modules into enterprise renewal cycles, while Oracle Corporation anchors strategy in cloud infrastructure integration.
- Distribution Centers:Logistics operators use catalog data to optimize picking workflows and returns processing.
- Content Creators:Agencies and studios manage digital asset libraries tied to product campaigns.
- Technology Vendors:Infrastructure and hardware suppliers maintain component catalogs for developer ecosystems.
Retail Chains command the largest deployment footprint. Software Providers are gaining share fastest as vendor consolidation accelerates across enterprise accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outspends Germany on API-first catalog platforms, while China's cross-border enforcement drives faster adoption than India's emerging manufacturing incentives.
United States
Omnichannel retailers demand sub-second inventory synchronization across physical POS and e-commerce storefronts. The FCC and FTC influence data governance standards for telecommunications and consumer protection compliance. Silicon Valley and Seattle clusters host cloud-native vendors architecting elastic compute solutions for real-time stock-level updates.
Germany
Pharmaceutical distributors and industrial manufacturers prioritize GDPR-compliant hybrid deployments for sensitive product data. The EU AI Act mandates automated audit trails for algorithmic product recommendations, requiring ISO 42001 certification. Berlin and Munich procurement committees now embed explainability modules into catalog search ranking systems.
China
Cross-border e-commerce exporters face SAMR enforcement of product labeling accuracy on import platforms. The MIIT and GB standards framework governs data localization requirements for marketplace connectivity. Shenzhen and Hangzhou technology clusters drive demand for centralized repositories with multi-jurisdiction attribute mapping capabilities.
India
Electronics manufacturers under the PLI scheme require catalog systems compliant with BIS standards and DGFT export documentation. The RBI and SEBI influence financial data governance for B2B marketplace operators. Bangalore and Hyderabad SaaS vendors serve direct-to-consumer brands syndicating content to TikTok Shop and Instagram Commerce.
United Kingdom
Post-Brexit regulatory divergence forces parallel compliance architectures for EU and domestic market access. The Information Commissioner's Office enforces GDPR-equivalent data residency requirements for catalog hosting. London financial services and Manchester retail clusters drive private cloud deployments for audit trail mandates.
Global Catalog Management Software Market Competitive Landscape
Top-tier vendors anchor enterprise ERP integration, while mid-market specialists compete on API-first delivery and content syndication speed. The market structures around three strategic archetypes: horizontal platform bundlers, vertical content specialists, and cloud-native challengers. Dominant competitive moves include strategic partnerships with hyperscalers and portfolio diversification into adjacent digital asset management capabilities.
Within the horizontal platform tier, SAP SE and Oracle Corporation exemplify bundling strategies that leverage installed base relationships to absorb catalog modules into broader enterprise renewal cycles. Salsify occupies a defensible specialist position against these horizontal providers, representing the vertical content archetype focused on consumer brand syndication workflows. These three companies collectively illustrate how vendor consolidation pressures are compressing point-solution providers toward integrated product experience platforms.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Salsify |
| Coupa Software Inc. |
| ServiceNow Inc. |
| Broadcom Inc. |
| Fujitsu Limited |
| Amdocs |
| Others |
Supply & Pricing Matrix
Product data architects concentrated in Bangalore and Hyderabad drive labor-cost differentials that widen pricing-tier spreads between premium API-first platforms and economy-tier catalog publishing tools.
Pricing Analysis
Capacity additions in India's SaaS corridor are reshaping price floors for mid-market cloud deployments. Pricing stratifies across premium, standard, and economy tiers, with differentiation hinging on ISO 42001 certification status and API latency guarantees. Cost compression in the economy tier is intensifying because hyperscaler infrastructure costs are falling faster than vendor pricing discipline. Retail chains with omnichannel complexity show the least price sensitivity, while single-channel publishers absorb the most margin pressure.
Supply Chain Analysis
Reverse logistics flows for catalog data—customer returns triggering attribute updates, supplier document revisions, and marketplace delistings—create continuous enrichment cycles that strain legacy batch architectures. Engineering talent concentrates in the United States, Germany, and India. Component dependencies span graph database engines, LLM inference APIs, and compliance validation modules. Single-source vulnerability rests on AWS, Azure, and Google Cloud concentration for hosting. Distribution runs through direct SaaS sales, systems integrator partnerships, and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's compliance cost premium against India's lighter regulatory burden positions South Asian SaaS vendors as geographic-arbitrage beneficiaries for mid-market accounts.
For Market Incumbents: Cement ERP integration moats by deepening native connectors for SAP and Oracle environments, where proprietary data models resist standard API connectivity. Threats from cloud-native challengers with sub-second latency architectures demand capacity addition in United States hyperscaler regions to match performance benchmarks. Certification investment in ISO 42001 AI management systems secures procurement committee mandates at German and French retailers.
For New Entrants and Emerging Players: Begin with India's PLI-scheme electronics manufacturers, where BIS standards compliance and DGFT export documentation requirements outpace incumbent localization speed. The most penetrable segment is direct-to-consumer brands syndicating content to TikTok Shop and Instagram Commerce, where horizontal platforms lack native channel adapters. A vertical-specific go-to-market angle—content syndication for consumer electronics with rapid lifecycle turnover—bypasses entrenched horizontal competition.
For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, seeking catalog modules to complete product experience platform stacks. Long-term viability favors vendors with graph-native architectures and generative AI enrichment pipelines over relational-schema legacy codebases. Acquisition target archetypes include mid-market specialists with proven API-first delivery and established marketplace connectors. The signal to watch is procurement committee consolidation from point solutions toward integrated product experience platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native ERP connectors for SAP and Oracle environments compress implementation timelines and defend renewal rates. |
| Acquisition of Specialist Firm | Graph database expertise from Neo4j or Amazon Neptune practitioners accelerates migration from SQL schemas. |
| Strategic Partnership | Hyperscaler alliances with AWS, Azure, or Google Cloud embed catalog modules into cloud marketplace procurement flows. |
| Geographic Expansion | Localized hosting in Germany and France satisfies GDPR territorial enforcement and EU AI Act audit trail mandates. |
| Product Launch | Generative AI content enrichment modules automate attribute extraction from unstructured supplier documents. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged CTOs at retail chains, IT procurement officers at consumer goods manufacturers, platform engineers at cloud-native vendors, and integration specialists at systems integrators. Secondary sources encompassed SEC filings, hyperscaler capex disclosures, EU regulatory filings, and BIS standards documentation. Bottom-up and top-down triangulation reconciled vendor-reported bookings with enterprise IT spending surveys.
Rate-of-change decomposition across the analysis window isolated volume and pricing drivers by deployment model, organization size, vertical industry, and integration complexity. CAGRs derived from segment-level growth trajectories weighted by current revenue bases. Industry-specific inputs included API latency benchmarks, compliance certification adoption curves, and graph database migration timelines.
Several conditions sit outside the modeled scope, including macroeconomic shocks to enterprise software budgets and unanticipated regulatory divergence between jurisdictions. Forecasts reflect assumptions about continued cloud migration momentum and stable hyperscaler pricing. Practitioners should monitor procurement committee consolidation patterns and generative AI capability announcements for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Live Chat Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Air Cargo Software Market
Software & Services
Sports League Management Software Market
Software & Services
Software Repository Market
Software & Services
Global Retail Management Systems Software Market
Software & Services
Labor Management Software Market
Software & Services
ID Photo Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Global Localization Software Market
Software & Services
Global Municipal Software Market
Software & Services
GCC Human Capital Management Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Lead Management Software Market
Software & Services
Statistics Software Market
Software & Services
United Kingdom HR Payroll Software Market