
 Curriculum Mapping Software Market | 2026-2036
Curriculum Mapping Software Market Size, Share, and Industry Trends Forecast 2026-2036
Curriculum Mapping Software Market Insights
Single-source procurement of legacy curriculum management systems is restructuring into multi-vendor cloud ecosystems across North American school districts. PowerSchool Group LLC leverages its established K-12 data infrastructure to extend into mapping workflows. Chalk Education Inc. competes through specialized assessment-linkage features that differentiate its platform from generalist learning management systems.
Curriculum mapping software constitutes a digital platform that codifies learning objectives, instructional sequences, and assessment benchmarks into searchable, cross-referenced databases with version control and alignment-scoring algorithms. Its primary purpose enables educational institutions to demonstrate standards compliance, close achievement gaps, and coordinate instruction across distributed faculty. Cloud-based deployment leads product type demand as districts abandon server maintenance burdens, while assessment management functionality captures the deepest margin pools due to integrated analytics requirements. K-12 schools remain the dominant end user segment though corporate training shows the fastest expansion as credentialing bodies mandate documented competency pathways.
The U.S. Department of Education's Every Student Succeeds Act accountability provisions, combined with state-level accreditation standards enforced by regional bodies like the Western Association of Schools and Colleges, compel institutions to maintain auditable curriculum documentation. GDPR and state student privacy laws including California's Student Online Personal Information Protection Act restrict cross-border data flows, forcing vendors to architect region-segregated hosting. Stakeholders must monitor how emerging AI-generated content detection requirements reshape mapping integrity standards and procurement criteria.
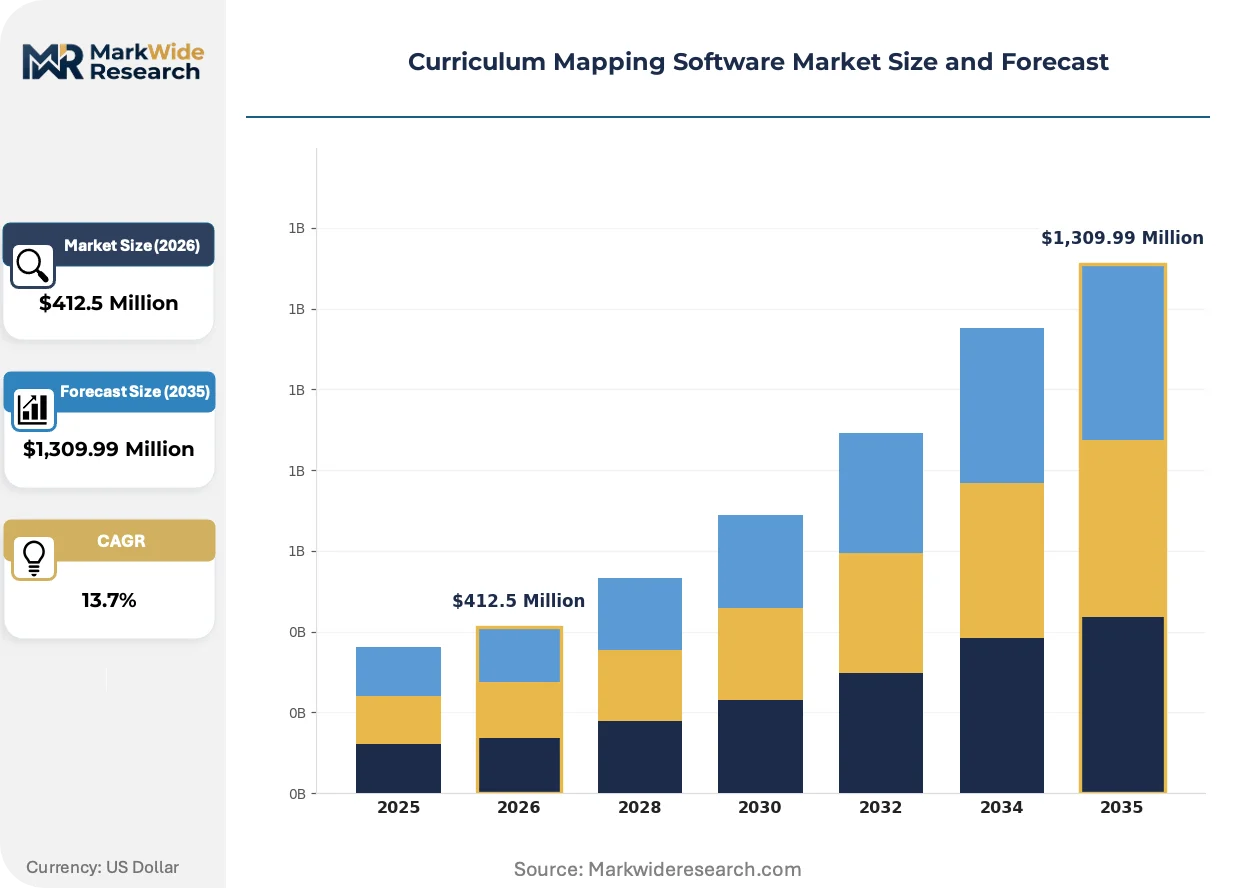
Market Dynamics
The U.S. Department of Education's outcome-based accountability mandates are forcing districts to replace opaque curriculum documentation with auditable, standards-aligned digital systems that trace student competencies through every instructional touchpoint.
Growth Catalysts
- ESSA Accountability Mandates:The Every Student Succeeds Act requires documented evidence of curriculum alignment to state standards, compelling K-12 districts to adopt traceable mapping platforms that satisfy federal audit requirements.
- Cloud Migration:Server maintenance burdens and cybersecurity liabilities are pushing institutions toward SaaS deployment models that offload infrastructure management to specialized vendors.
- California University Systems:The state's three-tier public higher education structure generates concentrated procurement volume for alignment tools that coordinate course sequencing across community colleges, state universities, and research institutions.
Market Restraints
- GDPR Data Localization:European student privacy protections restrict cross-border hosting of academic records, forcing vendors to architect region-segregated infrastructure that fragments platform economics.
- California SOPIPA Compliance:The Student Online Personal Information Protection Act imposes vendor liability for unauthorized data use, raising legal costs and limiting third-party integration flexibility.
- Legacy System Entrenchment:Decades-old student information systems in large urban districts create integration friction that prolongs sales cycles and inflates implementation costs.
Strategic Opportunities
- Corporate Credentialing Mandates:Professional certification bodies are requiring documented competency pathways, expanding addressable market beyond traditional academic institutions into workforce training.
- AI Content Detection Standards:Emerging requirements for verifying human-generated instructional materials are creating new product categories that map curriculum integrity against generative AI contamination.
- Assessment-Analytics Convergence:The integration of learning analytics with curriculum alignment tools is opening margin-rich service tiers that bundle predictive intervention recommendations.
Industry Challenges
- Instructional Design Talent Scarcity:The specialized skill set required to translate pedagogical frameworks into machine-readable competency taxonomies outpaces available practitioner supply.
- Multi-Vendor Integration Complexity:District procurement of best-of-breed point solutions creates interoperability burdens that strain IT departments and delay value realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curriculum Mapping Software Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,309.99 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Open Source End User: K-12 Schools, Higher Education, Tutoring Centers, Corporate Training Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Server-Based Functionality: Assessment Management, Resource Allocation, Course Development, Reporting Tools |
| Companies Covered | Chalk Education Inc., Eduphoria! Inc., Atlas Curriculum Mapping, Curriculum Trak, PlanbookEdu LLC, Rubicon International, OnCourse Systems for Education, PowerSchool Group LLC, Kiddom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curriculum Mapping Software Market Trends and Innovations
Generative AI capabilities are infiltrating curriculum development workflows, forcing platform vendors to pivot from static mapping repositories toward dynamic, adaptive systems that respond to real-time student performance data.
Natural language processing engines trained on academic standards corpora are electrifying the speed at which districts can align existing instructional materials to new state frameworks. California's largest unified districts are deploying these tools to retrofit legacy curricula rather than rebuild from scratch. The compression of alignment timelines from semester-long projects to weeks is reshaping vendor pricing models toward usage-based structures.
The U.S. Department of Education's pending guidance on AI-generated content in instructional materials is creating compliance uncertainty that favors vendors with built-in provenance tracking. District procurement officers are prioritizing platforms that can audit content authorship chains. This regulatory friction is accelerating consolidation around vendors with established data governance architectures.
Subscription fatigue among district technology budgets is fragmenting procurement authority from central IT to individual schools and departments. Site-based purchasing of specialized mapping modules is displacing district-wide enterprise licenses in Texas and Florida metropolitan systems. This decentralization favors nimble vendors with low-friction onboarding and modular pricing tiers.
Curriculum Mapping Software Market Segmentation
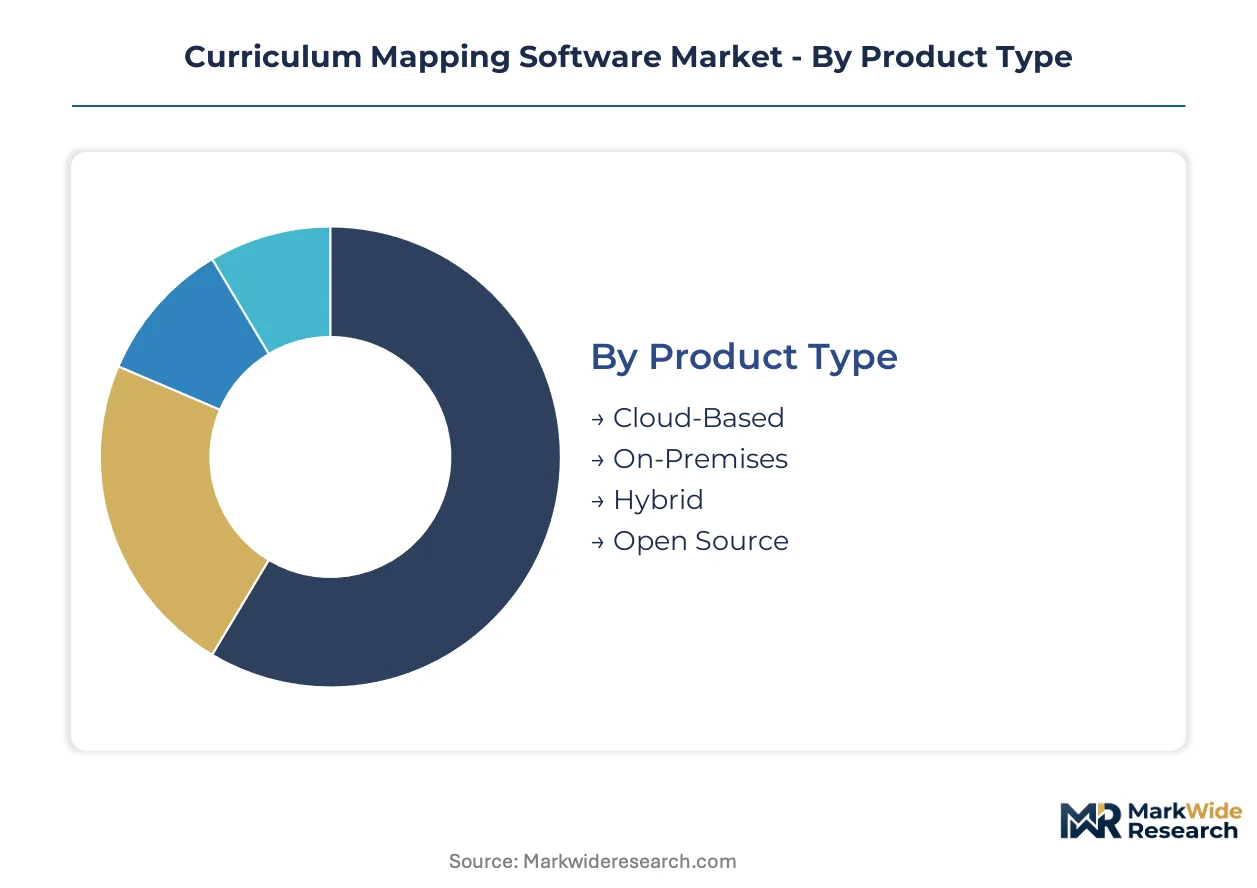
Curriculum mapping software segments diverge sharply in infrastructure requirements and buyer sophistication. Cloud-native architectures demand minimal capital outlay while on-premises systems require substantial server investment. Understanding these capital-intensity gradients reveals which vendor configurations align with district budget cycles and IT maturity levels.
Product Type:
Capital intensity varies dramatically across deployment architectures, with self-hosted systems demanding the heaviest upfront infrastructure commitment.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server procurement and maintenance burdens. California's university systems and large metropolitan districts concentrate demand here, driven by cybersecurity liability concerns and ESSA audit requirements for traceable standards alignment.
- On-Premises:Dedicated hardware installations demand substantial capital allocation for servers, backup systems, and IT staffing. Legacy-entrenched urban districts with decades-old student information systems maintain this preference due to integration friction with cloud platforms.
- Hybrid:Split architectures balance sensitive data local storage with cloud-based collaboration tools. Institutions with mixed compliance requirements across departments favor this middle-ground approach.
- Open Source:Community-developed platforms require internal development resources rather than licensing fees. Budget-constrained rural districts and specialized charter networks drive adoption here.
Cloud-Based absorbs the bulk of installed capacity; Open Source is expanding most quickly among resource-limited institutions.
End User:
Buyer sophistication and procurement authority shape segment boundaries, from centralized district IT to decentralized corporate L&D departments.
- K-12 Schools:District-wide implementations coordinate curriculum alignment across distributed faculty. Federal ESSA accountability mandates and state accreditation standards enforced by regional bodies like the Western Association of Schools and Colleges compel adoption of auditable mapping systems.
- Higher Education:Multi-campus coordination demands sophisticated course sequencing tools. California's three-tier public university structure generates concentrated procurement volume for alignment platforms spanning community colleges, state universities, and research institutions.
- Tutoring Centers:Boutique operations require lightweight, rapid-deployment solutions. Franchise networks and independent operators prioritize mobile accessibility and parent-facing progress dashboards.
- Corporate Training:Credentialing bodies mandate documented competency pathways. Professional certification organizations and enterprise L&D departments represent the steepest expansion trajectory as compliance requirements extend beyond traditional academic boundaries.
K-12 Schools anchor current revenue; Corporate Training climbs the fastest as workforce credentialing regulations tighten.
Deployment Model:
Data sovereignty requirements and integration complexity determine infrastructure choices across institutional types.
- Public Cloud:Shared infrastructure delivers economies of scale for standardized workloads. GDPR restrictions on cross-border academic records and California's SOPIPA student privacy law constrain deployment options for vendors without region-segregated hosting.
- Private Cloud:Dedicated tenant environments address stringent security requirements. Research institutions and healthcare-affiliated universities with HIPAA obligations concentrate demand in this segment.
- Hybrid Cloud:Sensitive records remain on-premises while collaborative features leverage cloud elasticity. Districts navigating legacy system entrenchment favor this transitional architecture.
- Server-Based:Fully localized installations persist where network reliability concerns or historical IT investment predominate. Remote rural districts with intermittent connectivity maintain this preference.
Public Cloud captures dominant share; Private Cloud gains share fastest among security-sensitive research institutions.
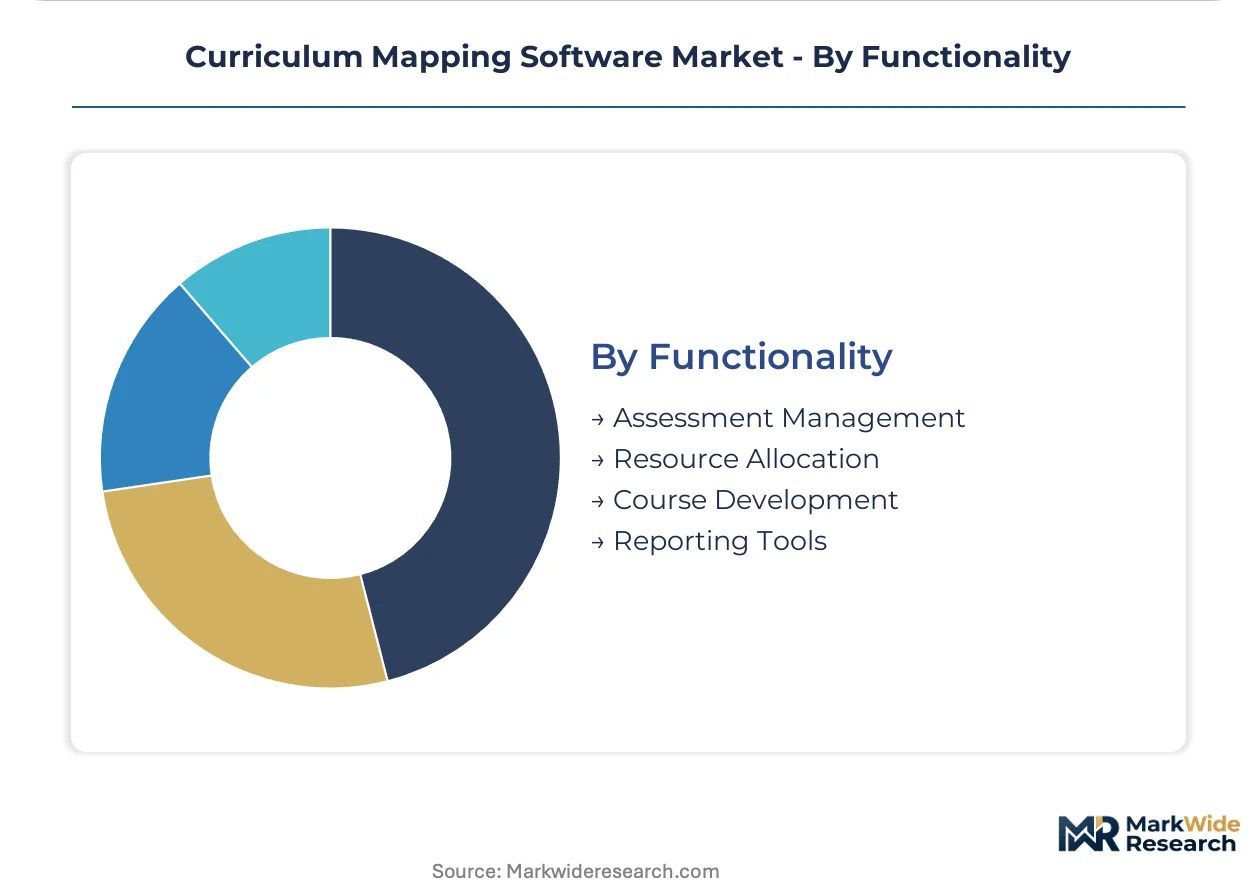
Functionality:
Integration depth with assessment systems and analytics engines determines margin capture and renewal rates.
- Assessment Management:Embedded analytics and predictive intervention recommendations command premium pricing. The convergence of learning analytics with alignment tools opens margin-rich service tiers that bundle competency tracking and early warning systems.
- Resource Allocation:Budget planning and staffing optimization modules address administrative pain points. Large unified districts facing teacher shortage pressures prioritize these capabilities.
- Course Development:Instructional design workflows and standards alignment engines accelerate curriculum retrofitting. Natural language processing tools trained on academic standards corpora are electrifying alignment speed in this segment.
- Reporting Tools:Compliance documentation and stakeholder dashboards satisfy audit requirements. Federal and state accountability mandates drive baseline demand across all buyer categories.
Assessment Management commands the deepest margin pools; Course Development shows the steepest adoption acceleration as AI-powered alignment tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure density in Northern California's Bay Area anchors curriculum mapping software development, with hyperscale data centers feeding SaaS platforms deployed across institutional networks worldwide.
United States
Federal ESSA accountability mandates and state accreditation standards enforced by regional bodies like the Western Association of Schools and Colleges drive district procurement of auditable mapping systems. The U.S. Department of Education's outcome-based accountability provisions compel traceable curriculum documentation. California's three-tier public university structure—spanning community colleges, California State University campuses, and University of California research institutions—generates concentrated procurement volume for course sequencing tools.
United Kingdom
GDPR restrictions on cross-border academic records force vendors to architect region-segregated hosting infrastructure that fragments platform economics. The Office for Students' quality assurance frameworks mandate documented learning outcomes alignment. London's edtech cluster and university consortiums in the Russell Group drive adoption of cloud-native curriculum coordination platforms.
Germany
The Kultusministerkonferenz coordinates curriculum standards across Länder, creating complex multi-jurisdictional alignment requirements for mapping vendors. Germany's federal data protection authority enforces strict student privacy protocols under BDSG. Bavaria's technical universities and Baden-Württemberg's vocational education networks represent concentrated demand for competency-tracking systems.
India
The National Education Policy's emphasis on outcome-based learning and credit transfer frameworks accelerates institutional demand for alignment tools. UGC and AICTE accreditation mandates require documented curriculum mapping for autonomous college status. Karnataka's Bangalore tech corridor and Maharashtra's Mumbai-Pune higher education belt host the densest concentration of platform deployments.
Australia
TEQSA's quality standards and the Australian Curriculum's cross-curriculum priorities compel schools to maintain auditable learning pathway documentation. The Privacy Act's APP guidelines restrict student data handling practices. New South Wales' Sydney education technology hub and Victoria's Melbourne university cluster anchor regional platform adoption.
Curriculum Mapping Software Market Competitive Landscape
Global majors compete with regional champions across deployment architecture and integration depth, with market structure tiering between established K-12 data infrastructure extenders and specialized assessment-linkage pure-plays. Consolidation pressures intensify as districts abandon single-source legacy procurement for multi-vendor cloud ecosystems. Three strategic archetypes dominate: platform extenders leveraging existing data infrastructure, specialized assessment-integrators, and modular point-solution vendors. Competitive moves center on M&A to acquire NLP alignment engines and strategic partnerships with regional accreditation bodies.
Within the platform extender archetype, PowerSchool Group LLC occupies a position anchored by established K-12 data infrastructure, while Chalk Education Inc. exemplifies the specialized assessment-linkage tier. Kiddom Inc. sits within the modular point-solution category serving decentralized district procurement patterns. These three represent the competitive spectrum from enterprise-scale integration to nimble site-based deployment.
| Leading Market Players |
|---|
| Chalk Education Inc. |
| Eduphoria! Inc. |
| Atlas Curriculum Mapping |
| Curriculum Trak |
| PlanbookEdu LLC |
| Rubicon International |
| OnCourse Systems for Education |
| PowerSchool Group LLC |
| Kiddom Inc. |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure costs cascade through curriculum mapping software pricing tiers, with hyperscale data center investments in Northern California's Bay Area feeding subscription models that stratify across premium analytics bundles, standard alignment modules, and economy-grade documentation tools for budget-constrained rural districts.
Pricing Analysis
Warranty and service bundling separates premium-tier vendors from stripped-down economy offerings, with comprehensive implementation support and dedicated customer success management included at the top tier while self-service onboarding dominates entry-level contracts. Three-tier pricing structure across premium, standard, and economy levels reflects integration depth with student information systems and assessment platforms. Pricing pressure stems from subscription fatigue fracturing district procurement authority toward site-based purchasing. K-12 IT departments exhibit highest price sensitivity due to competing technology budget demands, while corporate training divisions show lowest sensitivity given compliance mandate urgency.
Supply Chain Analysis
Direct-to-institution channels handle enterprise district and university system demand, while value-added resellers and regional education cooperatives serve decentralized school-level procurement. Software development concentrates in the United States, India, and the United Kingdom, with cloud infrastructure provisioning drawing from hyperscale providers with region-segregated hosting to satisfy GDPR and California SOPIPA requirements. Natural language processing engines and standards alignment algorithms constitute critical component dependencies. Single-source vulnerability in AI content detection licensing creates supply chain risk. Distribution runs through education technology procurement cooperatives and direct vendor sales teams to institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where Every Student Succeeds Act documentation mandates erect barrier-to-entry moats favoring vendors with established audit trail architectures and regional accreditation body partnerships.
For Market Incumbents: Hedge against modular point-solution disintermediation by acquiring natural language processing alignment engine specialists before pricing compression accelerates. Fortify data governance architectures to capture emerging AI-generated content detection procurement criteria. Deepen integration with legacy student information systems to prolong switching costs for entrenched urban districts.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in assessment-analytics bundles offers white-space entry for mid-tier vendors with predictive intervention capabilities. Target corporate training segments where credentialing body mandates outpace vendor supply. Pursue franchise tutoring network channel partnerships for rapid deployment volume without district sales cycle burdens.
For Investors and Strategic Acquirers: District procurement officer prioritization of provenance tracking capabilities is the leading indicator that AI content detection standards will consolidate vendor market share toward data governance leaders. Long-term viability centers on platforms with embedded analytics convergence and early warning system bundling. Monitor U.S. Department of Education AI guidance publication as inflection signal for compliance-driven procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of NLP Alignment Specialist | Accelerates retrofitting of legacy curricula to new state frameworks for California districts. |
| Regional Accreditation Body Partnership | Secures preferred vendor status with Western Association of Schools and Colleges and peer bodies. |
| AI Content Detection Module Launch | Addresses pending U.S. Department of Education guidance on generative AI instructional materials. |
| Corporate Credentialing Platform Extension | Captures workforce training demand from professional certification organizations beyond academic boundaries. |
| Site-Based Procurement Module Development | Aligns with Texas and Florida metropolitan district decentralization away from enterprise licenses. |
Research Methodology
Independent corroboration across district technology directors, curriculum coordinators, state procurement officers, and SaaS vendor product managers underwrites the qualitative findings in this study. Primary interviews with K-12 IT leadership, higher education registrar offices, and corporate learning and development executives combined with secondary validation from U.S. Department of Education ESSA documentation, state accreditation body standards, and California Student Online Personal Information Protection Act compliance filings. Bottom-up district adoption modeling and top-down addressable market sizing provided triangulation checks.
Rate-of-change decomposition across deployment architecture, end user sophistication, and functionality integration depth shaped the analytical framework. Segmentation dimensions modeled include cloud versus on-premises infrastructure, K-12 versus higher education versus corporate training buyer types, and assessment management versus course development capability tiers. CAGRs were derived from installed base growth trajectories and annual recurring revenue expansion patterns. Forecast inputs incorporated natural language processing maturity curves and AI content detection regulatory timeline assumptions.
Inputs from district technology budget surveys and vendor pricing disclosures were available through the study window; gaps in corporate training procurement transparency introduce uncertainty bands around that segment trajectory. Forecasts reflect documented assumptions regarding ESSA enforcement consistency and state accreditation standard harmonization. Practitioners should monitor U.S. Department of Education AI guidance publication and GDPR enforcement actions against academic data flows for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Lease Accounting and Management Software Market
Software & Services
Global Automotive Software Market
Software & Services
Retail Space Planning Software Market
Software & Services
Time and Attendance Software Market
Software & Services
Service Dispatch Software Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market
Software & Services
EDA Tools Market
Software & Services
Web Scraping Software Market
Software & Services
Tag Management Software Market
Software & Services
Trading Software Market
Software & Services
On-Call Scheduling Software Market
Software & Services
Photo Editing Software Market
Software & Services
Client Virtualization Software Market
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Global Nosql Software Market