
 Service Resource Planning (SRP) Saas Solutions Market | 2026-2036
Service Resource Planning (SRP) Saas Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Service Resource Planning (SRP) Saas Solutions Market Analytics
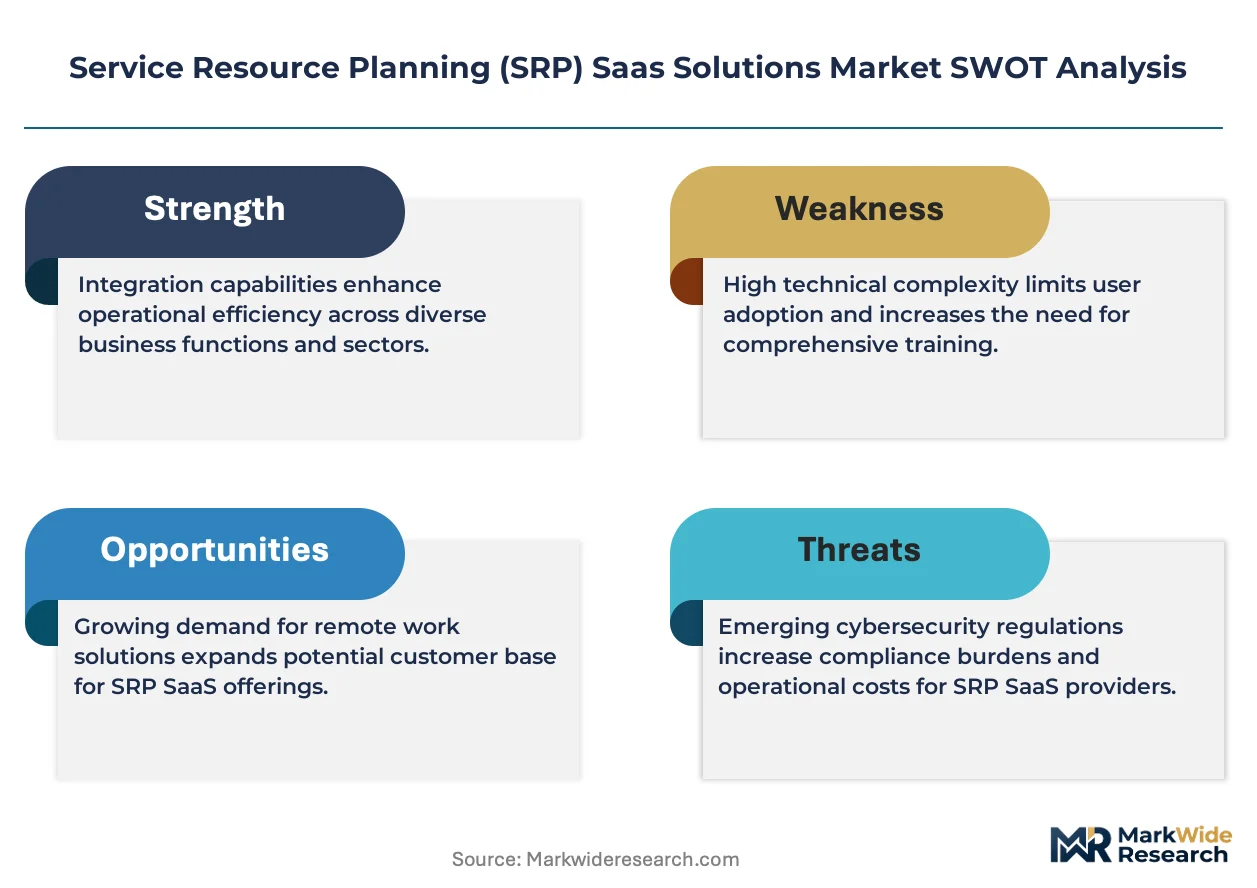
Multi-source vendor strategies is consolidating around platforms that unify professional services automation with enterprise resource planning. Oracle NetSuite leverages its native ERP architecture to anchor cloud-based SRP deployments for service-centric organizations. Salesforce Service Cloud competes through deep CRM connectivity that extends project pipelines into resource scheduling workflows. SAP Service Cloud differentiates via embedded analytics that sustain real-time utilization tracking across distributed service teams.
Service Resource Planning SaaS solutions constitute cloud-native software platforms that orchestrate project staffing, time capture, revenue recognition, and resource forecasting through multi-tenant architectures with API-first integration protocols. Their primary commercial purpose centers on replacing fragmented spreadsheets and legacy PSA tools with unified systems that improve utilization rates and project profitability. Public cloud deployments lead segment traction due to faster implementation cycles and lower capital requirements, while hybrid cloud configurations capture growth among regulated verticals requiring data residency controls. The industry vertical dimension shows healthcare and energy pulling ahead as buyers demand compliance-ready workforce planning against complex project backlogs.
ISO 27001 certification requirements shape vendor selection criteria for enterprise procurement teams evaluating SaaS platforms handling financial and personnel data. The EU AI Act and GDPR impose algorithmic transparency and data localization obligations on European deployments of automated resource allocation engines. In the United States, SOC 2 Type II attestations and sector-specific HIPAA safeguards govern healthcare implementations. Stakeholders must weigh interoperability commitments against emerging AI governance frameworks as automated scheduling and predictive staffing become standard platform capabilities.
Market Dynamics
Cloud-first mandates from enterprise IT departments are compressing implementation timelines and displacing legacy on-premises installations, forcing vendors to rearchitect deployment models around multi-tenant SaaS architectures with native API connectivity.
Growth Catalysts
- GDPR and EU AI Act compliance requirements:European enterprises are procuring certified SRP platforms that embed algorithmic transparency and data localization controls into workforce planning engines.
- Healthcare workforce optimization:HIPAA-covered entities are deploying integrated resource planning to manage clinical project staffing against complex compliance backlogs and reimbursement timelines.
- API-first integration protocols:Native connectivity with ERP and CRM systems is automating data flows between project delivery and financial operations, eliminating manual reconciliation.
Market Restraints
- Input cost concentration in hyperscale cloud infrastructure:AWS, Microsoft Azure, and Google Cloud pricing power constrains vendor margin flexibility for compute-intensive predictive analytics features.
- Data residency fragmentation:Divergent national data localization laws in Germany, France, and Switzerland force redundant infrastructure deployments that inflate operational overhead.
- Substitution by modular best-of-breed tools:Specialized project management and time-tracking applications threaten unified platform value propositions for smaller professional services firms.
Strategic Opportunities
- Underpenetrated mid-market segment in Italy and Spain:Professional services firms with 200-1,000 employees lack integrated resource planning and represent whitespace for verticalized SRP offerings.
- Convergence of AI/ML with resource forecasting:Predictive staffing algorithms trained on historical utilization patterns are enabling dynamic capacity planning that static spreadsheets cannot replicate.
- Channel innovation through system integrator partnerships:Accenture, Deloitte, and regional consultancies are building implementation practices that accelerate enterprise SRP adoption.
Industry Challenges
- ISO 27001 and SOC 2 Type II certification timelines:Six-to-twelve month attestation cycles delay vendor market entry and inflate pre-revenue engineering costs for security architecture.
- Integration complexity with legacy PSA tools:Data migration from fragmented spreadsheets and on-premises systems requires custom ETL pipelines that strain implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Resource Planning (SRP) Saas Solutions Market |
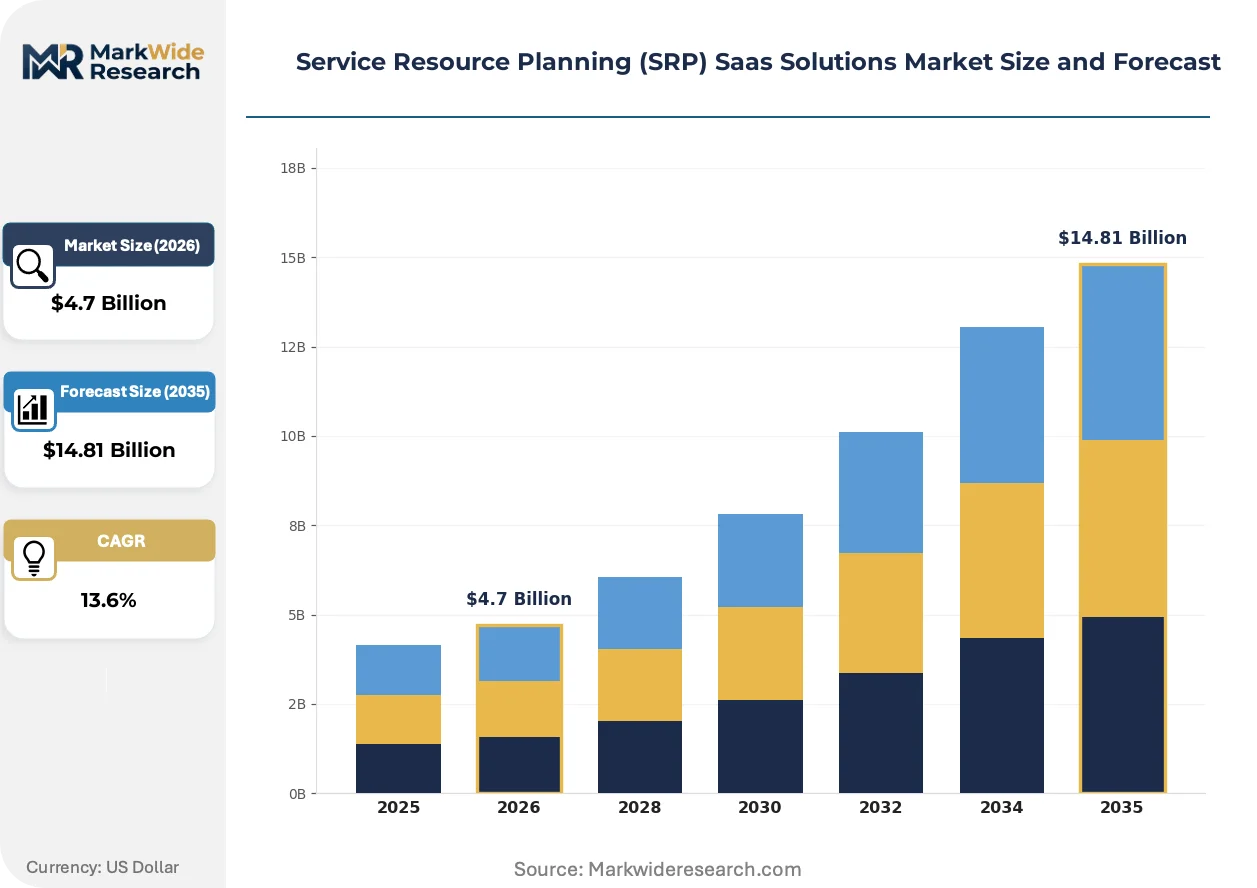
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Consulting, Implementation, Support, Maintenance Industry Vertical: Healthcare, Retail, Manufacturing, Energy End User: Small Businesses, Enterprises, Freelancers, Agencies |
| Companies Covered | Oracle NetSuite, Salesforce Service Cloud, SAP Service Cloud, Microsoft Dynamics 365 for Service, IFS Field Service Management, ServiceNow, Workday, FinancialForce, Kantata, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Resource Planning (SRP) Saas Solutions Market Evolving Landscape
Predictive analytics and embedded AI are compressing decision cycles across resource allocation, while regulatory pressure on algorithmic transparency is reshaping platform architecture requirements.
Machine learning-driven utilization forecasting is automating capacity planning for distributed service teams. Mid-to-large professional services firms in the United States are deploying these engines at eighteen-to-twenty-four month refresh cycles. The technology is automating manual spreadsheet-based resource matching that previously consumed partner-level attention.
EU AI Act algorithmic transparency mandates are forcing vendors to document automated scheduling decision logic. This regulatory pressure is accelerating investment in explainable AI modules that audit resource allocation rationale. Healthcare and energy verticals in Germany and France are demanding these capabilities to satisfy procurement compliance checkpoints.
Subscription-to-outcome pricing migration is altering vendor-customer contracting structures. Professional services buyers are negotiating utilization-rate guarantees rather than per-seat licenses, compressing vendor revenue recognition cycles. This shift is most visible among management consultancies in the United Kingdom and Netherlands seeking to align software costs with project margin performance.
Service Resource Planning (SRP) Saas Solutions Market Segmentation
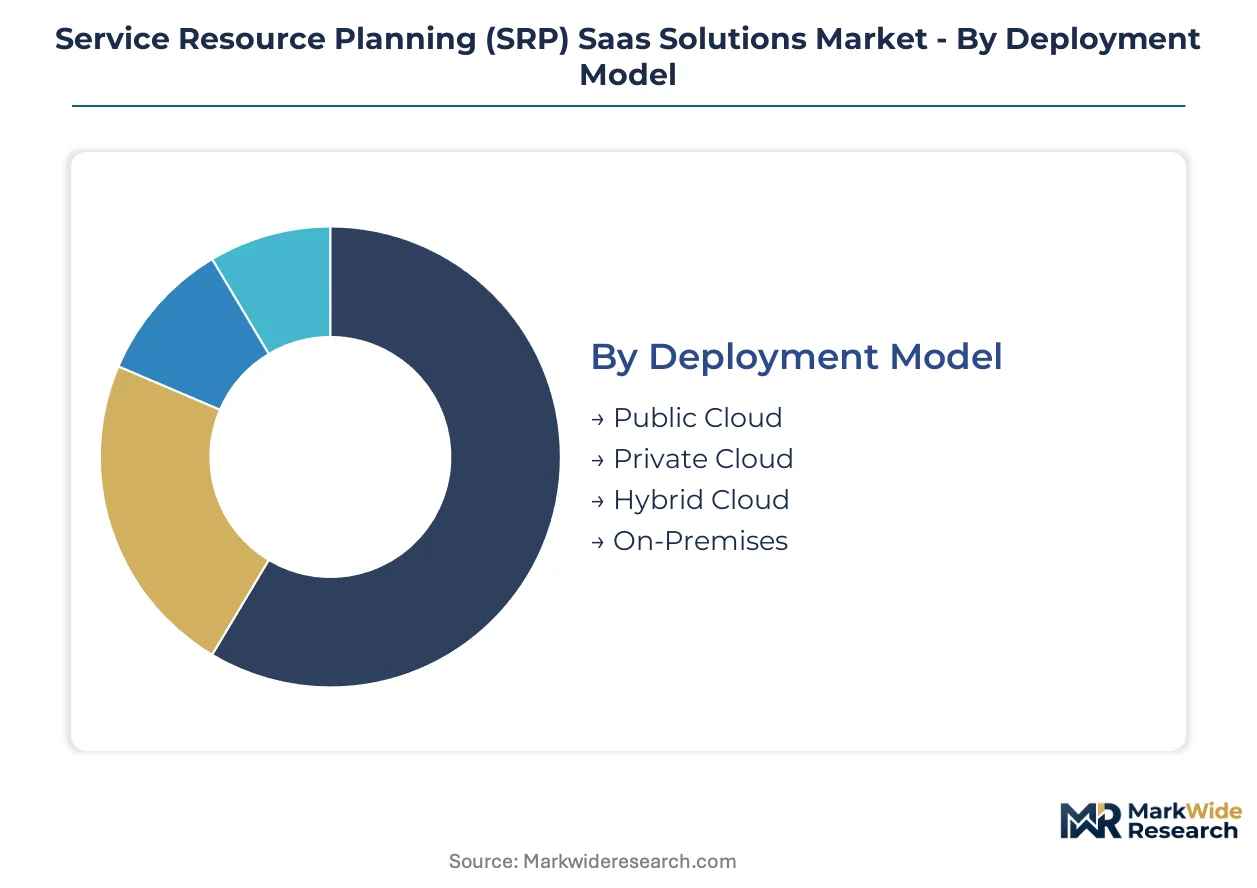
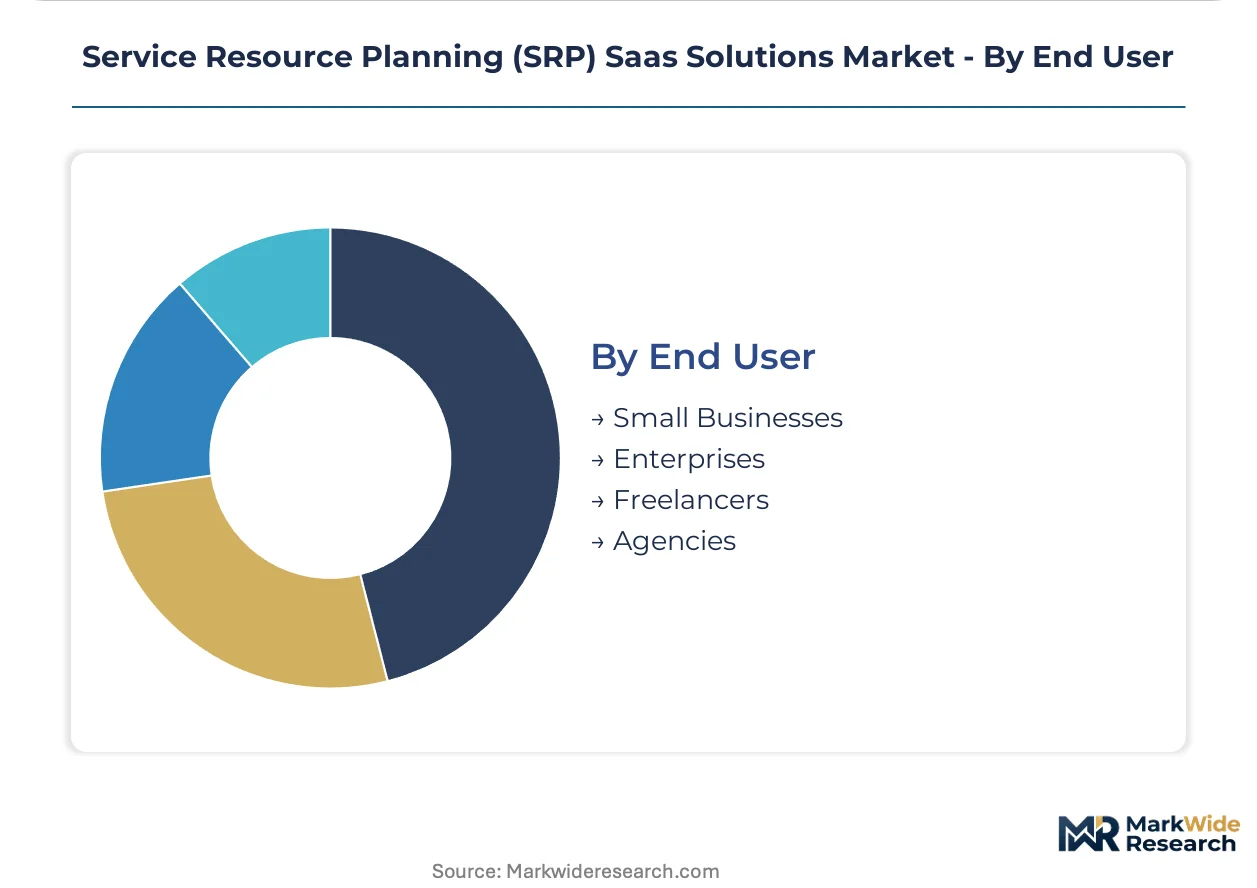
SRP SaaS buyers prioritize deployment flexibility, service depth, and vertical compliance when selecting platforms. Segmentation reveals how procurement criteria diverge across IT architecture preferences, professional services needs, and regulatory environments.
Deployment Model:
IT procurement teams weigh data sovereignty against implementation velocity when selecting infrastructure architectures.
- Public Cloud:Multi-tenant SaaS architectures deliver sub-90-day deployment cycles through AWS, Microsoft Azure, and Google Cloud infrastructure. Mid-to-large enterprises in the United States favor this model for workforce planning platforms requiring minimal capital expenditure and elastic compute scaling for predictive analytics workloads.
- Hybrid Cloud:Split architectures partition sensitive personnel data on private infrastructure while exposing scheduling APIs through public endpoints. Healthcare systems in Germany and France mandate this configuration to satisfy GDPR data localization requirements without sacrificing CRM connectivity.
- Private Cloud:Single-tenant dedicated environments serve defense contractors and government agencies with air-gapped security mandates.
- On-Premises:Legacy installations persist among regulated utilities requiring physical control over financial and HR data repositories.
Volume sits with Public Cloud; growth tilts toward Hybrid Cloud.
Service Type:
Professional services firms structure vendor relationships around internal technical capacity and project complexity.
- Implementation:System integrators configure ERP connectors, migrate historical utilization data, and establish forecasting workflows. Energy sector buyers in Texas and Alberta demand fixed-scope implementations tied to production deployment milestones rather than time-and-materials arrangements.
- Consulting:Change management specialists redesign staffing processes and train resource managers on predictive allocation tools. Retail chains expanding SRP footprints across multiple distribution centers rely on consulting engagements to standardize workforce planning methodologies.
- Support:Tiered helpdesk services address platform configuration issues and API troubleshooting for in-house IT teams.
- Maintenance:Subscription-based updates deliver security patches, compliance certifications, and feature releases on quarterly cycles.
Revenue concentrates in Implementation; margin expansion favors Consulting.
Industry Vertical:
Compliance requirements and project complexity dictate platform customization depth across buyer categories.
- Healthcare:HIPAA-covered entities deploy clinical workforce optimization against complex reimbursement timelines and credentialing backlogs. Hospital networks in California and New York prioritize platforms with pre-built compliance modules for shift scheduling and overtime tracking.
- Energy:Oilfield services and renewable project developers manage geographically dispersed teams across drilling sites and construction phases. Norwegian offshore operators and Texan solar EPC firms drive demand for mobile-first resource allocation with offline capability.
- Manufacturing:Discrete and process manufacturers synchronize shop-floor staffing with project-based engineering services.
- Retail:Seasonal workforce planning and multi-location staffing optimization dominate procurement criteria.
Contract value peaks in Healthcare; expansion velocity favors Energy.
End User:
Organizational scale determines feature requirements, integration complexity, and pricing model preferences.
- Enterprises:Fortune 500 professional services firms and healthcare systems deploy unified platforms across thousands of users with custom ERP connectors. These buyers negotiate outcome-based contracts linking software costs to utilization rate improvements and project margin targets.
- Agencies:Marketing and creative services firms with 50-200 employees prioritize rapid resource matching and client billing integration over advanced forecasting. London and Amsterdam-based agencies drive demand for subscription tiers with embedded CRM synchronization.
- Small Businesses:Independent consultancies and boutique firms adopt lightweight SRP modules through verticalized SaaS marketplaces.
- Freelancers:Solo practitioners utilize basic time-tracking and invoicing features within broader business management suites.
Revenue aggregates in Enterprises; subscriber acquisition concentrates in Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure concentration in Northern Virginia hyperscale campuses anchors North American SRP deployment velocity, while European data residency mandates reshape vendor architecture priorities across continental markets.
United States
Mid-to-large professional services firms in New York and Chicago drive demand for unified resource planning with embedded AI forecasting. HIPAA-covered hospital networks in California and Texas mandate SOC 2 Type II attestations for clinical workforce optimization platforms. The Boston metropolitan corridor concentrates SaaS vendor R&D operations alongside enterprise implementation partners.
Germany
Industrial engineering consultancies in Munich and Stuttgart require predictive staffing algorithms with EU AI Act-compliant explainability modules. The country's Federal Office for Information Security (BSI) shapes procurement criteria for cloud-based personnel data processing. Energy sector buyers in North Rhine-Westphalia deploy hybrid cloud configurations to satisfy GDPR localization requirements without sacrificing ERP connectivity.
United Kingdom
Management consultancies in London negotiate outcome-based contracts linking software costs to utilization rate improvements. The Financial Conduct Authority (FCA) influences data governance standards for SRP platforms serving financial services clients. The Thames Valley technology corridor hosts system integrator practices accelerating enterprise SRP adoption.
France
Healthcare workforce optimization demand concentrates among hospital networks in Île-de-France managing complex credentialing backlogs. The National Commission on Informatics and Liberty (CNIL) enforces algorithmic transparency obligations on automated resource allocation engines. Energy project developers in Provence-Alpes-Côte d'Azur deploy mobile-first resource allocation for distributed solar and offshore wind construction teams.
India
IT services firms in Bangalore and Hyderabad accelerate adoption of cloud-native SRP platforms to unify global project delivery operations. The country's Ministry of Electronics and Information Technology (MeitY) influences data localization requirements for personnel data processing. Mumbai-based system integrators build implementation practices serving mid-market professional services firms across the Asia-Pacific region.
Service Resource Planning (SRP) Saas Solutions Market Competitive Landscape
Platform consolidation through native ERP-CRM integration dominates the current landscape, compressing standalone PSA vendor margins. The vendor base organizes around three strategic archetypes: cloud-native ERP extenders, CRM-anchored workflow platforms, and verticalized professional services specialists. M&A activity concentrates on acquiring predictive analytics capabilities, while strategic partnerships with system integrators accelerate enterprise penetration.
Within the ERP-extender tier, Oracle NetSuite and SAP Service Cloud exemplify architectures that embed resource planning within broader financial operations. Salesforce Service Cloud occupies a position representing CRM-anchored competitive positioning, extending project pipelines into scheduling workflows. These three entities anchor the premium-tier segment where procurement teams prioritize pre-built integration protocols over best-of-breed modular alternatives.
| Leading Market Players |
|---|
| Oracle NetSuite |
| Salesforce Service Cloud |
| SAP Service Cloud |
| Microsoft Dynamics 365 for Service |
| IFS Field Service Management |
| ServiceNow |
| Workday |
| FinancialForce |
| Kantata |
| Others |
Value Network & Pricing Analysis
Hyperscale cloud infrastructure pricing indices from AWS, Microsoft Azure, and Google Cloud cascade through SRP SaaS vendor cost structures, compressing margin flexibility for compute-intensive predictive analytics tiers while forcing tiered subscription packaging that separates enterprise-grade AI forecasting from basic resource scheduling modules.
Pricing Analysis
Implementation service bundling distinguishes premium deployments from unbundled self-service tiers, with system integrator partnerships commanding fixed-scope premiums in energy sector procurements. Three-tier pricing structure across premium, standard, and economy levels segments by AI forecasting depth, API call volume, and vertical compliance certification. Cost compression in the standard tier intensifies because hyperscale compute pricing limits vendor margin flexibility. Small professional services firms exhibit highest price sensitivity, while Fortune 500 enterprises prioritize outcome-based contracts over per-seat economics.
Supply Chain Analysis
Customer data migration and legacy system decommissioning flows create reverse-logistics complexity for SRP vendors managing on-premises PSA tool retirements. Cloud infrastructure supply concentrates in the United States, Ireland, and Singapore hyperscale regions, with compute and storage capacity anchoring platform delivery. Vendor operations draw from API gateway services, machine learning training clusters, and compliance certification pipelines. Single-source vulnerability in hyperscale provider concentration threatens operational continuity. Distribution runs through direct enterprise sales teams and Accenture, Deloitte, and regional system integrator channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation accelerates as API-first integration mandates and ISO 27001 certification timelines force subscale vendors toward acquisition or exit, concentrating competitive capacity among ERP-native and CRM-anchored architectures.
For Market Incumbents: Deepen vertical integration into healthcare and energy compliance modules to defend against modular best-of-breed substitution. Anchor cloud-native forecasting capabilities within pre-built ERP connectors that accelerate implementation velocity. Prioritize SOC 2 Type II and EU AI Act certification investment to extend procurement eligibility across HIPAA-covered entities and European industrial consultancies. For New Entrants and Emerging Players: Enter via underpenetrated mid-market professional services firms in Italy and Spain with 200-1,000 employees lacking integrated resource planning. Target whitespace in mobile-first resource allocation for geographically dispersed energy construction teams. Build implementation partnerships with Mumbai-based system integrators serving Asia-Pacific mid-market expansion. For Investors and Strategic Acquirers: Distressed-cycle entries favor verticalized SRP specialists with pre-built healthcare credentialing modules in Germany and France facing EU AI Act compliance cost burdens. Long-term viability hinges on predictive analytics differentiation and system integrator channel density. Monitor hyperscale cloud pricing negotiations and GDPR enforcement patterns as margin inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native ERP-CRM connectivity eliminates manual reconciliation for Oracle NetSuite and Salesforce deployments. |
| Acquisition of Specialist Firm | Predictive analytics capabilities compress resource allocation decision cycles for mid-to-large enterprises. |
| Strategic Partnership | Accenture and Deloitte implementation practices accelerate enterprise SRP adoption across healthcare systems. |
| Geographic Expansion | Hybrid cloud configurations capture growth among German and French healthcare buyers requiring GDPR data residency. |
| Product Launch | Explainable AI modules satisfy EU AI Act algorithmic transparency mandates for automated scheduling engines. |
Research Methodology
Multi-period observation of SRP platform deployment cycles, certification timelines, and vendor pricing migrations anchored the trend analysis, supplemented by interviews with CTOs at professional services firms, IT procurement officers at healthcare systems, platform engineers at cloud-native vendors, and integration specialists at system integrators. Secondary validation drew from SEC filings of publicly traded SaaS vendors, hyperscaler capex disclosures, ISO 27001 certification registries, and EU AI Act implementation guidance. Bottom-up vendor revenue triangulation against top-down enterprise IT spending estimates refined market sizing.
Input-output matrices mapped deployment model preferences, organization size tiers, vertical compliance requirements, and regional adoption patterns across the projection horizon. Segmentation dimensions modeled include public-hybrid-private cloud architecture, professional services firm scale, healthcare-energy-manufacturing verticals, and North American-European-Asia-Pacific regulatory clusters. CAGRs derived from elasticity-adjusted demand curves incorporating API integration velocity and AI governance implementation rates.
Revisions become necessary when hyperscale cloud pricing volatility, GDPR enforcement escalation, or EU AI Act algorithmic audit mandates materialize outside baseline assumptions. Practitioners should monitor hyperscale infrastructure cost indices, BSI and CNIL regulatory guidance updates, and system integrator partnership announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Africa Sports Management Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Driver Updater Software Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Collaboration Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Business Productivity Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
Mind Mapping Software Market
Software & Services
Online Project Management Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Global Travel and Expense Management Software Market