
 Petcare Software Market | 2026-2036
Petcare Software Market Size, Share, and Industry Trends Forecast 2026-2036
Petcare Software Market Analysis
Enterprise-grade reliability is collapsing the gap between basic scheduling tools and full-stack practice management platforms. DaySmart Software leverages its vertical focus on service-based industries to sustain platform stickiness among grooming chains. Gingr anchors its position through specialized boarding and daycare workflow automation. PetExec Inc. differentiates via integrated payment processing and client communication modules.
Petcare software comprises digital platforms that coordinate appointment scheduling, medical record storage, billing automation, and client engagement for animal health and wellness businesses. These systems typically operate on cloud architectures with API connectivity to diagnostic equipment and pharmacy networks, enabling real-time data synchronization across distributed clinic locations. Management Software leads solution type adoption as multi-location veterinary groups consolidate fragmented operational tools. Cloud-Based deployment is displacing on-premise installations among mid-market grooming services seeking lower IT overhead. Booking Systems represent the fastest-growing feature category as mobile-first pet owners expect self-service reservation capabilities.
The FDA's Center for Veterinary Medicine scrutinizes software handling prescription management and diagnostic imaging, while HIPAA-adjacent state privacy laws govern client data protection in cross-border telehealth consultations. ISO 27001 certification has become a de facto procurement filter for enterprise veterinary groups evaluating vendor security posture. Stakeholders must weigh compliance automation investments against the margin compression from commoditized scheduling features.
Market Dynamics
Cloud migration is compressing the competitive moat between legacy on-premise veterinary systems and API-native platforms, forcing incumbent vendors to rearchitect core billing and medical record modules or cede mid-market accounts to vertical SaaS specialists.
Growth Catalysts
- HIPAA-adjacent state privacy mandates:Veterinary groups in California, Texas, and Florida face escalating client data protection requirements, driving procurement of ISO 27001-certified platforms with automated audit trails.
- Multi-location practice consolidation:Regional veterinary roll-ups demand centralized inventory management and cross-clinic scheduling, creating pull for cloud-native practice management suites with real-time synchronization.
- Telehealth reimbursement expansion:State-level veterinary telemedicine parity laws in New York, Colorado, and Washington mandate digital consultation documentation, accelerating adoption of integrated video and EHR workflows.
Market Restraints
- Input cost volatility in payment processing:Interchange fee compression and PCI-DSS compliance audits squeeze margins for platforms bundling integrated merchant services with core software subscriptions.
- Technical debt in legacy data migration:Decades of unstructured medical imaging and handwritten clinical notes resist automated extraction, prolonging implementation timelines for cloud conversions.
- Regulatory friction from FDA Center for Veterinary Medicine:Software handling prescription workflows faces 510(k) equivalence determinations and software-as-medical-device classification delays, extending go-to-market cycles.
Strategic Opportunities
- Underpenetrated rural veterinary networks:Solo practitioners in Montana, Wyoming, and the Dakotas operate on paper-based systems, presenting white space for mobile-first, low-bandwidth practice management tools.
- Behavioral health and wellness tracking:Integration of wearable pet activity monitors with EHR platforms enables preventive care subscription models beyond reactive clinical visits.
- Distribution innovation through veterinary buying groups:Cooperative purchasing organizations negotiate enterprise software licenses on behalf of independent clinics, creating channel leverage for vendors with group contract frameworks.
Industry Challenges
- Veterinary informatics talent scarcity:Cross-functional professionals fluent in both clinical workflows and HL7-FHIR interoperability standards command premium compensation, constraining vendor R&D velocity.
- Integration complexity with diagnostic equipment:Proprietary DICOM implementations from imaging manufacturers fragment API connectivity, requiring costly custom middleware development for each equipment partnership.
- Compliance timeline compression:State board of veterinary medicine rulemaking on telehealth credentialing outpaces software update cycles, forcing reactive feature development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petcare Software Market |
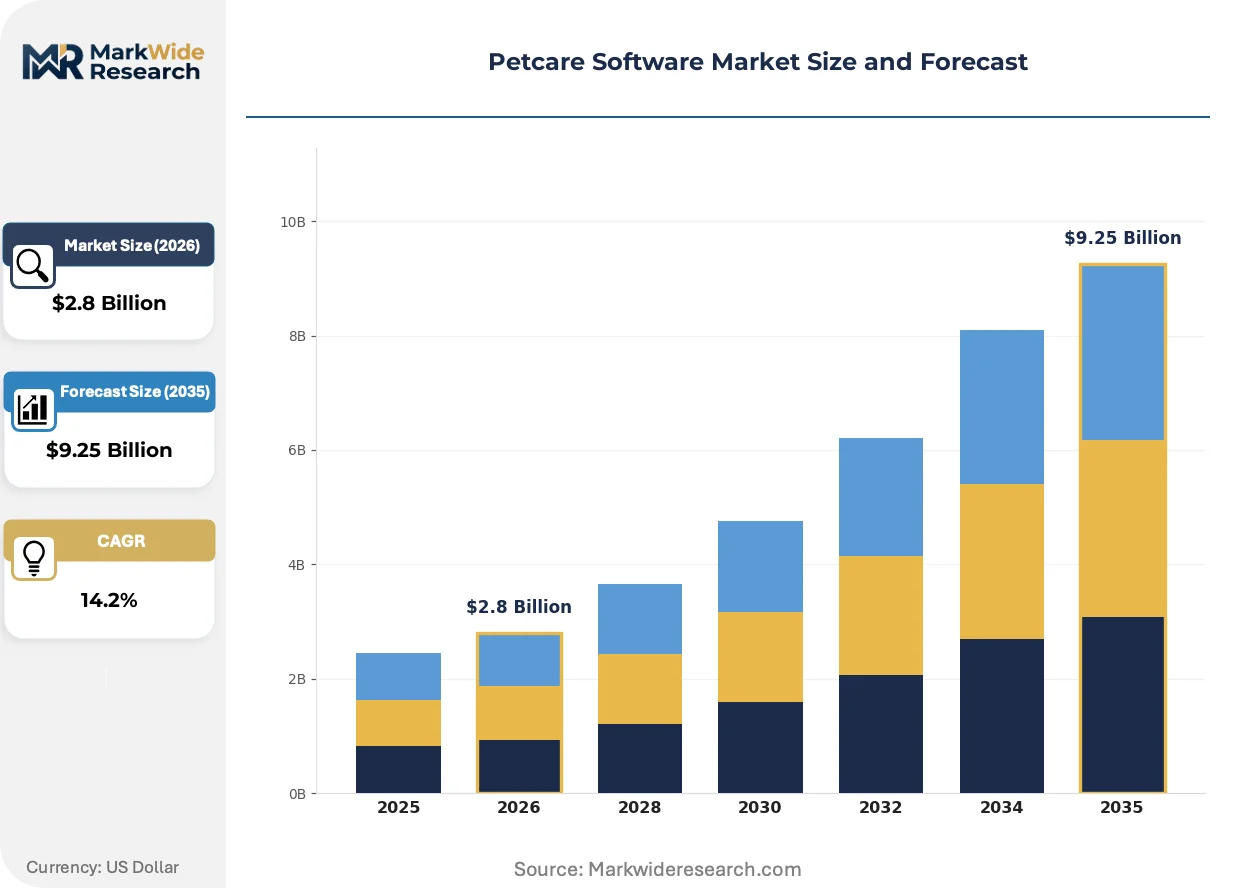
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Management Software, Booking Systems, Payment Processing, Digital Marketing End User: Pet Owners, Veterinary Clinics, Pet Grooming Services, Dog Walkers Deployment Model: Cloud-Based, On-Premise, Hybrid, Mobile Application Feature: Inventory Management, Appointment Scheduling, Client Communication, Reporting Tools |
| Companies Covered | 123Pet Software, Kennel Connection, Time To Pet, Gingr, PetExec Inc., DaySmart Software, Shepherd Software, Dog Biz Pro, PawLoyalty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petcare Software Market Emerging Trajectories
Artificial intelligence is embedding into diagnostic workflows and client communication channels, compressing the gap between data capture and clinical decision support while reshaping how practices allocate technical staff hours.
Large language models trained on veterinary corpora are displacing template-based clinical note generation, enabling veterinarians at emergency and specialty hospitals to produce structured SOAP notes from voice dictation in under thirty seconds. Platforms deploying this capability report measurable reductions in after-hours documentation burden. The technology is displacing traditional medical scribe services and compressing per-visit labor costs for high-volume emergency practices.
The FDA Center for Veterinary Medicine's draft guidance on predetermined change control plans for machine learning-enabled diagnostic software signals tighter post-market surveillance obligations. Device manufacturers must now submit algorithm update protocols as part of initial 510(k) submissions, lengthening regulatory pathways. Imaging AI vendors serving referral hospitals are responding by segregating locked-base algorithms from continuous-learning modules to isolate regulatory exposure.
Subscription unbundling is fragmenting the traditional all-in-one practice management procurement model, with grooming and boarding operators selecting best-of-breed scheduling tools separate from medical record systems. Mobile-first pet owners driving this shift expect self-service booking interfaces comparable to human wellness platforms. The pattern is most visible in metropolitan markets where single-location luxury pet hotels compete on digital experience rather than clinical integration depth.
Petcare Software Market Segmentation
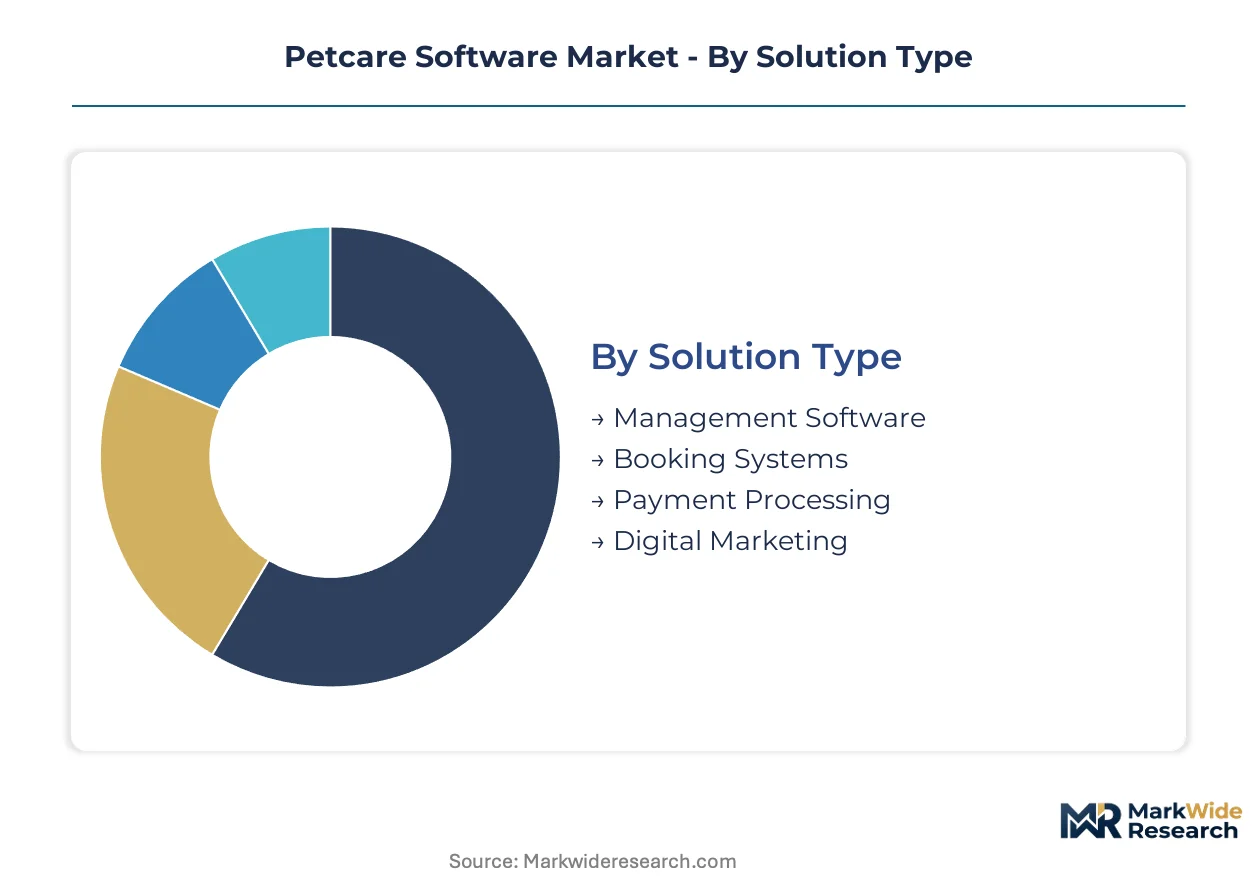
Petcare software procurement follows distinct regulatory and operational logic across solution categories. Veterinarians prioritize FDA-compliant prescription workflows while grooming chains optimize for payment integration and client retention metrics.
Solution Type:
FDA Center for Veterinary Medicine oversight separates prescription-capable platforms from wellness-only tools, creating procurement friction for multi-service operators.
- Management Software:Full-stack platforms coordinate medical records, billing, and inventory across distributed clinic locations. Regional veterinary roll-ups in Texas and Florida centralize operations on these systems to satisfy state audit requirements for multi-site practices.
- Booking Systems:Self-service reservation interfaces dominate metropolitan grooming markets where mobile-first pet owners expect instant confirmation. New York and Colorado operators report higher client acquisition rates after deploying consumer-grade scheduling portals.
- Payment Processing:Integrated merchant services reduce checkout friction for high-volume daycare facilities.
- Digital Marketing:Automated client outreach tools target retention for subscription-based wellness programs.
Established volume favors Management Software; emerging adoption favors Booking Systems.
End User:
Customer technical sophistication spans paper-based solo practitioners to enterprise IT departments, fragmenting pricing power across the vendor base.
- Veterinary Clinics:Multi-location groups demand ISO 27001-certified cloud platforms with HL7-FHIR interoperability for diagnostic equipment integration. California practices face the strictest state-level data protection mandates, filtering vendor selection toward compliance-automation specialists.
- Pet Owners:Direct-to-consumer wellness apps leverage wearable device APIs for preventive care subscriptions. Washington and Colorado telehealth parity laws enable video consultation reimbursement, accelerating platform development.
- Pet Grooming Services:Booking-centric operators prioritize low-bandwidth mobile tools over clinical depth.
- Dog Walkers:Solo operators drive demand for lightweight scheduling without EHR complexity.
Revenue concentration sits with Veterinary Clinics; user growth velocity clusters around Pet Owners.
Deployment Model:
Infrastructure preferences split along rural-urban connectivity divides and legacy system replacement cycles.
- Cloud-Based:Real-time synchronization enables cross-clinic scheduling for consolidated veterinary groups. Montana and Wyoming solo practitioners remain underserved due to bandwidth constraints, creating white space for low-latency architectures.
- Mobile Application:Field-based dog walkers and house-call veterinarians depend on offline-capable native apps. Dakota-based mobile practitioners prioritize GPS-integrated routing over desktop functionality.
- On-Premise:Legacy server installations persist in security-sensitive specialty hospitals.
- Hybrid:Mixed architectures bridge cloud convenience with local imaging storage for large files.
Cloud-Based deployments dominate new procurement; Mobile Application represents the steepest expansion trajectory.
Feature:
Module unbundling allows operators to assemble best-of-breed stacks rather than accepting monolithic suites.
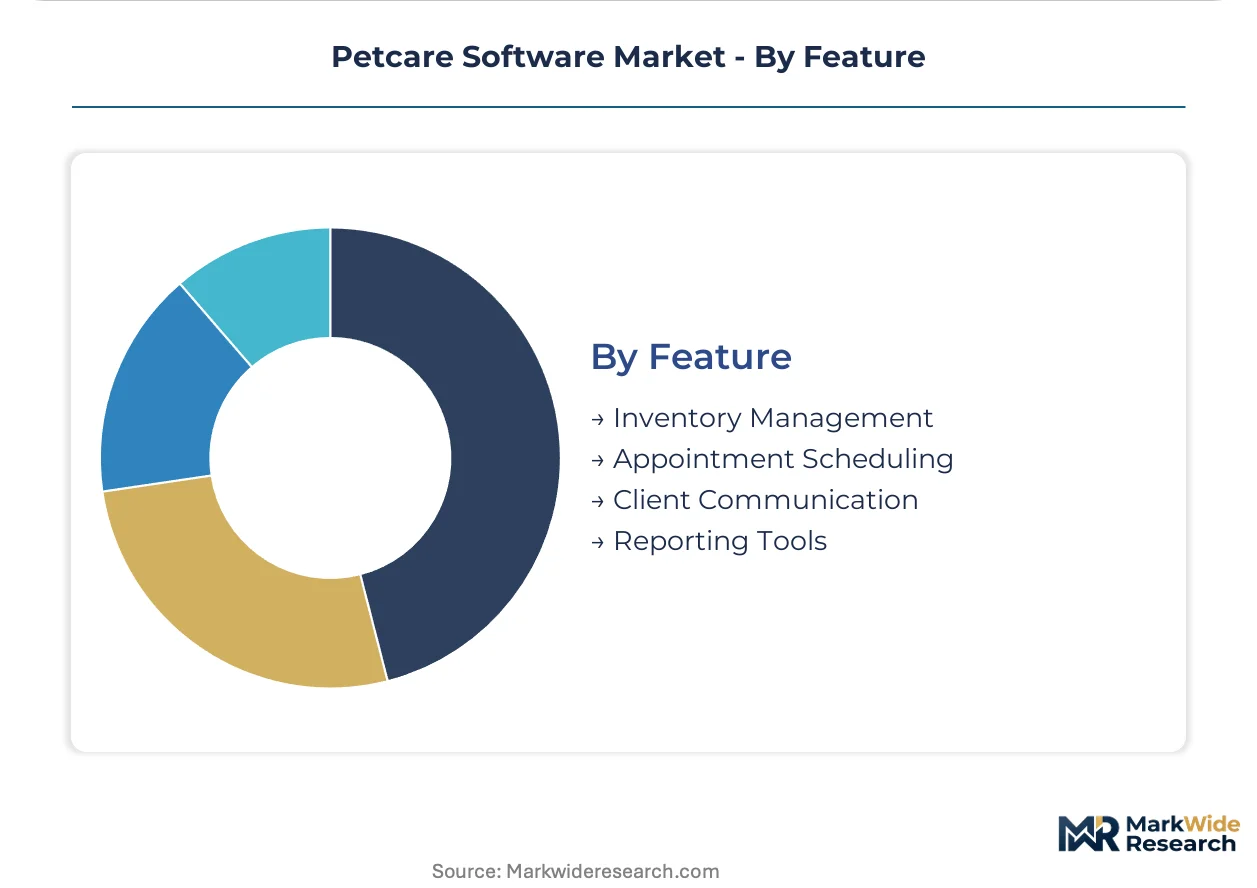
- Appointment Scheduling:Self-service booking portals reduce front-desk labor costs for high-volume grooming chains. Texas and Florida operators report 30% reduction in no-shows after deploying automated reminder sequences.
- Client Communication:Two-way messaging and telehealth video integrate with EHR documentation to satisfy state veterinary board audit requirements. New York's telemedicine credentialing rules mandate encrypted consultation logs, favoring platforms with native compliance tooling.
- Inventory Management:Automated reordering prevents stockouts for vaccine-dependent practices.
- Reporting Tools:Financial analytics support acquisition due diligence for regional roll-ups.
Feature adoption clusters on Appointment Scheduling; regulatory pressure accelerates Client Communication deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investment and veterinary practice consolidation patterns concentrate software demand in specific national markets. Regulatory divergence across jurisdictions fragments vendor compliance requirements. Metropolitan pet ownership density and digital payment penetration determine platform economics.
United States
Multi-location veterinary roll-ups in Texas and Florida drive enterprise software procurement for centralized inventory management. The FDA Center for Veterinary Medicine enforces 510(k) requirements on prescription management modules, extending vendor certification timelines. California practices face the strictest state-level data protection mandates, filtering vendor selection toward ISO 27001-certified platforms with automated audit trails.
Germany
Specialty veterinary hospitals in Bavaria and North Rhine-Westphalia demand HL7-FHIR interoperability for diagnostic equipment integration. The EU AI Act imposes conformity assessments on machine learning-enabled diagnostic software, segregating locked-base algorithms from continuous-learning modules. Berlin-based practice groups consolidate operations on cloud-native suites to satisfy GDPR cross-border data transfer requirements.
United Kingdom
Corporate veterinary chains in Greater London and the Southeast prioritize client communication modules with encrypted telehealth documentation. The Information Commissioner's Office enforces veterinary data protection standards parallel to human healthcare GDPR extensions. Manchester and Birmingham grooming operators adopt best-of-breed scheduling tools separate from medical record systems.
Japan
Metropolitan Tokyo and Osaka veterinary clinics integrate wearable pet activity monitors with EHR platforms for preventive care subscriptions. METI guidelines on software-as-medical-device classification create regulatory friction for AI diagnostic tools. Yokohama-based specialty hospitals maintain hybrid cloud-on-premise architectures for large imaging file storage.
Australia
Sydney and Melbourne multi-location practices accelerate cloud migration to enable real-time synchronization across distributed clinics. The Therapeutic Goods Administration scrutinizes software handling prescription workflows with medical device classification protocols. Brisbane grooming chains prioritize low-bandwidth mobile tools for field-based operations.
Petcare Software Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Full-stack practice management vendors compete with specialized point-solution providers across scheduling, boarding, and payment processing segments. Strategic archetypes include vertical SaaS specialists, horizontal platform extenders, and legacy on-premise incumbents rearchitecting for cloud delivery. M&A activity concentrates among regional veterinary roll-ups seeking unified technology stacks, while API-native platforms pursue partnership networks with diagnostic equipment manufacturers.
Within the vertical specialist tier, Gingr and PetExec Inc. exemplify focused workflow automation for boarding and daycare operations. DaySmart Software occupies a position bridging service-industry horizontal platforms with petcare-specific feature depth. These three companies represent distinct approaches to client retention: specialized operational tooling, integrated payment processing, and cross-vertical platform stickiness.
| Leading Market Players |
|---|
| 123Pet Software |
| Kennel Connection |
| Time To Pet |
| Gingr |
| PetExec Inc. |
| DaySmart Software |
| Shepherd Software |
| Dog Biz Pro |
| PawLoyalty |
| Others |
Supply Flow & Price Mechanics
ISO 27001 certification gates both vendor qualification and subscription tier differentiation, forcing mid-market veterinary groups to pay premium rates for automated audit trails while budget-conscious groomers accept stripped-down scheduling tools without compliance automation.
Pricing Analysis
FDA Center for Veterinary Medicine oversight dictates the pricing tier structure across prescription-capable platforms, with 510(k)-certified modules commanding substantial premiums over wellness-only alternatives. Three-tier pricing structure across premium, standard, and economy levels separates enterprise multi-location suites with HL7-FHIR interoperability from basic cloud scheduling tools. Cost compression in the standard tier is intensifying because payment processing margin squeeze and PCI-DSS audit requirements erode bundled merchant service profits. Solo practitioners in bandwidth-constrained rural markets exhibit highest price sensitivity, while consolidated veterinary roll-ups absorb premium pricing for centralized inventory and cross-clinic synchronization capabilities.
Supply Chain Analysis
The United States and Germany anchor cloud infrastructure and diagnostic equipment integration development for veterinary software platforms. Software-as-a-service delivery draws from hyperscaler compute capacity, API middleware libraries, and specialized DICOM parsing engines. Single-source vulnerability concentrates in proprietary imaging manufacturer protocols, which fragment connectivity and force costly custom development for each equipment partnership. Distribution runs through veterinary buying groups and cooperative purchasing organizations that negotiate enterprise licenses on behalf of independent clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional professionals fluent in both clinical workflows and interoperability standards command premium compensation, constraining vendor R&D velocity and creating acquisition premiums for teams with proven integration experience.
For Market Incumbents: Shield market position by accelerating backward integration into diagnostic equipment API partnerships before imaging manufacturers consolidate connectivity standards. Invest in ISO 27001 certification automation to capture procurement filters from California and Texas multi-location roll-ups facing state-level data protection mandates. Prioritize locked-base algorithm architectures that segregate continuous-learning modules from FDA-regulated diagnostic cores. For New Entrants and Emerging Players: Mobile-first, low-bandwidth practice management tools for Montana, Wyoming, and Dakota solo practitioners represent an underserved service-layer gap where paper-based operations persist. Target rural veterinary networks with offline-capable native apps featuring GPS-integrated routing over desktop functionality. Pursue channel partnerships with regional veterinary buying groups to bypass direct enterprise sales cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native platform segments as containerized deployment reduces infrastructure overhead per customer. Long-term viability favors vendors with demonstrated FDA 510(k) clearance velocity and established group purchasing organization contract frameworks. Watch for state telemedicine parity law expansion as signal for integrated video consultation platform valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7-FHIR connectivity to diagnostic equipment enables real-time medical record synchronization across distributed clinic locations. |
| Acquisition of Specialist Firm | Targeted purchases of DICOM middleware developers resolve proprietary imaging protocol fragmentation for referral hospitals. |
| Strategic Partnership | Veterinary buying group alliances create channel leverage and accelerate enterprise license penetration among independent clinics. |
| Product Launch | Voice-dictated SOAP note generation using large language models reduces after-hours documentation burden for emergency practices. |
| Geographic Expansion | Low-bandwidth mobile-first tools capture white space in rural Montana and Wyoming markets underserved by cloud-heavy incumbents. |
Methodological Framework
A standing panel of veterinary practice managers, IT procurement officers at multi-location groups, diagnostic equipment integration specialists, and state veterinary board regulators provided ongoing calibration throughout data collection. Primary interviews with cloud platform vendors and grooming chain operators combined with secondary validation against FDA Center for Veterinary Medicine guidance documents, state board of veterinary medicine rulemaking records, and ISO certification databases. Bottom-up deployment estimates and top-down market sizing triangulated against hyperscaler petcare vertical revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation modeling incorporated solution type, deployment model, end-user technical sophistication, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to adoption rate data, with cross-clinic scheduling demand and telehealth reimbursement expansion serving as key forecast inputs.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine oversight and state veterinary telemedicine parity regimes; material policy shifts would require re-modeling of prescription workflow and video consultation adoption trajectories. Recalibration cycles align with material shifts in multi-location practice consolidation patterns and diagnostic equipment manufacturer API standardization initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Printing Software Market
Software & Services
Global Local SEO Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Global Jewelry Store Management Software Market
Software & Services
HR Saas Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Productivity Management Software Market
Software & Services
Global Job Evaluation Software Market
Software & Services
Neurodiverse Workforce Productivity Tools Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
Multiexperience Development Platforms Market
Software & Services
Global API Management Software Market
Software & Services
Test Automation Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Metal Fabrication Software Market