
 Global Switchgear Monitoring Market | 2026-2036
Global Switchgear Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Switchgear Monitoring Market Outlook
Data center operators is repositioning switchgear monitoring procurement toward predictive, cloud-native architectures. ABB leverages its digital substation portfolio to anchor premium positioning in utility-scale deployments. Siemens sustains technology leadership through integrated IoT analytics platforms that span transmission and distribution networks. Schneider Electric differentiates via edge-computing controllers designed for critical power infrastructure.
Switchgear monitoring encompasses sensor arrays, protective relays, software analytics, and control systems that track thermal load, partial discharge, gas insulation integrity, and mechanical wear in electrical switching apparatus. These systems enable condition-based maintenance, fault anticipation, and arc-flash prevention across medium- and high-voltage installations. Software and analytics segments are capturing expanding margin pools as utilities shift from hardware-centric to subscription-based service models. Sensor hardware remains volume-dominant but faces commoditization pressure from low-cost Asian suppliers. SCADA-integrated installations retain pricing power in offshore wind and heavy industrial settings where real-time interoperability commands premium valuation.
The IEC 61850 communication standard, IEEE C37.118 synchrophasor protocols, and EU F-Gas Regulation collectively shape product certification requirements and cross-border market access for monitoring system vendors. Germany's Bundesnetzagentar enforces network stability mandates that compel transmission operators to deploy continuous switchgear condition assessment. Stakeholders must weigh captive software development against third-party platform partnerships as utilities consolidate vendor relationships around interoperable, cybersecurity-hardened architectures.
Market Dynamics
Grid operators are abandoning time-based maintenance schedules in favor of continuous condition assessment powered by IEC 61850-compliant sensor networks and cloud-native analytics platforms.
Growth Catalysts
- EU F-Gas Regulation:Mandatory leak detection protocols for SF6-insulated switchgear are compelling utilities across Germany, France, and Italy to retrofit monitoring systems.
- Data center buildouts:Hyperscale operators in Northern Virginia and Frankfurt are specifying predictive arc-flash detection as standard procurement criteria.
- Offshore wind integration:Subsea cable terminations and converter stations require real-time partial discharge monitoring to maintain transmission availability.
Market Restraints
- Sensor commoditization:Low-cost Asian manufacturers are compressing hardware margins for temperature and pressure transducers.
- Cybersecurity compliance costs:IEC 62351 certification timelines and penetration testing requirements extend product development cycles by 8-14 months.
- Copper and rare earth volatility:Magnetostrictive sensor cores and shielding materials face input cost swings that destabilize project quoting.
Strategic Opportunities
- India's transmission expansion:Central Electricity Authority mandates for smart grid infrastructure create first-mover positioning for integrated monitoring-communication platforms.
- Digital twin convergence:Pairing switchgear sensors with physics-based simulation models enables predictive failure windows measured in months rather than days.
- Subscription service models:Utilities in Texas and California are piloting hardware-as-a-service contracts that bundle sensors, analytics, and maintenance.
Industry Challenges
- Legacy SCADA interoperability:Proprietary protocols from 1990s-era installations resist seamless integration with modern IoT architectures.
- Field engineering scarcity:Qualified technicians capable of calibrating partial discharge sensors and interpreting gas analysis data remain concentrated in Western Europe and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Switchgear Monitoring Market |
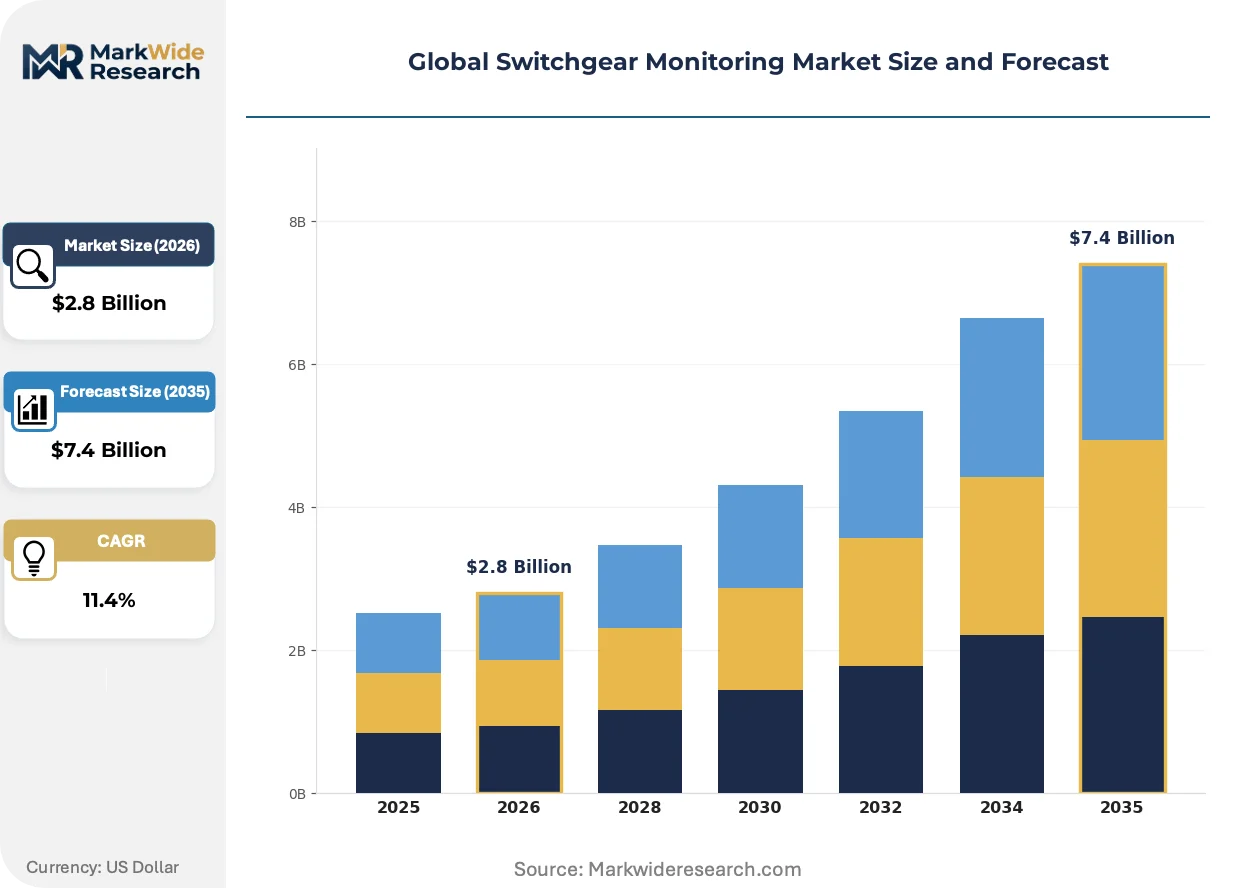
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Relay, Sensor, Software, Controller End User: Utilities, Industrial Sector, Commercial Facilities, Data Centers Installation: Onshore, Offshore, Indoor, Outdoor Technology: IoT, Cloud-based, Analytics, SCADA |
| Companies Covered | ABB, Siemens, Schneider Electric, Eaton, General Electric, Mitsubishi Electric, KONČAR Group, Emerson Electric, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Switchgear Monitoring Market Strategic Shifts
Switchgear monitoring is migrating from standalone hardware installations toward software-defined architectures where analytics engines and machine learning models determine maintenance priority.
Optical partial discharge detection is electrifying competitive positioning in high-voltage substations. UV-sensitive photon counters and fiber-optic acoustic sensors detect corona activity without electromagnetic interference. Transmission operators in Germany and Japan are mandating these systems for 420kV and above installations. The technology is electrifying procurement specifications by collapsing the distinction between diagnostic and protective functions.
EU F-Gas Regulation phase-down schedules are accelerating SF6 alternative adoption. Vacuum interrupters and dry air insulation require modified monitoring parameters for pressure stability and contact wear assessment. Manufacturers must recalibrate sensor algorithms and alarm thresholds. German transmission system operators are driving standardization through VDE working groups to ensure cross-vendor interoperability.
Buyer consolidation around integrated platform vendors is compressing the supplier base. Mid-sized utilities in the US Southeast and Midwest are abandoning multi-vendor sensor strategies in favor of single-source digital substation contracts. Channel partners with cybersecurity hardening capabilities and 24/7 remote diagnostics support are displacing traditional equipment distributors. This concentration is most visible in Texas, where ERCOT grid reliability mandates favor vendors with demonstrated outage response protocols.
Global Switchgear Monitoring Market Segmentation
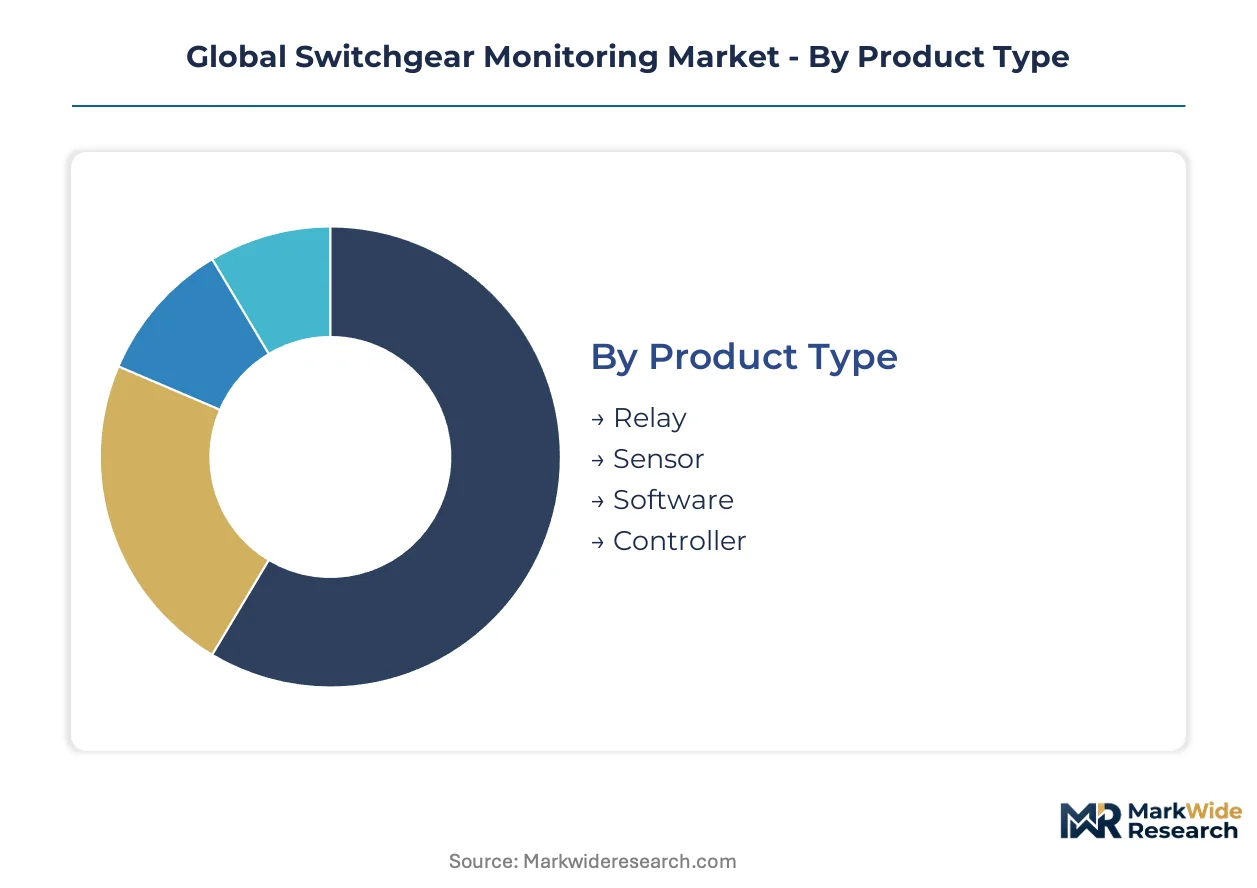
Switchgear monitoring procurement splits across hardware, software, and service layers with divergent margin profiles. Capital allocation patterns reveal where vendors capture recurring revenue versus one-time equipment sales.
Product Type:
Upfront capital intensity peaks with controller hardware requiring embedded cybersecurity certification and edge-computing architectures.
- Software:Cloud-native analytics platforms command subscription pricing models that transform utility procurement from CapEx to OpEx. Data center operators in Northern Virginia and Frankfurt are mandating predictive arc-flash algorithms as standard procurement criteria.
- Sensor:Temperature, pressure, and partial discharge transducers form the volume base but face margin compression from low-cost Asian manufacturers. IEC 61850-compliant sensor networks are becoming mandatory in German transmission substations under Bundesnetzagentur network stability mandates.
- Relay:Protective relays integrate fault detection with breaker control logic in medium-voltage installations.
- Controller:Edge-computing controllers process sensor data locally for sub-10ms response times in critical power infrastructure.
Most installed capacity flows through Sensor hardware. Expansion is steepest in Software.
End User:
Customer sophistication determines pricing power, with hyperscale operators demanding integrated platform contracts while industrial buyers negotiate component-level procurement.
- Data Centers:Hyperscale operators specify predictive maintenance architectures with 99.999% availability guarantees. Northern Virginia and Frankfurt clusters are driving adoption of continuous thermal monitoring and arc-flash detection systems.
- Utilities:Transmission and distribution operators face regulatory compulsion to deploy condition-based maintenance under EU F-Gas Regulation and Germany's network stability mandates.
- Industrial Sector:Heavy manufacturing facilities prioritize SCADA-integrated installations where real-time interoperability commands premium valuation in offshore wind and petrochemical settings.
- Commercial Facilities:Hospital and airport operators seek simplified monitoring packages with remote diagnostics support.
Data Centers command the highest per-site spend. Utilities provide the deepest installed base with replacement cycle visibility.
Installation:
Environmental exposure severity dictates sensor specification grades and maintenance access economics.
- Offshore:Subsea cable terminations and converter stations require corrosion-hardened partial discharge monitoring to maintain transmission availability. North Sea wind farms and Japanese offshore clusters are mandating real-time gas analysis for SF6-insulated switchgear.
- Outdoor:Transmission substations across Germany and Texas face temperature cycling and moisture ingress challenges that accelerate sensor degradation.
- Indoor:Controlled environments in data centers and commercial buildings permit standard-grade sensor specifications.
- Onshore:Land-based wind and solar integration sites require modular monitoring architectures for rapid deployment.
Outdoor deployments dominate cumulative installations. Offshore applications are climbing the fastest.
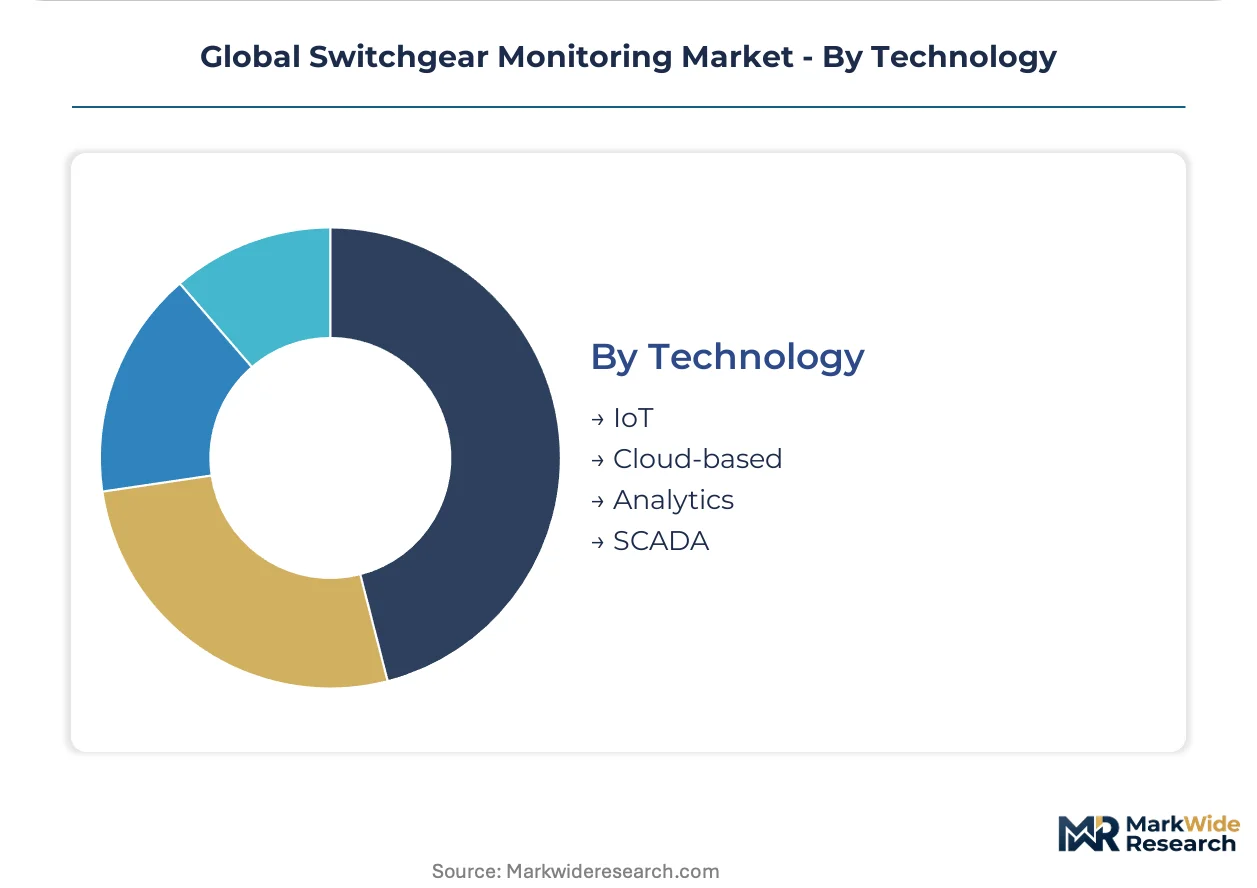
Technology:
Architecture choices determine interoperability scope and cybersecurity compliance burden.
- IoT:Wireless sensor networks reduce cabling costs but introduce IEC 62351 certification timelines that extend product development cycles by 8-14 months.
- Cloud-based:Centralized analytics platforms enable fleet-level pattern recognition across distributed switchgear populations.
- Analytics:Machine learning models trained on historical failure data generate predictive maintenance windows measured in months rather than days.
- SCADA:Legacy protocol integration retains pricing power in heavy industrial settings where real-time control system interoperability commands premium valuation.
SCADA-integrated systems anchor the existing installed base. Cloud-based architectures are gaining share fastest among new procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting procurement toward jurisdictions with harmonized certification standards and lower compliance friction. German manufacturers capture premium positioning through early IEC 61850 adoption, while Asian suppliers compete on sensor hardware cost structures.
United States
Data center buildouts in Northern Virginia and Texas are driving predictive maintenance adoption. FERC reliability mandates and ERCOT grid stability requirements compel transmission operators to deploy continuous condition assessment systems. Hyperscale operators in Dallas-Fort Worth and Ashburn clusters specify arc-flash detection as standard procurement criteria.
Germany
Grid modernization investments and renewable integration mandates are accelerating replacement cycles. Bundesnetzagentur enforces network stability protocols that require continuous switchgear condition assessment in transmission substations. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate demand for IEC 61850-compliant monitoring platforms.
China
Central Electricity Authority mandates for smart grid infrastructure create demand for integrated monitoring-communication platforms. MIIT standards for industrial IoT security shape product certification requirements for domestic and foreign vendors. Manufacturing concentrations in Yangtze River Delta and Pearl River Delta drive volume procurement of sensor hardware.
India
Transmission expansion under national smart grid missions creates first-mover positioning for platform vendors. CEA technical standards for substation automation influence procurement specifications across state electricity boards. Industrial corridors in Gujarat and Maharashtra concentrate early deployments of predictive maintenance architectures.
Japan
Offshore wind integration and subsea cable monitoring requirements drive specialized sensor demand. METI energy security initiatives support domestic manufacturing of high-voltage monitoring systems. Technology clusters in Kanto and Kansai regions anchor development of optical partial discharge detection systems.
Global Switchgear Monitoring Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors consolidate around interoperable platform architectures. The supplier base stratifies into three tiers: integrated electrical conglomerates with digital substation portfolios, specialized sensor manufacturers facing commoditization pressure, and software-native analytics providers. Competitive moves center on cybersecurity certification acceleration and cloud-native service model transitions.
Within the integrated systems tier, ABB, Siemens, and Schneider Electric occupy positions defined by digital substation and IoT analytics capabilities. These European-headquartered conglomerates exemplify the shift toward subscription-based service models and edge-computing architectures. Their market presence anchors premium positioning in utility-scale deployments where IEC 61850 compliance and 24/7 remote diagnostics support determine vendor selection.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Eaton |
| General Electric |
| Mitsubishi Electric |
| KONČAR Group |
| Emerson Electric |
| Hitachi |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between IEC 61850-compliant digital substation platforms and commodity sensor hardware manifests in divergent margin architectures across procurement channels. Premium-tier vendors in Germany and Japan capture pricing power through embedded cybersecurity certification and 24/7 remote diagnostics bundling, while low-cost Asian manufacturers compress hardware margins through direct-to-utility volume contracts.
Pricing Analysis
Distributor margins for sensor hardware compress under direct-to-OEM procurement trends, while systems integrators retain 15-25 point markups on bundled analytics subscriptions. Subscription-based SaaS pricing for cloud-native platforms transforms utility procurement from CapEx to OpEx, with price differentiation driven by cybersecurity certification tier and after-sales service bundling. Pricing pressure intensifies in temperature and pressure transducer segments due to low-cost Chinese manufacturing scale. Data center operators in Northern Virginia show lowest price sensitivity, prioritizing 99.999% availability guarantees over per-unit hardware costs.
Supply Chain Analysis
Magnetostrictive sensor cores and rare earth shielding materials rest on concentrated Chinese and Japanese specialty metal suppliers, with IEC 62351-compliant embedded processors sourcing from Taiwanese and South Korean semiconductor foundries. Copper winding materials and SF6 gas insulation components face commodity price volatility that destabilizes project quoting timelines. Single-source vulnerability concentrates in high-voltage optical sensor subassemblies where Japanese photonics manufacturers dominate. Distribution runs through authorized systems integrators with cybersecurity hardening capabilities, displacing traditional equipment distributors in Texas and California utility markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in switchgear monitoring hinges on software-defined service transitions that collapse hardware replacement cycles into recurring analytics revenue, with cloud-native platform shifts capturing OpEx budget reallocation from data center operators.
For Market Incumbents: Cement platform stickiness through IEC 62351 certification acceleration and captive development of edge-computing controller architectures. Deepen backward integration into optical partial discharge sensor manufacturing to defend against Japanese photonics specialists. Prioritize 24/7 remote diagnostics infrastructure buildout in Texas ERCOT markets where grid reliability mandates favor demonstrated outage response protocols.
For New Entrants and Emerging Players: Cloud-native SaaS distribution routes offer lowest customer acquisition friction for predictive analytics modules targeting mid-sized US Southeast utilities abandoning multi-vendor sensor strategies. India's transmission expansion under Central Electricity Authority smart grid mandates presents the most penetrable geography for integrated monitoring-communication platforms. Lead with hardware-as-a-service pilot contracts that bundle sensors, analytics, and maintenance to bypass incumbent procurement relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where cybersecurity certification timelines extend product development cycles 8-14 months, favoring acquirers with existing IEC 62351 infrastructure. Long-term viability centers on software revenue mix and subscription renewal rates rather than hardware shipment volumes. Target acquisition archetype: specialized sensor manufacturers with optical partial discharge IP and established German transmission operator relationships. Signal to watch: Bundesnetzagentur mandate expansion beyond transmission to distribution substations.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Substation Platform Integration | Consolidates vendor relationships around IEC 61850-compliant architectures with embedded cybersecurity. |
| Optical Partial Discharge Sensor Development | Captures 420kV+ transmission procurement specifications in Germany and Japan through UV photon counting. |
| Hardware-as-a-Service Contract Pilots | Transforms utility procurement from CapEx to OpEx in Texas and California markets. |
| SF6 Alternative Monitoring Recalibration | Aligns sensor algorithms with EU F-Gas Regulation phase-down schedules for vacuum interrupters. |
| Cybersecurity Certification Acceleration | Compresses IEC 62351 development timelines to match competitor platform roadmaps. |
Study Parameters
Bottom-up utility and data center operator modeling reconciled against top-down sensor hardware production tracking forms the analytical core of this study. Primary interviews with transmission planning officers, substation automation engineers, hyperscale facility directors, and cybersecurity compliance leads combined with secondary validation from FERC reliability filings, IEC standards documentation, Bundesnetzagentur network stability mandates, and EIA smart grid investment disclosures. Triangulation across stakeholder inputs and regulatory databases ensures segmentation accuracy across hardware, software, and service layers.
Input-output matrices map sensor unit shipments to installed base expansion across the projection horizon, with value outputs derived from pricing surveys across German, US, and Japanese procurement channels. Segmentation dimensions modeled include product type tier, end-user sophistication, installation environment severity, and technology architecture choice. CAGRs reflect weighted averages of replacement cycle visibility, regulatory mandate timing, and digital service adoption curves. Industry-specific forecast inputs incorporate offshore wind integration pipelines and data center construction permits.
The model assumes a particular technology adoption path; alternative pathways for wireless IoT sensor networks versus hardwired IEC 61850 architectures would alter the outlook for cybersecurity compliance timelines and deployment cost structures. Forecasts reflect assumptions about regulatory enforcement consistency, rare earth material supply continuity, and utility budget allocation patterns. Material deviation in EU F-Gas Regulation enforcement intensity or Chinese sensor export licensing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
US Air Filter Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
Electrodialysis System Market