
 Lab Centrifuges Market | 2026-2036
Lab Centrifuges Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Centrifuges Market Outlook
Buyer concentration among hospital labs is broadening as decentralized clinical networks expand procurement autonomy across regional health systems. Thermo Fisher Scientific leverages its diagnostic workflow integration to sustain instrument placement in high-throughput facilities. Beckman Coulter anchors ultracentrifuge demand through deep specialization in bioprocessing separations. Eppendorf competes in microcentrifuge niches where benchtop footprint and protocol flexibility dominate purchasing criteria.
Lab centrifuges are precision instruments that generate centrifugal force measured in relative centrifugal force (RCF) to separate substances by density, with operational speeds ranging from hundreds to over 100,000 revolutions per minute depending on rotor configuration and sample requirements. Refrigerated units command premium positioning in protein purification workflows where thermal stability protects sample integrity, while microcentrifuge adoption accelerates in molecular biology settings handling sub-milliliter volumes. Ultracentrifuge placements concentrate margin pools in academic institutions running density gradient separations for viral vector research.
FDA 21 CFR Part 11 compliance requirements shape electronic records and signature capabilities in pharmaceutical labs, while EU MDR traceability standards affect equipment qualification documentation for clinical diagnostics deployed in European hospital networks. ISO 13485 quality management expectations extend to contract research organizations qualifying centrifuges for GMP-regulated separations. Stakeholders must monitor evolving regulatory divergence between US and European electronic data integrity standards when configuring global instrument platforms.
Market Dynamics
Biopharmaceutical manufacturing scale-up is compressing instrument replacement cycles as contract manufacturers face audit pressure for validated equipment fleets. FDA 21 CFR Part 11 compliance mandates are forcing hardware refresh decisions across pharmaceutical quality control labs.
Growth Catalysts
- Cell and gene therapy manufacturing:Viral vector production requires ultracentrifuge density gradient separations at clinical and commercial scale. Contract development organizations in Germany and Switzerland are qualifying refrigerated units for GMP workflows.
- FDA 21 CFR Part 11:Electronic records and signature requirements are accelerating replacement of legacy analog centrifuges in US pharmaceutical labs. Equipment vendors must embed audit trails and access controls to maintain placement.
- Protein purification workflows:Thermal stability demands in structural biology are pulling refrigerated microcentrifuge placements into academic core facilities. Sample integrity protocols now specify tight temperature tolerances.
Market Restraints
- Stainless steel and rare earth magnet costs:Rotor fabrication relies on specialty alloys and permanent magnet materials subject to supply volatility. Price swings compress margin pools for mid-tier equipment vendors.
- Rotor manufacturing concentration:Precision-machined titanium and carbon fiber composite rotors source from a limited supplier base in Germany and Japan. Single-source dependencies create qualification bottlenecks.
- Centrifuge-free cell isolation:Acoustic and microfluidic separation technologies are advancing in cell therapy process development. Early-stage adopters are piloting these methods for gentle, label-free cell handling.
Strategic Opportunities
- India biopharma manufacturing:CDSCO quality mandates and export-oriented production are creating demand for validated centrifuge fleets. Local analytical instrumentation distributors are building service capabilities.
- AI-enabled predictive maintenance:Sensor-embedded rotors and vibration analysis algorithms are converging to reduce unplanned downtime. Equipment-as-a-service models are emerging in high-throughput screening facilities.
- EU MDR traceability requirements:In vitro diagnostic device regulations are mandating enhanced equipment qualification documentation. Clinical diagnostic labs require audit-ready instrument lifecycle records.
Industry Challenges
- Field service engineer scarcity:Ultracentrifuge maintenance requires specialized training in vacuum system and drive motor repair. Vendors struggle to staff qualified technicians for rapid rotor balancing and seal replacement.
- Legacy LIMS integration:Older laboratory information management systems lack API connectivity for automated centrifuge run logging. Biopharma labs face manual data transcription burdens during validation audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Centrifuges Market |
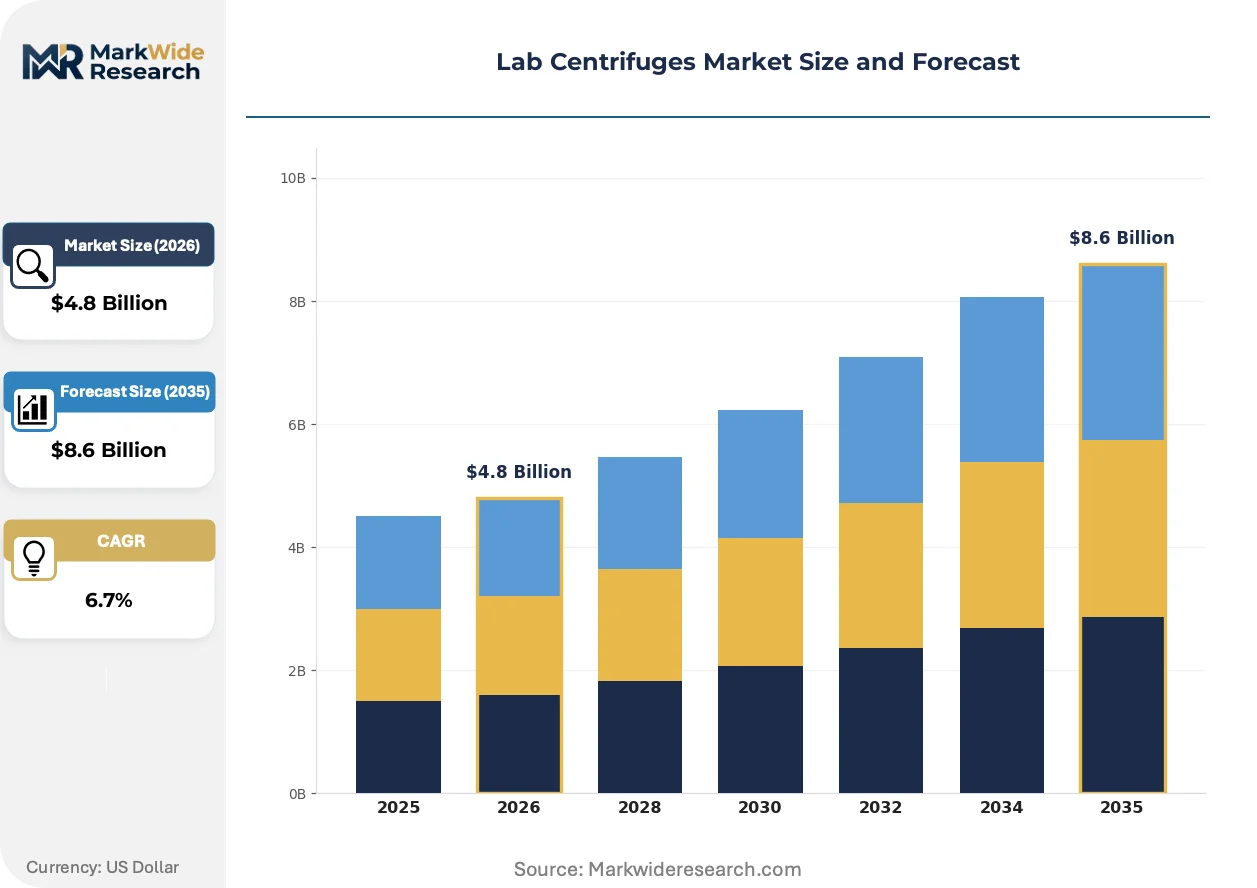
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated, Microcentrifuge, Ultracentrifuge, Swinging-Bucket Application: Clinical Research, Blood Separation, Molecular Biology, Protein Purification End User: Pharmaceutical Labs, Academic Institutions, Hospital Labs, Contract Research Organizations Technology: Fixed Angle, Variable Speed, Continuous Flow, High-Efficiency |
| Companies Covered | Andreas Hettich, HERMLE Labortechnik, Thermo Fisher Scientific, Sartorius, Kubota, Beckman Coulter, Sigma Laborzentrifugen, NuAire, Eppendorf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Centrifuges Market Strategic Shifts
Digital connectivity and automated sample handling are restructuring how centrifuges fit into integrated laboratory workflows. Vendors are competing on data integrity architecture rather than rotational speed specifications alone.
Brushless DC motor technology is overtaking traditional induction motor drives in benchtop microcentrifuge segments. Molecular biology core facilities at US research universities are specifying these units for reduced maintenance intervals and quieter operation. The shift is compressing service revenue streams for legacy motor replacement parts while extending instrument depreciation schedules.
EU MDR Annex I general safety and performance requirements are mandating enhanced risk management documentation for clinical diagnostic centrifuges. Manufacturers must demonstrate biological safety and electromagnetic compatibility through notified body assessment. Hospital labs in France and Italy are prioritizing CE-IVDR compliant units to avoid procurement disqualification.
Service contract unbundling is fragmenting how academic and industrial buyers acquire maintenance coverage. Core facilities at US medical schools are negotiating à la carte rotor inspection and calibration schedules separate from full-service agreements. This pattern is most visible in California and Massachusetts where shared instrumentation models concentrate bargaining power among consortia buyers.
Lab Centrifuges Market Segmentation
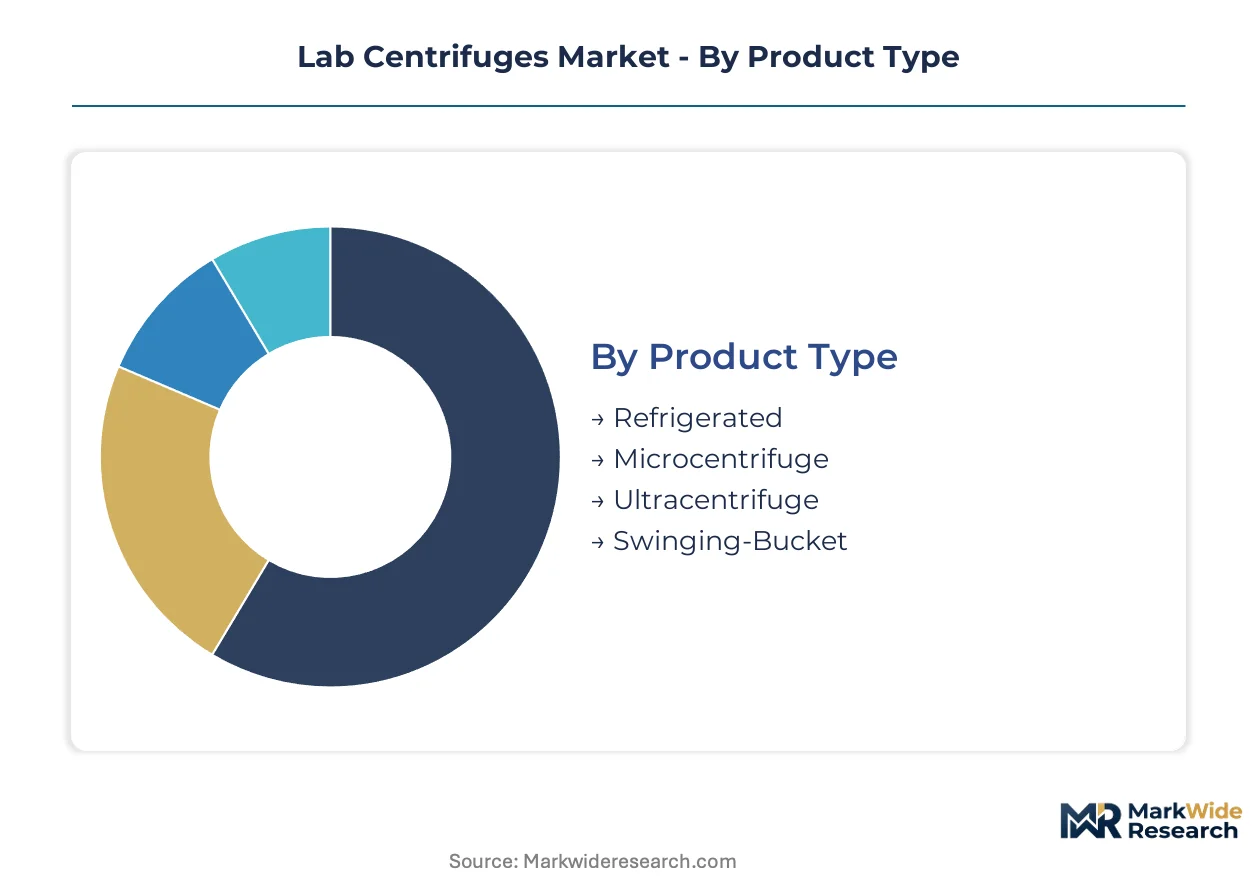
Centrifuge purchasing decisions split across thermal requirements, sample volume, and rotational force specifications. Each segment carries distinct qualification burdens and service contract structures that reshape vendor economics.
Product Type:
Thermal stability requirements dominate capital allocation in bioprocessing workflows.
- Refrigerated:These units maintain sub-ambient temperatures through compressor-driven cooling circuits integrated with the rotor chamber. Pharmaceutical quality control labs in Germany specify tight temperature tolerances for protein stability during extended runs. FDA 21 CFR Part 11 compliance mandates are accelerating replacement cycles in US biopharma facilities.
- Microcentrifuge:Compact benchtop instruments handle sub-milliliter volumes with brushless DC motor drives displacing induction systems. Academic core facilities in Massachusetts prioritize reduced footprint and protocol flexibility for high-throughput molecular biology workflows.
- Ultracentrifuge:Vacuum-enclosed systems generate forces exceeding 100,000 x g for density gradient separations.
- Swinging-Bucket:Rotor design permits horizontal tube orientation during acceleration for flat gradient interfaces.
Refrigerated units lead on scale; microcentrifuges lead on momentum.
Application:
Workflow specificity determines rotor configuration and speed calibration requirements.
- Clinical Research:Diagnostic validation demands traceable calibration certificates and audit-ready run logs. Hospital labs in France face EU MDR documentation requirements for equipment qualification.
- Blood Separation:Density gradient media separate plasma, buffy coat, and erythrocyte fractions at controlled speeds.
- Molecular Biology:Nucleic acid extraction and PCR preparation drive high-volume microcentrifuge placements in shared instrumentation cores.
- Protein Purification:Thermal-sensitive samples require refrigerated centrifugation with tight temperature control during lengthy ultracentrifugation steps. Structural biology facilities at Swiss research institutes specify cryogenic-compatible rotors for membrane protein studies.
Blood separation leads on scale; protein purification leads on momentum.
End User:
Procurement autonomy and validation burden vary sharply across institutional types.
- Pharmaceutical Labs:GMP-regulated environments mandate IQ/OQ/PQ qualification protocols and electronic signature capabilities. FDA audit pressure compresses replacement cycles for legacy analog instruments.
- Academic Institutions:Shared core facilities negotiate unbundled service contracts with à la carte rotor inspection schedules. University consortia in California concentrate purchasing power for volume discounts.
- Hospital Labs:Decentralized clinical networks are broadening procurement autonomy across regional health systems.
- Contract Research Organizations:CDSCO quality mandates in India are driving validated centrifuge fleet expansion for export-oriented biopharma manufacturing.
Pharmaceutical labs lead on scale; contract research organizations lead on momentum.
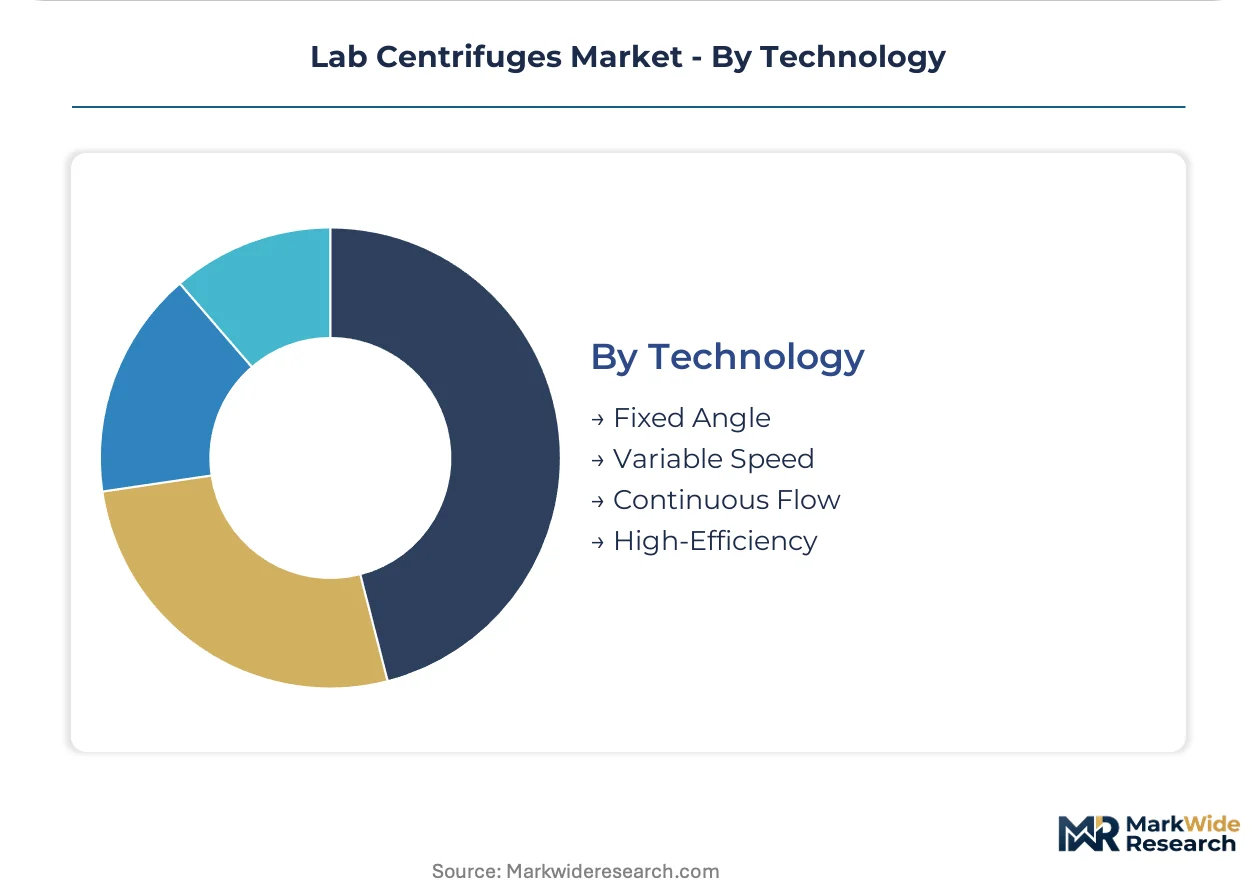
Technology:
Motor and rotor engineering choices determine maintenance intervals and energy consumption profiles.
- Fixed Angle:Rigid rotor geometry delivers rapid pelleting for routine sample preparation with simpler mechanical construction.
- Variable Speed:Programmable acceleration and deceleration curves protect delicate gradients from disturbance. Bioprocessing applications in Switzerland specify precise speed ramping for viral vector separations.
- Continuous Flow:Zonal rotors permit uninterrupted feed of large-volume samples for industrial-scale separations.
- High-Efficiency:Optimized aerodynamics and drive systems reduce energy consumption and heat generation during extended runs. Sustainability mandates at Danish research institutes are prioritizing these units for core facility upgrades.
Variable speed leads on scale; high-efficiency leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering talent anchors rotor fabrication clusters, while Swiss bioprocessing specialists and US pharmaceutical quality engineers concentrate demand for validated equipment fleets across three continents.
United States
FDA 21 CFR Part 11 compliance mandates accelerate hardware refresh cycles in pharmaceutical quality control labs across New Jersey and Massachusetts. The agency's electronic records requirements disqualify legacy analog centrifuges from GMP-regulated separations. Boston's contract development organizations are qualifying refrigerated units for viral vector manufacturing workflows.
Germany
Baden-Württemberg's analytical instrumentation manufacturers cluster around precision-machined titanium rotor production for ultracentrifuge applications. EU MDR traceability standards mandate enhanced equipment qualification documentation for clinical diagnostic deployments. Munich-area bioprocessing facilities specify cryogenic-compatible rotors for membrane protein structural biology studies.
Switzerland
Swissmedic oversight shapes GMP validation protocols for contract manufacturing organizations in Basel and Zurich. The regulator's quality mandates align with FDA requirements for export-oriented biopharma production. Basel's viral vector manufacturing hubs are driving refrigerated ultracentrifuge placements for density gradient separations at commercial scale.
India
CDSCO quality mandates and export-oriented biopharma manufacturing create demand for validated centrifuge fleets in Maharashtra and Gujarat. The national pharmaceutical regulator's standards align with FDA and EMA expectations for contract research organizations. Hyderabad's analytical instrumentation distributors are building field service capabilities for GMP-regulated separations.
Japan
METI industrial policy supports precision manufacturing capabilities for carbon fiber composite rotors in Nagoya and Osaka regions. PMDA pharmaceutical regulations require electronic data integrity standards for clinical trial sample processing. Osaka's molecular biology core facilities specify brushless DC motor microcentrifuges for high-throughput nucleic acid extraction workflows.
Lab Centrifuges Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across equipment tiers, creating a bifurcated structure where scale-driven diagnostic workflow integrators face benchtop footprint specialists. The vendor base organizes around three strategic archetypes: full-service laboratory conglomerates, precision rotor fabricators with captive machining capabilities, and microcentrifuge specialists optimized for molecular biology protocols. Dominant competitive moves include M&A for diagnostic workflow integration and strategic partnerships for AI-enabled predictive maintenance platforms.
Among German precision engineering specialists, Andreas Hettich and HERMLE Labortechnik represent the rotor fabrication archetype with deep specialization in clinical centrifugation. Thermo Fisher Scientific occupies a position exemplifying the diversified conglomerate model, leveraging diagnostic workflow integration across high-throughput pharmaceutical facilities. Beckman Coulter and Eppendorf anchor distinct specialization vectors—ultracentrifuge bioprocessing separations versus microcentrifuge benchtop flexibility—each representing competitive positioning against integrated rivals.
| Leading Market Players |
|---|
| Andreas Hettich |
| HERMLE Labortechnik |
| Thermo Fisher Scientific |
| Sartorius |
| Kubota |
| Beckman Coulter |
| Sigma Laborzentrifugen |
| NuAire |
| Eppendorf |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between GMP-validated ultracentrifuges and benchtop microcentrifuges manifests in both pricing power and supply chain configuration. FDA 21 CFR Part 11 compliance requirements for electronic records and audit trails concentrate premium pricing in pharmaceutical quality control labs, while commodity microcentrifuge segments face cost compression from brushless DC motor standardization.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for entry-level microcentrifuge segments as local manufacturers achieve ISO 13485 certification. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated refrigerated units with embedded compliance software from basic fixed-angle models. Pricing pressure stems from rare earth magnet cost volatility in rotor fabrication. Hospital labs in decentralized clinical networks exhibit highest price sensitivity, while contract development organizations prioritize qualification documentation over unit cost.
Supply Chain Analysis
Refurbishment flows for titanium rotors extend asset lifecycles and create secondary supply channels for academic core facilities. Precision-machined rotor fabrication concentrates in Germany and Japan, with carbon fiber composite sourcing from Nagoya-area specialists. Raw material dependencies include specialty titanium alloys, rare earth permanent magnets, and cryogenic-compatible seal materials. Single-source vulnerability persists in vacuum system drive motor components. Distribution runs through analytical instrumentation distributors with captive field service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where FDA 21 CFR Part 11 compliance mandates and EU MDR traceability requirements shift procurement criteria toward validated equipment fleets with embedded audit capabilities.
For Market Incumbents: Lock in rotor fabrication capacity through long-term supply agreements with Baden-Württemberg precision machinists. Deepen captive maintenance capabilities to offset compression in replacement parts revenue from extended brushless DC motor lifecycles. Defend against acoustic and microfluidic separation substitutes by embedding predictive maintenance sensors that demonstrate total cost of ownership superiority.
For New Entrants and Emerging Players: CDSCO quality mandates in India open a window for validated centrifuge fleet expansion among export-oriented contract research organizations. Target Maharashtra and Gujarat biopharma manufacturing clusters where local distributors are building GMP service capabilities. Penetrate through equipment-as-a-service models with unbundled rotor inspection schedules that mirror California academic consortia purchasing patterns.
For Investors and Strategic Acquirers: Consolidation pressure builds where field service engineer scarcity constrains ultracentrifuge maintenance response times. Acquire precision rotor fabricators with vacuum system drive motor repair capabilities to capture aftermarket margin pools. Monitor viral vector manufacturing scale-up announcements from Basel and Boston contract development organizations as inflection indicators for refrigerated ultracentrifuge demand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Predictive Maintenance Platform | Sensor-embedded rotors reduce unplanned downtime in high-throughput screening facilities. |
| GMP Validation Service Expansion | IQ/OQ/PQ documentation capabilities secure placement in FDA-audited pharmaceutical labs. |
| Brushless DC Motor Transition | Quieter operation and extended depreciation schedules displace legacy induction systems. |
| EU MDR Compliance Certification | CE-IVDR documentation avoids procurement disqualification in French and Italian hospital labs. |
| India Distribution Partnership | Hyderabad and Mumbai service capabilities capture CDSCO-mandated validation demand. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with biopharma quality control directors, academic core facility managers, GMP field service engineers, and analytical instrumentation procurement officers informed demand-side dynamics. Secondary sources include FDA 21 CFR guidance documents, EU MDR technical documentation requirements, CDSCO quality circulars, and ISO 13485 certification databases. Bottom-up instrument placement tracking and top-down biopharma manufacturing capacity analysis were triangulated against rotor fabrication capacity estimates.
Rate-of-change decomposition separates volume growth from mix-shift toward higher-specification units across the projection horizon. Segmentation dimensions modeled include thermal configuration, rotor speed class, end-user validation burden, and geographic regulatory cluster. CAGRs were derived from instrument replacement cycle compression analysis and bioprocessing capacity expansion trajectories. Viral vector manufacturing scale-up intensity and FDA audit frequency served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export restriction scenarios or accelerated centrifuge-free cell isolation adoption. Practitioners should monitor METI industrial policy announcements for carbon fiber rotor supply signals and Swissmedic GMP inspection schedules for validation demand triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Balanced Salt Solution for Cell Culture Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Micro-Bioreactors Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Global Transfection Technologies Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Automated Cell Counting Market