
 Botanical Extraction Equipment Market | 2026-2036
Botanical Extraction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Botanical Extraction Equipment Market Analytics
Modular skid-mounted extraction systems is expanding buyer choice by letting food and beverage processors scale capacity without full plant reconstruction. Alfa Laval leverages its separation technology heritage to dominate large-scale solvent recovery installations. GEA sustains competitive positioning through integrated process engineering that spans extraction through downstream purification. Eden Labs specializes in compact supercritical fluid units tailored to small-scale producers entering craft botanical segments.
Botanical extraction equipment encompasses mechanical and chemical processing systems designed to isolate bioactive compounds from plant matrices using pressure, temperature, solvent, or mechanical force parameters, with supercritical fluid extraction typically operating at pressures exceeding 7.4 MPa and temperatures near 31°C for CO2-based separation. These systems serve pharmaceutical, nutraceutical, and cosmetic industries requiring standardized phytochemical inputs for formulation consistency. Supercritical fluid extraction commands premium positioning due to solvent-free output and terpene preservation advantages, while solvent extraction retains volume leadership across high-capacity pharmaceutical operations. Batch extraction technology occupies the installed base majority, though continuous extraction architectures are gaining traction among nutraceutical manufacturers pursuing throughput optimization.
FDA cGMP guidelines and EMA GMP Annex 2 standards shape equipment validation protocols, compelling manufacturers to deploy stainless-steel construction with clean-in-place functionality and batch traceability documentation. REACH compliance in Europe and EPA solvent emission regulations in the United States further constrain solvent selection and recovery system design. Stakeholders must monitor evolving pharmacopeial monograph revisions and state-level cannabis processing codes that redefine acceptable extraction methodologies and purity thresholds.
Market Dynamics
Pharmaceutical manufacturers in Germany and the United States are scaling solvent extraction capacity to meet EMA and FDA purity mandates for active botanical compounds. Supercritical CO2 extraction demand concentrates in California's cannabis processing cluster and Switzerland's phytopharmaceutical hub.
Growth Catalysts
- EMA GMP Annex 2 standards:European pharmaceutical manufacturers are retrofitting extraction lines with stainless-steel construction and clean-in-place functionality to satisfy batch traceability documentation requirements.
- Cannabis processing cluster expansion:California's regulated adult-use market is driving demand for supercritical CO2 systems that preserve terpene profiles while eliminating residual solvent concerns.
- Modular skid-mounted architectures:Food and beverage processors are adopting scalable extraction footprints that bypass full plant reconstruction during capacity expansion cycles.
Market Restraints
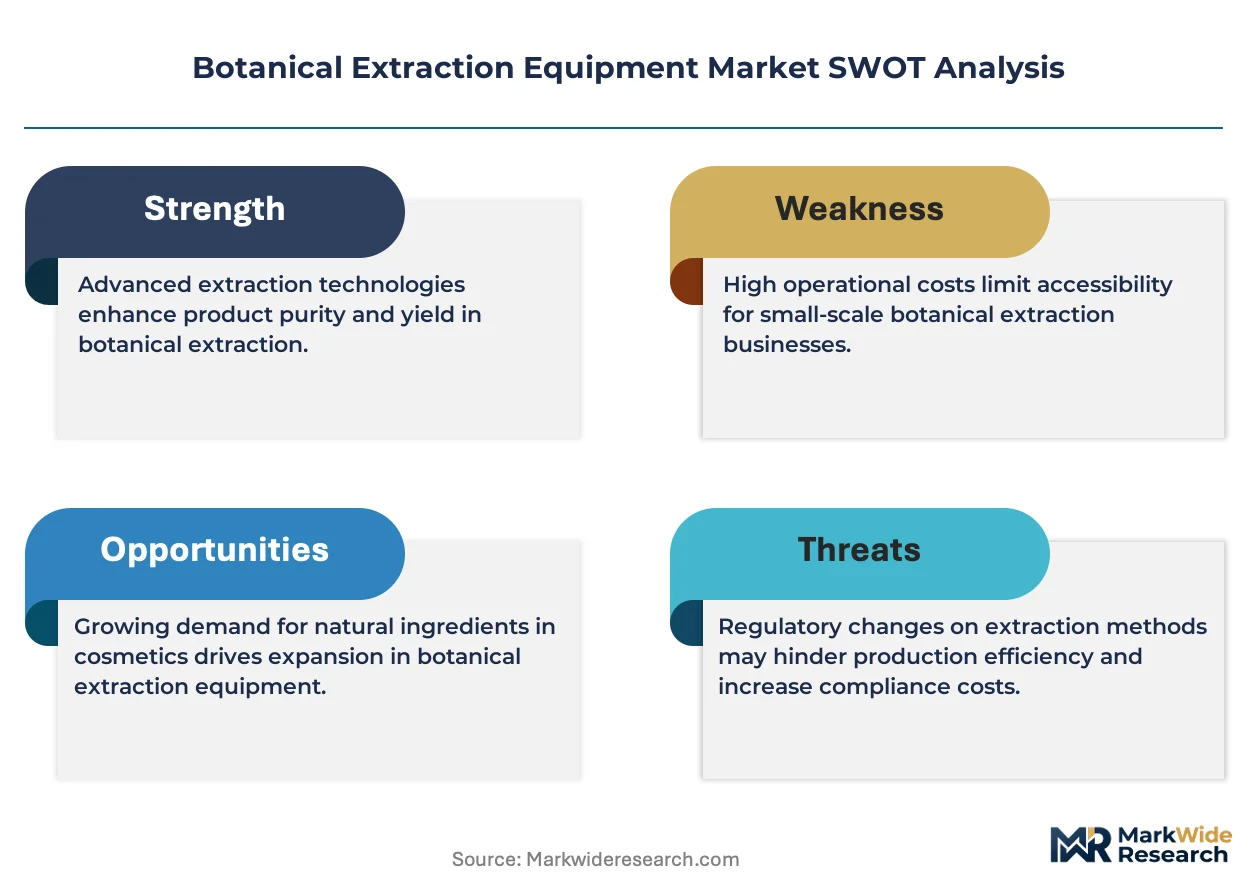
- Supercritical CO2 capex intensity:High-pressure vessel fabrication and precision pump systems require capital outlays that exclude small-scale botanical processors from premium extraction technology.
- EPA solvent emission regulations:Recovery system design constraints in the United States limit hydrocarbon solvent selection and increase compliance engineering costs for pharmaceutical extraction facilities.
- Batch extraction throughput ceilings:Installed base majority technology faces fundamental cycle-time limitations that continuous extraction architectures are beginning to displace in nutraceutical manufacturing.
Strategic Opportunities
- India phytopharmaceutical manufacturing:CDSCO regulatory harmonization with ICH guidelines is creating first-mover advantages for equipment suppliers deploying cGMP-compliant extraction trains.
- Pressurized liquid extraction convergence:Integration of accelerated solvent extraction with automated sample preparation is opening workflow efficiencies in analytical and preparative scale applications.
- REACH solvent substitution incentives:ECHA authorization restrictions on traditional extraction solvents are accelerating demand for bio-based alternatives and supercritical fluid process retrofits.
Industry Challenges
- High-pressure systems engineering talent:Supercritical CO2 extraction operations require specialized technicians familiar with 7.4 MPa operating envelopes and critical point control protocols.
- Legacy solvent extraction integration:Pharmaceutical manufacturers face revalidation complexity when bridging continuous extraction architectures with existing downstream purification infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanical Extraction Equipment Market |
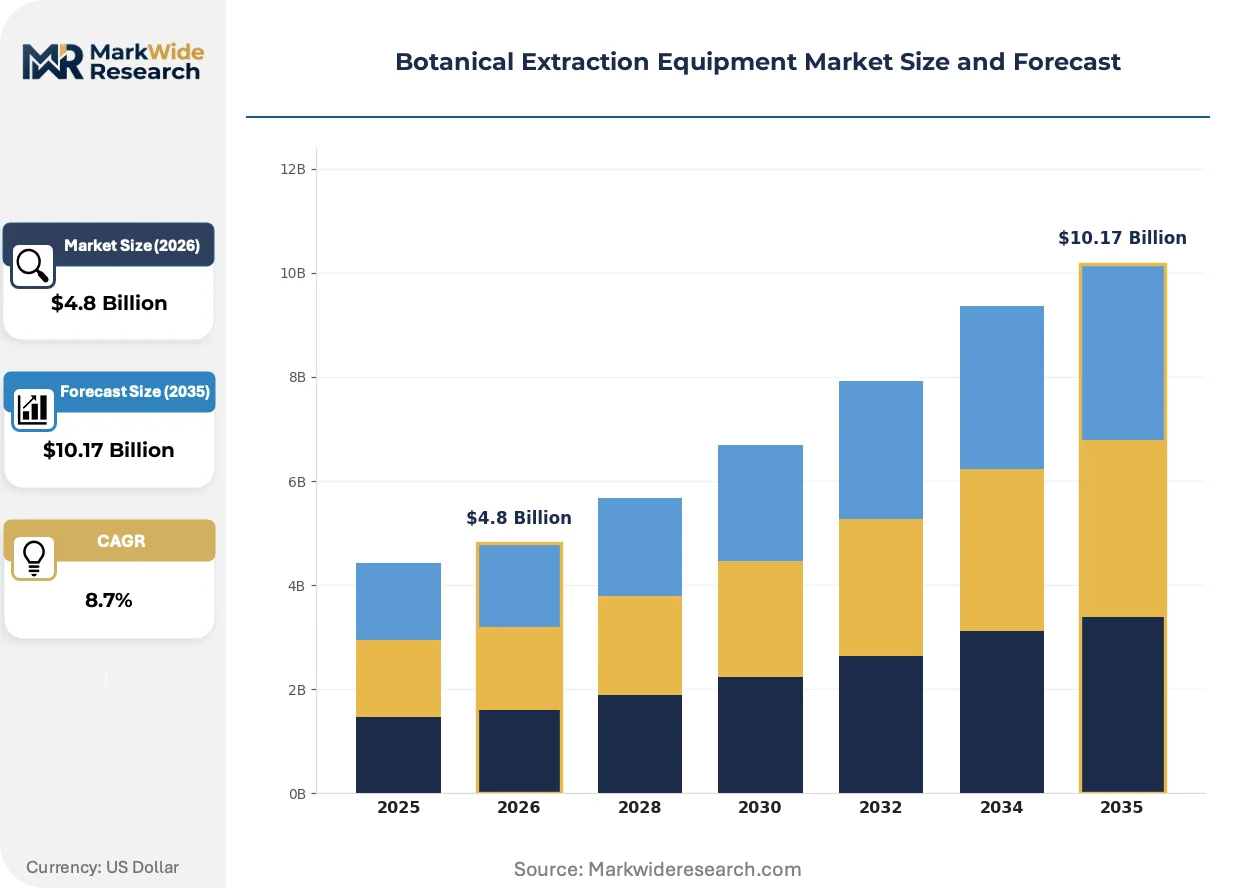
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Press, Steam Distillation, Solvent Extraction, Supercritical Fluid Extraction Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Technology: Batch Extraction, Continuous Extraction, Integrated Extraction, Manual Extraction End User: Large Scale Manufacturers, Small Scale Producers, Research Institutions, Herbal Products Companies |
| Companies Covered | Alfa Laval, GEA, Eden Labs, Andritz, Flottweg, GTech Bellmor, Buchi Labortechnik AG, Waters Corporation, Cheersonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanical Extraction Equipment Market Evolving Landscape
Extraction technology architectures are fragmenting across scale-specific configurations as buyer segments diverge in performance requirements and capital deployment capacity.
Modular skid-mounted extraction systems are modularizing deployment patterns across food and beverage processing facilities. Mid-scale botanical ingredient manufacturers are adopting containerized extraction units at accelerated procurement cycles. This architecture is modularizing capacity planning by decoupling extraction throughput from fixed civil infrastructure investments.
REACH compliance deadlines in Europe are compressing solvent selection flexibility for phytopharmaceutical manufacturers. ECHA authorization requirements for traditional hydrocarbon extraction media are redirecting capital toward supercritical CO2 and pressurized ethanol alternatives. German extraction facilities are responding fastest, with Switzerland's phytopharmaceutical hub accelerating parallel solvent substitution timelines.
Certification-driven procurement is displacing price-primary vendor selection in pharmaceutical-grade extraction equipment. FDA cGMP and EMA GMP Annex 2 documentation requirements are elevating validation protocol completeness above initial capital cost in supplier evaluation matrices. This shift is most visible among United States and German active pharmaceutical ingredient manufacturers consolidating approved vendor lists.
Botanical Extraction Equipment Market Segmentation
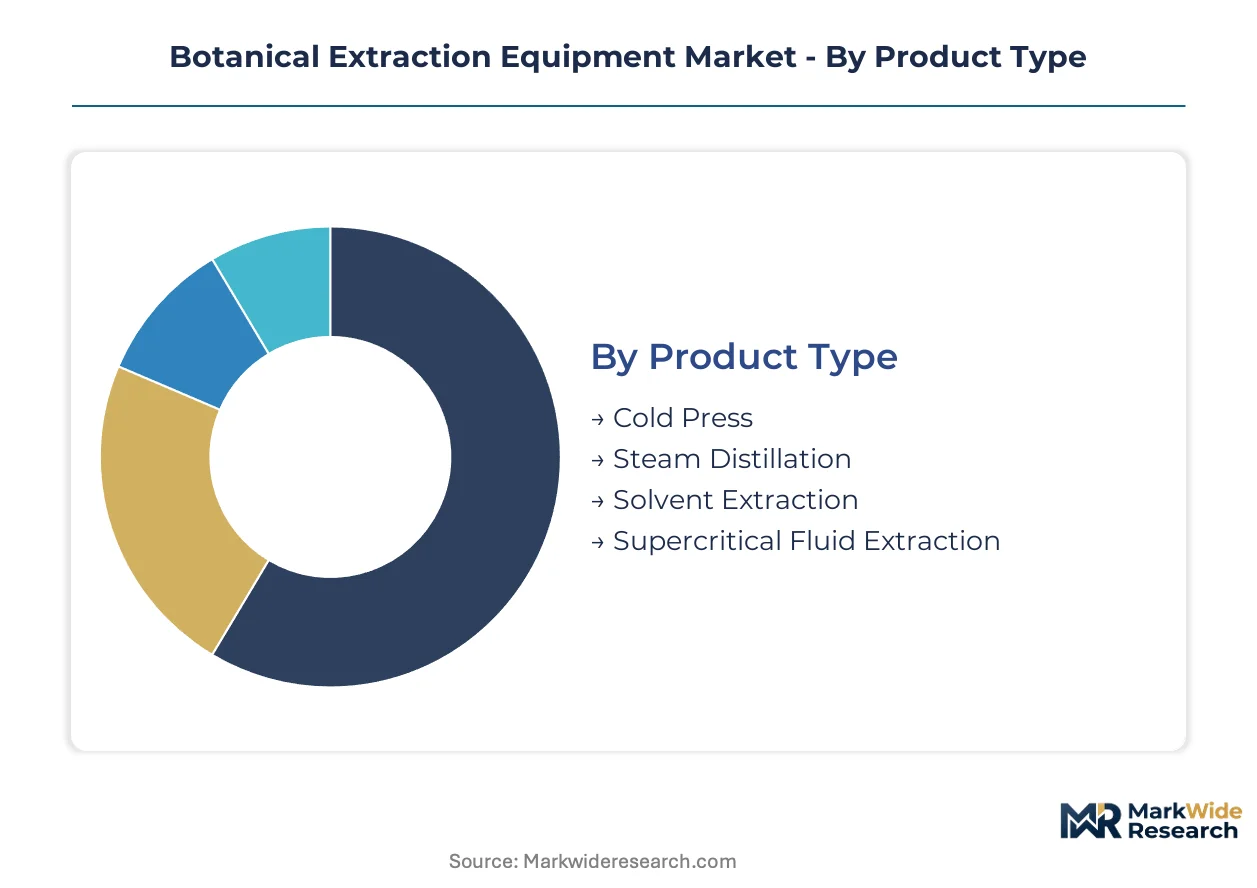
Equipment segmentation in botanical extraction reflects divergent buyer priorities across purity mandates, throughput requirements, and capital deployment capacity. Pharmaceutical manufacturers demand validated stainless-steel systems with batch traceability, while craft botanical processors prioritize compact footprints and terpene preservation.
Product Type:
Pressure and solvent parameters define extraction performance, with each technology occupying distinct positions on the purity-throughput-capital spectrum.
- Cold Press:Mechanical compression at ambient temperature preserves heat-sensitive phytochemicals without solvent introduction. Olive oil processors in Spain and California deploy screw-press configurations for polyphenol retention. Equipment capex stays accessible for small-scale botanical oil producers.
- Steam Distillation:Volatile compound separation through heated water vapor remains dominant for essential oil recovery from lavender, eucalyptus, and citrus matrices. Bulgarian rose oil cooperatives and Indian sandalwood processors maintain installed capacity majority.
- Solvent Extraction:Hydrocarbon or ethanol-based systems achieve highest yields for lipophilic active compounds. German pharmaceutical manufacturers scale capacity to meet EMA GMP Annex 2 documentation requirements.
- Supercritical Fluid Extraction:CO2 above critical point (7.4 MPa, 31°C) delivers solvent-free output with tunable selectivity. Switzerland's phytopharmaceutical hub and California cannabis processors concentrate demand for terpene-preserving configurations.
Solvent extraction leads on scale; supercritical fluid extraction leads on momentum.
Application:
End-use sectors impose divergent validation, throughput, and formulation consistency requirements that reshape equipment procurement priorities.
- Food & Beverage:Flavor and color extraction for natural ingredient labeling compliance drives modular skid-mounted adoption. European botanical extract suppliers prioritize clean-label certification over maximum yield.
- Pharmaceuticals:Active botanical compound isolation demands FDA cGMP and EMA GMP Annex 2 compliant systems with clean-in-place functionality. German and United States manufacturers dominate validated equipment procurement.
- Cosmetics:Essential oil and antioxidant extraction for premium skincare formulations emphasizes batch consistency over throughput maximization. French and Korean cosmetic ingredient suppliers concentrate demand.
- Nutraceuticals:Standardized phytochemical inputs for dietary supplements are displacing batch architectures with continuous extraction for throughput optimization. United States contract manufacturers lead retrofit cycles.
Pharmaceuticals leads on scale; nutraceuticals leads on momentum.
Technology:
Operational architecture determines cycle economics, with continuous systems gaining traction where throughput pressure exceeds legacy equipment depreciation schedules.
- Batch Extraction:Discrete processing cycles dominate installed base across pharmaceutical and essential oil operations. Equipment familiarity and revalidation simplicity sustain procurement preference among conservative buyers.
- Continuous Extraction:Uninterrupted feedstock processing architectures reduce labor intensity and cycle-time variability. United States nutraceutical manufacturers pursuing throughput optimization drive fastest adoption curves.
- Integrated Extraction:Combined extraction-purification workflows reduce intermediate handling and contamination exposure. Swiss phytopharmaceutical facilities prioritize single-train configurations for high-value botanical APIs.
- Manual Extraction:Operator-dependent processing persists in artisanal essential oil and small-batch herbal product segments. Indian and Moroccan traditional medicine producers maintain equipment demand.
Batch extraction leads on scale; continuous extraction leads on momentum.
End User:
Buyer scale and technical capability determine equipment complexity tolerance, with mid-scale processors driving fastest procurement velocity for modular configurations.
- Large Scale Manufacturers:Pharmaceutical and food ingredient multinationals deploy centralized extraction trains with solvent recovery integration. German and United States facilities concentrate demand for stainless-steel validated systems.
- Small Scale Producers:Craft botanical and artisanal essential oil operations prioritize compact supercritical CO2 and cold press units. California cannabis microprocessors and European herbal distilleries drive procurement.
- Research Institutions:Analytical and pilot-scale extraction for phytochemical characterization requires flexible pressure-temperature parameter control. University and government laboratory procurement emphasizes method development compatibility.
- Herbal Products Companies:Traditional medicine and Ayurvedic product manufacturers balance yield optimization with processing cost containment. Indian and Chinese domestic suppliers dominate regional equipment sourcing.
Large scale manufacturers leads on scale; small scale producers leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale botanical extraction originated in European pharmaceutical centers during the post-war standardization of phytochemical manufacturing. Germany and Switzerland established the foundational engineering practices that now propagate through FDA and EMA regulatory harmonization.
United States
California's cannabis processing cluster drives supercritical CO2 system procurement for terpene-preserving extraction configurations. FDA cGMP guidelines mandate stainless-steel construction with clean-in-place functionality for pharmaceutical-grade installations. Greater Boston and the Pacific Northwest concentrate nutraceutical contract manufacturing capacity where continuous extraction architectures displace batch systems.
Germany
EMA GMP Annex 2 compliance requirements propel solvent extraction line retrofits among active pharmaceutical ingredient manufacturers. REACH solvent substitution deadlines accelerate pressurized ethanol and supercritical fluid process investments. Baden-Württemberg and North Rhine-Westphalia host the densest concentration of validated extraction train engineering.
Switzerland
Swissmedic oversight elevates documentation protocol completeness above capital cost in vendor selection matrices. The Basel-Zurich corridor anchors phytopharmaceutical manufacturing where integrated extraction-purification workflows reduce contamination exposure. Domestic facilities prioritize single-train configurations for high-value botanical APIs.
India
CDSCO regulatory harmonization with ICH guidelines creates first-mover positioning for cGMP-compliant equipment suppliers. Maharashtra and Gujarat concentrate phytopharmaceutical manufacturing investment responding to export market certification requirements. Traditional Ayurvedic processing clusters in Kerala and Karnataka balance yield optimization with cost containment.
China
NMPA botanical drug registration reforms standardize extraction methodology documentation for domestic and export markets. Yangtze River Delta pharmaceutical manufacturers scale solvent recovery capacity to meet emission control mandates. Pearl River Delta essential oil processors deploy steam distillation for lavender and citrus volatile compound recovery.
Botanical Extraction Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification completeness and validation documentation depth. The vendor base stratifies between large-scale separation technology heritage firms and compact system specialists serving craft botanical entrants. Three archetypes dominate: integrated process engineering conglomerates, precision pump and vessel fabricators, and skid-mounted modular system integrators. Capacity expansion and geographic licensing partnerships constitute the dominant competitive moves as regulatory divergence across jurisdictions fragments standardization pathways.
Within the integrated process engineering tier, Alfa Laval and GEA exemplify large-scale solvent recovery heritage positioning. Eden Labs occupies a position among compact supercritical fluid specialists addressing small-scale craft botanical processors. Buchi Labortechnik AG represents precision laboratory and pilot-scale equipment archetypes serving analytical method development workflows.
| Leading Market Players |
|---|
| Alfa Laval |
| GEA |
| Eden Labs |
| Andritz |
| Flottweg |
| GTech Bellmor |
| Buchi Labortechnik AG |
| Waters Corporation |
| Cheersonic |
| Others |
Value Network & Pricing Analysis
Specialized high-pressure systems engineering talent concentrated in Germany and Switzerland creates labor-cost differentials that widen pricing-tier spreads between premium supercritical CO2 configurations and standard solvent extraction units. FDA cGMP and EMA GMP Annex 2 validation documentation requirements compress margins for mid-tier equipment suppliers while elevating certified stainless-steel construction premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical-grade systems from food-grade modular units and manual artisanal configurations. Price differentiation rests on certification completeness and clean-in-place functionality depth. Cost compression in the economy tier is intensifying because Indian and Chinese domestic suppliers expand capacity without Western validation overhead. Contract manufacturers in the nutraceutical segment exhibit highest price sensitivity; Swiss phytopharmaceutical facilities show least sensitivity due to single-train configuration requirements.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for pharmaceutical manufacturing equipment are redirecting component sourcing toward Maharashtra and Gujarat fabrication clusters. High-pressure vessel fabrication draws from German and Swiss precision engineering bases; precision pump systems sources from United States and Japanese fluid handling specialists. Single-source vulnerability concentrates in supercritical CO2 compressor assemblies. Distribution runs through direct OEM sales for large pharmaceutical installations and regional distributor networks for craft botanical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EMA GMP Annex 2 compliance deadlines force pharmaceutical manufacturers toward premium validated systems regardless of capital cost premiums.
For Market Incumbents: Lock in approved vendor list status at German and United States active pharmaceutical ingredient manufacturers before CDSCO harmonization opens Indian procurement to new entrants. Backward integration into precision pump manufacturing defends margin position against Japanese fluid handling specialists expanding into extraction system bundling. Certification investment in Swissmedic documentation protocols creates switching-cost barriers. For New Entrants and Emerging Players: REACH solvent substitution deadlines in Europe open a window for pressurized ethanol and supercritical CO2 system specialists to capture retrofit cycles at German extraction facilities. Target India's phytopharmaceutical manufacturing expansion in Maharashtra and Gujarat where CDSCO regulatory harmonization creates first-mover positioning for cGMP-compliant equipment suppliers. Go-to-market through analytical method development partnerships with university laboratories builds reference installations. For Investors and Strategic Acquirers: Integrated process engineering conglomerates are the most active acquirer in this space, seeking precision vessel fabrication capabilities to complete extraction-purification workflow coverage. Five-to-ten year viability favors suppliers with dual certification depth across FDA and EMA jurisdictions. Watch for Swissmedic documentation protocol revisions as inflection indicator accelerating vendor consolidation toward full-validation specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Modular skid-mounted architectures let food processors scale without plant reconstruction. |
| Backward Integration | In-house precision pump production reduces dependency on Japanese fluid handling suppliers. |
| Certification Investment | Swissmedic and FDA cGMP documentation depth elevates approved vendor list positioning. |
| Geographic Expansion | Indian phytopharmaceutical clusters in Maharashtra create first-mover licensing opportunities. |
| Joint Venture | University laboratory partnerships build reference installations for analytical scale configurations. |
Research Methodology
Direct dialogue with extraction plant engineers, pharmaceutical procurement directors, regulatory affairs specialists, and craft botanical processors anchored qualitative grounding. Secondary validation drew from FDA 483 inspection observations, EMA GMP inspection deficiency databases, CDSCO guidance documents, and Swissmedic manufacturing authorization registers. Bottom-up equipment shipment analysis triangulated against top-down pharmaceutical capital expenditure disclosures across the analysis window.
Bottom-up modeling aggregated unit-level procurement patterns by pressure rating, vessel capacity, and automation tier. Segmentation dimensions spanned extraction technology, application sector, operational architecture, and end-user scale class. CAGRs derived from regression against pharmaceutical manufacturing investment cycles and cannabis processing license issuance trajectories. Supercritical CO2 adoption curves and continuous extraction retrofit rates supplied industry-specific forecast inputs.
Revisions become necessary when EMA or FDA guidance document revisions materially alter validation protocol requirements, or when REACH authorization schedules accelerate solvent substitution timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Asia-Pacific Transfection Reagent and Equipment Market
Biotechnology Equipment
Laboratory Andrology Equipment Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Airlift Bioreactors Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Small-Scale Bioreactors Market