
 Global Continuous Bioprocessing Market | 2026-2036
Global Continuous Bioprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
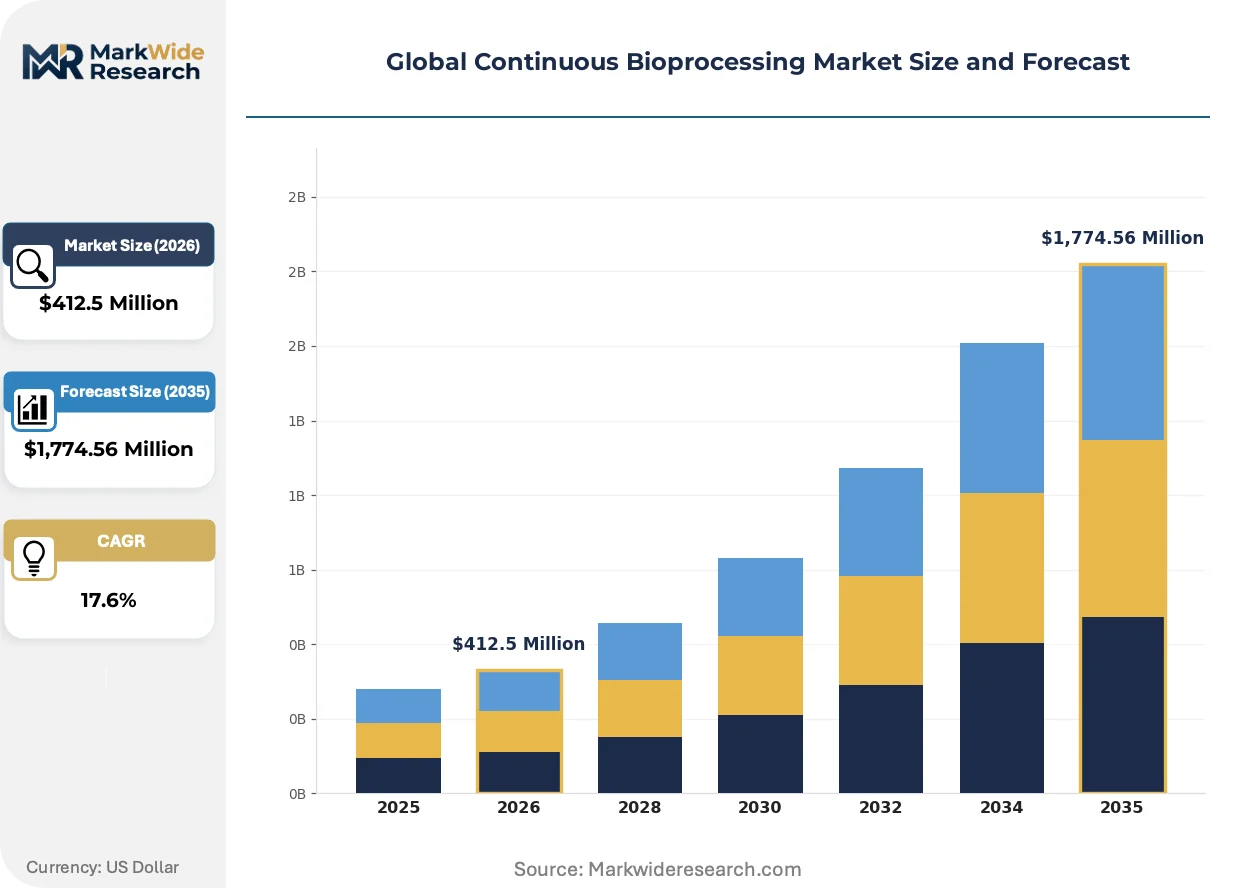
Global Continuous Bioprocessing Market Foresight
ISO 14644 cleanroom classification is unwinding the competitive landscape for equipment suppliers. Thermo Fisher Scientific leverages its integrated automation portfolio to anchor large-scale perfusion deployments. Danaher Corporation sustains technology leadership through chromatography and filtration synergies across its operating companies.
Continuous bioprocessing refers to the uninterrupted production of biologics where cells, media, and products flow steadily through interconnected unit operations rather than discrete batch cycles, typically operating at perfusion rates of 1-2 reactor volumes per day with real-time process analytical technology monitoring. The approach eliminates hold times, reduces facility footprints, and enables steady-state quality profiles for monoclonal antibodies and viral vectors. Single-use bioreactors and perfusion systems command the dominant installed base, while membrane filtration and continuous centrifugation technologies capture expanding margin pools as titers rise and harvest economics tighten. Chromatography remains the most technically contested segment as multi-column periodic counter-current systems displace batch protein A capture.
FDA process validation guidance, EMA's Good Manufacturing Practice Annex 15, and ISO 13485 quality management standards collectively elevate barrier-to-entry for new equipment entrants while accelerating replacement cycles among established biopharmaceutical manufacturers. Contract manufacturing organizations face compressed timelines to demonstrate continuous process equivalency against legacy batch filings. Stakeholders must weigh capital redeployment toward integrated digital twin platforms against modular retrofit strategies as regulatory precedents for continuous biologics licensure accumulate.
Market Dynamics
Perfusion-based manufacturing platforms are compressing batch cycle economics and forcing biopharmaceutical manufacturers to reconfigure facility layouts around continuous unit operations rather than discrete stainless-steel trains.
Growth Catalysts
- EMA Good Manufacturing Practice Annex 15:The guideline's emphasis on real-time release testing validates continuous process analytical technology investments by major biologics manufacturers.
- Perfusion bioreactor titers:Steady-state cell densities exceeding 100 million cells per milliliter in Chinese hamster ovary lines compress downstream harvest volumes and facility capital intensity.
- Multi-product facility expansion:Contract manufacturing organizations in Germany, the United States, and Singapore are retrofitting legacy batch suites for continuous monoclonal antibody production.
Market Restraints
- Single-use consumables cost structure:Perfusion cell culture bags and sterile connectors represent 35-45 percent of variable production costs at commercial scale.
- Filtration membrane supply concentration:Hollow-fiber and flat-sheet membrane manufacturing clusters in the United States and Japan create single-source vulnerability for perfusion system operators.
- Chromatography resin binding capacity:Protein A capture resins exhibit throughput limitations above 5 grams per liter per hour under continuous loading conditions.
Strategic Opportunities
- India biologics manufacturing:CDSCO's accelerated approval pathways for biosimilars create first-mover advantage for continuous process filings by multinational sponsors.
- Digital twin integration:Convergence of mechanistic modeling with real-time spectroscopic sensors enables predictive control of perfusion rate and viability.
- Cell and gene therapy viral vectors:Adeno-associated virus production in perfusion mode addresses yield bottlenecks that constrain gene therapy commercialization.
Industry Challenges
- Process analytical technology calibration:Raman and near-infrared spectroscopy models require extensive training datasets across clone and media variations.
- Legacy batch filing equivalence:Demonstrating comparability between continuous and historical batch data packages consumes 18-24 months of regulatory preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Continuous Bioprocessing Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,774.56 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Bioreactors, Fixed-Bed Bioreactors, Hollow Fiber Bioreactors, Packed-Bed Bioreactors, Perfusion Systems Technology: Membrane Filtration, Chromatography, Cell Culture, Microcarrier, Continuous Centrifugation Application: Monoclonal Antibodies, Vaccines, Recombinant Proteins, Cell & Gene Therapy, Viral Vectors End User: Biopharmaceutical Manufacturers, Contract Manufacturing Organizations, Research Institutes, Academic Laboratories |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Sartorius AG, Merck KGaA, Repligen Corporation, 3M, Eppendorf SE, Lonza Group AG, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Continuous Bioprocessing Market Shifts & Advancements
Automation architectures are collapsing the boundary between upstream cell culture and downstream purification, enabling closed-loop control that was technically inaccessible under batch paradigms.
Micro-bioreactor systems with working volumes below 250 milliliters are miniaturizing process development workflows for perfusion parameter optimization. Biopharmaceutical manufacturers deploy these systems at 10-20x throughput versus traditional 2-liter glass vessels. The approach compresses clone selection timelines from twelve months to four months while preserving predictive correlation to manufacturing scale.
REACH chemical registration requirements for novel perfusion media components are forcing reformulation of proprietary feeds and basal mixtures. Suppliers must disclose substance identity and tonnage thresholds that were previously protected as trade secrets. European biomanufacturers face 18-24 month delays for new media qualification while awaiting ECHA dossier approvals.
Buyers are consolidating vendor relationships around integrated continuous bioprocessing platforms rather than assembling point solutions. Large-cap biopharmaceutical companies now specify single-source accountability for perfusion, harvest, and capture chromatography modules. This preference shift disadvantages specialized equipment suppliers in the United States and Germany who lack downstream breadth.
Global Continuous Bioprocessing Market Segmentation
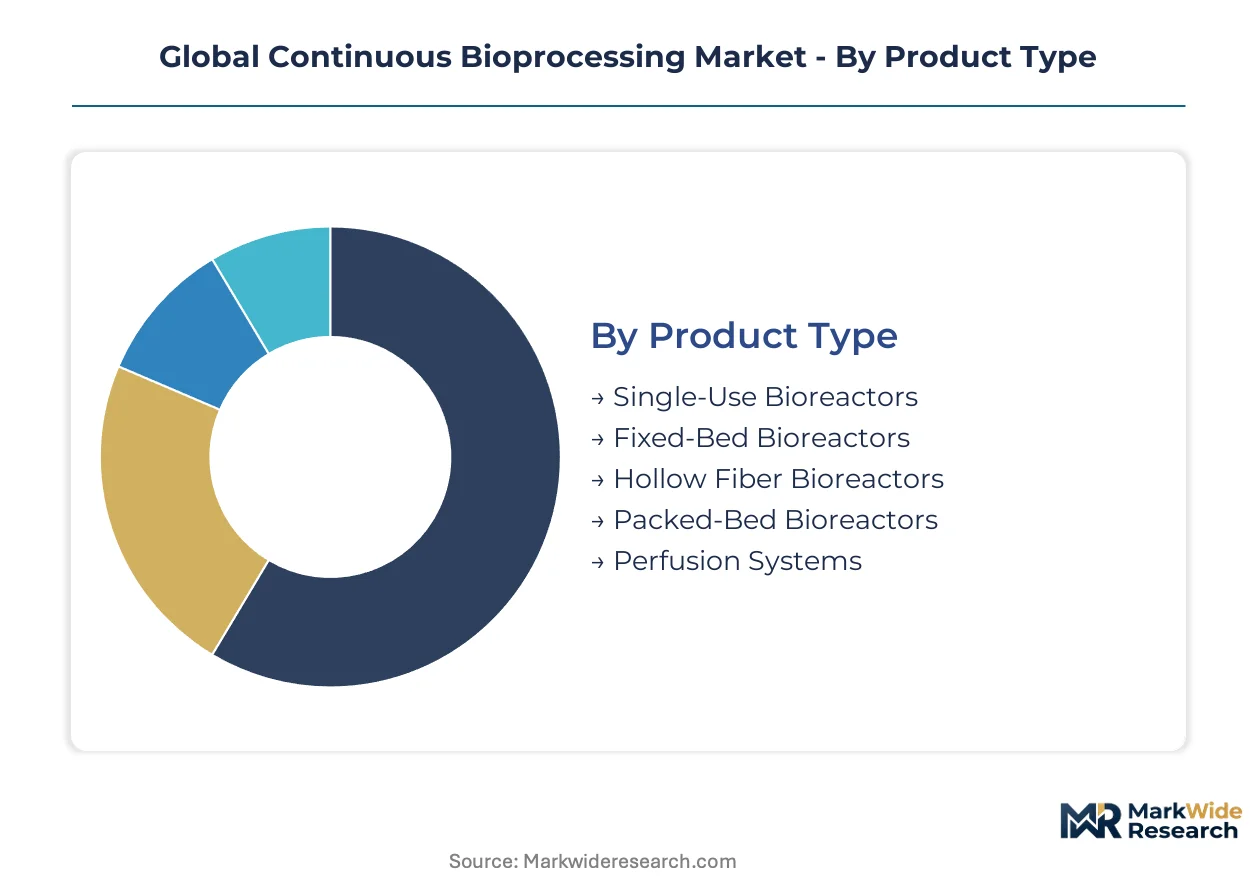
Segmentation reveals where equipment vendors and consumables suppliers capture differentiated returns. Technology choices determine facility capital intensity, while application mix dictates regulatory complexity and batch release economics.
Product Type:
Margin pools concentrate in systems that enable steady-state operation at high cell densities with minimal operator intervention.
- Single-Use Bioreactors:Polymeric vessels with integrated sensors eliminate cleaning validation cycles and reduce cross-contamination risk in multi-product facilities. Demand clusters in the United States and Germany where contract manufacturing organizations retrofit legacy stainless-steel suites for perfusion monoclonal antibody production.
- Perfusion Systems:Integrated platforms combining cell retention devices with automated media exchange control steady-state operation at 1-2 reactor volumes per day. Chinese hamster ovary line manufacturers in China and Singapore deploy these systems to compress downstream harvest volumes as titers exceed 5 grams per liter.
- Hollow Fiber Bioreactors:Capillary-based perfusion systems support adherent cell cultures for viral vector manufacturing with low shear stress environments.
- Fixed-Bed Bioreactors:Macroporous carriers immobilize cells within a packed matrix for continuous product secretion without cell retention devices.
- Packed-Bed Bioreactors:Denser cell immobilization enables high volumetric productivity for secreted recombinant proteins in perfusion mode.
The dominant share belongs to single-use bioreactors, while perfusion systems are closing the gap fastest.
Technology:
Technology selection hinges on whether the process goal is cell retention, product purification, or integrated closed-loop control.
- Chromatography:Multi-column periodic counter-current systems displace batch protein A capture through continuous loading above 5 grams per liter per hour. Biopharmaceutical manufacturers in Germany and Switzerland prioritize these systems for monoclonal antibody facilities seeking real-time release testing under EMA Annex 15.
- Membrane Filtration:Tangential-flow and perfusion membranes enable cell retention and product concentration with automated flux control. Supply concentration in the United States and Japan creates sourcing vulnerability for perfusion system operators dependent on hollow-fiber and flat-sheet geometries.
- Cell Culture:Perfusion media formulation and feeding strategies sustain steady-state viability above 90 percent over 60-day campaigns.
- Continuous Centrifugation:Disc-stack and tubular bowl systems harvest high-density cultures without membrane fouling at titers above 10 million cells per milliliter.
- Microcarrier:Bead-based supports enable adherent cell expansion in stirred-tank bioreactors for vaccine and viral vector production.
Chromatography commands the highest equipment margins, though membrane filtration is expanding most quickly as titers rise.
Application:
Application mix determines regulatory pathway complexity and process analytical technology investment intensity.
- Monoclonal Antibodies:Well-characterized glycoproteins with established critical quality attributes enable platform perfusion processes transferable across molecules. FDA process validation guidance drives adoption in the United States, while EMA Annex 15 accelerates European deployments.
- Cell & Gene Therapy:Autologous and allogeneic therapies demand closed, automated manufacturing to meet release specifications for living drug products. Viral vector production in perfusion mode addresses yield bottlenecks constraining adeno-associated virus commercialization.
- Vaccines:Continuous egg-free and cell-based production platforms replace batch embryonated egg processes for pandemic readiness.
- Recombinant Proteins:Insulin, growth factors, and enzymes leverage perfusion to achieve consistent post-translational modification profiles.
- Viral Vectors:Lentiviral and adenoviral platforms for gene therapy require specialized containment and separation technologies.
Monoclonal antibodies retain the largest installed base, while cell and gene therapy is climbing the fastest.
End User:
End user type shapes procurement patterns between capital-intensive platform purchases and flexible consumables contracts.
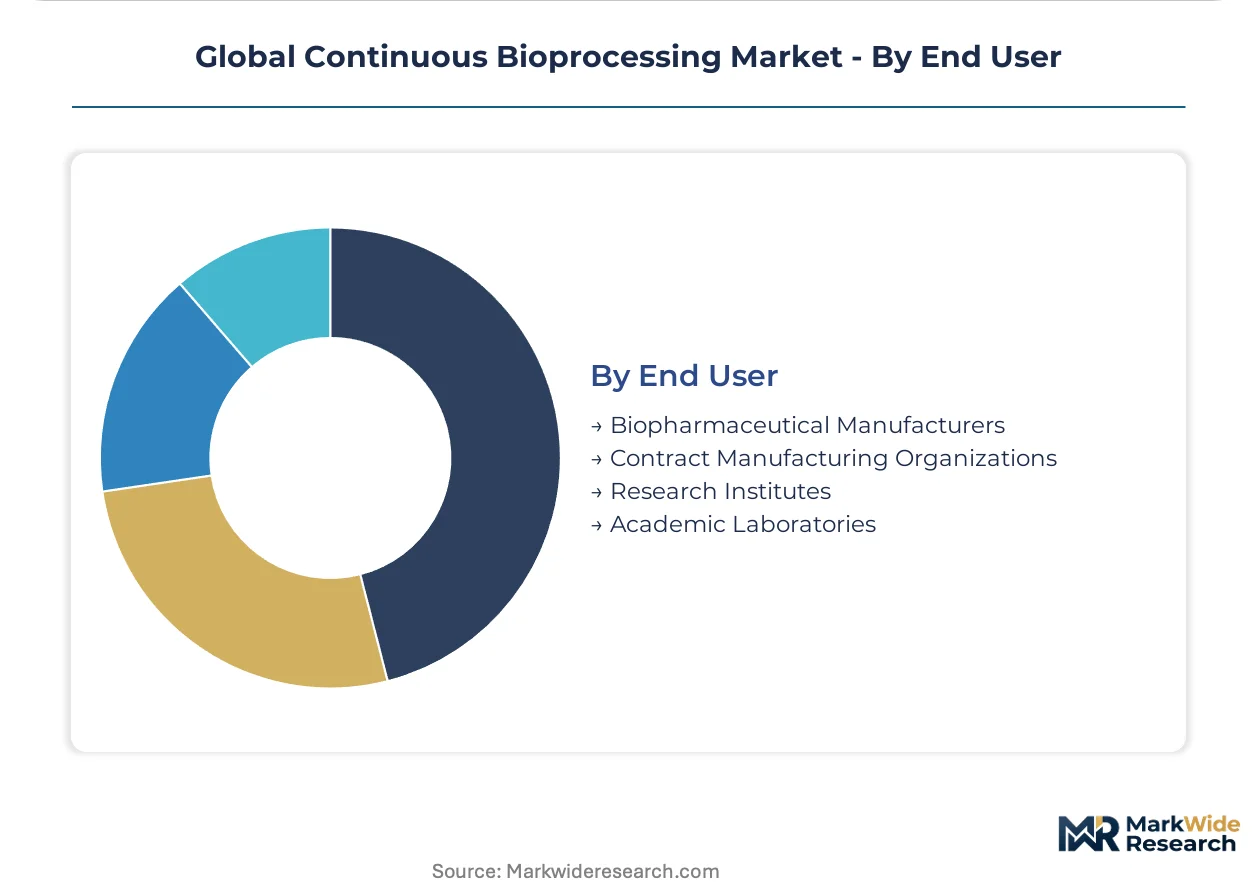
- Biopharmaceutical Manufacturers:Large-cap companies specify single-source accountability for integrated perfusion, harvest, and capture chromatography modules. Thermo Fisher Scientific and Danaher Corporation anchor these relationships through automation and filtration synergies.
- Contract Manufacturing Organizations:Multi-product facilities in Singapore, Germany, and the United States retrofit legacy batch suites to secure continuous process biologics contracts from multinational sponsors.
- Research Institutes:Micro-bioreactor systems below 250 milliliters compress clone selection timelines from twelve months to four months for perfusion parameter optimization.
- Academic Laboratories:Access to shared continuous processing infrastructure depends on national research council funding priorities and industry partnership structures.
Biopharmaceutical manufacturers dominate capital deployment, though contract manufacturing organizations are gaining share fastest as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA process validation guidance and EMA's Annex 15 framework are accelerating facility retrofits across major biomanufacturing clusters. National regulators in Germany, China, and Singapore are aligning inspection protocols with continuous process analytical technology standards.
United States
Large-cap biopharmaceutical manufacturers in Massachusetts and North Carolina are retrofitting legacy stainless-steel suites for perfusion monoclonal antibody production. FDA guidance on real-time release testing validates investments in integrated automation platforms. The Greater Boston cluster anchors contract manufacturing organization expansion for continuous viral vector manufacturing.
Germany
Multi-product facilities in Bavaria and Baden-Württemberg prioritize multi-column periodic counter-current chromatography systems for real-time release testing under EMA Annex 15. The country's national pharmaceutical regulator enforces stringent Good Manufacturing Practice standards for continuous biologics licensure. Basel-adjacent manufacturing corridors attract Swiss-sponsored perfusion platform deployments.
China
Domestic biologics manufacturers in Shanghai and Suzhou deploy perfusion systems to compress downstream harvest volumes as Chinese hamster ovary titers exceed 5 grams per liter. NMPA accelerated approval pathways for biosimilars incentivize first-mover continuous process filings. The Yangtze River Delta concentrates single-use bioreactor demand from emerging biopharmaceutical sponsors.
Singapore
Contract manufacturing organizations retrofit legacy batch suites to secure continuous process biologics contracts from multinational sponsors. The country's national pharmaceutical regulator harmonizes inspection standards with FDA and EMA precedents for perfusion-based manufacturing. Tuas Biomedical Park anchors integrated continuous processing infrastructure investments.
Switzerland
Swissmedic oversight of continuous biologics licensure accumulates regulatory precedents that shape European validation requirements. Basel and Zurich host specialized chromatography and filtration technology development for monoclonal antibody facilities. The country's precision manufacturing base supplies membrane filtration components to German perfusion system operators.
Global Continuous Bioprocessing Market Competitive Landscape
Listed leaders compete with private specialists across automation and filtration technology portfolios. The vendor base consolidates around integrated platform providers capable of single-source accountability for perfusion, harvest, and capture chromatography modules. Three archetypes dominate: diversified life science conglomerates with automation synergies, filtration-focused specialists with membrane technology depth, and chromatography purists with multi-column system expertise. Competitive moves center on strategic partnerships for digital twin integration and geographic expansion into India biologics manufacturing.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify platform integration strategies. Sartorius AG occupies a position among filtration-focused specialists with German manufacturing heritage. These three entities anchor vendor consolidation trends as large-cap biopharmaceutical manufacturers specify single-source accountability requirements.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Sartorius AG |
| Merck KGaA |
| Repligen Corporation |
| 3M |
| Eppendorf SE |
| Lonza Group AG |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
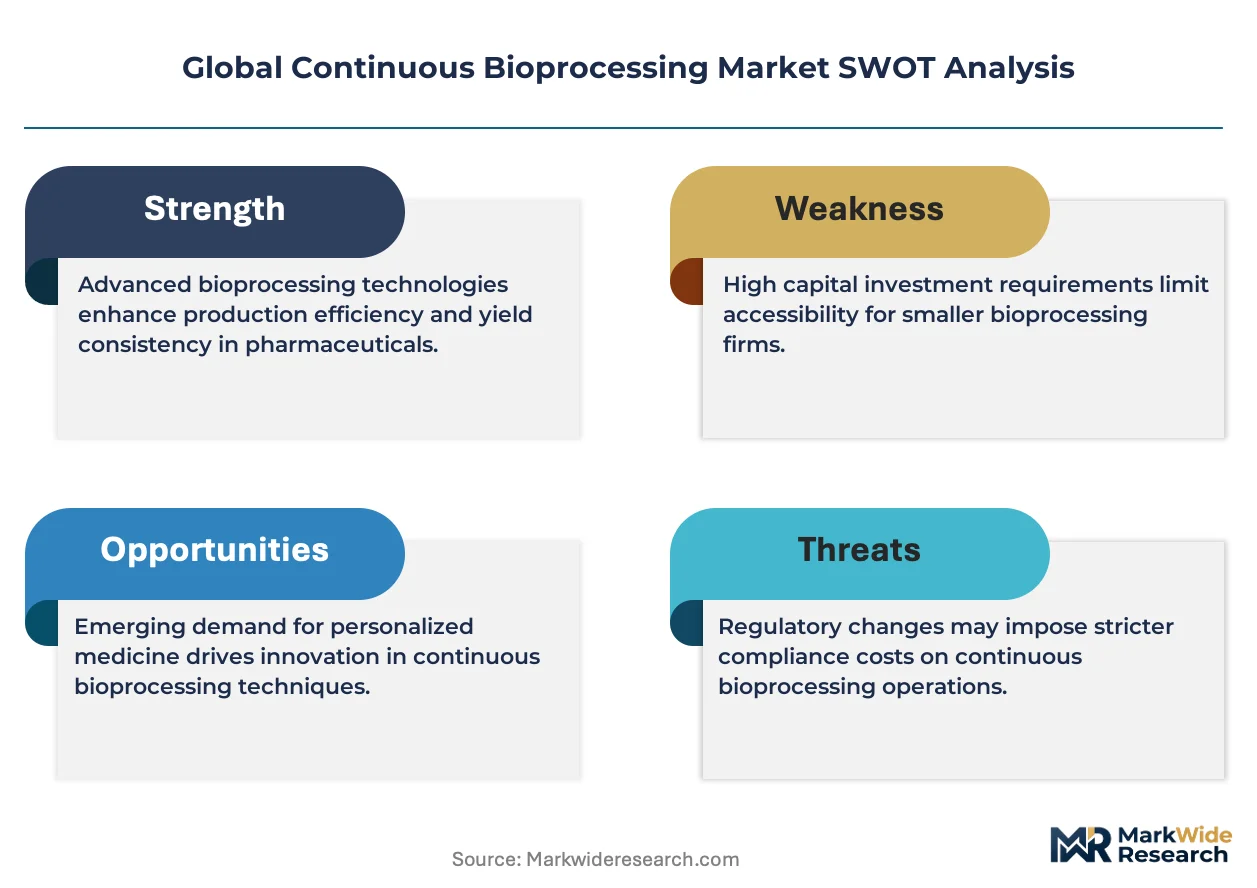
ISO 13485 quality management certification gates both equipment supplier qualification and price differentiation across the Global Continuous Bioprocessing Market, compressing margin structures for uncertified entrants while enabling premium positioning for validated automation platforms.
Pricing Analysis
Certification level (ISO 14644/FDA-grade) creates the primary spread between equipment tiers, with validated perfusion systems commanding substantial premiums over non-validated alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects automation depth, sensor integration density, and regulatory documentation packages. Cost compression in single-use consumables is intensifying because hollow-fiber membrane supply concentration limits vendor switching. Contract manufacturing organizations exhibit highest price sensitivity due to compressed client margins, while large-cap biopharmaceutical manufacturers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Hollow-fiber membrane manufacturing clusters in the United States and Japan create single-source vulnerability for perfusion system operators dependent on specific fiber geometries and molecular weight cutoffs. The supply chain draws from German precision engineering for chromatography skids, Swiss filtration components, and Chinese single-use vessel molding. Tariff exposure runs through polymer resin imports subject to REACH registration delays. Distribution runs through direct OEM relationships for large-scale deployments and distributor networks for research-scale systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Continuous Bioprocessing Market represents a platform-economics inflection where integrated automation ecosystems displace point-solution vendors, driven by FDA and EMA convergence on real-time release testing standards that demand interoperability across perfusion, harvest, and capture chromatography modules.
For Market Incumbents: Consolidate automation portfolios around single-source accountability for continuous bioprocessing platforms, deepening chromatography-filtration synergies to defend against modular retrofit competitors. Expand service revenue through predictive maintenance contracts tied to digital twin deployments. Prioritize backward integration into membrane manufacturing to reduce supply concentration risk. For New Entrants and Emerging Players: Anchor in India biologics manufacturing where CDSCO accelerated approval pathways for biosimilars create first-mover advantage for continuous process filings. Target viral vector production for cell and gene therapy applications, where yield bottlenecks and specialized containment requirements favor nimble automation specialists over legacy batch equipment vendors. Pursue partnership-based go-to-market models with contract manufacturing organizations in Singapore and Germany. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed filtration specialists lacking downstream chromatography breadth. The five-to-ten year viability window favors platforms with demonstrated FDA continuous biologics licensure precedents. Watch for inflection signals in digital twin integration capabilities, as mechanistic modeling convergence with real-time spectroscopic sensors separates acquisition-ready targets from stranded technology bets.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Predictive control of perfusion rate and viability compresses process development timelines for monoclonal antibody manufacturers. |
| Regulatory Precedent Accumulation | FDA continuous biologics licensure filings validate platform investments and create barrier-to-entry for non-validated competitors. |
| Membrane Manufacturing Backward Integration | In-house production of hollow-fiber components reduces single-source vulnerability and stabilizes variable cost structures. |
| Cell and Gene Therapy Viral Vector Expansion | Perfusion-mode adeno-associated virus production addresses yield constraints constraining gene therapy commercialization. |
| Multi-Product Facility Retrofit | Legacy batch suite conversions in Germany and Singapore secure continuous process biologics contracts from multinational sponsors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with bioprocess engineers, regulatory affairs specialists at biopharmaceutical manufacturers, contract manufacturing organization facility directors, and filtration technology procurement leads. Secondary validation drew from FDA guidance documents, EMA Annex 15 revisions, ISO 14644 cleanroom standards, and SEC filings of listed life science conglomerates. Bottom-up equipment shipment estimates and top-down biologics capacity expansion projections were triangulated to anchor market sizing.
Across the analysis window, the forecast framework modeled product type segmentation (single-use bioreactors, perfusion systems, chromatography skids), technology categories (membrane filtration, continuous centrifugation, multi-column capture), application mix (monoclonal antibodies, cell and gene therapy, vaccines), and end-user archetypes (large-cap manufacturers, contract manufacturing organizations, research institutes). CAGRs were derived from segment-level growth rate distributions weighted by installed base evolution and replacement cycle acceleration. Forecast inputs included perfusion bioreactor titer trajectories, regulatory approval pathway timelines, and single-use consumables cost elasticity assumptions.
Material uncertainties — EMA Annex 15 implementation delays, REACH chemical registration backlogs for novel media components, and hollow-fiber membrane supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization and technology adoption curves that could shift with macroeconomic conditions or competitive dynamics. Practitioners should keep alternative scenarios live as FDA and EMA inspection protocol convergence for continuous biologics evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Bioartificial Renal Assist Devices Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Tissue Expansion Market