
 Americas Acrylic Teeth Market | 2026-2036
Americas Acrylic Teeth Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Acrylic Teeth Market Analysis
EPA dental amalgam effluent guidelines is hardening sustainability compliance across North American dental manufacturing, pushing laboratories toward PMMA-based alternatives with lower environmental discharge profiles. Dentsply Sirona leverages its vertically integrated resin compounding network to control raw material quality from polymer synthesis through finished tooth fabrication. Ivoclar Vivadent anchors premium positioning through proprietary nanofiller reinforcement technologies that extend acrylic tooth wear resistance. Keystone Industries competes on regional manufacturing proximity, operating production assets that reduce lead times to Latin American distributors.
Americas acrylic teeth are cross-linked polymethyl methacrylate prosthetic devices manufactured through compression molding or injection molding processes, with Vickers hardness ratings typically ranging from 20 to 30 HV to balance occlusal durability against ridge resorption protection. Their primary commercial purpose is restoring masticatory function and aesthetic appearance in edentulous or partially edentulous patients across dental clinic and laboratory workflows. Full dentures occupy the largest volume share given aging demographic profiles across the Americas, while partial dentures represent the fastest-expanding category as tooth-retained prosthodontics gains preference over implant-only solutions. Dental laboratories command the dominant procurement channel position, though direct-to-clinic distribution is gaining share as chairside digital workflows compress traditional intermediary roles.
FDA 510(k) clearance requirements govern acrylic teeth marketed in the United States, while Health Canada's Medical Devices Bureau applies comparable biocompatibility standards under the Canadian Medical Devices Regulations. Brazil's ANVISA maintains distinct polymer purity testing protocols that create additional compliance layers for manufacturers serving Latin America's largest national market. Stakeholders must monitor evolving dental device reclassification proposals across multiple Americas jurisdictions, as regulatory convergence or divergence will reshape registration cost structures and competitive access timelines.
Market Dynamics
Government reimbursement programs across Brazil and Mexico are expanding prosthodontic access, creating volume pull-through that reshapes procurement patterns across dental laboratory networks. FDA biocompatibility standards and evolving ISO dental material certifications are hardening material compliance requirements for cross-linked PMMA formulations, forcing manufacturers to recalibrate quality systems.
Growth Catalysts
- ANVISA reimbursement expansion:Brazil's national health regulator has broadened prosthodontic coverage under public dental programs, driving acrylic teeth procurement volumes through São Paulo state laboratory clusters.
- Compression molding scale economies:Dental laboratories serving Latin American trade corridors are consolidating production runs to capture unit cost reductions on full denture bases.
- Digital workflow integration:Chairside CAD/CAM systems are compressing traditional intermediary roles, accelerating direct-to-clinic distribution channel development.
Market Restraints
- Methyl methacrylate price volatility:Petrochemical feedstock fluctuations create margin pressure for manufacturers lacking captive resin supply.
- São Paulo production concentration:Geographic clustering of dental laboratory capacity exposes supply chains to localized logistics disruptions.
- ISO 22112 certification timelines:Extended testing protocols for denture base polymers delay new product registrations across multiple Americas jurisdictions.
Strategic Opportunities
- Mexico's underpenetrated northern states:Chihuahua and Nuevo León present expansion potential as cross-border dental tourism corridors mature.
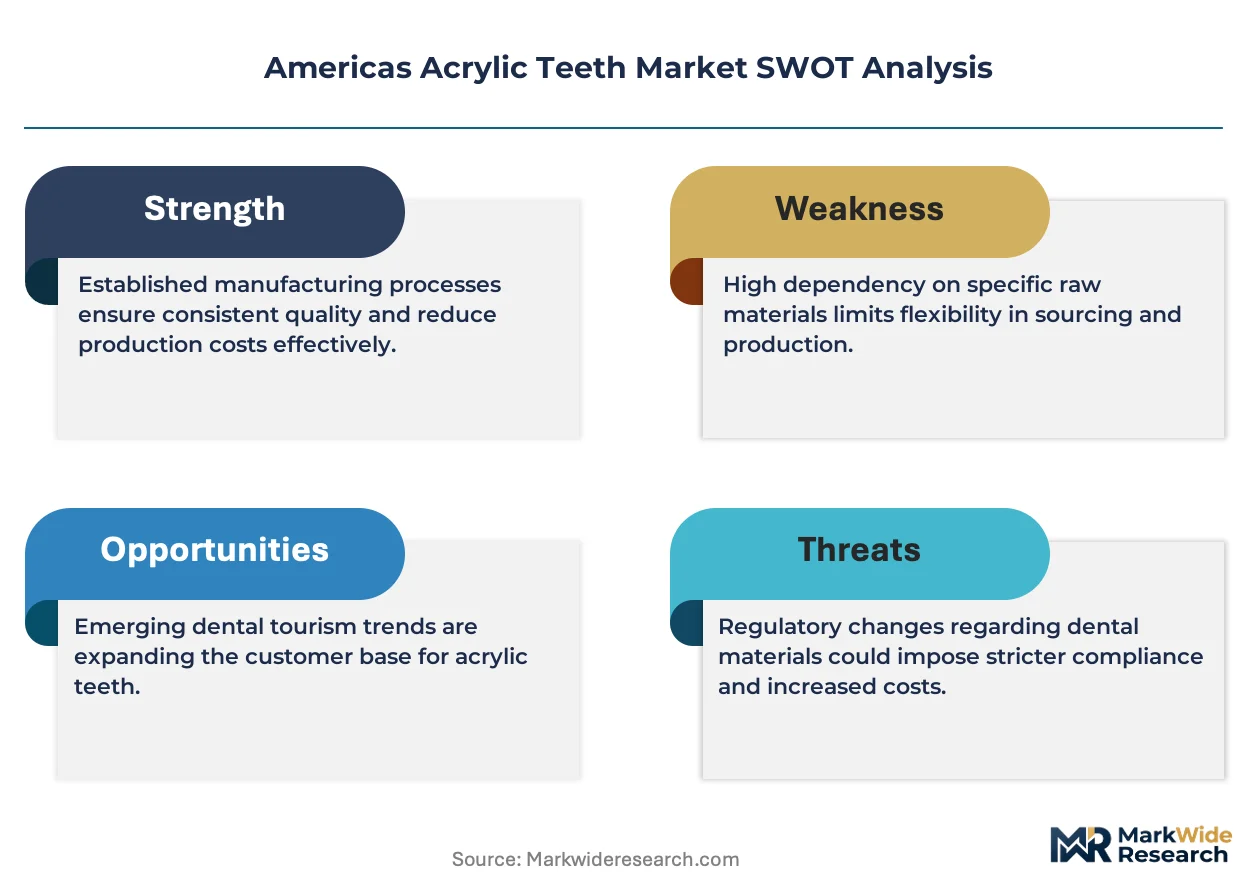
- EPA dental amalgam effluent compliance:North American sustainability mandates are pushing laboratories toward PMMA-based alternatives with lower environmental discharge profiles.
- 3D printing convergence:Photopolymer jetting technologies are enabling same-day denture fabrication, opening chairside production models.
Industry Challenges
- Prosthodontic technician scarcity:Specialized mold finishing and characterization skills are aging out of the workforce faster than training programs replenish supply.
- Legacy equipment integration:Digital impression systems require capital reconfiguration for laboratories operating traditional flask-and-press workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Acrylic Teeth Market |
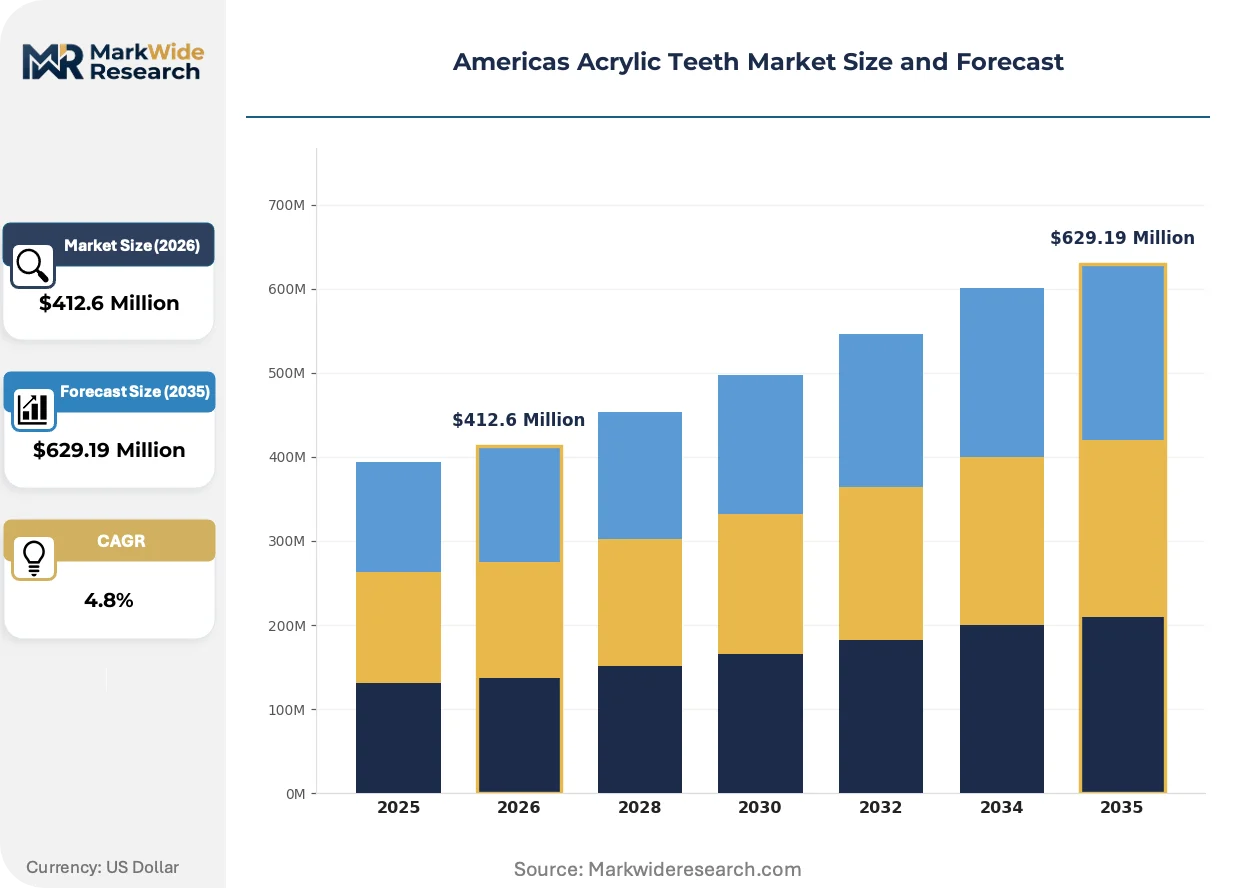
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Dentures, Partial Dentures, Temporary Dentures, Immediate Dentures Application: Hospitals, Dental Clinics, Mobile Dental Services, Home Care Material: PMMA, Acrylic Resin, Biocompatible Polymers, Composite Materials Customer Type: Individuals, Dental Professionals, Dental Laboratories, Institutions |
| Companies Covered | Heraeus Kulzer, GC Corporation, Dentsply Sirona, Keystone Industries, Lang Dental Manufacturing Co., Inc., Ivoclar Vivadent, 3M ESPE, New Stetic, Vita Zahnfabrik H. Rauter, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Acrylic Teeth Market Emerging Trajectories
Material science advances and regulatory convergence are compressing product development cycles while reshaping competitive differentiation around biocompatibility credentials. Digital manufacturing technologies are fragmenting traditional production hierarchies between centralized laboratories and chairside workflows.
Injection-molded acrylic teeth are overtaking compression-molded alternatives in high-throughput dental laboratories. Brazilian and Mexican distributors are prioritizing these formulations for their dimensional stability and reduced porosity. The technology is overtaking legacy production methods by enabling standardized shade matching at scale while compressing per-unit labor requirements.
Health Canada's Medical Devices Bureau is tightening biocompatibility documentation requirements under revised Canadian Medical Devices Regulations. Manufacturers must now submit extended cytotoxicity testing for PMMA formulations destined for Canadian dental clinics. Premium nanofiller-reinforced product lines face the steepest compliance cost increases as testing protocols expand.
Dental laboratories are unbundling after-sales shade customization services from base tooth procurement. Large clinic chains across the United States are negotiating direct supply agreements that bypass traditional distributor markups. This pattern is most visible in Florida and Texas, where dental service organizations are consolidating purchasing power across multi-location networks.
Americas Acrylic Teeth Market Segmentation
Acrylic teeth procurement patterns diverge sharply across clinical settings and material specifications. Each segmentation axis reveals distinct cost sensitivities, regulatory exposure, and workflow integration requirements that reshape competitive positioning.
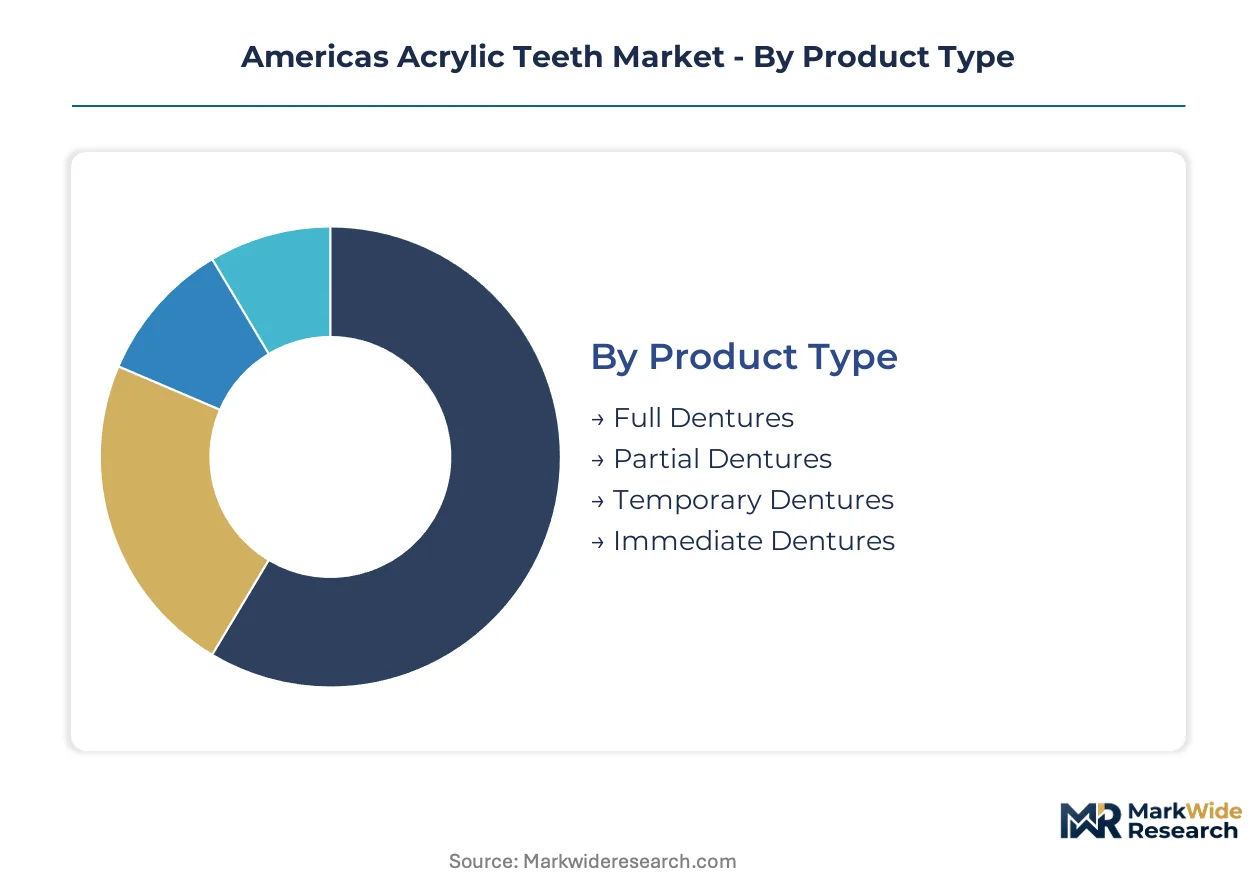
Product Type:
Prosthodontic complexity and reimbursement eligibility separate buyers across this dimension.
- Full Dentures:Complete arch replacements fabricated from cross-linked PMMA formulations with Vickers hardness ratings between 20-30 HV. Brazil's São Paulo state laboratory cluster processes the highest procurement volumes as ANVISA reimbursement programs expand public dental access.
- Partial Dentures:Tooth-retained prosthetics combining acrylic teeth with cobalt-chromium or flexible nylon frameworks. Demand concentrates in Mexico's northern border states where cross-border dental tourism corridors mature and patients prefer removable alternatives to implant-only solutions.
- Temporary Dentures:Interim prosthetics fabricated from standard PMMA without nanofiller reinforcement. Shorter clinical lifespans limit material investment.
- Immediate Dentures:Same-day insertion devices requiring pre-extraction impressions and rapid acrylic processing. Chairside digital workflows compress traditional laboratory turnaround times.
Volume sits with Full Dentures; growth tilts toward Partial Dentures.
Application:
Capital intensity and patient throughput determine procurement scale and material grade selection.
- Dental Clinics:Fixed-location practices generating recurring prosthodontic demand across routine and cosmetic services. Florida and Texas dental service organizations consolidate purchasing power through direct supply agreements that bypass traditional distributor markups.
- Hospitals:Acute care settings requiring acrylic teeth for trauma reconstruction and oncology-related extractions. Higher biocompatibility documentation burdens under FDA 510(k) and Health Canada Medical Devices Bureau standards elevate compliance costs.
- Mobile Dental Services:Transportable clinics serving rural and underserved populations across Brazil's interior states and Mexico's southern regions. Compression-molded formulations dominate due to equipment portability constraints.
- Home Care:Direct-to-patient delivery models emerging through tele-dentistry platforms. Regulatory ambiguity around impression-taking jurisdiction limits scale.
Procurement value concentrates in Dental Clinics; expansion accelerates fastest in Mobile Dental Services.
Material:
Polymer purity certifications and wear resistance specifications create tiered price-performance tradeoffs.
- PMMA:Cross-linked polymethyl methacrylate manufactured through compression or injection molding. Brazilian distributors prioritize injection-molded variants for dimensional stability and standardized shade matching at production scale.
- Acrylic Resin:Conventional formulations lacking advanced cross-linking density. Price-sensitive procurement channels in Mexico's public health system favor these materials.
- Biocompatible Polymers:Enhanced formulations meeting ISO 22112 extended cytotoxicity testing protocols. Health Canada's tightened documentation requirements under revised Medical Devices Regulations drive compliance cost premiums.
- Composite Materials:Hybrid formulations incorporating ceramic fillers for improved aesthetic translucency. Limited adoption due to higher per-unit costs and specialized characterization labor requirements.
Unit economics favor PMMA; Biocompatible Polymers capture the steepest margin expansion trajectory.
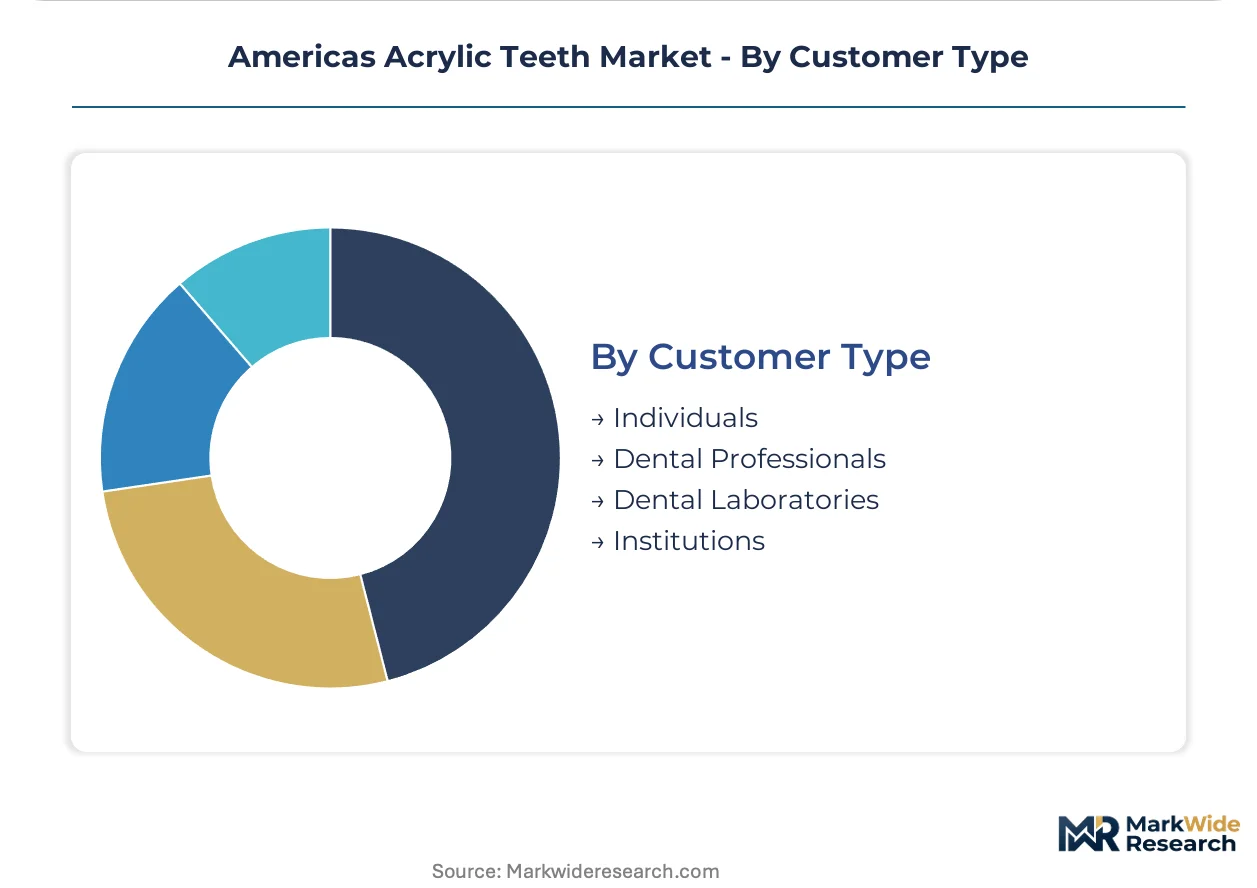
Customer Type:
Technical sophistication and order consolidation power shape supplier relationship structures.
- Dental Laboratories:Centralized production facilities commanding dominant procurement channel position through volume aggregation. São Paulo's laboratory cluster leverages scale advantages to serve Latin American trade corridors.
- Dental Professionals:Individual practitioners and small group practices with fragmented purchasing patterns. Direct-to-clinic distribution gains share as chairside CAD/CAM systems compress traditional intermediary roles.
- Individuals:End-patients accessing acrylic teeth through retail dental product channels. Limited regulatory oversight creates quality variability risks.
- Institutions:Government health systems and educational dental schools with formal tender processes. ANVISA polymer purity testing protocols add registration complexity for manufacturers serving Brazil's public sector.
Revenue concentration rests with Dental Laboratories; channel disruption targets Dental Professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's dental laboratory cluster processes the highest acrylic teeth procurement volumes across the Americas, serving Latin American trade corridors with compression-molded and injection-molded PMMA formulations.
Brazil
ANVISA reimbursement expansion drives public dental program growth across São Paulo, Minas Gerais, and Rio de Janeiro states. Brazil's national health regulator maintains distinct polymer purity testing protocols that add registration complexity for cross-linked PMMA suppliers. São Paulo's laboratory cluster leverages scale advantages to aggregate demand from dental clinics throughout Mercosur trade zones.
United States
FDA 510(k) clearance requirements govern acrylic teeth marketing, with Florida and Texas dental service organizations consolidating purchasing power across multi-location networks. EPA dental amalgam effluent guidelines push laboratories toward PMMA-based alternatives with lower environmental discharge profiles. California's dental laboratory networks face the steepest sustainability compliance costs under state-level environmental regulations.
Mexico
Cross-border dental tourism corridors mature in Chihuahua and Nuevo León, driving preference for tooth-retained partial dentures over implant-only solutions. Government reimbursement programs broaden prosthodontic access through public health system tenders. Northern border states concentrate procurement volume as US patients seek cost-advantaged restorative procedures.
Canada
Health Canada's Medical Devices Bureau tightens biocompatibility documentation requirements under revised Canadian Medical Devices Regulations. Extended cytotoxicity testing for PMMA formulations elevates compliance costs for premium nanofiller-reinforced product lines. Ontario's dental laboratory networks process the dominant procurement share through provincial health system contracts.
Americas Acrylic Teeth Market Vendor Landscape
The competitive structure tilts toward vertically integrated multinational suppliers controlling resin compounding through finished tooth fabrication. Three archetypes dominate: premium-tier specialists commanding nanofiller reinforcement technology premiums, regional manufacturers competing on distribution proximity, and diversified dental conglomerates leveraging backward integration into polymer synthesis. Capacity consolidation and direct-to-clinic channel development represent the dominant competitive moves reshaping intermediary relationships.
Among diversified dental technology conglomerates, Dentsply Sirona and Ivoclar Vivadent exemplify contrasting strategic positions. Dentsply Sirona occupies a scale-driven archetype through captive resin supply networks spanning polymer synthesis to finished tooth production. Ivoclar Vivadent anchors the premium-tier vector through proprietary material reinforcement technologies. Keystone Industries represents the regional manufacturing archetype, with production assets positioned to compress lead times to Latin American distributor networks.
| Leading Market Players |
|---|
| Heraeus Kulzer |
| GC Corporation |
| Dentsply Sirona |
| Keystone Industries |
| Lang Dental Manufacturing Co., Inc. |
| Ivoclar Vivadent |
| 3M ESPE |
| New Stetic |
| Vita Zahnfabrik H. Rauter |
| Others |
Supply Flow & Price Mechanics
Performance-grade bifurcation between nanofiller-reinforced premium lines and standard cross-linked PMMA formulations manifests in divergent pricing architectures and supply chain footprints across the Americas. Premium tiers command material-science premiums through proprietary reinforcement technologies while standard grades compete on compression-molding scale economies in São Paulo laboratory clusters.
Pricing Analysis
Value-based pricing anchors on wear-resistance outcomes and biocompatibility certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates nanofiller-reinforced products from injection-molded PMMA and basic compression-molded alternatives. Price differentiation hinges on ISO 22112 certification status and Vickers hardness performance brackets. Cost compression in economy-grade temporary denture segments is intensifying because methyl methacrylate feedstock volatility squeezes margin structures. Dental service organizations in Florida and Texas exhibit lowest price sensitivity through consolidated volume purchasing, while individual practitioners in Mexico's public health system show highest sensitivity to per-unit material costs.
Supply Chain Analysis
Regional distribution centers in São Paulo, Miami, and Mexico City operate hub-and-spoke patterns serving dental laboratory networks and direct-to-clinic channels. Manufacturing concentrates in Brazil, the United States, and Mexico, with São Paulo's laboratory cluster processing dominant procurement volumes for Latin American trade corridors. Raw material flows draw from petrochemical feedstock suppliers in the US Gulf Coast and Brazilian polymer synthesis facilities. Supply chain risk centers on methyl methacrylate price volatility tied to crude oil derivatives. Distribution runs through dental laboratory aggregators and emerging direct-to-clinic platforms compressing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas acrylic teeth market sits in a technology-transition phase as chairside CAD/CAM and photopolymer jetting systems displace traditional flask-and-press laboratory workflows. Digital manufacturing convergence is fragmenting production hierarchies and compressing intermediary roles across procurement channels.
For Market Incumbents: To counter digital workflow disruption from chairside manufacturing systems, incumbents should deepen backward integration into resin compounding to control feedstock quality and cost structures. Certification investment in Health Canada's extended cytotoxicity testing protocols and ANVISA polymer purity standards creates defensive moats against lower-cost regional competitors lacking quality system infrastructure. For New Entrants and Emerging Players: Capture white-space opportunity in Mexico's underpenetrated northern states of Chihuahua and Nuevo León where cross-border dental tourism corridors mature and demand for tooth-retained partial dentures outpaces implant-only solutions. Target mobile dental services across Brazil's interior states with portable compression-molded formulations suited to equipment-constrained field operations. Go-to-market leverage rests on direct clinic partnerships bypassing São Paulo laboratory cluster intermediaries. For Investors and Strategic Acquirers: Re-rating potential sits with regional manufacturers possessing captive resin supply and ANVISA registration infrastructure given Brazil's reimbursement expansion catalyst. Long-term viability over a 5-10 year horizon favors assets with digital workflow integration capabilities and direct-to-clinic channel control. Acquisition target archetype: mid-scale Brazilian or Mexican producers with established laboratory relationships and untapped northern Mexico geographic expansion capacity. Signal to watch: FDA 510(k) clearance timelines for photopolymer-based same-day denture systems as inflection indicator for chairside disruption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polymer synthesis controls methyl methacrylate cost exposure and quality consistency from feedstock through finished tooth. |
| ISO 22112 Certification Investment | Extended cytotoxicity testing documentation satisfies Health Canada's tightened Medical Devices Bureau requirements for premium product lines. |
| Direct-to-Clinic Distribution Buildout | Bypassing São Paulo laboratory aggregators captures margin compression from dental service organization consolidated purchasing power. |
| Photopolymer Jetting Technology Adoption | Same-day denture fabrication capability opens chairside production models competing with traditional laboratory turnaround times. |
| ANVISA Registration Infrastructure Expansion | Brazil's distinct polymer purity testing protocols create competitive access barriers protecting registered suppliers from unregistered imports. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dental laboratory owners, prosthodontic technicians, dental service organization procurement directors, and ANVISA regulatory affairs specialists combined with bottom-up and top-down triangulation. Secondary sources encompassed FDA 510(k) clearance databases, Health Canada Medical Devices Bureau submission records, ANVISA polymer purity testing protocols, and Brazilian dental trade association production statistics. Cross-validation across stakeholder perspectives ensured data integrity against official regulatory documentation.
Segment-level granularity modeled product type, application setting, material grade, and customer channel dimensions across the projection horizon. Geographic disaggregation captured national regulatory cluster variations between FDA, Health Canada, and ANVISA jurisdictions. CAGRs derived from trend-line extrapolation of historical procurement volumes adjusted for reimbursement policy shifts and digital workflow penetration rates. Industry-specific forecast inputs included methyl methacrylate feedstock price trajectories and dental technician workforce aging patterns affecting production capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory reclassification proposals and photopolymer jetting technology adoption curves. Outputs reflect documented assumptions around reimbursement expansion timelines and petrochemical feedstock stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Etching Liquid Market
Dental Devices
Digital Facebow Market
Dental Devices
Dental Implants Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental Crown Removal Market
Dental Devices
Dental Healing Caps Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Dental Contouring Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
US Dental Splint Market
Dental Devices
Dental Forceps Market
Dental Devices
Dental Whitening Lamps Market