
 Dental Autoclave Market | 2026-2036
Dental Autoclave Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Autoclave Market Outlook
Dental clinics are repositioning infection control budgets toward automated sterilization workflows. Midmark Corporation leverages its North American service infrastructure to sustain recurring revenue from tabletop autoclave placements. Tuttnauer anchors European demand through vacuum autoclave specialization for high-throughput practices. MELAG Medizintechnik GmbH & Co. KG dominates German-speaking markets with precision-engineered steam sterilizers that exceed BfArM validation thresholds.
A dental autoclave is a pressure-sealed sterilization chamber that subjects instruments to saturated steam at temperatures typically ranging from 121°C to 134°C, eliminating microbial life including spores. Its primary purpose is to ensure reusable dental handpieces, burs, and surgical kits meet clinical sterility assurance levels before patient contact. Vacuum autoclave systems lead product type demand where porous loads and wrapped instrument sets require complete air evacuation. Tabletop configurations capture the fastest growth among end user segments as solo and group dental clinics prioritize space-efficient sterilization. Electric technology occupies the dominant share, though hybrid systems are gaining traction where energy cost volatility affects practice economics.
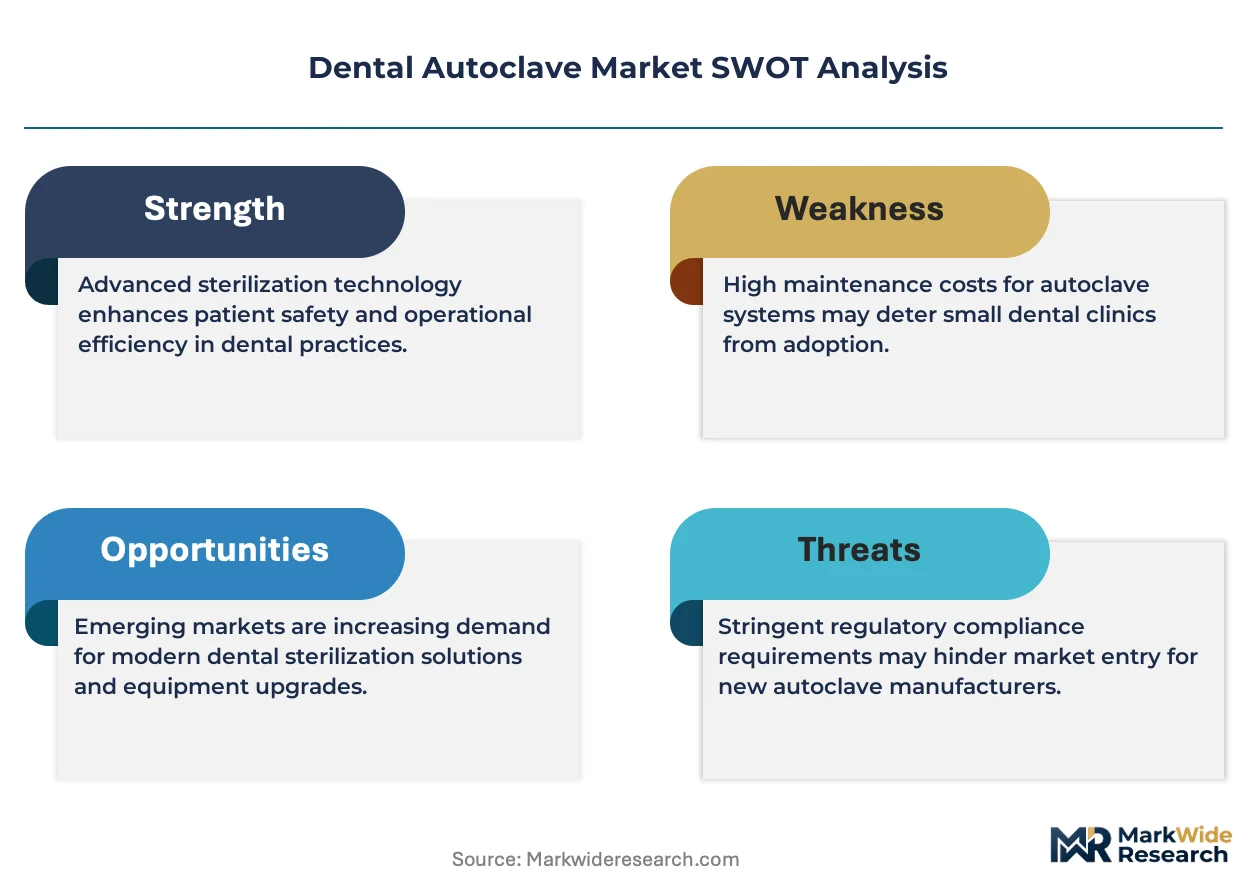
FDA 510(k) clearance requirements and EU MDR Class IIa sterilization device standards shape product development timelines and market access barriers for manufacturers. ISO 17665 steam sterilization validation protocols further constrain design flexibility, forcing R&D investment toward documented biological kill assurance. BfArM in Germany adds national layer requirements that filter out lower-capability suppliers. Stakeholders must monitor how evolving sustainability mandates affect autoclave water consumption specifications and energy labeling thresholds.
Market Dynamics
Dental autoclave procurement is tightening around validated steam sterilization protocols as EU MDR Class IIa device standards and FDA 510(k) clearance requirements compress supplier qualification timelines. Practice consolidation and infection control liability exposure are accelerating replacement cycles for tabletop vacuum systems.
Growth Catalysts
- EU MDR sterilization device standards:Tightened validation requirements for steam-based equipment are filtering out non-compliant suppliers and concentrating procurement among certified manufacturers.
- German dental practice networks:Dense clinic clusters under BfArM oversight sustain premium autoclave replacement demand through mandatory compliance audits.
- Vacuum autoclave technology:Complete air evacuation capabilities for porous loads and wrapped instrument sets are becoming standard in high-throughput practices.
Market Restraints
- Copper and stainless steel input volatility:Chamber and heating element material costs fluctuate with commodity markets, compressing margin stability for mid-tier manufacturers.
- ISO 17665 validation documentation burden:Biological kill assurance protocols extend R&D timelines and raise barrier to entry for new market participants.
- Single-use instrument substitution:Disposable handpiece and bur adoption in cost-sensitive clinics reduces sterilization cycle volume per practice.
Strategic Opportunities
- Hybrid energy systems:Electric-steam hybrid autoclaves address energy cost volatility in markets with deregulated utility pricing.
- Automated workflow integration:RFID-tracked instrument sets and cloud-connected cycle logging align with dental clinic digitization investments.
- BfArM-tier validation exports:German-certified sterilizers command premium positioning in adjacent European markets with harmonized MDR recognition.
Industry Challenges
- Biomedical validation engineering talent:Scarcity of specialists capable of documenting ISO 17665 steam penetration studies slows product development pipelines.
- Legacy practice management software:Integration friction with non-API-enabled sterilization log systems blocks real-time compliance reporting adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Autoclave Market |
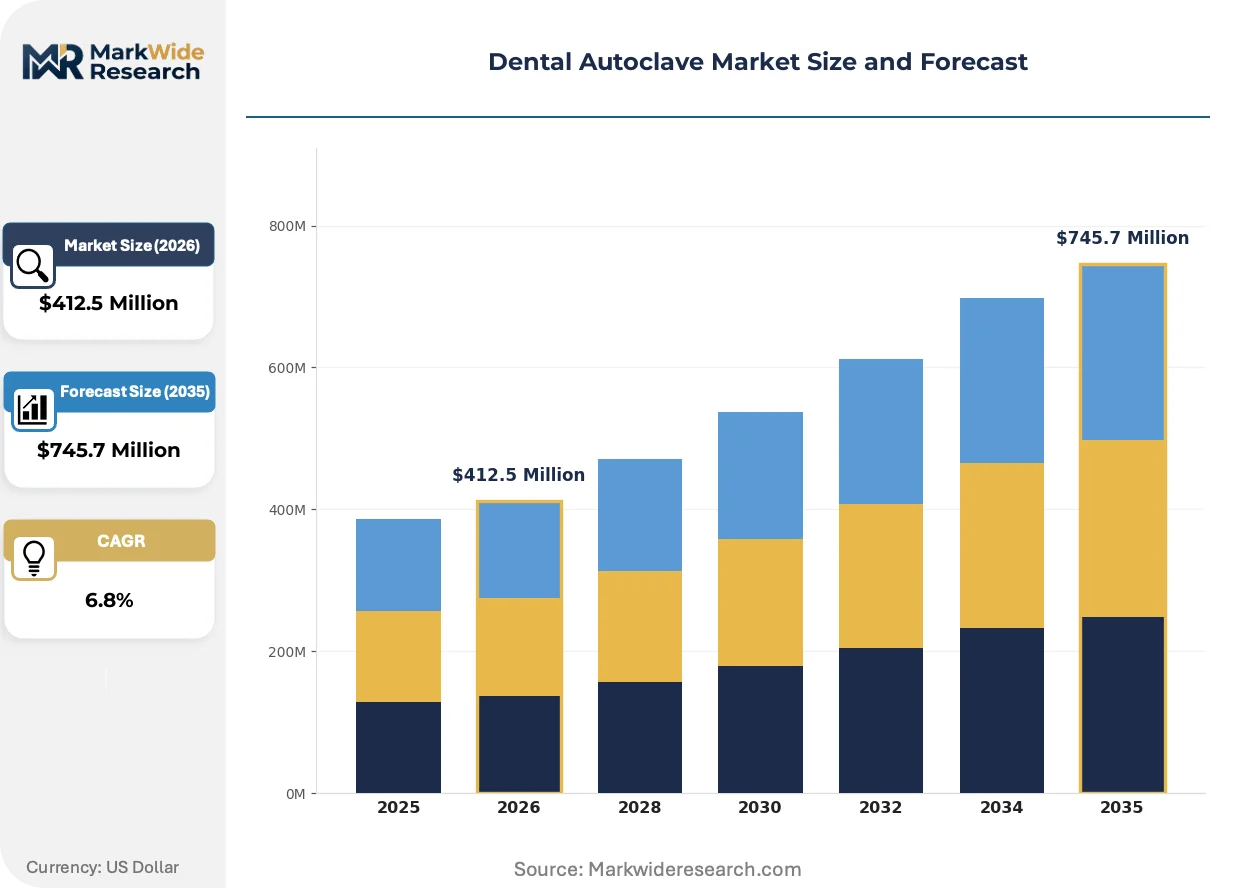
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Displacement, Vacuum Autoclave, Steam Sterilizer, Tabletop Autoclave End User: Dental Clinics, Hospitals, Academic Institutions, Research Labs Technology: Electric, Gas-powered, Hybrid, Solar-powered Size: Small, Medium, Large, Custom |
| Companies Covered | Midmark Corporation, Dentsply Sirona, Tuttnauer, SciCan Ltd., Priorclave Ltd, MELAG Medizintechnik GmbH & Co. KG, Getinge AB, Mocom, W&H Dentalwerk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Autoclave Market Strategic Shifts
Steam sterilization technology is converging with digital traceability and energy optimization as regulatory documentation requirements intensify. Equipment vendors are repositioning around validated workflow automation rather than standalone hardware sales.
Smart autoclave systems with embedded cycle validation sensors and automated digital logging are integrating with practice management platforms. Group dental clinics and dental service organizations are adopting these systems fastest to standardize compliance across multi-site operations. This integration is compressing competitive differentiation toward software-enabled service bundles rather than chamber engineering alone.
EU MDR Class IIa sterilization device standards are extending validation documentation requirements to software components controlling steam parameters. Manufacturers must now submit updated technical files for firmware revisions, lengthening product update cycles. Vacuum autoclave product lines face the heaviest documentation burden due to their complexity in air removal validation protocols.
After-sales service contracts are unbundling from equipment purchase as buyers seek predictable maintenance costs. Dental service organizations are negotiating enterprise-level service agreements covering calibration, biological indicator testing, and preventive maintenance across their clinic portfolios. Germany shows the most advanced unbundling, with BfArM-mandated annual validation requirements creating captive recurring revenue streams for certified service providers.
Dental Autoclave Market Segmentation
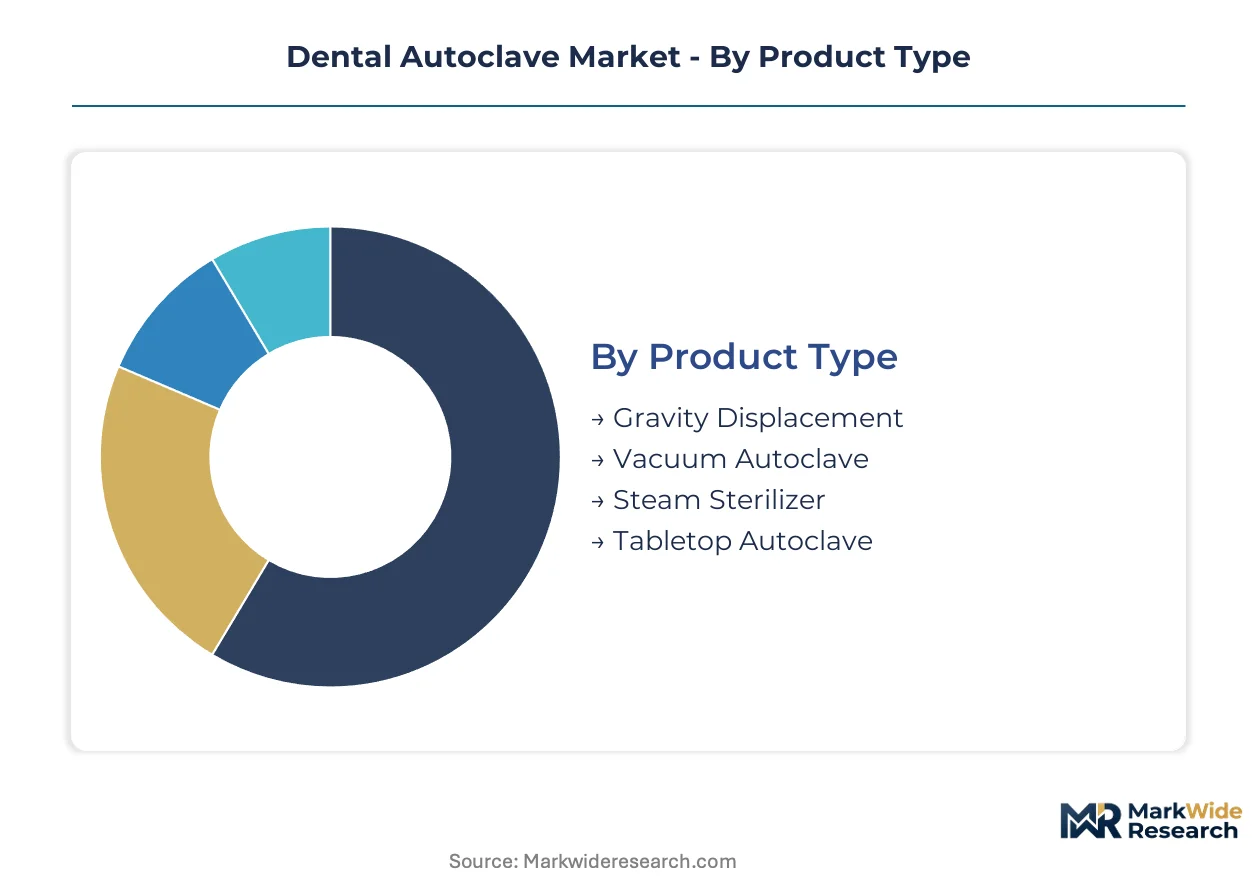
Dental autoclave segmentation reflects divergent sterilization throughput requirements and infrastructure constraints across practice types. Equipment specifications vary sharply between high-volume hospital central sterile departments and space-constrained solo dental clinics.
Product Type:
Supply concentration clusters around vacuum-capable systems where air evacuation engineering creates durable competitive moats.
- Vacuum Autoclave:Saturated steam penetration through pre-vacuum pulses eliminates trapped air from porous loads and wrapped instrument sets. German dental service organizations under BfArM audit mandates specify vacuum systems exclusively for wrapped surgical kit sterilization. Chamber engineering complexity limits qualified suppliers to established European and North American manufacturers with documented ISO 17665 validation histories.
- Tabletop Autoclave:Compact footprint configurations integrate gravity displacement or limited vacuum capability for point-of-use placement within dental operatories. Solo practices in the United States prioritize tabletop units to avoid dedicated sterilization room construction costs. FDA 510(k) clearance timelines for tabletop systems run shorter than large-chamber hospital equipment, accelerating manufacturer refresh cycles.
- Gravity Displacement:Passive air displacement through steam density differential suits unwrapped solid instrument loads in cost-sensitive settings.
- Steam Sterilizer:Broad-category chamber systems encompassing both gravity and vacuum variants for institutional central sterile supply departments.
Vacuum autoclave systems absorb the bulk of installed capacity in regulated European markets; tabletop autoclave configurations are expanding most quickly among North American group dental practices.
End User:
Procurement authority concentration varies dramatically between independent clinician-owners and centralized purchasing departments.
- Dental Clinics:Private practice and group clinic settings generate the highest unit volume demand, with replacement cycles averaging five to seven years under routine use conditions. German dense practice networks under mandatory BfArM compliance audits sustain premium equipment procurement despite higher capital costs. Clinic consolidation into dental service organizations is standardizing equipment specifications across multi-site portfolios.
- Hospitals:Central sterile processing departments require large-chamber autoclaves with validated load patterns for mixed surgical instrument sets. United States hospital procurement favors vendors with 24-hour service response capabilities and spare parts inventory commitments. Joint Commission accreditation surveys drive documentation rigor exceeding typical dental clinic requirements.
- Academic Institutions:Dental schools combine clinical training sterilization with research protocol requirements, creating mixed-load validation challenges.
- Research Labs:Specialized biological and materials research applications require custom cycle programming beyond standard clinical parameters.
Dental clinics absorb the bulk of installed capacity through sheer practice number density; hospitals command the steepest expansion trajectory in absolute equipment value per installation.
Technology:
Energy input configuration directly determines operating economics and site infrastructure requirements across installation contexts.
- Electric:Resistance heating elements provide precise temperature control and eliminate combustion exhaust management, dominating urban clinic installations where gas line availability varies. Electric systems face margin pressure from utility rate volatility in deregulated markets such as Texas and Germany. Chamber insulation and heating element efficiency specifications increasingly influence procurement scoring in sustainability-conscious health systems.
- Hybrid:Dual electric-steam or electric-gas configurations allow operational flexibility where energy pricing fluctuates seasonally or by time-of-use rates. German manufacturers have pioneered hybrid system integration to address industrial electricity pricing premiums. Capital cost premiums over pure electric systems limit hybrid penetration to high-throughput settings with predictable load volumes.
- Gas-powered:Direct steam generation from natural gas or propane suits rural clinics without three-phase electrical service.
- Solar-powered:Photovoltaic-assisted pre-heating or battery-buffered operation remains experimental, with limited commercial deployment in off-grid humanitarian dental programs.
Electric technology absorbs the bulk of installed capacity through infrastructure ubiquity; hybrid configurations are gaining share fastest in energy-price-volatile European markets.
Size:
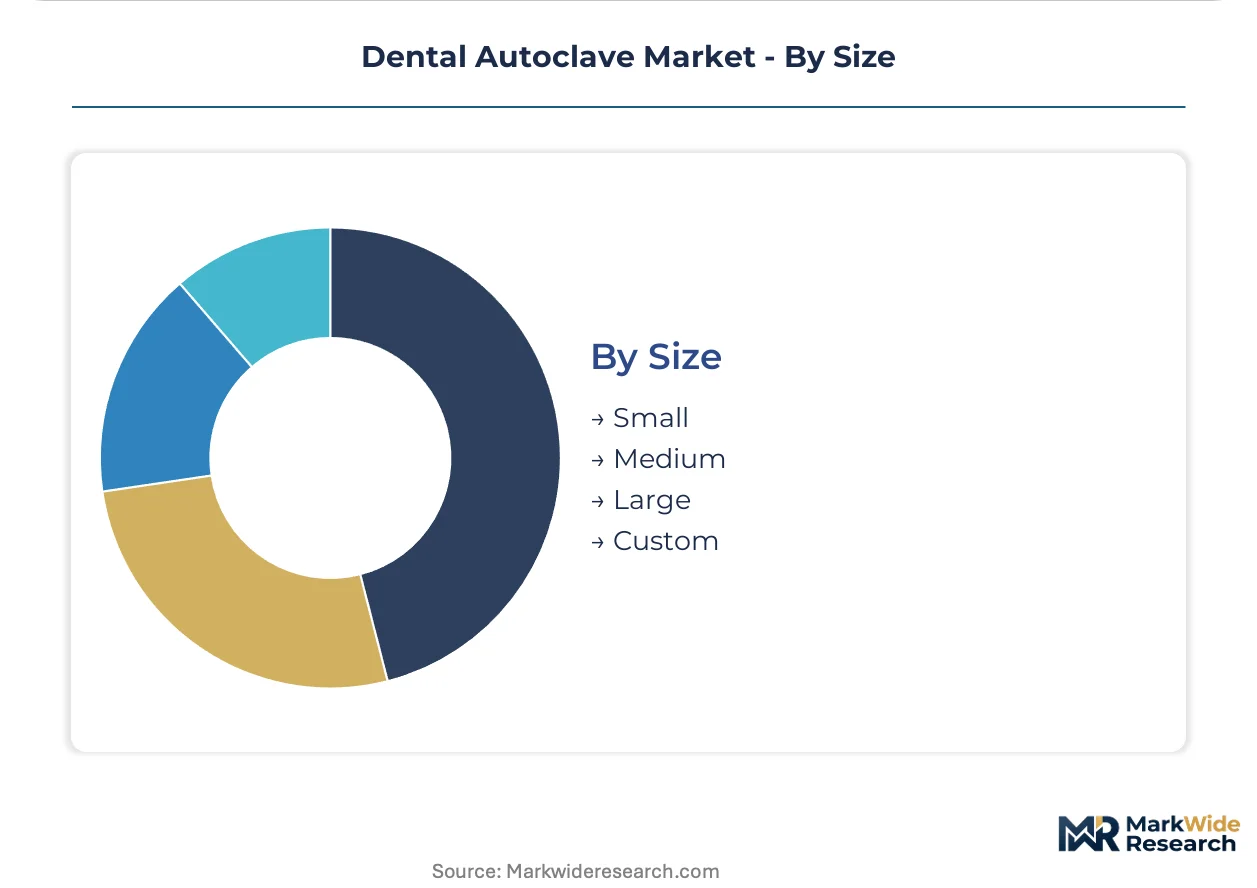
Chamber volume specification tracks instrument throughput requirements and physical space constraints in inverse proportion.
- Small:Chamber volumes under 20 liters suit single-operator practices with low daily instrument turnover. United States mobile dental van programs specify compact autoclaves to maximize treatment space within vehicle footprints. Small chamber systems face displacement pressure from single-use instrument substitution in cost-sensitive Medicaid-serving clinics.
- Medium:20-60 liter chambers balance load flexibility with space efficiency for group practices with three to six operatories. German mid-sized dental clinics under BfArM oversight favor medium vacuum systems with validated wrapped load capability. Medium units capture replacement demand from aging small-chamber gravity systems seeking compliance upgrade paths.
- Large:Institutional central sterile departments require 100+ liter chambers for batch processing of surgical kits across multiple specialties.
- Custom:Non-standard dimensions address architectural constraints or specialized load configurations in hospital renovation projects.
Medium size configurations absorb the bulk of installed capacity across mixed-practice dental settings; small chamber systems face the steepest displacement pressure from instrument disposability trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical device zones in Bavaria and North Rhine-Westphalia concentrate autoclave engineering talent and validation laboratories. These clusters attract sterilization equipment investment through proximity to BfArM oversight infrastructure and dense dental practice networks.
Germany
BfArM-mandated compliance audits accelerate replacement cycles for vacuum autoclaves in high-throughput dental clinics. The EU MDR Class IIa sterilization device standards filter procurement toward ISO 17665-validated manufacturers. Bavaria's medical technology corridor around Munich hosts precision engineering firms serving sterilization equipment supply chains.
United States
FDA 510(k) clearance timelines shape product development pipelines for tabletop autoclave manufacturers targeting group dental practices. Solo clinics prioritize space-efficient sterilization to avoid dedicated room construction costs. The Dallas-Fort Worth metroplex concentrates dental service organization headquarters driving standardized multi-site equipment procurement.
Japan
PMDA medical device registration requirements extend validation documentation to firmware controlling steam parameters. METI industrial standards push energy efficiency specifications for electric heating element designs. The Kansai region around Osaka maintains precision manufacturing clusters supplying chamber engineering components.
United Kingdom
MHRA post-Brexit conformity assessment procedures create parallel regulatory pathways alongside retained EU MDR requirements. Dental clinic consolidation into corporate groups standardizes infection control equipment specifications. London's private dental sector sustains premium autoclave procurement despite compressed NHS capital budgets.
France
ANSM national sterilization guidelines exceed baseline EU MDR requirements for biological indicator testing frequency. Île-de-France dental practices under regional health authority oversight specify validated vacuum systems for wrapped surgical kits. The Lyon biomedical cluster supports aftermarket service engineering for autoclave calibration networks.
Dental Autoclave Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with validation-capable incumbents capturing premium procurement while OEM assemblers serve cost-sensitive replacement demand. The supplier base concentrates around three strategic archetypes: European precision engineering houses with documented ISO 17665 histories, North American service-integrated distributors, and Asian contract manufacturers scaling standard chamber designs. Competitive positioning hardens through M&A consolidation of aftermarket service networks and vertical integration into sensor and control component supply.
Among European precision engineering specialists, MELAG Medizintechnik GmbH & Co. KG and Tuttnauer occupy positions defined by vacuum autoclave specialization and BfArM-tier validation exports. Midmark Corporation represents the North American service-integrated archetype, leveraging recurring revenue from tabletop placements. These three firms exemplify how regional regulatory proximity shapes sustainable competitive positioning in sterilization equipment markets.
| Leading Market Players |
|---|
| Midmark Corporation |
| Dentsply Sirona |
| Tuttnauer |
| SciCan Ltd. |
| Priorclave Ltd |
| MELAG Medizintechnik GmbH & Co. KG |
| Getinge AB |
| Mocom |
| W&H Dentalwerk |
| Others |
Value Chain & Pricing Dynamics
Biomedical validation engineering talent concentrated in Bavaria and North Rhine-Westphalia feeds labor-cost differentials that widen pricing-tier spreads between ISO 17665-validated premium systems and standard tabletop configurations. German precision engineering wages compress margins for mid-tier manufacturers while sustaining premium positioning for BfArM-certified suppliers.
Pricing Analysis
Short lead-time premiums command substantial markups for vacuum autoclaves with documented ISO 17665 validation histories, while spot inventory of tabletop gravity systems trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates BfArM-validated German manufacturers from North American service-integrated distributors and Asian contract assemblers. Price differentiation hinges on certification grade and after-sales service bundling. Pricing pressure stems from copper and stainless steel input volatility compressing margins for mid-tier manufacturers. Dental service organizations show lowest price sensitivity due to enterprise procurement scale; solo Medicaid-serving clinics exhibit highest sensitivity amid single-use instrument substitution trends.
Supply Chain Analysis
Workforce availability for precision chamber engineering constrains manufacturing scale-up in Germany, Italy, and the United States where qualified welding and sensor integration specialists cluster. Raw material dependencies center on copper heating elements, 316L stainless steel chambers, and silicon pressure sensors sourced from specialized foundries. Single-source vulnerability for vacuum pump subassemblies from German and Japanese suppliers creates chokepoint exposure. Distribution runs through dental equipment distributors with field service capabilities, bypassing direct manufacturer-to-clinic sales for all but the largest dental service organization accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where control over sensor and control component supply determines margin sustainability. Players are pursuing backward integration into pressure transducer and cycle validation sensor production to escape supplier pricing power.
For Market Incumbents: Hedge against single-use instrument substitution by deepening software-enabled service bundles with RFID-tracked instrument sets and cloud-connected cycle logging. Acquire aftermarket service networks in North America to replicate German-style captive recurring revenue streams. BfArM-mandated annual validation requirements create defensive moats for certified service providers.
For New Entrants and Emerging Players: Enter via hybrid energy system specialization targeting Texas and German markets with deregulated utility pricing volatility. White-space opportunities concentrate in solar-assisted pre-heating configurations for off-grid humanitarian dental programs. Target dental service organization procurement standardization mandates with API-enabled sterilization log integration. Position around firmware differentiation where EU MDR Class IIa documentation burdens slow incumbent refresh cycles.
For Investors and Strategic Acquirers: Re-rating potential sits with European precision engineering houses possessing documented ISO 17665 validation histories given EU MDR sterilization device standard tightening. Long-term viability over a five-to-ten-year window favors suppliers with BfArM-tier certification export capability into adjacent European markets. Monitor dental clinic consolidation rates as inflection indicator for enterprise service contract penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Revision Documentation | EU MDR Class IIa requirements extend validation to steam parameter control software, lengthening update cycles. |
| Aftermarket Service Network Acquisition | BfArM-mandated annual validation creates captive recurring revenue streams for certified providers. |
| Hybrid Energy System Development | Electric-steam configurations address utility rate volatility in deregulated German and Texas markets. |
| RFID-Enabled Workflow Integration | Cloud-connected cycle logging aligns with dental clinic digitization investments and compliance standardization. |
| Sensor Component Backward Integration | In-house production of pressure transducers and validation sensors reduces supplier pricing power exposure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this dental autoclave market analysis. Primary interviews with biomedical engineers, dental clinic purchasing managers, GPO contracts specialists, and aftermarket service technicians combined with FDA 510(k) clearance databases, EU MDR technical documentation, BfArM audit protocols, and ISO 17665 validation records. Bottom-up unit shipment estimates triangulated against top-down equipment replacement cycle modeling.
Granularity-level modeling deployed product-type splits across vacuum, tabletop, gravity displacement, and steam sterilizer configurations; end-user segmentation across dental clinics, hospitals, academic institutions, and research labs; technology differentiation across electric, hybrid, gas-powered, and solar-assisted systems; and size-tier analysis across small, medium, large, and custom chamber volumes. CAGRs derived from replacement cycle compression analysis and procedural volume elasticity across the projection horizon. Forecast inputs incorporated EU MDR implementation timelines, BfArM audit mandate expansion, and dental service organization procurement standardization trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper and stainless steel commodity volatility, single-use instrument substitution acceleration, or firmware documentation requirement relaxation. Forecasts reflect documented assumptions regarding procedural volume growth and regulatory enforcement intensity. Material deviation in dental clinic consolidation rates or EU MDR sterilization device standard interpretation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Microsurgery Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
US Orthodontics Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Dental Air Polishers Market
Dental Devices
Dental Scalers Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental Restoration Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Global Dental Turbine Market
Dental Devices
Dental Needle Market