
 Middle East and Africa Centrifugal Pumps Market | 2026-2036
Middle East and Africa Centrifugal Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Centrifugal Pumps Market Foresight
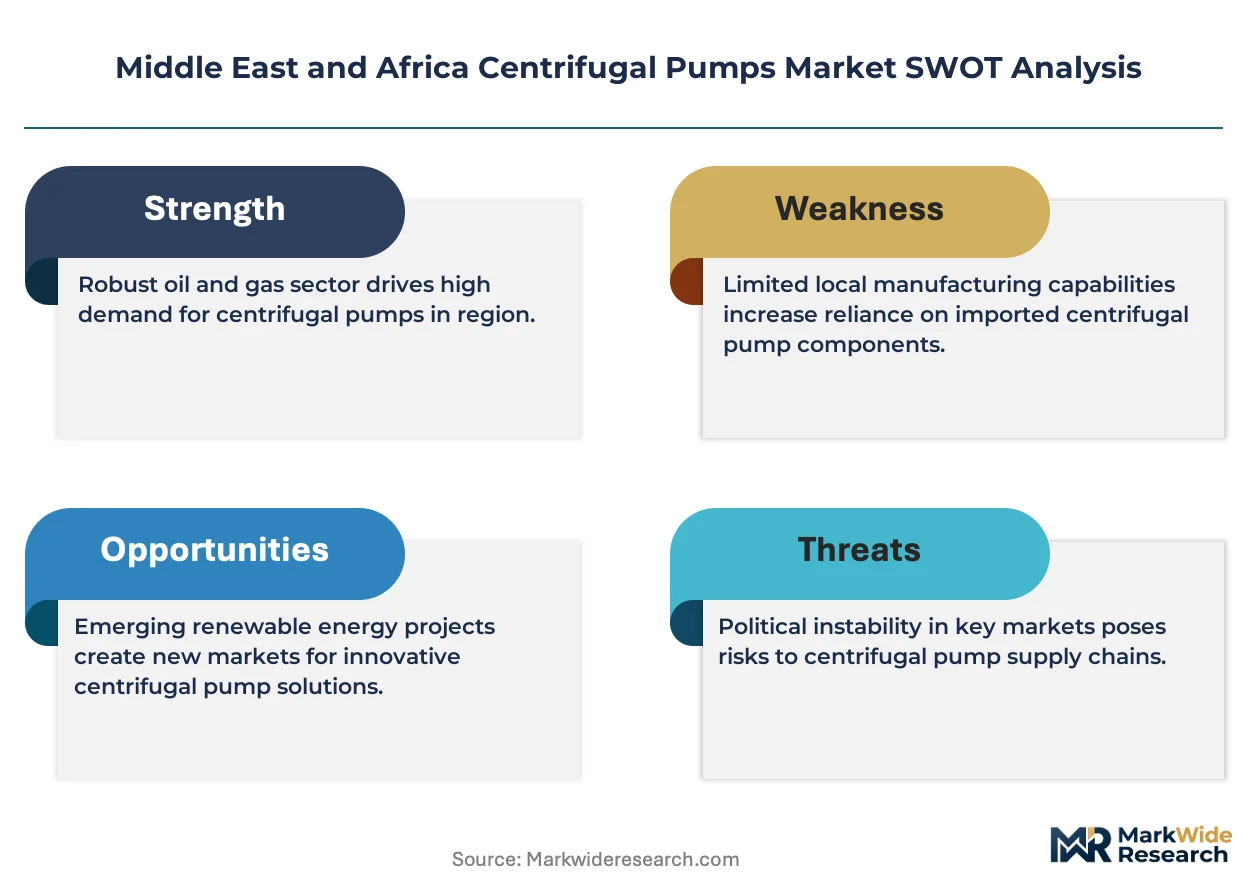
Modular pump skids with integrated variable frequency drives is repositioning buyer evaluation criteria across the Middle East and Africa. Flowserve Corporation leverages its aftermarket service density in Saudi Arabia's Eastern Province to sustain recurring revenue streams. KSB SE & Co. KGaA anchors its position through localized casting and machining operations in South Africa. Baker Hughes Company competes aggressively in subsea and offshore tie-ins where API specification compliance controls contract eligibility.
A centrifugal pump converts rotational kinetic energy into hydrodynamic energy to move fluids through volute or diffuser casings, with impeller diameters and specific speed parameters dictating head-capacity curves for water, hydrocarbons, and chemical slurries. Single stage configurations dominate volume sales in municipal water distribution where lower head requirements prevail, while multi stage pumps capture premium positioning in desalination reverse osmosis feed applications. Solar technology adoption is accelerating fastest across North African agricultural belts where grid reliability constraints and diesel cost volatility push farmers toward photovoltaic-driven surface pumping systems.
Saudi Standards, Metrology and Quality Organization (SASO) efficiency mandates and South Africa's National Regulator for Compulsory Specifications (NRCS) pressure equipment regulations are tightening minimum performance thresholds for imported pump sets. Abu Dhabi Quality and Conformity Council (QCC) certification requirements for potable water systems further filter market access for non-compliant suppliers. Stakeholders must monitor how Egypt's new industrial licensing framework and Morocco's renewable energy integration standards reshape procurement specifications before committing to regional manufacturing footprints.
Market Dynamics
SASO efficiency mandates and variable frequency drive adoption are compressing procurement cycles across Saudi Arabia's municipal water sector, forcing suppliers to recertify product lines ahead of 2026 compliance deadlines.
Growth Catalysts
- Desalination reverse osmosis feed demand:UAE's Taweelah and Jubail Phase 3 expansions are pulling multi-stage high-pressure pump configurations into procurement pipelines.
- SASO efficiency tier upgrades:Saudi Arabia's minimum performance standards are retiring IE1 motor-pump combinations from import eligibility.
- Solar surface pumping:Morocco's Noor Ouarzazate corridor and Tunisia's Cap Bon agricultural belt are deploying photovoltaic-driven centrifugal systems for irrigation.
Market Restraints
- Cast iron and stainless steel input volatility:Foundry energy costs in Egypt and Turkey are transmitting 15-20% price swings into pump casing procurement.
- European component concentration:Premium mechanical seal and bearing supply clusters in Germany and Italy create 8-12 week lead time exposure for African assembly plants.
- API 610 specification rigidity:Oil and gas project tenders disqualify modified-standard pumps, limiting local fabrication participation.
Strategic Opportunities
- Nigeria's municipal rehabilitation pipeline:Lagos State Water Corporation and Federal Ministry of Water Resources are bundling pump station upgrades with World Bank facility financing.
- Digital twin integration:Predictive maintenance algorithms paired with vibration sensors are opening aftermarket service contracts previously captured by OEMs.
- Egypt's industrial licensing reform:New automotive and textile zone approvals are mandating closed-loop cooling systems with specified pump efficiency curves.
Industry Challenges
- API and ISO certification timelines:Third-party witnessed testing at notified bodies in South Africa and UAE is extending product launch schedules by 4-6 months.
- Legacy control system integration:SCADA retrofit projects in older Saudi Aramco facilities require proprietary protocol gateways that fragment supplier accountability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Centrifugal Pumps Market |
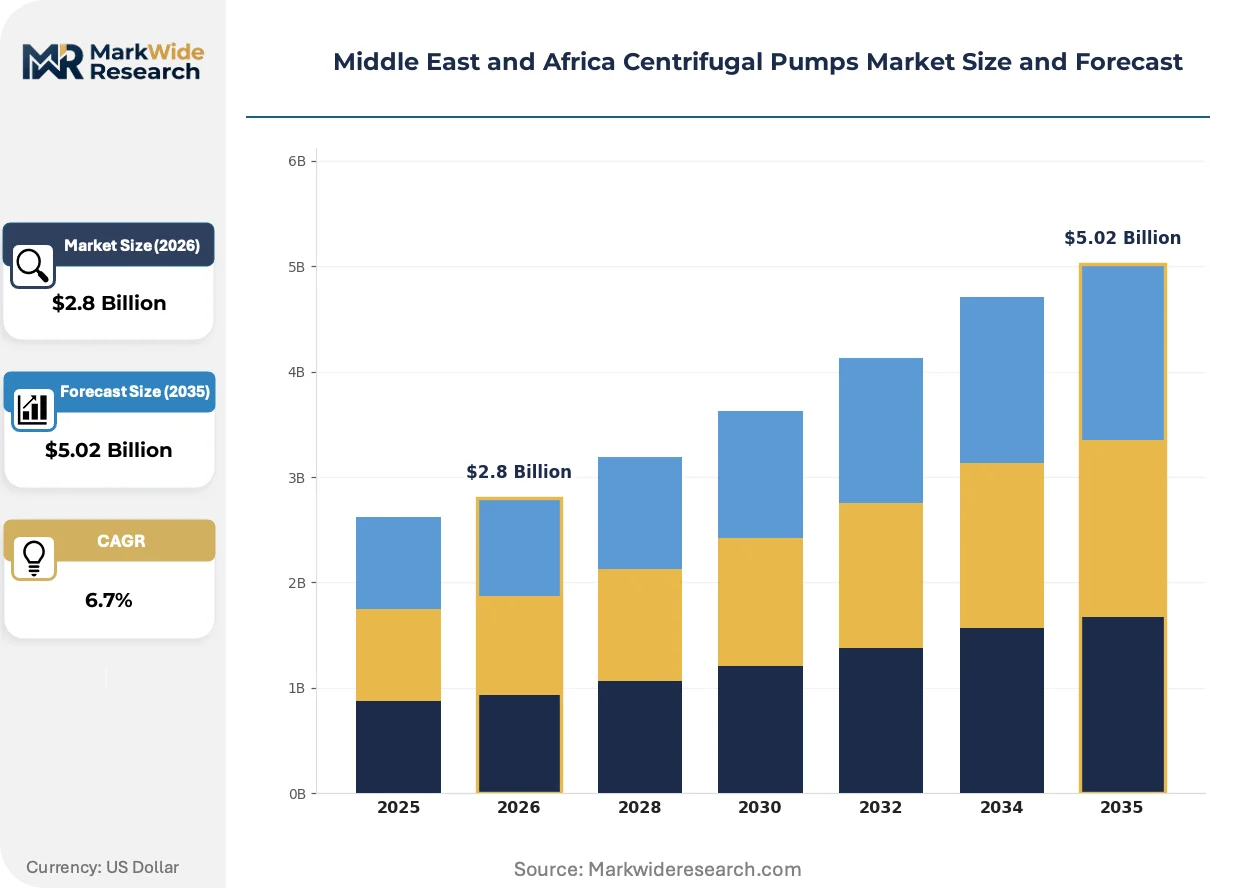
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Multi Stage, Submersible, Vertical End User: Oil & Gas, Water Utilities, Chemical Processing, Power Generation Technology: Electric, Hydraulic, Mechanical, Solar Application: Agriculture, Industrial, Municipal, HVAC |
| Companies Covered | Flowserve Corporation, Baker Hughes Company, KSB SE & Co. KGaA, Sulzer Ltd, Grundfos Holding A/S, Xylem Inc, The Weir Group PLC, Schlumberger Limited, Ebara Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Centrifugal Pumps Market Shifts & Advancements
Modular pump skids with embedded intelligence are displacing field-assembled configurations across the Middle East and Africa, compressing installation timelines and shifting warranty liability upstream to packaged system suppliers.
Variable frequency drive technology is integrating permanent magnet synchronous motors into standard pump lines, enabling part-load efficiency gains that static-speed alternatives cannot match. Saudi Arabia's water utilities are specifying VFD-ready skids in 60% of new tenders. The technology is integrating predictive energy management into municipal procurement evaluation matrices.
SASO's technical regulations for energy efficiency are tightening minimum IE3 motor requirements for pumps above 7.5kW, effective across all Saudi imports. Industrial buyers are pre-emptively retiring IE2 inventory to avoid stranded asset risk. The regulation is compressing supplier certification backlogs at SASO-recognized testing laboratories.
Equipment-as-a-service contracting is displacing capital purchase models in South Africa's mining water management sector. Anglo American and Sibanye-Stillwater are unbundling pump provision from maintenance liability. The shift is most visible in Mpumalanga's coal belt and the Northern Cape iron ore districts.
Middle East and Africa Centrifugal Pumps Market Segmentation
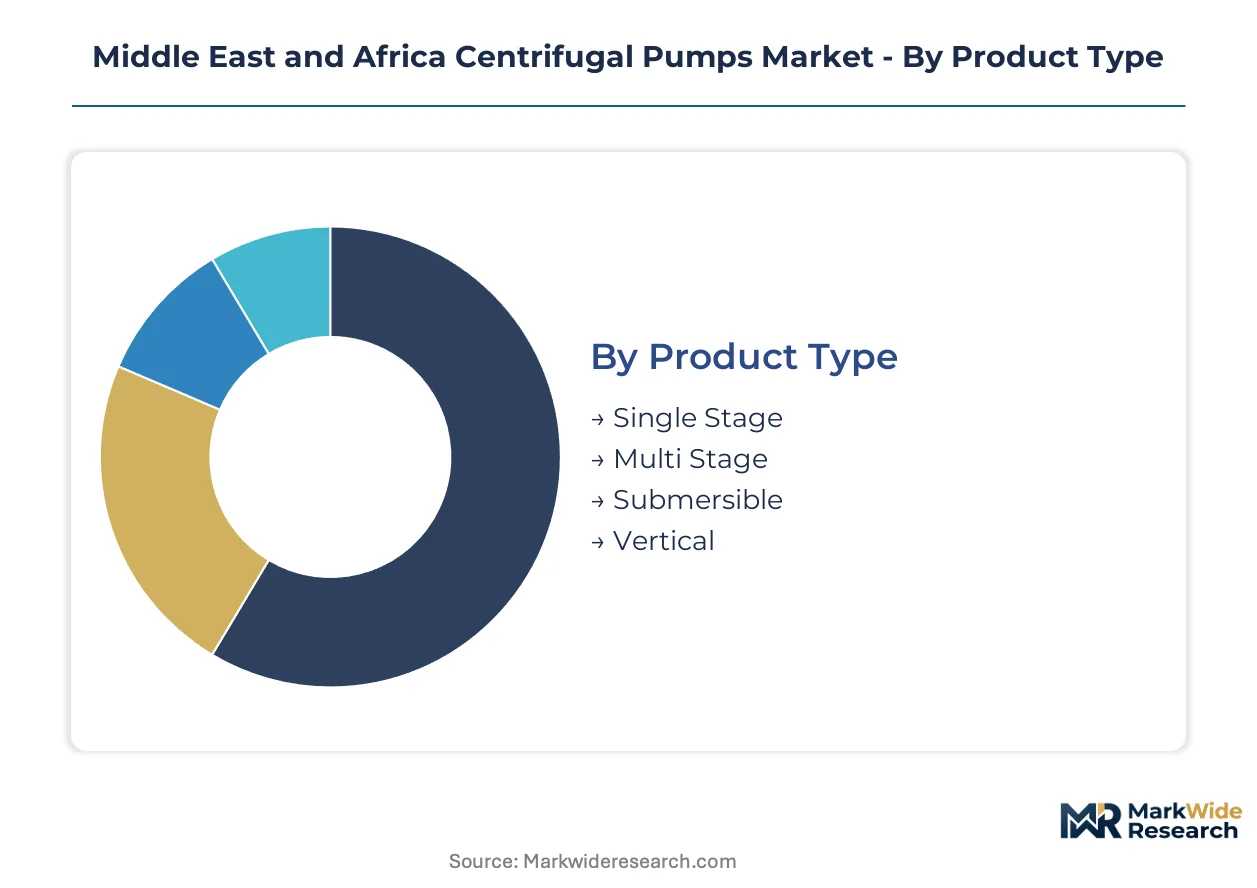
Centrifugal pump procurement across the Middle East and Africa fragments sharply across duty cycles and energy sources. Upgrade timelines and replacement frequencies diverge substantially between municipal water networks and hydrocarbon extraction operations. Understanding these segment boundaries clarifies where specification rigidity gives way to price competition.
Product Type:
Replacement cycles vary dramatically by impeller configuration and bearing assembly complexity in regional desalination and irrigation corridors.
- Single Stage:One impeller generates moderate discharge pressure for low-head water transfer. Municipal distribution networks across Egypt's Nile Delta and Jordan's highland zones specify these units for their simplicity and field-serviceability. SASO efficiency mandates are accelerating motor upgrades in Saudi Arabia's aging single-stage installed base.
- Multi Stage:Stacked impeller assemblies deliver high-pressure feed for reverse osmosis trains. UAE's Taweelah and Saudi Arabia's Jubail Phase 3 expansions are pulling these configurations into procurement pipelines. API 610 compliance requirements extend lead times for oilfield multi-stage orders.
- Submersible:Motor-pump integration for borehole extraction dominates Nigeria's groundwater rehabilitation programs and Morocco's deep aquifer projects.
- Vertical:Space-constrained installations in UAE desalination plants and South African mining dewatering favor inline suction configurations.
Volume placements concentrate in Single Stage; the faster expansion belongs to Multi Stage.
End User:
Cost tier stratification separates specification-heavy hydrocarbon applications from price-sensitive municipal procurement across the region.
- Oil & Gas:API 610 and ISO 13709 compliance gates entry into Saudi Aramco and ADNOC maintenance contracts. Subsea tie-ins and offshore platform duties demand metallurgical certifications that local foundries struggle to match.
- Water Utilities:Gulf Cooperation Council desalination operators and Nigeria's state water boards drive the largest unit volumes. World Bank facility financing in Lagos and Abuja is bundling pump station upgrades with efficiency monitoring systems.
- Chemical Processing:Egypt's new industrial zones and Morocco's phosphate processing corridors specify corrosion-resistant alloys for aggressive slurry handling.
- Power Generation:Cooling water circulation duties at South Africa's Eskom facilities and UAE's Barakah nuclear plant require seismic qualification and redundant sealing systems.
Water Utilities command the dominant placement volumes; Oil & Gas claims the steepest margin tiers.
Technology:
Customer type splits between grid-connected utilities and off-grid agricultural operators seeking diesel displacement.
- Electric:Grid-tied induction motors dominate Saudi municipal tenders and South African industrial parks. IE3 efficiency mandates are retiring IE2 inventory across SASO-regulated imports.
- Hydraulic:Fluid power transmission serves mobile dewatering rigs in Nigeria's Niger Delta and mining pit operations in Zambia's Copperbelt.
- Mechanical:Direct-drive configurations persist in remote Saharan boreholes where maintenance access is seasonal.
- Solar:Photovoltaic surface pumping is climbing fastest across Tunisia's Cap Bon agricultural belt and Morocco's Noor Ouarzazate corridor. Grid reliability constraints and diesel cost volatility push farmers toward DC-driven centrifugal systems.
Electric placements dominate current volumes; Solar is gaining share fastest among new installations.
Application:
Geography concentrates mature replacement demand in Gulf municipal networks against greenfield agricultural expansion in North Africa.
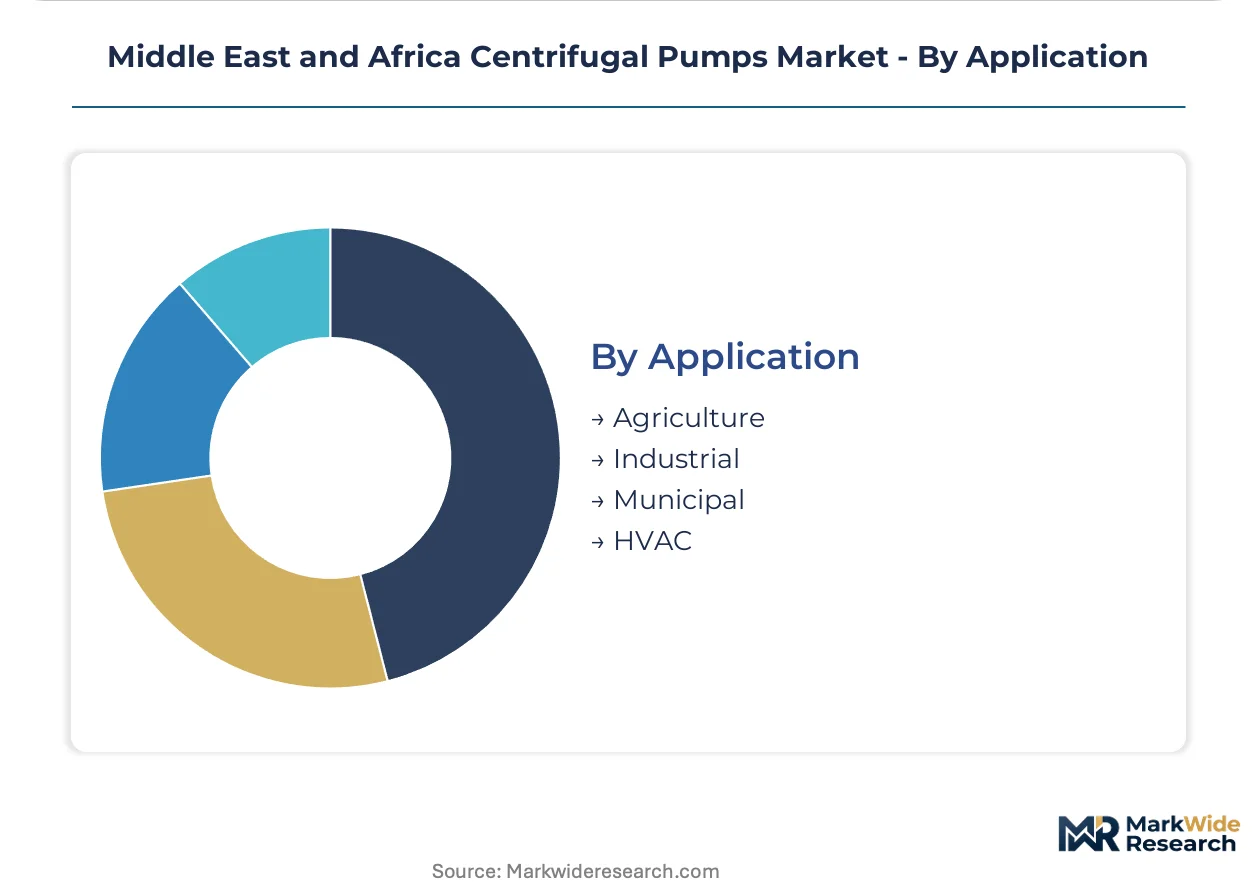
- Agriculture:Solar-powered surface pumping for date palm irrigation in Saudi Arabia's Al-Qassim region and citrus groves in South Africa's Limpopo Valley. Groundwater depletion is deepening boreholes and extending submersible pump specifications.
- Industrial:Closed-loop cooling for Egypt's new automotive zones and textile clusters. Process duty cycles favor modular skids with embedded variable frequency drives.
- Municipal:Saudi Arabia's water transmission mains and Nigeria's distribution rehabilitation programs. SCADA retrofit requirements fragment supplier accountability in legacy Saudi Aramco facilities.
- HVAC:Chilled water circulation in UAE commercial towers and South African hospital complexes. Part-load efficiency specifications favor permanent magnet synchronous motor integration.
Municipal applications anchor volume placements; Agriculture shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Turkey's foundry belt and South Africa's industrial hubs, while consumption pulls strongest from Saudi Arabia's water infrastructure programs and the UAE's desalination corridors. This geographic split shapes procurement patterns and supplier certification priorities.
Saudi Arabia
SASO efficiency mandates are compressing procurement cycles across municipal water transmission networks. The regulator's IE3 motor requirements for pumps above 7.5kW are retiring IE1 and IE2 inventory from import eligibility. Riyadh's water distribution rehabilitation and Jubail's Phase 3 desalination expansion are pulling multi-stage high-pressure configurations into active tender pipelines.
United Arab Emirates
ADNOC maintenance contracts and Taweelah desalination expansion are driving specification-heavy procurement for subsea and offshore pump systems. The Abu Dhabi Quality and Conformity Council certification requirements for potable water systems filter market access for non-compliant suppliers. Dubai's commercial tower HVAC retrofits and Barakah nuclear plant cooling water duties favor permanent magnet synchronous motor integration.
South Africa
The National Regulator for Compulsory Specifications pressure equipment regulations are tightening minimum performance thresholds for imported pump sets. Eskom's cooling water circulation requirements and solar-powered irrigation projects in Limpopo Valley are redirecting supplier priorities. Mpumalanga's coal belt and Northern Cape iron ore districts are unbundling pump provision from maintenance liability through equipment-as-a-service contracting.
Nigeria
Lagos State Water Corporation and Federal Ministry of Water Resources are bundling pump station upgrades with World Bank facility financing. Groundwater rehabilitation programs in the Niger Delta favor submersible motor-pump integration for borehole extraction. Deep aquifer projects are extending pump specifications as groundwater depletion intensifies.
Egypt
New industrial licensing frameworks for automotive and textile zones are mandating closed-loop cooling systems with specified pump efficiency curves. Nile Delta municipal distribution networks specify single-stage units for field-serviceability. Foundry energy cost volatility is transmitting price swings into pump casing procurement from Egyptian suppliers.
Middle East and Africa Centrifugal Pumps Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across specification tiers, creating a tiered structure where API compliance gates premium positioning. The vendor base organizes around three strategic archetypes: integrated energy-service conglomerates with subsea capabilities, European pump specialists with localized casting operations, and diversified industrials with aftermarket service density. Competitive moves concentrate on M&A for technology access and geographic expansion through regional manufacturing footprints.
Among the integrated energy-service tier, Baker Hughes Company and Schlumberger Limited occupy positions shaped by offshore project specifications. Within the European specialist segment, KSB SE & Co. KGaA anchors its regional presence through localized production capabilities. Flowserve Corporation exemplifies the aftermarket-focused archetype, leveraging service density in Saudi Arabia's Eastern Province to sustain recurring revenue streams.
| Leading Market Players |
|---|
| Flowserve Corporation |
| Baker Hughes Company |
| KSB SE & Co. KGaA |
| Sulzer Ltd |
| Grundfos Holding A/S |
| Xylem Inc |
| The Weir Group PLC |
| Schlumberger Limited |
| Ebara Corporation |
| Others |
Supply & Pricing Matrix
SASO IE3 motor efficiency mandates in Saudi Arabia are gating qualified supply and premium-tier pricing access for centrifugal pump suppliers serving municipal water utilities across the Gulf Cooperation Council. The regulation compresses procurement cycles as buyers pre-emptively retire non-compliant inventory, concentrating pricing power with certified manufacturers while forcing recertification costs onto uncertified competitors.
Pricing Analysis
Margin tightening in standard-tier pump configurations reflects foundry energy cost volatility in Egypt and Turkey transmitting into casing procurement. Three-tier pricing structure across API-certified premium, IE3-compliant standard, and non-certified economy levels separates specification-heavy oilfield contracts from price-sensitive agricultural applications. Cost-down pressure on economy-tier units accelerates because Nigerian state water boards prioritize upfront capital savings over lifecycle efficiency. Municipal utilities in Saudi Arabia and the UAE demonstrate lowest price sensitivity due to World Bank facility financing and efficiency mandate compliance requirements.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale desalination project demand while distributor networks serve fragmented agricultural buyers across North Africa. Manufacturing gravity centers on Turkey's foundry belt, South Africa's machining hubs, and Germany's precision component clusters for mechanical seals and bearings. Raw material dependencies draw from Egyptian cast iron suppliers, Turkish stainless steel processors, and Italian bearing manufacturers. Single-source vulnerability concentrates in European mechanical seal supply where 8-12 week lead times expose African assembly plants to project delays. Distribution runs through regional EPC contractors for large infrastructure and agricultural cooperatives for solar-powered irrigation systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa centrifugal pumps market sits in a technology-transition phase as variable frequency drive integration with permanent magnet synchronous motors displaces static-speed induction motor configurations across municipal procurement specifications.
For Market Incumbents: Deploy aftermarket service density as the primary defensive lever. Flowserve Corporation's recurring revenue model in Saudi Arabia's Eastern Province demonstrates how localized maintenance contracts lock out competitor replacement bids. Incumbents should anchor positions through backward integration into foundry operations in Turkey or South Africa to mitigate cast iron input volatility. Certification investment at SASO-recognized laboratories gates premium-tier access against emerging Asian competitors. For New Entrants and Emerging Players: SASO efficiency tier upgrades in Saudi Arabia open a window for IE3-certified pump specialists to capture municipal rehabilitation contracts. The most penetrable white-space sits in Nigeria's groundwater rehabilitation programs where submersible motor-pump integration for deep aquifer extraction outpaces established supplier coverage. Solar surface pumping across Tunisia's Cap Bon agricultural belt offers a second entry vector. A go-to-market angle pairing photovoltaic system integration with pump provision bypasses grid-reliability constraints that handicap pure-play electric suppliers. For Investors and Strategic Acquirers: Equipment-as-a-service contracting adoption by Anglo American and Sibanye-Stillwater in South Africa's mining belt is the leading indicator that recurring revenue models are displacing capital purchase economics. Long-term viability favors suppliers with embedded intelligence capabilities for predictive maintenance algorithms. Acquisition targets should display regional manufacturing footprints in Turkey or South Africa paired with digital twin integration expertise. The signal to monitor is bundling of pump provision with maintenance liability in World Bank-financed water infrastructure projects.| Strategic Initiative | Industry Significance |
|---|---|
| IE3 Motor Certification Investment | SASO compliance gates import eligibility for pumps above 7.5kW in Saudi municipal tenders. |
| Localized Casting Operations | KSB's South African machining footprint reduces lead time exposure from European component clusters. |
| Digital Twin Integration | Predictive maintenance algorithms open aftermarket contracts previously captured by OEM service networks. |
| Solar Pump System Bundling | Photovoltaic-driven configurations capture North African agricultural demand amid diesel cost volatility. |
| Equipment-as-a-Service Transition | Anglo American's unbundling of pump provision from maintenance liability reshapes mining sector procurement. |
Research Methodology
Trade association filings, customs import records, and regulatory certification databases formed the secondary backbone for this analysis. Primary interviews with desalination project engineers, municipal water procurement officers, aftermarket service heads, and foundry operations managers validated demand assumptions and pricing dynamics. The approach combined bottom-up unit placement tracking across single-stage, multi-stage, and submersible configurations with top-down value aggregation using disclosed contract values from Taweelah and Jubail Phase 3 expansions.
Bottom-up modeling tracked pump shipments by product type, end-use sector, and technology across the projection horizon. Segmentation dimensions included impeller configuration, duty cycle intensity, motor efficiency tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to disclosed desalination capacity additions and agricultural electrification programs. Industry-specific forecast inputs incorporated SASO compliance deadline schedules and World Bank facility financing pipelines for Nigerian water rehabilitation.
The model assumes a particular technology adoption path for variable frequency drive integration; alternative pathways for permanent magnet synchronous motor penetration would alter the outlook for efficiency-tier pricing premiums. Forecasts reflect assumptions regarding foundry energy cost stabilization and European component lead time normalization. Periodic stress-testing of base assumptions is recommended given regulatory enforcement variability across Gulf Cooperation Council jurisdictions and commodity price exposure in Turkish and Egyptian supply bases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Electric Submersible Pump Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Single-Stage Centrifugal Pumps Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Electrostatic Coalescers Market