
 Pressure Pumping Market | 2026-2036
Pressure Pumping Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Pumping Market Analysis
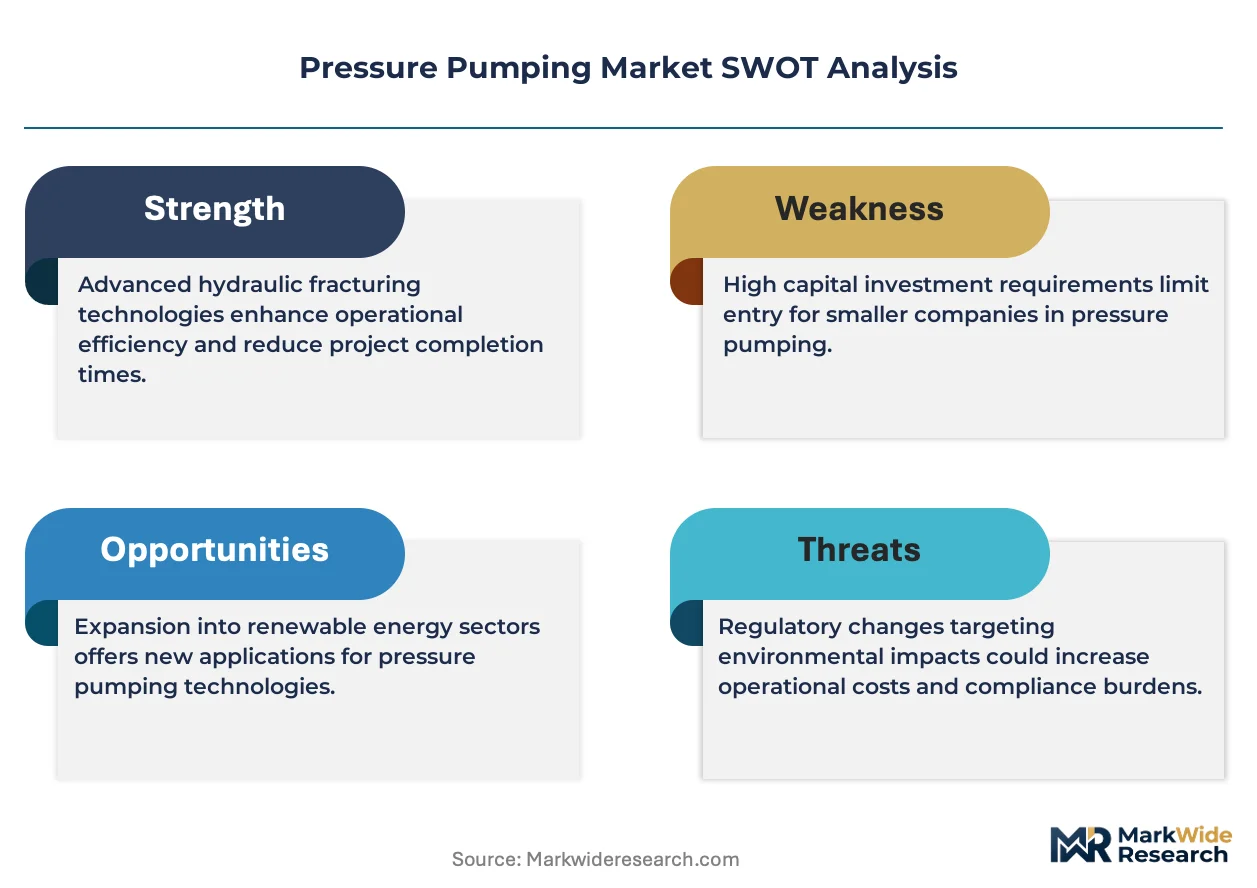
HPHT-rated pumping specifications is collapsing the gap between legacy equipment and next-generation well demands. Halliburton leverages its integrated well construction portfolio to anchor deepwater and unconventional contracts across multiple basins. Schlumberger sustains technology leadership through automated fracturing fleets and real-time pressure monitoring systems. Baker Hughes differentiates via proprietary pump designs that extend mean time between failures in abrasive downhole conditions.
Pressure pumping encompasses the high-pressure injection of fracturing fluids, proppants, and chemical slurries into subsurface formations, typically operating at surface pressures exceeding 15,000 psi to create and maintain conductive fracture networks. Hydraulic fracturing commands the largest revenue share within service types, while cementing provides steadier margin pools tied to well integrity mandates. Smart Technologies and Automated Systems represent the fastest-expanding technology categories as operators reduce surface crew exposure and optimize stage-by-stage proppant placement.
The EPA regulates methane emissions and wastewater disposal from hydraulic fracturing operations, while OSHA sets workplace exposure limits for respirable silica during sand handling. State-level regulators in Texas and New Mexico impose additional casing and cementing standards that directly shape equipment specification requirements. Stakeholders must monitor evolving state primacy over Class II injection wells and the trajectory of federal methane rules to anticipate capital allocation shifts.
Market Dynamics
HPHT-rated pumping specifications are collapsing the capability gap between legacy equipment and next-generation well demands, forcing capital redeployment toward automated fleets and real-time pressure monitoring systems across North American unconventional basins.
Growth Catalysts
- EPA Methane Standards:The EPA's tightened methane emission rules are accelerating equipment upgrade cycles across Texas and New Mexico onshore fields, compelling operators to retire older pumping fleets ahead of depreciation schedules.
- Super-Pad Developments:Permian Basin shale operators are consolidating completion programs around multi-well pad architectures that demand higher-specification pumping capacity per surface location.
- Electric Fracturing:Grid-tied and turbine-powered electric fracturing fleets are cutting fuel costs and emissions profiles, drawing capital allocation from diesel-dependent equipment providers.
Market Restraints
- Proppant Supply Concentration:Northern White Sand deposits in Wisconsin and Minnesota face rail logistics bottlenecks that transmit price volatility directly to pumping service cost structures.
- High-Pressure Equipment Lead Times:Specialized forgings and alloy castings for 15,000+ psi pump components concentrate among a limited supplier base, extending procurement cycles to 26-32 weeks.
- Class II Injection Well Permitting:State primacy disputes over wastewater disposal permitting in Texas and New Mexico are creating regulatory friction that delays completion schedules.
Strategic Opportunities
- Argentina Vaca Muerta:Underpenetrated shale development in Neuquén Province offers whitespace for pumping service providers as YPF and international operators scale horizontal drilling programs.
- Automated Proppant Placement:Convergence of real-time pressure telemetry with machine learning algorithms is enabling stage-by-stage optimization that reduces fluid volumes and improves EUR.
- OSHA Silica Rule Enforcement:Tighter respirable silica exposure mandates are creating aftermarket demand for enclosed sand handling systems and dust suppression technologies.
Industry Challenges
- Specialized Technician Scarcity:High-pressure pump maintenance and HPHT well control expertise remain concentrated among aging workforce cohorts, constraining fleet utilization rates.
- Legacy Fleet Integration:Retrofitting older pumping units with automated controls and emissions monitoring hardware creates software-hardware compatibility failures that extend downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Pumping Market |
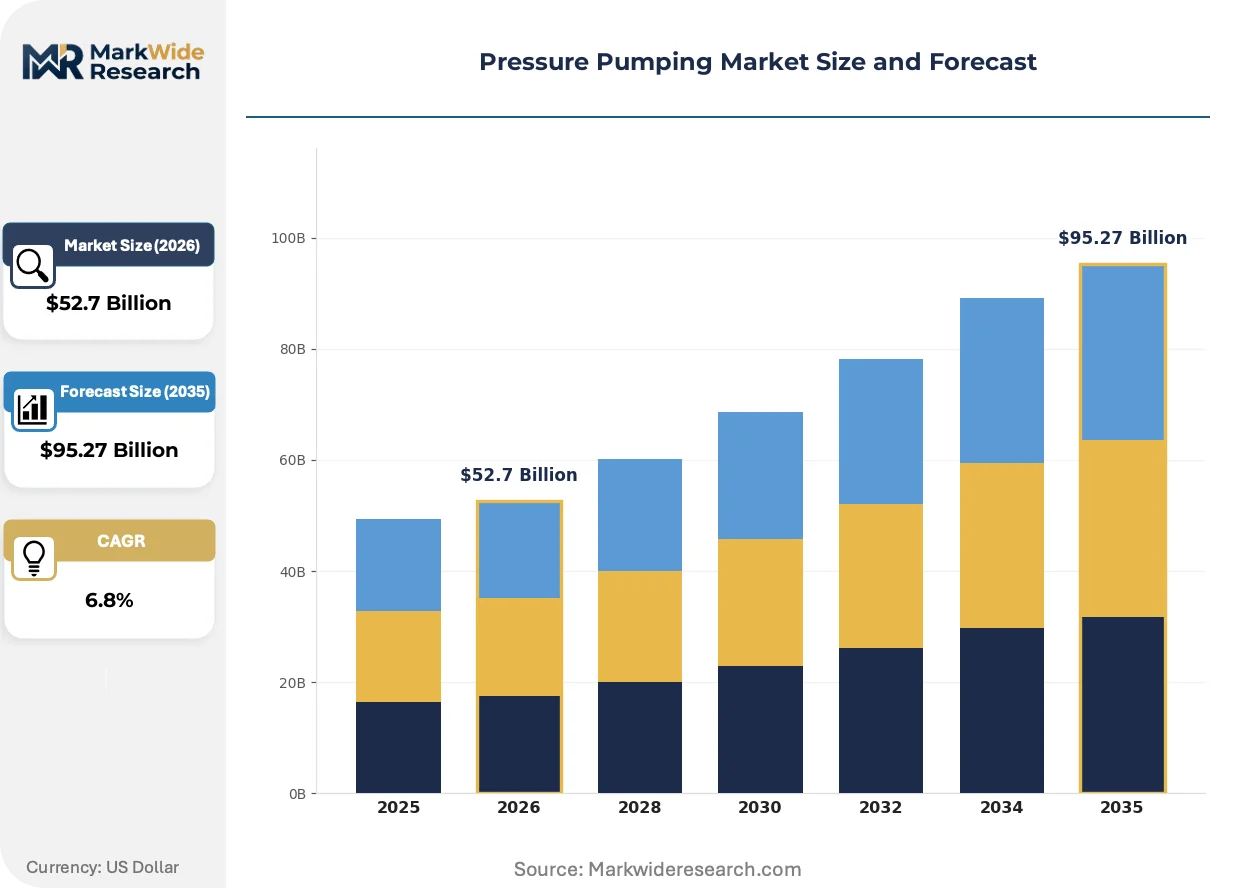
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hydraulic Fracturing, Cementing, Coiled Tubing, Acidizing End User: Oil & Gas Companies, E&P Firms, Service Providers, Contractors Application: Onshore Activities, Offshore Operations, Well Completion, Enhanced Oil Recovery Technology: Conventional Techniques, Automated Systems, Smart Technologies, Hybrid Solutions |
| Companies Covered | Weatherford International, Trican Well Service, Schlumberger, ProPetro Holding Corp, Liberty Oilfield Services, Halliburton, Calfrac Well Services, RPC Inc, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Pumping Market Emerging Trajectories
Digitalization and electrification are actively compressing the operational footprint of pressure pumping services while tightening the link between surface equipment performance and subsurface outcomes.
Electric fracturing technology is miniaturizing the power generation and distribution architecture required for high-pressure pumping operations. Permian Basin operators are deploying mobile turbine and grid-intertie systems at accelerating rates. This shift is miniaturizing the diesel fuel logistics chain while collapsing emissions profiles below EPA methane rule thresholds.
OSHA's enforcement of respirable crystalline silica exposure limits is reshaping sand handling protocols across US onshore basins. The agency's 2016 rule and subsequent amendments mandate engineering controls and medical surveillance programs. Smaller independent operators in the Permian and Eagle Ford are most affected, responding through enclosed proppant conveyor systems and pneumatic transfer technologies.
Super-pad development patterns are consolidating pumping demand around fewer, larger-scale completion programs. Oilfield service procurement is migrating toward integrated multi-well contracts that bundle drilling, completion, and production services. This concentration is most visible in the Delaware and Midland sub-basins, where private equity-backed operators are driving standardization of 50+ stage lateral designs.
Pressure Pumping Market Segmentation
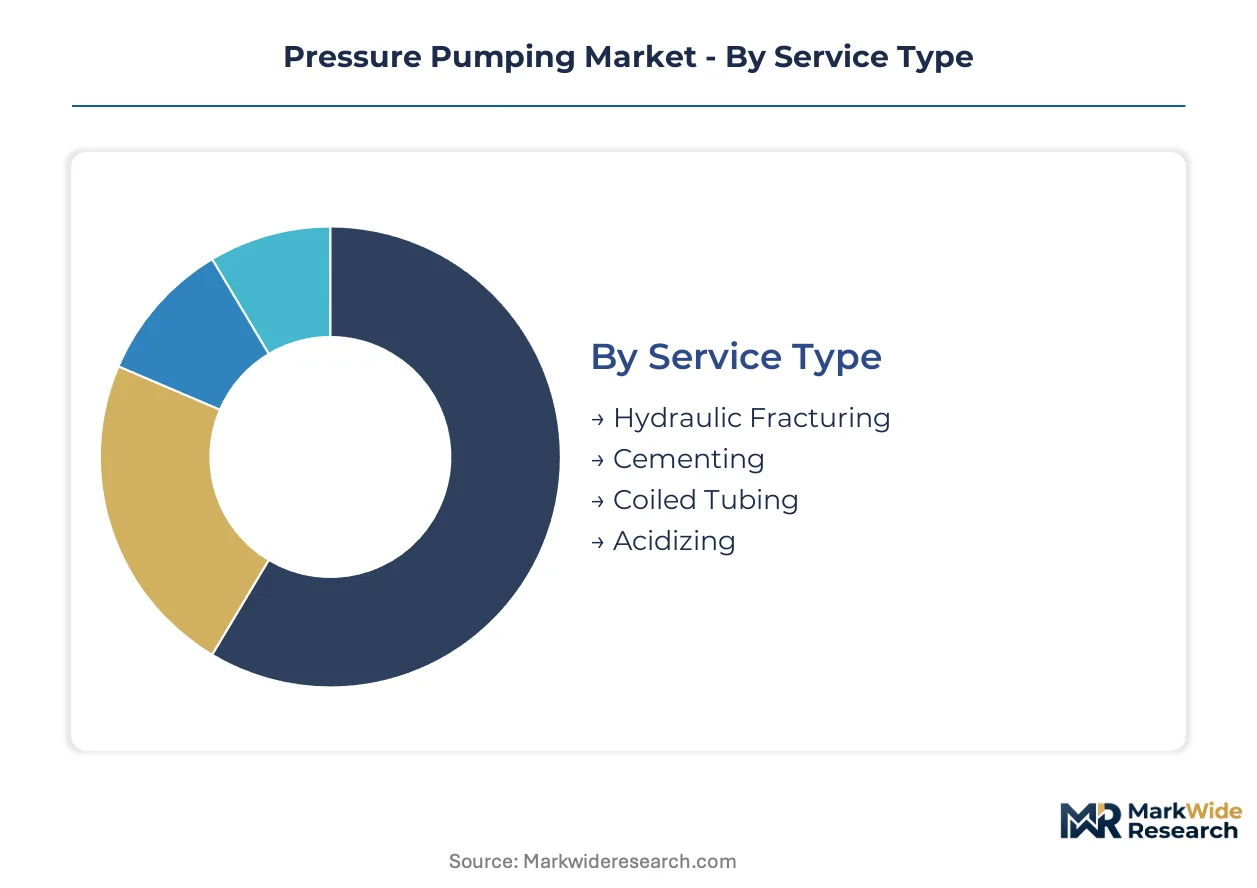
Pressure pumping segmentation reveals how capital flows through distinct service channels and technology tiers. Equipment specifications and regulatory compliance requirements vary sharply across these boundaries, shaping procurement patterns and margin structures.
Service Type:
Channel mix varies dramatically: hydraulic fracturing flows through integrated service contracts, while cementing and acidizing often route through discrete well integrity packages.
- Hydraulic Fracturing:High-pressure injection of proppant-laden fluids at surface pressures exceeding 15,000 psi creates conductive fracture networks in tight formations. Permian Basin super-pad developments concentrate demand for 50+ stage lateral completions, forcing fleet standardization around higher-specification pumping capacity.
- Cementing:Well integrity mandates drive steadier margin pools through zonal isolation and casing support services. EPA methane rules and state-level casing standards in Texas and New Mexico directly shape equipment specification requirements for primary and remedial cementing programs.
- Coiled Tubing:Continuous pipe technology enables live well interventions without killing the wellbore.
- Acidizing:Matrix and fracture acid stimulation restores permeability in carbonate formations.
Hydraulic fracturing dominates installed base. Automated cementing systems are where expansion concentrates.
End User:
Cost tier segmentation separates integrated majors with captive procurement from independent E&Ps reliant on spot market capacity.
- Oil & Gas Companies:Integrated majors and large independents negotiate multi-year bundled contracts spanning drilling through production. These operators in the Delaware and Midland sub-basins are consolidating procurement around integrated multi-well completion programs.
- E&P Firms:Private equity-backed exploration and production companies drive standardization of high-intensity completion designs. Their capital allocation shifts between diesel and electric fracturing fleets are accelerating equipment retirement cycles ahead of depreciation schedules.
- Service Providers:Third-party pumping contractors supply capacity to operators without captive fleets.
- Contractors:Specialized subcontractors handle discrete phases of stimulation and intervention work.
Oil & Gas Companies anchor contract volumes. E&P Firms are gaining share fastest in next-generation fleet deployment.
Application:
Volume concentration tracks the migration of drilling activity between onshore unconventional basins and deepwater frontiers.
- Onshore Activities:Unconventional shale development accounts for the overwhelming majority of pumping hours. Texas and New Mexico field operations concentrate around multi-well pad architectures that demand sustained high-pressure capacity per surface location.
- Offshore Operations:Deepwater and shelf completions require HPHT-rated equipment for high-pressure reservoirs. Gulf of Mexico developments impose stricter well control protocols and longer equipment lead times due to specialized forging requirements.
- Well Completion:Initial stimulation and integrity services for new wellbores.
- Enhanced Oil Recovery:Secondary and tertiary recovery methods including waterflooding and CO2 injection.
Onshore Activities command the steepest expansion trajectory. Offshore Operations retain premium pricing power.
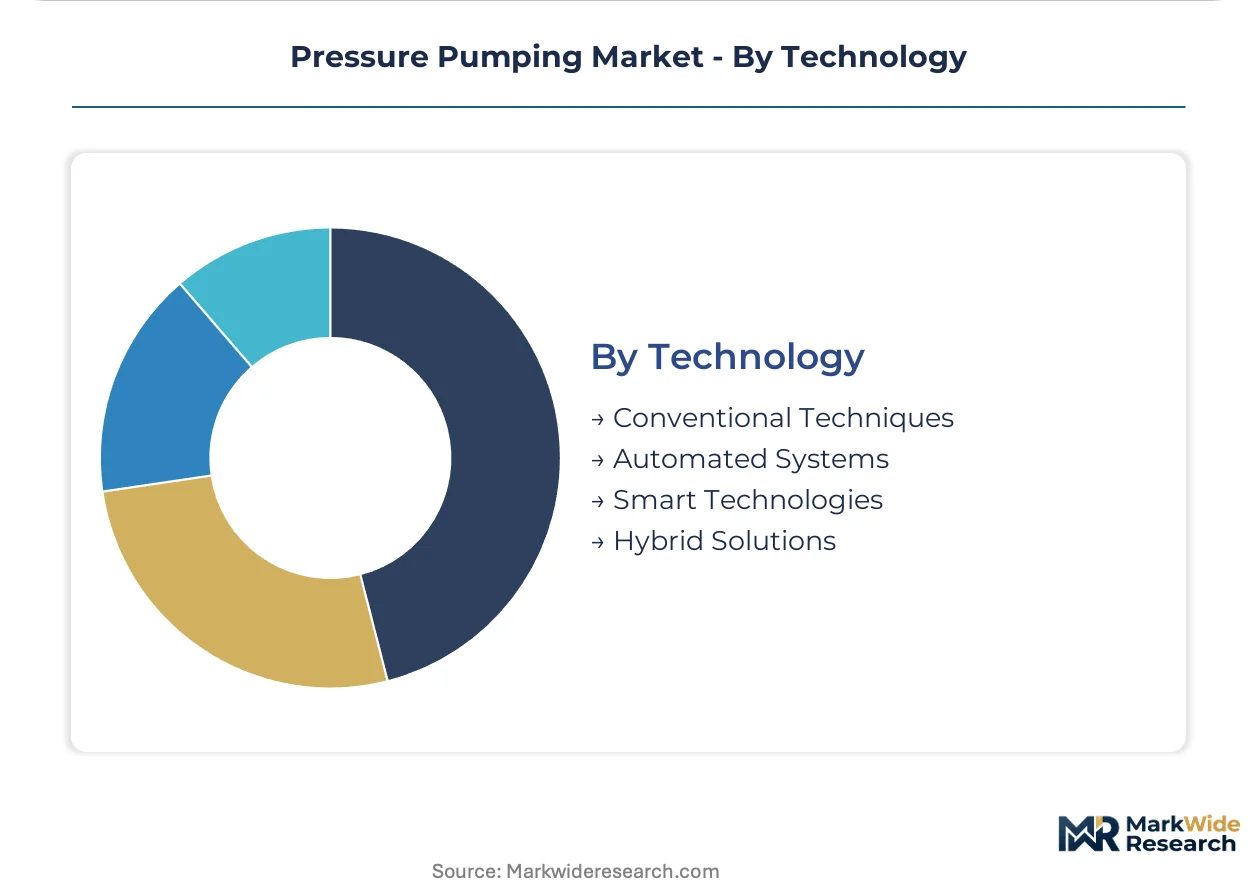
Technology:
Supply concentration in high-pressure component forging shapes which technology tiers operators can access within reasonable procurement cycles.
- Automated Systems:Real-time pressure telemetry and machine learning algorithms enable stage-by-stage proppant placement optimization. Permian Basin deployments are cutting fluid volumes and improving estimated ultimate recovery while reducing surface crew exposure.
- Smart Technologies:Sensor-integrated pumping units deliver predictive maintenance and performance diagnostics. These systems are climbing the fastest as operators retrofit legacy fleets to meet EPA methane monitoring mandates.
- Conventional Techniques:Diesel-powered mechanical pumping with manual controls and limited data integration.
- Hybrid Solutions:Mixed configurations combining electric power with conventional pumping architectures.
Conventional Techniques still dominate installed base. Automated Systems are where vendor R&D concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Argentina and the Middle East exhibit the highest price elasticity, while operators in the United States and Saudi Arabia absorb premium pricing for HPHT-rated equipment and automated fleet capabilities.
United States
Permian Basin super-pad developments and Delaware sub-basin consolidation drive fleet standardization around 50+ stage lateral completions. EPA methane emission standards and OSHA silica exposure rules compel equipment upgrades across Texas and New Mexico. Midland-Odessa anchors the densest pumping service cluster, where electric fracturing deployments are displacing diesel fleets at accelerating rates.
Saudi Arabia
Gas field development and tight sandstone stimulation programs expand demand for high-pressure pumping capacity in the Eastern Province. Saudi Aramco's localization mandates under the In-Kingdom Total Value Add program reshape procurement toward domestic service partnerships. The Dammam-Khobar industrial corridor concentrates equipment maintenance and technician training infrastructure.
Argentina
Vaca Muerta shale development in Neuquén Province offers whitespace for pumping service providers as YPF and international operators scale horizontal drilling. The country's national energy regulator imposes strict well integrity and wastewater disposal protocols that elevate equipment specification requirements. Neuquén city and Añelo field operations cluster around multi-well pad architectures demanding sustained high-pressure capacity.
Canada
Montney and Duvernay tight gas developments sustain demand for fracturing services despite regulatory headwinds in Alberta and British Columbia. Environment and Climate Change Canada methane regulations and provincial carbon pricing schemes accelerate electric fleet trials. Calgary anchors service company headquarters and equipment logistics coordination for Western Canadian Sedimentary Basin operations.
China
Sichuan Basin shale gas development and Xinjiang tight oil programs concentrate state-backed investment in domestic pumping capacity. The Ministry of Ecology and Environment enforces wastewater disposal and air emission standards that shape equipment procurement specifications. Chengdu and Karamay field operations deploy automated fracturing systems under national energy security directives.
Pressure Pumping Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the pressure pumping market. The vendor base concentrates around integrated oilfield service conglomerates with captive R&D pipelines and regional specialists with fleet flexibility advantages. Three archetypes dominate: full-service majors with integrated well construction portfolios, mid-scale independents with basin-specific density, and technology-focused specialists with proprietary automation platforms. Competitive dynamics center on fleet electrification investments and multi-year integrated contract structures that bundle drilling through completion services.
Among North American-based service providers, Halliburton, Schlumberger, and Baker Hughes occupy positions as archetype anchors for integrated capability. Halliburton exemplifies the full-service model with deepwater and unconventional contract penetration. Schlumberger represents technology-forward positioning through automated fleet architectures. Baker Hughes sits within the specialty equipment tier with differentiated pump design expertise. Liberty Oilfield Services and ProPetro Holding Corp exemplify the independent scale-focused archetype with Permian Basin density. Calfrac Well Services and Trican Well Service represent Canadian regional specialists with Montney and Duvernay market presence. Weatherford International and RPC Inc occupy positions as diversified oilfield service providers with pumping as a component segment rather than core focus.
| Leading Market Players |
|---|
| Weatherford International |
| Trican Well Service |
| Schlumberger |
| ProPetro Holding Corp |
| Liberty Oilfield Services |
| Halliburton |
| Calfrac Well Services |
| RPC Inc |
| Baker Hughes |
| Others |
Supply Flow & Price Mechanics
Fleet utilization rates above 85 percent in the Permian Basin compress marginal cost curves for pumping service providers while erecting price floors that protect incumbent margins. This scale concentration simultaneously locks in supply chain preferences for just-in-time alloy component procurement and shapes how operators negotiate multi-well completion bundles across Texas and New Mexico.
Pricing Analysis
EPA methane emission standards dictate the pricing tier structure across North American pressure pumping markets, forcing operators into premium automated fleet contracts or economy-tier legacy equipment retirement. Three-tier pricing structure across premium, standard, and economy levels separates electric fracturing deployments with real-time monitoring from conventional diesel units and from end-of-life mechanical fleets. Cost compression in standard-tier diesel capacity is intensifying because E&P firms accelerate electric fleet trials. Private equity-backed independents exhibit highest price sensitivity, while integrated majors absorb premium pricing for HPHT-rated automated systems.
Supply Chain Analysis
Strategic stockpiling of specialized forgings and alloy castings dominates inventory strategy among tier-one pumping equipment manufacturers, buffering against 26-32 week procurement cycles for 15,000+ psi pump components. Geographic supply concentration centers on Germany, Japan, and the United States for high-pressure alloy forgings, with China supplying auxiliary electrical systems and control hardware. Raw material dependencies rest on nickel-based superalloys, chromium steel castings, and high-grade silica proppant. Single-source vulnerability in specialized forging capacity creates structural supply chain risk. Distribution runs through integrated service contracts that bundle pumping with drilling and completion services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric fracturing technology represents a high-growth disruption reshaping capital allocation across North American unconventional basins, with EPA methane rules serving as the regulatory inflection accelerating fleet turnover beyond normal depreciation cycles.
For Market Incumbents: Shield market position by accelerating backward integration into specialized alloy forging capacity to secure component supply against 26-32 week lead times. Consolidate procurement relationships with Permian Basin super-pad operators through multi-year integrated contracts bundling drilling, completion, and production services. Electric fleet investments represent the critical lever for margin defense against diesel-dependent competitors.
For New Entrants and Emerging Players: Certification fast-tracks through EPA emissions compliance and OSHA silica exposure standards open whitespace in aftermarket enclosed sand handling systems and dust suppression technologies. Target Argentina's Vaca Muerta formation in Neuquén Province, where YPF and international operators scale horizontal programs with underpenetrated pumping service coverage. Go-to-market angle centers on automated proppant placement systems with machine learning-enabled stage optimization.
For Investors and Strategic Acquirers: Technology-focused specialists with proprietary automation platforms and captive electric fracturing IP represent the most defensible acquisition archetype across the analysis window. Long-term viability frames around five-to-ten year fleet electrification trajectories and regulatory tightening on methane monitoring. The signal to watch is state primacy disputes over Class II injection well permitting in Texas and New Mexico, which would compress completion schedules and concentrate demand around vertically integrated service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Deployment | Grid-tied turbine systems cut EPA methane exposure while collapsing diesel logistics costs in Permian operations. |
| Automated Proppant Placement | Machine learning algorithms optimize stage-by-stage fluid volumes and improve estimated ultimate recovery metrics. |
| HPHT Equipment Certification | 15,000+ psi pump specifications unlock deepwater Gulf of Mexico and super-pad unconventional contracts. |
| Backward Integration into Forging | Captive alloy casting capacity insulates against supplier concentration and 26-32 week procurement cycles. |
| Argentina Market Entry | Vaca Muerta shale development in Neuquén Province offers whitespace as YPF scales horizontal drilling programs. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with pumping service executives, E&P procurement directors, HPHT equipment engineers, and regulatory compliance officers; and secondary validation through EPA enforcement databases, OSHA silica rule filings, FERC infrastructure reports, and state regulatory primacy documentation. Bottom-up triangulation against top-down macro indicators anchored volume and value estimates.
Across the analysis window, the forecasting framework modeled service type segmentation, technology tier adoption curves, and basin-specific activity intensity. CAGRs derived from equipment deployment rates, fleet retirement schedules, and regulatory compliance timelines. Industry-specific inputs included electric fracturing penetration assumptions and super-pad completion stage counts.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA methane rule enforcement and Permian Basin activity concentration; material deviation would warrant model refresh. Revision becomes warranted when state primacy disputes over Class II injection well permitting cross thresholds that materially delay completion schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Chemical Metering Pumps Market
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Steam Jet Ejector Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Metering Pump Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Water Intake Screens Market