
 Global Non-Surgical Aesthetic Devices Market | 2026-2036
Global Non-Surgical Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Surgical Aesthetic Devices Market Foresight
Software-defined treatment protocols and subscription-based consumable models are pivoting how non-surgical aesthetic devices generate recurring revenue. Allergan leverages its integrated toxin-filler-device ecosystem to lock in clinic loyalty through bundled service contracts. Galderma competes by anchoring its energy-based platforms to its dermal filler installed base, creating cross-selling leverage in dermatology clinics.
Non-surgical aesthetic devices encompass laser, radiofrequency, ultrasound, and light-based systems engineered to deliver thermal or mechanical tissue modification without incision, typically operating at wavelengths between 532 nm and 10,600 nm depending on chromophore targeting. These instruments serve commercial purposes across skin rejuvenation, body contouring, and hair removal by inducing controlled dermal or subcutaneous responses. Laser devices dominate installed base and replacement cycles, while radiofrequency platforms capture expanding margin pools as manufacturers integrate real-time temperature feedback and AI-guided dosing. Ultrasound devices for body contouring represent the fastest-growing application segment, driven by physician demand for adipose tissue disruption without downtime.
FDA 510(k) clearances and CE marking under the EU MDR govern device safety profiles, clinical evidence requirements, and post-market surveillance obligations, directly shaping product development timelines and market access costs. The MDR's heightened scrutiny of energy-based devices has forced manufacturers to rebuild technical documentation and clinical portfolios, favoring firms with established regulatory infrastructure. Stakeholders must monitor how emerging AI-driven treatment planning features trigger new software-as-medical-device classifications across jurisdictions.
Market Dynamics
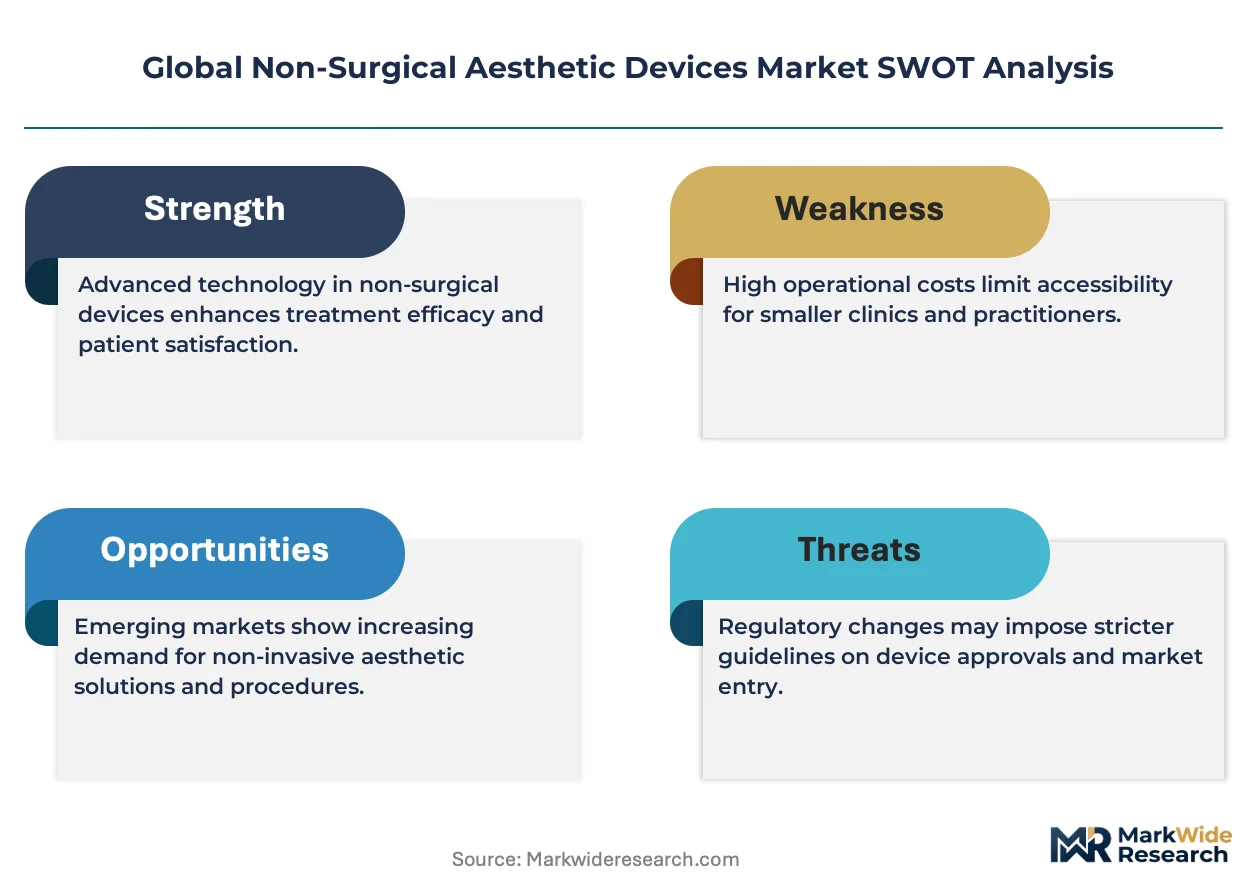
The non-surgical aesthetic devices market pivots on tightening FDA 510(k) and EU MDR safety thresholds that force manufacturers toward AI-guided dosing systems and real-time temperature feedback modules. Device procurement cycles compress as clinics demand platforms with embedded compliance documentation.
Growth Catalysts
- EU MDR Technical Documentation Mandates:Heightened clinical evidence requirements for energy-based devices favor established manufacturers with regulatory infrastructure, accelerating consolidation among compliant platform suppliers.
- Radiofrequency with AI-Guided Dosing:Dermatology clinics adopt these systems for margin expansion through reduced operator variability and standardized treatment outcomes across patient populations.
- South Korea Clinic Density:Seoul's medical tourism corridor drives concentrated demand for multi-modality platforms serving inbound aesthetic patients seeking same-day procedures.
Market Restraints
- EU MDR Re-Certification Burden:Technical documentation rebuilds for legacy laser platforms extend timelines 18-24 months, freezing product portfolios for mid-tier manufacturers lacking dedicated regulatory teams.
- Optical Component Supply Concentration:German and Japanese precision laser source suppliers control critical wavelength-specific hardware, exposing device assemblers to allocation risk during demand surges.
- Non-Invasive Body Contouring Efficacy Ceiling:Ultrasound adipose disruption delivers measurable but modest fat reduction compared to surgical liposuction, limiting patient candidacy and repeat procedure rates.
Strategic Opportunities
- Brazil Elective Aesthetic Penetration:São Paulo and Rio de Janeiro clinics show underdeveloped adoption of combined radiofrequency-microneedling platforms versus North American and Asian benchmarks.
- Subscription Consumable Models:Manufacturers capture recurring revenue through locked-in treatment tip contracts and software-defined protocol updates, shifting clinic relationships from transactional to annuity-based.
- AI Treatment Planning Software:FDA software-as-medical-device pathways for automated dosing algorithms create first-mover advantages for platforms with embedded machine learning modules.
Industry Challenges
- Cross-Trained Technician Scarcity:Clinics struggle to recruit operators proficient across laser, radiofrequency, and ultrasound modalities, forcing extended training investments or reduced device utilization rates.
- Legacy Platform Integration Complexity:New AI-guided systems require data bridge construction to existing patient management software, extending implementation timelines and inflating total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Surgical Aesthetic Devices Market |
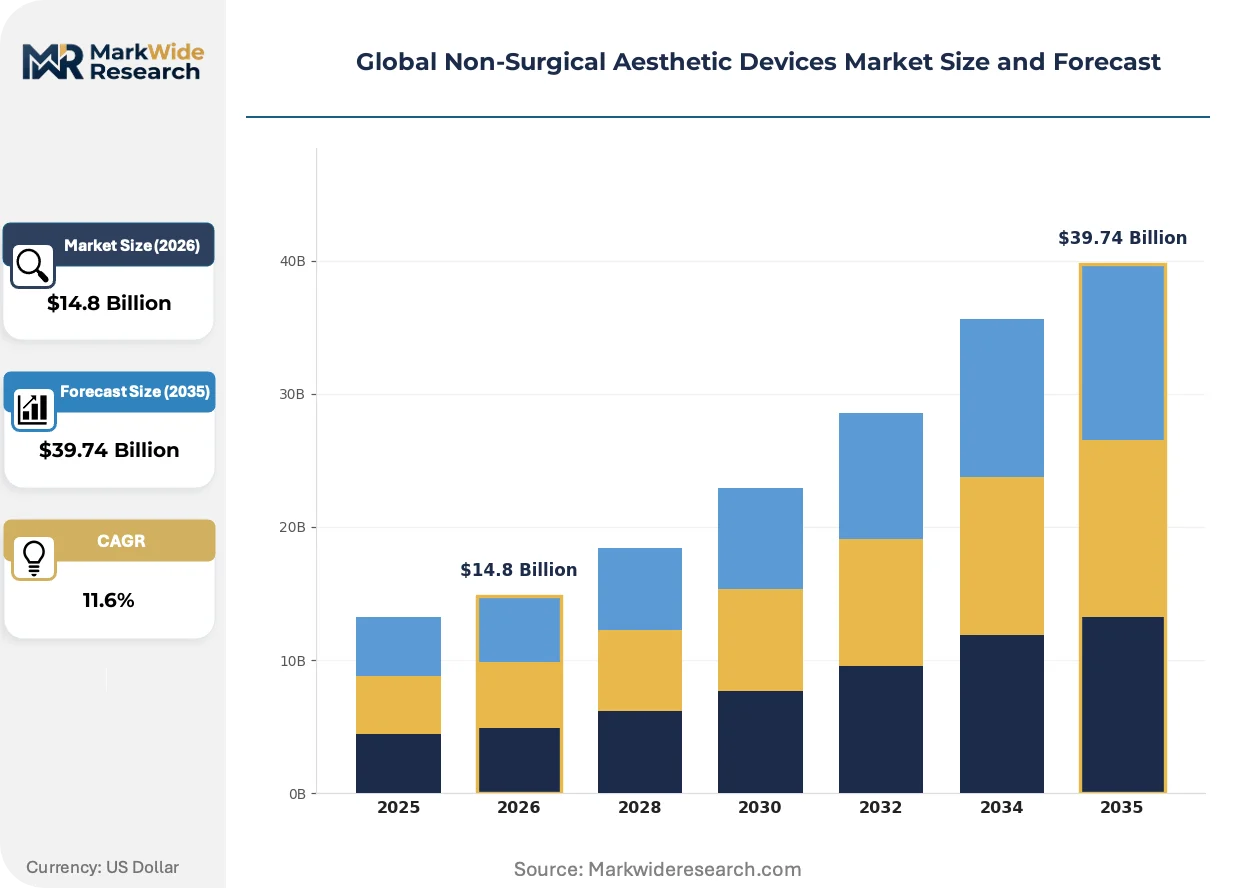
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Devices, Ultrasound Devices, Radiofrequency Devices, Light Therapy Devices Technology: Biotechnology, Electromagnetic Radiation, Electroporation, Nanotechnology Application: Skin Rejuvenation, Body Contouring, Hair Removal, Acne Treatment End User: Dermatology Clinics, Beauty Salons, Medical Spas, Home Care |
| Companies Covered | Allergan, Galderma, Cutera, Cynosure, Alma Lasers, Fotona, Lumenis, Merz Pharmaceuticals, Bausch Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Surgical Aesthetic Devices Market Shifts & Advancements
Device architecture is pivoting toward software-defined treatment protocols that embed compliance documentation and enable remote parameter updates. Manufacturers compete through ecosystem lock-in rather than hardware differentiation alone.
Radiofrequency platforms are integrating real-time impedance monitoring and closed-loop temperature control to eliminate operator-dependent variability. Medical spas in the United States adopt these systems fastest, compressing training requirements and reducing liability exposure. The technology is integrating predictive maintenance algorithms that flag electrode degradation before treatment failure.
FDA 510(k) clearance pathways for combination devices now require discrete clinical evidence for each energy modality rather than predicate-device equivalence. Laser-radiofrequency platforms face extended review timelines, favoring manufacturers with dedicated regulatory affairs infrastructure. Dermatology chains respond by consolidating procurement around suppliers with established 510(k) track records.
Clinic procurement committees now prioritize bundled service contracts covering hardware, consumables, and software updates over capital purchase arrangements. Medical spa chains in South Korea lead this shift, trading upfront margin for predictable operational expenditure structures. Brazil and Mexico follow as franchise clinic networks expand, standardizing equipment specifications across multi-site operations.
Global Non-Surgical Aesthetic Devices Market Segmentation
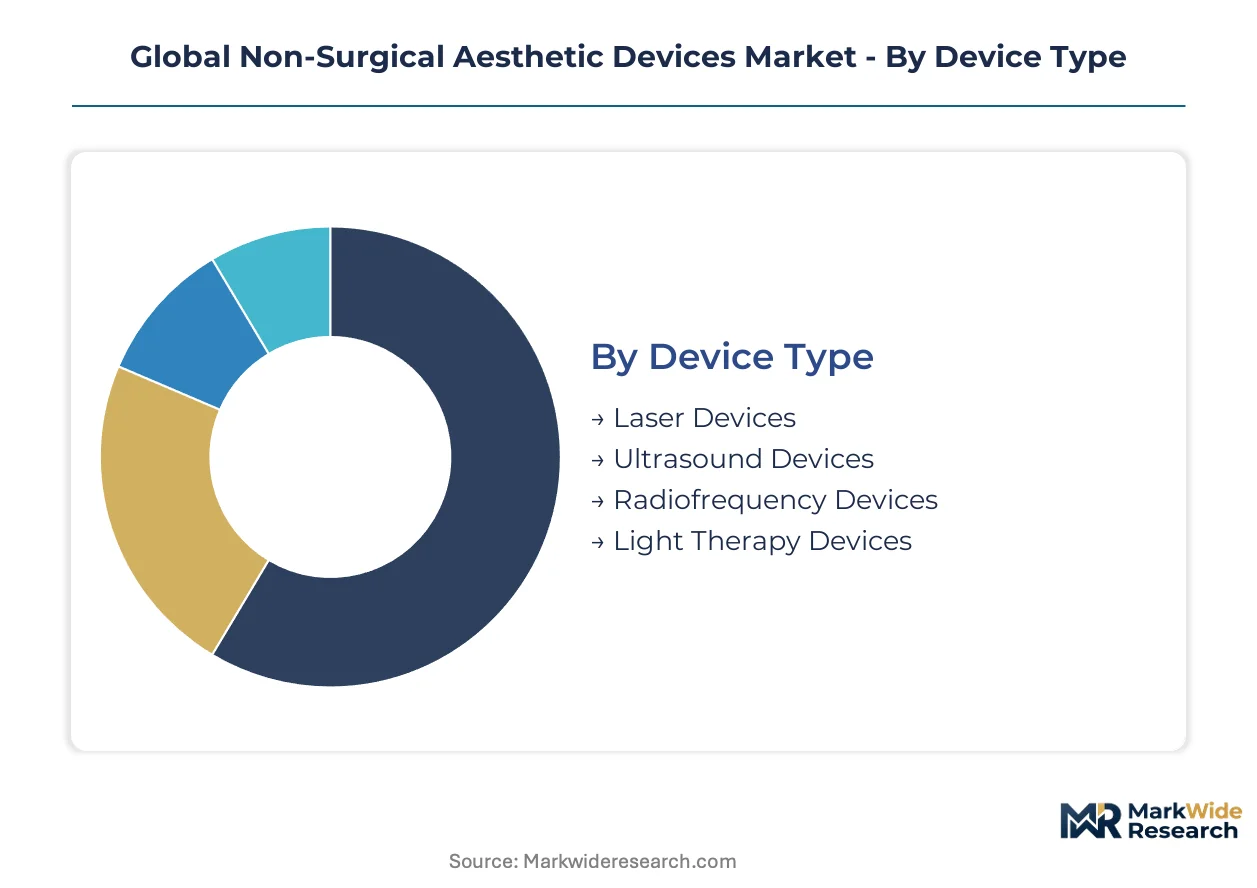
Segmentation in non-surgical aesthetic devices reveals distinct procurement patterns across device architectures and care settings. Manufacturers optimize platform configurations differently for high-volume clinic chains versus specialized dermatology practices, while technology choices determine regulatory pathway complexity and margin structure.
Device Type:
Standalone laser systems dominate capital budgets, while radiofrequency and ultrasound platforms increasingly embed into multi-modality consoles to maximize treatment room throughput.
- Laser Devices:These systems operate across 532 nm to 10,600 nm wavelengths targeting specific chromophores for skin resurfacing, pigmentation correction, and vascular lesions. Demand concentrates in United States dermatology chains where replacement cycles accelerate as FDA 510(k) pathways tighten predicate-device equivalence standards.
- Radiofrequency Devices:Thermal tissue modification through electromagnetic energy delivery now integrates real-time impedance monitoring and closed-loop temperature control. Medical spas in Seoul and São Paulo adopt these platforms fastest for margin expansion through reduced operator training requirements and standardized outcomes.
- Ultrasound Devices:Mechanically disrupts adipose tissue at focal depths without epidermal damage.
- Light Therapy Devices:LED and IPL platforms serve entry-level aesthetic practices with lower capital barriers.
Volume placements concentrate in laser devices; the faster expansion belongs to ultrasound devices.
Technology:
Cost tiers separate legacy electromagnetic platforms from emerging biotech and nanotech approaches requiring specialized manufacturing partnerships.
- Electromagnetic Radiation:Mature energy delivery mechanisms power the majority of installed laser and radiofrequency systems. United States and South Korean clinics represent the primary demand concentration as these markets prioritize proven efficacy data over novel mechanism claims.
- Biotechnology:Cell-derived growth factors and biostimulatory agents increasingly combine with energy-based devices for enhanced tissue response. Dermatology clinics in Brazil show accelerating interest in biotech-integrated protocols despite premium pricing.
- Electroporation:Transient membrane permeabilization enables topical agent penetration without needle injection.
- Nanotechnology:Targeted delivery systems and nano-structured surfaces remain early-stage with limited commercial deployment.
Revenue concentration sits with electromagnetic radiation; biotechnology platforms are climbing the fastest.
Application:
Customer type stratification shows dermatology clinics prioritizing clinical evidence depth while medical spas emphasize treatment throughput and same-day patient turnover.
- Skin Rejuvenation:Collagen remodeling and textural improvement procedures command the broadest addressable patient base across age demographics. United States medical spa chains standardize procurement around multi-modality platforms serving this application to maximize device utilization rates.
- Body Contouring:Non-invasive adipose reduction through cryolipolysis, ultrasound, or radiofrequency addresses patient demand for surgical alternatives. Clinics in Brazil and South Korea drive concentrated adoption as body aesthetic procedures carry strong cultural prioritization.
- Hair Removal:Laser-based permanent hair reduction represents a mature, price-commoditized segment.
- Acne Treatment:Light-based and energy modalities target inflammatory and scarring presentations.
Procedure volume concentrates in skin rejuvenation; body contouring shows the steepest expansion trajectory.
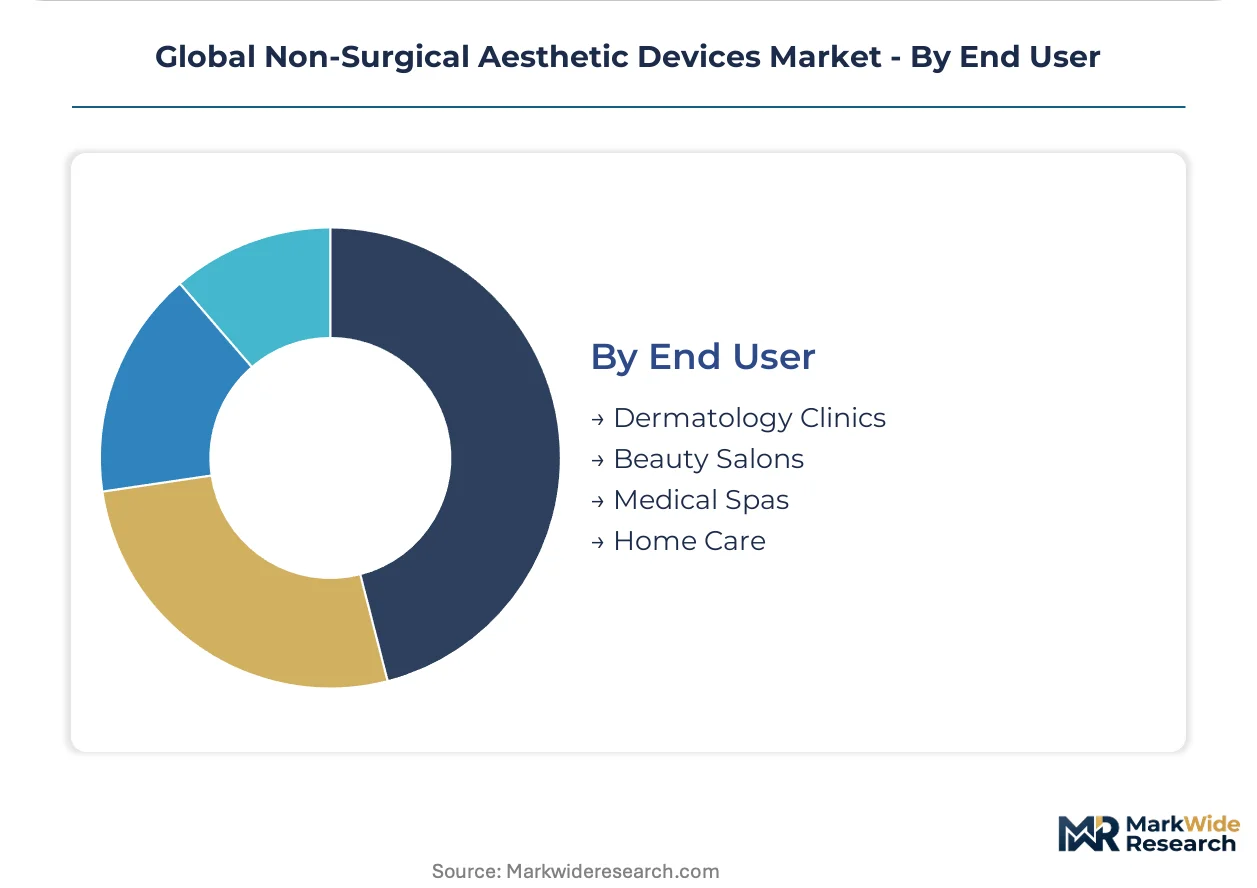
End User:
Supply concentration favors established manufacturers with dedicated regulatory affairs infrastructure serving institutional purchasers over fragmented home care channels.
- Dermatology Clinics:Physician-supervised settings demand platforms with comprehensive clinical evidence packages and FDA 510(k) or CE marking documentation. These buyers in the United States and Germany consolidate procurement around suppliers with established regulatory track records.
- Medical Spas:Non-physician operated facilities prioritize ease of use, training compression, and bundled service contracts. South Korean medical spa chains lead the shift toward subscription-based consumable models trading upfront margin for predictable operational expenditure.
- Beauty Salons:Lower-regulation jurisdictions permit aesthetic device operation without medical supervision.
- Home Care:Consumer-directed devices face efficacy limitations and safety liability constraints.
Capital deployment concentrates in dermatology clinics; medical spas are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's medical tourism corridor concentrates procurement of multi-modality aesthetic platforms, with clinic density exceeding any other metropolitan cluster worldwide. The United States, South Korea, Brazil, Germany, and Japan anchor device demand through distinct regulatory pathways and patient payment structures.
United States
Dermatology chains in Los Angeles and New York accelerate replacement cycles for laser systems as FDA 510(k) pathways tighten predicate-device equivalence standards. The FDA's heightened scrutiny of energy-based device submissions extends review timelines, favoring manufacturers with established regulatory infrastructure. Miami's medical spa corridor drives concentrated adoption of subscription-based consumable models among franchise clinic networks.
South Korea
Seoul's Gangnam district operates the densest concentration of aesthetic clinics globally, with multi-modality platforms serving inbound medical tourists seeking same-day procedures. The MFDS maintains streamlined approval pathways for devices with prior FDA clearance, accelerating market access for compliant manufacturers. Busan's emerging clinic networks standardize procurement around bundled service contracts covering hardware, consumables, and software updates.
Brazil
São Paulo and Rio de Janeiro clinics show underdeveloped adoption of combined radiofrequency-microneedling platforms versus North American benchmarks, presenting expansion opportunities for compliant suppliers. ANVISA's regulatory framework for Class III medical devices requires local clinical trials, extending market entry timelines for foreign manufacturers. The country's elective aesthetic penetration rates support premium pricing for platforms with embedded AI-guided dosing systems.
Germany
Dermatology practices in Munich and Hamburg consolidate procurement around suppliers with established CE marking track records under the EU MDR's heightened technical documentation mandates. The MDR's 18-24 month recertification timelines for legacy laser platforms freeze product portfolios for mid-tier manufacturers lacking dedicated regulatory teams. Stuttgart's precision optics cluster supplies critical wavelength-specific laser sources to device assemblers worldwide.
Japan
Tokyo's aesthetic clinics prioritize platforms with comprehensive clinical evidence packages as PMDA review standards align with FDA and EU MDR rigor. The country's aging demographic drives demand for skin rejuvenation applications, with medical spas in Osaka adopting radiofrequency systems for reduced operator training requirements. Nagoya's manufacturing base produces specialized optical components for energy-based device integration.
Global Non-Surgical Aesthetic Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the non-surgical aesthetic devices market, with integrated pharmaceutical-device conglomerates holding structural advantages in bundled service contracting. The vendor base stratifies into three tiers: established conglomerates with regulatory infrastructure, mid-scale specialists in single energy modalities, and emerging platform developers targeting AI-guided dosing niches. Dominant competitive moves include M&A activity to acquire regulatory track records and strategic partnerships with precision optics suppliers to secure component allocation.
Within the integrated conglomerate tier, Allergan and Galderma anchor competitive positioning through toxin-filler-device ecosystem bundling that locks in clinic loyalty. Cutera exemplifies the mid-scale specialist archetype, occupying a position between diversified conglomerates and emerging developers. These companies represent distinct strategic postures: Allergan and Galderma sit within pharmaceutical-origin diversification, while Cutera occupies the pure-play energy-based device segment.
| Leading Market Players |
|---|
| Allergan |
| Galderma |
| Cutera |
| Cynosure |
| Alma Lasers |
| Fotona |
| Lumenis |
| Merz Pharmaceuticals |
| Bausch Health |
| Others |
Supply & Pricing Matrix
Precision laser source pricing indices in Germany and Japan cascade through device assembler cost structures, compressing margins for mid-tier manufacturers while premium-tier suppliers absorb volatility through captive optical component production and long-term offtake agreements with Stuttgart and Nagoya clusters.
Pricing Analysis
Cost-down pressure on standard-tier laser platforms accelerates because EU MDR recertification timelines force mid-scale manufacturers to discount legacy inventory ahead of technical documentation deadlines. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared systems with AI-guided dosing from predicate-equivalent devices and unbundled hardware-only configurations. Price differentiation rests on CE marking tier and embedded software subscription status. Medical spa chains in South Korea show lowest price sensitivity; Brazilian franchise clinics exhibit highest.
Supply Chain Analysis
ANVISA's local clinical trial mandates for Class III device registration reshape sourcing toward Brazilian assembly partnerships for foreign manufacturers seeking market access. German and Japanese suppliers dominate wavelength-specific optical components; Chinese metalwork and precision machining feed console housing production. Single-source vulnerability concentrates in ytterbium-doped fiber laser sources from Stuttgart-area specialists. Distribution runs through direct sales forces serving dermatology chains and distributor networks covering medical spa franchises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical component fabrication capacity constraints in Germany and Japan prop pricing power for vertically integrated device manufacturers, sustaining margin premiums through supply scarcity.
For Market Incumbents: Cement ecosystem lock-in through bundled toxin-filler-device service contracts that raise switching costs for dermatology chains. Deepen backward integration into precision laser source production to neutralize allocation risk from Stuttgart and Nagoya suppliers. Prioritize regulatory infrastructure investment ahead of EU MDR's escalating clinical evidence thresholds.
For New Entrants and Emerging Players: MFDS streamlined approval pathways in South Korea open a window for AI-guided dosing platforms with prior FDA clearance to penetrate Seoul's Gangnam clinic corridor. Target underpenetrated combined radiofrequency-microneedling adoption in São Paulo and Rio de Janeiro. Pursue white-label manufacturing partnerships with established optical component suppliers to compress time-to-revenue.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale specialists frozen by EU MDR recertification burdens in Germany and the United States. Long-term viability hinges on regulatory track record depth rather than hardware differentiation alone. Monitor FDA software-as-medical-device clearance velocity as inflection signal for AI-integrated platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Rebuild | Accelerates consolidation by freezing non-compliant legacy portfolios for mid-tier manufacturers lacking dedicated regulatory teams. |
| AI-Guided Dosing FDA Submission | Creates first-mover advantage for platforms embedding machine learning modules under software-as-medical-device pathways. |
| Subscription Consumable Model Rollout | Transforms clinic relationships from transactional hardware purchases to annuity-based operational expenditure structures. |
| Precision Optics Supplier Partnership | Secures allocation priority for ytterbium-doped fiber sources from Stuttgart and Nagoya clusters during demand surges. |
| Multi-Modality Platform Integration | Maximizes treatment room throughput for Seoul medical tourism corridor seeking same-day procedure density. |
Research Methodology
FDA 510(k) clearance databases, EU MDR technical documentation filings, and MFDS approval registries formed the secondary backbone. Primary interviews with dermatology clinic procurement directors, medical spa franchise operators, biomedical engineers at device manufacturers, and GPO contracts managers validated demand assumptions. Customs data from German and Japanese precision optics exports anchored supply-side modeling. Bottom-up device shipment estimates and top-down aesthetic procedure volume data underwent triangulation.
Historical replacement cycle analysis across laser, radiofrequency, and ultrasound platforms established baseline trendlines. Segmentation modeling spanned device architecture, energy delivery technology, clinical application, and end-user setting across the projection horizon. CAGR derivation incorporated regulatory pathway timeline assumptions, clinic density growth patterns, and consumable attach rate trajectories. AI software integration penetration and subscription contract adoption curves served as industry-specific forecast inputs.
Caveats apply where FDA software-as-medical-device reclassification or EU MDR enforcement intensity shifts could materially shift the outlook. Forecasts embed assumptions regarding optical component supply stability and medical tourism recovery velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Display Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Global Occlusion Devices Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
T-Piece Resuscitator Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Global Nebulizers Market
Medical Devices
Transportable Ventilator Market
Medical Devices
Global Intravenous Infusion Pump Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
United States Organ Preservation Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Midline Catheters Market