
 Graft vs Host Disease Market | 2026-2036
Graft vs Host Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Graft vs Host Disease Market Intelligence
Capital-intensity divergence between large-cap biopharmaceutical firms and mid-therapy developers is reorganizing competitive dynamics in the Graft vs Host Disease landscape. Incyte leverages its JAK inhibitor franchise to sustain leadership in steroid-refractory acute cases across North American transplant centers. Novartis anchors its position through integrated cell therapy and small-molecule portfolios that span prevention and treatment protocols.
Graft vs Host Disease represents an immune-mediated complication following allogeneic hematopoietic stem cell transplantation, wherein donor T cells recognize recipient tissues as foreign and mount cytotoxic attacks against skin, liver, and gastrointestinal epithelium; therapeutic management requires immunosuppressive modulation ranging from corticosteroid induction to targeted biologic intervention. Corticosteroids retain the largest installed base as first-line induction therapy despite well-documented long-term toxicity profiles that limit duration. Monoclonal antibodies represent the fastest-expanding segment, driven by mechanistic specificity against cytokine signaling pathways and improved outcomes in steroid-refractory populations.
FDA breakthrough therapy designation and EMA PRIME eligibility criteria are compressing development timelines for novel biologics while raising evidentiary standards for comparative efficacy against corticosteroid benchmarks. The EU's MDR framework and FDA's evolving guidance on cell and gene therapy products are reshaping manufacturing compliance requirements for advanced therapy medicinal products. Stakeholders must monitor how payer consolidation and outcomes-based contracting for transplant episodes reshape access dynamics for premium-priced biologics.
Market Dynamics
Allogeneic transplant volume expansion at tertiary oncology centers is compressing the therapeutic window for prophylactic intervention, forcing developers to accelerate mechanistic differentiation ahead of corticosteroid refractory progression.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The pathway compresses Phase II-to-approval timelines for novel biologics targeting steroid-refractory acute presentations. Developers leverage this to outpace corticosteroid benchmark comparisons.
- Japan's transplant infrastructure maturation:PMDA reimbursement alignment with biologic prophylaxis protocols expands the addressable pool for therapeutic candidates in high-volume hematology centers.
- Monoclonal antibody mechanistic specificity:Cytokine pathway targeting delivers improved progression-free survival in gastrointestinal and hepatic involvement cases versus broad immunosuppression.
Market Restraints
- Biologic manufacturing concentration:Single-source contract development organizations in Switzerland and Germany create supply vulnerability for advanced therapy medicinal products requiring cold-chain integrity.
- EMA MDR compliance burden:The EU's Medical Device Regulation imposes extended quality management system audits that delay commercial launch timelines by 12-18 months for cell therapy adjuncts.
- Corticosteroid substitution persistence:First-line induction protocols at US academic medical centers resist displacement due to institutional familiarity and formulary inertia despite toxicity documentation.
Strategic Opportunities
- Germany's ATMP reimbursement corridor:The G-BA's early benefit assessment pathway for advanced therapy medicinal products creates favorable access conditions for prophylactic biologics in allogeneic protocols.
- Chimeric antigen receptor T-cell convergence:Integration of CAR-T conditioning regimens with GVHD prophylaxis biologics opens combination therapy positioning for cytokine signaling inhibitors.
- Direct-to-transplant-center distribution:Bypassing wholesale pharmaceutical channels through specialty pharmacy partnerships reduces margin leakage and improves cold-chain custody documentation.
Industry Challenges
- Cell therapy manufacturing skill scarcity:Qualified personnel for GMP-compliant allogeneic cell processing remain concentrated at fewer than 40 US and European facilities, constraining batch scale-up.
- Comparative efficacy trial design complexity:FDA and EMA divergence on acceptable corticosteroid refractory endpoints forces parallel protocol development, inflating clinical program costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graft vs Host Disease Market |
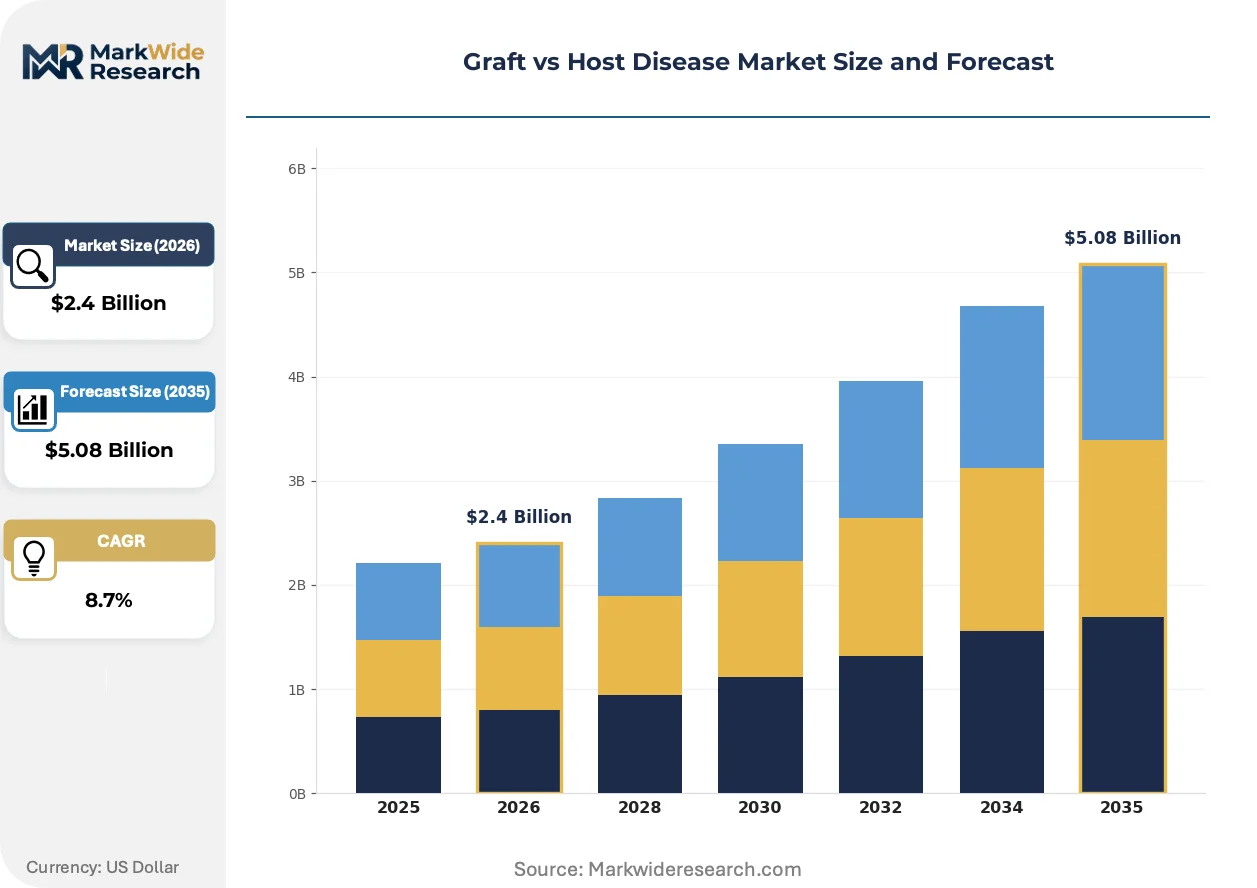
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Corticosteroids, Monoclonal Antibodies, Antimetabolites, Intravenous Immunoglobulin Stage: Acute, Chronic, Severe, Relapsed End User: Hospitals, Specialty Clinics, Research Institutions, Homecare Patient Demographics: Pediatric, Adult, Elderly, Transplant Recipients |
| Companies Covered | Incyte, Novartis, Pfizer, Sanofi, Bristol Myers Squibb, AbbVie, Astellas Pharma, Johnson and Johnson, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graft vs Host Disease Market Strategic Shifts & Innovations
Mechanistic precision in immunomodulation is displacing empiric corticosteroid escalation, while regulatory frameworks on both sides of the Atlantic accelerate evidentiary compression for biologic candidates.
JAK inhibitor small-molecules are supplanting calcineurin-based prophylaxis in steroid-refractory acute protocols at North American transplant centers. Academic medical center formularies in the United States and Canada are adopting these agents within 18 months of label expansion. The shift is compressing the revenue window for broad immunosuppressants and forcing incumbent portfolio restructuring toward targeted signaling modulation.
REACH authorization requirements for novel chemical entities are extending toxicology submission timelines for European prophylactic candidates. ECHA's substance evaluation workload has created bottlenecks at CRO toxicology facilities in Germany and the Netherlands. Developers are responding by front-loading non-clinical packages and securing rapporteur assignment early in the centralized procedure.
Episode-based reimbursement for allogeneic transplant procedures is bundling prophylactic biologic costs into DRG-equivalent payments at US centers of excellence. Medicare Advantage plans in Florida and Texas are piloting outcomes-adjusted contracts that penalize readmission for severe acute presentation. This compresses unit economics for premium-priced monoclonal antibodies and favoring agents with demonstrable steroid-sparing impact on length-of-stay metrics.
Graft vs Host Disease Market Segmentation
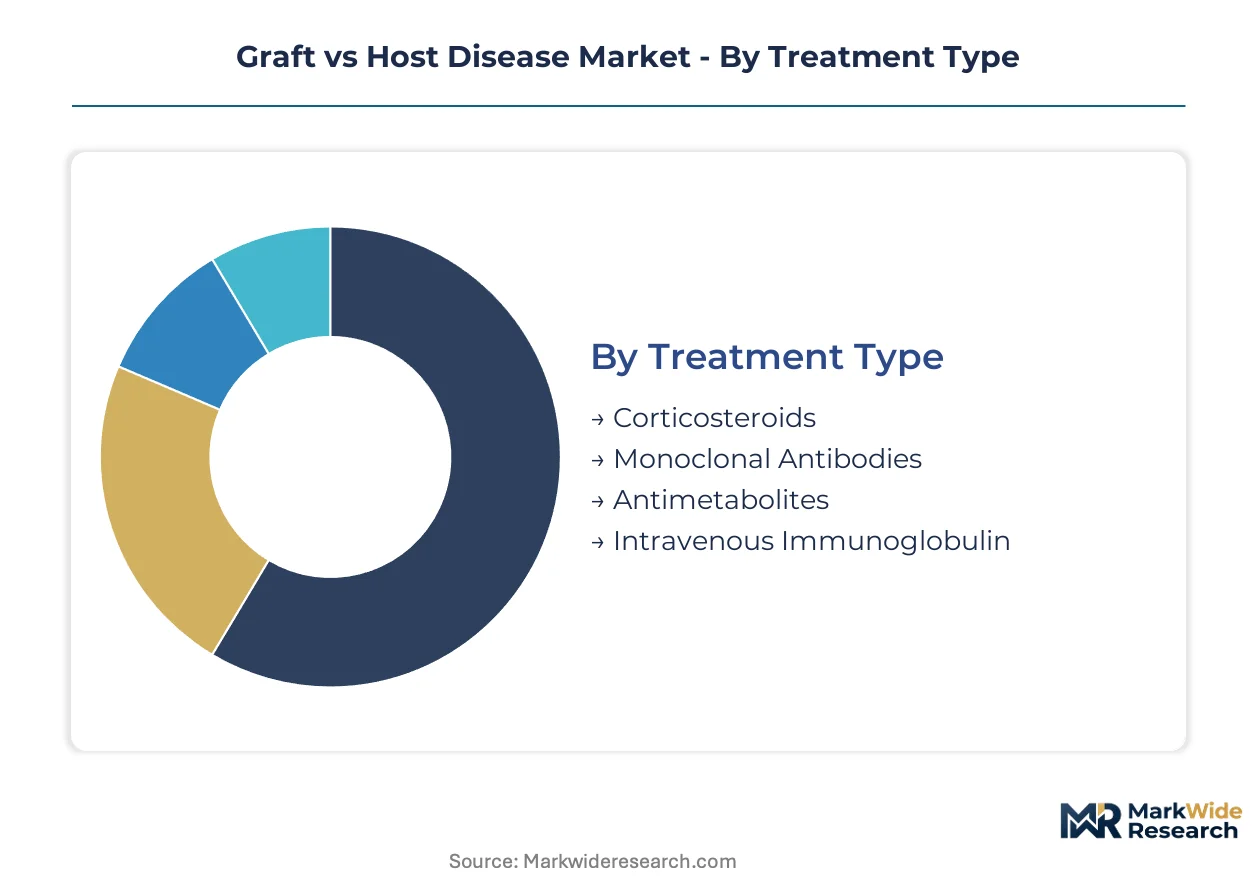
Treatment modality selection in Graft vs Host Disease hinges on disease severity, transplant center protocol maturity, and payer reimbursement tiering. Channel dynamics vary sharply across prophylactic versus therapeutic contexts, with hospital-based infusion centers capturing biologic administration while retail pharmacies handle corticosteroid maintenance.
Treatment Type:
Channel mix diverges sharply: corticosteroids flow through wholesale distributors to hospital formularies, while monoclonal antibodies require specialty pharmacy cold-chain custody with direct-to-site delivery.
- Monoclonal Antibodies:Engineered proteins targeting cytokine signaling pathways such as IL-6, TNF-alpha, and JAK-STAT axes deliver mechanistic specificity unavailable with broad immunosuppression. Demand concentrates at US academic medical centers and German university hospitals where transplant volumes exceed 200 allogeneic procedures annually and formulary committees prioritize steroid-sparing protocols.
- Corticosteroids:Synthetic glucocorticoids including methylprednisolone and prednisone remain the institutional standard for first-line induction despite cumulative toxicity profiles. Volume concentrates in India and Brazil where cost containment at public tertiary centers limits biologic penetration; EMA and national regulators maintain stringent documentation requirements for corticosteroid-sparing transitions.
- Antimetabolites:Cytotoxic agents such as methotrexate and mycophenolate mofetil function as prophylactic adjuncts in calcineurin-based regimens.
- Intravenous Immunoglobulin:Polyclonal antibody preparations from pooled plasma serve refractory cases with infectious complications.
Established volume favors corticosteroids; emerging adoption favors monoclonal antibodies.
Stage:
Cost tier stratification separates acute intervention—commanding premium biologic pricing—from chronic management where reimbursement bundling compresses margins.
- Acute:Onset within 100 days post-transplant characterized by skin, liver, and gastrointestinal involvement requiring immediate immunosuppressive escalation. Pediatric and adult transplant recipients at US centers of excellence drive demand for JAK inhibitor integration; FDA breakthrough therapy designations accelerate label expansion for refractory presentations.
- Severe:Grade III-IV presentations per modified Glucksberg criteria necessitate intensive care unit admission and combination biologic protocols. German and Japanese transplant networks report highest severe case density due to older donor-recipient age matching; PMDA and EMA parallel track reviews compress development timelines for salvage therapies.
- Chronic:Multi-organ fibrotic sequelae developing after day 100 requiring prolonged immunomodulation.
- Relapsed:Recurrence following initial response or taper failure demanding mechanism-switch strategies.
Acute presentations absorb the highest per-patient therapy costs; chronic stages extend treatment duration but fragment revenue across multiple agents.
End User:
Application context determines procurement authority: hospital pharmacy and therapeutics committees control biologic access, while homecare nursing agencies administer subcutaneous maintenance.
- Hospitals:Tertiary oncology and transplant centers with dedicated hematopoietic stem cell units perform 80% of allogeneic procedures in the United States, Germany, and Japan combined. These institutions maintain centralized biologic procurement through group purchasing organizations and restricted formulary tiers for novel agents.
- Specialty Clinics:Outpatient infusion centers affiliated with transplant programs manage post-discharge biologic administration and corticosteroid taper protocols.
- Research Institutions:National Cancer Institute-designated centers and European Organisation for Research and Treatment of Cancer nodes conduct Phase II-III trials for mechanistic candidates.
- Homecare:Skilled nursing services deliver subcutaneous immunoglobulin and oral maintenance regimens to stable chronic patients.
Hospital concentration shapes pricing power for prophylactic biologics; homecare expansion extends addressable duration for maintenance therapies.
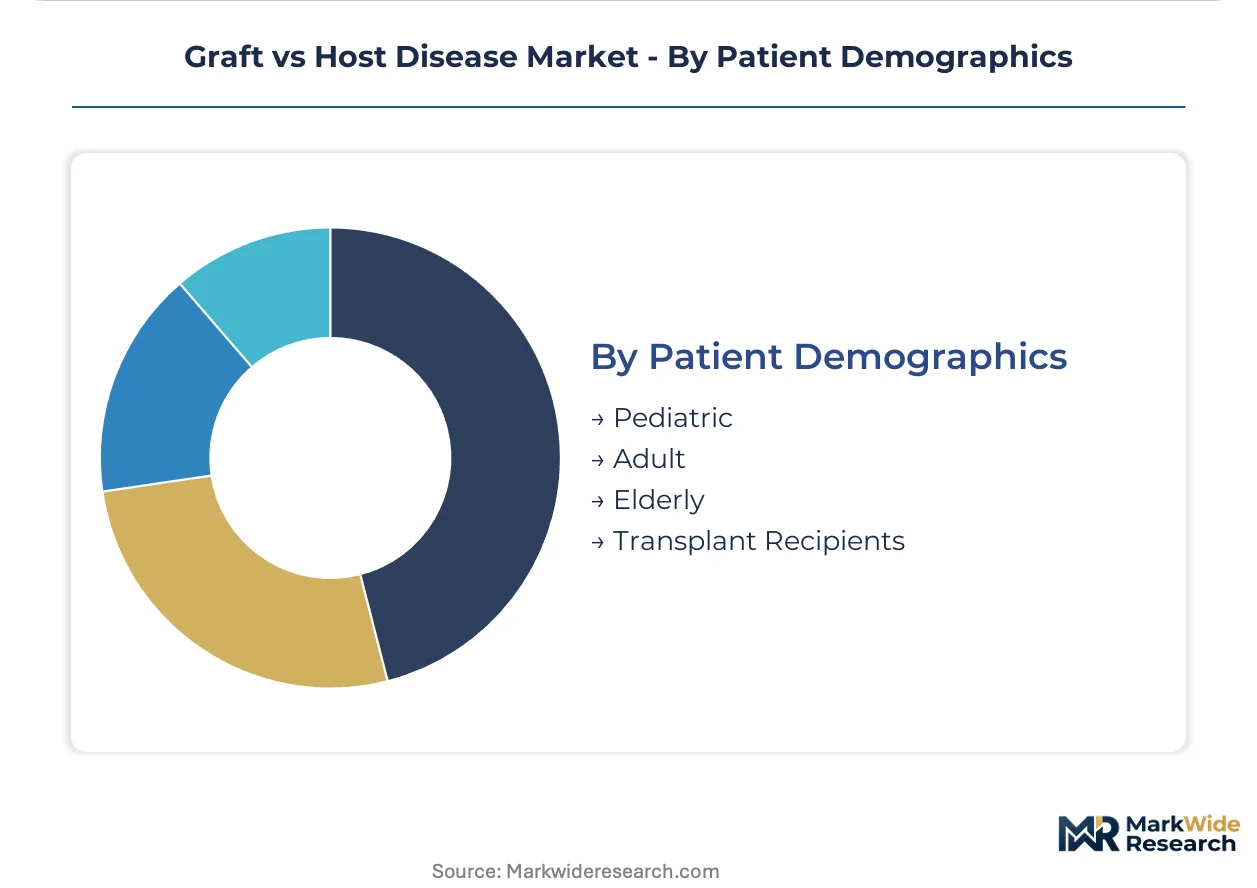
Patient Demographics:
Volume distribution skews toward adult transplant recipients, while pediatric protocols command premium pricing for weight-based dosing and orphan indications.
- Transplant Recipients:Allogeneic hematopoietic stem cell transplantation patients constitute the definitional population for both prophylaxis and treatment, with risk stratification by donor match, conditioning intensity, and graft source determining therapy selection.
- Adult:Patients aged 18-65 years represent the median transplant demographic with highest procedure volume at US and German centers; Medicare Advantage and statutory health insurance reimbursement frameworks favor established biologics over experimental mechanisms.
- Pediatric:Patients under 18 years require specialized dosing, toxicity monitoring, and developmental outcome tracking.
- Elderly:Patients over 65 years with reduced-intensity conditioning regimens experience distinct GVHD phenotypes.
Adult volume sustains current revenue bases; pediatric and elderly subpopulations present the steepest expansion trajectories for mechanism-specific development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for GVHD therapeutics varies sharply across transplant centers. United States academic medical centers absorb premium biologic pricing with limited resistance. German statutory insurers negotiate aggressively on prophylactic protocols. Japanese reimbursement panels impose strict cost-effectiveness thresholds.
United States
FDA breakthrough therapy designations compress development timelines for steroid-refractory candidates. Medicare Advantage plans in Florida and Texas pilot outcomes-adjusted contracts that penalize severe acute readmissions. MD Anderson Cancer Center and Memorial Sloan Kettering anchor the highest allogeneic transplant volumes globally.
Germany
The G-BA's early benefit assessment pathway for advanced therapy medicinal products shapes access conditions for prophylactic biologics. EMA MDR compliance extends quality management audits for cell therapy adjuncts. Heidelberg and Berlin university hospitals concentrate the highest severe case density due to older donor-recipient matching protocols.
Japan
PMDA reimbursement alignment with biologic prophylaxis expands the addressable pool at high-volume hematology centers. METI industrial policy supports domestic manufacturing capacity for cold-chain-dependent monoclonal antibodies. Tokyo and Osaka transplant networks report accelerating adoption of JAK inhibitor integration.
United Kingdom
NICE technology appraisals impose cost-per-QALY thresholds that filter premium biologic access. MHRA post-Brexit regulatory autonomy accelerates parallel track reviews with FDA. London and Manchester tertiary centers drive protocol innovation through NHS England specialized commissioning.
Switzerland
Swissmedic's streamlined authorization for orphan indications attracts biologic developers seeking rapid European market entry. The country's contract development organizations concentrate GMP manufacturing for advanced therapy medicinal products. Basel and Zurich clusters host the highest density of transplant-associated pharmacovigilance expertise.
Graft vs Host Disease Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the GVHD therapeutic landscape. Large-cap biopharmaceutical firms leverage integrated cell therapy and small-molecule portfolios spanning prevention and treatment protocols. Mid-cap specialists concentrate on mechanistic differentiation within cytokine signaling pathways. Competitive moves center on strategic partnerships for manufacturing scale and portfolio diversification into prophylactic positioning.
Within the large-cap integrated tier, Novartis and Bristol Myers Squibb occupy positions spanning cell therapy conditioning through salvage intervention. Incyte exemplifies the targeted-therapy archetype with JAK inhibitor concentration. Among diversified biopharmaceutical operators, Pfizer and AbbVie represent cost-leadership positioning through corticosteroid and immunomodulatory maintenance portfolios.
| Leading Market Players |
|---|
| Incyte |
| Novartis |
| Pfizer |
| Sanofi |
| Bristol Myers Squibb |
| AbbVie |
| Astellas Pharma |
| Johnson and Johnson |
| Roche |
| Others |
Cost & Logistics Intelligence
JAK inhibitor substitution for calcineurin-based prophylaxis is simultaneously redrawing manufacturing geography toward Swiss and German CDMO clusters while compressing pricing power for legacy immunosuppressant portfolios. This input shift concentrates high-value biologic production in Alpine corridor facilities and forces tiered pricing stratification across prophylactic versus salvage therapy contexts.
Pricing Analysis
After-sales revenue from specialty pharmacy administration and patient monitoring contracts drives lifetime value for monoclonal antibody portfolios. Three-tier pricing structure across premium biologic, standard small-molecule, and economy corticosteroid levels reflects mechanistic differentiation and reimbursement tiering. Pricing pressure stems from Medicare Advantage bundling of transplant episodes into DRG-equivalent payments. Academic medical centers show lowest price sensitivity due to formulary autonomy; public tertiary centers in emerging markets exhibit highest sensitivity.
Supply Chain Analysis
Swissmedic cold-chain certification bottlenecks constrain batch release velocity for advanced therapy medicinal products. Manufacturing concentrates in Switzerland, Germany, and the United States where GMP-compliant allogeneic cell processing facilities cluster. Raw material dependencies include recombinant protein media, single-use bioreactor components, and cryopreservation excipients. Single-source contract development organization concentration creates vulnerability to EMA MDR audit delays. Distribution runs through direct-to-transplant-center specialty pharmacy partnerships bypassing wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
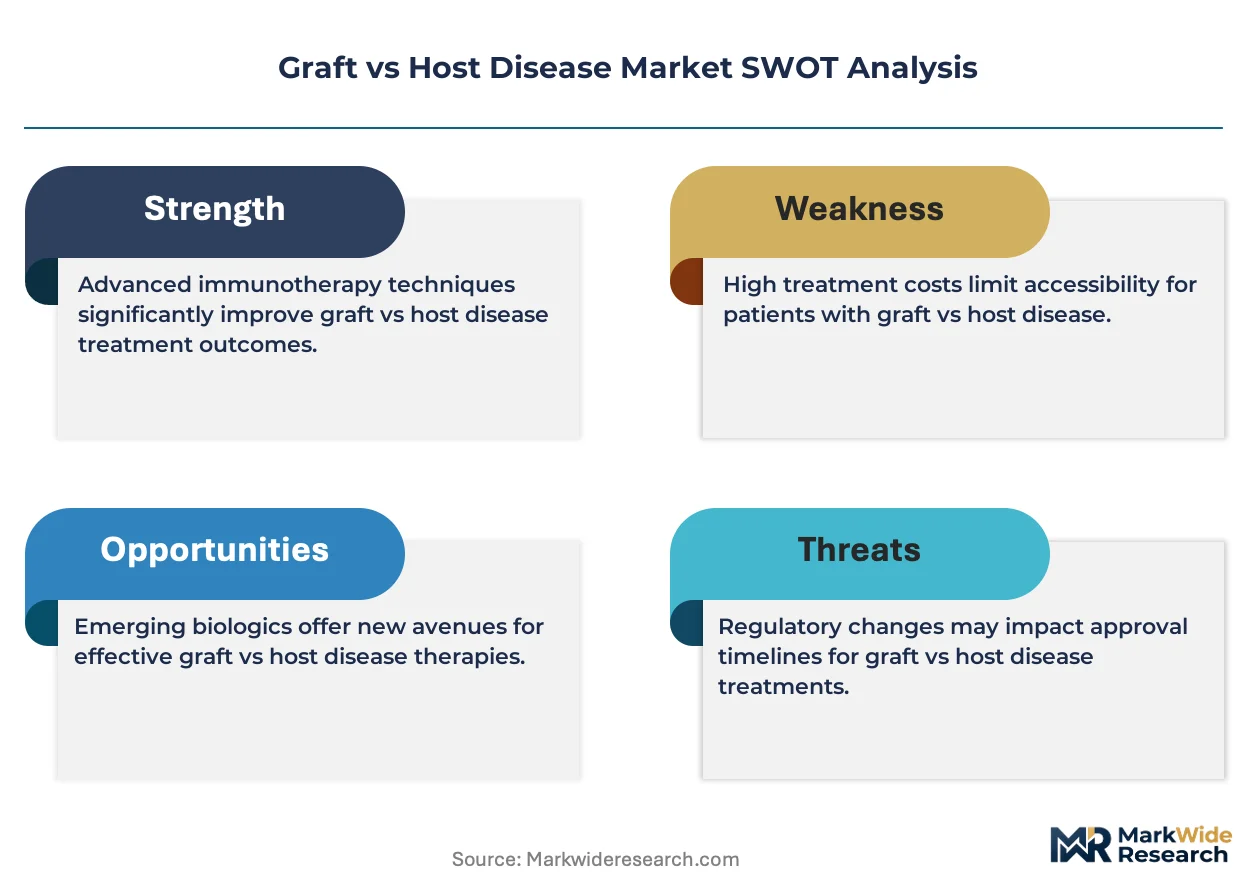
The Graft vs Host Disease market functions as a defensive-moat arena where FDA breakthrough therapy designations and transplant center formulary entrenchment create substantial switching costs for incumbent biologic portfolios.
For Market Incumbents: Fortify manufacturing capacity in Swiss and German CDMO corridors to preempt supply bottlenecks for JAK inhibitor and monoclonal antibody candidates. Deepen backward integration into recombinant protein media production to reduce single-source dependencies. Secure long-term specialty pharmacy partnerships before Medicare Advantage bundling accelerates channel consolidation. For New Entrants and Emerging Players: Post-discharge corticosteroid taper management services represent an underserved layer where incumbent biologic developers under-invest in patient adherence infrastructure. Target chronic GVHD maintenance protocols at US community oncology practices where formulary access barriers are lower than academic centers. Pursue direct-to-clinic distribution partnerships with regional transplant networks outside the three dominant metropolitan clusters. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap developers with parallel FDA and EMA regulatory submissions and established rapports with German G-BA assessors. Long-term viability hinges on prophylactic positioning ahead of CAR-T conditioning regimen expansion. Watch PMDA reimbursement alignment decisions for Japanese hematology centers as the inflection signal for Asia-Pacific market access trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation Pursuit | Compresses Phase II-to-approval timelines for steroid-refractory candidates against corticosteroid benchmarks. |
| EMA MDR Compliance Investment | Prevents 12-18 month quality audit delays for cell therapy adjunct commercial launches. |
| Specialty Pharmacy Partnership Expansion | Secures cold-chain custody documentation and bypasses wholesale margin leakage. |
| G-BA Early Benefit Assessment Preparation | Unlocks favorable ATMP reimbursement conditions in German statutory health insurance. |
| PMDA Reimbursement Alignment Engagement | Captures biologic prophylaxis expansion in Japanese high-volume hematology centers. |
Research Approach
Cross-validation between primary interviews with transplant center formulary directors, regulatory affairs leads at biologic developers, and specialty pharmacy procurement managers anchors the qualitative findings. Secondary validation draws from FDA breakthrough therapy designation filings, EMA centralized procedure assessment reports, ClinicalTrials.gov protocol registries, and German G-BA benefit assessment documents. Bottom-up patient volume modeling at named US, German, and Japanese transplant centers triangulates against top-down market sizing from payer reimbursement data.
Sensitivity analysis across pricing, transplant volume, and regulatory approval probability assumptions shapes the analytical framework throughout the projection horizon. Segmentation dimensions include treatment modality, disease severity stage, end-user institution type, and regional regulatory cluster. CAGRs derive from procedure volume trajectories at tier-one transplant centers and biologic adoption curves within institutional protocols. Forecast inputs incorporate PMDA reimbursement panel decisions and Medicare Advantage bundling pilot outcomes.
Forecasts assume regulatory continuity in FDA breakthrough designation criteria and EMA MDR enforcement timelines; material policy shifts would require re-modeling of development timeline and access assumptions. Specific risks include corticosteroid substitution persistence at US academic centers and REACH authorization bottlenecks for European prophylactic candidates. Practitioners should keep alternative scenarios live as transplant episode reimbursement bundling and JAK inhibitor integration protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Sickle Cell Treatment Market
Hematology
Multiple Myeloma Treatment Market
Hematology
Anemia Drugs Market
Hematology
Hemocytometer Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Pancytopenia Market
Hematology
Alpha Thalassemia Market
Hematology
Lymphopenia Therapeutics Market
Hematology
Global Non-Hodgkin Lymphoma Therapeutics Market
Hematology
Thrombocytopenia Treatment Market
Hematology
Polycythemia Vera Market
Hematology
Sickle Cell Anemia Market
Hematology
Haematocrit Centrifuge Market
Hematology
Myelodysplastic Syndrome (MDS) Treatment Market
Hematology
Global Sickle Cell Disease Treatment Market