
 Flap Rudder Market | 2026-2036
Flap Rudder Market Size, Share, and Industry Trends Forecast 2026-2036
Flap Rudder Market Intelligence
Naval procurement budgets are unwinding toward commercial shipbuilder demand as merchant fleet renewal cycles accelerate. Becker Marine Systems GmbH leverages its Becker Flap technology leadership to dominate high-efficiency rudder retrofits across European container lines. Kongsberg Gruppen anchors its position through integrated bridge-to-propeller automation packages that bundle flap rudder controls with dynamic positioning systems. Damen Marine Components competes via captive supply chains serving its parent yard network and third-party retrofit channels.
A flap rudder is a high-lift marine steering device incorporating a hinged trailing-edge flap that amplifies hydrodynamic force at low speeds and reduced rudder angles, typically fabricated from nickel-aluminum-bronze castings or welded high-tensile steel with composite bearing surfaces. The assembly generates asymmetric thrust vectors that shorten vessel turning circles by 15-25 percent compared to conventional spade rudders, enabling precise harbor maneuvering for ultra-large crude carriers and post-Panamax boxships. Electro-hydraulic actuation systems command the dominant share of newbuild installations due to their compatibility with integrated bridge controls and variable load feedback. Composite material technology is gaining fastest in specialized applications where reduced magnetic signature and corrosion resistance justify premium procurement for mine countermeasure and research vessels.
IMO's Energy Efficiency Existing Ship Index and Carbon Intensity Indicator frameworks are forcing fleet operators to document maneuvering efficiency gains from flap rudder retrofits in their compliance submissions. Classification societies including DNV and Lloyd's Register have issued unified requirements for high-lift rudder structural fatigue assessment under revised IACS polar class rules. Shipowners and naval architects must monitor how pending EU maritime emissions trading system scope expansion revalues steering system efficiency in total voyage carbon accounting.
Market Dynamics
The IMO's EEXI and CII carbon intensity frameworks are forcing fleet operators to document maneuvering efficiency gains from steering system retrofits in their compliance submissions. This regulatory pressure is restructuring procurement priorities across commercial shipping.
Growth Catalysts
- IMO Carbon Intensity Regulations:The EEXI and CII frameworks mandate documented efficiency improvements from high-lift rudder retrofits, creating compliance-driven demand across existing fleets.
- Container Vessel Newbuilds:Chinese state-owned shipyards are scaling output for post-Panamax boxships requiring precision harbor maneuvering systems.
- Nickel-Aluminum-Bronze Castings:Advanced metallurgy extends rudder service intervals in corrosive marine environments, reducing lifecycle operating costs for bulk carrier operators.
Market Restraints
- Electro-Hydraulic Actuation Costs:Precision servo valves and high-pressure hydraulic infrastructure require capital outlays that deter retrofit adoption in aging coaster fleets.
- European Supply Concentration:Specialized foundry capacity for marine-grade nickel-aluminum-bronze concentrates in German and Dutch industrial clusters, creating geographic vulnerability.
- Composite Bearing Lead Times:PTFE-impregnated filament wound bearing manufacturers face 18-24 month order backlogs, delaying project commissioning.
Strategic Opportunities
- EU Emissions Trading System Expansion:Pending scope expansion to maritime transport revalues steering efficiency in voyage carbon accounting, creating incentive for premium rudder upgrades.
- Mine Countermeasure Vessels:Reduced magnetic signature requirements from composite flap rudders open specialized procurement channels outside commercial shipping.
- Integrated Bridge Automation:Convergence of flap rudder controls with dynamic positioning systems enables bundled sales to offshore support vessel operators.
Industry Challenges
- IACS Polar Class Fatigue Assessment:Revised unified requirements for high-lift rudder structural analysis extend certification timelines and engineering review costs.
- Legacy Hydraulic System Integration:Retrofit projects face compatibility failures when mating modern flap actuation to 1990s-era steering gear with obsolete control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flap Rudder Market |
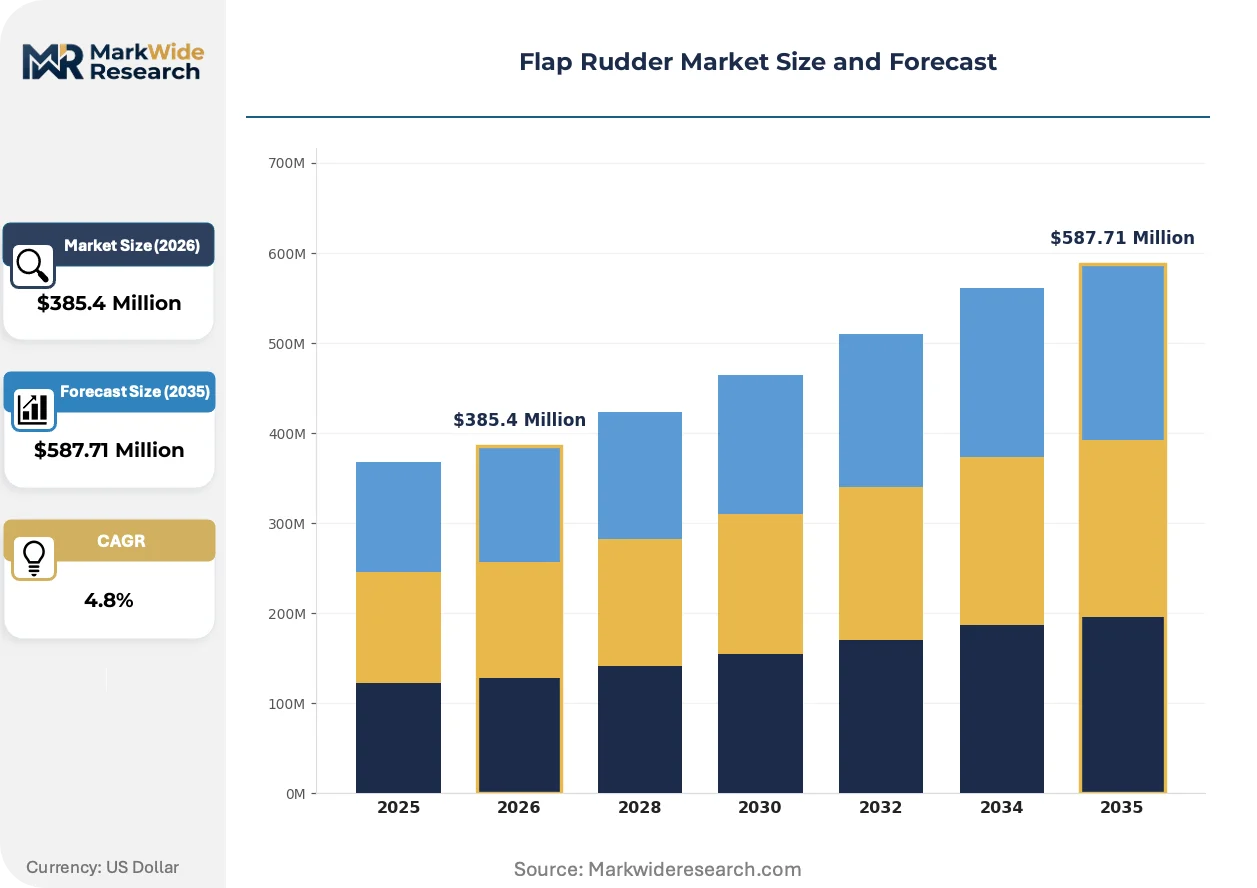
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electro-Hydraulic, Hydraulic, Manual, Servo-Mechanical, Mechanical Technology: Composite Material, Stainless Steel, Aluminum Alloy, Titanium Alloy, Carbon Fiber Application: Commercial Shipping, Naval Vessels, Offshore Support, Passenger Ferries, Research Vessels End User: Shipbuilders, Maritime Defense Contractors, Charter Operators, Marine Engineering Firms |
| Companies Covered | Becker Marine Systems GmbH, Kongsberg Gruppen, Damen Marine Components, De Waal BV, Nakashima Propeller, Kamome Propeller, Wuxi Delin Marine Equipment, Jiangsu China Empire Offshore Engineering Equipment Manufacture, YMV Crane and Winch Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flap Rudder Market Strategic Shifts & Innovations
Steering system architecture is converging with vessel automation platforms, compressing the traditional separation between propulsion and maneuvering controls. This integration is redrawing competitive boundaries among marine equipment suppliers.
Composite flap rudder technology is supplanting conventional nickel-aluminum-bronze castings in specialized naval applications. Mine countermeasure and research vessel operators are adopting carbon-fiber-reinforced polymer flaps to achieve magnetic signature reduction and corrosion immunity. The structural consequence is fragmenting the supplier base between commodity foundries and aerospace-tier composite manufacturers.
The European Union's maritime emissions trading system expansion is forcing voyage-level carbon accounting that includes maneuvering efficiency. Shipowners must now document rudder performance in fuel consumption calculations. Container lines operating EU-Asia routes are prioritizing flap rudder retrofits that deliver measurable CII rating improvements.
After-sales service unbundling is disrupting traditional equipment procurement. Shipowners are separating rudder hardware purchases from installation and commissioning contracts, awarding these to independent yard networks. This pattern is most visible in Singapore and Rotterdam, where specialized marine service providers are capturing lifecycle revenue previously retained by original equipment manufacturers.
Flap Rudder Market Segmentation
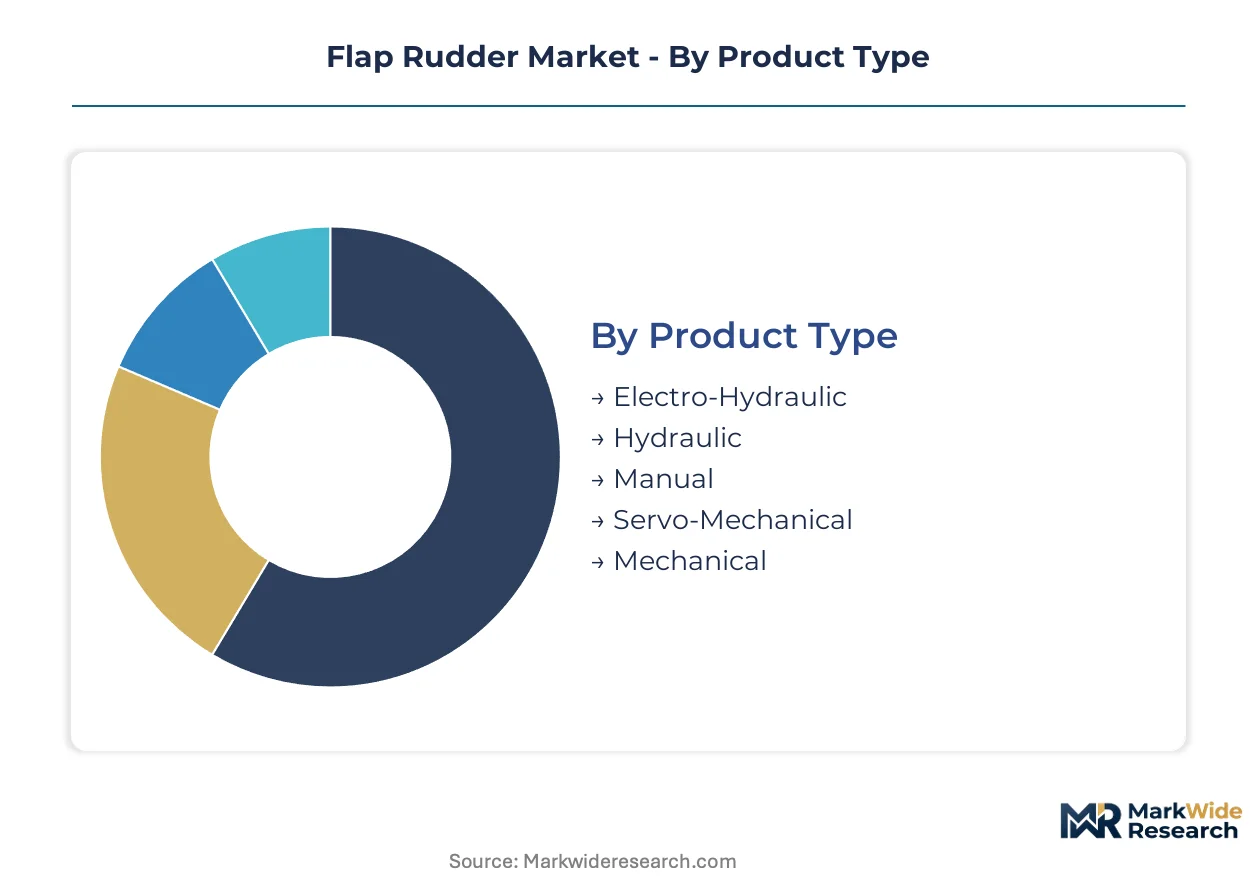
Segmentation in the flap rudder market reveals distinct margin architectures across actuation technologies, material science tiers, and vessel procurement channels. Procurement patterns diverge sharply between newbuild specifications and retrofit upgrades, with regulatory compliance timelines reshaping demand concentration across each dimension.
Product Type:
Electro-hydraulic systems command the premium margin tier due to their integration complexity with bridge automation platforms and dynamic positioning networks.
- Electro-Hydraulic:Precision servo-actuated systems with variable load feedback loops interface directly with integrated bridge controls. Demand concentrates in Chinese state-owned shipyards producing post-Panamax container vessels where IMO CII compliance documentation requires measurable maneuvering efficiency gains.
- Hydraulic:Conventional high-pressure hydraulic infrastructure dominates retrofit channels where existing steering gear infrastructure can be partially retained. European container lines facing EEXI deadlines drive replacement cycles in Hamburg and Rotterdam port clusters.
- Manual:Direct mechanical linkages serve small coastal craft and legacy fishing fleets with minimal automation requirements.
- Servo-Mechanical:Hybrid electromechanical actuation bridges cost-sensitive mid-market segments in Southeast Asian ship repair yards.
- Mechanical:Basic linkage systems persist in developing-country coaster fleets where capital constraints override efficiency premiums.
Electro-hydraulic holds installed capacity. Servo-mechanical is rotating up the share rankings.
Technology:
Material selection stratifies procurement into corrosion-resistant marine alloys versus specialized composites where magnetic signature reduction justifies substantial cost premiums.
- Composite Material:Carbon-fiber-reinforced polymer flaps with PTFE-impregnated bearings eliminate magnetic signature and corrosion vulnerability. Naval mine countermeasure programs in Germany and France specify these for operational survivability in littoral zones.
- Stainless Steel:Austenitic and duplex grades balance cost with seawater corrosion resistance for commercial bulk carrier operators prioritizing service interval extension.
- Aluminum Alloy:Lightweight extrusions serve high-speed passenger ferries where reduced mass improves fuel efficiency and dynamic response.
- Titanium Alloy:Premium-grade corrosion immunity targets specialized research vessels and polar-class icebreakers operating in extreme chemical environments.
- Carbon Fiber:Advanced prepreg layup techniques from aerospace supply chains penetrate naval procurement where weight reduction and radar signature control converge.
Stainless steel retains volume leadership. Composite material is gaining share fastest in defense applications.
Application:
Vessel type determines regulatory exposure and thus retrofit urgency, with carbon intensity frameworks creating divergent procurement timelines across fleet segments.
- Commercial Shipping:Container lines, bulk carriers, and tankers face binding CII rating requirements that revalue steering efficiency in voyage economics. Retrofit demand clusters around Singapore and Rotterdam where specialized service providers unbundle installation from hardware supply.
- Naval Vessels:Mine countermeasure and research platforms specify composite flap rudders for magnetic signature suppression. Procurement flows through national defense ministries with extended qualification cycles.
- Offshore Support:Dynamic positioning integration requirements favor electro-hydraulic bundles from Kongsberg and comparable automation specialists serving North Sea oilfield logistics.
- Passenger Ferries:Harbor maneuvering precision and vibration reduction priorities drive specification in Mediterranean and Baltic short-sea routes.
- Research Vessels:Silent operation and precise station-keeping requirements combine with ice-class structural demands in polar expedition fleets.
Commercial shipping anchors volume demand. Naval vessels are climbing the fastest on specialized composite specifications.
End User:
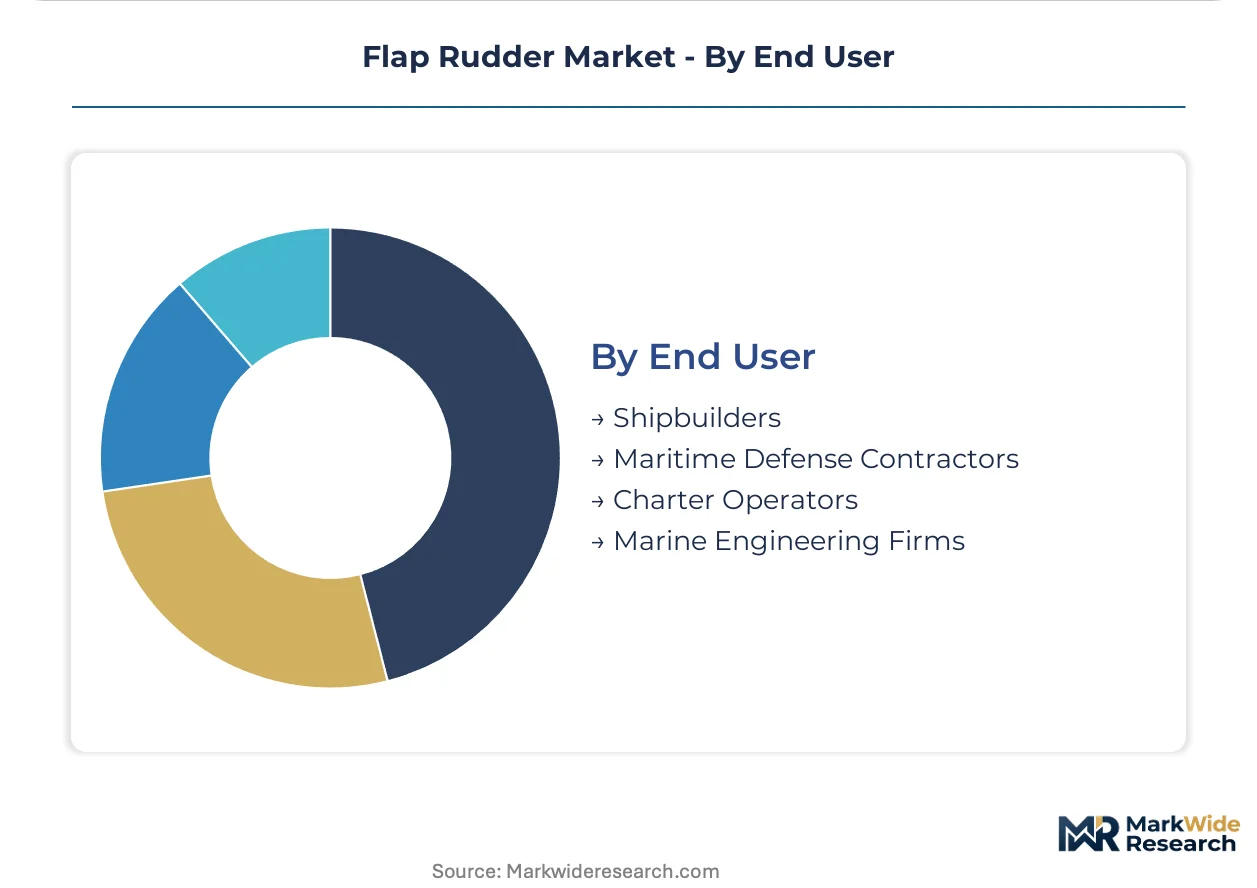
Procurement authority fragmentation between shipbuilders, defense contractors, and fleet operators creates channel complexity with divergent technical specification processes.
- Shipbuilders:Chinese state-owned yards in Shanghai and Dalian specify flap rudders at hull construction stage, capturing efficiency gains in original CII baselines rather than retrofit documentation.
- Maritime Defense Contractors:German and French naval primes integrate composite flap technology into mine countermeasure vessel platforms with multi-year development horizons.
- Charter Operators:Third-party ship management groups in Greece and Singapore drive retrofit procurement as they assume technical compliance responsibility from vessel owners.
- Marine Engineering Firms:Independent naval architects and classification society consultants specify rudder upgrades as part of comprehensive energy efficiency studies for existing fleets.
Shipbuilders control newbuild specification. Charter operators are rotating up the share rankings in retrofit channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipowner procurement authority concentrates in German and Greek chartering clusters, Chinese state-owned yards, and Singapore-based technical managers. Regulatory compliance timelines vary sharply across these buyer archetypes, creating divergent retrofit urgency and newbuild specification patterns.
China
State-owned shipyards in Shanghai and Dalian scale post-Panamax container vessel output requiring precision harbor maneuvering systems. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate energy-efficient steering retrofits. Yangtze River Delta manufacturing clusters supply nickel-aluminum-bronze castings for both domestic yards and export markets.
Germany
Container lines headquartered in Hamburg face binding EEXI deadlines that prioritize documented maneuvering efficiency gains. The Federal Maritime and Hydrographic Agency enforces strict structural fatigue assessments under revised IACS polar class rules. Industrial foundries in the Ruhr region concentrate specialized capacity for marine-grade alloy production.
Netherlands
Rotterdam port cluster technical managers unbundle rudder hardware from installation contracts, capturing lifecycle revenue. The Dutch Emissions Authority implements EU maritime emissions trading system scope expansion that revalues steering efficiency in voyage carbon accounting. Damen shipyards in Gorinchem integrate captive supply chains serving both parent network and third-party retrofit channels.
Singapore
Greek-controlled charter operators route retrofit procurement through Singapore-based technical management groups assuming compliance responsibility. The Maritime and Port Authority enforces port state control inspections that flag steering system deficiencies triggering replacement cycles. Jurong ship repair yards specialize in flap rudder commissioning independent of original equipment manufacturer service contracts.
Japan
Propeller and rudder fabricators in Nagoya and Kobe supply integrated maneuvering packages to domestic shipbuilders. The Ministry of Economy, Trade and Industry promotes next-generation ship technology adoption through targeted subsidies. Osaka Bay industrial corridors maintain precision machining capacity for high-lift rudder flap actuation mechanisms.
Flap Rudder Market Key Industry Players
Player mix skews toward European specialist fabricators with captive foundry capacity and integrated automation bundlers serving offshore vessel operators. Market structure concentrates around three strategic archetypes: metallurgy-led hardware specialists, bridge-to-propeller automation integrators, and shipyard-captive component suppliers. Competitive moves center on strategic partnerships with classification societies for streamlined certification and geographic expansion into Chinese state-owned yard supply chains.
Among German-based specialists, Becker Marine Systems GmbH exemplifies the metallurgy-led archetype through its established Becker Flap technology position. Kongsberg Gruppen anchors the automation-integrator tier by bundling rudder controls with dynamic positioning systems. Damen Marine Components occupies the shipyard-captive position, serving both its parent yard network and independent retrofit channels. These three entities represent distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Becker Marine Systems GmbH |
| Kongsberg Gruppen |
| Damen Marine Components |
| De Waal BV |
| Nakashima Propeller |
| Kamome Propeller |
| Wuxi Delin Marine Equipment |
| Jiangsu China Empire Offshore Engineering Equipment Manufacture |
| YMV Crane and Winch Systems |
| Others |
Cost & Logistics Intelligence
Composite flap substitution for nickel-aluminum-bronze castings is simultaneously fragmenting supply geography toward aerospace-tier manufacturers and compressing pricing economics in legacy foundry-dependent tiers. This material transition revalues corrosion immunity and magnetic signature reduction against traditional alloy durability premiums.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate procurement for nickel-aluminum-bronze rudder assemblies. Three-tier pricing structure across electro-hydraulic integrated systems, conventional hydraulic retrofits, and mechanical linkages reflects automation complexity and certification grade differentiation. Cost compression in hydraulic retrofit tiers is intensifying because charter operators unbundle hardware from installation contracts. Greek-controlled fleet managers exhibit highest price sensitivity, while German naval primes accept substantial premiums for composite magnetic-signature specifications.
Supply Chain Analysis
Germany and the Netherlands anchor specialized foundry capacity for marine-grade nickel-aluminum-bronze castings serving European retrofit demand. China draws from Yangtze River Delta manufacturing clusters for both domestic state-owned yard supply and export fabrication. Raw material dependencies center on nickel ore imports, high-tensile steel plate, and PTFE-impregnated filament wound bearings. Single-source vulnerability concentrates in German Ruhr region alloy production. Distribution runs through Rotterdam and Singapore port clusters where technical management groups unbundle lifecycle service contracts from original equipment manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service unbundling is expanding faster than hardware procurement, creating recurring-revenue layers in installation, commissioning, and classification compliance documentation. This service-attach dynamic revalues supplier relationships toward lifecycle partnership models.
For Market Incumbents: Consolidate captive foundry capacity in Germany and the Netherlands to defend alloy supply security against composite material substitution. Deepen backward integration into PTFE-impregnated bearing manufacturing to compress 18-24 month lead times threatening project commissioning timelines. Lock long-term supply agreements with Chinese state-owned yards before automation bundlers capture newbuild specification authority.
For New Entrants and Emerging Players: Certification fast-track partnerships with DNV and Lloyd's Register open retrofit channels in Hamburg and Rotterdam port clusters where EEXI deadlines compress procurement timelines. Target Southeast Asian servo-mechanical retrofit segments where cost-sensitive mid-market buyers seek electro-hydraulic alternatives. Lead with independent installation and commissioning capabilities to capture service revenue incumbents forfeit through hardware-centric pricing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with European metallurgy-led specialists holding Becker Flap technology positions and integrated automation bundlers serving offshore vessel operators. Long-term viability hinges on composite material transition pace and EU maritime emissions trading system scope expansion enforcement. Watch IACS polar class rule revisions as inflection indicator for structural fatigue assessment engineering cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Ruhr region alloy production consolidation secures nickel-aluminum-bronze supply against German naval prime demand concentration. |
| Composite Material Qualification | Carbon-fiber-reinforced polymer flap certification with Lloyd's Register opens mine countermeasure vessel procurement channels. |
| Installation Service Unbundling | Independent commissioning capabilities in Singapore and Rotterdam capture lifecycle revenue from hardware OEMs. |
| Classification Society Partnership | Streamlined DNV structural fatigue assessment reduces IACS polar class certification timelines for retrofit projects. |
| Bridge Automation Integration | Dynamic positioning system bundling with Kongsberg Gruppen anchors offshore support vessel specification authority. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with naval architects at classification societies, procurement leads at Chinese state-owned shipyards, technical managers at Singapore-based charter operators, and aftermarket service heads at European retrofit yards. Secondary validation drew from Lloyd's Register certification databases, DNV structural assessment guidelines, IMO EEXI and CII compliance documentation, and customs trade records for nickel-aluminum-bronze alloy shipments. Bottom-up vessel fleet analysis triangulated against top-down equipment manufacturer capacity assessments.
Across the analysis window, projections integrated actuation technology segmentation, material science tier differentiation, and vessel procurement channel dynamics. CAGRs were derived from regression analysis of newbuild output cycles and retrofit compliance deadline clustering. Forecast inputs incorporated Chinese Ministry of Ecology and Environment dual carbon goal enforcement intensity and EU maritime emissions trading system scope expansion implementation pace.
Underlying assumptions cover regulatory compliance timeline adherence and nickel price volatility bands, with deviation risk concentrated in composite material qualification delays and IACS polar class rule revision scope. Recalibration cycles align with material shifts in IMO carbon intensity framework enforcement and Chinese state-owned yard output scaling decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Hydrogen Ships Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
LNG Bunkering Vessel Market
Marine
Jack-Up Vessels Market
Marine
Military Marine Engine Market
Marine
Marine Strip Market
Marine
Sailboat Propellers Market
Marine
Marine Elevators Market
Marine
Electric Ship Market
Marine
Marine Spreader Lights Market
Marine
Jet Boat Market
Marine
Marine Filter Market
Marine
Asia-Pacific Offshore Support Vessels Market
Marine
Global Discount-Marine Trenchers Market
Marine
US Fish Finders Market
Marine
Electric Boat Market