
 Synthetic Lubricants Market | 2026-2036
Synthetic Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Lubricants Market Intelligence
Procurement power among large-scale vehicle assemblers and power plants is shifting purchasing decisions toward suppliers with global distribution networks. Shell plc leverages its extensive logistics infrastructure to serve these consolidated buyers. Fuchs Petrolub SE differentiates through its specialization in industrial and metalworking fluids. Exxon Mobil Corporation sustains its market position through significant R&D investment in polyalphaolefin (PAO) technologies.
Synthetic lubricants are engineered chemical compounds, distinct from mineral oils refined from crude. These fluids are designed with specific molecular structures to deliver superior thermal stability and lubricity in extreme operating conditions found in heavy machinery. Polyalphaolefins (PAOs) and Esters command the largest share of the product type segment due to their versatile performance characteristics. Demand for polyalkylene glycols is accelerating, particularly for applications in hydraulic systems where fire resistance is critical.
Environmental regulations, including standards set by the US EPA and Europe's ECHA under REACH, govern the biodegradability and toxicity of lubricant formulations. The ISO 14001 standard for environmental management systems also encourages the use of less hazardous synthetic lubricants in industrial settings. Formulators must now balance meeting stricter environmental mandates with achieving higher performance benchmarks for next-generation engines and machinery.
Market Dynamics
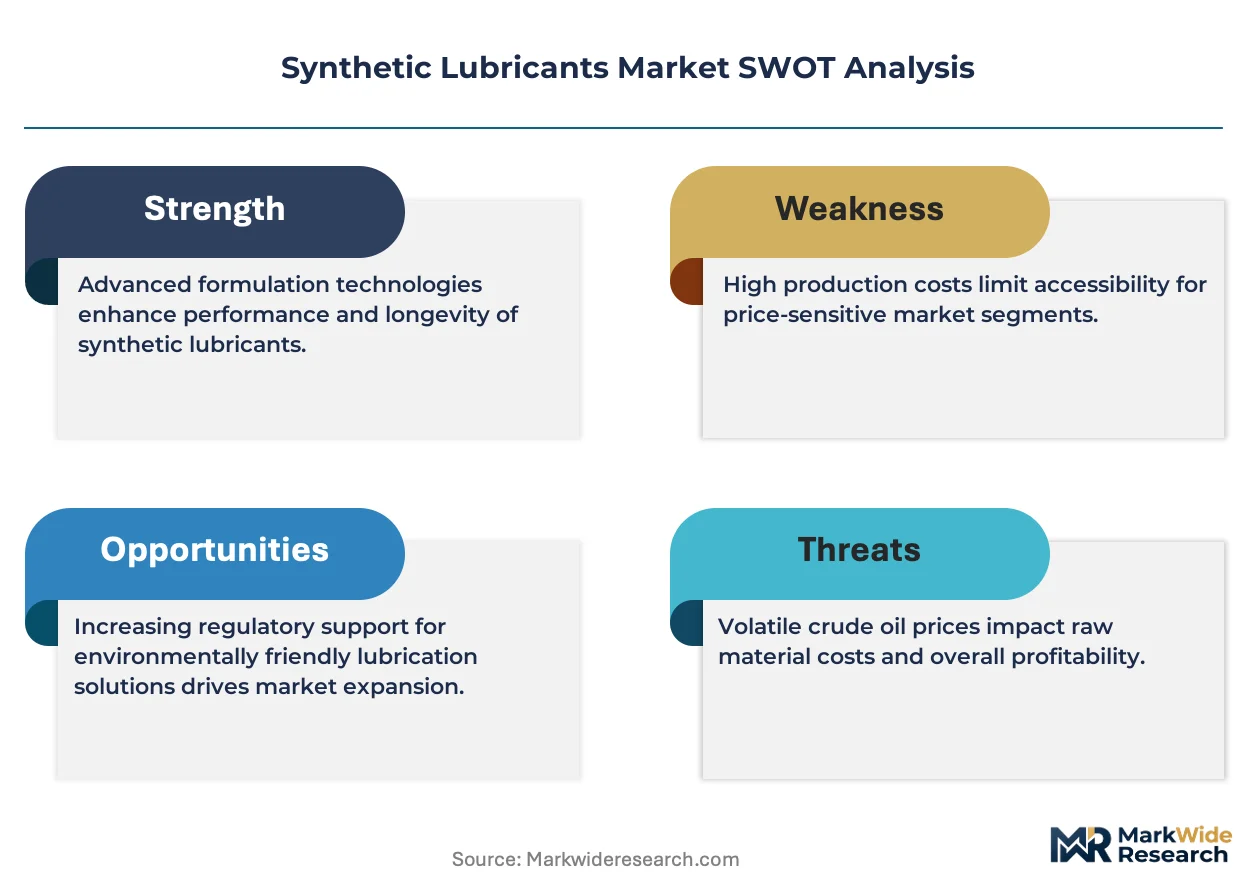
The synthetic lubricants market is defined by the tension between escalating performance requirements from advanced machinery and increasingly stringent environmental regulations. This dynamic compels formulators to innovate beyond traditional performance metrics, balancing lubricity and thermal stability with biodegradability and non-toxicity under mandates from agencies like the ECHA and EPA.
Growth Catalysts
- Aerospace Engine Demand:The push for higher thrust and fuel efficiency in commercial and military aviation engines necessitates lubricants with superior thermal and oxidative stability, which only advanced synthetic formulations can provide.
- Environmental Management Standards:Adoption of the ISO 14001 standard encourages industrial facilities to shift from mineral oils to biodegradable synthetic esters and polyalkylene glycols to minimize environmental impact from spills or disposal.
- Wind Turbine Expansion:The rapid build-out of onshore and offshore wind farms creates demand for specialized gear oils that can operate for long intervals in extreme temperatures and high-load conditions, favoring synthetic products.
Market Restraints
- Base Oil Cost Volatility:The pricing of key synthetic base stocks, particularly polyalphaolefins (PAOs) and esters, remains significantly higher and more volatile than that of conventional Group I and II mineral oils, limiting adoption in cost-sensitive applications.
- Specialized Additive Supply:Production of high-performance additives required for advanced synthetic formulations is concentrated among a few specialized chemical manufacturers, creating potential supply chain bottlenecks and pricing power.
- Mineral Oil Performance Gains:Advances in hydrocracking technology are improving the quality of Group III mineral oils, allowing them to serve as a lower-cost substitute for synthetics in moderately demanding automotive and industrial applications.
Strategic Opportunities
- Biodegradable Marine Lubricants:Stricter vessel discharge regulations from the International Maritime Organization create a significant opportunity for environmentally acceptable lubricants (EALs) based on synthetic esters, particularly for vessels operating in sensitive ecosystems.
- Industrialization in Southeast Asia:Rapid manufacturing growth in countries like Vietnam and Indonesia presents an underpenetrated market for high-performance industrial lubricants, moving beyond basic commodity fluids.
- Sensor Integration:Combining synthetic lubricants with embedded sensors for real-time condition monitoring allows for a shift toward predictive maintenance services, creating new revenue streams beyond fluid sales for equipment operators.
Industry Challenges
- Global Regulatory Harmonization:Formulators face significant complexity and cost in developing products that can comply with disparate chemical registration and labeling requirements, such as the EU's REACH and the US's TSCA.
- Formulation Expertise Scarcity:A shortage of experienced tribologists and chemical engineers capable of balancing the complex interplay between base oils, additives, and new environmental rules constrains new product development.
- Compatibility with Legacy Seals:Ensuring that new synthetic lubricant formulations are compatible with the wide variety of elastomeric seals and gaskets in older industrial machinery presents a persistent technical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Lubricants Market |
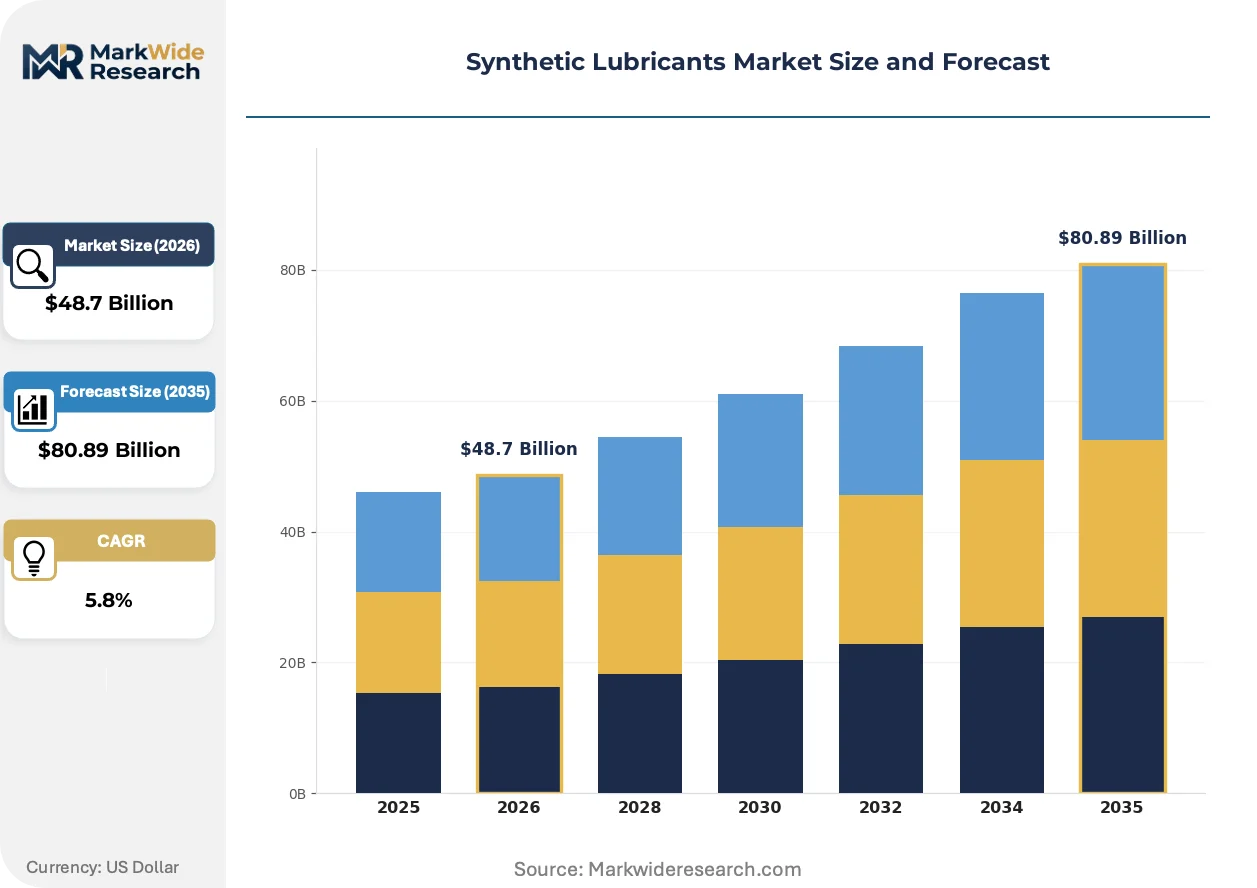
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyalphaolefins, Esters, Polyalkylene Glycols, Alkylated Naphthalenes, Silicone Fluids, Others Application: Heavy Machinery, Marine Equipment, Aerospace Engines, Power Generation, Metalworking Fluids, Hydraulic Systems End User: Vehicle Assemblers, Shipyards, Aircraft Manufacturers, Power Plants, Foundries, Construction Equipment Operators Packaging Type: Drums, Totes, Carboys, Bulk Tanks, Pails, Canisters |
| Companies Covered | TotalEnergies SE, Valvoline Incorporated, Exxon Mobil Corporation, The Lubrizol Corporation, Fuchs Petrolub SE, Shell plc, BP plc, Castrol Limited, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Lubricants Market Strategic Shifts & Innovations
Innovation is driven by the need to enhance mechanical efficiency while adhering to a stricter global environmental compliance framework. This dual objective is pushing development in base oil chemistry and additive technologies to deliver performance with a reduced ecological footprint.
Advanced additive packages serve as performance-enhancing modifiers within synthetic base oils. Industrial end-users in sectors like heavy manufacturing and power generation are increasingly specifying lubricants with custom additive blends. This development is modularizing lubricant design, enabling formulators to create application-specific fluids by combining pre-qualified components rather than developing new formulations from scratch.
China's GB standards governing energy efficiency and environmental impact for lubricants are influencing product development far beyond its borders. The regulations compel formulators to prioritize low-viscosity oils that reduce friction and emissions, accelerating the transition away from conventional fluids. This shift is most pronounced in the automotive and heavy machinery sectors, impacting both domestic production and import requirements.
A notable behavioral shift is the move from unit-price purchasing to a total cost of ownership (TCO) evaluation model. This disrupts traditional sales channels by emphasizing the long-term value of synthetics, such as extended drain intervals and reduced energy use. This TCO-based procurement is most visible within capital-intensive industries like mining and commercial transportation in North America and Europe.
Synthetic Lubricants Market Segmentation
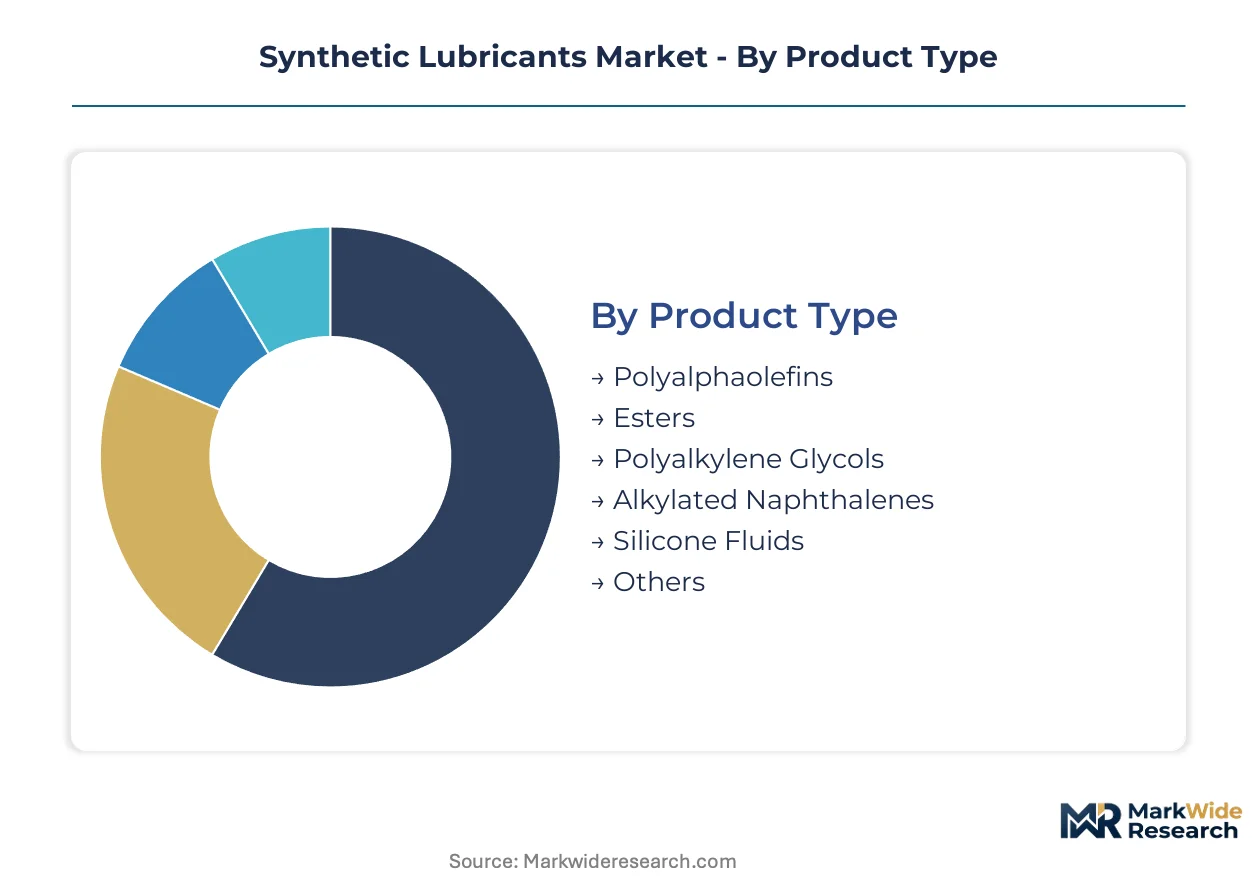
Understanding the Synthetic Lubricants Market through segmentation reveals how diverse performance requirements and operational environments shape product development and procurement. This granular analysis highlights where specialized formulations are most critical and how distinct end-user needs influence supply chain dynamics, ensuring targeted innovation and market penetration.
Product Type:
The product type segmentation highlights the spectrum from highly customized chemical compounds to more standardized formulations, each tailored for specific performance attributes.
- Polyalphaolefins (PAOs):These synthetic hydrocarbons offer superior thermal stability and viscosity index, making them ideal for extreme temperature applications. Demand from high-performance automotive engines in Germany and aerospace applications in the United States drives significant consumption.
- Esters:Known for excellent lubricity, biodegradability, and solvency, esters are frequently used in fire-resistant hydraulic fluids and environmentally acceptable lubricants. European Union regulations and the push for sustainable solutions in marine applications in Norway stimulate demand.
- Polyalkylene Glycols:These synthetic lubricants are crucial for applications requiring fire resistance and high thermal stability, particularly in industrial hydraulic systems.
- Alkylated Naphthalenes:Used primarily as blend components or additives, these compounds enhance thermal stability and solvency in various synthetic lubricant formulations.
- Silicone Fluids:Offering broad temperature range performance and dielectric properties, silicone fluids find niche applications in electrical insulation and damping.
- Others:This category encompasses a variety of specialized synthetic base stocks, including polyinternalolefins and phosphate esters, catering to highly specific industrial requirements.
Leading the category by volume: Polyalphaolefins. Growing fastest: Esters.
Application:
Application segmentation reflects the diverse performance demands placed on synthetic lubricants across various industrial and transportation sectors.
- Aerospace Engines:These applications require lubricants with exceptional thermal and oxidative stability to withstand high temperatures and pressures in commercial and military aircraft engines. Demand from aircraft manufacturers in the United States and France remains consistently high.
- Heavy Machinery:Synthetic lubricants for heavy machinery must endure high loads, extreme temperatures, and extended operating intervals in sectors like mining and construction. Manufacturing hubs in China and Germany drive substantial consumption for these robust formulations.
- Marine Equipment:Specialized lubricants protect critical components in vessels, with a growing emphasis on environmentally acceptable formulations to comply with international maritime regulations.
- Power Generation:Lubricants for turbines and auxiliary equipment in power plants require high thermal stability and long service life to ensure continuous operation.
- Metalworking Fluids:These synthetic fluids provide cooling and lubrication during machining processes, improving tool life and surface finish in industrial manufacturing.
- Hydraulic Systems:Synthetic hydraulic fluids offer enhanced performance, including fire resistance and improved viscosity stability, critical for industrial and mobile equipment.
The segment driving overall market expansion is Aerospace Engines, with Hydraulic Systems demonstrating significant growth momentum.
End User:
End-user segmentation illustrates how distinct customer types and their procurement models influence the demand for synthetic lubricants.
- Vehicle Assemblers:Large-scale automotive manufacturers integrate synthetic lubricants into new vehicles for enhanced performance and extended service intervals. Major automotive production facilities in Japan and Germany represent substantial buyers.
- Power Plants:These facilities require high-performance synthetic lubricants for turbines, generators, and auxiliary equipment to ensure operational reliability and efficiency. Demand from power generation infrastructure in India and the United States is consistent.
- Shipyards:These industrial users require lubricants for marine engines, gearboxes, and hydraulic systems during vessel construction and maintenance.
- Aircraft Manufacturers:Producers of commercial and military aircraft specify high-performance synthetic lubricants for engine and airframe components.
- Foundries:Foundries utilize synthetic lubricants for various machinery, including casting equipment and material handling systems, where high temperatures are common.
- Construction Equipment Operators:These end-users demand durable synthetic lubricants for heavy machinery operating in challenging environmental conditions.
Large-scale industrial users like Power Plants dominate consumption, while Aircraft Manufacturers show accelerating demand.
Packaging Type:
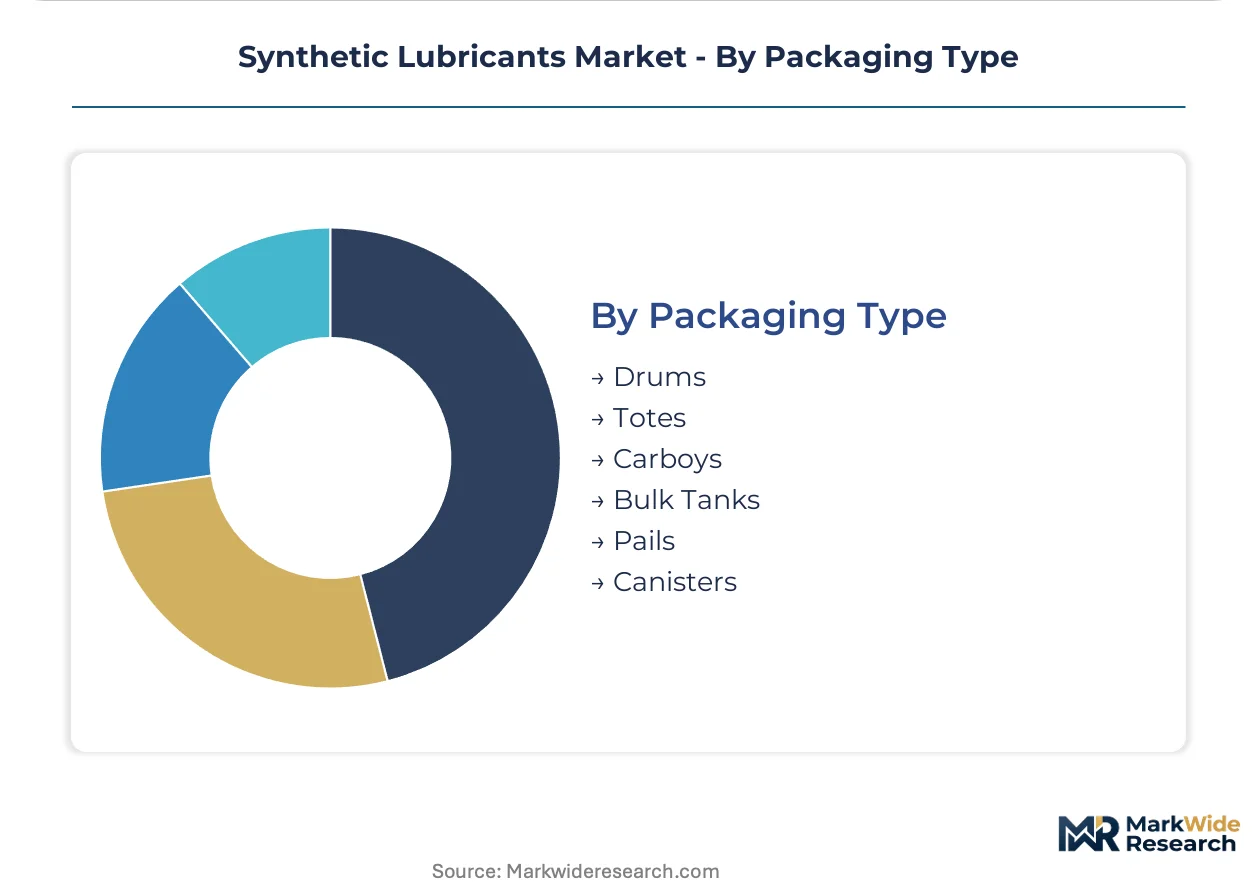
Packaging type segmentation reflects the varying scales of lubricant distribution and consumption, driven by volume and distribution logistics.
- Drums:These 200-liter containers are a standard packaging format for industrial and commercial users, balancing bulk efficiency with manageability. Manufacturing facilities in Vietnam and Indonesia frequently procure lubricants in drum quantities.
- Totes:Intermediate bulk containers (IBCs) offer a cost-effective solution for mid-to-large volume users, reducing handling and waste compared to drums. Industrial operations in Brazil and Mexico increasingly adopt tote packaging for efficiency.
- Carboys:Smaller capacity containers, carboys are typically used for specialized or lower-volume synthetic lubricant formulations.
- Bulk Tanks:Large-volume storage solutions, bulk tanks facilitate direct supply to major industrial facilities, minimizing packaging waste and logistical costs.
- Pails:These smaller containers, typically 5-gallon, serve automotive service centers and smaller industrial operations requiring manageable quantities.
- Canisters:The smallest packaging format, canisters are often used for consumer-grade synthetic lubricants or very specific, low-volume industrial applications.
High-volume industrial supply favors Bulk Tanks, with Drums serving diverse mid-scale needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global synthetic lubricants market demonstrates varied demand patterns influenced by regional industrial activity and regulatory frameworks. Production of key base stocks, particularly polyalphaolefins, is often concentrated near petrochemical hubs in the Middle East and North America, supporting worldwide supply chains. This geographic distribution underpins the market's global reach and localized application.
Germany
Germany's advanced manufacturing sector drives significant demand for synthetic lubricants in automotive and heavy machinery applications. The EU's REACH regulation heavily influences chemical composition and market access for new products within the country. Industrial lubricant consumption shows notable concentration in manufacturing hubs within Bavaria and North Rhine-Westphalia, supporting precision engineering.
United States
The United States aerospace industry requires high-performance synthetic lubricants for commercial and military aircraft engines. US EPA standards govern the biodegradability and toxicity of lubricant formulations, impacting product development. Demand from aircraft manufacturers in Seattle and Wichita remains consistently high, alongside power generation infrastructure.
China
China's extensive heavy machinery and automotive sectors create substantial consumption for robust synthetic lubricant formulations. The country's GB standards governing energy efficiency and environmental impact compel formulators to prioritize low-viscosity oils. Manufacturing hubs in the Yangtze River Delta and Pearl River Delta drive significant demand for industrial synthetics.
Norway
Norway's maritime sector shows strong demand for environmentally acceptable lubricants, particularly for vessels operating in sensitive ecosystems. European Union regulations and the International Maritime Organization's stricter vessel discharge rules stimulate the use of synthetic esters. Offshore oil and gas operations in Stavanger also require specialized high-performance fluids.
India
India's expanding power generation infrastructure requires high-performance synthetic lubricants for turbines and auxiliary equipment. The country's Bureau of Indian Standards (BIS) sets quality benchmarks for industrial lubricants, ensuring operational reliability. Demand from power plants in Maharashtra and Gujarat is consistent, supporting continuous energy supply.
Synthetic Lubricants Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized niches like biodegradable marine lubricants and sensor-integrated solutions. The market exhibits a tiered structure, with global energy majors competing alongside specialized chemical manufacturers. Key strategic archetypes include integrated oil and gas companies, focused industrial lubricant specialists, and additive technology providers. Dominant competitive moves involve strategic partnerships for additive development and geographic expansion into industrializing regions.
Within the integrated oil and gas archetype, companies like Shell plc and Exxon Mobil Corporation leverage extensive global distribution networks to serve large-scale vehicle assemblers and power plants. These entities maintain broad market presence, supported by significant investments in research and development, particularly for advanced base oil technologies such as polyalphaolefins. Fuchs Petrolub SE, conversely, represents a specialized industrial lubricant provider, differentiating through its focused expertise in industrial and metalworking fluids. These distinct approaches underscore the market's varied competitive strategies, balancing extensive reach with deep technical specialization.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Valvoline Incorporated |
| Exxon Mobil Corporation |
| The Lubrizol Corporation |
| Fuchs Petrolub SE |
| Shell plc |
| BP plc |
| Castrol Limited |
| Chevron Corporation |
Cost & Logistics Intelligence
Captive supply of polyalphaolefins by integrated oil and gas majors anchors their market position and provides a degree of pricing power over specialized formulators. This integration choice influences both raw material availability and the final cost structure for synthetic lubricants.
Pricing Analysis
Warranty bundling and extended service intervals drive the value-based pricing model for high-performance synthetic lubricants. Price differentiation stems from superior performance characteristics, such as thermal stability, and adherence to stringent certifications like ISO 14001. Upward pricing pressure arises from the high cost and volatility of synthetic base stocks like PAOs and esters, alongside significant R&D investments. Large-scale aerospace and power generation buyers demonstrate lower price sensitivity due to total cost of ownership evaluations.
Supply Chain Analysis
Dual-sourcing requirements for critical components are becoming common, reflecting buyer strategies to mitigate supply risks. Supply of key petrochemical feedstocks for polyalphaolefins concentrates in the Middle East and North America, influencing global availability. The industry relies heavily on specialized additives, often sourced from a few chemical manufacturers, creating potential bottlenecks. Commodity price volatility for base oils represents a structural supply chain risk. Distribution runs through extensive global networks for major players, complemented by specialized regional channels for niche products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synthetic lubricants market is engaged in a vertical-integration race, with players pursuing advanced base oil research as a key upstream lever to control performance and cost.
For Market Incumbents: Acquire specialized additive technology firms to secure key formulation components and reduce supply chain vulnerabilities. Invest heavily in polyalphaolefin (PAO) and ester R&D to counter performance gains in Group III mineral oils. Expand global logistics infrastructure to serve consolidated buyers, mitigating the threat from emerging regional competitors. Defend market share against specialized entrants targeting high-growth niches like biodegradable marine lubricants.
For New Entrants and Emerging Players: Capture underpenetrated segments in rapidly industrializing regions like Southeast Asia with performance-enhancing industrial lubricants. Target the growing demand for environmentally acceptable lubricants (EALs) in marine applications, leveraging ester-based formulations. Develop sensor-integrated lubricant solutions to offer predictive maintenance services, creating a new revenue stream beyond fluid sales. Focus on specialized expertise and TCO-based value propositions rather than competing on commodity pricing.
For Investors and Strategic Acquirers: Exit pathways concentrate in niche formulators with proprietary additive technologies or strong regional distribution networks. The market's long-term viability hinges on balancing stricter environmental mandates with escalating performance requirements over the next decade. Acquisition targets should include specialized chemical manufacturers focused on advanced additive development or companies with established positions in high-growth application areas like wind energy. A signal to watch is increased M&A activity for firms offering integrated condition monitoring and lubricant solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Esters | Addresses accelerating demand for biodegradable and fire-resistant synthetic lubricants, particularly in marine and hydraulic systems. |
| Backward Integration into Additive Production | Secures critical supply of specialized performance-enhancing chemicals, reducing reliance on third-party manufacturers. |
| Long-term Supply Agreements with OEMs | Establishes stable demand channels and embeds synthetic lubricants into next-generation engine and machinery designs. |
| Investment in Predictive Maintenance Platforms | Creates new service revenue streams by combining lubricant sales with real-time condition monitoring for equipment operators. |
| Green Certification Program Development | Aligns product portfolios with evolving environmental regulations and strengthens market access in regions like the European Union. |
Research Approach
Industry reports, regulatory documentation from the EU REACH and US EPA, and academic research formed the secondary backbone of this study. Primary research involved in-depth interviews with R&D directors, procurement leads from large vehicle assemblers, plant managers in manufacturing hubs, and environmental compliance officers. This approach ensured a robust understanding of market dynamics through bottom-up and top-down triangulation.
A bottom-up estimation of end-use consumption, validated by top-down market sizing, underpinned the analytical framework over the projection horizon. Segmentation dimensions modeled included product type, application, end-user, packaging type, and regional regulatory frameworks. Compound annual growth rates were derived based on historical growth trends, projected industrial output, and regulatory impact assessments. Key industry-specific forecast inputs included aerospace engine production forecasts and wind turbine installation rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to volatility in base oil pricing and unforeseen regulatory shifts in major economies. The forecasts reflect assumptions regarding technological advancements and market adoption rates. A model refresh is warranted upon material change in global environmental compliance frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Kenya Lubricants Market
Lubricants
Africa Lubricants Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Vietnam Automotive Engine Oils Market
Lubricants
Thailand Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
United Kingdom Lubricants Market
Lubricants
Gun Lubricant Market
Lubricants
Germany Lubricants Market
Lubricants
Egypt Lubricants Market
Lubricants
Global Process Oil Market
Lubricants
Israel Lubricants Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Industrial Lubricants Market