
 Apple Fiber Market | 2026-2036
Apple Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Apple Fiber Market Outlook
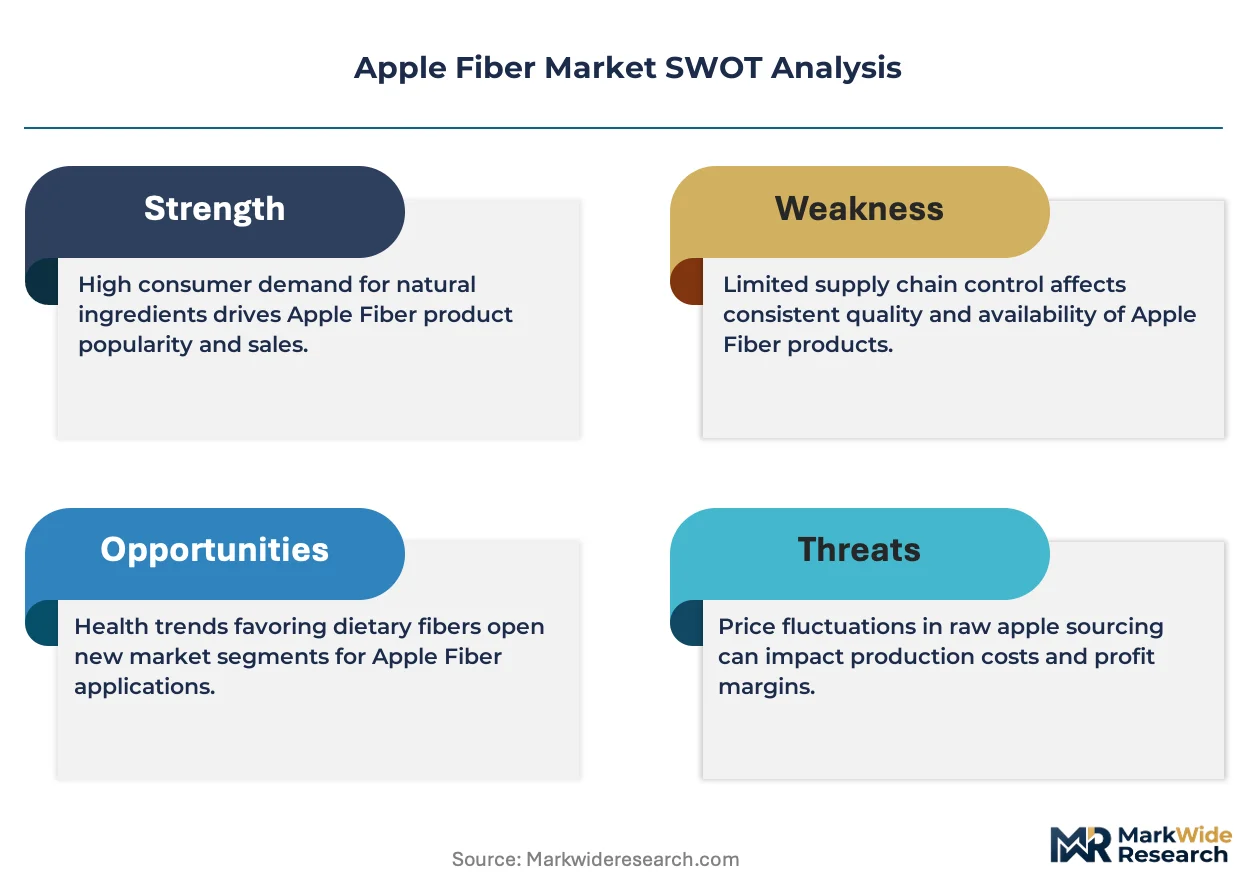
Wheat bran in premium baked goods is consolidating toward apple fiber as formulators seek lower-carbohydrate, allergen-friendly alternatives with comparable water-binding capacity. J. Rettenmaier & Söhne GmbH + Co KG leverages its German milling heritage to dominate pharmaceutical-grade fiber specifications. Herbafood Ingredients GmbH sustains R&D intensity on organic apple fiber variants for clean-label contracts. Ingredion Incorporated anchors North American supply through its starch and fiber distribution infrastructure.
Apple fiber consists of the insoluble and soluble cell-wall polysaccharides recovered from apple pomace after juice extraction, typically containing 40-60% total dietary fiber with pectin fractions contributing viscosity and gelation in food matrices. Its primary commercial purpose centers on texturizing, bulking, and nutritional fortification in reduced-calorie and high-fiber consumer products. Powder formats command the deepest margin pools due to ease of dosing and shelf stability in industrial formulations. Nutritional supplements represent the fastest-expanding application as sports nutrition brands seek prebiotic fiber sources with consumer-friendly fruit provenance. Bakery products remain the most mature segment, though premiumization toward artisan and gluten-free lines sustains volume.
The FDA's dietary fiber definition under Nutrition Facts labeling rules shapes which isolated fibers qualify for health claims in U.S. food products, while the EU Green Deal's circular economy action plan accelerates valorization of apple processing byproducts across member states. EFSA's ongoing evaluations of novel fiber health claims influence investment timelines for European suppliers. Stakeholders must monitor evolving fiber qualification thresholds in major jurisdictions to align R&D pipelines with compliant positioning.
Market Dynamics
The EU Green Deal's circular economy mandates are compressing approval timelines for upcycled apple pomace derivatives, forcing ingredient suppliers to reconfigure extraction protocols around waste valorization compliance rather than conventional fiber isolation economics.
Growth Catalysts
- Clean-label bakery reformulation:German and U.S. food manufacturers are substituting wheat bran with apple fiber to achieve lower carbohydrate profiles while maintaining water-binding functionality in gluten-free and artisan product lines.
- EFSA novel fiber evaluations:The European regulator's ongoing health claim assessments are creating compliant positioning pathways that accelerate R&D investment into pectin-rich apple fiber fractions for prebiotic applications.
- Sports nutrition prebiotic demand:Powder-format apple fiber with consumer-friendly fruit provenance is capturing formulation slots in nutritional supplements as brands seek digestible fiber sources with transparent sourcing narratives.
Market Restraints
- Apple pomace supply concentration:Dependency on Swiss and German juice processing clusters creates geographic vulnerability in raw material flows for fiber extraction facilities.
- FDA fiber definition uncertainty:The U.S. regulator's evolving qualification thresholds for isolated dietary fibers under Nutrition Facts labeling rules generate compliance friction for imported apple fiber shipments.
- Oat and chicory root substitution:Established prebiotic fiber alternatives with lower unit economics and deeper supplier bases constrain apple fiber penetration in mass-market nutritional applications.
Strategic Opportunities
- Pharmaceutical-grade fiber specifications:J. Rettenmaier & Söhne GmbH + Co KG's German milling heritage demonstrates viable positioning in excipient and laxative formulations with premium margin structures.
- Organic certification pipelines:Herbafood Ingredients GmbH's R&D intensity on organic variants aligns with clean-label contract requirements from European retail private-label programs.
- North American distribution infrastructure:Ingredion Incorporated's starch and fiber network offers captive channel access for apple fiber volume scaling across U.S. and Canadian food manufacturing.
Industry Challenges
- Pectin fraction standardization:Variable polysaccharide recovery rates from different apple cultivars and pressing methods complicate consistent viscosity performance in industrial bakery formulations.
- Cross-contamination protocols:Facilities processing both conventional and organic apple fiber must maintain segregated production lines, elevating capital requirements for dual-certification compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Fiber Market |
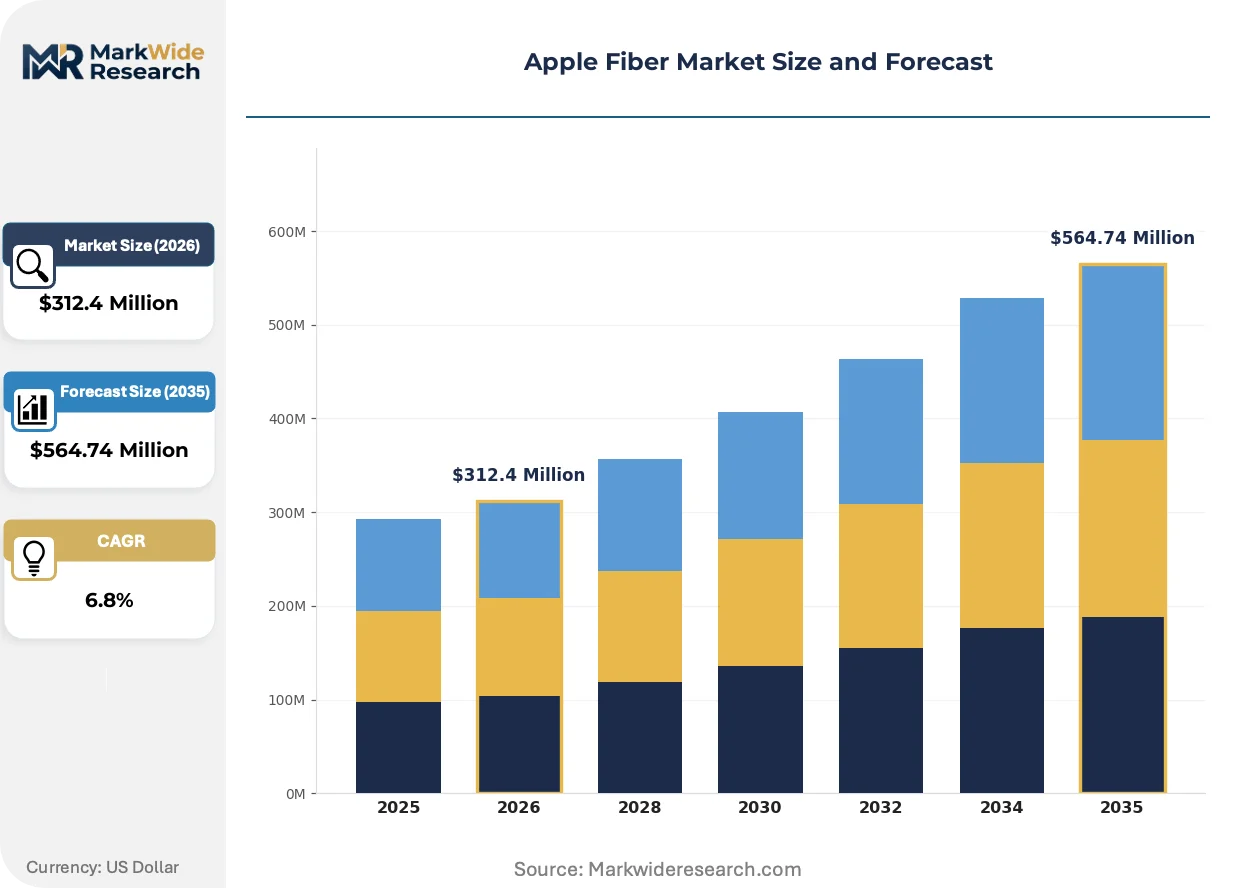
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juice Pulp, Whole Fibers, Powder, Concentrates Application: Food & Beverage, Nutritional Supplements, Bakery Products, Animal Feed End User: Food Manufacturers, Beverage Companies, Health Stores, Pet Food Producers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | J. Rettenmaier & Söhne GmbH + Co KG, Ingredion Incorporated, Herbafood Ingredients GmbH, Unipektin Ingredients, Doehler Group SE, Marshall Ingredients, CFF GmbH & Co. KG, LaBudde Group, Mayer Brothers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Fiber Market Strategic Shifts
Enzymatic extraction protocols and precision fermentation of apple pomace derivatives are displacing conventional mechanical pressing, enabling higher pectin yields with reduced thermal degradation of functional polysaccharides.
Membrane filtration technology is absorbing soluble fiber fractions previously discarded in waste streams, allowing Swiss and German processors to capture pectin and oligosaccharides for pharmaceutical and nutraceutical applications. Ingredient houses in these clusters are retrofitting juice extraction facilities with ceramic microfiltration modules. This capital deployment is compressing payback periods for pomace valorization investments while expanding addressable fiber product categories beyond insoluble bulk ingredients.
REACH registration requirements for novel food contact substances are forcing apple fiber suppliers to document migration profiles of extraction solvents and processing aids in packaging applications. The European Chemicals Agency's substance evaluation timelines are extending commercialization lead times for modified pectin grades intended for edible films and coatings. German formulators are responding by prioritizing GRAS-affirmed processing methods that preempt ECHA scrutiny.
Long-term supply agreements are displacing spot purchasing in bakery and supplement manufacturing procurement functions, as buyers seek price stability amid volatile apple crop yields and energy-intensive drying costs. Swiss ingredient distributors are offering multi-year contracts with volume commitments and indexed pricing to secure allocation from constrained pomace supply. This contracting pattern is most visible in Western European premium baked goods segments where reformulation cycles extend 18-24 months.
Apple Fiber Market Segmentation
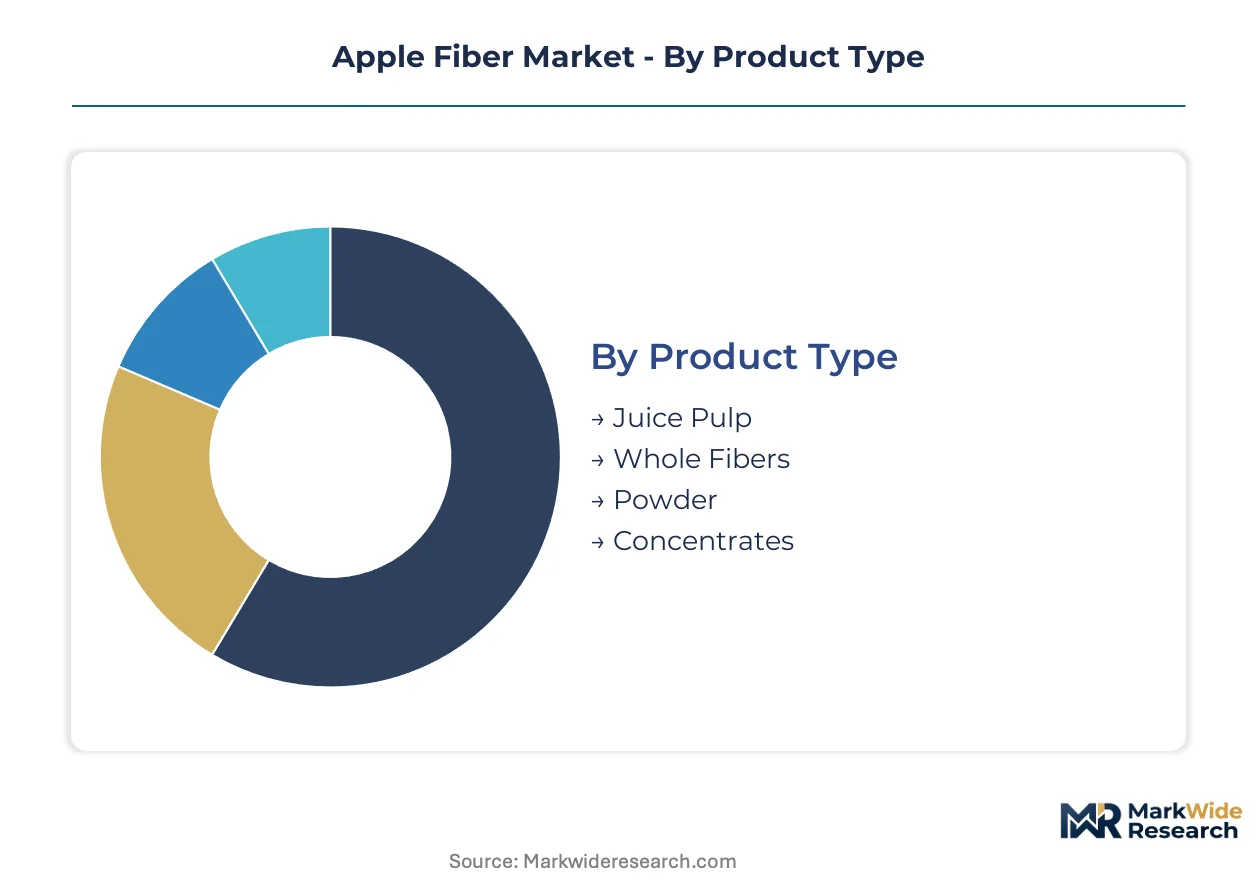
Apple fiber procurement patterns diverge sharply across product formats and end-use specifications. Formulators select grades based on solubility profiles, particle size distributions, and organic certification status rather than commodity pricing alone.
Product Type:
Upgrade cycles in this category track reformulation velocity in clean-label bakery and sports nutrition segments, where water-binding capacity and prebiotic functionality drive specification changes.
- Powder:Fine-milled insoluble and soluble fractions with standardized particle sizes between 100-300 microns enable precise dosing in industrial bakery lines and supplement capsules. German and Swiss food manufacturers dominate volume procurement for gluten-free bread applications where powder format ensures homogeneous hydration. Shelf stability and ease of pneumatic conveying cement powder's position as the default specification for large-scale contract manufacturing.
- Whole Fibers:Coarse cell-wall matrices retain structural integrity for texturizing applications in premium pet food and artisan bakery segments. Demand clusters in North American natural pet food channels where visible fiber inclusions signal ingredient transparency to consumers. Higher moisture sensitivity and irregular dosing characteristics constrain penetration beyond niche premium positioning.
- Juice Pulp:Semi-dried pomace residues with variable fiber content serve regional feed markets and lower-tier food applications. Proximity to pressing operations in German juice processing clusters determines economic viability given transport cost sensitivity.
- Concentrates:Pectin-enriched soluble fiber extracts command pharmaceutical and nutraceutical specifications where viscosity modulation and gelation properties are critical. EFSA novel fiber evaluations are accelerating compliant positioning for prebiotic health claims in European markets.
Volume placements concentrate in Powder; the faster expansion belongs to Concentrates.
Application:
Cost tier differentiation separates commodity feed applications from pharmaceutical-grade fiber specifications, with margin structures varying by certification requirements and functional performance guarantees.
- Bakery Products:Reformulation of wheat bran-dependent recipes toward apple fiber achieves lower net carbohydrate declarations while maintaining crumb structure and moisture retention. U.S. and German clean-label manufacturers lead substitution volumes in gluten-free and artisan product lines. Water-binding capacity parity with conventional bran sources determines adoption velocity in industrial-scale operations.
- Nutritional Supplements:Prebiotic positioning in sports nutrition and digestive health formats leverages consumer-friendly fruit provenance narratives. Powder-format apple fiber captures formulation slots in protein bars and fiber supplements where transparent sourcing commands premium pricing. FDA fiber definition compliance under Nutrition Facts labeling rules shapes qualification for health claims in U.S. products.
- Food & Beverage:Beverage fortification and dairy alternative texturizing applications utilize soluble pectin fractions for mouthfeel modification. EU Green Deal circular economy mandates are compressing approval timelines for upcycled pomace derivatives in these formulations.
- Animal Feed:Regional ruminant and companion animal feed applications absorb lower-grade fiber streams with minimal processing. Proximity to German and Swiss juice processing clusters determines supply economics given moisture content and perishability constraints.
Volume placements concentrate in Bakery Products; Nutritional Supplements are climbing the fastest.
End User:
Customer type segmentation reflects divergent procurement sophistication, with multinational food manufacturers demanding certified supply chains versus regional health stores prioritizing organic provenance claims.
- Food Manufacturers:Industrial-scale bakery and packaged goods producers specify apple fiber for reformulation mandates targeting clean-label positioning and carbohydrate reduction. Long-term supply agreements with indexed pricing are displacing spot purchasing as buyers seek stability amid volatile apple crop yields.
- Beverage Companies:Functional drink and dairy alternative formulators utilize soluble pectin fractions for viscosity and suspension properties. REACH registration requirements for novel food contact substances are extending commercialization lead times for modified grades.
- Health Stores:Independent and chain retailers stock organic-certified apple fiber supplements targeting prebiotic and digestive wellness positioning. Consumer education investments differentiate private-label offerings in this channel.
- Pet Food Producers:Premium natural and raw pet food manufacturers incorporate visible fiber inclusions for digestive health marketing. North American specialty pet food channels show strongest demand concentration.
Volume placements concentrate in Food Manufacturers; the steepest expansion trajectory belongs to Pet Food Producers.
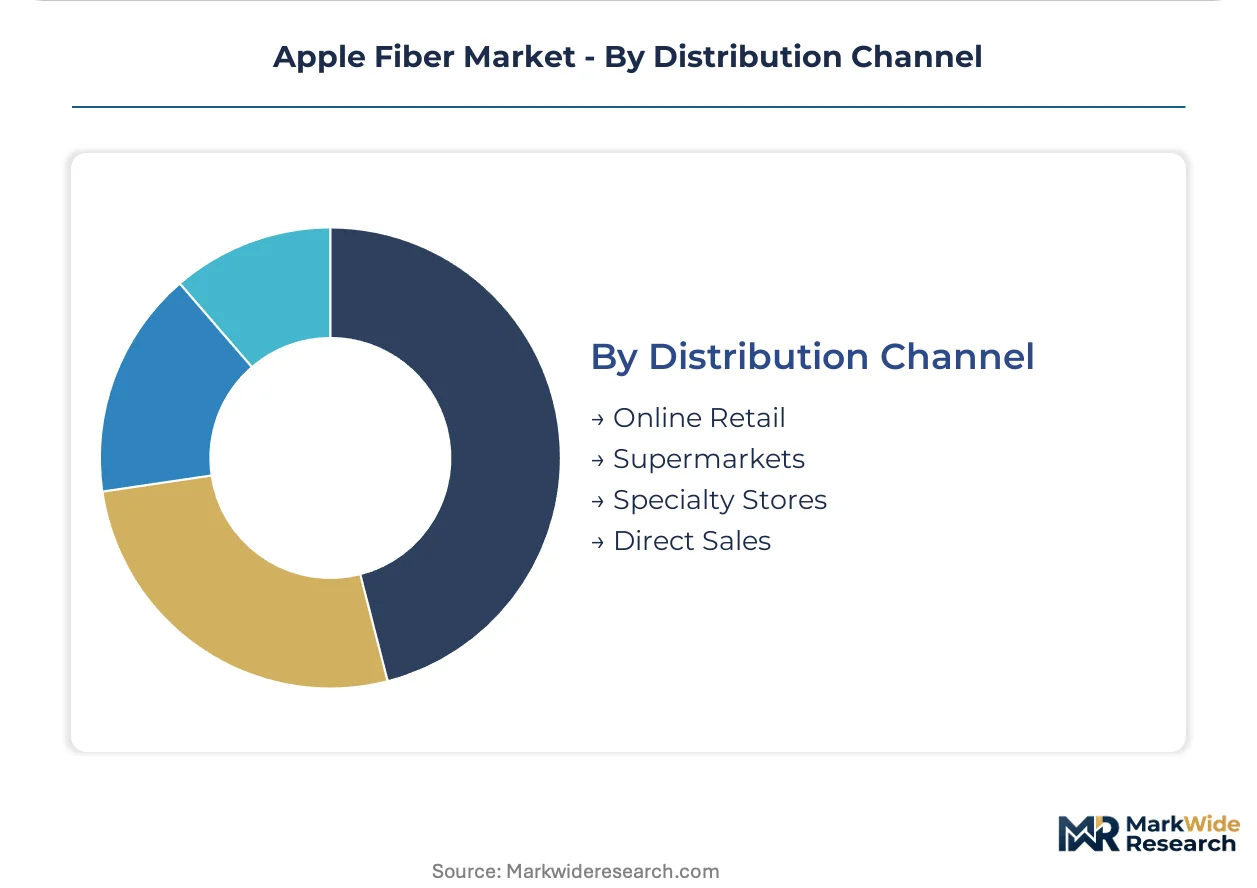
Distribution Channel:
Supply concentration in Swiss and German ingredient processing clusters shapes channel economics, with direct sales capturing pharmaceutical-grade volumes and online retail fragmenting supplement accessibility.
- Direct Sales:Long-term contracts between fiber extractors and multinational food manufacturers secure volume allocation with specification guarantees. Swiss distributors are offering multi-year agreements with volume commitments to bakery and supplement manufacturers facing 18-24 month reformulation cycles.
- Specialty Stores:Independent natural products retailers and ingredient distributors serve smaller-scale organic and clean-label formulators. Geographic proximity to German milling heritage clusters enables just-in-time delivery for regional bakery operations.
- Supermarkets:Mass-market retail placement for consumer-packaged apple fiber supplements remains limited given category novelty and education requirements.
- Online Retail:E-commerce platforms enable direct-to-consumer supplement sales and bulk ingredient access for small-scale food entrepreneurs. Transparency in sourcing narratives drives conversion in this channel.
Volume placements concentrate in Direct Sales; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial zones and Swiss ingredient processing clusters anchor production capacity through targeted circular economy incentives under the EU Green Deal framework.
Germany
Clean-label bakery reformulation and pharmaceutical-grade fiber specifications drive procurement from Baden-Württemberg and Bavaria processing facilities. The EU Green Deal's waste valorization mandates compress approval timelines for upcycled apple pomace derivatives. Ingredient extraction specialists in Rosenberg and Iggelheim retrofit juice facilities with membrane filtration modules to capture pectin fractions for nutraceutical applications.
Switzerland
Premium pet food texturizing and sports nutrition prebiotic formulations sustain demand for coarse whole fiber grades. Swissmedic's novel food substance evaluations shape commercialization pathways for modified pectin grades in edible films. Zurich-area distributors negotiate multi-year supply agreements with indexed pricing to secure allocation from constrained pomace flows.
United States
Gluten-free artisan bakery lines and nutritional supplement fortification absorb powder-format volumes from Midwest contract manufacturers. FDA dietary fiber definition uncertainty under Nutrition Facts labeling rules generates compliance friction for imported shipments. Wisconsin and Washington State juice processing clusters supply regional extraction facilities with variable cultivar feedstock.
France
Organic certification pipelines for retail private-label programs concentrate procurement around Auvergne-Rhône-Alpes ingredient houses. ANSM oversight of novel food contact substances extends lead times for modified grades intended for packaging applications. Lyon-based formulators prioritize GRAS-affirmed processing methods to preempt regulatory scrutiny.
United Kingdom
Sports nutrition brands seeking transparent sourcing narratives specify apple fiber with consumer-friendly fruit provenance for prebiotic positioning. FSA novel food consultations influence investment timelines for European suppliers exporting into British formulations. London-area health stores stock organic-certified supplements targeting digestive wellness segments.
Apple Fiber Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated milling heritage players dominating pharmaceutical-grade specifications while regional extractors serve commodity feed applications. The vendor base organizes around three strategic archetypes: integrated juice processors with captive pomace supply, independent fiber specialists with certified organic pipelines, and multinational distributors leveraging starch and sweetener infrastructure for cross-selling. Capacity expansion and backward integration into pressing operations represent the dominant competitive moves as suppliers seek to lock in raw material security.
Within the heritage-milling tier, J. Rettenmaier & Söhne GmbH + Co KG exemplifies German precision in pharmaceutical-grade fiber specifications, while Herbafood Ingredients GmbH occupies a position aligned with clean-label organic certification pipelines. Ingredion Incorporated anchors North American volume scaling through its established starch and fiber distribution infrastructure.
| Leading Market Players |
|---|
| J. Rettenmaier & Söhne GmbH + Co KG |
| Ingredion Incorporated |
| Herbafood Ingredients GmbH |
| Unipektin Ingredients |
| Doehler Group SE |
| Marshall Ingredients |
| CFF GmbH & Co. KG |
| LaBudde Group |
| Mayer Brothers |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade organic certification creates a steep price cliff between premium and commodity apple fiber tiers, with German and Swiss processing clusters capturing margin premiums through dual-certified production lines while spot-market juice pulp trades at energy-cost parity. This bifurcation forces buyers into long-term contracting to secure specification-grade supply, compressing procurement flexibility for reformulation cycles.
Pricing Analysis
Volume placements concentrate in standard-grade powder formats where per-kilogram economics approach commodity feed inputs, while pharmaceutical and organic-certified concentrates command substantial premia through pectin standardization guarantees. Price differentiation stems from EFSA health claim compliance status and dual organic-conventional certification overhead. Cost compression in standard grades intensifies as oat and chicory root substitutes erode volume commitments. Mass-market bakery manufacturers exhibit acute price sensitivity, whereas sports nutrition brands absorb premia for transparent fruit provenance narratives.
Supply Chain Analysis
Apple pomace supply rests on German, Swiss, and Washington State juice processing clusters where seasonal cultivar availability constrains year-round fiber extraction economics. Raw material flows draw from cider pressing operations, membrane filtration retrofits, and energy-intensive drying infrastructure. Single-source vulnerability concentrates in Baden-Württemberg pressing facilities where EU Green Deal waste valorization mandates accelerate capacity reconfiguration. Distribution runs through direct long-term contracts with indexed pricing rather than spot-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into pressing operations has become the defining competitive race, with suppliers securing captive pomace flows to insulate against crop yield volatility and energy cost spikes.
For Market Incumbents: Deepen membrane filtration capabilities in Rosenberg and Iggelheim facilities to capture pectin fractions for pharmaceutical specifications, while extending multi-year supply agreements with Swiss distributors to lock in bakery reformulation cycles. Oat fiber substitution in mass-market applications threatens volume erosion without premium tier migration. For New Entrants and Emerging Players: Launch via online retail channels targeting North American pet food producers seeking visible fiber inclusions with transparent sourcing narratives, where premium positioning tolerates higher unit economics. Organic certification pipelines for private-label supplement contracts represent the most penetrable white space. For Investors and Strategic Acquirers: Re-rating potential sits with integrated juice processors possessing captive pomace supply and existing membrane filtration infrastructure, given EU Green Deal circular economy acceleration as a demand catalyst. Watch EFSA novel fiber evaluation timelines as the signal for health claim commercialization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pressing Operations | Captive pomace supply from German cider facilities eliminates raw material concentration risk. |
| Membrane Filtration Retrofit | Ceramic microfiltration modules in Swiss clusters capture pectin fractions for pharmaceutical grades. |
| Organic Certification Pipeline | Dual-certified production lines align with EU retail private-label clean-label procurement mandates. |
| Long-Term Supply Agreement | Indexed multi-year contracts with U.S. Midwest contract manufacturers secure reformulation cycle stability. |
| EFSA Health Claim Compliance Investment | Novel fiber evaluation pathways unlock prebiotic positioning in European sports nutrition formulations. |
Study Parameters
Trade databases, EU regulatory filings, and food industry processing statistics formed the secondary backbone, cross-referenced with primary interviews involving German milling operations managers, Swiss ingredient procurement leads, U.S. bakery reformulation specialists, and membrane filtration technology providers. Bottom-up volume modeling triangulated against top-down expenditure analysis across application segments.
Bottom-up unit economics analysis across powder, whole fiber, and concentrate grades integrated with top-down clean-label bakery and sports nutrition expenditure tracking. Segmentation dimensions spanned product format, application category, certification status, and regional processing cluster. CAGRs derived from trend extrapolation of reformulation cycle velocity and waste valorization investment flows, with apple crop yield variability and energy cost indices as key sensitivity inputs.
Regulatory timeline slippage, apple harvest volatility, and oat fiber substitution acceleration are the dominant revision risks to modeled outputs. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
Global Cotton Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Green Fibers Market
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Woolen Textiles Market
Natural Fibers
Jute Bags Market
Natural Fibers
Cellulose Market